
 Camera Module Lens Market | 2026-2036
Camera Module Lens Market Size, Share, and Industry Trends Forecast 2026-2036
Camera Module Lens Market Insights
Periscope-grade optical zoom is reorganizing competitive dynamics in the Camera Module Lens Market. Sunny Optical Technology leverages its vertical integration across glass molding and actuator assembly to dominate high-magnification designs. LG Innotek sustains its position through captive supply relationships with flagship smartphone OEMs. Largan Precision anchors the premium plastic-aspherical segment with wafer-level optics expertise.
A camera module lens is an optomechanical assembly of one or more refractive elements—typically 5P, 6P, 7P, or glass-plastic hybrid stacks—that focuses incident light onto a CMOS image sensor with specified modulation transfer function performance. Its primary commercial purpose is to deliver resolving power, field curvature control, and aberration correction within strict thickness constraints for portable imaging devices. Plastic-aspherical lenses capture the highest shipment volumes due to cost scalability, while periscope architectures represent the fastest-expanding margin pool as fold-optics enable 5x–10x equivalent focal lengths without device thickness penalties. Glass elements command premium positioning in low-light and cinematic applications where thermal stability and transmission efficiency outweigh material costs.
FCC equipment authorization rules in the United States govern electromagnetic compatibility for camera modules with integrated autofocus voice coil motors, while China's MIIT enforces imaging performance benchmarks for networked devices. REACH substance restrictions in Europe constrain the use of certain optical coatings and rare-earth dopants, forcing reformulation of anti-reflective layers. Stakeholders must monitor how divergent regional certification timelines for next-generation optical formats reshape sourcing strategies and capital allocation across glass foundries and lens assembly houses.
Market Dynamics
Multi-lens array proliferation in smartphones is compressing design cycles and forcing lens suppliers to synchronize glass molding, actuator assembly, and wafer-level optics under unified thermal management protocols.
Growth Catalysts
- MIIT imaging benchmarks:China's networked device certification mandates higher resolution thresholds, compelling OEMs to upgrade lens stacks and creating captive demand for 7P and hybrid glass-plastic assemblies.
- Periscope architectures:Fold-optics enabling 5x–10x equivalent focal lengths without thickness penalties are penetrating flagship smartphone tiers, expanding addressable margin pools for precision glass foundries.
- East Asian manufacturing clusters:Concentrated production across Shenzhen, Gumi, and Taichung reduces logistics friction and accelerates prototype-to-volume timelines for multi-element lens modules.
Market Restraints
- Optical glass supply concentration:Premium borosilicate and lanthanum-doped substrates depend on a limited set of Japanese and German melt houses, exposing lens assemblers to allocation risk during demand spikes.
- REACH substance restrictions:ECHA constraints on rare-earth dopants and certain anti-reflective coatings force reformulation of high-transmission layers, extending qualification timelines.
- Plastic-aspherical thermal limits:Polymer lens elements exhibit focal length drift above 60°C, constraining their deployment in automotive and industrial imaging where ambient temperatures fluctuate.
Strategic Opportunities
- Automotive surround-view penetration:ADAS camera counts per vehicle are climbing toward twelve-unit configurations, opening volume demand for wide-angle lens modules with extended temperature ratings.
- EU Green Deal circularity mandates:Upcoming eco-design requirements for electronics will favor lens suppliers with closed-loop glass recycling and reduced rare-earth content, rewarding early compliance investment.
- Computational-optics convergence:Synthesis of diffractive elements with traditional refractive stacks enables aberration correction in thinner form factors, creating differentiation for module integrators mastering both disciplines.
Industry Challenges
- Voice coil motor calibration:Sub-micron autofocus repeatability requires closed-loop control algorithms and magnetic field characterization that strain in-house firmware capabilities at mid-tier lens houses.
- Cross-regional certification drift:Divergent FCC electromagnetic compatibility and MIIT imaging performance timelines force parallel qualification tracks, inflating program management overhead.
- Wafer-level optics yield:Scaling precision molding across 300mm glass wafers demands capital-intensive diamond-turning and metrology equipment that compresses returns for sub-scale competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Camera Module Lens Market |
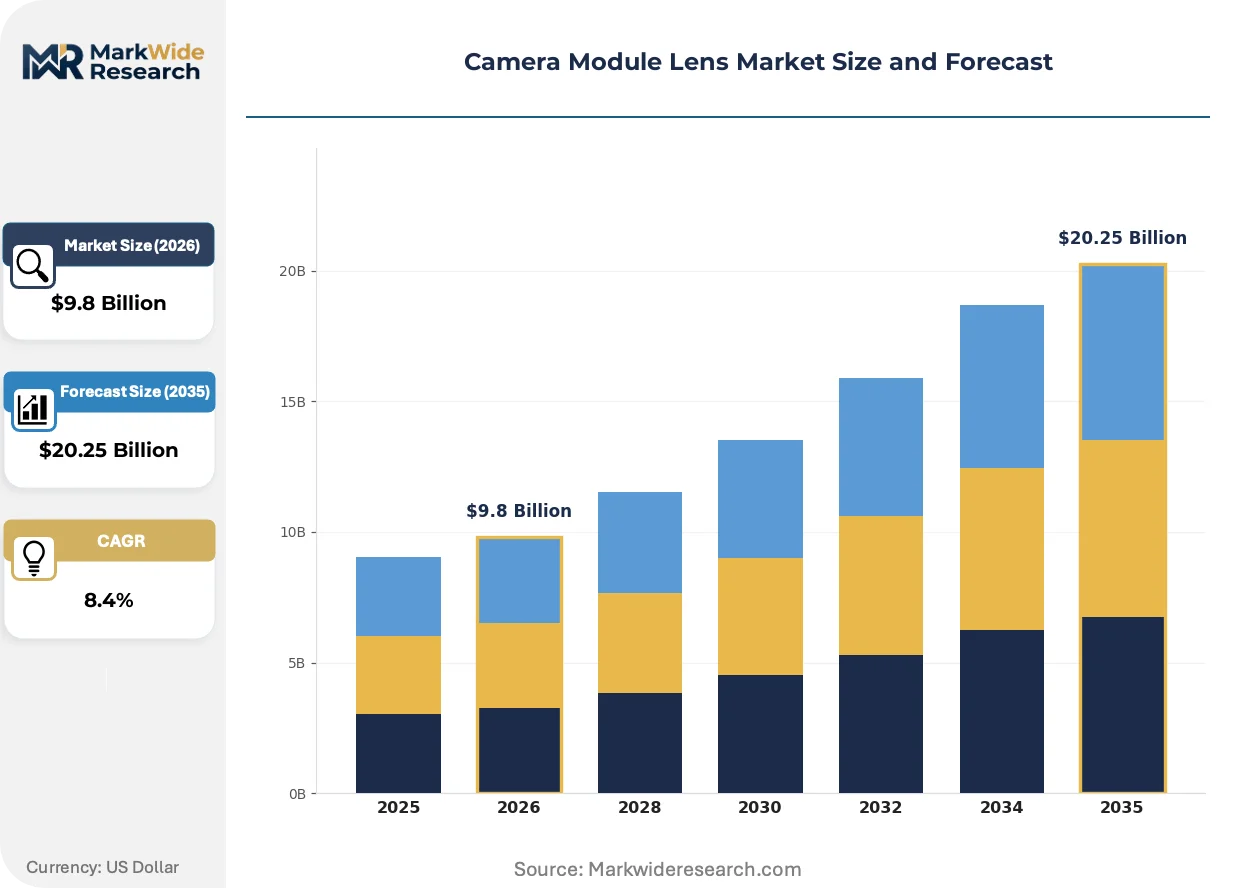
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $20.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wide-Angle, Telephoto, Macro, Periscope Lens Material: Glass, Plastic, Aspherical, Coated Application: Smartphones, Tablets, Security Cameras, Drones Technology: Auto Focus, Optical Zoom, Image Stabilization, Low-Light |
| Companies Covered | Chicony Electronics, Lite-On Technology, Sunny Optical Technology, Largan Precision, Toshiba Corporation, Samsung Electro-Mechanics, Sharp Corporation, OFILM Group, LG Innotek, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Camera Module Lens Market Trends and Innovations
Computational imaging pipelines are decoupling optical hardware from final image quality, enabling lens designs that trade raw resolving power for manufacturability and then recover acutance through algorithmic reconstruction.
Glass-plastic hybrid stacks are fragmenting the traditional lens hierarchy by merging the thermal stability of molded glass with the aspheric complexity of injection-molded polymers. Flagship smartphone OEMs are adopting 1G6P and 2G5P configurations for primary wide cameras, compressing the premium formerly reserved for all-glass cinema lenses into sub-8mm z-height modules. This convergence is fragmenting supplier tiers as glass foundries acquire plastic molding capabilities and polymer houses backward-integrate into precision glass pressing.
REACH substance restrictions are forcing reformulation of anti-reflective and anti-smudge coatings across lens surfaces supplied into European end-markets. ECHA's evolving candidate list for Substances of Very High Concern now captures certain fluorinated compounds used in oleophobic layers, compelling deposition houses to qualify alternative chemistries. Module assemblers serving pan-European smartphone and automotive OEMs are consolidating coating qualification programs to reduce redundant testing cycles.
Buyer concentration among tier-one smartphone OEMs is compressing lens vendor negotiation leverage and accelerating specification harmonization. Procurement teams at flagship device manufacturers now mandate unified modulation transfer function curves and thermal drift tolerances across multi-source lens qualifications, eroding the differentiation that previously sustained price premiums for incumbent suppliers. This consolidation is most visible in South Korean and Chinese smartphone supply chains, where captive lens affiliates and independent module houses compete for allocation within rigid performance bands.
Camera Module Lens Market Segmentation
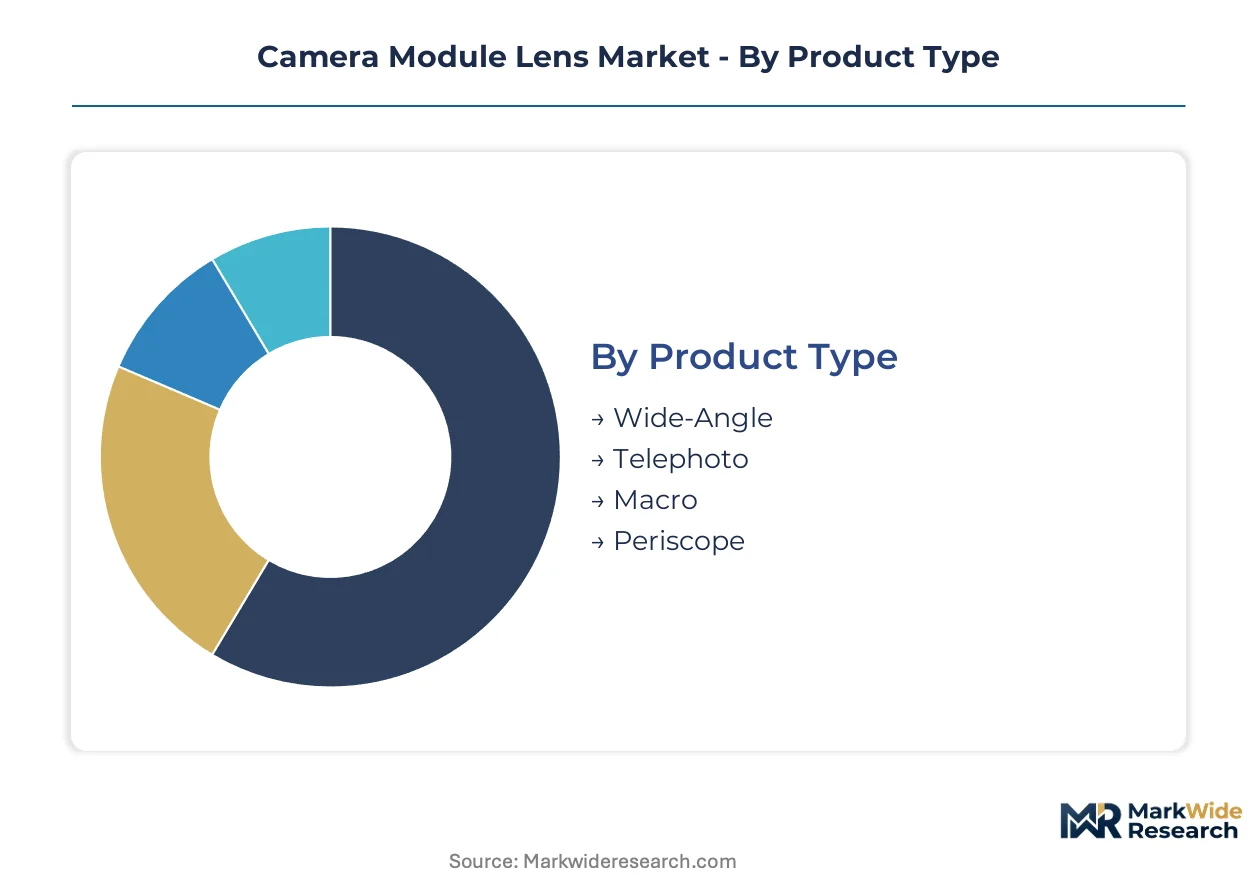
Camera module lens segmentation reveals how technical specifications map to divergent certification requirements and margin structures. Product type and material choices determine which regulatory frameworks govern qualification timelines and coating formulations.
Product Type:
MIIT imaging benchmarks in China and FCC electromagnetic rules in the United States apply differential stringency across optical configurations, with periscope and telephoto designs facing elevated scrutiny for integrated voice coil motors.
- Wide-Angle:These 5P and 6P lens stacks deliver expansive field-of-view coverage for primary smartphone cameras. Demand concentrates in Shenzhen and Gumi manufacturing corridors where flagship OEMs specify sub-8mm z-height modules with distortion correction below 2%.
- Telephoto:Longer equivalent focal lengths require tighter tolerances on element centration and air gaps. South Korean smartphone manufacturers drive adoption of 7P configurations with optical path lengths exceeding 15mm, subject to MIIT resolution verification for networked devices.
- Macro:Close-focus designs prioritize working distance and magnification ratio over absolute resolving power. Taichung-based module houses supply these into mid-tier smartphone tiers with relaxed thermal drift specifications.
- Periscope:Fold-optics architectures with prism-based light path redirection enable 5x–10x zoom without thickness penalties. These command premium positioning as glass foundries in Japan and Germany supply the critical borosilicate substrates.
Established volume favors Wide-Angle; emerging adoption favors Periscope.
Lens Material:
REACH substance restrictions in Europe fragment material selection, with rare-earth dopants and fluorinated coatings facing reformulation mandates that extend qualification cycles for coated and certain glass variants.
- Glass:Molded borosilicate and lanthanum-doped elements provide thermal stability and transmission efficiency for automotive and cinematic applications. Japanese melt houses in Osaka and German suppliers anchor premium substrate supply, exposing assemblers to allocation risk during demand spikes.
- Plastic:Injection-molded polymer lenses enable cost-scalable aspheric complexity for high-volume smartphone deployment. These dominate shipment volumes but exhibit focal length drift above 60°C, constraining use in automotive surround-view systems where NHTSA durability standards apply.
- Aspherical:Non-spherical surface profiles correct aberration in fewer elements, reducing stack height. Wafer-level molding expertise concentrates in Taichung, where diamond-turning capabilities differentiate tier-one suppliers from sub-scale competitors.
- Coated:Anti-reflective and oleophobic layers face ECHA constraints on perfluorinated compounds, forcing deposition houses to qualify alternative chemistries for European-bound modules.
Plastic captures dominant volume share; glass-plastic hybrid configurations are climbing the fastest as flagship OEMs adopt 1G6P and 2G5P stacks.
Application:
End-use concentration determines thermal rating requirements and regulatory jurisdiction, with automotive and security applications imposing stricter environmental testing than consumer mobile devices.
- Smartphones:Multi-lens array proliferation compresses design cycles and forces synchronization of glass molding, actuator assembly, and wafer-level optics. China's MIIT certification mandates higher resolution thresholds for networked imaging devices.
- Tablets:Larger device footprints accommodate longer optical path lengths but demand lower unit economics. Procurement teams specify relaxed modulation transfer function curves compared to flagship smartphone tiers.
- Security Cameras:Continuous operation requirements favor all-glass designs with extended temperature ratings. FCC equipment authorization governs electromagnetic compatibility for pan-tilt-zoom configurations with integrated autofocus motors.
- Drones:Weight constraints and vibration exposure prioritize compact, shock-resistant lens modules. Aviation regulatory frameworks in multiple jurisdictions impose additional electromagnetic interference testing beyond consumer device standards.
Smartphones anchor current revenue; automotive-derivative security and drone applications are gaining share fastest.
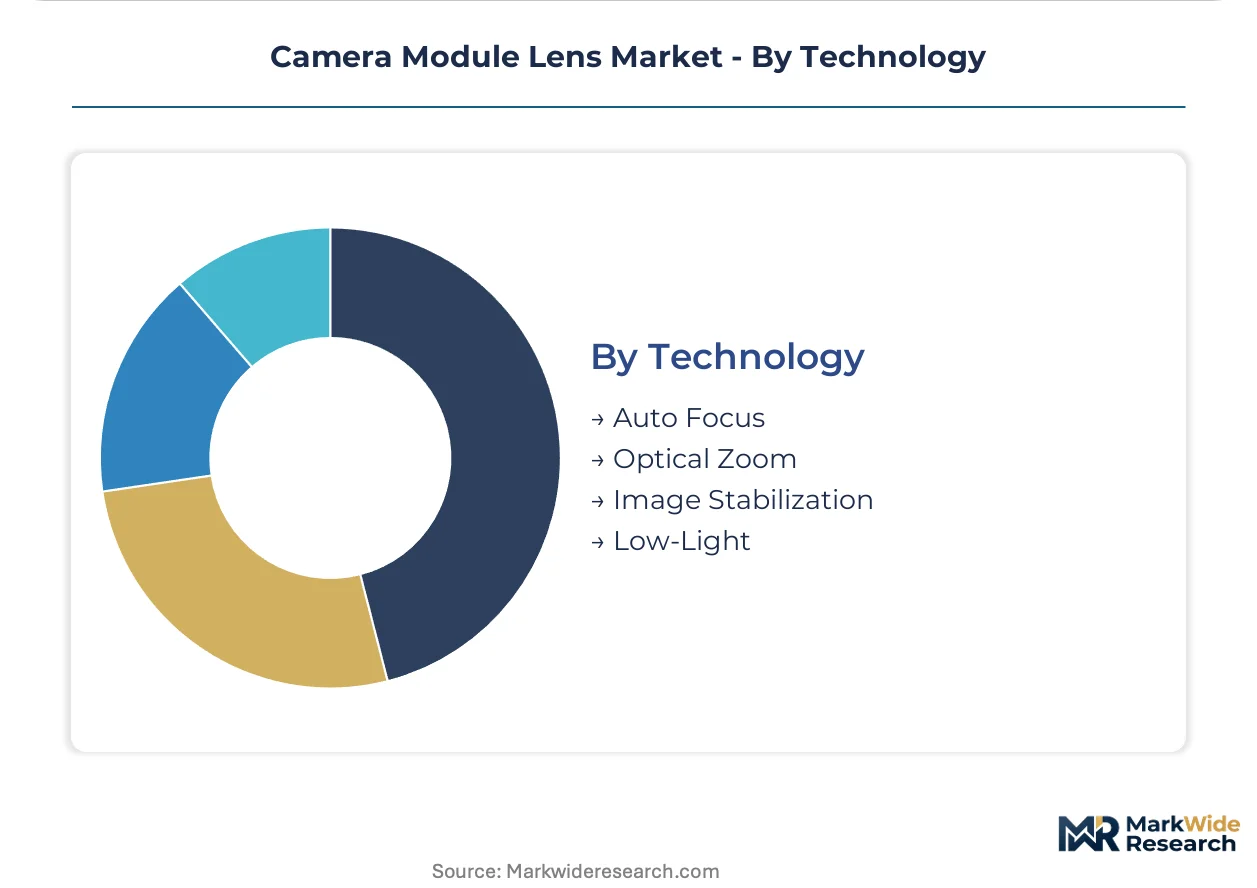
Technology:
Voice coil motor integration and computational-optics convergence differentiate technology tiers, with calibration requirements straining firmware capabilities at mid-tier lens houses.
- Auto Focus:Voice coil motor assemblies with closed-loop control algorithms achieve sub-micron repeatability. Magnetic field characterization requirements strain in-house capabilities, favoring suppliers with captive actuator production.
- Optical Zoom:True optical magnification through moving element groups maintains image quality across focal lengths. Periscope architectures represent the steepest expansion trajectory as fold-optics penetrate flagship tiers.
- Image Stabilization:Sensor-shift and lens-shift mechanisms compensate for hand tremor and vehicle vibration. Automotive qualification demands extended temperature operation beyond consumer mobile specifications.
- Low-Light:Large aperture designs and specialized glass formulations maximize photon collection. These command premium positioning where thermal stability and transmission efficiency outweigh material costs.
Auto Focus saturates smartphone volumes; Low-Light and Image Stabilization differentiate premium tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in camera module lenses tilt heavily toward East Asian manufacturing clusters, with China, South Korea, and Taiwan running structural surpluses while the United States and Germany absorb premium volumes through device assembly and automotive integration channels.
China
MIIT certification mandates for networked imaging devices compel domestic OEMs to source 7P and hybrid glass-plastic lens stacks from Shenzhen and Dongguan module houses. The Pearl River Delta concentrates wafer-level optics molding capacity, where foundries serve both local smartphone brands and export-bound contract manufacturers.
South Korea
Flagship smartphone OEMs in Gumi and Suwon specify periscope-grade optical zoom modules with integrated voice coil motors, driving captive demand for precision borosilicate substrates. MFDS-aligned quality protocols govern automotive camera qualifications for surround-view ADAS deployments.
Japan
METI standards for precision optics constrain anti-reflective coating formulations, forcing reformulation of rare-earth dopant chemistries in Osaka and Nagoya glass melt houses. Kyushu-based substrate suppliers anchor premium thermal-stability lens element production for cinematic and low-light applications.
Taiwan
Taichung diamond-turning capabilities differentiate tier-one aspherical lens suppliers from sub-scale competitors, with wafer-level molding expertise concentrated in central manufacturing corridors. Local module houses supply both consumer mobile and industrial imaging end-uses under divergent thermal rating specifications.
Germany
REACH substance restrictions from ECHA force European-bound lens modules to qualify alternative fluorinated coating chemistries, extending qualification timelines for deposition houses serving automotive OEMs in Stuttgart and Munich. Bavarian precision optics clusters specialize in all-glass designs for extended temperature ratings.
Camera Module Lens Market Competitive Landscape
Concentration sits with vertically integrated optical specialists and captive electronics affiliates. The vendor base stratifies across three tiers: glass foundries with in-house molding capacity, independent lens assemblers serving multi-source OEM programs, and module integrators combining optics with voice coil motor calibration. Competitive moves center on backward integration into precision glass pressing and geographic expansion into automotive-qualified manufacturing corridors.
Among East Asian specialists, Sunny Optical Technology, Largan Precision, and LG Innotek exemplify distinct strategic positions within the lens supply hierarchy. Sunny Optical Technology represents the vertically integrated archetype spanning glass molding through actuator assembly. Largan Precision occupies a position anchored in premium plastic-aspherical wafer-level expertise. LG Innotek sits within the captive supply tier, serving flagship smartphone OEMs through integrated module production. These three entities collectively illustrate how technical specialization and customer relationship configuration determine competitive positioning.
| Leading Market Players |
|---|
| Chicony Electronics |
| Lite-On Technology |
| Sunny Optical Technology |
| Largan Precision |
| Toshiba Corporation |
| Samsung Electro-Mechanics |
| Sharp Corporation |
| OFILM Group |
| LG Innotek |
| Others |
Pricing and Supply Chain Analysis
Wafer-level optics capacity utilization above 85% in Taichung and Shenzhen compresses margin floors for mid-tier lens assemblers while amplifying pricing power for diamond-turning specialists. Scale concentration in East Asian molding clusters forces buyers into long-term allocation contracts that embed volume-commitment penalties, tightening the feedback loop between supply scarcity and price rigidity.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the Camera Module Lens Market. Price differentiation rests on MIIT certification grade and glass-plastic hybrid content, with 7P periscope modules commanding substantial premiums over 5P wide-angle stacks. Pricing pressure stems from buyer consolidation among flagship smartphone OEMs mandating unified MTF curves across multi-source qualifications. Mid-tier smartphone manufacturers exhibit highest price sensitivity, while automotive ADAS integrators prioritize thermal rating over unit cost.
Supply Chain Analysis
Container availability constraints on the Shanghai-Rotterdam trade lane extend inbound logistics costs for European-bound borosilicate substrates. Supply concentrates in China, South Korea, and Taiwan for precision molding and actuator assembly, while Japan and Germany anchor premium glass melt capacity. Raw material dependencies include lanthanum-doped optical glass, rare-earth dopants, and fluorinated coating precursors facing REACH reformulation mandates. Single-source vulnerability at Japanese melt houses in Osaka exposes assemblers to allocation risk during demand spikes. Distribution runs through Shenzhen module houses to global smartphone OEM assembly facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Camera Module Lens Market rewards suppliers mastering closed-loop voice coil motor calibration and 300mm wafer-level molding—capabilities where qualified talent pools remain thin across Dongguan and Taichung manufacturing corridors.
For Market Incumbents: Consolidate captive supply relationships with flagship smartphone OEMs through dedicated 7P and periscope-grade production lines. Deepen backward integration into precision glass pressing to offset allocation risk at Japanese melt houses. Lock in multi-year coating qualification programs ahead of ECHA substance list expansions. For New Entrants and Emerging Players: Differentiate on automotive-qualified lens modules with extended temperature ratings above 85°C, where incumbent smartphone-focused suppliers exhibit thermal drift limitations. Target white-space demand in drone imaging and security camera surround-view configurations with relaxed MTF specifications. Pursue qualification partnerships with Tier 2 automotive module integrators seeking second-source optics. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among lens assemblers with captive voice coil motor production and multi-year OEM allocation contracts. Long-term viability favors entities bridging glass foundry and plastic molding capabilities under unified thermal management protocols. Monitor periscope penetration rates in mid-tier smartphone segments as inflection signal for margin pool expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Glass Pressing | Captive borosilicate supply from Osaka melt houses reduces allocation exposure during demand spikes. |
| Periscope Module Volume Scale-Up | Fold-optics qualification with MIIT resolution benchmarks opens flagship smartphone allocation. |
| Automotive Thermal Rating Certification | MFDS-aligned protocols for ADAS surround-view systems unlock twelve-unit vehicle configurations. |
| Coating Chemistry Reformulation | ECHA-compliant fluorinated alternatives qualify European-bound modules under REACH substance restrictions. |
| Wafer-Level Optics Capacity Expansion | 300mm diamond-turning deployment in Taichung differentiates tier-one suppliers from sub-scale competitors. |
Research Methodology
A spread of perspectives from optical design engineers, smartphone procurement directors, glass foundry operations managers, and automotive Tier 1 supplier quality leads converged on the working assumptions shaping this analysis. Primary fieldwork across Shenzhen, Gumi, and Taichung manufacturing corridors combined with secondary validation from MIIT certification databases, FCC equipment authorization filings, ECHA substance restriction updates, and SEC disclosures from listed lens assemblers. Bottom-up unit economics triangulated against top-down smartphone production forecasts anchored the volume projections.
Segmentation dimensions modeled span product type, lens material composition, application end-use, and technology integration across the projection horizon. CAGRs derived from historical shipment trajectories and OEM content-per-device roadmaps. Industry-specific forecast inputs include periscope adoption curves in flagship smartphone tiers and ADAS camera count expansion in automotive platforms.
Decision-makers should treat outputs as directional under assumptions of sustained MIIT imaging benchmark stringency and REACH substance list stability; material deviation would warrant model refresh. Specific risks include sudden borosilicate supply disruption, accelerated computational-optics substitution, or divergent regional certification timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Lasers Market
Optics
Global Semiconductor Lasers Market
Optics
Optical Fiber Market
Optics
Fiber-Optic Filters Market
Optics
AR and VR Lens Market
Optics
Advanced Optics Market
Optics
Global Fiber Optic Components Market
Optics
Fiber-Optic Couplers Market
Optics
India Laser Market
Optics
Global Super Hi Vision Market
Optics
Optical Liquid Level Sensor Market
Optics
Optical Telephoto Lens Market
Optics
Glass Scintillator Market
Optics
MEMS Mirrors Market
Optics
Asia Pacific Smartphone Camera Lens Market
Optics
Global Optical Lens Market