
 Europe Smart Glass Market | 2026-2036
Europe Smart Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Smart Glass Market Foresight
Commercial building owners are redrawing procurement priorities around dynamic glazing systems. Saint-Gobain leverages its integrated flat glass and coatings portfolio to dominate specification-driven projects across France and Benelux. AGC Glass Europe anchors regional supply through its specialized electrochromic production lines in Belgium. Smartglass International competes on project customization for heritage building retrofits where dimensional constraints limit standard product fit.
Europe smart glass encompasses electrically active glazing that modulates light transmission, thermal transmittance, or opacity in response to voltage, temperature, or light stimuli, typically achieving solar heat gain coefficients between 0.09 and 0.60 depending on tint state and coating stack. Electrochromic devices employ tungsten oxide and nickel oxide thin films separated by solid polymer electrolytes, enabling gradual opacity shifts over 3-5 minutes for precision daylight management in occupied spaces. The technology dimension shows polymer dispersed liquid crystal segments capturing premium margins in privacy applications, while nanotechnology-enabled coatings extend durability in automotive sunroofs. Architecture applications lead volume, though aerospace segments sustain higher per-unit pricing through FAA-EASA dual certification requirements.
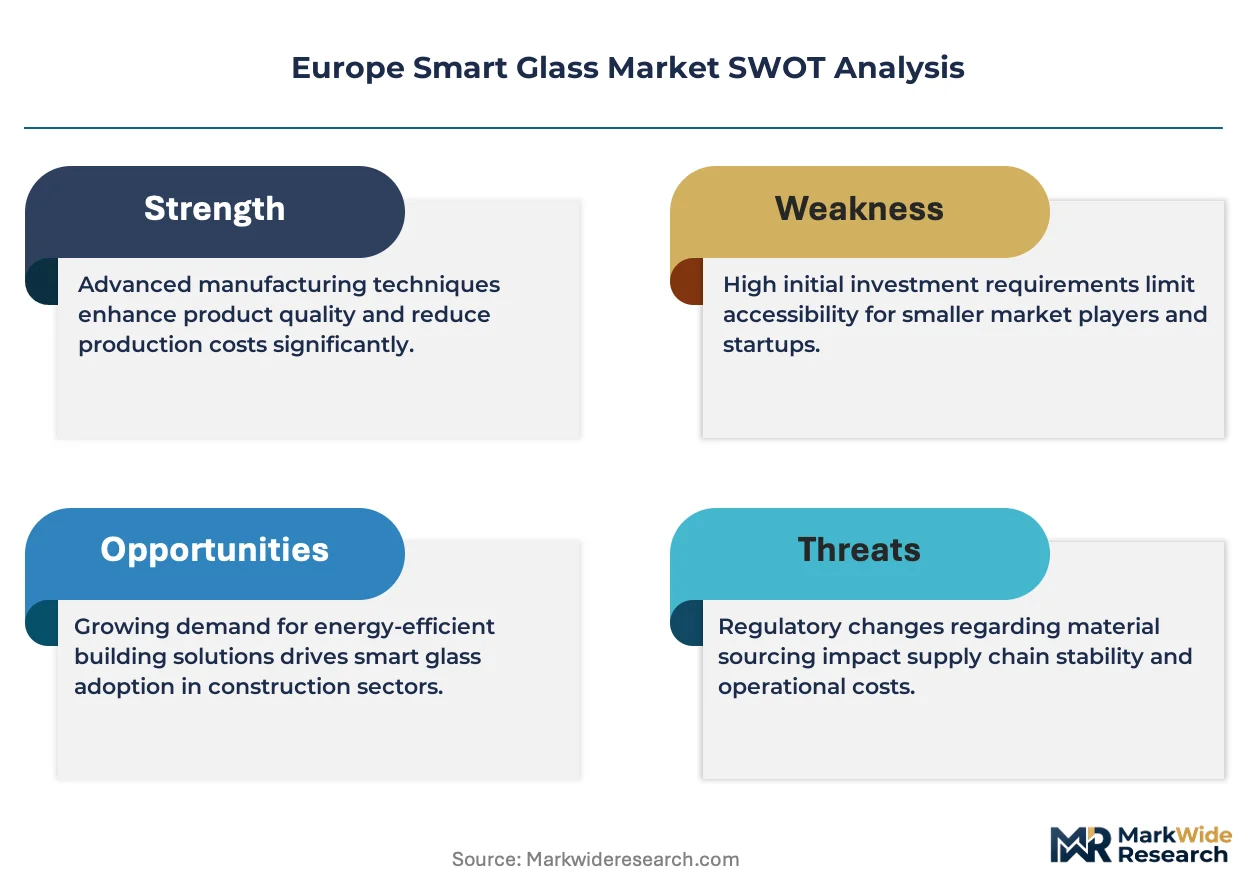
The EU Green Deal and Energy Performance of Buildings Directive mandate near-zero energy standards for new public buildings, directly accelerating electrochromic and SPD specification rates across Germany, France, and Nordic markets. ECHA REACH compliance governs the chromium and tungsten compounds used in electrochromic layers, adding material qualification costs that favor established suppliers with dedicated regulatory affairs teams. Stakeholders must monitor the F-Gas Regulation's phase-down trajectory, as suspended particle devices rely on encapsulated fluids with specific global warming potential thresholds that could trigger reformulation requirements or supply discontinuities.
Market Dynamics
The EU Energy Performance of Buildings Directive is compressing specification timelines for electrochromic glazing across member states, forcing developers to front-load smart glass procurement decisions before construction permits finalize.
Growth Catalysts
- EU Green Deal building mandates:Near-zero energy standards for new public buildings accelerate electrochromic specification rates across Germany, France, and Nordic markets. Municipal procurement offices now embed dynamic glazing into tender requirements.
- Net-zero commercial towers:Developers from Munich to Hamburg integrate electrochromic systems into facade engineering to meet thermal efficiency thresholds. Saint-Gobain and AGC Glass Europe anchor supply for these projects.
- Tungsten oxide thin-film advances:Solid-state electrochromic devices achieve faster tint-state transitions, reducing the 3-5 minute switching window that previously limited occupant acceptance in daylight-critical spaces.
Market Restraints
- ECHA REACH compliance costs:Chromium and tungsten compound qualification adds material testing overhead that disadvantages smaller suppliers without dedicated regulatory affairs teams.
- F-Gas Regulation phase-down:Suspended particle devices rely on encapsulated fluids with specific global warming potential thresholds, triggering reformulation requirements or supply discontinuities for fluid-dependent architectures.
- Polymer dispersed liquid crystal cost premiums:Privacy applications command higher per-square-meter pricing than electrochromic alternatives, limiting penetration in cost-sensitive renovation projects.
Strategic Opportunities
- Heritage building retrofits:Dimensional constraints in protected structures limit standard product fit, creating project-customization demand where Smartglass International competes against templated offerings.
- Aerospace certification dual-track:FAA-EASA certification requirements sustain premium pricing in aviation segments, with electrochromic sunroofs penetrating business jet and commercial aircraft refit cycles.
- Automotive SPD convergence:Suspended particle devices integrate with roof systems in electric vehicle platforms, leveraging nanotechnology-enabled coatings for durability in high-vibration environments.
Industry Challenges
- Electrolyte manufacturing talent scarcity:Solid polymer electrolyte production requires specialized thin-film deposition expertise concentrated in Belgium and northern France, constraining capacity expansion.
- Facade integration complexity:Building information modeling teams lack standardized protocols for coordinating electrochromic control systems with HVAC and lighting automation, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Smart Glass Market |
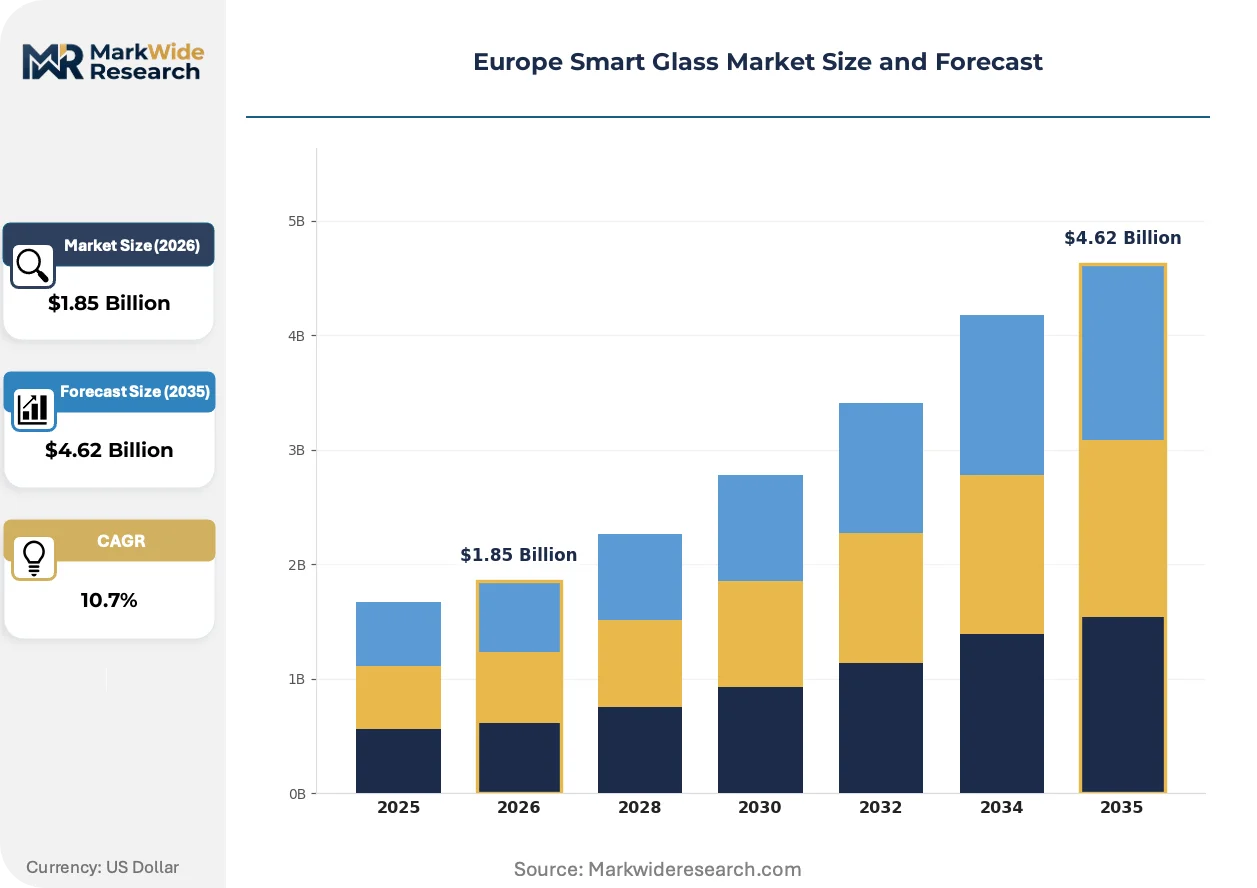
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.62 Billion |
| CAGR (2026 – 2036) | 10.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Thermochromic, Photochromic, SPD Technology: Nanotechnology, LCD, Polymer Dispersed Liquid Crystal, Electrochromic Application: Automotive, Architecture, Aerospace, Consumer Electronics End User: Residential, Commercial, Industrial, Transportation |
| Companies Covered | Saint-Gobain, PPG Industries, AGC Glass Europe, Smartglass International, EControl-Glas, Smartglass Technologies, Gentex Corporation, Polytronix Inc, RavenBrick LLC, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Smart Glass Market Shifts & Advancements
Electrochromic glazing is displacing conventional static low-E coatings as the default specification for premium commercial facades. Three convergent developments are compressing the technology adoption cycle across European construction markets.
Solid-state electrochromic devices with tungsten oxide-nickel oxide thin-film stacks are displacing liquid crystal alternatives in daylight management applications. German commercial developers specify these systems for net-zero office towers from Munich to Hamburg. The technology is displacing manual blind installations by embedding automated tint-state control directly into glazing units, eliminating the maintenance burden of mechanical shading systems.
The EU F-Gas Regulation is tightening global warming potential thresholds for encapsulated fluids in suspended particle devices. Manufacturers must reformulate or discontinue fluid-dependent product lines before phase-down deadlines. Belgian production facilities face the most acute compliance pressure, as SPD supply chains concentrate in the Benelux corridor.
Building owners now bundle glazing procurement with performance guarantees covering thermal transmittance and daylight autonomy metrics. French and Nordic markets lead this contracting evolution, with developers transferring operational risk to glazing suppliers through 15-year energy performance contracts. Specification decisions increasingly hinge on modeled energy savings rather than upfront capital cost.
Europe Smart Glass Market Segmentation
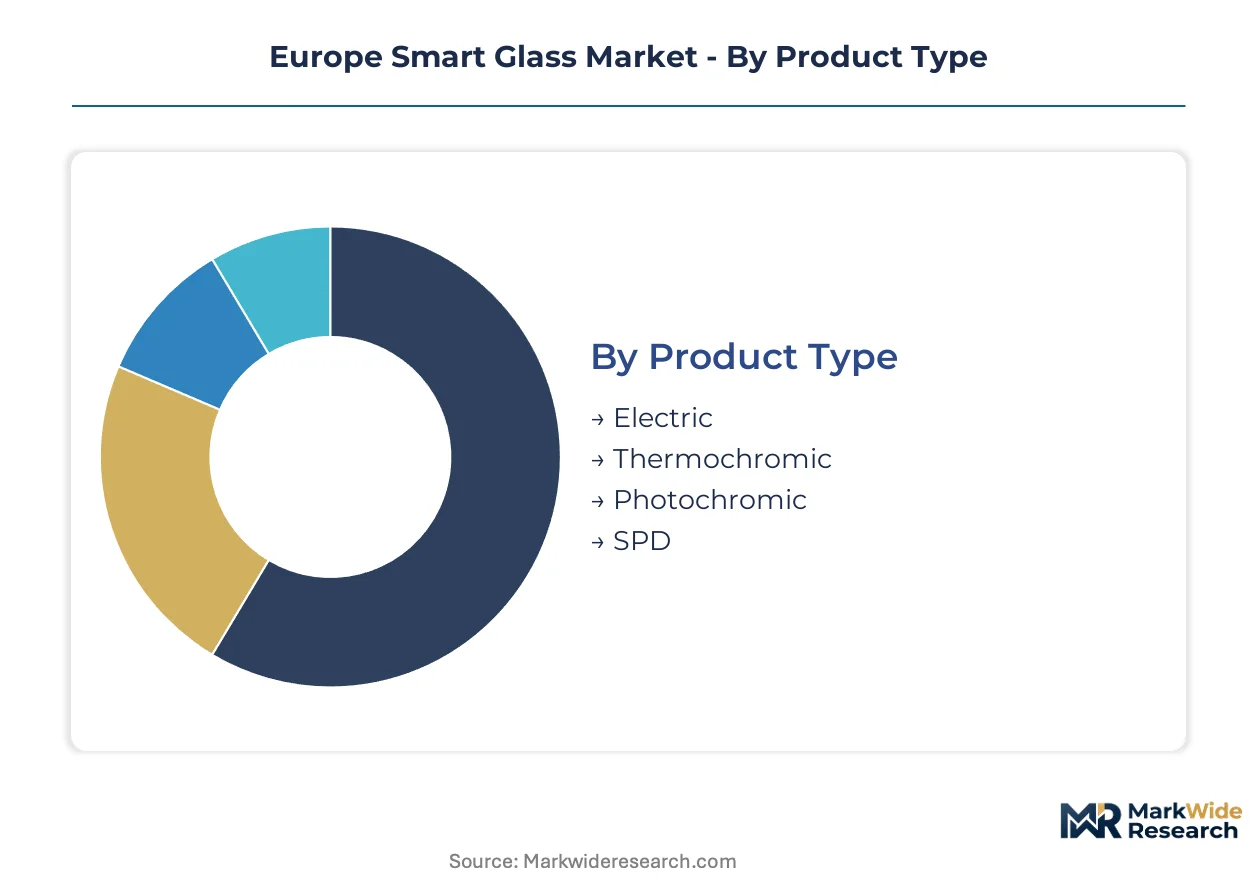
Smart glass procurement patterns diverge sharply across product architectures and end-use requirements. Specification engineers weight thermal modulation precision against switching speed, privacy opacity, and facade integration complexity when mapping technologies to building or vehicle programs.
Product Type:
Margin pools concentrate in electrically active systems where control precision commands premium specification, while passive alternatives compete on installation simplicity and maintenance elimination.
- Electric:Voltage-responsive glazing achieves tint-state modulation through external power input, enabling real-time automated control tied to daylight sensors and building management systems. German commercial developers specify these systems for net-zero office towers from Munich to Hamburg, transferring operational risk through 15-year energy performance contracts. The dominant share belongs to Electric, while SPD is closing the gap fastest.
- SPD:Suspended particle devices modulate opacity through encapsulated fluid orientation under electric field application, delivering near-instantaneous switching for automotive and aviation privacy applications. Belgian production facilities face acute F-Gas Regulation compliance pressure as reformulation deadlines approach.
- Thermochromic:Temperature-responsive coatings shift optical properties based on surface heat, eliminating wiring infrastructure for residential skylight retrofits.
- Photochromic:UV-triggered darkening suits eyewear and small-format consumer electronics where electrical connectivity is impractical.
Electric systems capture specification dominance in commercial architecture, while SPD penetrates fastest in electric vehicle roof integrations.
Technology:
Technology selection tracks end-use tolerance for switching latency, with architectural daylight management accepting gradual transitions that aviation and automotive segments reject.
- Electrochromic:Tungsten oxide-nickel oxide thin-film stacks separated by solid polymer electrolytes enable gradual opacity shifts over 3-5 minutes. French and Nordic markets lead contracting evolution as developers bundle glazing procurement with thermal transmittance and daylight autonomy guarantees. Electrochromic holds the installed base leadership, while Nanotechnology-enabled coatings are expanding share fastest through durability extensions.
- Nanotechnology:Coatings incorporating nanostructured materials extend device lifespan in high-vibration automotive sunroof environments and aerospace pressure cycling.
- Polymer Dispersed Liquid Crystal:Privacy-on-demand glazing commands per-square-meter premiums above electrochromic alternatives, limiting renovation penetration.
- LCD:Liquid crystal architectures deliver rapid switching for consumer electronics displays and instrument panels where refresh speed dominates thermal management.
Electrochromic retains the dominant specification share, though Nanotechnology-enabled durability solutions are climbing the fastest as automotive OEMs extend warranty requirements.
Application:
Application segmentation reflects divergent certification burdens and per-unit value concentration, with aviation sustaining premium pricing through dual-track FAA-EASA requirements.
- Architecture:Facade integration dominates volume as EU Green Deal mandates compress specification timelines for new public buildings across Germany, France, and Nordic markets. Architecture commands the volume leadership, while Aerospace is advancing fastest on per-unit value expansion.
- Aerospace:Electrochromic sunroofs penetrate business jet and commercial aircraft refit cycles, with certification complexity sustaining margin structures unavailable in construction.
- Automotive:Electric vehicle platforms integrate SPD roof systems, leveraging nanotechnology-enabled coatings for durability in high-vibration environments.
- Consumer Electronics:Small-format displays and adaptive eyewear drive unit volume at compressed price points.
Architecture absorbs the dominant capacity allocation, while Aerospace is gaining share fastest through extended OEM warranty programs.
End User:
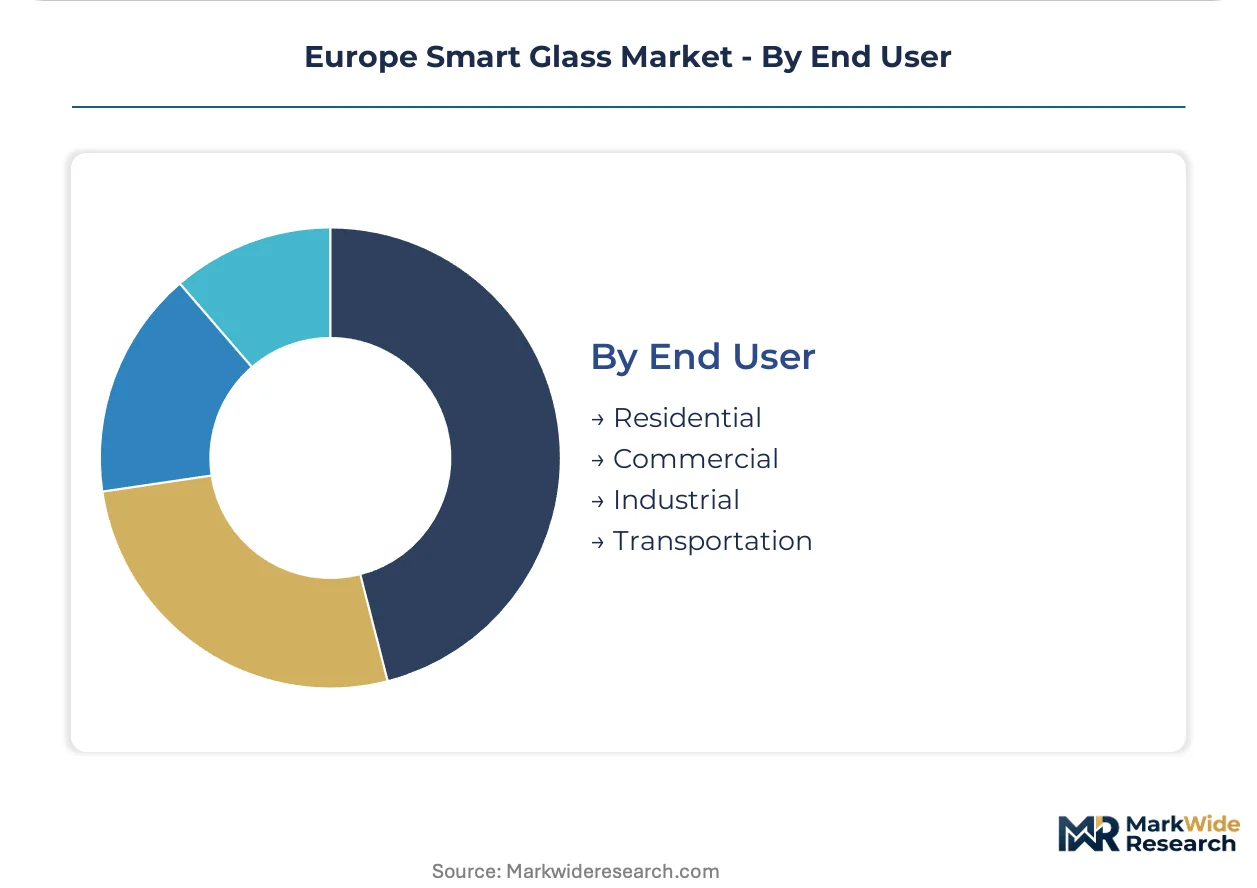
End user segmentation tracks procurement sophistication, with commercial developers transferring operational risk through performance contracts unavailable to residential purchasers.
- Commercial:Building owners bundle glazing with 15-year energy performance guarantees covering thermal transmittance and daylight autonomy metrics. Municipal procurement offices embed dynamic glazing into tender requirements under EU Green Deal implementation. Commercial holds the dominant share, while Transportation is expanding fastest.
- Transportation:Automotive OEMs and aviation retrofitters specify certified systems where durability testing exceeds architectural standards.
- Residential:Heritage building retrofits create project-customization demand where dimensional constraints limit standard product fit.
- Industrial:Manufacturing facilities deploy smart glazing for process control environments requiring precise thermal management.
Commercial procurement commands the dominant specification volume, while Transportation is climbing fastest as electric vehicle production scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube canal network underwrites Central European distribution efficiency for electrochromic glazing shipments moving between manufacturing clusters and construction sites.
Germany
Municipal procurement offices in Munich, Hamburg, and Frankfurt embed dynamic glazing into tender requirements under EU Green Deal implementation. The country's national building energy regulator enforces thermal efficiency mandates through the Building Energy Act. Bavaria's sustainable construction corridor concentrates specification activity where developers bundle glazing with 15-year performance guarantees.
France
Commercial developers in Paris and Lyon transfer operational risk to suppliers through energy performance contracts covering daylight autonomy metrics. The national environmental health and safety regulator governs chromium compound usage in electrochromic thin-film production. The Île-de-France region anchors specification-driven projects where Saint-Gobain leverages its integrated flat glass portfolio.
Netherlands
Port of Rotterdam logistics enable just-in-time delivery of electrochromic units to North Sea canal construction corridors. The national environmental assessment agency enforces REACH compliance protocols for tungsten oxide imports. Randstad urban agglomerations concentrate net-zero office tower development where facade integration complexity extends commissioning timelines.
Belgium
Benelux production facilities face acute F-Gas Regulation compliance pressure as reformulation deadlines approach for suspended particle device fluids. The national chemicals regulator oversees electrolyte manufacturing qualification for solid polymer deposition lines. Specialized electrochromic production concentrates in Flanders where thin-film expertise constrains capacity expansion.
Sweden
Nordic municipal procurement offices specify electrochromic systems for near-zero energy public buildings ahead of 2030 directive deadlines. The national chemicals agency enforces ECHA REACH protocols for nickel oxide thin-film imports. Stockholm's sustainable construction cluster drives premium specification rates where thermal transmittance guarantees command contracting premiums.
Europe Smart Glass Market Competitive Landscape
Concentration sits with diversified materials conglomerates controlling integrated flat glass and coatings supply chains. The vendor base organizes around three strategic archetypes: integrated building materials suppliers with specification-driven project access, specialized electrochromic technology developers with proprietary thin-film expertise, and regional fabrication specialists competing on project customization. Dominant competitive moves include capacity expansion in Benelux production corridors and strategic partnerships between glazing suppliers and building automation integrators.
Within the integrated materials tier, Saint-Gobain and AGC Glass Europe occupy positions where specification relationships with commercial developers transfer into tender advantages. Smartglass International exemplifies the project-customization archetype, competing where dimensional constraints in heritage retrofits limit standard product fit. These three entities anchor the competitive structure while smaller specialists concentrate on sub-segment applications.
| Leading Market Players |
|---|
| Saint-Gobain |
| PPG Industries |
| AGC Glass Europe |
| Smartglass International |
| EControl-Glas |
| Smartglass Technologies |
| Gentex Corporation |
| Polytronix Inc |
| RavenBrick LLC |
| Others |
Supply & Pricing Matrix
ECHA REACH compliance gates both supplier qualification and price differentiation simultaneously, as chromium and tungsten compound testing overhead favors established vendors with dedicated regulatory affairs teams while compressing margins for smaller entrants attempting to undercut on project bids.
Pricing Analysis
Volume-discount tiering structures separate specification-grade electrochromic systems from standard architectural glazing and economy-tier passive alternatives. Pricing stratifies across premium, standard, and economy tiers based on certification grade and customization level, with heritage retrofit projects commanding premiums for dimensional adaptation. Cost compression in the standard tier is intensifying because Belgian SPD manufacturers face F-Gas Regulation reformulation deadlines. Municipal procurement offices exhibit lowest price sensitivity due to 15-year performance guarantee requirements, while residential renovators remain most cost-constrained.
Supply Chain Analysis
Inventory lead times for solid polymer electrolytes extend commissioning timelines as thin-film deposition expertise concentrates in Belgium and northern France. Manufacturing draws from tungsten oxide feedstocks sourced from Germany and Austria, nickel oxide from Nordic suppliers, and specialized polymer electrolytes from Benelux chemical corridors. Single-source vulnerability sits with Flanders-based electrolyte production lines where talent scarcity constrains capacity expansion. Distribution runs through Rhine-Main-Danube canal networks linking production clusters to Munich-Hamburg construction corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal implementation fragments procurement across member-state regulatory timelines, creating niche opportunities for specialists who align certification pathways with local building permit deadlines.
For Market Incumbents: Secure specification relationships with municipal procurement offices in Germany and France before tender requirements crystallize. Anchor capacity expansion in Flanders to capture electrolyte manufacturing scarcity premiums. Defend against emerging nanotechnology coating specialists by embedding durability guarantees into 15-year energy performance contracts. For New Entrants and Emerging Players: CE marking fast-track through notified bodies in the Netherlands accelerates market access for heritage retrofit specialists. Target Sweden and Finland where near-zero energy public building mandates outpace established supply capacity. Pursue project-customization angles where dimensional constraints in protected structures limit templated offerings. For Investors and Strategic Acquirers: The 2030 F-Gas Regulation phase-down deadline reshapes the acquisition landscape toward fluid-independent electrochromic architectures. Five-to-ten-year viability favors thin-film deposition specialists with captive electrolyte supply or nanotechnology-enabled durability platforms. Watch Belgian regulatory enforcement intensity as the inflection signal for SPD supply discontinuities.| Strategic Initiative | Industry Significance |
|---|---|
| Electrolyte Manufacturing Scale-Up | Flanders capacity expansion captures scarcity premiums as REACH compliance barriers deepen. |
| Backward Integration into Tungsten Oxide | Upstream control over electrochromic feedstocks insulates margin pressure from commodity volatility. |
| Heritage Building Certification Program | Specialized dimensional adaptation protocols unlock protected-structure retrofit demand. |
| Building Automation Integration Partnership | HVAC control system coordination addresses facade commissioning complexity extending timelines. |
| Aerospace Dual-Certification Investment | FAA-EASA pathway sustains premium pricing unavailable in construction procurement. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ECHA regulatory filings, EU construction permit databases, and Benelux chemicals trade data, combining interviews with facade engineers, municipal procurement officers, electrolyte manufacturing directors, and building automation integrators with bottom-up and top-down triangulation across product architecture and end-use segments.
Segmentation dimensions modeled include technology type, application vertical, end-user procurement sophistication, and regional regulatory cluster across the projection horizon. CAGRs derive from installed base evolution and replacement cycle analysis, incorporating EU Energy Performance of Buildings Directive compliance timelines and F-Gas Regulation phase-down trajectories as structural demand drivers.
Underlying assumptions cover REACH enforcement consistency and construction permit issuance rates, with deviation risk concentrated in Belgian regulatory interpretation variance and electrolyte manufacturing talent pipeline constraints. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Lasers Market
Optics
Smartphone Lenses Market
Optics
Camera Module Lens Market
Optics
Global Semiconductor Lasers Market
Optics
Fiber Optic Development Tools Market
Optics
Optical Telescope Market
Optics
Optical Microscope Market
Optics
Asia Pacific Smartphone Camera Lens Market
Optics
Anti Glare Film Market
Optics
Fiber Optic Cable Market
Optics
Optical Receivers Market
Optics
Fixed Focal Length Lenses Market
Optics
Optical Profilometer Market
Optics
Excimer Lasers for DUV Lithography Market
Optics
Global Fiber Optic Sensors Market
Optics
Quartz Glass Market