
 Distributed Fiber Optic Sensor (DFOS) Market | 2026-2036
Distributed Fiber Optic Sensor (DFOS) Market Size, Share, and Industry Trends Forecast 2026-2036
Distributed Fiber Optic Sensor (DFOS) Market Analytics
Aftermarket service revenue is fragmenting across hardware-software bundles and pure analytics subscriptions. Schlumberger Limited leverages its integrated drilling-services footprint to bundle DFOS installations with well-intervention contracts. Halliburton anchors its position through fiber-enabled fracture monitoring tied to its pressure-pumping operations. Baker Hughes competes by extending its turbomachinery diagnostics platform to include distributed temperature sensing for pipeline integrity.
Distributed Fiber Optic Sensor systems employ standard or specialty single-mode fibers to detect temperature, strain, acoustic, and pressure variations along cable lengths extending tens of kilometers, with spatial resolutions down to one meter depending on the interrogator unit. The primary industrial purpose is continuous, real-time structural and environmental monitoring across infrastructures where point sensors prove impractical or cost-prohibitive. Temperature sensors dominate current deployment volumes in oil and gas and power cable monitoring, while acoustic sensors represent the fastest-expanding category as pipeline operators adopt fiber-optic leak detection to satisfy tightening methane regulations. Rayleigh scattering technology leads in civil infrastructure applications for distributed vibration sensing on bridges and railways, whereas Brillouin scattering commands premium positioning in geotechnical and dam safety markets requiring simultaneous temperature and strain measurement.
The US Department of Transportation PHMSA pipeline safety rules and the EU F-Gas Regulation shape product certification requirements and deployment timelines for methane leak detection systems. China's GB standards for fiber optic sensing in tunnel safety and Japan's METI energy infrastructure resilience guidelines further define technical compliance thresholds for equipment suppliers. Stakeholders must monitor how regulatory divergence between North American performance-based rules and European prescriptive standards influences R&D allocation and regional product roadmaps.
Market Dynamics
Permian Basin operators and Gulf Coast LNG terminals are consolidating DFOS procurement around integrated service contracts that bundle hardware deployment with real-time analytics, compressing vendor margins while locking in multi-year monitoring agreements.
Growth Catalysts
- IEC 61757 certification requirements:Oil and gas pipeline operators now mandate certified fiber optic sensors for subsea leak detection, accelerating replacement of legacy point-sensor networks.
- EU Green Deal methane rules:European energy infrastructure operators face binding emissions reduction timelines that fiber-optic distributed acoustic sensing satisfies more cost-effectively than satellite monitoring.
- Brillouin scattering advances:Simultaneous temperature and strain measurement capabilities are displacing separate sensor installations in dam safety and geotechnical monitoring applications.
Market Restraints
- Specialty fiber input concentration:High-purity germanium-doped preform supply concentrates among three Asian manufacturers, creating vulnerability to export restriction shocks.
- Interrogator unit technical ceiling:Spatial resolution below one meter requires prohibitively expensive ultra-fast photon counting hardware that limits adoption in precision manufacturing.
- F-Gas Regulation compliance friction:European sensor deployments face extended certification timelines when refrigerant-based cooling systems in interrogator units fall under phasedown schedules.
Strategic Opportunities
- India tunnel safety mandates:GB standards adoption in Himalayan infrastructure projects creates first-mover positioning for DFOS vendors establishing local calibration facilities.
- Offshore wind cable monitoring:Subsea array interconnection failures drive demand for distributed temperature sensing across North Sea and Baltic installations.
- AI-photonics convergence:Machine learning inference at the interrogator edge is virtualizing cloud analytics, enabling real-time pattern recognition without latency penalties.
Industry Challenges
- Photonics engineering talent scarcity:DFOS system design requires rare cross-training in optical physics and signal processing that universities produce insufficiently.
- Legacy SCADA integration complexity:Brownfield industrial sites operate proprietary protocols that demand costly middleware development for fiber sensor data ingestion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Distributed Fiber Optic Sensor (DFOS) Market |
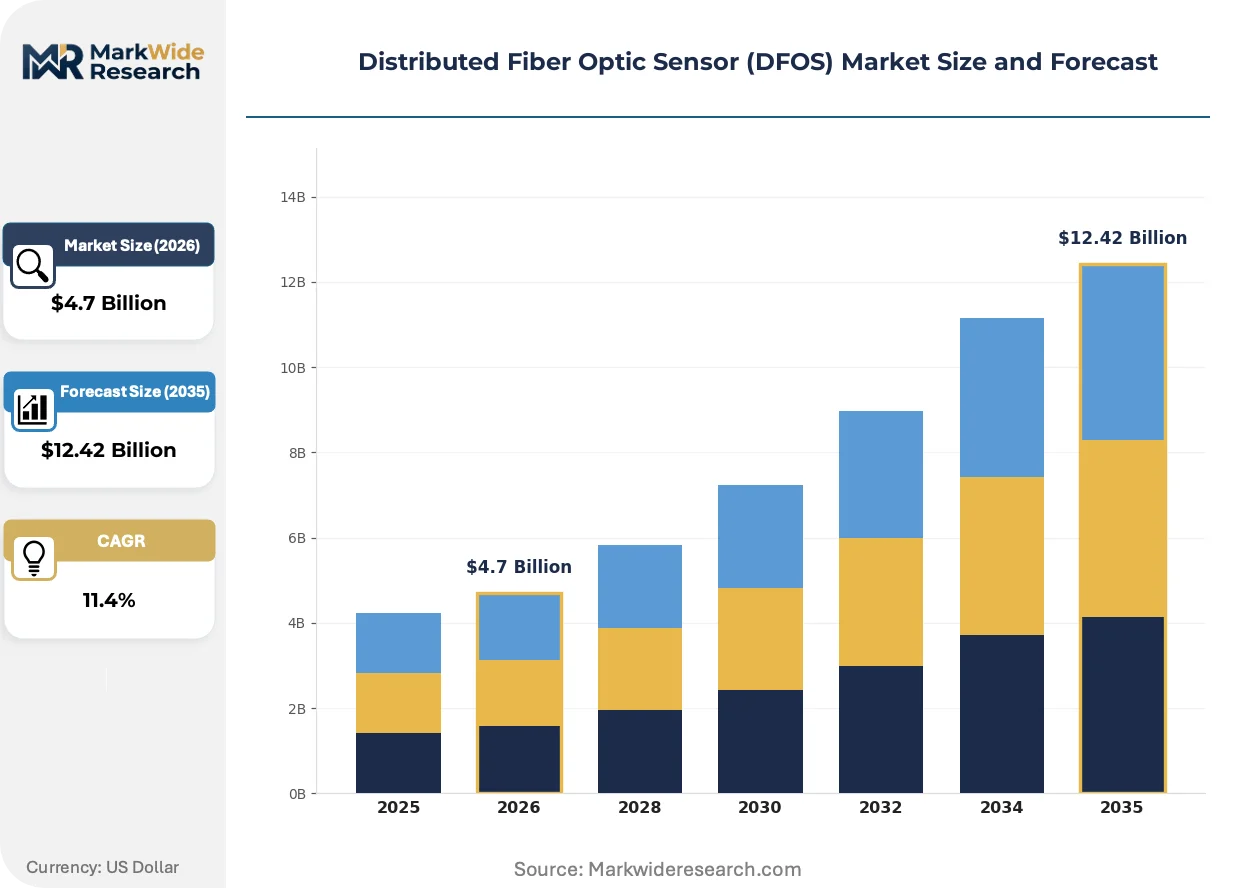
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $12.42 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temperature Sensors, Strain Sensors, Acoustic Sensors, Pressure Sensors Technology: Rayleigh Scattering, Brillouin Scattering, Fabry-Perot Interferometry, Raman Scattering Application: Civil Infrastructure Monitoring, Oil & Gas Exploration, Environmental Monitoring, Defense & Security End User: Energy Sector, Manufacturing, Transportation, Telecommunications |
| Companies Covered | Schlumberger Limited, Halliburton, Baker Hughes, Yokogawa Electric Corporation, Luna Innovations, OFS Fitel, AP Sensing, Omnisens, Weatherford, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Distributed Fiber Optic Sensor (DFOS) Market Evolving Landscape
Machine learning inference is migrating from cloud servers to edge interrogator units, compressing response latency for leak detection while reducing bandwidth costs. This shift is redrawing competitive boundaries between hardware manufacturers and analytics software providers.
Rayleigh-based distributed vibration sensing is virtualizing traditional accelerometer networks on bridges and railways. Civil engineering contractors in Germany and Japan are adopting single-mode fiber installations during concrete pouring, embedding structural health monitoring at marginal incremental cost. The technology is compressing the addressable market for conventional wired sensor systems.
The EPA's updated methane emissions detection mandates under the Inflation Reduction Act are forcing pipeline operators to demonstrate continuous monitoring coverage. Midstream companies in Texas and Louisiana are responding by specifying DFOS cables with 24/7 acoustic signature recognition, prioritizing regulatory audit trails over capital cost minimization.
Aftermarket service unbundling is fragmenting vendor relationships. Large oilfield service buyers now separate hardware procurement from analytics subscriptions, pitting Schlumberger's integrated bundles against pure-play software vendors. This behavior is most visible among Permian Basin independents optimizing vendor management overhead.
Distributed Fiber Optic Sensor (DFOS) Market Segmentation
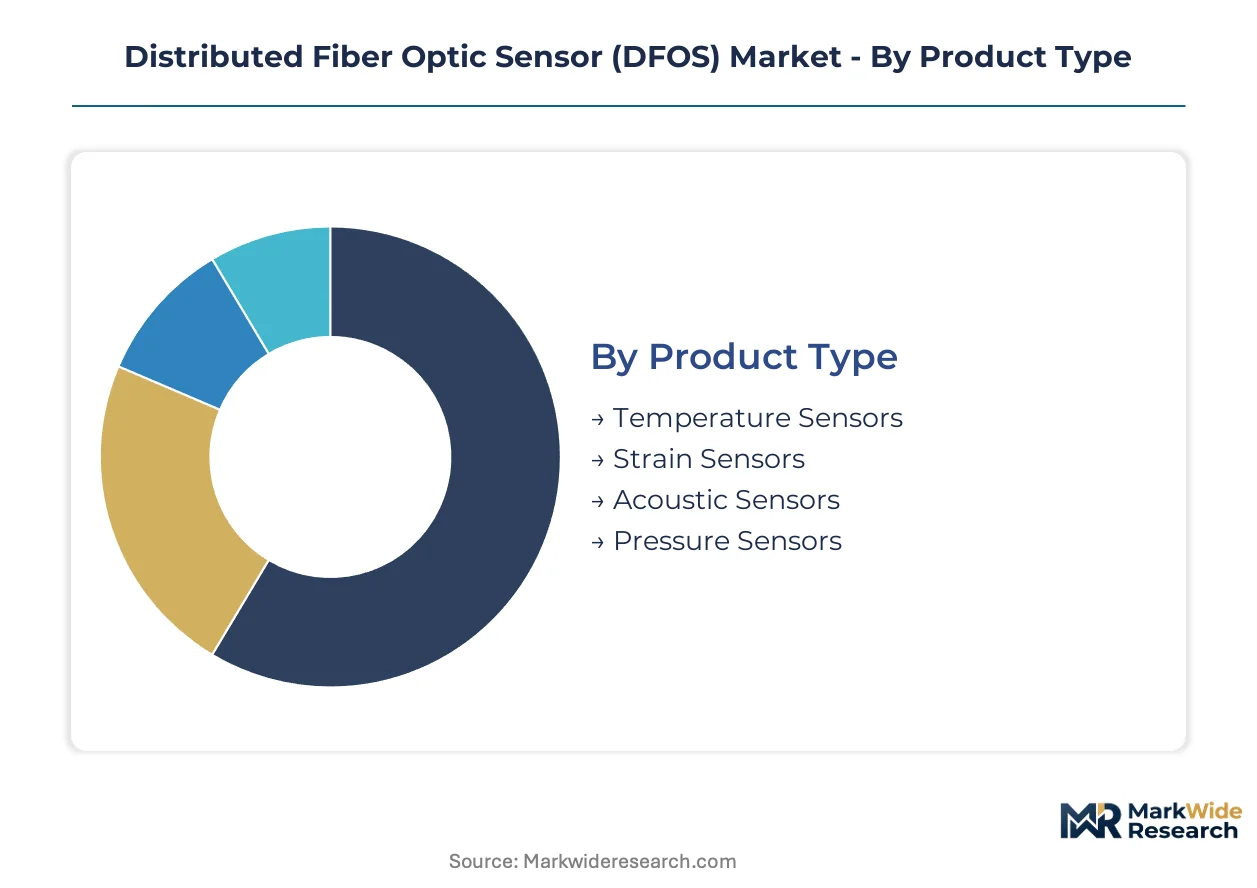
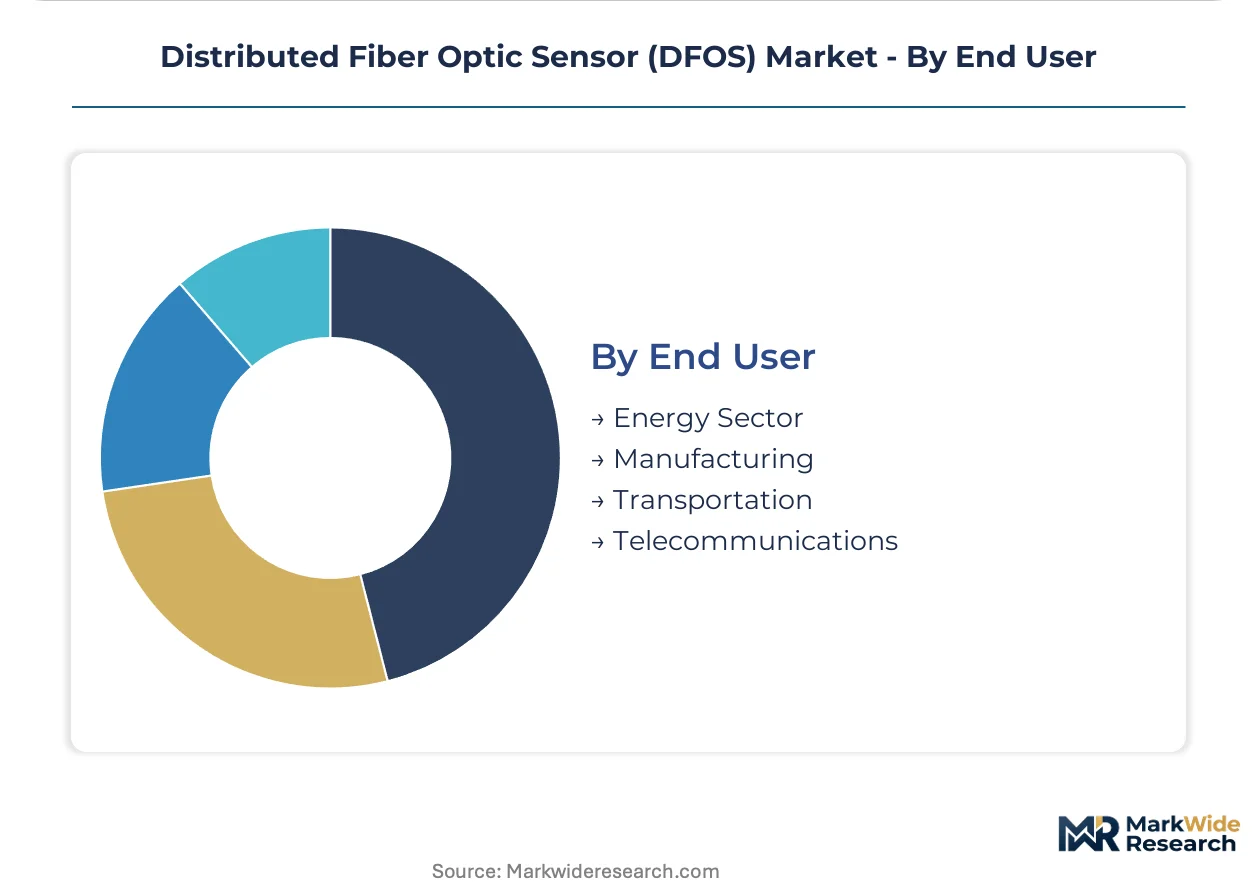
Segmentation in the DFOS market determines service contract structures and margin capture. Hardware-software bundles command premium pricing in oil and gas, while pure analytics subscriptions fragment vendor relationships. Understanding where each segment concentrates procurement power shapes effective market entry.
Product Type:
After-sales service intensity varies sharply across sensor types, with temperature and acoustic platforms requiring continuous calibration support.
- Temperature Sensors:Standard single-mode fibers detect thermal gradients along cable lengths extending tens of kilometers. Permian Basin operators and Gulf Coast LNG terminals drive the largest procurement volumes as IEC 61757 certification mandates displace legacy point-sensor networks.
- Acoustic Sensors:Distributed acoustic sensing converts fiber cables into continuous vibration detectors through coherent Rayleigh backscatter analysis. Pipeline operators in Texas and Louisiana specify 24/7 acoustic signature recognition to satisfy EPA methane detection mandates under the Inflation Reduction Act.
- Strain Sensors:Brillouin scattering-based strain measurement serves dam safety and geotechnical monitoring in Germany and Japan.
- Pressure Sensors:Fabry-Perot interferometry enables high-precision downhole pressure monitoring for well-intervention contracts.
Temperature sensors hold the largest share; momentum sits with acoustic sensors.
Technology:
Cost tiers separate mature scattering methods from premium interferometric approaches, with deployment scale determining unit economics.
- Rayleigh Scattering:Coherent optical time-domain reflectometry enables distributed vibration sensing across civil infrastructure. German and Japanese contractors embed single-mode fibers during concrete pouring for bridge and railway monitoring at marginal incremental cost.
- Brillouin Scattering:Simultaneous temperature and strain measurement through spontaneous Brillouin frequency shift analysis commands premium positioning. Dam safety applications in China and geotechnical projects across the Himalayan region require this dual-parameter capability.
- Fabry-Perot Interferometry:Cavity-based sensing delivers point-precision pressure measurement for subsea wellheads.
- Raman Scattering:Temperature-only sensing through anti-Stokes intensity ratio provides cost-effective solutions for power cable thermal monitoring.
Rayleigh scattering dominates civil infrastructure; Brillouin scattering gains share fastest in safety-critical applications.
Application:
Customer type concentration differs by application maturity, with oil and gas consolidating procurement while environmental monitoring fragments.
- Oil & Gas Exploration:Integrated service contracts bundle DFOS hardware with real-time analytics, compressing vendor margins while locking in multi-year monitoring agreements. Permian Basin independents now separate hardware procurement from software subscriptions to optimize vendor management overhead.
- Civil Infrastructure Monitoring:Single-mode fiber installation during construction embeds structural health monitoring at marginal cost. German and Japanese engineering specifications increasingly mandate fiber inclusion in concrete pouring phases.
- Environmental Monitoring:Methane leak detection specifications under EPA and EU Green Deal rules drive specification of distributed acoustic sensing over satellite alternatives.
- Defense & Security:Perimeter intrusion detection and border monitoring applications require classified certification pathways.
Oil and gas exploration holds the largest share; civil infrastructure monitoring climbs the fastest as construction-phase embedding standardizes.
End User:
Supply concentration in specialty fiber preforms creates divergent procurement risk profiles across end-user sectors.
- Energy Sector:Pipeline operators and LNG terminal developers consolidate procurement around integrated monitoring contracts. Gulf Coast infrastructure projects specify certified sensors for subsea leak detection under PHMSA safety rules.
- Transportation:Railway and highway authorities adopt distributed vibration sensing for structural health monitoring. Japanese and German rail operators lead standardization of fiber-embedded concrete specifications.
- Manufacturing:Precision process monitoring applications face spatial resolution constraints below one meter.
- Telecommunications:Existing fiber infrastructure repurposing for sensing creates hybrid service opportunities.
The energy sector holds the largest share; transportation gains share fastest through infrastructure embedding mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Permian Basin operators demonstrate the lowest price elasticity, absorbing bundled service premiums for certified leak detection, while European independents negotiate aggressively on hardware margins to preserve analytics flexibility.
United States
PHMSA pipeline safety rules and EPA methane mandates under the Inflation Reduction Act drive specification of 24/7 acoustic monitoring systems. Gulf Coast LNG terminal developers consolidate procurement around multi-year integrated contracts. Houston-based midstream operators embed DFOS cables during new construction to satisfy regulatory audit requirements.
Germany
Railway authorities mandate fiber-embedded concrete specifications for bridge and tunnel projects, creating construction-phase demand. EU F-Gas Regulation compliance timelines extend certification for refrigerant-cooled interrogator units. Engineering contractors in Bavaria standardize Rayleigh-based vibration sensing across Autobahn infrastructure monitoring.
China
GB standards for tunnel safety in Himalayan infrastructure projects accelerate DFOS deployment. MIIT industrial guidance prioritizes domestic fiber optic sensing capabilities. State-owned pipeline operators in Sichuan-Chongqing specify Brillouin scattering systems for geotechnical monitoring of high-pressure gas transmission routes.
Japan
METI energy infrastructure resilience guidelines define technical thresholds for sensor certification. Shinkansen rail operators embed distributed vibration sensing during track renewal programs. Engineering clusters in Nagoya-Chubu region integrate fiber monitoring into seismic-resistant building specifications.
United Kingdom
North Sea offshore wind cable interconnection failures drive distributed temperature sensing demand. The country's national energy regulator mandates continuous subsea monitoring for export cable arrays. Aberdeen-based marine contractors specify certified sensors for floating wind foundation integrity programs.
Distributed Fiber Optic Sensor (DFOS) Market Competitive Landscape
Integrated oilfield service providers and pure-play fiber sensing specialists split the market along the hardware-software boundary. Market structure concentrates procurement leverage among Permian Basin operators and Gulf Coast LNG developers who negotiate bundled multi-year agreements. Three archetypes dominate: full-service energy contractors, dedicated photonics hardware manufacturers, and analytics-software pure-plays. Competitive moves center on strategic partnerships to bridge capability gaps and geographic expansion into India and offshore wind markets.
Within the integrated services tier, Schlumberger Limited and Halliburton exemplify archetypes that leverage drilling-services footprints to bundle DFOS installations with broader well-intervention contracts. Baker Hughes occupies a position spanning turbomachinery diagnostics and pipeline integrity sensing. These three anchors represent how energy-sector incumbents defend positioning through customer relationship density rather than photonics specialization alone.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Halliburton |
| Baker Hughes |
| Yokogawa Electric Corporation |
| Luna Innovations |
| OFS Fitel |
| AP Sensing |
| Omnisens |
| Weatherford |
| Others |
Value Network & Pricing Analysis
Shanghai-to-Rotterdam maritime freight corridors govern landed cost differentials for germanium-doped fiber preforms, compressing margins for European interrogator manufacturers while amplifying price premiums for certified sensor bundles in North American oilfield contracts.
Pricing Analysis
After-sales service revenue tiers anchored by multi-year calibration contracts drive lifetime value capture across the installed base. Hardware-software bundles command three-tier pricing structure across premium, standard, and economy levels, with IEC 61757 certification grade and real-time analytics inclusion serving as primary price differentiation drivers. Pricing pressure stems from Permian Basin operators unbundling procurement to optimize vendor management overhead. Integrated service buyers demonstrate lowest price sensitivity, while pure hardware purchasers negotiate aggressively on unit costs.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk assessment for specialty fiber inputs. High-purity germanium-doped preform manufacturing concentrates in China, Japan, and South Korea, with rare-earth processing and photonics-grade silica drawing serving as critical component dependencies. Single-source vulnerability persists for ultra-fast photon counting modules used in sub-meter resolution interrogators. Distribution runs through direct OEM relationships for oilfield service tiers and regional systems integrators for civil infrastructure deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cross-training scarcity in optical physics and signal processing constrains system design capacity, creating asymmetric value capture for employers retaining photonics engineering talent.
For Market Incumbents: Insulate margin positions by deepening backward integration into specialty fiber preform supply and securing captive calibration facility networks in Gulf Coast logistics hubs. The unbundling threat from Permian Basin independents demands defensive certification investments to lock in analytics subscription retention. Priority lever rests on multi-year integrated service contracts that embed hardware replacement cycles. For New Entrants and Emerging Players: Himalayan infrastructure corridors in India represent the most penetrable geographic white space, with GB standards adoption creating first-mover calibration facility requirements. Offshore wind cable monitoring across North Sea installations offers second entry vector through distributed temperature sensing specialization. Go-to-market execution should anchor on partnerships with marine contractors holding floating wind foundation contracts. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors analytics-software pure-plays with edge-AI inference capabilities virtualizing cloud dependencies. Long-term viability hinges on interrogator unit architectures enabling real-time pattern recognition without latency penalties. Acquisition target archetype combines photonics hardware heritage with machine learning engineering density. Signal to watch: EPA enforcement intensity under Inflation Reduction Act methane mandates accelerating replacement demand cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-AI Integration | Machine learning inference at interrogator units reduces bandwidth costs for Permian operators. |
| Certification Pre-Positioning | IEC 61757 compliance investment locks in oilfield service contract renewals against unbundling. |
| Backward Integration | Germanium-doped preform captive supply insulates margin from Asian export restriction shocks. |
| Geographic Expansion | Local calibration facilities in India capture Himalayan tunnel safety mandate timing. |
| Platform Extension | Turbomachinery diagnostics heritage extends into pipeline integrity sensing for LNG terminals. |
Research Methodology
Operator-level perspectives from pipeline integrity engineers, photonics system architects, LNG terminal procurement leads, and civil infrastructure project managers anchored the qualitative base. Primary interview data combined with secondary validation from IEC standards documentation, EPA enforcement disclosures, PHMSA incident reports, and EU Green Deal implementation guidance. Bottom-up deployment volume estimates triangulated against top-down energy infrastructure capex trajectories.
Scenario-bracketing around regulatory enforcement intensity and specialty fiber supply disruption anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include sensor type, scattering technology, application vertical, and end-user sector procurement concentration. CAGRs derived from installed base expansion rates and replacement cycle acceleration under methane detection mandates. Forecast inputs incorporated interrogator unit cost curves and AI-photonics convergence adoption thresholds.
Practitioners should monitor IEC 61757 certification timeline extensions, F-Gas Regulation refrigerant phasedown impacts on interrogator cooling systems, and export restriction announcements for germanium-doped preforms as early signals for forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
North America Optical Film Market
Optical Components
North America Lithium Niobate Modulator Market
Optical Components
Ring Panel Filters Market
Optical Components
Optical Fiber and Plastic Conduit Market
Optical Components
Polarizer Film Market
Optical Components
Asia-Pacific Optical Film Market
Optical Components
Passive Optical Component Market
Optical Components
Optical Position Sensors Market
Optical Components
Photointerrupter Market
Optical Components
Europe Optical Imaging Market
Optical Components
Spectroradiometers Market
Optical Components
Liquid Light Guides Market
Optical Components
Optical Modulators Market
Optical Components
Silicon Photonics Market
Optical Components
Optical Image Stabilization (OIS) Actuators Market
Optical Components
Co-Packaged Optics Market