

Acousto Optical Cavity Dumper Market Size, Share, and Industry Trends Forecast 2026-2036
Acousto Optical Cavity Dumper Market Insights
Asset-light leasing arrangements for high-value acousto-optic modulators is tilting competitive dynamics toward firms that can bundle service contracts with hardware access. Gooch & Housego leverages its vertical integration in tellurium dioxide crystal growth to control input costs. Isomet Corporation anchors its position through specialized RF driver electronics that pair with cavity dumper heads. Coherent competes across the full laser systems stack, extending its reach into downstream micromachining workflows.
An acousto optical cavity dumper is a Q-switching device that uses a piezoelectric transducer to launch ultrasonic waves through an optical crystal, creating a diffraction grating that extracts stored cavity energy in nanosecond pulses. The device operates at RF frequencies typically between 40 MHz and 200 MHz, with tellurium dioxide and fused silica serving as common interaction media, and its primary purpose is to generate high-peak-power optical pulses for precision material removal and time-resolved spectroscopy. Bulk cavity dumpers dominate current procurement volumes due to established repairability and thermal management paths, while fiber-integrated dumpers represent the fastest-expanding segment as OEMs seek plug-and-play compatibility with fiber laser architectures. Scientific research applications sustain premium pricing, though semiconductor manufacturing demand is broadening the addressable base.
ISO 10110 surface quality standards and FDA laser product regulations shape device certification requirements for medical and industrial deployment, while REACH compliance in Europe constrains material choices for crystal substrates and bonding compounds. The FCC governs RF emission profiles from driver electronics in the United States, creating cross-jurisdictional design complexity for multi-region suppliers. Stakeholders must track evolving RoHS exemptions for piezoelectric ceramics and assess whether regional content rules in defense procurement will fragment supply qualifications.
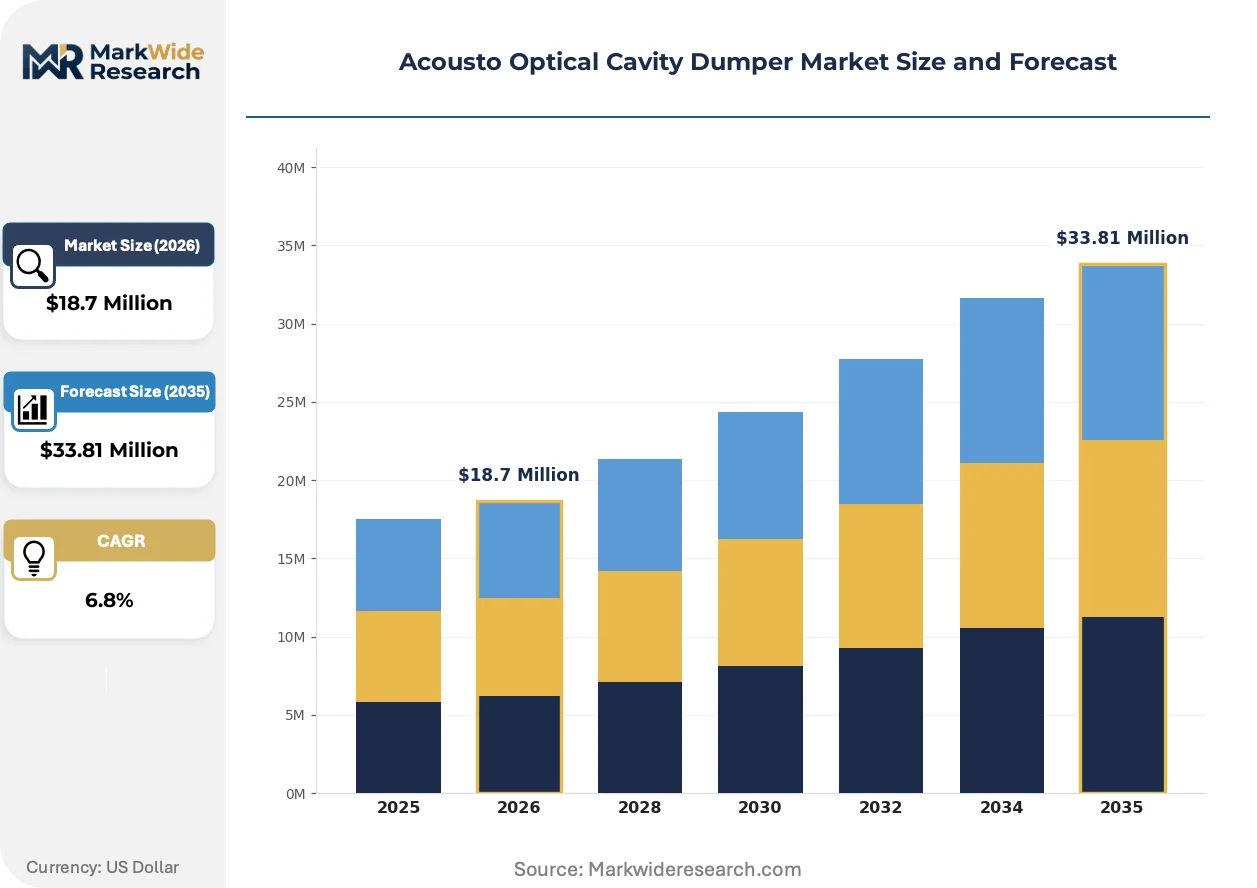
Market Dynamics
Semiconductor lithography roadmaps now mandate sub-picosecond pulse control, forcing cavity dumper manufacturers to synchronize RF driver electronics with EUV scanner timing protocols. This specification tightening concentrates procurement among suppliers capable of crystal growth, transducer bonding, and RF synthesis under one quality system.
Growth Catalysts
- Laser Micromachining Expansion:Die singulation and TSV drilling in advanced packaging fabs in Germany and Japan now specify cavity-dumped sources for edge quality control.
- RoHS Exemption Renewal:European Commission extensions for lead zirconate titanate in high-power piezoelectric transducers secure material supply continuity through 2026.
- Time-Resolved Spectroscopy:Ultrafast chemistry departments at US national laboratories are replacing mechanical choppers with solid-state cavity dumpers for jitter reduction.
Market Restraints
- Tellurium Supply Concentration:Over 70% of refined tellurium originates as copper smelter byproduct in China, exposing crystal substrate costs to base metal cycle volatility.
- RF Driver Thermal Limits:Gallium nitride power amplifiers required for 200 MHz operation remain constrained by foundry capacity at specialized compound semiconductor fabs.
- Substitution by SESAM:Semiconductor saturable absorber mirrors in mode-locked fiber lasers eliminate external modulation for some femtosecond applications.
Strategic Opportunities
- India PLI Scheme:Production-linked incentives for semiconductor and photonics manufacturing create localized assembly demand for cavity dumper subsystems.
- Quantum Sensing Convergence:Integration of acousto-optic modulators with cold atom interferometers for gravimetry opens instrumentation verticals beyond laser machining.
- Asset-Light Service Models:Leasing arrangements bundling cavity dumper heads with predictive maintenance contracts penetrate mid-tier micromachining job shops.
Industry Challenges
- Transducer Bonding Artisanry:Acoustic impedance matching between lithium niobate transducers and tellurium dioxide crystals requires technicians with decade-long apprenticeship experience.
- Multi-Jurisdiction Certification:Simultaneous FCC RF emission testing, FDA laser product classification, and REACH substance documentation extends qualification timelines.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acousto Optical Cavity Dumper Market Trends and Innovations
RF driver architectures and crystal fabrication methods are converging to enable fiber laser integration, while regulatory pressure on hazardous substances accelerates material substitutions. These forces are compressing product lifecycles and redrawing supplier qualifications.
Fiber-integrated cavity dumpers using micro-optic benches and pigtailed collimators are rendering obsolete free-space bulk modulators in OEM fiber laser builds. Medical device manufacturers and precision welding system integrators now specify plug-and-play compatibility with MOPA architectures. The shift eliminates alignment labor and vibration sensitivity penalties that previously favored discrete optical assemblies.
REACH authorization timelines for cadmium and lead compounds are constraining piezoelectric ceramic formulations in European-sourced devices. ECHA substance evaluation pressures manufacturers to qualify bismuth sodium titanate alternatives with comparable electromechanical coupling coefficients. Medical laser OEMs serving EU markets are accelerating supplier audits to preempt substitution deadlines.
Buyers now unbundle hardware acquisition from calibration and refurbishment services, treating cavity dumpers as consumable subsystems with defined mean-time-between-failure metrics. This behavior compresses replacement cycles and shifts margin capture toward service networks with regional stocking points. The pattern is most visible in German and Japanese automotive micromachining supply chains, where line-down costs exceed component replacement economics.
Acousto Optical Cavity Dumper Market Segmentation
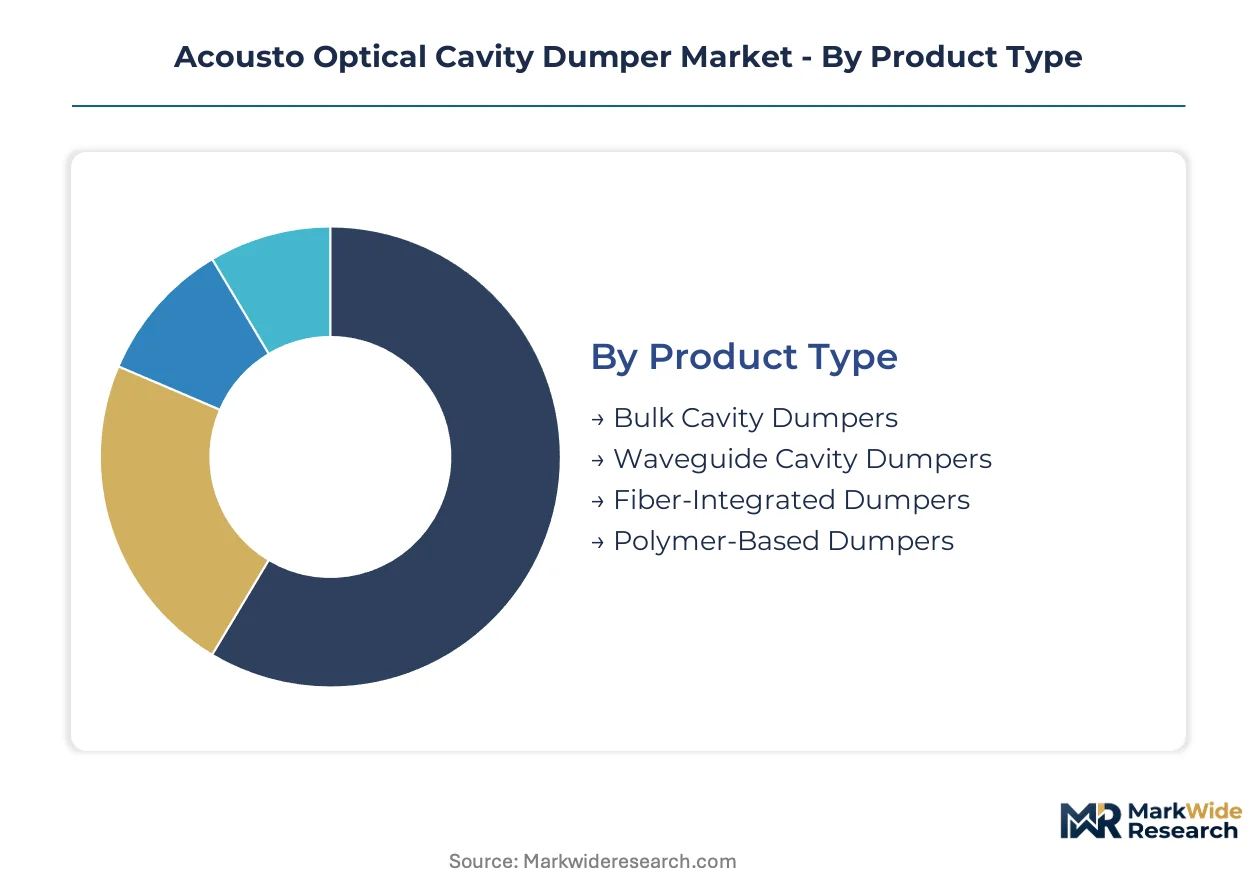
Cavity dumper procurement patterns diverge sharply across product architectures and end-use workflows. Segment boundaries determine which suppliers control RF driver electronics, crystal fabrication, or system integration margins.
Product Type:
Bulk cavity dumpers turn over slowest due to decade-long service lives in free-space laser systems, while polymer-based alternatives refresh fastest as disposable components in cost-sensitive instrumentation.
- Bulk Cavity Dumpers:Free-space acousto-optic cells using tellurium dioxide crystals bonded to lithium niobate transducers deliver nanosecond pulse extraction with established thermal management paths. Semiconductor fabrication facilities in Germany and Japan specify these for die singulation where repairability outweighs integration density.
- Fiber-Integrated Dumpers:Micro-optic bench assemblies with pigtailed collimators plug directly into MOPA fiber laser architectures, eliminating alignment labor. Medical device manufacturers driving plug-and-play compatibility requirements represent the steepest expansion trajectory for this format.
- Waveguide Cavity Dumpers:Channel-waveguide geometries in thin-film lithium niobate substrates suit compact rangefinder and lidar subsystems.
- Polymer-Based Dumpers:Organic acousto-optic materials in disposable sensing heads target price-constrained environmental monitoring applications.
Bulk cavity dumpers dominate installed base. Fiber-integrated dumpers are where expansion concentrates.
Technology:
Cost tiers separate mature acousto-optic platforms from emerging alternatives, with RF synthesis complexity driving price stratification.
- Acousto-Optic Modulation:Ultrasonic wave diffraction through TeO₂ or fused silica crystals at 40-200 MHz frequencies enables Q-switching with sub-nanosecond jitter. Precision photonics clusters in the United States and Japan anchor procurement for time-resolved spectroscopy where solid-state reliability displaces mechanical choppers.
- Electro-Optic Modulation:Pockels cells using potassium dihydrogen phosphate crystals achieve faster switching without acoustic transit time limitations. EUV lithography scanner synchronization requirements in German fabs concentrate demand for sub-picosecond pulse control.
- Magneto-Optic Modulation:Faraday rotation devices in terbium gallium garnet suit high-power isolation and polarization control.
- Fabry-Pérot Cavities:Etalon-based wavelength selection supports narrow-linewidth seed laser stabilization.
Acousto-optic modulation commands the broadest application footprint. Electro-optic platforms are climbing the fastest in value terms.
Application:
Volume concentration varies by capital equipment cycle timing, with scientific research sustaining premium pricing through grant-funded procurement.
- Laser Micromachining:Cavity-dumped sources execute TSV drilling and edge quality control in advanced packaging workflows. Automotive supply chains in Germany treat these as consumable subsystems with defined mean-time-between-failure metrics.
- Scientific Research:Ultrafast chemistry departments at US national laboratories deploy cavity dumpers for jitter reduction in time-resolved spectroscopy. Grant-funded procurement sustains premium pricing tolerance unavailable in industrial accounts.
- Optical Telecommunication Testing:Pulse characterization equipment for fiber optic network validation requires standardized modulation formats.
- Material Processing:Surface texturing and marking applications in job shops prioritize cost per watt over pulse fidelity.
Laser micromachining generates the highest unit volumes. Scientific research preserves margin structure.
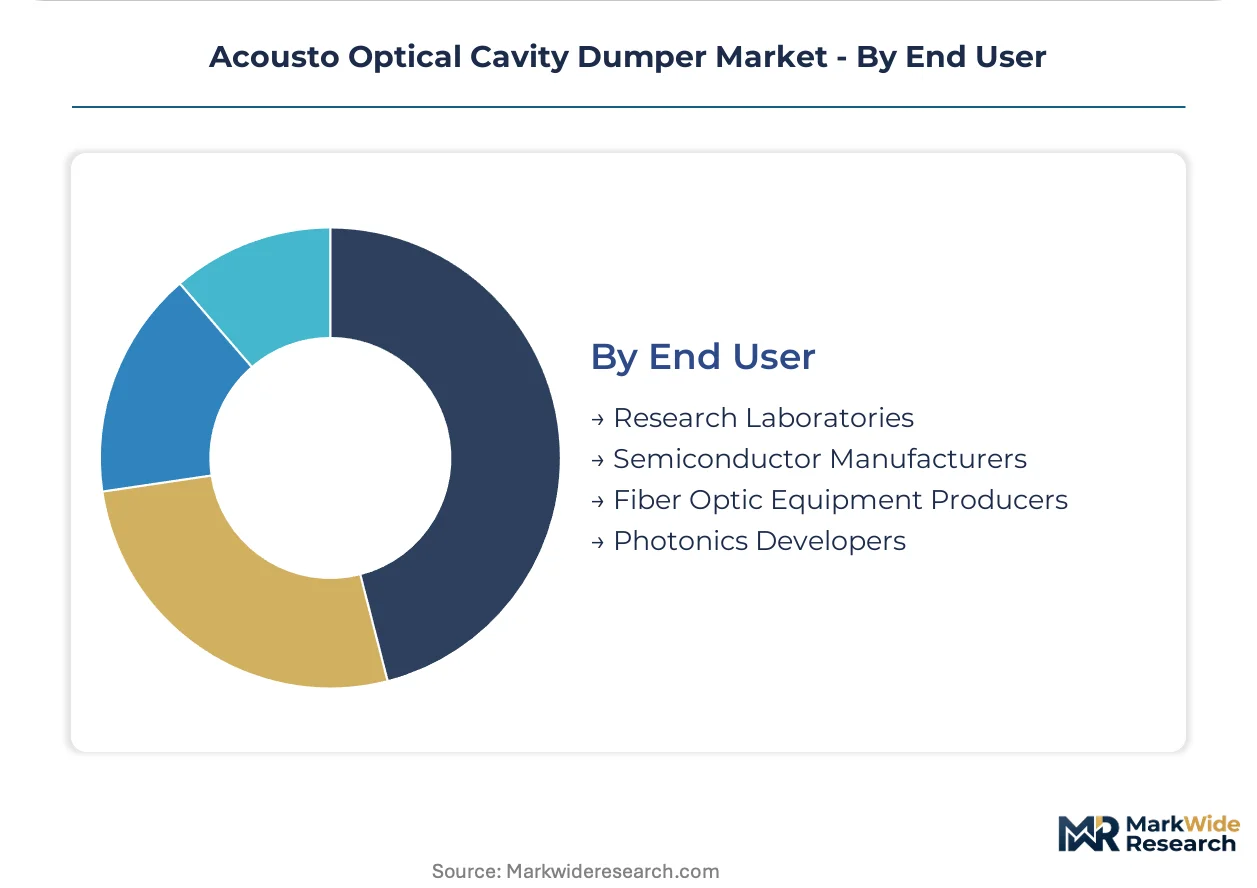
End User:
Customer type determines service bundling expectations, with semiconductor manufacturers demanding predictive maintenance contracts and research laboratories accepting bare hardware.
- Semiconductor Manufacturers:Fab operators in Germany and Japan specify cavity dumper subsystems with synchronized RF drivers for EUV scanner timing protocols. Asset-light leasing arrangements with bundled service contracts penetrate this segment as line-down costs exceed component replacement economics.
- Research Laboratories:National science facilities and university ultrafast groups prioritize pulse fidelity metrics over total cost of ownership. Calibration and refurbishment services are unbundled from hardware acquisition.
- Fiber Optic Equipment Producers:OEMs integrating cavity dumpers into test and measurement platforms seek plug-and-play fiber compatibility.
- Photonics Developers:Early-stage instrument companies prototype with modular bulk modulators before committing to custom fiber-integrated designs.
Semiconductor manufacturers anchor procurement value. Research laboratories maintain specification leadership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production-linked incentives for semiconductor manufacturing in India and precision photonics clusters in Germany, Japan, and the United States are redrawing procurement geography for acousto-optic subsystems.
Germany
Automotive micromachining supply chains in Bavaria and Baden-Württemberg specify cavity-dumped sources for die singulation with defined mean-time-between-failure metrics. REACH compliance constraints on piezoelectric ceramics accelerate supplier audits for bismuth sodium titanate alternatives. The precision photonics cluster around Munich anchors EUV scanner timing protocol development.
United States
National laboratory ultrafast chemistry departments replace mechanical choppers with solid-state cavity dumpers for jitter reduction in time-resolved spectroscopy. FCC RF emission testing from driver electronics creates design complexity for multi-region suppliers. Boston and Silicon Valley precision manufacturing corridors concentrate grant-funded procurement.
Japan
Advanced packaging fabs specify cavity-dumped sources for TSV drilling and edge quality control in semiconductor fabrication. METI industrial standards shape certification requirements for medical and industrial laser deployment. The precision optics corridor between Tokyo and Yokohama dominates crystal fabrication and transducer bonding expertise.
India
PLI scheme incentives for semiconductor and photonics manufacturing create localized assembly demand for cavity dumper subsystems. BIS standards compliance requirements shape import substitution strategies for RF driver electronics. Bengaluru and Hyderabad emerging as precision photonics assembly hubs for regional supply.
China
Copper smelter byproduct concentration for refined tellurium exposes crystal substrate costs to base metal cycle volatility. GB standards and MIIT regulations govern laser product classification and RF emission profiles. Yangtze River Delta precision manufacturing zones concentrate downstream micromachining system integration.
Acousto Optical Cavity Dumper Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated specialists capable of crystal growth, transducer bonding, and RF synthesis under unified quality systems. Three archetypes dominate: tellurium dioxide crystal growers controlling input costs, RF driver electronics specialists pairing modulation heads with synthesized frequency control, and full-stack laser system integrators extending into downstream workflows. Competitive moves center on backward integration into tellurium supply and asset-light service models bundling hardware with predictive maintenance contracts.
Among UK-based precision photonics suppliers, Gooch & Housego exemplifies the crystal-growth archetype through captive tellurium dioxide production. Isomet Corporation anchors the RF driver specialization tier with synthesized frequency control expertise. Coherent occupies the full-system integration position, spanning modulation subsystems through complete laser architectures.
| Leading Market Players |
|---|
| Gooch & Housego |
| Isomet Corporation |
| Brimrose Corporation of America |
| Coherent |
| L3Harris Technologies |
| AA Opto Electronic |
| AMS Technologies |
| IntraAction Corp. |
| Lightcomm Technology |
| Others |
Pricing and Supply Chain Analysis
The Yangtze River Delta precision manufacturing zones anchor tellurium dioxide crystal substrate supply, and their exposure to copper smelter byproduct volatility transmits directly into RF driver electronics pricing power for cavity dumper manufacturers. Buyers in German automotive micromachining chains now unbundle hardware from service contracts, compressing replacement cycles and shifting margin capture toward regional calibration networks.
Pricing Analysis
Certification level (ISO 10110 surface quality, FDA laser product classification, CE marking) creates the primary spread between premium scientific research units and economy-tier job shop equipment. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales bundling intensity and thermal management specification tightness. Cost compression in mid-tier fiber-integrated formats is intensifying because OEMs specify plug-and-play MOPA compatibility as table stakes. Semiconductor manufacturers show least price sensitivity due to line-down cost exposure, while precision welding job shops prioritize cost per watt over pulse fidelity.
Supply Chain Analysis
Export control regimes restricting compound semiconductor foundry capacity constrain gallium nitride power amplifier flows for 200 MHz RF drivers. Crystal substrate fabrication concentrates in China, Japan, and Germany, with transducer bonding artisanry anchored in the Tokyo-Yokohama precision optics corridor. Supply chain risk centers on single-source vulnerability for refined tellurium derived from copper smelter byproduct concentration. Distribution runs through OEM system integrators and specialized photonics distributors serving semiconductor fabrication and research laboratory end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among semiconductor manufacturers in Germany and Japan who specify synchronized EUV scanner timing protocols, fragmenting supplier qualification requirements across multi-jurisdiction certification regimes.
For Market Incumbents: Pre-empt SESAM substitution in femtosecond fiber laser applications by accelerating bismuth sodium titanate qualification ahead of REACH authorization deadlines. Deepen backward integration into tellurium supply through offtake arrangements with copper smelter operations, securing input cost stability against base metal cycle volatility. Prioritize RF driver thermal management R&D to exploit gallium nitride foundry capacity constraints as a competitive moat. For New Entrants and Emerging Players: India's PLI scheme for semiconductor and photonics manufacturing represents underpenetrated localized assembly demand for cavity dumper subsystems. Target Bengaluru and Hyderabad precision photonics clusters with RF driver electronics specialization, leveraging BIS standards compliance as qualification leverage. Enter through asset-light leasing models bundling predictive maintenance contracts to penetrate mid-tier micromachining job shops. For Investors and Strategic Acquirers: Long-term, this sits as a captive-material play because tellurium dioxide crystal growth expertise requires decade-long apprenticeship pipelines that cannot be replicated through capital deployment alone. Acquisition targets should display unified quality systems spanning crystal fabrication, transducer bonding, and RF synthesis. Watch for RoHS exemption non-renewal for lead zirconate titanate as the inflection signal forcing material substitution investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tellurium Supply | Captive raw material sourcing insulates Gooch & Housego from copper smelter byproduct volatility. |
| Fiber-Integrated Product Line Expansion | Micro-optic bench assemblies address MOPA architecture demand from medical device OEMs. |
| REACH-Compliant Piezoelectric Qualification | Bismuth sodium titanate substitution secures European market access ahead of authorization deadlines. |
| Asset-Light Leasing Model Deployment | Predictive maintenance contracts penetrate German automotive micromachining supply chains. |
| Multi-Jurisdiction Certification Investment | Simultaneous FCC, FDA, and CE marking capability accelerates procurement timelines. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with RF driver electronics engineers, semiconductor fab procurement managers, and ultrafast spectroscopy laboratory directors; and secondary validation through SEC filings of laser system integrators, ECHA substance evaluation databases, and METI industrial standard documentation. Bottom-up triangulation across product architecture segments converged with top-down demand modeling from lithography roadmaps and micromachining capital equipment cycles.
Forecast inputs incorporated acousto-optic modulation technology maturity curves, fiber laser architecture adoption patterns, and regional semiconductor fabrication capacity buildouts across the projection horizon. Segmentation dimensions modeled include product type (bulk, fiber-integrated, waveguide, polymer-based), application workflow (laser micromachining, scientific research, telecommunications testing), and end-user procurement behavior (semiconductor manufacturers, research laboratories, fiber optic equipment producers). CAGRs derived from installed base turnover rates and replacement cycle compression observed in German and Japanese automotive supply chains.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated laser system integrators into modulation subsystem supply would shift outcomes. Material shifts in RoHS exemption status for piezoelectric ceramics or tellurium supply concentration disruption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.