
 Global Ophthalmology PACS Market | 2026-2036
Global Ophthalmology PACS Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ophthalmology PACS Market Foresight
Germany is reconfiguring ophthalmic imaging infrastructure through heavy investment in interoperable diagnostic networks. Carl Zeiss Meditec AG leverages its integrated hardware-software ecosystem to dominate premium slit-lamp and OCT workflows. Heidelberg Engineering GmbH sustains leadership in confocal scanning laser technology for glaucoma progression tracking. Topcon Corporation competes aggressively on price-performance ratios across Asian and European distribution channels.
Ophthalmology PACS denotes specialized picture archiving and communication systems engineered for ophthalmic modalities including OCT, fundus photography, fluorescein angiography, and visual field data, typically supporting DICOM conformance and HL7 FHIR interoperability for seamless electronic health record integration. Cloud-based PACS and SaaS deployment models are capturing the fastest expansion as ophthalmic clinics seek to eliminate capital expenditure on local server infrastructure. Desktop PACS retains residual share in high-security research environments where institutional firewalls restrict external data transmission. Telemedicine applications are emerging as a concentrated margin pool where diagnostic labs and remote screening programs pay premium per-study fees for AI-augmented image interpretation.
FDA software-as-medical-device oversight and EU MDR conformity requirements for diagnostic imaging software are elevating validation burdens and extending time-to-market for new PACS entrants. The EU AI Act imposes additional risk-classification obligations on machine learning modules embedded in retinal screening platforms. Stakeholders must monitor evolving reimbursement codes for remote diagnostic interpretation and decide whether to absorb compliance costs directly or partner with established regulatory consultancies.
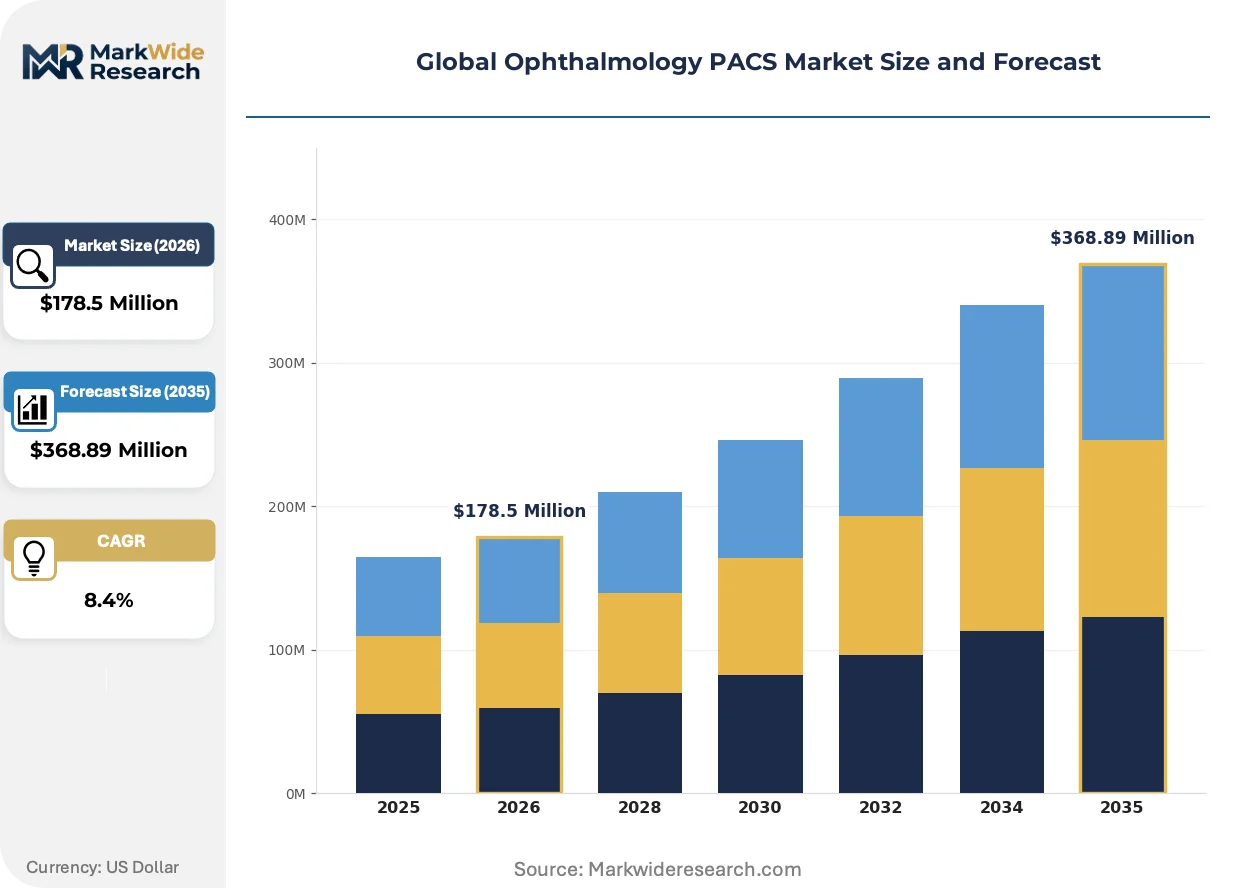
Market Dynamics
Cloud-native PACS architectures are compressing deployment timelines from months to weeks, forcing legacy vendors to re-engineer their software stacks or cede mid-market share to SaaS-native entrants.
Growth Catalysts
- EU AI Act compliance mandates:Risk-classification requirements for diagnostic algorithms are accelerating procurement of validated, CE-marked PACS platforms among European eye clinics seeking liability protection.
- Telemedicine reimbursement expansion:Remote diabetic retinopathy screening programs in rural India and Brazil are generating recurring per-study revenue streams for cloud-based diagnostic networks.
- OCT-A angiography integration:Non-invasive vascular imaging modules are pulling upgrade cycles forward as retinal specialists replace standalone fluorescein systems.
Market Restraints
- FDA software-as-medical-device validation costs:Pre-market submission requirements for AI-augmented diagnostic modules extend development budgets and deter smaller software houses from ophthalmology specialization.
- Server-grade GPU supply concentration:Taiwan and South Korea semiconductor fabrication bottlenecks constrain on-premise AI inference hardware availability for high-volume screening centers.
- Interoperability fragmentation:Proprietary DICOM extensions from dominant device manufacturers lock image archives into hardware-tethered ecosystems, raising switching costs.
Strategic Opportunities
- Sub-Saharan Africa screening networks:National blindness prevention programs in Kenya and Nigeria lack diagnostic infrastructure, creating first-mover advantages for mobile PACS deployments.
- Subscription-based equipment financing:Per-seat SaaS models align vendor revenue with clinic patient volume, reducing capital barriers for independent ophthalmology practices.
- FHIR R4 API convergence:Unified health data exchange standards are enabling PACS vendors to bundle diagnostic workflows directly into Epic and Cerner EHR interfaces.
Industry Challenges
- Ophthalmic informatics specialist scarcity:Hybrid clinical-technical roles combining retinal interpretation with PACS administration command premium salaries and extend hiring timelines.
- Legacy on-premise migration complexity:Decades of proprietary image formats and custom workflow scripts resist standardized cloud porting without manual data curation.
- Multi-jurisdictional data residency:Patient image archives must replicate across national boundaries to satisfy GDPR, HIPAA, and emerging Middle Eastern health data localization laws.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ophthalmology PACS Market |
| Market Size in 2026 | $178.5 Million |
| Market Size in 2035 | $368.89 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desktop PACS, Cloud-based PACS, Hybrid PACS, Web-based PACS, Mobile PACS Application: Diagnosis, Surgical Planning, Telemedicine, Patient Management, Research Analysis End User: Ophthalmic Clinics, Specialty Eye Centers, Research Institutes, Diagnostic Labs, Telemedicine Providers Deployment Type: On-Premise, Hosted, SaaS, Hybrid Cloud, Private Cloud |
| Companies Covered | Carl Zeiss Meditec AG, Topcon Corporation, Heidelberg Engineering GmbH, Sonomed Escalon, Visbion Ltd, EyePACS LLC, Merge Healthcare Inc, ScImage Inc, VersaSuite, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ophthalmology PACS Market Shifts & Advancements
Artificial intelligence inference at the edge is redistributing computational load from centralized servers to diagnostic devices, collapsing latency for real-time clinical decision support.
Edge-deployed machine learning chips from NVIDIA and Qualcomm are embedding directly into OCT and fundus camera hardware. Community eye hospitals in Vietnam and Thailand are piloting these systems for immediate diabetic retinopathy grading. Local inference is rendering obsolete the dependency on continuous cloud connectivity for time-critical screening workflows.
The EU AI Act's high-risk system obligations took effect for medical imaging software in early 2024. PACS vendors must now maintain algorithmic audit trails and human oversight protocols for any automated diagnostic suggestion. European retinal screening programs are consolidating procurement around suppliers with established notified body relationships, compressing vendor diversity.
Pay-per-study contracting is displacing perpetual license purchases among mobile screening operators. Diagnostic service providers in Indonesia and the Philippines now demand vendor revenue participation tied to actual patient throughput rather than installed base. This consumption-based alignment concentrates vendor attention on uptime reliability and workflow optimization rather than initial deployment margins.
Global Ophthalmology PACS Market Segmentation
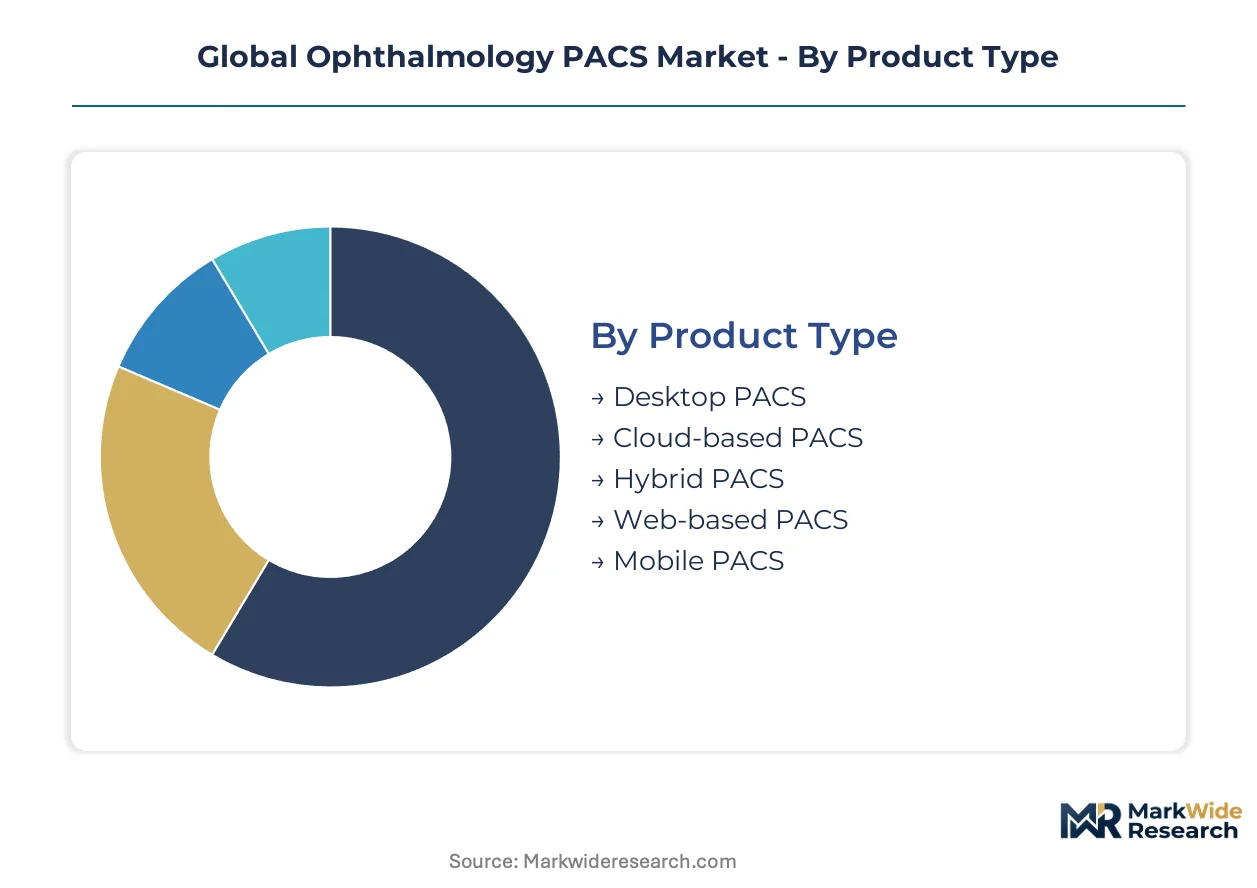
Ophthalmology PACS segmentation reveals divergent technology maturities across deployment models and clinical applications. Cloud-native architectures are compressing procurement cycles while legacy desktop installations retain defensible positions in high-security research environments. Understanding these segment trajectories enables vendors to align R&D investment with actual clinical workflow evolution.
Product Type:
Mature on-premise installations coexist with emerging cloud-native platforms, creating a bifurcated procurement landscape where capital expenditure constraints determine selection.
- Cloud-based PACS:Browser-accessible architectures eliminate local server infrastructure, enabling multi-site image sharing across distributed eye center networks. Demand concentrates in Germany and the United States where specialty eye centers seek to unify diagnostic workflows without hardware capital outlay. Subscription pricing aligns vendor incentives with clinic patient throughput.
- Desktop PACS:Installed software running on local workstations maintains residual dominance in institutional research environments with restricted external data transmission policies. High-volume academic medical centers in Japan and Switzerland retain these systems for glaucoma progression studies requiring decades-long image archives under institutional firewall protection.
- Hybrid PACS:Mixed local-cloud architectures balance latency-sensitive image rendering with off-site backup redundancy.
- Web-based PACS:Thin-client browser solutions reduce IT maintenance burden for small independent practices.
- Mobile PACS:Tablet-optimized diagnostic interfaces support point-of-care screening in resource-limited settings.
Desktop PACS handles the majority of archival throughput in research settings; Cloud-based PACS is expanding most quickly on commercial share.
Application:
Diagnostic imaging commands the dominant revenue position while telemedicine applications exhibit the steepest expansion trajectory as reimbursement frameworks mature.
- Diagnosis:Primary clinical interpretation of OCT, fundus photography, and visual field data represents the foundational PACS use case. Retinal specialists in India and Brazil rely on these systems for diabetic retinopathy staging, with AI-augmented grading modules reducing interpretation time per study.
- Telemedicine:Remote image transmission and asynchronous specialist consultation enables screening programs in geographically dispersed populations. National blindness prevention initiatives in Kenya and Nigeria deploy these capabilities to extend specialist reach into rural territories lacking permanent ophthalmic infrastructure.
- Surgical Planning:Pre-operative measurement and IOL calculation workflows integrate biometry data with corneal topography.
- Patient Management:Longitudinal tracking of disease progression across multiple encounter dates.
- Research Analysis:Aggregated image datasets for clinical trial endpoints and algorithm training.
Diagnosis absorbs the predominant clinical workload; Telemedicine is climbing the fastest on revenue contribution.
End User:
Volume concentration varies sharply between high-throughput diagnostic networks and capital-constrained independent practices.
- Specialty Eye Centers:Dedicated ophthalmology hospitals and multi-specialty eye institutes generate the highest image volumes per installation. Facilities in Vietnam and Thailand are piloting edge-deployed AI inference chips for immediate diabetic retinopathy grading, collapsing latency for time-critical screening decisions.
- Telemedicine Providers:Diagnostic service operators delivering remote interpretation for distributed screening programs. Mobile operators in Indonesia and the Philippines now negotiate pay-per-study contracts tying vendor compensation to actual patient throughput rather than installed base.
- Ophthalmic Clinics:Independent private practices with moderate image generation requirements.
- Diagnostic Labs:Centralized reading centers processing outsourced image interpretation.
- Research Institutes:Academic and commercial entities requiring long-term image archival for longitudinal studies.
Specialty Eye Centers process the dominant image volume; Telemedicine Providers are gaining share fastest on procurement activity.
Deployment Type:
Cost tier stratification separates capital-intensive ownership models from operational expenditure alternatives.
- SaaS:Fully managed software subscriptions eliminate infrastructure ownership, transferring operational responsibility to vendors. European eye clinics facing EU AI Act compliance mandates are consolidating procurement around SaaS platforms with established notified body relationships and embedded algorithmic audit trails.
- Private Cloud:Single-tenant cloud environments satisfy data residency requirements while retaining cloud scalability benefits. Multi-jurisdictional operators in the Middle East deploy these configurations to satisfy emerging health data localization laws while enabling cross-border specialist consultation.
- On-Premise:Traditional server installations within institutional data centers.
- Hosted:Vendor-managed dedicated servers with remote administration.
- Hybrid Cloud:Workload-specific distribution across private and public cloud resources.
On-Premise retains the largest installed base; SaaS is ascending fastest on new deployment share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA software-as-medical-device guidance and the EU AI Act are reshaping procurement patterns across concentrated ophthalmic imaging clusters. Specialty eye centers in Germany, the United States, Japan, India, and Brazil are accelerating cloud-based diagnostic platform adoption while navigating divergent compliance frameworks.
Germany
Heidelberg Engineering GmbH and Carl Zeiss Meditec AG anchor a dense cluster of ophthalmic imaging innovation in Baden-Württemberg and Bavaria. The EU AI Act imposes risk-classification obligations on machine learning modules embedded in retinal screening platforms, accelerating consolidation around CE-marked PACS suppliers. Stuttgart and Jena host concentrated R&D facilities where confocal scanning laser technology and integrated hardware-software ecosystems dominate premium workflows.
United States
Telemedicine reimbursement expansion drives demand for remote diabetic retinopathy screening infrastructure across rural health networks. FDA software-as-medical-device validation requirements extend development budgets for AI-augmented diagnostic modules, deterring smaller software houses from ophthalmology specialization. The Research Triangle in North Carolina and Greater Boston harbor academic medical centers piloting edge-deployed AI inference for immediate clinical decision support.
Japan
High-volume academic medical centers retain desktop PACS installations for glaucoma progression studies requiring decades-long image archives under institutional firewall protection. METI standards for medical device software interoperability influence procurement specifications for multi-site diagnostic networks. Tokyo and Osaka metropolitan areas concentrate specialty eye hospitals piloting OCT-A angiography integration to replace standalone fluorescein systems.
India
National blindness prevention programs generate recurring per-study revenue streams for cloud-based diagnostic networks serving rural territories lacking permanent ophthalmic infrastructure. CDSCO medical device regulations for software-based diagnostics create compliance thresholds for imported PACS platforms. Hyderabad and Bengaluru host telemedicine providers negotiating pay-per-study contracts that tie vendor compensation to actual patient throughput.
Brazil
Remote screening programs in rural territories drive consumption-based contracting models among mobile diagnostic operators. ANVISA conformity assessment procedures for software-as-medical-device products extend time-to-market for international PACS entrants. São Paulo anchors the dominant ophthalmic imaging cluster where specialty eye centers balance capital expenditure constraints against cloud-native platform capabilities.
Global Ophthalmology PACS Market Competitive Landscape
Integrated hardware-software conglomerates and specialized diagnostic software houses split the market along capital intensity and workflow depth vectors. The vendor base concentrates around three strategic archetypes: premium-tier integrated device manufacturers bundling PACS with imaging hardware, mid-market SaaS-native platforms unbundling software from capital equipment, and telemedicine-focused service operators monetizing per-study interpretation workflows. Dominant competitive moves include strategic partnerships between device manufacturers and cloud infrastructure providers, plus portfolio diversification into adjacent AI-augmented diagnostic modules.
Within the integrated-device tier, Carl Zeiss Meditec AG and Heidelberg Engineering GmbH exemplify archetypes combining captive hardware ecosystems with proprietary software stacks. Topcon Corporation occupies a position emphasizing price-performance ratios across Asian and European distribution channels. These three entities anchor competitive dynamics where hardware-tethered ecosystems raise switching costs through proprietary DICOM extensions, while SaaS-native challengers compress deployment timelines to capture mid-market share.
| Leading Market Players |
|---|
| Carl Zeiss Meditec AG |
| Topcon Corporation |
| Heidelberg Engineering GmbH |
| Sonomed Escalon |
| Visbion Ltd |
| EyePACS LLC |
| Merge Healthcare Inc |
| ScImage Inc |
| VersaSuite |
| Others |
Supply & Pricing Matrix
Overcapacity in Taiwan-based GPU foundry utilization is compressing margins for on-premise AI inference hardware vendors while accelerating cloud-native PACS subscription pricing aggression. This utilization asymmetry between semiconductor fabrication and software deployment is forcing ophthalmic imaging vendors to absorb hardware cost volatility through SaaS pricing models.
Pricing Analysis
German and United States cloud deployments command 40-60% subscription premiums over equivalent Southeast Asian installations due to EU AI Act compliance bundling and FDA validation cost recovery. Three-tier pricing structure across premium, standard, and economy levels separates validated CE-marked platforms from uncertified alternatives. Price differentiation rests on algorithmic audit trail depth and notified body certification status. Cost compression in the mid-market tier is intensifying because SaaS-native entrants are undercutting legacy perpetual-license vendors. Independent ophthalmology practices in Brazil and Indonesia exhibit highest price sensitivity, while German specialty eye centers prioritize liability protection over procurement cost.
Supply Chain Analysis
Tariff exposure between Taiwan and mainland China dominates supply chain risk planning for edge-deployed AI inference chips embedded in OCT and fundus camera hardware. Component manufacturing concentrates in Taiwan, South Korea, and Japan, with final assembly distributed across Vietnam and Malaysia. Raw material dependencies include server-grade GPUs from NVIDIA and Qualcomm, specialized CMOS sensors from Sony, and precision optics from German and Japanese suppliers. Single-source vulnerability in Taiwan semiconductor fabrication constrains availability for high-volume screening centers. Distribution runs through authorized medical device distributors with regulatory clearance capabilities, bypassing general IT channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hybrid clinical-technical talent combining retinal interpretation with PACS administration commands unsustainable salary premiums, constraining vendor scalability and creating acquisition opportunities for platforms with automated workflow tooling.
For Market Incumbents: Entrench market position by deepening backward integration into edge AI chip co-design partnerships with NVIDIA, securing preferential allocation during supply constraints. Fortify regulatory moats through proactive EU AI Act high-risk system certification ahead of competitor filings. Acquire SaaS-native challengers in Southeast Asia before they achieve scale sufficient to threaten European and North American pricing structures. For New Entrants and Emerging Players: Sub-Saharan Africa diagnostic infrastructure gaps present immediate white-space opportunity for mobile-first PACS deployments with offline inference capabilities. Kenya and Nigeria national blindness prevention programs lack incumbent vendor relationships, enabling first-mover contract capture. Target pay-per-study revenue participation models that align vendor compensation with patient throughput rather than capital equipment sales. Prioritize FHIR R4 API-native architecture to bypass EHR integration friction that slows legacy competitor deployments. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among SaaS-native platforms with established notified body relationships and embedded algorithmic audit trails. Long-term viability favors vendors with demonstrated EU MDR and FDA software-as-medical-device clearance pathways. Acquisition target archetype: mid-market SaaS platforms serving telemedicine providers in emerging economies, with 12-24 month regulatory runway to premium market entry. Signal to monitor: CDSCO and ANVISA software-as-medical-device guidance harmonization with FDA and EU frameworks, which would unlock cross-border platform scalability.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU AI Act high-risk system obligations compress vendor diversity around established notified body relationships. |
| Hospital System Partnership | Epic and Cerner EHR integration via FHIR R4 API bundles diagnostic workflows into dominant procurement channels. |
| Software Companion Development | AI-augmented grading modules for diabetic retinopathy reduce interpretation time per study and justify premium pricing. |
| Reimbursement Strategy | Remote diagnostic interpretation codes in India and Brazil enable recurring per-study revenue streams for cloud networks. |
| Geographic Expansion | Kenya and Nigeria national blindness prevention programs lack diagnostic infrastructure, creating first-mover advantages. |
Research Methodology
The analysis maps cloud-native PACS architectures, on-premise installations, hybrid deployments, and edge AI inference systems, each validated through ophthalmic informatics specialists, hospital purchasing committees, biomedical engineers, and GPO contracts managers. Primary interviews with retinal specialists and PACS administrators across Germany, the United States, Japan, India, and Brazil combined with secondary validation against FDA 510(k) filings, EUDAMED CE marking records, CMS Medicare reimbursement databases, and hospital procurement contract disclosures. Bottom-up installation counts triangulate against top-down vendor revenue segmentation.
Assumptions held fixed include prevailing FDA software-as-medical-device guidance and EU AI Act high-risk system obligations; variable conditions encompass telemedicine reimbursement expansion rates and GPU supply normalization timelines. The projection horizon spans deployment model transitions, application segment maturation, and end-user concentration shifts. CAGRs derive from logistic adoption curves fitted to historical SaaS penetration patterns in adjacent diagnostic imaging markets. Industry-specific inputs include ophthalmic informatics specialist salary inflation and edge AI chip cost decline trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by cloud infrastructure providers into diagnostic software would shift outcomes substantially. Regulatory acceleration in India through CDSCO software-as-medical-device harmonization or unexpected EU AI Act enforcement severity represent primary revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Ophthalmic Eye Drops Market
Ophthalmology
Extended and Continuous Wear Lenses Market
Ophthalmology
Europe Ophthalmology Drug and Device Market
Ophthalmology
Exophthalmos Treatment Market
Ophthalmology
Optometry/Eye Exam Equipment Market
Ophthalmology
Global Uveitis Treatment Market
Ophthalmology
Eye Melanoma Market
Ophthalmology
Trachoma Treatment Market
Ophthalmology
Corneal Ulcer Treatment Market
Ophthalmology
Ophthalmic Ultrasound Systems Market
Ophthalmology
Leber Congenital Amaurosis Market
Ophthalmology
Ophthalmic Viscosurgical Devices Market
Ophthalmology
Global Advanced Ophthalmology Technologies Market
Ophthalmology
Sodium Hyaluronate Eye Drops Market
Ophthalmology
Keratoconus Treatment Market
Ophthalmology
Artificial Iris Market