
 Sodium Hyaluronate Eye Drops Market | 2026-2036
Sodium Hyaluronate Eye Drops Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Hyaluronate Eye Drops Market Outlook
Subscription-based replenishment programs for chronic dry eye patients is hardening into a standard revenue layer. Alcon leverages direct-to-patient platforms to secure recurring revenue streams. Santen Pharmaceutical anchors its position through specialized ophthalmology channel relationships in Asia-Pacific markets. URSAPHARM Arzneimittel GmbH differentiates via preservative-free manufacturing technology that commands premium positioning.
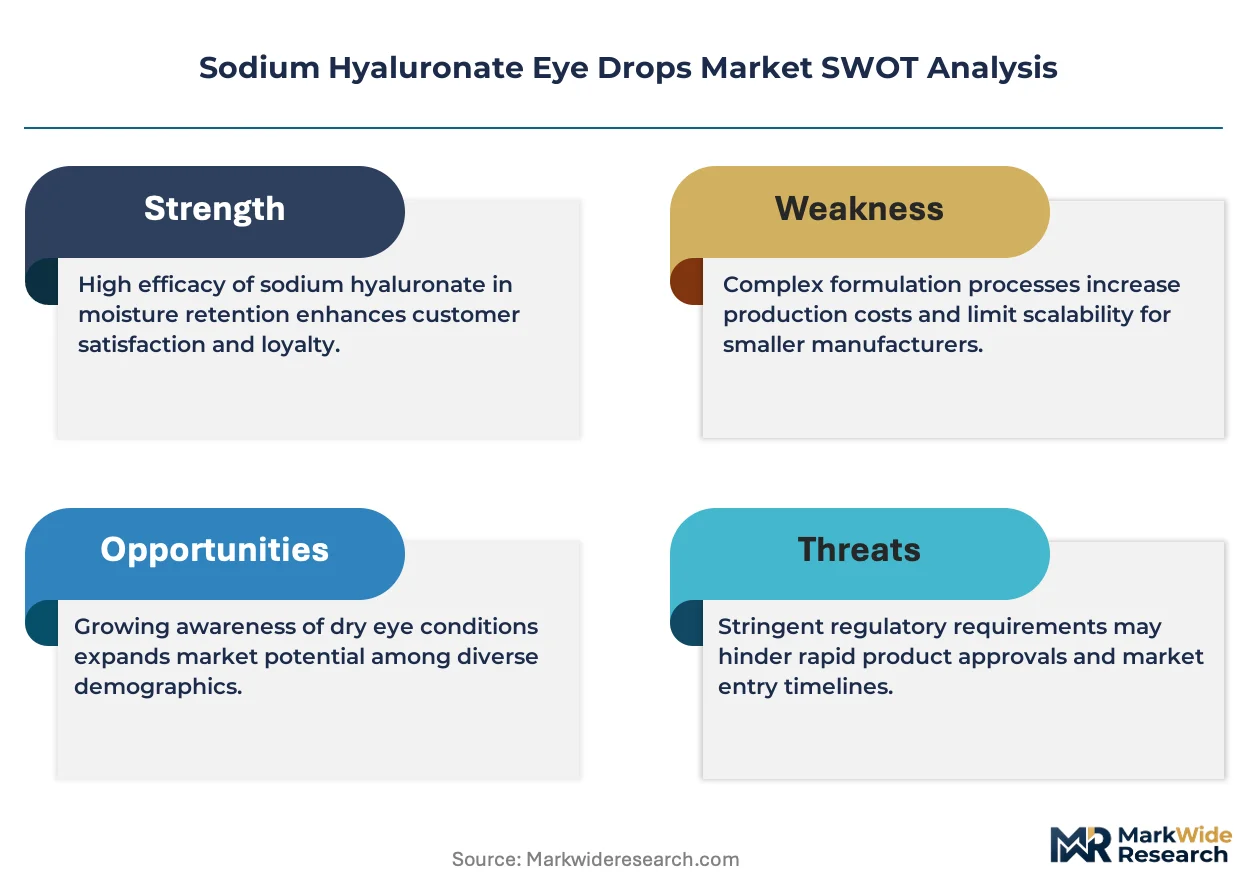
Sodium hyaluronate eye drops consist of high-molecular-weight hyaluronic acid salts dissolved in buffered aqueous solutions, typically at concentrations between 0.1% and 0.4%, functioning primarily as viscoelastic tear film substitutes that prolong ocular surface retention. Preservative-free formulations now lead volume growth as clinicians prioritize cytotoxicity reduction for long-term therapy patients. Dry eye syndrome represents the most mature therapy area with established reimbursement pathways, while post-surgery care applications yield concentrated margin pools due to hospital procurement premiums. Single-dose vials compete aggressively against multi-dose preserved alternatives in institutional settings where infection control protocols dominate purchasing criteria.
The US FDA enforces stringent sterility and container closure integrity requirements under ophthalmic drug guidance documents, while the EU MDR mandates enhanced clinical evidence for Class IIa and IIb medical device classifications affecting preservative delivery systems. Japan's PMDA maintains distinct pharmacopoeial standards for hyaluronic acid molecular weight specifications that shape import eligibility. Stakeholders must monitor evolving preservative bans and container sustainability mandates that will reshape formulation economics and packaging investments.
Market Dynamics
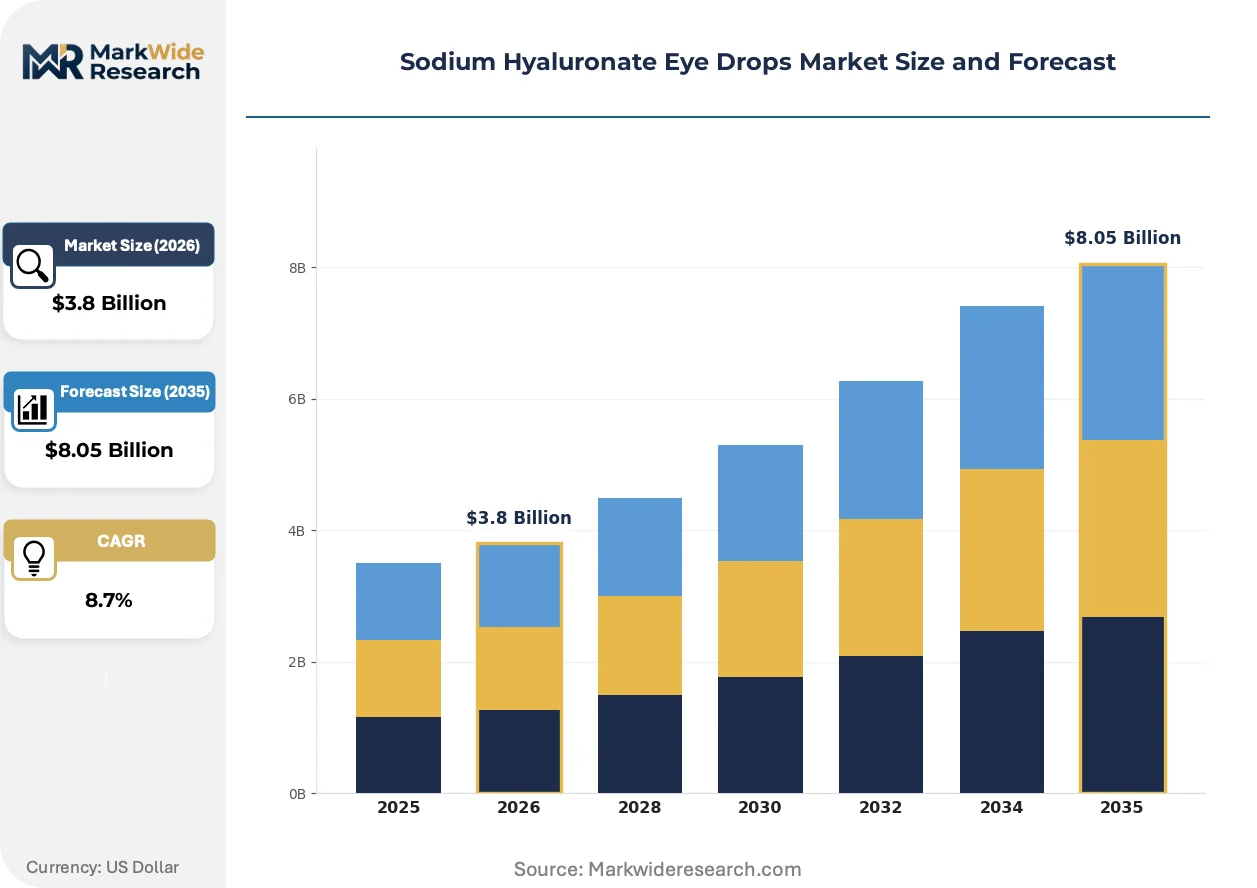
Preservative-free formulation migration is compressing manufacturing economics while expanding addressable patient populations across chronic dry eye and post-surgical recovery segments. The shift demands capital-intensive sterile filling infrastructure and is accelerating vendor consolidation around specialized blow-fill-seal capabilities.
Growth Catalysts
- EU MDR sterility mandates:Enhanced container closure integrity requirements for Class IIa and IIb ophthalmic devices are disqualifying multi-dose preserved alternatives, redirecting procurement toward single-dose and novel preservative-free delivery systems.
- Japan's PMDA molecular weight specifications:Distinct pharmacopoeial standards for hyaluronic acid purity and molecular weight distribution create import barriers that favor domestic and pre-qualified foreign manufacturers with established dossiers.
- Contact lens wearer expansion:Extended daily wear schedules and silicone hydrogel material proliferation generate sustained demand for compatible lubricating solutions without cytotoxic preservatives.
Market Restraints
- Sodium hyaluronate raw material concentration:Fermentation-derived high-molecular-weight hyaluronic acid supply concentrates among three specialized biopolymer producers, creating input cost volatility and qualification timeline risk.
- Blow-fill-seal equipment scarcity:Aseptic processing machinery for preservative-free unit-dose production faces 18-24 month lead times, constraining capacity expansion for mid-scale entrants.
- Autologous serum substitute development:Patient-derived tear film replacements for severe dry eye are capturing refractory case referrals in tertiary ophthalmology centers.
Strategic Opportunities
- India's CDSCO fast-track pathway:Accelerated approval mechanisms for essential ophthalmic medicines enable first-mover positioning in an underpenetrated chronic dry eye market with expanding private insurance coverage.
- Digital eye strain pediatric expansion:Screen-time-related ocular surface dysfunction in adolescent populations represents an emerging prescription category without established therapeutic guidelines.
- Subscription direct-to-patient platforms:Recurring replenishment models bypass traditional pharmacy distribution, capturing patient adherence data and lifetime value economics.
Industry Challenges
- Aseptic process engineering talent scarcity:Qualified personnel for sterile ophthalmic manufacturing command premium compensation, constraining facility ramp rates and operational scale-up.
- ISO 15378 certification timelines:Primary packaging material compliance for medicinal products requires 12-18 month qualification cycles, delaying formulation launches and supplier switches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Hyaluronate Eye Drops Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Preservative-Free, Preserved, Gel Drops, Single-Dose Vials Therapy Area: Dry Eye Syndrome, Allergies, Post-Surgery Care, Eye Fatigue Distribution Channel: Online Pharmacies, Offline Retail, Hospitals, Clinics Customer Type: Retail Customers, Healthcare Professionals, Institutions, Distributors |
| Companies Covered | Alcon, Bausch & Lomb, Santen Pharmaceutical, Allergan, Novartis, Johnson and Johnson, Bayer Inc., URSAPHARM Arzneimittel GmbH, Thea Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Hyaluronate Eye Drops Market Strategic Shifts
Cross-functional convergence between pharmaceutical formulation science and medical device engineering is redefining competitive differentiation in ocular surface therapy delivery systems.
Novel blow-fill-seal automation is automating aseptic unit-dose production at throughputs previously achievable only with preserved multi-dose alternatives. Contract manufacturers in Germany and Japan are deploying integrated vision inspection and laser coding systems to meet EU MDR unique device identifier requirements. This automation is compressing per-unit cost differentials between preservative-free and preserved formulations, eroding the historical price premium barrier.
REACH candidate list expansion for benzalkonium chloride and polyquaternium preservatives is forcing reformulation commitments across European ophthalmic portfolios. The European Chemicals Agency's 2023-2025 substance evaluation timeline is accelerating preservative-free transition investments ahead of potential authorization restrictions. Multi-dose preserved products face declining hospital formulary acceptance as procurement committees anticipate regulatory phase-out scenarios.
Telemedicine-enabled prescription renewal is disintermediating traditional optometry channels for established dry eye patients. Direct-to-patient platforms in the United States and Germany are capturing refill volume through automated compliance monitoring and insurance pre-authorization integration. This channel shift concentrates patient data assets with platform operators, repositioning traditional retail pharmacy relationships.
Sodium Hyaluronate Eye Drops Market Segmentation
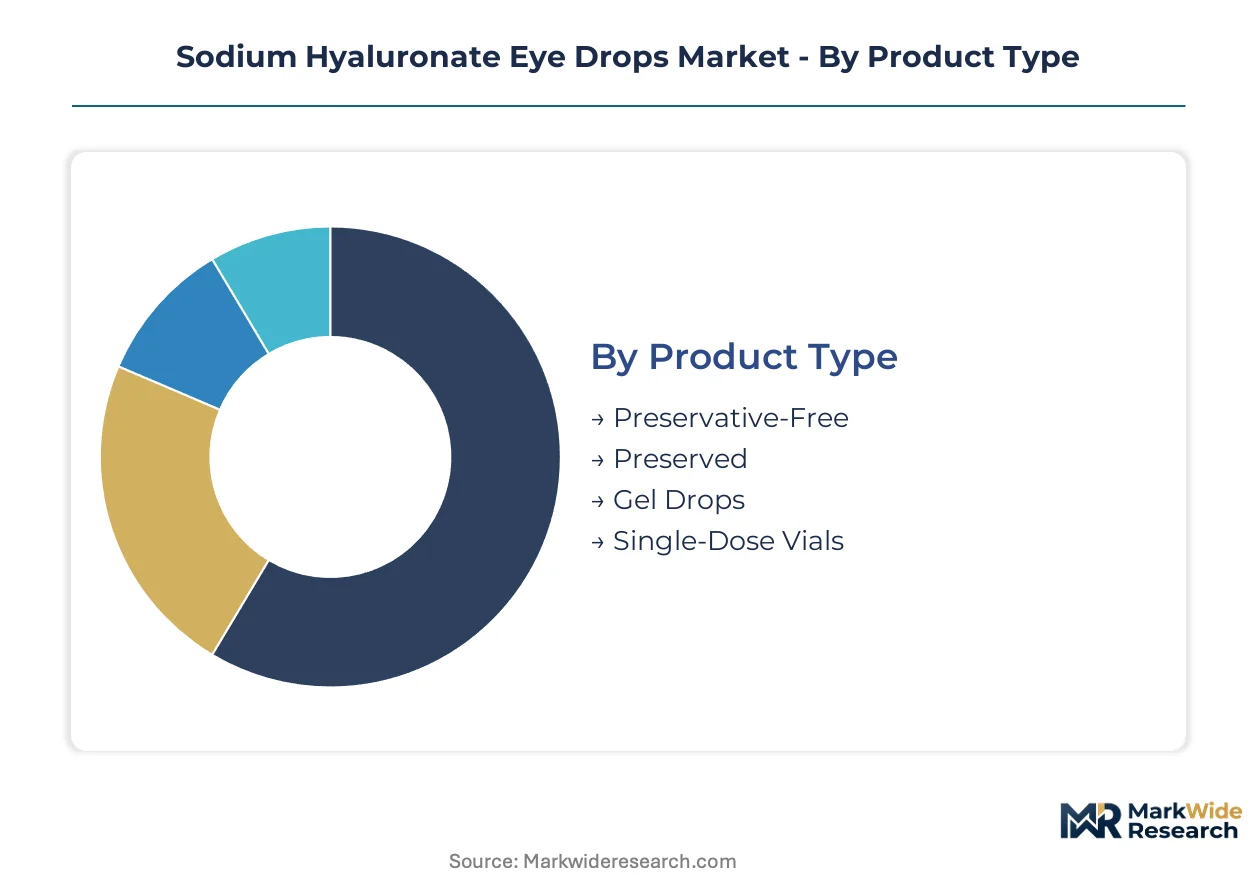
Segmentation in sodium hyaluronate eye drops reveals how capital deployment, regulatory positioning, and channel access determine competitive returns. Manufacturers must align formulation investments with specific patient pathways and procurement environments.
Product Type:
Capital intensity varies sharply across manufacturing modalities, with aseptic infrastructure requirements dictating entry barriers and margin structures.
- Preservative-Free:Blow-fill-seal production lines demand 18-24 month equipment lead times and ISO 15378-certified primary packaging. Demand concentrates in Germany and Japan where EU MDR sterility mandates and PMDA molecular weight specifications favor qualified suppliers with established dossiers.
- Preserved:Multi-dose formulations utilizing benzalkonium chloride or polyquaternium preservatives face REACH candidate list pressures. Hospital procurement committees in the United States are redirecting volume toward single-dose alternatives as regulatory phase-out scenarios materialize.
- Gel Drops:High-viscosity formulations at 0.3-0.4% concentration target overnight retention requirements.
- Single-Dose Vials:Unit-dose packaging eliminates contamination risk for contact lens wearers and post-surgical patients.
Most installed capacity flows through Preserved formulations. Expansion is steepest in Preservative-Free segments.
Therapy Area:
Reimbursement maturity and clinical evidence requirements segment opportunity by patient severity and treatment setting.
- Dry Eye Syndrome:Chronic therapy with established insurance pathways generates recurring prescription volume. Digital eye strain among screen-dependent professionals drives clinical prescribing in the United States and Germany.
- Post-Surgery Care:Hospital procurement premiums and concentrated patient volumes yield favorable margin pools. Cataract and refractive surgery recovery protocols in Japan mandate specific hyaluronic acid molecular weight ranges.
- Allergies:Seasonal demand peaks require flexible manufacturing scheduling.
- Eye Fatigue:Screen-time-related ocular surface dysfunction in adolescent populations lacks established therapeutic guidelines.
Dry Eye Syndrome commands the largest prescription base. Post-Surgery Care delivers the highest per-unit economics.
Distribution Channel:
Channel selection determines patient data access, compliance monitoring capabilities, and insurance integration complexity.
- Online Pharmacies:Subscription replenishment platforms capture lifetime value through automated adherence tracking. Direct-to-patient models in the United States bypass traditional retail pharmacy relationships.
- Hospitals:Institutional procurement prioritizes infection control protocols and formulary standardization.
- Offline Retail:Pharmacy counter access remains dominant for acute symptom purchases.
- Clinics:Ophthalmology channel relationships anchor specialized prescribing in Asia-Pacific markets.
Online Pharmacies are gaining share fastest among chronic patients. Hospitals maintain volume concentration for surgical indications.
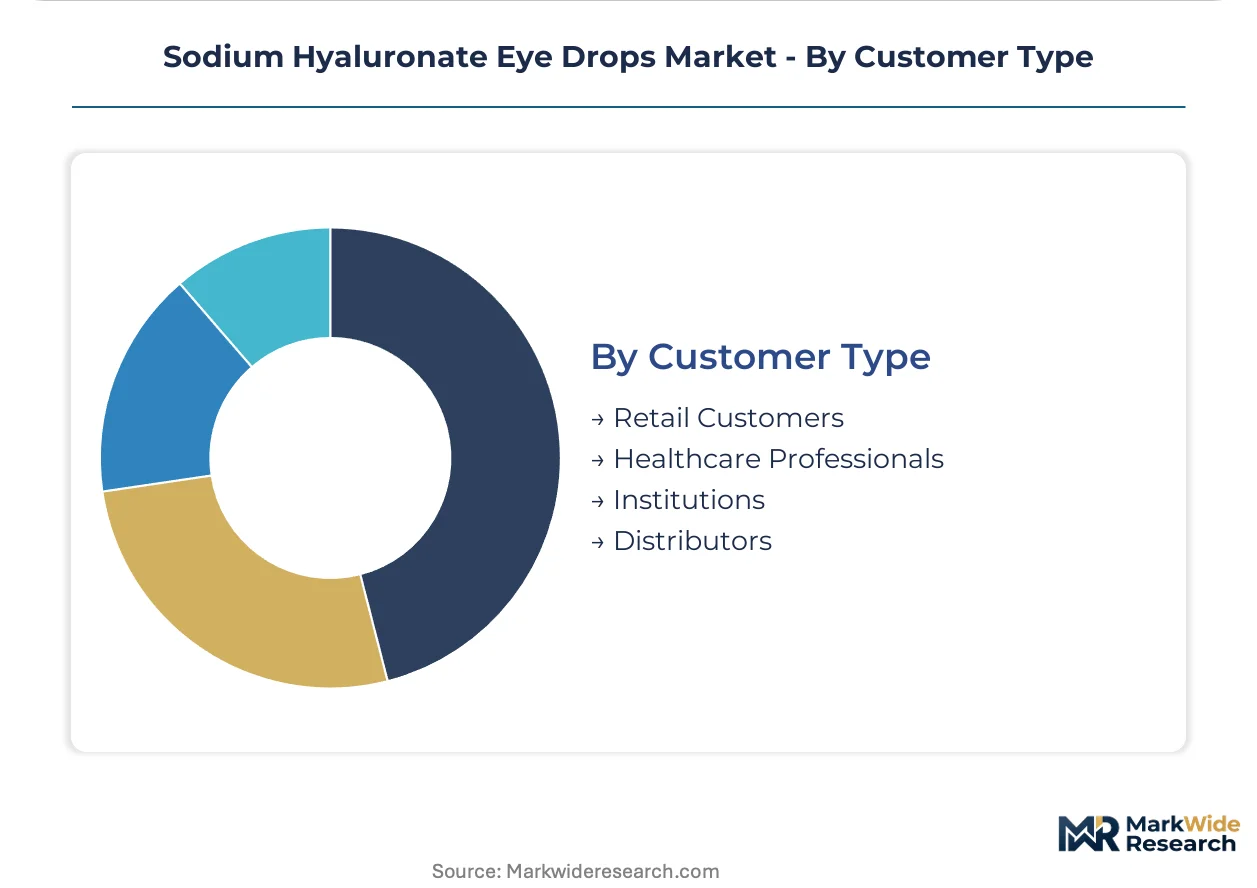
Customer Type:
Purchasing authority and volume scale differentiate service requirements and contract structures.
- Healthcare Professionals:Ophthalmologists and optometrists drive prescription decisions through clinical preference. Specialized channel relationships with Santen Pharmaceutical dominate Asia-Pacific institutional access.
- Institutions:Hospital procurement committees enforce sterility standards and infection control protocols.
- Retail Customers:Over-the-counter purchases respond to brand recognition and price positioning.
- Distributors:Wholesale intermediaries manage logistics for multi-channel coverage.
Healthcare Professionals control prescription flow. Institutions concentrate volume for post-surgical applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers migrate production toward jurisdictions with streamlined sterile filling certification and favorable preservative transition timelines. The EU MDR and FDA divergence on container closure standards creates compliance-cost arbitrage that shapes facility location decisions.
United States
Digital eye strain among screen-dependent professionals drives clinical prescribing in metropolitan ophthalmology practices. The FDA enforces stringent sterility requirements under ophthalmic drug guidance documents that disqualify older multi-dose formats. Contract manufacturers in the Research Triangle and Boston corridor deploy blow-fill-seal automation to meet hospital procurement standards.
Germany
Aging demographics and established reimbursement pathways sustain chronic dry eye prescription volumes. The ECHA REACH candidate list expansion for benzalkonium chloride accelerates preservative-free transition investments across European portfolios. Industrial clusters in Baden-Württemberg and Bavaria concentrate sterile filling infrastructure for unit-dose ophthalmic production.
Japan
PMDA pharmacopoeial standards for hyaluronic acid molecular weight distribution create import barriers favoring pre-qualified suppliers. Cataract and refractive surgery recovery protocols mandate specific hyaluronic acid specifications that shape procurement decisions. The Kansai region anchors domestic manufacturing capacity for specialized ophthalmology channel relationships.
India
Expanding private insurance coverage and underpenetrated chronic dry eye diagnosis create first-mover positioning opportunities. CDSCO fast-track pathways for essential ophthalmic medicines compress approval timelines relative to mature markets. Maharashtra and Gujarat host emerging contract manufacturing capacity targeting export qualification for regulated markets.
China
Contact lens wearer expansion and silicone hydrogel material proliferation generate sustained demand for compatible lubricating solutions. NMPA standards for ophthalmic preparations evolve toward international harmonization while maintaining distinct documentation requirements. Yangtze River Delta manufacturing zones attract sterile filling investments serving domestic and Asia-Pacific regional markets.
Sodium Hyaluronate Eye Drops Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with formulation complexity and regulatory dossier depth determining competitive position. The vendor base concentrates around three specialized biopolymer producers for high-molecular-weight hyaluronic acid inputs, creating upstream leverage that shapes downstream economics. Strategic archetypes include integrated ophthalmic pharmaceutical companies, sterile-focused contract manufacturing organizations, and regional channel specialists with established institutional relationships. Capacity expansion through blow-fill-seal automation and strategic partnerships for preservative-free technology access represent dominant competitive moves.
Among integrated ophthalmic specialists, Alcon and Santen Pharmaceutical exemplify divergent channel strategies. Alcon leverages direct-to-patient platforms to secure recurring revenue streams through subscription-based replenishment programs. Santen Pharmaceutical anchors its position through specialized ophthalmology channel relationships in Asia-Pacific markets. URSAPHARM Arzneimittel GmbH occupies a position within the preservative-free manufacturing tier, where sterile processing capabilities command premium positioning in hospital procurement environments.
| Leading Market Players |
|---|
| Alcon |
| Bausch & Lomb |
| Santen Pharmaceutical |
| Allergan |
| Novartis |
| Johnson and Johnson |
| Bayer Inc. |
| URSAPHARM Arzneimittel GmbH |
| Thea Pharmaceuticals |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap specialists in Baden-Württemberg and Bavaria anchor sterile filling capacity for preservative-free formulations, translating ISO 15378 certification scarcity into sustained pricing power against commodity preserved alternatives. Their ownership structure prioritizes long-term dossier investments over quarterly margin extraction, tightening supply discipline as EU MDR sterility mandates reshape hospital procurement criteria.
Pricing Analysis
Capacity additions in Germany and Japan are reshaping price floors for blow-fill-seal unit-dose production, compressing historical premiums between preservative-free and preserved tiers. Three-tier pricing structure across premium, standard, and economy levels separates ISO 15378-certified sterile formulations from multi-dose preserved alternatives and basic saline substitutes. Pricing pressure stems from REACH-driven reformulation timelines as benzalkonium chloride faces authorization restrictions. Hospital procurement committees demonstrate lowest price sensitivity, prioritizing infection control protocols over per-unit cost.
Supply Chain Analysis
Return flows of expired single-dose vials for material recovery remain underdeveloped, exposing sustainability gaps as ECHA packaging mandates intensify. Fermentation-derived high-molecular-weight hyaluronic acid concentrates among specialized biopolymer producers in Germany, Japan, and the United States, creating input bottlenecks for qualified entrants. Supply chain risk centers on single-source vulnerability for pharmaceutical-grade sodium hyaluronate meeting PMDA molecular weight specifications. Distribution runs through specialized ophthalmology channel relationships in Asia-Pacific and direct-to-patient subscription platforms in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as chronic dry eye therapy shifts toward preservative-free specifications with established reimbursement pathways. Demand migration toward premium sterile formulations rewards dossier depth and regulatory qualification timelines over manufacturing scale alone.
For Market Incumbents: Deploy blow-fill-seal automation to defend position against contract manufacturing organizations capturing hospital procurement volume. Alcon's direct-to-patient subscription platforms demonstrate channel control as a viable lever against retail pharmacy disintermediation. Consolidation of sterile filling talent in Germany and Japan creates geographic moats that mid-scale entrants cannot replicate without 18-24 month qualification cycles.
For New Entrants and Emerging Players: The premium-to-economy price gap in India's underpenetrated chronic dry eye market offers first-mover positioning through CDSCO fast-track pathways. Target adolescent digital eye strain segments lacking established therapeutic guidelines, leveraging telemedicine-enabled prescription renewal to bypass traditional optometry channel capture. Partner with established biopolymer producers for sodium hyaluronate supply security rather than backward integration into fermentation capacity.
For Investors and Strategic Acquirers: Integrated ophthalmic pharmaceutical companies with preservative-free manufacturing capabilities are the most active acquirers in this space, seeking sterile processing assets to complement branded portfolios. Long-term viability hinges on EU MDR compliance positioning and molecular weight specification dossiers that outlast regulatory transition periods. Monitor ECHA authorization timelines for benzalkonium chloride as an inflection signal for accelerated preservative-free transition investments.
| Strategic Initiative | Industry Significance |
|---|---|
| Blow-Fill-Seal Capacity Expansion | URSAPHARM and German CMOs deploy automation to meet EU MDR unit-dose sterility mandates. |
| Preservative-Free Formulation Transition | REACH candidate list pressures force reformulation commitments ahead of authorization restrictions. |
| Direct-to-Patient Platform Development | Alcon captures recurring revenue through subscription replenishment bypassing retail pharmacy. |
| PMDA Dossier Investment | Santen Pharmaceutical anchors Asia-Pacific position through molecular weight specification compliance. |
| ISO 15378 Certification Acceleration | Primary packaging qualification compresses supplier switching timelines for sterile ophthalmic products. |
Study Parameters
Direct dialogue with ophthalmology practice managers, hospital procurement directors, sterile manufacturing engineers, and regulatory affairs specialists at sodium hyaluronate producers grounded qualitative insights. Secondary validation drew from FDA ophthalmic drug guidance documents, EMA MDR implementation guidance, PMDA pharmacopoeial standards, and hospital formulary databases. Bottom-up prescription volume modeling and top-down market sizing triangulated segment-level outputs.
Bottom-up demand modeling tracked patient population flows through dry eye syndrome diagnosis pathways, post-surgical recovery protocols, and contact lens wearer lubricant purchasing patterns across the projection horizon. Segmentation dimensions included formulation type, therapy area, distribution channel, and customer purchasing authority. CAGRs derived from volume-price elasticity analysis calibrated against reimbursement pathway maturity and regulatory transition timelines.
Caveats apply where ECHA authorization decisions or PMDA molecular weight specification revisions could materially shift the outlook for multi-dose preserved alternatives. Forecasts reflect assumptions regarding sterile filling capacity expansion rates and biopolymer producer qualification timelines. Practitioners should monitor REACH substance evaluation outcomes and blow-fill-seal equipment order backlogs for early signals of supply constraint intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
3D Printed Ophthalmic Implants Market
Ophthalmology
Dacryocystitis Treatment Market
Ophthalmology
Optometry/Eye Exam Equipment Market
Ophthalmology
Fungal Eye Infection Market
Ophthalmology
Diabetes Associated Ophthalmic Treatment Market
Ophthalmology
Global Anterior Uveitis Treatment Market
Ophthalmology
Retinal Detachment Diagnostic Market
Ophthalmology
Corneal Ulcer Treatment Market
Ophthalmology
Cataract Treatment Market
Ophthalmology
Asia-Pacific Conjunctivitis Treatment Market
Ophthalmology
Extended and Continuous Wear Lenses Market
Ophthalmology
Japan Dry Eye Syndrome Market
Ophthalmology
Global Advanced Ophthalmology Technologies Market
Ophthalmology
Global Artificial Tear Market
Ophthalmology
Macular Edema and Macular Degeneration Market
Ophthalmology
Eye Infections Treatment Market