
 Global Ophthalmology Market | 2026-2036
Global Ophthalmology Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ophthalmology Market Outlook
Silicone-hydrogel is shifting from niche to mainstream in contact lens formulations, cutting material costs while extending wear-time tolerability. Alcon, Inc. leverages its captive polymer supply chain to defend margin structure across daily disposable portfolios. Essilor International S.A. anchors its position through integrated lens design and retail network density. Carl Zeiss Meditec AG differentiates via optical coherence tomography hardware-software bundling that locks in replacement cycles.
Ophthalmology encompasses the medical and surgical management of eye disorders, spanning refractive correction, cataract extraction, glaucoma filtration, and retinal intervention through instruments achieving micron-level precision. The discipline serves both vision restoration and chronic disease management across outpatient and surgical settings. Diagnostic Equipment commands durable revenue streams because capital platforms require proprietary consumables and software subscriptions. Cataract Surgery applications generate the highest procedure volumes globally, though Refractive Surgery yields superior per-case margins where laser platforms amortize across high-throughput ambulatory settings. Ophthalmic Devices face margin compression where reimbursement pools tighten for mature procedures.
The FDA governs premarket pathways for intraocular lenses and excimer laser systems, while the EMA's MDR recertification demands intensify clinical evidence requirements for European commercial access. ISO 13485 quality management standards shape supplier qualification across OEM supply chains, filtering subscale component vendors from tier-one procurement lists. Stakeholders must weigh regulatory capital intensity against the defensibility of premium positioning as payer scrutiny tightens on ophthalmic procedure economics.
Market Dynamics
The ophthalmology sector is restructuring around software-locked diagnostic platforms that convert capital sales into recurring revenue streams, forcing incumbents to rebuild business models around consumable attach rates rather than hardware margins.
Growth Catalysts
- FDA Breakthrough Devices Program:Accelerated review timelines for novel diagnostic platforms compress time-to-revenue for OCT angiography and AI-guided screening tools, lowering regulatory capital barriers for first-movers.
- Silicone-hydrogel polymerization advances:Extended-wear contact lens formulations now achieve 30-day continuous use tolerability, expanding addressable populations beyond traditional daily-wear segments into overnight orthokeratology applications.
- Ambulatory surgery center expansion:United States outpatient facilities are capturing cataract volume from hospital settings, amortizing femtosecond laser platforms across higher case throughput with same-day discharge protocols.
Market Restraints
- MDR clinical evidence demands:EMA recertification requirements for intraocular lenses now mandate extended follow-up data, extending European commercialization timelines and freezing smaller manufacturers from tier-one hospital procurement lists.
- Heidelberg polymer supply concentration:Specialty silicone-hydrogel raw material production clusters in southwestern Germany, creating single-source vulnerability for contact lens formulators without backward integration into monomer synthesis.
- Excimer laser technical ceiling:Ablation precision asymptotically approaches 0.25 micron accuracy without corresponding gains in biomechanical stability, limiting differentiation among refractive surgery platform vendors.
Strategic Opportunities
- India tier-2 city penetration:Diagnostic equipment deployment in Surat, Lucknow, and Coimbatore remains 60% below metropolitan saturation, offering first-mover advantage for phacoemulsification systems with localized service networks.
- Tele-ophthalmology reimbursement expansion:Medicare remote screening codes now cover diabetic retinopathy detection via smartphone-mounted fundus cameras, unlocking rural United States access without specialist density.
- AI-OCT convergence:Deep learning segmentation algorithms layered on optical coherence tomography hardware automate glaucoma progression detection, reducing specialist interpretation burden and enabling technician-operated screening workflows.
Industry Challenges
- Vitreoretinal surgeon training pipeline:Fellowship positions in submacular surgery and pneumatic retinopexy techniques lag case volume growth, creating procedural backlogs in tertiary centers.
- ISO 13485 supplier recertification:Component vendors face 18-month audit cycles for intraocular lens haptics and injector systems, forcing OEMs to dual-source critical subassemblies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ophthalmology Market |
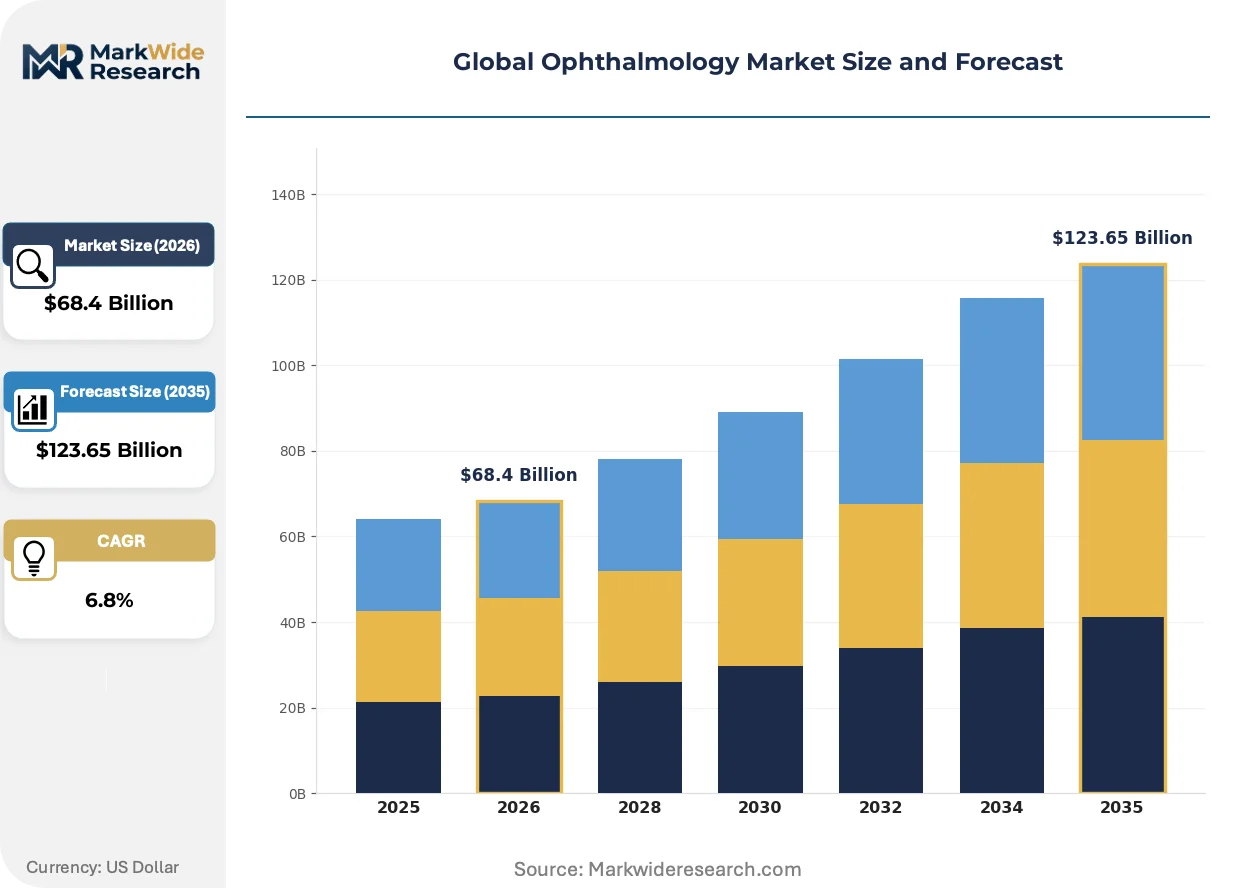
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ophthalmic Devices, Vision Care Products, Surgical Instruments, Diagnostic Equipment Application: Cataract Surgery, Glaucoma Treatment, Retinal Disorders, Refractive Surgery End User: Hospitals, Eye Clinics, Ambulatory Surgery Centers, Research Institutions Technology: Laser Technology, Optical Coherence Tomography, Phacoemulsification, Computerized Diagnosis |
| Companies Covered | Essilor International S.A., Novartis AG, Alcon, Inc., NIDEK CO., LTD., Topcon Corporation, Bausch Health Companies Inc., Johnson & Johnson Vision Care, Inc., Haag-Streit AG, Carl Zeiss Meditec AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ophthalmology Market Strategic Shifts
Digital biomarker extraction from routine imaging is converting ophthalmic diagnostics into predictive disease management platforms, shifting value capture from hardware vendors to algorithm developers and data-integrated care networks.
Extended-depth-of-focus intraocular lenses are electrifying presbyopia-correcting cataract surgery by eliminating halo and glare trade-offs associated with multifocal designs. Premium channel surgeons in the United States and Germany are converting 40% of eligible patients from monofocal to presbyopia-correcting platforms. This optical engineering leap is compressing the addressable market for post-cataract readers and contact lens supplementation.
EMA MDR recertification deadlines are forcing European intraocular lens manufacturers to rebuild clinical evidence packages from legacy CE-marked devices. Small-to-midscale vendors lacking post-market surveillance infrastructure are exiting the market or licensing distribution to larger portfolios. German and French hospital procurement consortia are consolidating supplier lists to three preferred vendors per category to simplify compliance verification.
After-sales service unbundling is disrupting traditional capital equipment contracts across Asian ophthalmology markets. Diagnostic platform purchasers in South Korea and Japan now separate hardware acquisition from software maintenance, training, and consumable supply into distinct procurement decisions. This fragmentation favors modular system architectures over integrated closed platforms, particularly in high-volume screening programs where uptime guarantees outweigh brand loyalty.
Global Ophthalmology Market Segmentation
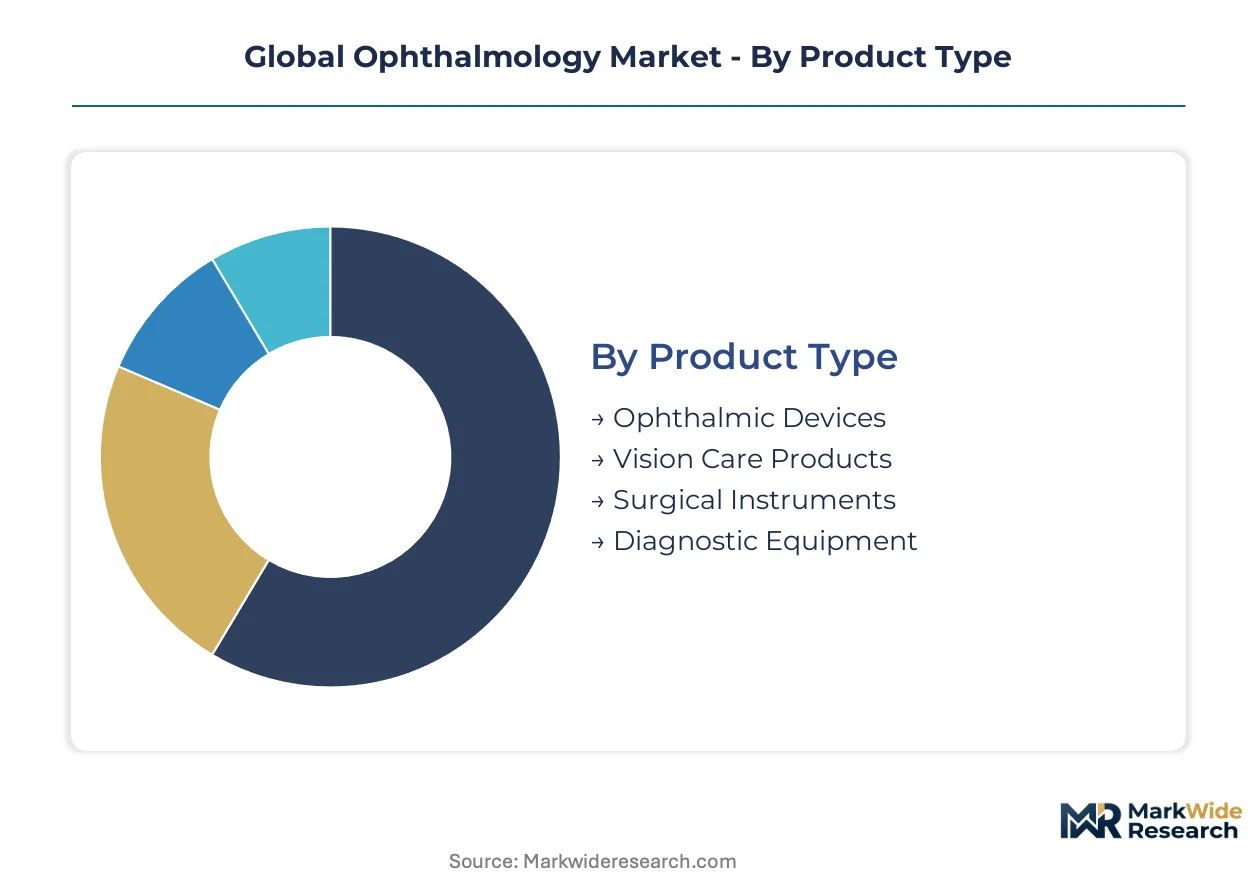
Segmentation in ophthalmology reveals how capital intensity, reimbursement pathways, and clinical workflow requirements fragment purchasing authority across distinct customer archetypes. Supply chain configuration and regulatory burden vary sharply by product category, forcing vendors to maintain parallel go-to-market structures.
Product Type:
Raw material concentration in polymer synthesis and optical-grade ceramics dictates margin resilience across product categories.
- Ophthalmic Devices:Intraocular lenses and contact lenses rely on silicone-hydrogel polymerization chemistry. Alcon's captive monomer supply in Freiburg insulates its daily disposable portfolio from Heidelberg supply shocks. Demand concentrates in United States ambulatory surgery centers where presbyopia-correcting platforms command premium reimbursement.
- Vision Care Products:Contact lens solutions and lens care systems represent recurring revenue attachments to hardware sales. Japanese and South Korean consumers drive single-use preservative-free formulation demand. Essilor's retail network density locks in solution bundling with lens purchases.
- Surgical Instruments:Phacoemulsification handpieces and vitrectomy probes require precision-machined titanium and disposable silicone sleeves. OEMs dual-source critical subassemblies to navigate ISO 13485 recertification delays.
- Diagnostic Equipment:OCT platforms and fundus cameras generate durable revenue through software subscriptions and proprietary consumables. Hardware-software bundling locks in replacement cycles at tertiary centers.
Today's leader: Ophthalmic Devices. Tomorrow's challenger: Diagnostic Equipment.
Application:
Procedure volume and per-case margin create divergent investment profiles across surgical applications.
- Cataract Surgery:Femtosecond laser platforms and advanced IOLs dominate capital allocation. United States outpatient facilities amortize equipment costs across high-throughput protocols. German hospital procurement consortia consolidate supplier lists to three preferred vendors per category.
- Refractive Surgery:Excimer and femtosecond laser systems yield superior per-case margins where platforms achieve utilization thresholds. South Korean and Japanese consumers drive premium SMILE procedure adoption.
- Glaucoma Treatment:Minimally invasive glaucoma surgery devices and sustained-release drug delivery systems address compliance failures in topical therapy. FDA Breakthrough Device designation accelerates novel implant pathways.
- Retinal Disorders:Anti-VEGF injection volume and vitrectomy complexity drive instrument sophistication. Fellowship training pipeline constraints create procedural backlogs in United States tertiary centers.
Cataract Surgery commands current revenue concentration. Refractive Surgery offers the steepest expansion trajectory as myopia prevalence climbs in East Asian youth populations.
End User:
Capital availability and procurement autonomy determine pricing power and contract structure.
- Hospitals:Integrated health systems leverage volume concentration for tiered pricing across premium, standard, and economy IOL tiers. EMA MDR recertification demands freeze smaller manufacturers from procurement lists.
- Ambulatory Surgery Centers:United States outpatient facilities capture cataract volume through same-day discharge protocols. After-sales service unbundling favors modular diagnostic architectures over integrated platforms.
- Eye Clinics:Private practice ophthalmologists prioritize equipment financing flexibility and localized service networks. Indian tier-2 cities present deployment gaps in Surat, Lucknow, and Coimbatore.
- Research Institutions:Academic medical centers drive AI-OCT algorithm development and clinical validation. Deep learning segmentation tools automate glaucoma progression detection.
Ambulatory Surgery Centers are gaining share fastest. Hospitals retain negotiating leverage through consolidated procurement.
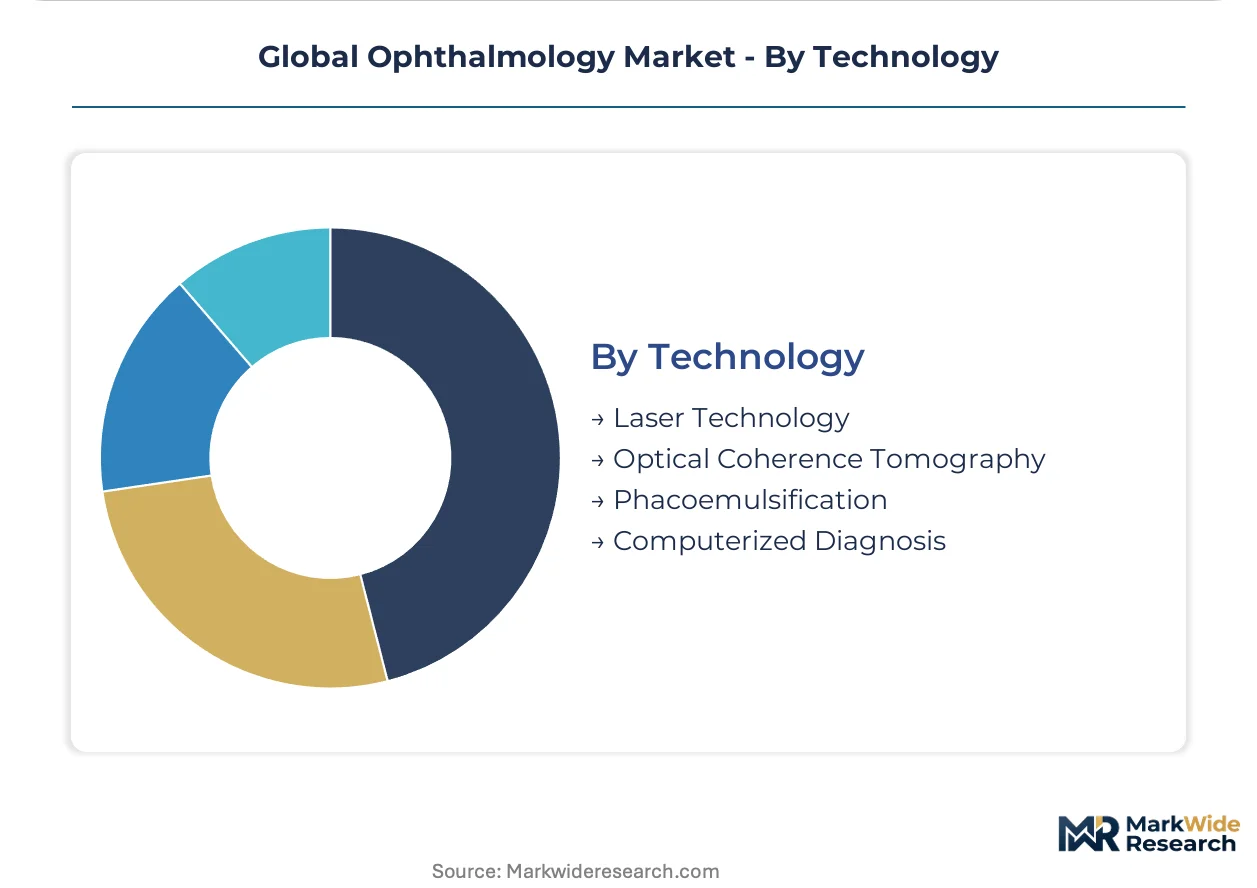
Technology:
Platform maturity and software-lock potential differentiate competitive durability.
- Optical Coherence Tomography:Hardware-software bundling creates replacement cycle predictability. Carl Zeiss Meditec's angiography modules lock in tertiary center loyalty through proprietary analysis workflows.
- Laser Technology:Excimer ablation precision approaches technical ceilings without biomechanical stability gains. Differentiation shifts to femtosecond flap creation and SMILE lenticule extraction.
- Phacoemulsification:Fluidics engineering and handpiece ergonomics determine surgeon preference. Localized service networks prove decisive in emerging market penetration.
- Computerized Diagnosis:AI-guided screening tools and smartphone-mounted fundus cameras unlock rural United States access through Medicare remote screening codes.
Optical Coherence Tomography anchors current platform revenue. Computerized Diagnosis represents the most disruptive substitution threat.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Heidelberg's silicone-hydrogel polymerization cluster anchors European ophthalmic materials supply, while United States ambulatory surgery centers drive premium device uptake. Japan and South Korea shape East Asian refractive surgery demand. India's tier-2 cities present deployment gaps for diagnostic platforms.
United States
Medicare remote screening codes for diabetic retinopathy detection unlock rural access through smartphone-mounted fundus cameras. FDA Breakthrough Devices Program accelerates OCT angiography and AI-guided screening tool approvals. Ambulatory surgery centers in Florida and Texas capture cataract volume from hospital settings through same-day discharge protocols.
Germany
EMA MDR recertification demands freeze smaller intraocular lens manufacturers from hospital procurement lists. German hospital procurement consortia consolidate supplier lists to three preferred vendors per category to simplify compliance verification. The Heidelberg polymer synthesis cluster supplies specialty silicone-hydrogel raw materials to contact lens formulators.
Japan
PMDA regulatory pathways shape premium refractive surgery platform approvals for SMILE lenticule extraction procedures. METI industrial policy supports domestic ophthalmic laser manufacturing. Tokyo and Osaka metropolitan areas concentrate femtosecond laser platform utilization across high-throughput screening networks.
India
Phacoemulsification system deployment in Surat, Lucknow, and Coimbatore remains 60% below metropolitan saturation levels. CDSCO medical device regulations govern intraocular lens and diagnostic equipment import licensing. Localized service networks prove decisive for equipment vendors penetrating tier-2 city markets.
South Korea
After-sales service unbundling disrupts traditional capital equipment contracts across diagnostic platform procurement. MFDS regulatory frameworks govern ophthalmic laser system approvals. Seoul metropolitan area consumers drive premium SMILE procedure adoption among East Asian youth populations.
Global Ophthalmology Market Competitive Environment
Global majors compete with regional champions across polymer supply chains and diagnostic platform distribution networks. The vendor base stratifies into three tiers: integrated multinationals with captive raw material supply, specialized equipment manufacturers with hardware-software bundling capabilities, and regional formulators dependent on external polymer sourcing. Two dominant competitive moves define current positioning: backward integration into monomer synthesis to defend margin structures, and AI-algorithm licensing to convert capital sales into recurring diagnostic revenue streams.
Within the integrated multinational tier, Alcon, Inc. and Essilor International S.A. exemplify divergent defensive strategies. Alcon anchors its position through captive silicone-hydrogel supply chain control in southwestern Germany. Essilor occupies a position defined by retail network density and lens-solution bundling across European and Asian markets. Carl Zeiss Meditec AG represents the hardware-software convergence archetype, with optical coherence tomography platforms that lock replacement cycles through proprietary analysis workflows.
| Leading Market Players |
|---|
| Essilor International S.A. |
| Novartis AG |
| Alcon, Inc. |
| NIDEK CO., LTD. |
| Topcon Corporation |
| Bausch Health Companies Inc. |
| Johnson & Johnson Vision Care, Inc. |
| Haag-Streit AG |
| Carl Zeiss Meditec AG |
| Others |
Value Chain & Pricing Dynamics
Silicone-hydrogel polymerization advances are compressing unit economics for daily disposable contact lenses while concentrating raw material supply in southwestern Germany. This dual effect amplifies margin pressure for formulators lacking captive monomer synthesis against Alcon's integrated Freiburg operations.
Pricing Analysis
Input-cost pass-through from specialty silicone-hydrogel monomers drives pricing stratification across premium, standard, and economy tiers of intraocular lenses. Price differentiation hinges on FDA Breakthrough Device designation and ISO 13485 certification grade, with tertiary centers absorbing premium markups for presbyopia-correcting platforms. Cost compression in economy IOL segments is intensifying because EMA MDR recertification demands freeze smaller manufacturers from hospital procurement lists. Ambulatory surgery centers exhibit highest price sensitivity due to same-day discharge protocol economics, while integrated health systems leverage volume concentration for tiered contracting.
Supply Chain Analysis
Regional distribution centers in Frankfurt, Singapore, and Dallas orchestrate hub-and-spoke patterns for phacoemulsification handpieces and diagnostic platforms. Geographic supply concentration centers on Germany for silicone-hydrogel polymers, Japan for precision optical components, and the United States for femtosecond laser assemblies. Raw material dependencies draw from titanium for surgical instruments, optical-grade ceramics for IOL haptics, and proprietary software licenses for OCT analysis modules. Single-source vulnerability in Heidelberg's monomer synthesis cluster poses structural risk to contact lens formulators without backward integration. Distribution runs through hospital procurement consortia in Europe and GPO contracts in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between United States ambulatory surgery centers and Indian tier-2 cities exploits reimbursement stability differentials against CDSCO import licensing cost structures.
For Market Incumbents: Deepen captive supply control over silicone-hydrogel monomer synthesis to defend margin structure against polymer supply shocks from Heidelberg concentration. Invest in AI-OCT algorithm development to convert hardware sales into recurring diagnostic revenue streams, countering modular platform unbundling in South Korea and Japan. For New Entrants and Emerging Players: Enter via smartphone-mounted fundus camera deployment for Medicare-covered diabetic retinopathy screening in rural United States markets. Target tele-ophthalmology reimbursement expansion as the most penetrable application layer, leveraging technician-operated workflows to bypass specialist density constraints. For Investors and Strategic Acquirers: Valuations sit cheapest among regional diagnostic equipment vendors lacking software-locked replacement cycles. Long-term viability across the analysis window favors platforms with consumable attach rates and proprietary algorithm licensing. Watch FDA Breakthrough Device designation velocity as the inflection signal for regulatory capital efficiency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Synthesis | Alcon's Freiburg captive supply insulates daily disposable margins from Heidelberg polymer shocks. |
| AI-OCT Software Companion Development | Deep learning segmentation algorithms automate glaucoma detection for technician-operated screening workflows. |
| CE Marking Pathway Investment | EMA MDR recertification demands freeze smaller IOL manufacturers from German hospital procurement lists. |
| Hospital System Partnership | United States ambulatory surgery centers amortize femtosecond laser costs across high-throughput cataract protocols. |
| Reimbursement Strategy | Medicare remote screening codes unlock rural diabetic retinopathy detection without specialist density. |
Study Parameters
Direct dialogue with hospital purchasing committees, GPO contracts managers, biomedical engineers, and ophthalmic surgeons grounded qualitative insights. Secondary validation drew from FDA 510(k) filings, EMA MDR submission databases, CMS Medicare reimbursement schedules, and hospital procurement consortium records. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across product type, application, end user, and technology dimensions.
Top-down macroeconomic indicators anchored aggregate market sizing, while bottom-up procedure volume and equipment placement data refined segment-level outputs across the projection horizon. Segmentation dimensions modeled include product category intensity, surgical application workflow, capital availability tier, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to normalized baseline data, incorporating FDA approval velocity, EMA recertification timelines, and ambulatory surgery center expansion rates as ophthalmology-specific forecast inputs.
Inputs from FDA filings and EMA submission databases were available through the study window; gaps in real-time ambulatory surgery center equipment utilization data introduce uncertainty bands around near-term diagnostic platform forecasts. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Ophthalmic Lasers Therapeutic Market
Ophthalmology
Age Related Vision Dysfunction Market
Ophthalmology
Europe Ophthalmology Market
Ophthalmology
Retinal Detachment Market
Ophthalmology
Bullous Keratopathy Market
Ophthalmology
India Ophthalmic Clinical Trials Market
Ophthalmology
Personalized LASIK Surgery Market
Ophthalmology
Fungal Eye Infection Market
Ophthalmology
Lubricating Eye Drops Market
Ophthalmology
Nystagmus Market
Ophthalmology
Corneal Ulcer Treatment Market
Ophthalmology
Herpes Zoster Ophthalmicus Market
Ophthalmology
Uveal Melanoma Market
Ophthalmology
Europe Dry Eye Syndrome Market
Ophthalmology
Lazy Eye Market
Ophthalmology
Conjunctivitis Market