
 Corneal Ulcer Treatment Market | 2026-2036
Corneal Ulcer Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Corneal Ulcer Treatment Market Analysis
Gene-therapy-enabled ocular delivery is tilting research priorities toward sustained-release platforms that reduce dosing frequency. Pfizer Inc. leverages its infectious disease pipeline to compete in antibiotic ophthalmic formulations. Novartis AG anchors its position through advanced corticosteroid combinations. Sun Pharmaceutical Industries Ltd. differentiates via cost-engineered generic antifungal therapies for emerging markets.
Corneal ulcer treatment encompasses pharmaceutical and surgical interventions targeting epithelial defects caused by bacterial, fungal, viral, or parasitic pathogens, typically administered through topical drops achieving therapeutic concentrations at the tear film-cornea interface. The primary purpose is to eradicate infection, modulate inflammation, and prevent stromal melting or perforation that leads to vision loss. Antibiotics retain the largest revenue share among product types due to bacterial ulcers comprising the dominant indication globally, while ocular delivery modes command premium pricing because of their targeted bioavailability advantages. Hospitals absorb the majority of systemic and injectable volumes, though ambulatory surgical centers are capturing shift volumes from cost-containment programs.
The FDA regulates ophthalmic drug safety through stringent sterility and endotoxin standards, while the EMA's MDR framework imposes enhanced clinical evidence requirements for Class III ocular devices. WHO inclusion of fungal keratitis on its neglected tropical disease watchlist is redirecting public procurement budgets toward antifungal capacity in endemic zones. Stakeholders must monitor reimbursement pathway divergence between topical and systemic administration modes as payers tighten prior authorization criteria.
Market Dynamics
The FDA's sterility and endotoxin standards for ophthalmic formulations are compressing development timelines while forcing manufacturers toward closed-system manufacturing investments. Hospital ophthalmology departments are consolidating procurement around sustained-release platforms that reduce nursing burden and readmission risk.
Growth Catalysts
- WHO Neglected Tropical Disease Watchlist:The inclusion of fungal keratitis redirects public procurement budgets toward antifungal capacity in endemic zones across South Asia and sub-Saharan Africa.
- EMA MDR Framework:Enhanced clinical evidence requirements for Class III ocular devices accelerate differentiation toward premium bioadhesive delivery systems with documented safety profiles.
- Gene-Therapy Platforms:Viral vector and lipid nanoparticle advances enable single-administration corneal gene editing, reducing lifetime treatment costs for herpetic ulcer recurrence.
Market Restraints
- API Supply Concentration:Fluoroquinolone and amphotericin B active pharmaceutical ingredients concentrate among Indian and Chinese contract manufacturers, exposing formulators to export license volatility.
- Reimbursement Divergence:US commercial payers and Medicare Advantage plans impose divergent prior authorization criteria for topical versus systemic administration, fragmenting prescribing patterns.
- Corneal Perforation Risk:Corticosteroid monotherapy without antimicrobial coverage accelerates stromal melting in misdiagnosed fungal ulcers, limiting off-label expansion.
Strategic Opportunities
- Teleophthalmology Triage:Remote corneal imaging and AI-assisted ulcer classification enable rural penetration in Brazil and Mexico where specialist density remains below WHO thresholds.
- Bioresorbable Collagen Shields:Integration of antibiotic-loaded collagen matrices with bandage contact lenses creates premium outpatient procedure bundles for ambulatory surgical centers.
- Japan PMDA Sakigake Pathway:Expedited review for regenerative medicine products accelerates entry for limbal stem cell therapies targeting chemical burn sequelae.
Industry Challenges
- Microbiologist Workforce Scarcity:Diagnostic laboratories in secondary markets lack personnel trained in corneal scraping culture and confocal microscopy interpretation, delaying pathogen identification.
- Good Manufacturing Practice Retrofit Costs:Legacy ophthalmic drop facilities require isolator technology and continuous particulate monitoring investments to meet revised FDA guidance on sterile processing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corneal Ulcer Treatment Market |
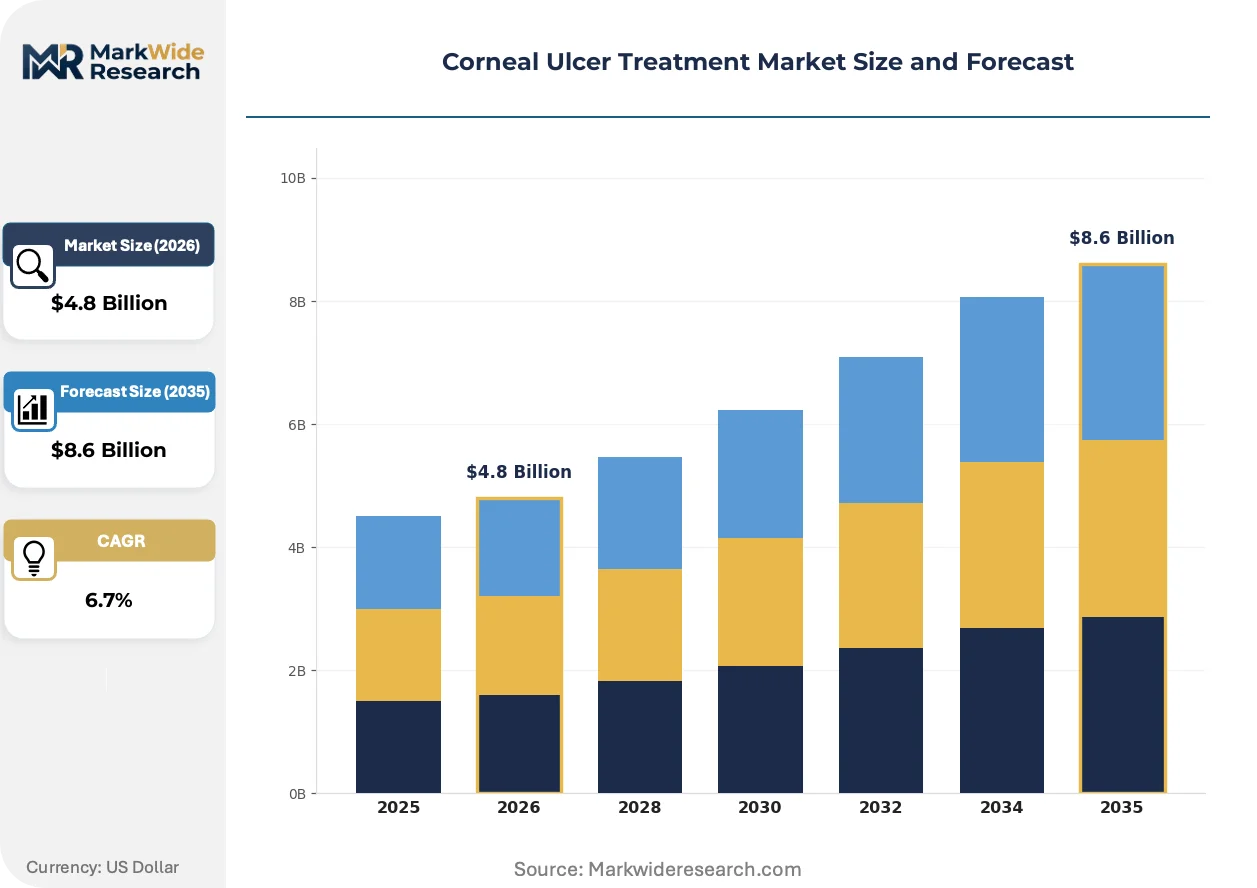
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Antifungals, Corticosteroids, Antivirals Delivery Mode: Topical, Systemic, Injectable, Ocular End User: Ophthalmology Clinics, Hospitals, Homecare Settings, Ambulatory Surgical Centers Indication: Bacterial Ulcer, Fungal Ulcer, Viral Ulcer, Others |
| Companies Covered | Pfizer Inc., Novartis AG, Sanofi, GlaxoSmithKline plc, Allergan, Bayer AG, Sun Pharmaceutical Industries Ltd., Teva Pharmaceutical Industries Ltd., Dr. Reddy’s Laboratories Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corneal Ulcer Treatment Market Emerging Trajectories
Sustained-release ocular delivery systems are compressing the competitive landscape by collapsing multi-dose regimens into single-intervention protocols. Formulation science, regulatory science, and care delivery models are converging around value-based outcomes.
Nanostructured lipid carriers and in situ gelling systems are hybridizing conventional eye drop viscosity with controlled-release kinetics. Academic medical centers in the United States and Germany are piloting these platforms for neurotrophic ulcer populations requiring months of therapy. The technology is hybridizing manufacturing requirements by demanding both sterile fill-finish and complex emulsion stability expertise that few contract development organizations possess.
The EMA's Medical Device Regulation imposes post-market surveillance obligations on ocular drug-device combinations previously regulated as drugs alone. Manufacturers must now maintain clinical follow-up registries for collagen shields and punctal plugs delivering antifungal agents. European hospital formularies are responding by restricting combination product access to centers with documented adverse event reporting capabilities.
Institutional procurement committees are unbundling pharmaceutical supply from surgical service contracts, enabling direct negotiation with specialty pharmacies. Ambulatory surgical centers in Florida and Texas are contracting with mail-order ophthalmic pharmacies for perioperative antibiotic prophylaxis. This disintermediation is most visible in Medicare Advantage networks where capitated payment structures reward inventory reduction.
Corneal Ulcer Treatment Market Segmentation
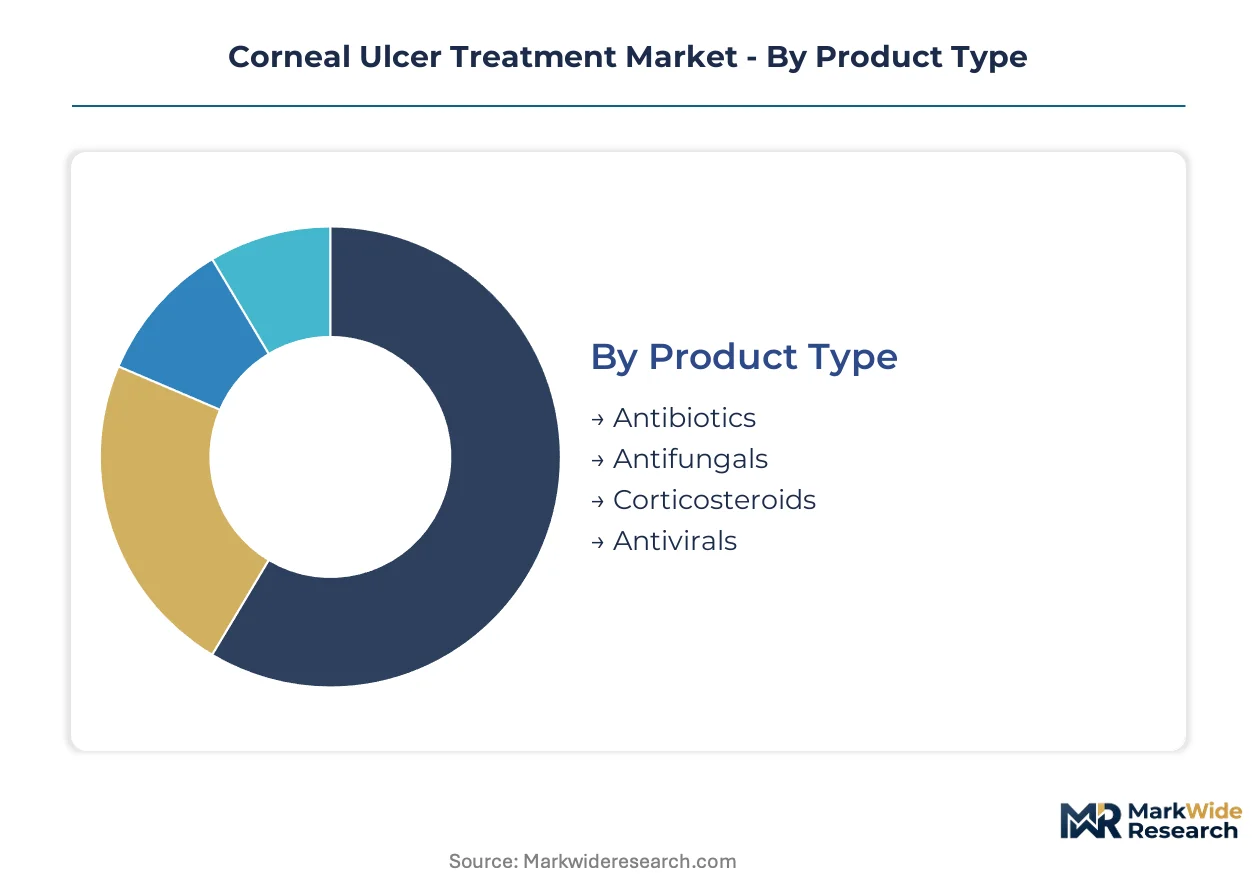
Corneal ulcer treatment markets fragment across therapeutic modality, administration route, and care setting. Each dimension carries distinct margin profiles, regulatory pathways, and procurement dynamics that reshape competitive positioning.
Product Type:
Cost tier stratification separates premium biologics from commoditized small-molecule formulations.
- Antibiotics:Fluoroquinolone and aminoglycoside formulations dominate bacterial keratitis protocols. Hospital formularies in the United States consolidate procurement around moxifloxacin and ciprofloxacin drops for Pseudomonas coverage.
- Antifungals:Natamycin and amphotericin B suspensions address filamentous fungal pathogens. Demand concentrates in South India and Ghana where agricultural trauma drives Fusarium and Aspergillus incidence.
- Corticosteroids:Prednisolone acetate and dexamethasone combinations modulate stromal inflammation post-antimicrobial initiation.
- Antivirals:Ganciclovir and trifluridine target herpetic dendritic ulcers and neurotrophic defects.
Antibiotics hold installed capacity. Antifungals are rotating up the share rankings.
Delivery Mode:
Application specificity determines bioavailability thresholds and reimbursement coding.
- Topical:Eye drops and ointments achieve tear film concentrations through frequent dosing regimens. Medicare Advantage plans in Florida and Texas impose prior authorization limits on branded topical formulations.
- Ocular:Intravitreal and intracameral injections, collagen shields, and sustained-release implants bypass epithelial barriers. Academic medical centers in Germany and Japan pilot lipid nanoparticle depots for neurotrophic ulcer populations.
- Systemic:Oral fluconazole and voriconazole address deep stromal involvement or impending perforation.
- Injectable:Subconjunctival and intrastromal antibiotic delivery reserves for non-responsive microbial keratitis.
Topical formulations hold installed capacity. Ocular delivery modes are rotating up the share rankings.
End User:
Customer type dictates procurement authority and outcome accountability structures.
- Hospitals:Tertiary ophthalmology departments manage perforated ulcers and therapeutic keratoplasty. The EMA's MDR framework requires Class III device registries for collagen shield combinations used in European hospital settings.
- Ambulatory Surgical Centers:Same-day procedures bundle bandage contact lens fitting with antibiotic prophylaxis. Centers in Texas and Arizona contract directly with mail-order specialty pharmacies to reduce inventory carrying costs.
- Ophthalmology Clinics:Private practice settings handle uncomplicated bacterial ulcers through empirical therapy protocols.
- Homecare Settings:Self-administered drop regimens require patient education and adherence monitoring infrastructure.
Hospitals hold installed capacity. Ambulatory surgical centers are rotating up the share rankings.
Indication:
Volume distribution tracks epidemiological burden and diagnostic accuracy in target populations.
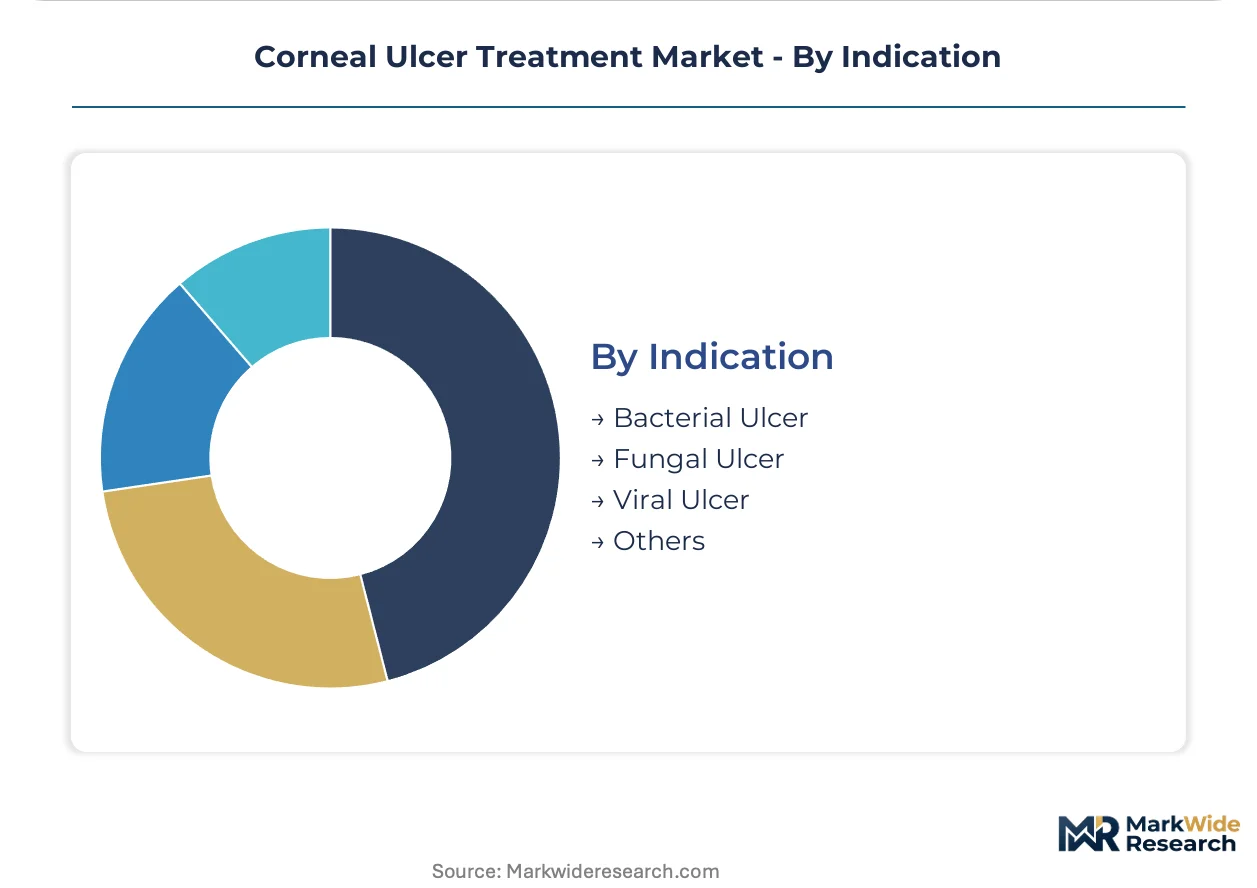
- Bacterial Ulcer:Pseudomonas aeruginosa and Staphylococcus aureus dominate contact lens-related cases. The FDA's sterility standards for preserved multi-dose bottles shape manufacturing investments for bacterial ulcer therapies.
- Fungal Ulcer:Filamentous fungi and yeast infections concentrate in tropical agricultural zones. WHO inclusion on the neglected tropical disease watchlist redirects public procurement budgets in India and Nigeria toward antifungal capacity.
- Viral Ulcer:Herpes simplex virus recurrence drives chronic management populations.
- Others:Acanthamoeba and microsporidial ulcers represent diagnostic challenges requiring confocal microscopy expertise.
Bacterial ulcer holds installed capacity. Fungal ulcer is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in the United States concentrate purchasing authority for advanced ocular delivery systems. Tertiary ophthalmology departments in Germany and Japan drive adoption of sustained-release platforms. Agricultural trauma patterns in India and Brazil sustain antifungal demand corridors.
United States
Specialized corneal care centers in Florida and Texas generate treatment volume through Medicare Advantage networks. The FDA's sterility guidance for ophthalmic formulations shapes manufacturing investments. Academic medical clusters in Boston and Baltimore pilot lipid nanoparticle depots for neurotrophic ulcer populations.
Germany
EMA MDR framework compliance costs filter hospital formulary access toward premium bioadhesive delivery systems. The country's national pharmaceutical regulator mandates Class III device registries for collagen shield combinations. Industrial concentration around Frankfurt and Munich supports sterile fill-finish contract manufacturing capacity.
India
Agricultural trauma drives Fusarium and Aspergillus incidence across South Indian states. WHO inclusion of fungal keratitis on the neglected tropical disease watchlist redirects public procurement budgets. Manufacturing clusters in Hyderabad and Ahmedabad supply fluoroquinolone active pharmaceutical ingredients to global formulators.
Japan
PMDA Sakigake pathway accelerates entry for regenerative medicine products targeting chemical burn sequelae. The national pharmaceutical regulator expedites review timelines for limbal stem cell therapies. Tokyo and Osaka academic centers anchor clinical trial infrastructure for gene-therapy-enabled ocular delivery.
Brazil
Teleophthalmology triage platforms penetrate rural zones where specialist density remains below WHO thresholds. The national health surveillance agency regulates import licensing for antifungal ophthalmic suspensions. São Paulo and Rio de Janeiro concentrate diagnostic laboratory capacity for corneal scraping culture interpretation.
Corneal Ulcer Treatment Market Vendor Landscape
Channel-controlling players compete with product-specialist players across distinct margin tiers. The market structure consolidates around multinational pharmaceutical conglomerates with infectious disease pipelines, while mid-scale generic manufacturers capture volume in emerging markets. Strategic archetypes include R&D-intensive innovators, cost-engineered generic suppliers, and regional distribution specialists. Dominant competitive moves encompass portfolio diversification into sustained-release platforms and geographic expansion through contract manufacturing partnerships.
Within the innovation-driven tier, Pfizer Inc. and Novartis AG exemplify multinational pharmaceutical conglomerates with established ophthalmic divisions. Sun Pharmaceutical Industries Ltd. occupies a position among cost-optimized generic manufacturers serving price-sensitive markets. These three entities represent the spectrum from premium branded formulations to commoditized small-molecule therapies.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Novartis AG |
| Sanofi |
| GlaxoSmithKline plc |
| Allergan |
| Bayer AG |
| Sun Pharmaceutical Industries Ltd. |
| Teva Pharmaceutical Industries Ltd. |
| Dr. Reddy's Laboratories Ltd. |
| Others |
Supply Flow & Price Mechanics
Air freight corridors connecting Hyderabad and Ahmedabad to Frankfurt and Munich carry active pharmaceutical ingredients whose cost volatility propagates through fluoroquinolone formulation pricing. These logistics dynamics compress margins for generic manufacturers while enabling branded players to sustain premium positioning through supply security guarantees.
Pricing Analysis
Cost-plus contracts with Indian and Chinese API suppliers index to commodity chemical benchmarks and currency fluctuations. Three-tier pricing structure across premium, standard, and economy levels separates patented sustained-release platforms from branded generics and commoditized drops. Cost compression in the generic tier is intensifying because Medicare Advantage prior authorization limits favor lower-cost alternatives. Ambulatory surgical centers exhibit highest price sensitivity due to capitated reimbursement structures, while academic medical centers accept premium pricing for documented outcome advantages.
Supply Chain Analysis
Export control regimes restricting dual-use biologics manufacturing equipment limit capacity expansion for lipid nanoparticle depots in emerging markets. API production concentrates in India, China, and the United States, with sterile fill-finish capacity clustering in Germany and Japan. Formulation science draws from fluoroquinolone precursors, amphotericin B fermentation stocks, and collagen matrix biomaterials. Single-source vulnerability runs through Indian contract manufacturers dependent on Chinese chemical intermediates. Distribution runs through hospital formularies, specialty pharmacy mail-order, and ambulatory surgical center direct contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Corneal ulcer treatment markets reward service-attach models where patient adherence monitoring and remote imaging subscriptions expand faster than pharmaceutical unit sales. Recurring revenue from teleophthalmology triage platforms outpaces hardware growth in Brazil and Mexico.
For Market Incumbents: Build regulatory data moats through FDA Class III device registries and EMA post-market surveillance infrastructure for collagen shield combinations. Consolidate procurement relationships with Medicare Advantage networks in Florida and Texas through outcome-based contracting. Counter generic erosion by anchoring hospital formulary position with sustained-release platform bundles that reduce nursing burden.
For New Entrants and Emerging Players: Pursue teleophthalmology-enabled rural penetration in Brazil and Mexico where specialist density gaps create white-space opportunity. Target fungal keratitis protocols in South India and Ghana where WHO watchlist status redirects public procurement budgets. Launch through diagnostic laboratory partnerships that address microbiologist workforce scarcity with AI-assisted culture interpretation.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational pharmaceutical conglomerates divesting ophthalmic divisions to sharpen infectious disease focus. Long-term viability hinges on sustained-release platform differentiation and gene-therapy pipeline optionality. Monitor FDA guidance evolution on sterile processing as inflection signal for manufacturing asset repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | PMDA Sakigake expedites limbal stem cell therapy entry in Japan. |
| Manufacturing Scale-Up | Closed-system isolator investments meet FDA sterility guidance revisions. |
| Hospital System Partnership | Academic medical centers in Boston pilot lipid nanoparticle depot protocols. |
| Reimbursement Strategy | Medicare Advantage prior authorization navigation unlocks ambulatory surgical center volume. |
| Pipeline Diversification | Gene-therapy platforms reduce lifetime treatment costs for herpetic recurrence. |
Methodological Framework
The analysis maps antibiotic, antifungal, corticosteroid, and antiviral therapeutic segments, each validated through hospital formulary directors, ambulatory surgical center procurement managers, regulatory affairs specialists, and teleophthalmology platform developers. Primary interviews combined with secondary validation from FDA filings, EMA MDR submissions, WHO neglected tropical disease reports, and hospital procurement databases. Bottom-up prescription volume modeling triangulated against top-down pharmaceutical revenue estimates.
Assumptions held fixed include regulatory pathway timelines and reimbursement code stability, while API pricing and teleophthalmology adoption rates varied across sensitivity scenarios. Segmentation dimensions span product type, delivery mode, end user, and indication, with regional regulatory clusters modeled separately. CAGRs derived from fitted growth curves applied to base-year estimates. Forecast inputs incorporated WHO fungal keratitis watchlist implementation pace and sustained-release platform clinical trial readouts.
Macroeconomic conditions sit as an overlay; deviation in currency exchange rates, freight costs, or healthcare reimbursement policy would shift the trajectory. Forecasts reflect documented assumptions on sterile manufacturing capacity expansion and teleophthalmology regulatory clearance timelines. Material shifts in FDA guidance on ophthalmic drug-device combination classification would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Epidemic Keratoconjunctivitis Treatment Market
Ophthalmology
Presbyopia Treatment Market
Ophthalmology
Bullous Keratopathy Market
Ophthalmology
Cataract Treatment Market
Ophthalmology
Ophthalmic Loupes Market
Ophthalmology
Global Artificial Tear Market
Ophthalmology
Vernal Keratoconjunctivitis Market
Ophthalmology
India Ophthalmic Clinical Trials Market
Ophthalmology
Europe Primary Angle-Closure Glaucoma Market
Ophthalmology
Blepharitis Treatment Market
Ophthalmology
Global Diabetic Macular Edema Market
Ophthalmology
Global Ophthalmology Market
Ophthalmology
Vitrectomy Machines Market
Ophthalmology
Tobramycin Eye Drop Market
Ophthalmology
Ophthalmology Diagnostics and Surgical Devices Market
Ophthalmology
USA Ophthalmic Devices Market