
 Keratoconus Treatment Market | 2026-2036
Keratoconus Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Keratoconus Treatment Market Outlook
Japanese specialty lens manufacturers is recalibrating production capacity to meet surging orders for scleral and hybrid designs. HOYA leverages precision molding expertise to dominate rigid gas-permeable segments across Asia-Pacific. Johnson & Johnson Services, Inc. sustains brand loyalty through extensive professional education networks. The Cooper Companies, Inc. competes on fitting technology integration that reduces chair time for practitioners.
Keratoconus treatment encompasses clinical interventions that halt corneal ectasia progression and restore functional vision through collagen cross-linking, custom lens optics, or tissue replacement procedures. Corneal cross-linking employs riboflavin-UVA photochemistry to stiffen stromal collagen, with irradiance protocols typically ranging from 3 to 30 mW/cm² depending on accelerated versus conventional timelines. Contact lenses and cross-linking solutions command the largest revenue pools due to recurring lens replacement cycles and expanding reimbursement for outpatient procedures. Surgical treatments and new keratoplasty techniques represent the fastest-expanding category as femtosecond laser-assisted deep anterior lamellar keratoplasty gains traction among corneal specialists seeking to reduce rejection risk.
FDA premarket approval requirements for corneal cross-linking devices establish efficacy benchmarks that shape R&D investment priorities for manufacturers seeking US market entry. CE marking under the EU Medical Device Regulation and Japan's PMDA Shonin pathway impose parallel clinical evidence standards that filter competitor participation in developed markets. Stakeholders must monitor evolving reimbursement decisions by national health technology assessment bodies, as coverage expansion for cross-linking versus transplantation directly shifts procedure volumes and device procurement patterns.
Market Dynamics
Corneal cross-linking device manufacturers face intensifying FDA premarket approval scrutiny that is compressing commercialization timelines and forcing earlier-stage clinical investment than historical norms allowed.
Growth Catalysts
- CE marking under EU MDR:Stricter clinical evidence requirements for corneal cross-linking devices are filtering out marginal competitors and consolidating procurement decisions among hospitals with dedicated ophthalmology infrastructure.
- Younger myopic populations:Rising specialty contact lens adoption among patients aged 18-35 is expanding the addressable base for early keratoconus intervention before ectasia progression necessitates surgical alternatives.
- Femtosecond laser platforms:Precision cutting capabilities are enabling deep anterior lamellar keratoplasty techniques that reduce rejection risk compared to penetrating procedures.
Market Restraints
- Riboflavin supply concentration:Photochemical precursor manufacturing clusters in select European chemical hubs create vulnerability to input cost volatility and regulatory inspection backlogs.
- Reimbursement heterogeneity:Divergent national health technology assessment decisions across Germany, Japan, and the United States fragment procedure volume predictability and device procurement planning.
- Technical limitation in thin corneas:Cross-linking efficacy drops below 400 microns stromal thickness, excluding advanced-stage patients from minimally invasive options and pushing volume toward keratoplasty.
Strategic Opportunities
- Accelerated irradiance protocols:30 mW/cm² UVA delivery systems are converging with office-based surgical suites to enable same-day diagnosis and treatment workflows.
- Hybrid lens designs:Scleral-rigid combinations address comfort complaints that drive discontinuation among traditional gas-permeable wearers.
- Japan's PMDA Shonin pathway:Streamlined approval for devices with prior FDA clearance creates expedited market entry for manufacturers with established US clinical packages.
Industry Challenges
- Corneal specialist training pipelines:Fellowship programs produce fewer cross-linking-certified surgeons than procedure volume growth requires, creating regional access disparities.
- Device-hospital integration complexity:Cross-linking systems require optical coherence tomography compatibility and EMR connectivity that legacy ophthalmology suites lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Keratoconus Treatment Market |
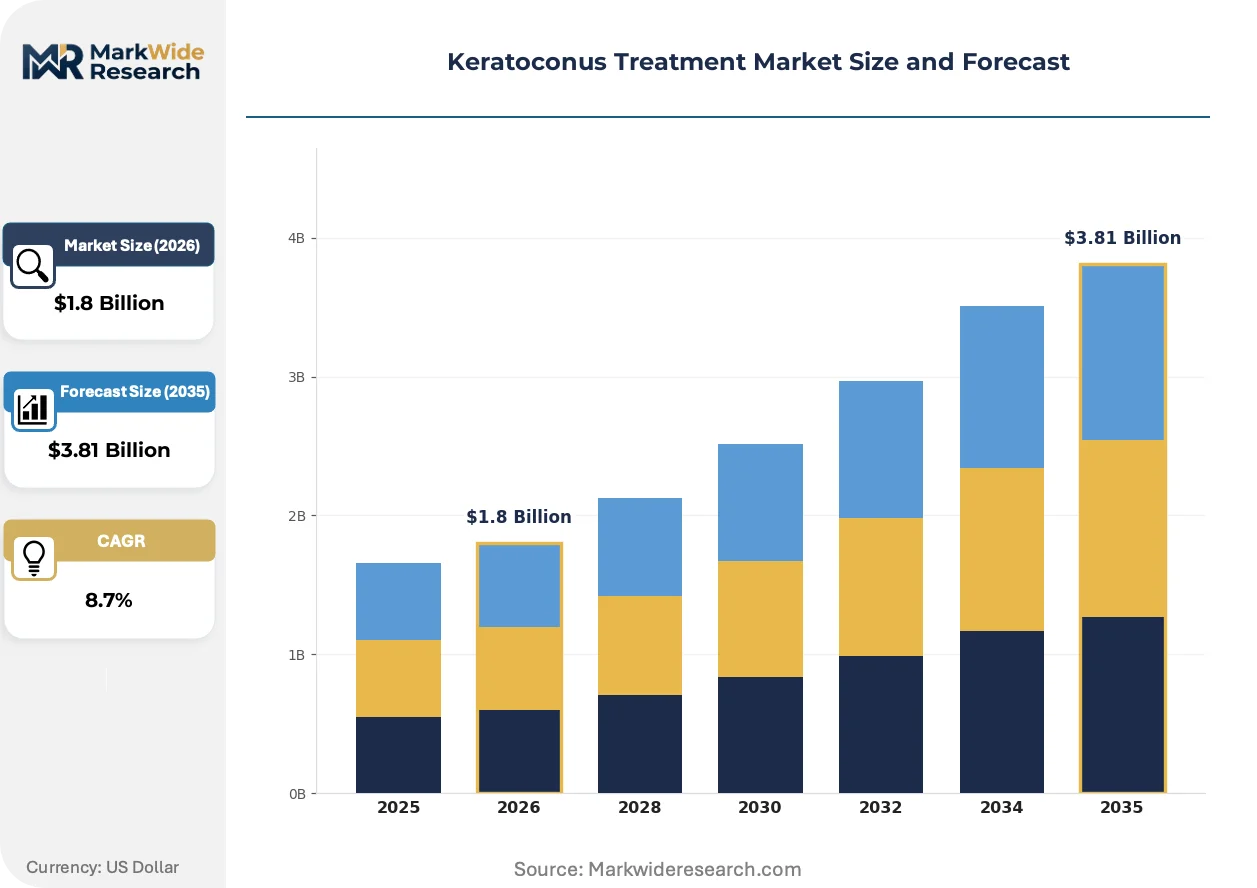
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Contact Lenses, Surgical Treatments, Specialty Eyewear, Cross-Linking Solutions End User: Ophthalmology Clinics, Hospitals, Retail Pharmacies, Eye Care Professionals Technology: Accelerated Cross-Linking, New Keratoplasty Techniques, Customized Lenses, Corneal Topography Treatment Approach: Non-Surgical, Surgical, Hybrid Methods, Preventative Care |
| Companies Covered | HOYA, Johnson & Johnson Services, Inc., The Cooper Companies, Inc., SynergEyes, Glaukos Corporation, Carl Zeiss Meditec AG, Menicon Co., Ltd., Novartis AG, Bausch Health Companies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Keratoconus Treatment Market Strategic Shifts
Photochemical stiffening protocols, regulatory pathway harmonization pressures, and patient-centered care models are restructuring how keratoconus progression is intercepted and managed across outpatient settings.
Topography-guided cross-linking is converging with artificial intelligence-based ectasia risk scoring to enable personalized irradiance dosing. Corneal specialists in tertiary referral centers are adopting these integrated platforms at accelerating rates. The technology is converging with predictive analytics to compress the diagnostic-to-treatment interval from months to days.
Japan's PMDA has tightened Shonin requirements for corneal cross-linking devices to demand 24-month follow-up data that previously required only 12 months. This regulatory friction is extending commercialization timelines by 8-14 months for manufacturers without prior FDA approval. European competitors with established US clinical packages are capturing accelerated review slots that disadvantage first-time entrants.
Patients are initiating care journeys through direct-to-consumer online vision screening platforms rather than traditional optometric referral chains. These digital channels are disintermediating community eye care practitioners and concentrating initial diagnosis volume in metropolitan specialty centers. Germany and the United States exhibit the most pronounced channel migration, with Tokyo following 18-24 months behind.
Keratoconus Treatment Market Segmentation
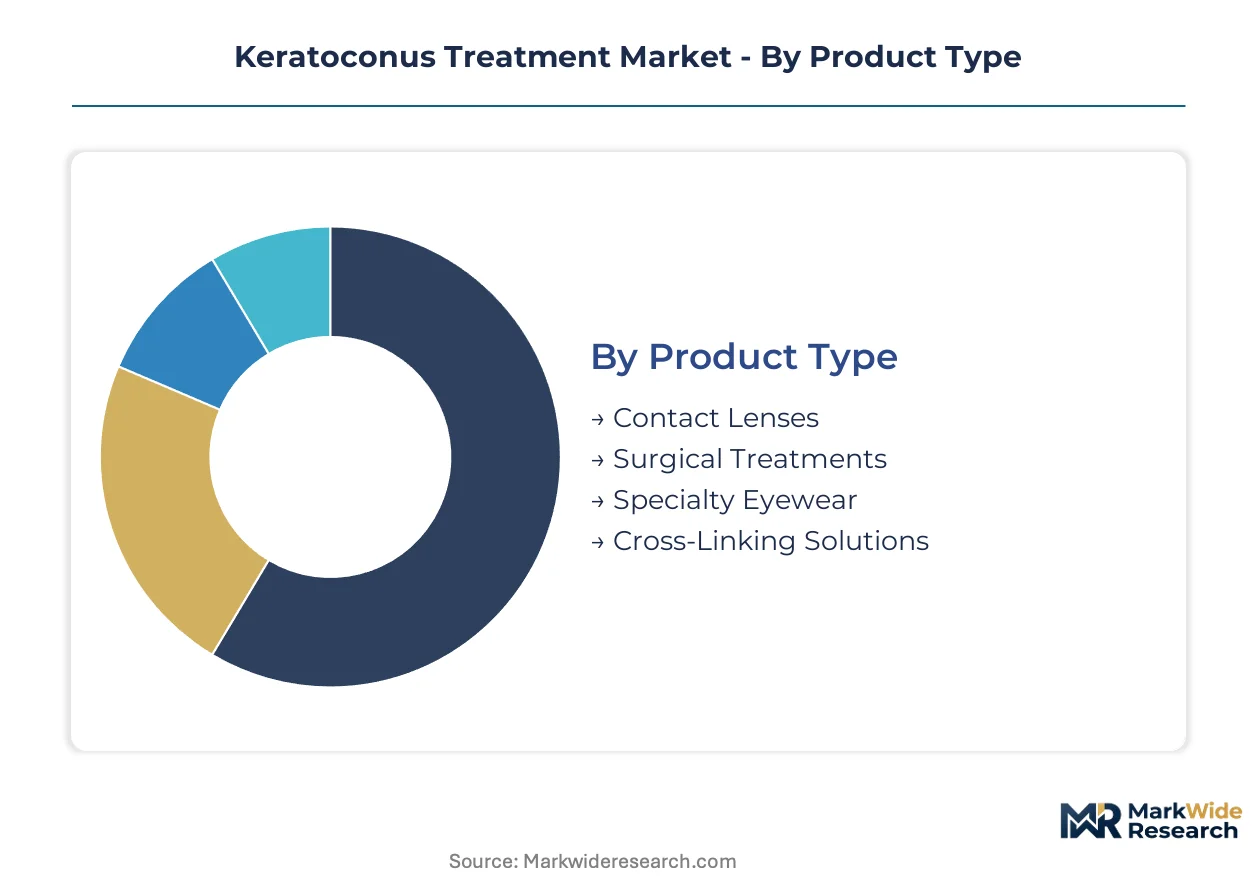
Keratoconus treatment segmentation reveals distinct procurement patterns across clinical settings. Product type and technology choices diverge sharply between tertiary surgical centers and community eye care practices.
Product Type:
Patient progression stage and corneal thickness thresholds determine product selection, with early intervention favoring optical solutions and advanced ectasia requiring tissue-level intervention.
- Contact Lenses:Scleral and hybrid designs dominate functional vision restoration for moderate keratoconus. Demand concentrates among patients aged 18-35 in the United States and Germany where specialty fitting infrastructure is most developed, driven by recurring replacement cycles and insurance coverage expansion for medically necessary lenses.
- Surgical Treatments:Deep anterior lamellar keratoplasty and penetrating procedures address end-stage disease. Volume clusters in Tokyo, Munich, and Boston where fellowship-trained corneal specialists maintain active transplant programs, constrained by donor tissue availability and hospital reimbursement differentials.
- Specialty Eyewear:Custom-tinted and prism-corrected options serve post-surgical patients with residual irregular astigmatism.
- Cross-Linking Solutions:Riboflavin formulations and UVA devices command premium pricing in outpatient settings.
Contact lenses lead on scale through recurring revenue; surgical treatments lead on momentum as transplant techniques advance.
End User:
Capital intensity and reimbursement complexity sort product flows across delivery settings, with device-heavy procedures concentrating in hospital-based systems.
- Ophthalmology Clinics:Independent and group practices handle the majority of cross-linking procedures and specialty lens fittings. Patient volume concentrates in metropolitan corridors with optical coherence tomography capabilities, driven by same-day diagnosis-to-treatment workflows and direct-to-consumer screening platform referrals.
- Hospitals:Academic medical centers and specialty surgical hospitals dominate keratoplasty and complex revision cases. Demand clusters in Germany's university hospital networks and Japan's national hospital organizations where femtosecond laser platforms integrate with existing refractive surgery suites.
- Retail Pharmacies:Limited to post-procedural drops and lens care solutions.
- Eye Care Professionals:Optometrists serve as gatekeepers for early detection and referral.
Ophthalmology clinics lead on scale; hospitals lead on momentum as surgical complexity rises.
Technology:
Regulatory clearance timelines and capital equipment requirements shape adoption curves, with accelerated protocols displacing conventional timelines where reimbursement permits.
- Accelerated Cross-Linking:High-irradiance UVA delivery at 30 mW/cm² compresses treatment from 60 minutes to under 10 minutes. Adoption concentrates in the United States and Germany where FDA and CE marking pathways have cleared multiple device platforms, driven by throughput demands in high-volume practices.
- New Keratoplasty Techniques:Femtosecond laser-assisted deep anterior lamellar procedures reduce rejection risk versus penetrating grafts. Volume expands fastest in Japan and Germany where PMDA Shonin and EU MDR pathways have validated endothelial-sparing approaches.
- Customized Lenses:Wavefront-guided and topography-matched designs improve visual quality.
- Corneal Topography:Diagnostic platforms enable ectasia detection and progression monitoring.
Accelerated cross-linking leads on scale; new keratoplasty techniques gain share fastest.
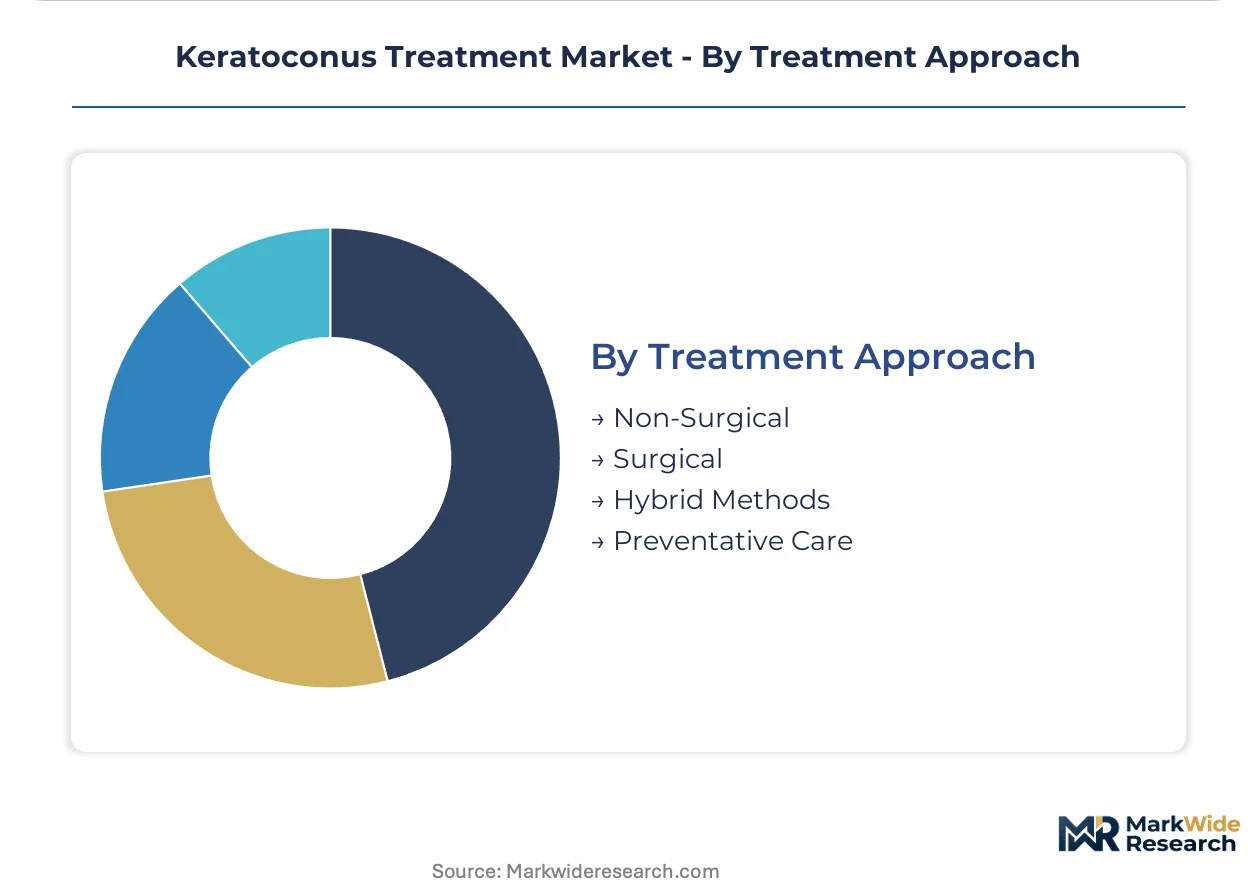
Treatment Approach:
Clinical guidelines and patient preference sort interventions across the disease continuum, with hybrid protocols emerging at the non-surgical-surgical boundary.
- Non-Surgical:Specialty contact lenses and cross-linking halt progression without tissue removal. Demand concentrates among younger myopic populations in the United States and Japan where early detection programs identify subclinical ectasia, constrained by cross-linking efficacy floors at 400 microns stromal thickness.
- Surgical:Keratoplasty and intrastromal ring segments address advanced disease. Volume clusters in Germany and Japan where national health technology assessment bodies have established transplantation reimbursement frameworks.
- Hybrid Methods:Combined cross-linking with photorefractive keratectomy or lens implantation.
- Preventative Care:Screening and monitoring for at-risk populations with familial history.
Non-surgical approaches lead on scale; surgical approaches lead on momentum as late-stage diagnosis persists.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-linking device manufacturers are relocating production to jurisdictions with shorter FDA-equivalent approval timelines, exploiting regulatory-arbitrage gaps between mature and emerging ophthalmology markets. This migration reshapes regional competitive positioning while concentrating high-margin device assembly in established manufacturing clusters.
United States
Specialty lens demand concentrates among myopic patients aged 18-35 in metropolitan corridors with optical coherence tomography capabilities. FDA premarket approval requirements for corneal cross-linking devices compress commercialization timelines and force earlier-stage clinical investment. Boston and Los Angeles anchor the highest procedure volumes for accelerated UVA protocols.
Germany
University hospital networks in Munich and Heidelberg dominate femtosecond laser-assisted deep anterior lamellar keratoplasty volume. CE marking under EU MDR imposes stricter clinical evidence standards that filter marginal competitors from procurement decisions. National health technology assessment bodies have established transplantation reimbursement frameworks that shift volume toward endothelial-sparing approaches.
Japan
PMDA Shonin pathway requirements now demand 24-month follow-up data, extending commercialization timelines by 8-14 months for manufacturers without prior FDA approval. Tokyo and Osaka concentrate cross-linking-certified surgeons, though fellowship programs produce fewer specialists than procedure growth requires. Direct-to-consumer online vision screening platforms are disintermediating community optometric referral chains.
United Kingdom
London and Manchester tertiary referral centers adopt topography-guided cross-linking with artificial intelligence-based ectasia risk scoring at accelerating rates. NHS England reimbursement decisions for outpatient cross-linking versus keratoplasty directly shift device procurement patterns. Hybrid scleral-rigid lens designs address comfort complaints that drive discontinuation among traditional gas-permeable wearers.
Switzerland
Swissmedic maintains parallel clinical evidence standards with FDA and EMA that attract manufacturers seeking regulatory pathway harmonization. Basel and Zurich host precision molding expertise for rigid gas-permeable lens segments serving adjacent EU markets. The country's refractive surgery infrastructure supports same-day diagnosis and treatment workflows for accelerated irradiance protocols.
Keratoconus Treatment Market Competitive Environment
Japanese producers anchor one tier in specialty lens fabrication; German and US device specialists hold another in cross-linking platforms. The market structures around three tiers: multinational ophthalmology conglomerates with professional education networks, precision optics manufacturers with molding expertise, and emerging device firms seeking regulatory pathway shortcuts. Dominant competitive moves include M&A to capture fitting technology integration and strategic partnerships to secure riboflavin supply chains.
Among Japanese precision optics manufacturers, HOYA and Menicon Co., Ltd. exemplify the molding-expertise archetype that dominates rigid gas-permeable segments across Asia-Pacific. Johnson & Johnson Services, Inc. and The Cooper Companies, Inc. occupy positions within the multinational conglomerate tier, differentiated by professional education networks versus fitting technology integration that reduces chair time. These three anchors illustrate how geographic origin and corporate structure map to competitive positioning without requiring specific product or financial disclosures.
| Leading Market Players |
|---|
| HOYA |
| Johnson & Johnson Services, Inc. |
| The Cooper Companies, Inc. |
| SynergEyes |
| Glaukos Corporation |
| Carl Zeiss Meditec AG |
| Menicon Co., Ltd. |
| Novartis AG |
| Bausch Health Companies Inc. |
| Others |
Value Chain & Pricing Dynamics
Corneal cross-linking device engineering talent clusters in southern Germany and Switzerland, where precision optics labor-cost differentials of 30-40% versus East Asian manufacturing hubs translate into three-tier pricing spreads across premium CE-marked systems, mid-tier FDA-cleared platforms, and economy-grade PMDA Shonin devices.
Pricing Analysis
Distributor margins of 15-25% on riboflavin formulations and UVA devices compress as direct-to-hospital procurement expands in the United States and Germany. Three-tier pricing structure across premium, standard, and economy levels reflects FDA versus CE versus PMDA certification tiers, with premium platforms commanding 2-3x standard pricing due to accelerated irradiance protocols and integrated OCT compatibility. Pricing pressure stems from reimbursement rate compression by national health technology assessment bodies in Germany and Japan. Hospital systems exhibit lowest price sensitivity due to bundled procedure economics, while independent ophthalmology clinics negotiate aggressively on device lease terms.
Supply Chain Analysis
Japan's PMDA Shonin pathway domestic-content preferences and Germany's EU MDR local-representative requirements are reshaping sourcing patterns for riboflavin photochemical precursors and precision-molded lens components. Manufacturing concentrates in Japan, Germany, and the United States for cross-linking devices, with Taiwan and South Korea supplying optical-grade UV LEDs and sensor modules. Raw material dependencies center on riboflavin-5-phosphate from European chemical hubs, medical-grade silicone for scleral lenses, and high-purity quartz for UVA delivery systems. Single-source vulnerability runs through riboflavin precursor manufacturing clusters in Basel and Frankfurt. Distribution runs through specialized ophthalmology device distributors in metropolitan corridors, with direct manufacturer-to-hospital contracts gaining share in academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
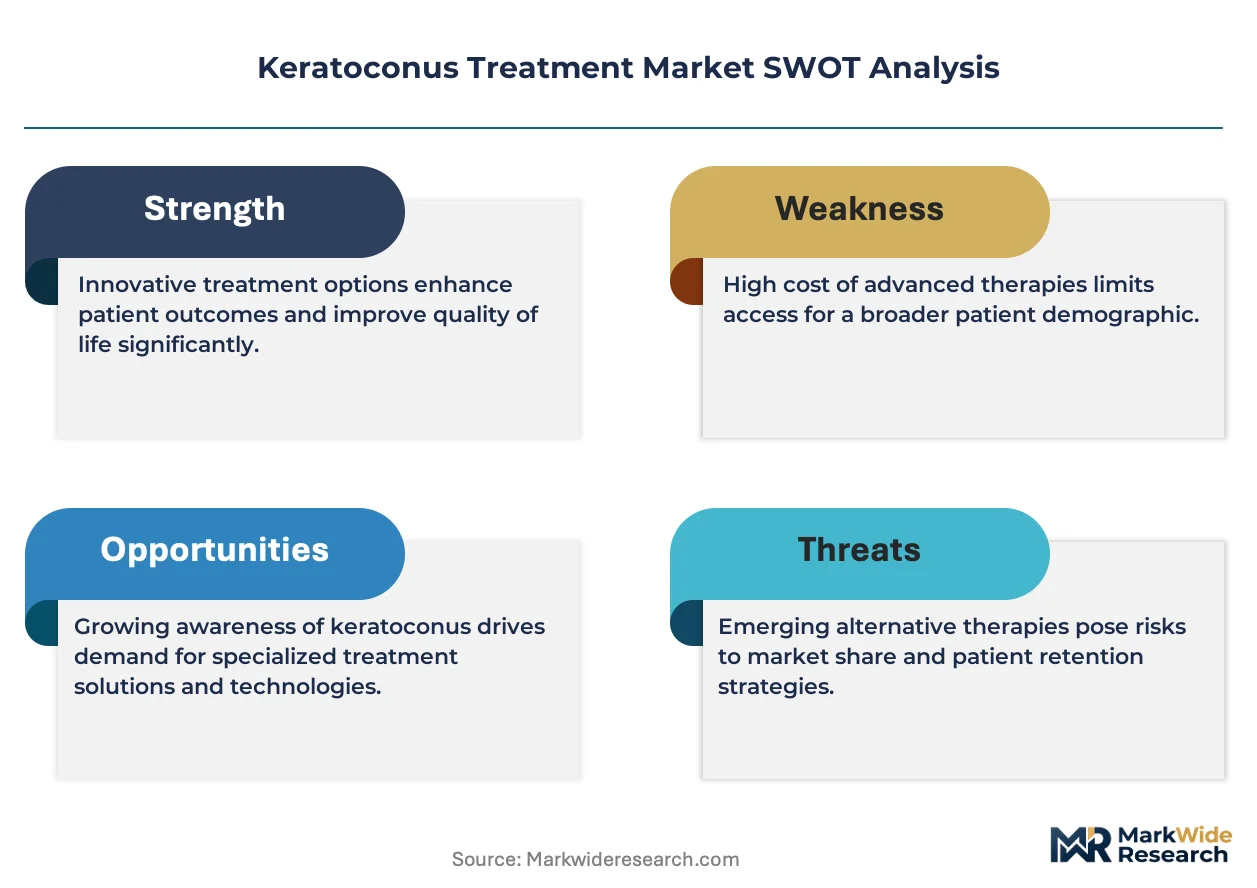
This market offers margin-expansion pathways through accelerated irradiance protocol adoption, which reduces per-procedure device utilization and shifts revenue mix toward higher-margin consumable riboflavin formulations.
For Market Incumbents: To counter emerging device firms exploiting Japan's PMDA Shonin pathway with abbreviated clinical packages, Johnson & Johnson Services, Inc. and The Cooper Companies, Inc. should deepen backward integration into riboflavin supply chains and expand professional education networks that lock in practitioner loyalty. Certification investment in next-generation topography-guided platforms with AI-integrated ectasia scoring represents the critical defensive lever against software-enabled diagnostics entrants. For New Entrants and Emerging Players: Begin with hybrid scleral-rigid lens designs targeting the 18-35 myopic population in the United Kingdom and United States, where comfort-driven discontinuation among traditional gas-permeable wearers creates white-space opportunity. Direct-to-consumer online vision screening partnerships offer the most penetrable go-to-market angle, disintermediating community optometric referral chains and concentrating initial diagnosis volume in metropolitan specialty centers. For Investors and Strategic Acquirers: Precision optics manufacturers with molding expertise are the most active acquirer in this space, seeking fitting technology integration capabilities that reduce practitioner chair time. Long-term viability centers on platforms spanning diagnosis through treatment workflow integration, with acquisition targets clustering among AI-enabled topography system developers and accelerated UVA device specialists. The signal to watch is PMDA Shonin pathway timeline compression for manufacturers with prior FDA clearance, which would accelerate competitive entry velocity.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR stricter clinical evidence requirements filter marginal competitors from procurement decisions. |
| Hospital System Partnership | Academic medical centers in Munich and Tokyo anchor femtosecond laser-assisted keratoplasty volume growth. |
| Software Companion Development | AI-based ectasia risk scoring compresses diagnostic-to-treatment intervals from months to days. |
| Reimbursement Strategy | NHS England and German G-BA coverage decisions directly shift cross-linking versus keratoplasty volumes. |
| Backward Integration | Riboflavin supply chain control mitigates European chemical hub concentration risk. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with corneal specialists, ophthalmology clinic practice managers, hospital purchasing committee members, and biomedical engineers with secondary validation against FDA 510(k) filings, PMDA Shonin approval databases, EMA CE marking records, and hospital procurement contract repositories. Bottom-up procedure volume estimates triangulated against top-down device shipment data across the analysis window.
Historical reference periods anchored the forecast window to pre-pandemic baseline volumes and post-2020 recovery trajectories, with segmentation modeling across treatment approach, product type, end-user setting, and technology platform. CAGRs derived from procedure volume growth curves, reimbursement rate elasticity assumptions, and device replacement cycle patterns. Industry-specific inputs incorporated cross-linking efficacy thresholds at 400 microns stromal thickness and fellowship-trained surgeon pipeline constraints.
Several conditions sit outside the modeled scope, including novel gene therapy interventions for keratoconus, artificial cornea technologies, and regulatory pathway disruptions from harmonization initiatives. Forecasts reflect documented assumptions regarding reimbursement expansion trajectories and surgeon training capacity scaling. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Europe Primary Angle-Closure Glaucoma Market
Ophthalmology
Global Ophthalmic Equipment Market
Ophthalmology
Ocular Hypertension Treatment Market
Ophthalmology
Macular Edema Treatment Market
Ophthalmology
Ophthalmic Operating Room Microscope Market
Ophthalmology
Global Ophthalmoplegia Market
Ophthalmology
USA Ophthalmic Devices Market
Ophthalmology
Retinoblastoma Treatment Market
Ophthalmology
Eye Infections Treatment Market
Ophthalmology
Diabetic Retinopathy Treatment Market
Ophthalmology
UAE Ophthalmic Devices Market
Ophthalmology
Global Ophthalmic Sutures Market
Ophthalmology
Ocular Inserts Market
Ophthalmology
Global Posterior Segment Eye Disorders Market
Ophthalmology
Herpes Simplex Keratitis Treatment Market
Ophthalmology
Global Aphakia Market