
 3D-Printed Maxillofacial Implants Market | 2026-2036
3D-Printed Maxillofacial Implants Market Size, Share, and Industry Trends Forecast 2026-2036
3D-Printed Maxillofacial Implants Market Outlook
The EU Green Deal is restructuring procurement criteria across European hospital systems, favoring implant suppliers with verified lifecycle assessments and reduced material waste. Materialise anchors its position through proprietary surgical planning software paired with titanium implant production. Stryker leverages its orthopedic scale to extend into maxillofacial applications with integrated navigation systems. KLS Martin competes through deep specialization in craniofacial fixation and patient-matched implant design.
3D-printed maxillofacial implants are patient-specific medical devices fabricated from titanium alloys, polyetheretherketone (PEEK), or bioceramic composites via additive manufacturing processes that achieve pore geometries down to 300-600 micrometers for osseointegration. These implants restore structural integrity and aesthetic function after trauma, tumor resection, or congenital deformity. Titanium implants dominate current surgical volume due to established biocompatibility and radiopacity, while PEEK implants represent the fastest-expanding category because of modulus-matching properties that reduce stress shielding in mandibular reconstruction. Trauma reconstruction generates the largest application share, though orthognathic surgery offers higher per-procedure margins as digital surgical planning penetrates elective craniofacial correction.
FDA 510(k) clearance pathways and the EU Medical Device Regulation (MDR) govern biocompatibility testing, sterilization validation, and post-market surveillance for these implants. ISO 10993 standards and ASTM F3055 specifications for additive manufacturing of metallic medical devices shape material qualification protocols. Stakeholders must monitor evolving software-as-medical-device classifications for AI-generated implant designs.
Market Dynamics
Patient-matched implant production is consolidating around digital surgical planning ecosystems that tether preoperative visualization to intraoperative navigation, compressing the traditional handoff between diagnostic imaging and device fabrication.
Growth Catalysts
- EU Medical Device Regulation:MDR Article 10 mandates post-market surveillance and clinical evidence for patient-specific devices, accelerating hospital adoption of validated additive manufacturing workflows to meet compliance thresholds.
- Polyetheretherketone modulus-matching:PEEK implants reduce stress shielding in mandibular reconstruction, driving surgical preference shifts in orthognathic and trauma applications where bone preservation dictates long-term outcomes.
- Academic medical center concentration:Complex craniofacial reconstruction volume clusters at tertiary referral hospitals in the United States, creating demand density that justifies dedicated additive manufacturing cell investments.
Market Restraints
- Titanium powder supply concentration:Spherical Ti-6Al-4V ELI powder for electron beam melting concentrates among a limited supplier base, exposing implant manufacturers to input cost volatility and lot-to-lot qualification delays.
- ISO 10993 biocompatibility testing burden:Cytotoxicity, sensitization, and systemic toxicity validation for novel pore geometries extends regulatory timelines by 12-18 months versus conventional machined implants.
- PEEK machining substitution:Subtractive manufacturing of patient-matched PEEK implants from stock shapes retains cost advantages for low-complexity geometries, limiting additive penetration in price-sensitive trauma reconstruction.
Strategic Opportunities
- Brazil ANVISA pathway acceleration:Emerging regulatory clarity for custom-made devices in Latin America's largest medical device market creates first-mover positioning for validated quality management systems.
- AI-generated implant design software:Machine learning automation of lattice optimization and anatomical mirroring converges with cloud-based surgical planning, collapsing the design-to-fabrication interval from weeks to days.
- India CDSCO custom device exemption:Regulatory provisions for patient-specific implants manufactured at point-of-care enable hospital-based production models that bypass traditional distributor channels.
Industry Challenges
- Additive manufacturing technician scarcity:Qualified operators for laser powder bed fusion and electron beam melting remain concentrated in aerospace and dental sectors, forcing implant manufacturers to compete for talent or build captive training pipelines.
- Software-as-medical-device classification uncertainty:FDA and EU MDR divergence on whether AI-generated implant designs constitute standalone regulated products creates compliance pathway ambiguity for integrated surgical planning platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D-Printed Maxillofacial Implants Market |
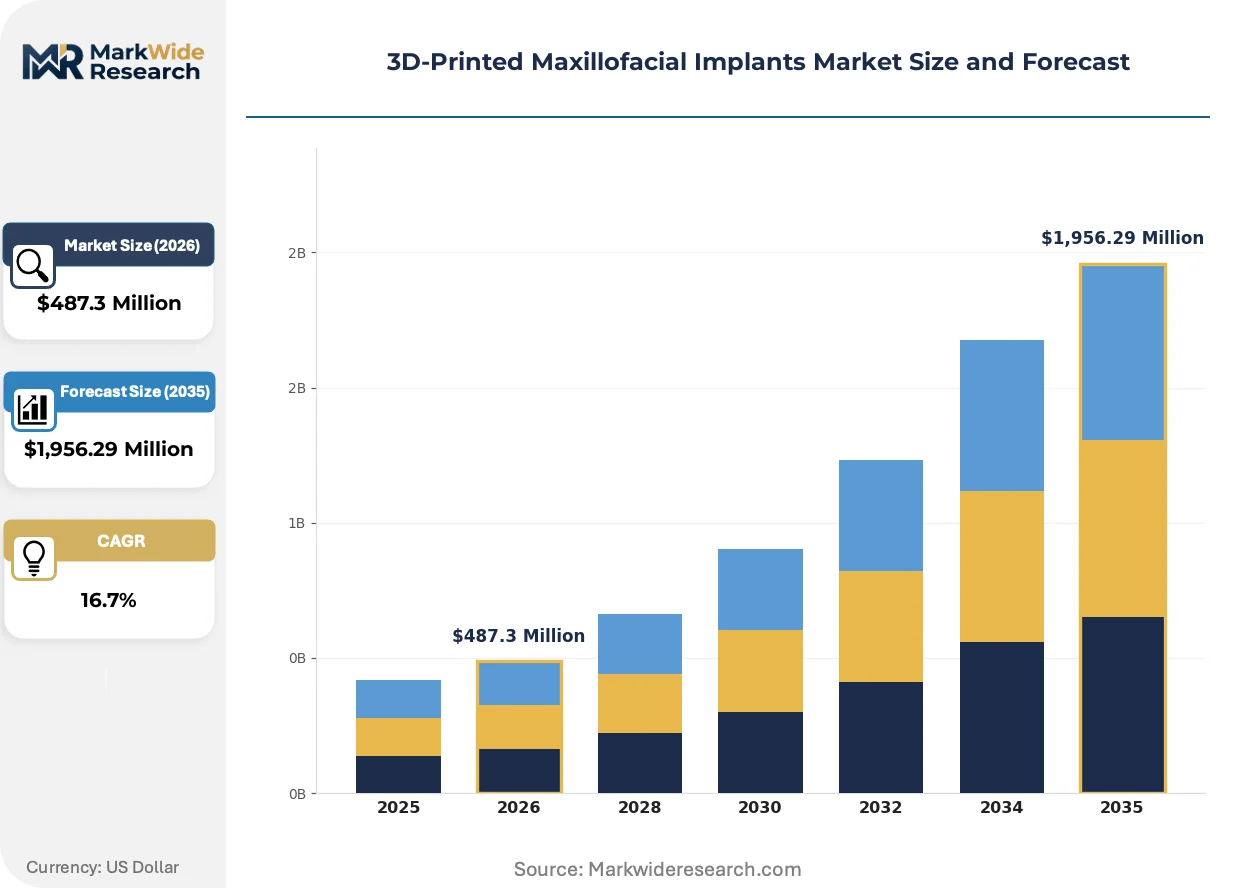
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,956.29 Million |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Custom Implants, PEEK Implants, Titanium Implants, Bioceramics End User: Hospitals, Dental Clinics, Research Institutions, Medical Laboratories Technology: Fused Deposition Modeling, Selective Laser Sintering, Stereolithography, Digital Light Processing Application: Trauma Reconstruction, Cosmetic Surgery, Tumor Reconstruction, Orthognathic Surgery |
| Companies Covered | Johnson & Johnson Services, KLS Martin, Materialise, B. Braun Melsungen, Medartis, Stryker, Medtronic, Integra LifeSciences, Zimmer Biomet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D-Printed Maxillofacial Implants Market Strategic Shifts
Digital thread integration is collapsing the fragmentation between diagnostic imaging, surgical simulation, and implant fabrication that historically required multiple vendor handoffs and manual data translation.
Multi-material jetting is unifying titanium lattice structures with PEEK load-bearing cores in single-build processes, eliminating the mechanical failure modes at metal-polymer interfaces that plagued two-component assemblies. Academic medical centers in Germany and the United States are piloting these hybrid constructs for orbital floor reconstruction where modulus gradients match adjacent bone. The technology is unifying previously separate supplier ecosystems into consolidated device-platform relationships.
EU AI Act risk classification for clinical decision support software is compelling implant manufacturers to rearchitect surgical planning modules as deterministic rather than probabilistic algorithms, stripping black-box optimization in favor of traceable geometric manipulation rules. MDR notified bodies in Germany and the Netherlands are prioritizing technical documentation reviews for AI-enabled design tools, creating a two-speed approval environment where simpler rule-based software clears faster.
Hospital procurement committees are consolidating vendor relationships around integrated device-and-software contracts that bundle preoperative planning, implant fabrication, and intraoperative navigation support. German university hospitals and US academic medical centers are displacing standalone implant suppliers in favor of platform providers capable of end-to-end digital workflow ownership, compressing the addressable vendor base and raising switching costs for incumbent device-only manufacturers.
3D-Printed Maxillofacial Implants Market Segmentation
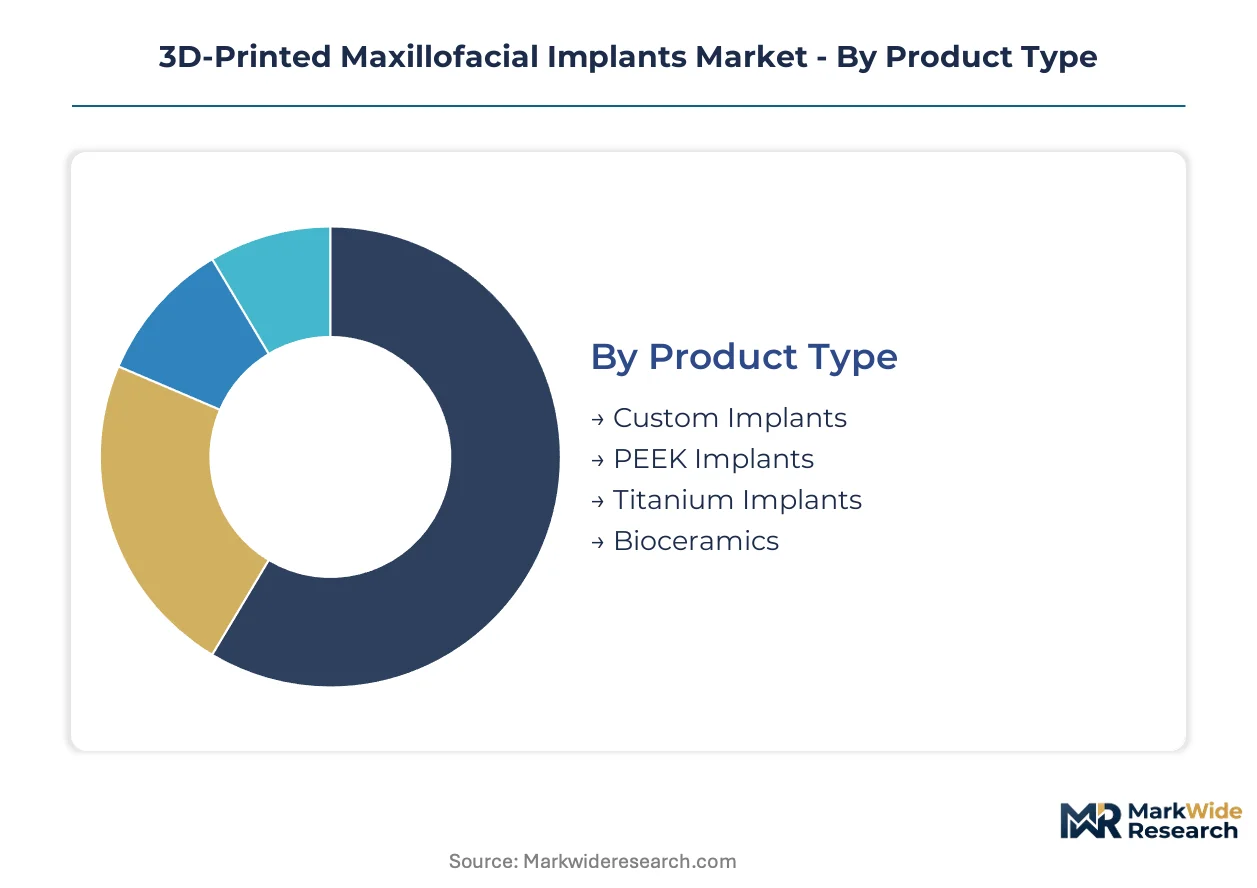
Segmentation in 3D-printed maxillofacial implants reveals how customization depth, regulatory pathway, and clinical setting interact to determine commercial viability. Each dimension carries distinct margin structures and technical requirements that reshape supplier positioning.
Product Type:
Customization intensity spans from patient-matched geometries requiring surgical planning integration to stock configurations with minimal design iteration.
- Custom Implants:Patient-specific geometries derived from CT/MRI data require ISO 13485 quality systems and MDR technical documentation. Academic medical centers in Germany and the United States drive procurement volume for complex craniofacial reconstruction where standard shapes fail.
- Titanium Implants:Ti-6Al-4V ELI powder processed via electron beam melting delivers radiopacity and established osseointegration. Trauma reconstruction in US tertiary hospitals dominates current surgical volume due to reimbursement familiarity and metallurgical confidence.
- PEEK Implants:Polyetheretherketone modulus-matching reduces stress shielding in mandibular applications, with demand accelerating in orthognathic surgery.
- Bioceramics:Hydroxyapatite and tricalcium phosphate composites support osteoconduction in orbital floor and small defect reconstruction.
Leading the category by volume: Titanium Implants. Growing fastest: PEEK Implants.
End User:
Procurement authority concentrates in institutions with additive manufacturing infrastructure and complex case volume sufficient to justify quality system investments.
- Hospitals:Tertiary academic medical centers in the United States and university hospitals in Germany command the highest case complexity. These institutions maintain captive design teams and direct supplier relationships that bypass distributor markups.
- Dental Clinics:Oral and maxillofacial surgery practices with in-house cone-beam CT capabilities are expanding into implant-supported prosthetics. Brazil and India show accelerating clinic-level adoption where regulatory pathways for custom devices have clarified.
- Research Institutions:University engineering departments and hospital-affiliated innovation centers pilot multi-material jetting and AI-generated lattice structures.
- Medical Laboratories:Specialized service bureaus provide design-to-fabrication outsourcing for hospitals lacking additive manufacturing capacity.
Highest absolute volume: Hospitals. Steepest expansion trajectory: Dental Clinics.
Technology:
Process selection trades resolution, build speed, and material compatibility against regulatory validation burden and equipment capital requirements.
- Selective Laser Sintering:Laser powder bed fusion of titanium achieves pore geometries down to 300-600 micrometers for osseointegration. FDA 510(k) clearance history and ASTM F3055 qualification protocols make this the default for metallic maxillofacial implants.
- Stereolithography:Photopolymer resin curing produces surgical guides and PEEK implant patterns with surface finish superior to powder-bed methods. German manufacturers leverage this for orbital floor reconstruction where anatomical precision dominates material strength.
- Fused Deposition Modeling:Thermoplastic extrusion serves prototyping and surgical planning models rather than terminal implant production due to layer adhesion limitations.
- Digital Light Processing:Mask-based photopolymerization accelerates build speed for dental surgical guides and diagnostic models.
Dominant installed base: Selective Laser Sintering. Gaining share fastest: Stereolithography.
Application:
Clinical indication determines reimbursement pathway, case urgency, and the relative weight of aesthetic versus functional outcomes in implant specification.
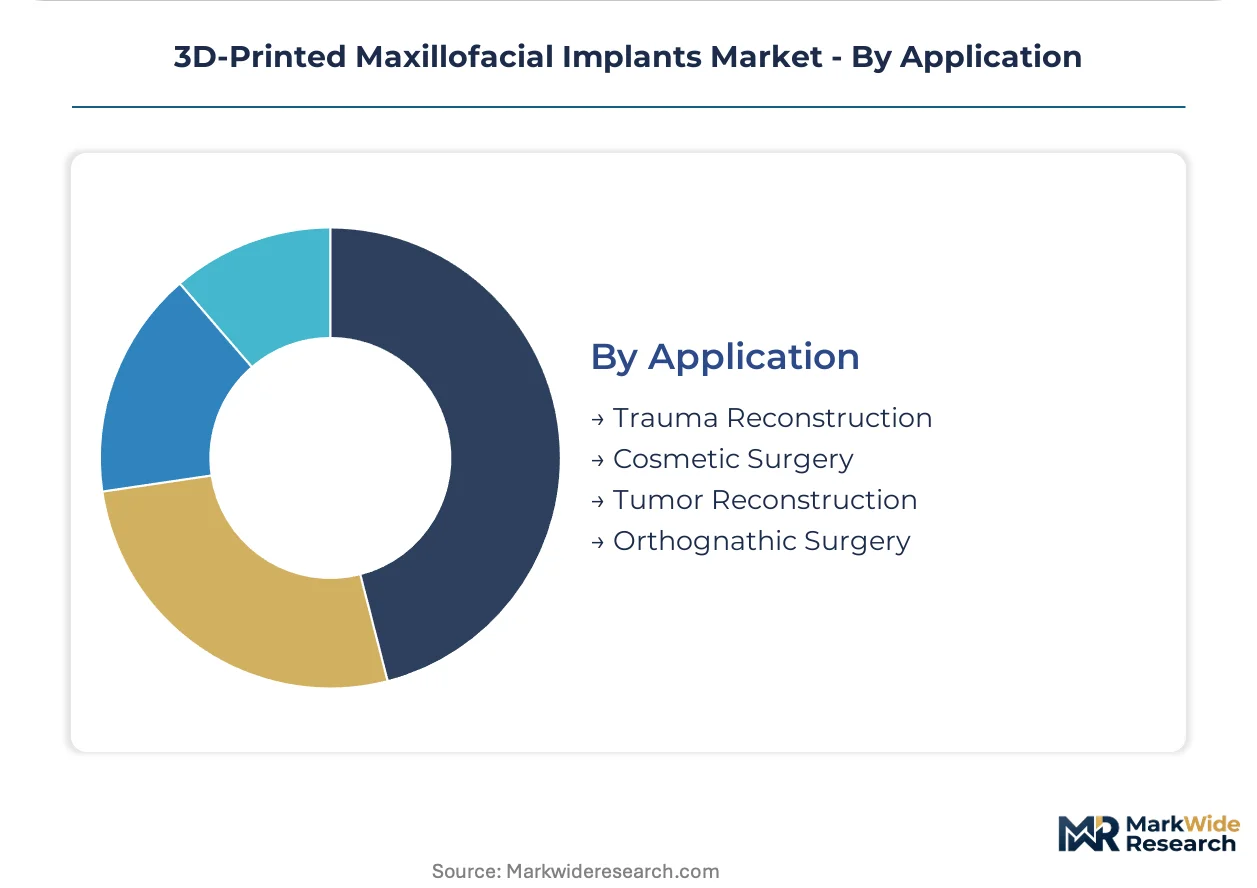
- Trauma Reconstruction:Acute facial fracture repair generates the largest procedure volume with established CPT coding and payer coverage. US Level I trauma centers drive demand for rapid-turnaround titanium implants where surgical scheduling tolerates minimal design iteration time.
- Orthognathic Surgery:Elective jaw realignment commands premium pricing and longer planning horizons that accommodate patient-matched PEEK implants. Private pay concentration in Germany and the United States supports higher per-procedure margins.
- Tumor Resection:Oncologic reconstruction requires large-segment implants with complex curvature matching resected bone.
- Cosmetic Surgery:Aesthetic craniofacial modification represents a nascent category with limited reimbursement and high patient out-of-pocket contribution.
Category volume leader: Trauma Reconstruction. Margin expansion focus: Orthognathic Surgery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity concentrates in German precision engineering clusters and US medical technology corridors, while demand generation tilts toward tertiary hospitals in both markets. Emerging production nodes in India and Brazil are capturing regional service bureau work.
United States
Academic medical centers in Boston and Baltimore drive complex craniofacial reconstruction volume that justifies captive additive manufacturing investments. FDA 510(k) clearance pathways for patient-matched titanium implants accelerate commercial timelines versus de novo submissions. The Cleveland Clinic and Mayo Clinic anchor multi-hospital networks standardizing digital surgical planning protocols.
Germany
University hospitals in Munich and Heidelberg are expanding patient-specific implant programs with direct government research funding. EU Medical Device Regulation Article 10 mandates post-market surveillance that favors validated additive manufacturing workflows. The Stuttgart precision engineering corridor hosts electron beam melting equipment suppliers serving adjacent medical device fabricators.
India
CDSCO custom device exemptions enable point-of-care production models at tertiary hospitals in Mumbai and Delhi. Maxillofacial trauma volume at public hospitals creates demand density for rapid-turnaround titanium implants. The Bangalore medical device cluster is incubating design-to-fabrication service bureaus targeting domestic hospital procurement.
Brazil
ANVISA regulatory clarity for custom-made devices is accelerating dental clinic adoption in São Paulo and Rio de Janeiro. Oral and maxillofacial surgery practices with cone-beam CT capabilities are integrating implant-supported prosthetics. The Campinas technology corridor is attracting multinational service bureau investments for Latin American market coverage.
Japan
PMDA consultation pathways for additive manufactured devices are shortening pre-submission timelines for titanium lattice structures. Tertiary hospitals in Tokyo and Osaka are piloting patient-matched PEEK implants for mandibular reconstruction. The Nagoya medical device manufacturing cluster is adapting automotive precision engineering capabilities to orthopedic applications.
3D-Printed Maxillofacial Implants Market Competitive Environment
The competitive structure tilts toward integrated platform providers that bundle surgical planning software with implant fabrication. Tier-one orthopedic conglomerates compete against specialized craniofacial fixation houses and independent additive manufacturing service bureaus. Three archetypes dominate: diversified medtech giants with maxillofacial extensions, pure-play patient-matched implant designers, and hospital-embedded production facilities. Consolidation pressure is forcing standalone implant suppliers into strategic partnerships with surgical navigation vendors.
Within the integrated platform tier, Materialise and Stryker represent contrasting approaches to digital workflow ownership. Materialise anchors its position through proprietary surgical planning software paired with titanium implant production. Stryker leverages orthopedic scale to extend into maxillofacial applications with integrated navigation systems. KLS Martin occupies a specialist position through deep craniofacial fixation expertise and patient-matched implant design capabilities.
| Leading Market Players |
|---|
| Johnson & Johnson Services |
| KLS Martin |
| Materialise |
| B. Braun Melsungen |
| Medartis |
| Stryker |
| Medtronic |
| Integra LifeSciences |
| Zimmer Biomet |
| Others |
Value Chain & Pricing Dynamics
Spherical Ti-6Al-4V ELI powder costs cascade through electron beam melting workflows into tiered implant pricing that separates academic medical center contracts from distributor-served trauma reconstruction. German university hospitals negotiate direct supply agreements that bypass markups embedded in multi-hospital procurement networks.
Pricing Analysis
Value-based pricing anchors on osseointegration outcomes and surgical planning integration rather than commodity metal weight. Three-tier pricing structure across premium patient-matched, standard modular, and economy stock geometries reflects ISO 13485 certification depth and design iteration intensity. Pricing pressure stems from PEEK machining substitution in mandibular applications where subtractive methods retain cost advantages. Dental clinics in Brazil and India exhibit highest price sensitivity, while US academic medical centers prioritize workflow integration over unit cost.
Supply Chain Analysis
Photoresist supply for stereolithography surgical guides rests on Japanese and German specialty chemical producers with limited alternative sourcing. Titanium powder concentrates among US, German, and Chinese suppliers, with spherical Ti-6Al-4V ELI grades subject to lot-to-lot qualification delays. Single-source vulnerability in electron beam melting equipment creates bottleneck risk for implant manufacturers scaling production. Distribution runs through hospital procurement committees consolidating around integrated device-and-software platform contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Patient-matched additive manufacturing is displacing conventional machining in complex craniofacial reconstruction, with digital surgical planning software becoming the primary value capture point rather than the implant itself.
For Market Incumbents: Deploy backward integration into titanium powder qualification to secure input cost stability against lot-to-lot variability from concentrated suppliers. Consolidate surgical planning software acquisitions to defend against platform displacement by orthopedic conglomerates extending into maxillofacial applications. FDA software-as-medical-device classification uncertainty threatens integrated workflow margins and demands proactive regulatory architecture investment. For New Entrants and Emerging Players: ANVISA regulatory clarity for custom-made devices in Brazil opens a window for validated quality management systems targeting dental clinic adoption in São Paulo and Rio de Janeiro. CDSCO custom device exemptions in India enable point-of-care production models that bypass traditional distributor channels entirely. Target service bureau partnerships with tertiary hospitals lacking captive additive manufacturing capacity as the most penetrable entry vector. For Investors and Strategic Acquirers: Hospital procurement committee consolidation around integrated platform contracts is the leading indicator that standalone implant suppliers face strategic irrelevance without surgical planning software attachment. Mid-cap specialists with deterministic AI design tools and MDR technical documentation readiness represent prime acquisition targets. Watch EU AI Act risk classification enforcement as the inflection signal for compliance-cost divergence between rule-based and probabilistic algorithm architectures.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Investment | Accelerates hospital adoption by meeting EU Article 10 post-market surveillance mandates. |
| AI-Generated Design Software Development | Collapses design-to-fabrication intervals from weeks to days for patient-matched geometries. |
| Multi-Material Jetting Capability Buildout | Unifies titanium lattice structures with PEEK cores in single-build hybrid constructs. |
| Hospital System Partnership Expansion | Secures end-to-end digital workflow contracts that raise switching costs for competitors. |
| Point-of-Care Production Model Pilot | Captures CDSCO-enabled domestic manufacturing opportunities in Indian tertiary hospitals. |
Study Parameters
Independent corroboration across FDA 510(k) clearance databases, EU MDR notified body technical documentation reviews, and hospital procurement contract disclosures underwrites the qualitative findings in this study. Primary interviews with maxillofacial surgeons, biomedical engineers at academic medical centers, GPO contracts managers, and additive manufacturing operations directors combined with secondary validation from ASTM F3055 standards documentation, ISO 10993 biocompatibility test records, and customs trade data for titanium powder imports. Bottom-up procedure volume estimates and top-down equipment installation counts were triangulated to anchor market sizing.
Comparable-period analysis anchored the projection horizon to historical reconstruction procedure growth patterns and additive manufacturing adoption curves across medical device applications. Segmentation dimensions modeled include customization intensity, material category, end-user institution type, and regional regulatory pathway cluster. CAGRs were derived from fitted adoption curves incorporating electron beam melting equipment deployment rates and PEEK modulus-matching preference shifts. Forecast inputs incorporated digital surgical planning software penetration trajectories and AI-generated design automation timelines.
The model assumes a particular technology adoption path; alternative pathways for multi-material jetting hybrid constructs or point-of-care production models would alter the outlook for supplier concentration and margin distribution. Forecasts reflect assumptions about MDR enforcement consistency, titanium powder supply stability, and software-as-medical-device classification convergence. Regulatory divergence between FDA and EU MDR, powder supply disruption, and AI Act risk tiering constitute the trigger set warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Medical Suction Devices Market
Medical Devices
Europe Electroencephalography Devices Market
Medical Devices
Bilirubin Meters Market
Medical Devices
Global Connected Medical Devices Market
Medical Devices
Disposable Thermometer Market
Medical Devices
China Electrocardiograph (ECG) Market
Medical Devices
Global Electrotherapy Devices Market
Medical Devices
Global Trauma Fixation Devices Market
Medical Devices
Neurofeedback Systems Market
Medical Devices
Medical Pendant Market
Medical Devices
Global Infusion Pump Software Market
Medical Devices
Peritoneal Catheter Systems Market
Medical Devices
Tissue Sectioning Market
Medical Devices
Global Wearable Injector Devices Market
Medical Devices
Global Photomedicine Market
Medical Devices
Infusion Fluid Holder Market