
 In-Vitro Transcription Templates Market | 2026-2036
In-Vitro Transcription Templates Market Size, Share, and Industry Trends Forecast 2026-2036
In-Vitro Transcription Templates Market Analysis
CRISPR-edited linear template synthesis is reconfiguring manufacturing workflows across mRNA therapeutics, replacing circular plasmid backbones with scarless, high-fidelity transcription substrates. Thermo Fisher Scientific leverages its integrated reagent-to-instrument ecosystem to dominate clinical-grade template supply chains. New England Biolabs anchors research-grade demand through its Phusion polymerase and HiScribe platform positioning. GenScript Biotech Corporation competes on custom synthetic template turnaround times for gene therapy developers.
In-vitro transcription templates are purified DNA sequences containing promoter elements and open reading frames that RNA polymerases transcribe into RNA molecules in cell-free reactions; typical specifications require endotoxin levels below 0.1 EU per microgram and sequence fidelity exceeding 99.9% for clinical applications. Linear templates now lead product type demand as they eliminate antibiotic resistance marker contamination risks inherent to plasmid backbones. GMP-grade segments command premium positioning as FDA and EMA both mandate documented template provenance for commercial mRNA drug substance. Research-grade categories sustain volume through CRISPR guide RNA and protein expression screening workflows.
FDA's Chemistry, Manufacturing, and Controls guidance for mRNA vaccines and EMA's Good Manufacturing Practice Annex 2 revisions for biologicals both mandate template identity verification and stability testing that shapes supplier qualification timelines. ISO 13485 certification and ICH Q5D-derived nucleic acid standards further filter market access for template providers seeking pharmaceutical partnerships. Stakeholders must monitor emerging WHO mRNA technology transfer hub specifications and evolving dual-use research oversight as template synthesis capabilities proliferate beyond traditional biotech clusters.
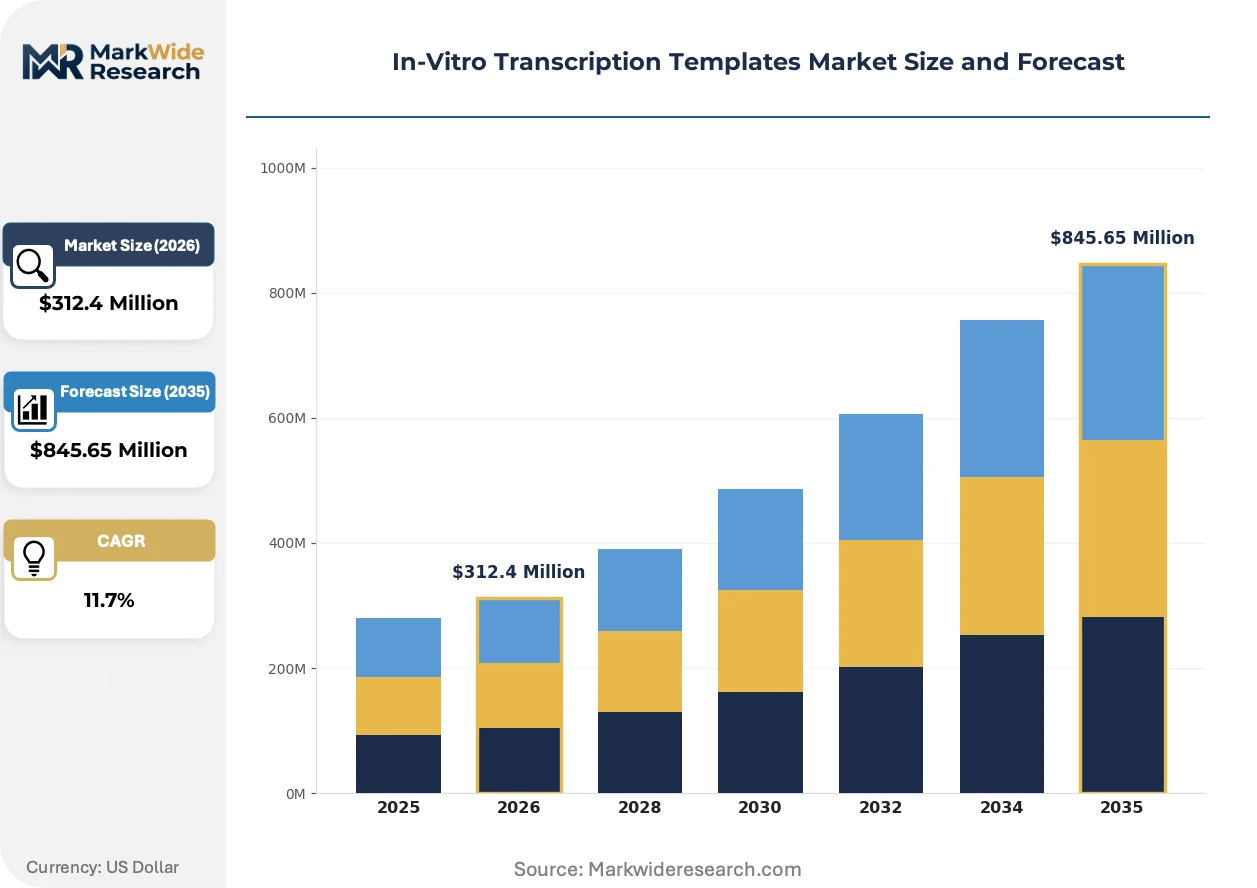
Market Dynamics
Linear template synthesis is compressing manufacturing timelines for mRNA therapeutics by eliminating plasmid propagation steps and antibiotic resistance marker purification, while FDA and EMA documentation requirements for template provenance are extending supplier qualification cycles.
Growth Catalysts
- EMA Annex 2 GMP revisions:Mandated nucleic acid documentation standards are forcing mRNA vaccine developers to upgrade template sourcing, creating pull-through demand for certified providers.
- Cell therapy manufacturing:CRISPR-edited linear templates are displacing conventional plasmid workflows in CAR-T and gene editing applications due to scarless integration requirements.
- China biologics clusters:Concentrated mRNA manufacturing investment in Suzhou and Shanghai is generating localized template procurement demand at scale.
Market Restraints
- Phosphoramidite input volatility:Oligonucleotide synthesis feedstock pricing fluctuates with specialty chemical supply chains, compressing margins for synthetic template providers.
- GMP-grade capacity concentration:Clinical-grade template production clusters in the United States and Germany, creating geographic supply risk for Asia-Pacific developers.
- Sequence fidelity ceilings:Current polymerase error rates in long linear template synthesis limit applications exceeding ten kilobases in gene therapy constructs.
Strategic Opportunities
- India CDMO expansion:Underdeveloped GMP-grade template infrastructure creates white space for qualified suppliers serving domestic vaccine developers and export markets.
- Self-amplifying mRNA formats:Emerging replicon designs require specialized template architectures with dual promoter elements, opening premium customization segments.
- WHO technology transfer hubs:mRNA manufacturing capability building in South Africa and Senegal is generating demand for template synthesis training and supply partnerships.
Industry Challenges
- GMP certification timelines:ISO 13485 and ICH Q5D compliance pathways extend twelve to eighteen months, delaying market entry for new template providers.
- Multi-enzyme process integration:Coordinating polymerase selection, DNase treatment, and chromatographic purification requires specialized bioprocess engineering talent in short supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In-Vitro Transcription Templates Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $845.65 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Templates, Plasmid Templates, Viral Templates, Synthetic Templates Grade: Research Grade, GMP Grade, Analytical Grade, Industrial Grade Application: mRNA Production, Gene Therapy, Vaccine Development, Protein Expression End User: Biotechnology Companies, Pharmaceutical Firms, Academic Institutions, Research Laboratories |
| Companies Covered | New England Biolabs, Bio-Rad Laboratories Inc., Thermo Fisher Scientific Inc., Danaher Corporation, GenScript Biotech Corporation, Promega Corporation, Takara Bio Inc., TriLink BioTechnologies, Agilent Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-Vitro Transcription Templates Market Emerging Trajectories
Template manufacturing is converging with synthetic biology toolsets, compressing development cycles while regulatory documentation requirements are expanding. These shifts are reconfiguring supplier capabilities and buyer qualification criteria.
Enzymatic DNA synthesis is hybridizing with traditional phosphoramidite chemistry to enable longer, more complex linear templates without cloning steps. Gene therapy developers are adopting these hybrid workflows for clinical candidate screening. The approach is compressing template procurement timelines from weeks to days while reducing sequence error rates.
FDA Chemistry, Manufacturing, and Controls guidance for mRNA vaccines now requires documented template stability data across manufacturing hold times. This mandate is extending analytical development burdens onto template suppliers. GMP-grade segments are responding by investing in forced degradation studies and real-time stability programs.
CDMOs are unbundling template synthesis from fill-finish services, creating specialized procurement relationships with dedicated nucleic acid manufacturers. Large mRNA vaccine developers are consolidating supplier panels to three to five qualified providers per region. This consolidation is most visible in Germany and the United States where centralized manufacturing clusters dominate commercial production.
In-Vitro Transcription Templates Market Segmentation
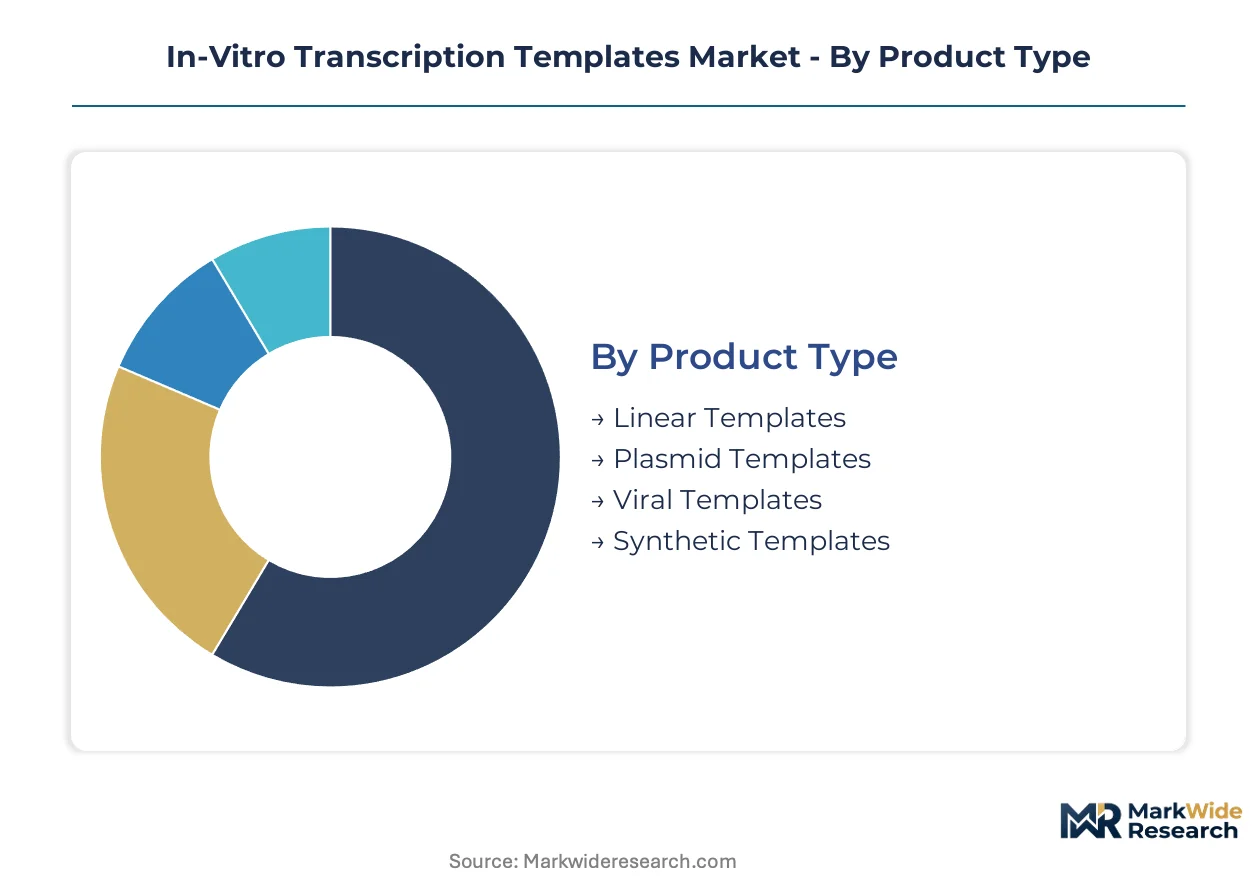
Template procurement cycles vary dramatically by segment, compressing from days for research-grade synthetic products to eighteen-month qualification windows for GMP-grade plasmid backbones. Understanding these velocity differentials helps suppliers align capacity investments with actual demand patterns across clinical and non-clinical workflows.
Product Type:
Linear templates turn over fastest in clinical pipelines, while plasmid workflows retain longer development timelines due to propagation requirements and antibiotic resistance marker documentation.
- Linear Templates:Scarless DNA substrates eliminate circular backbone contamination risks and support rapid CRISPR-edited workflows. CAR-T developers in Germany and mRNA vaccine manufacturers in the United States are standardizing on linear formats to compress cell therapy manufacturing timelines.
- Plasmid Templates:Circular DNA vectors carrying promoter elements and antibiotic resistance markers remain entrenched in legacy protein expression screening. Academic laboratories in China sustain volume demand despite clinical migration toward linear alternatives.
- Viral Templates:Adenoviral and lentiviral delivery backbones for gene therapy applications requiring nuclear import mechanisms.
- Synthetic Templates:Chemically synthesized oligonucleotide substrates for short RNA and guide RNA production with rapid turnaround specifications.
Plasmid templates dominate installed base across research applications. Linear templates are where expansion concentrates in commercial mRNA and cell therapy manufacturing.
Grade:
Cost tiers separate research-grade commoditized supply from GMP-grade premium positioning, with analytical and industrial grades occupying intermediate price-performance positions.
- GMP Grade:Clinical-grade templates manufactured under ISO 13485 and ICH Q5D-derived nucleic acid standards with documented provenance and forced degradation stability data. FDA Chemistry, Manufacturing, and Controls guidance and EMA Annex 2 revisions mandate this grade for commercial mRNA drug substance production.
- Research Grade:Non-GMP templates for CRISPR guide RNA synthesis, protein expression screening, and preclinical candidate evaluation. Biotechnology companies in Suzhou and Shanghai clusters procure at volume for early-stage pipeline development.
- Analytical Grade:High-purity templates for assay development and reference standard applications with defined certificate of analysis requirements.
- Industrial Grade:Bulk-scale templates for enzyme manufacturing and diagnostic reagent production with relaxed sequence fidelity specifications.
Research grade commands highest unit volumes. GMP grade is climbing the fastest as commercial mRNA programs advance toward regulatory submission.
Application:
Application segments map directly to end-use maturity, with vaccine development and protein expression representing established demand pools while gene therapy applications are gaining share fastest.
- mRNA Production:Templates encoding therapeutic or prophylactic mRNA sequences with 5' cap and poly-A tail elements for lipid nanoparticle formulation. EMA and FDA documentation requirements for template identity verification are extending supplier qualification timelines.
- Gene Therapy:Templates for viral vector production and gene editing reagents requiring scarless integration capabilities. CRISPR-edited linear templates are displacing conventional plasmid workflows in this segment due to reduced off-target risks.
- Vaccine Development:Infectious disease and oncology vaccine templates with rapid iteration requirements for antigen sequence optimization.
- Protein Expression:Templates for recombinant protein and antibody production in cell-free or cell-based systems.
Protein expression represents the most mature installed base. Gene therapy is where expansion concentrates as clinical programs advance toward commercialization.
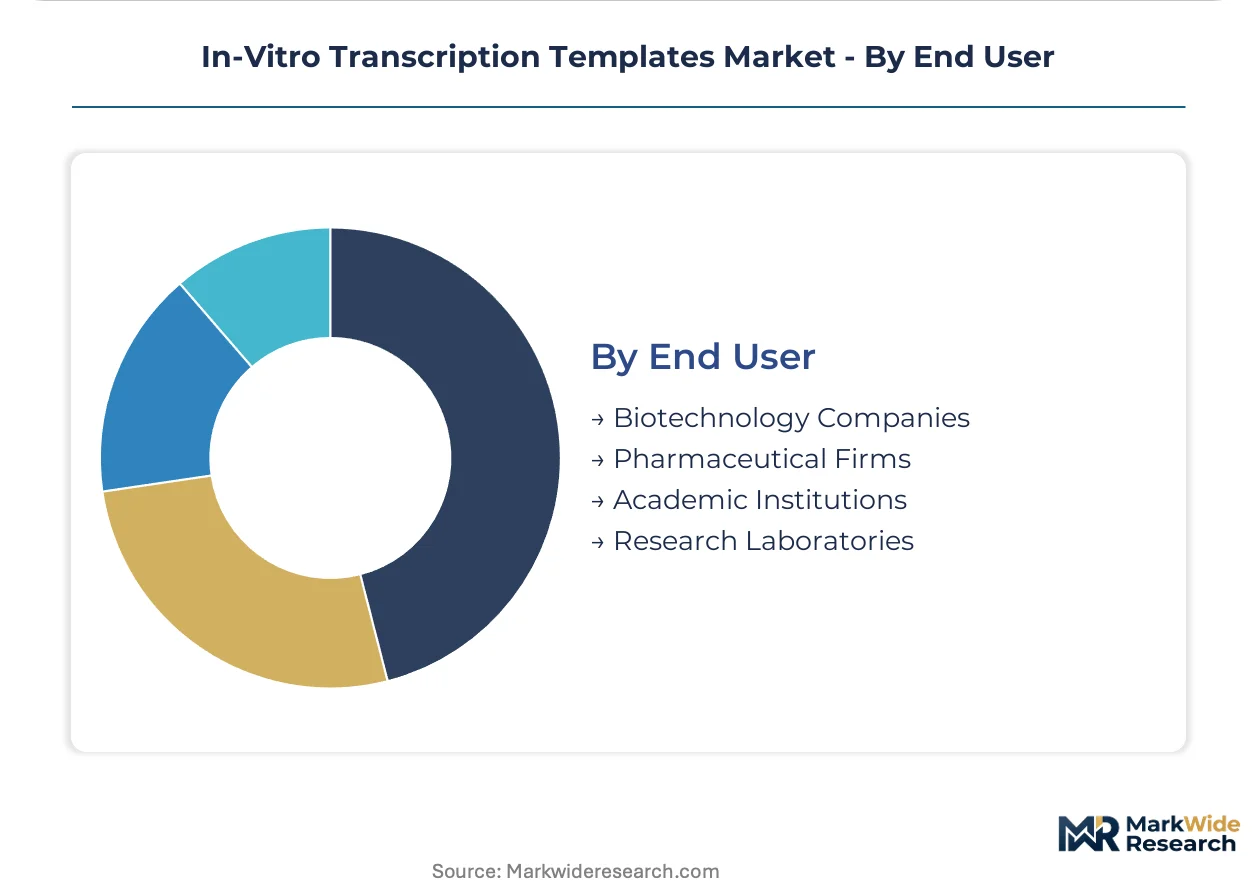
End User:
Customer type determines procurement sophistication, with pharmaceutical firms demanding integrated supply chain documentation and academic institutions prioritizing cost and turnaround speed.
- Biotechnology Companies:Mid-stage developers requiring flexible template sourcing for pipeline candidates across multiple modalities. These firms are consolidating supplier panels to three to five qualified providers per region to reduce qualification burden.
- Pharmaceutical Firms:Large developers with captive template manufacturing or long-term CDMO partnerships for commercial-scale mRNA production. These buyers mandate ISO 13485 certification and documented template stability programs.
- Academic Institutions:University laboratories with decentralized procurement and research-grade volume requirements.
- Research Laboratories:Government and nonprofit research facilities with specialized template needs for basic science applications.
Academic institutions represent the broadest installed base. Biotechnology companies are where expansion concentrates as cell therapy and mRNA pipelines mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German template manufacturers export GMP-grade linear substrates to mRNA vaccine producers across the European Union and United States, establishing a transatlantic supply corridor that handles the majority of clinical-grade procurement outside North America.
United States
FDA Chemistry, Manufacturing, and Controls guidance drives template provenance documentation requirements for commercial mRNA drug substance. The agency mandates identity verification and stability testing that extends supplier qualification timelines. Greater Boston and the San Francisco Bay Area host concentrated biotechnology clusters where CAR-T developers and vaccine manufacturers standardize on CRISPR-edited linear formats.
Germany
EMA Annex 2 GMP revisions mandate nucleic acid documentation standards that force mRNA developers to upgrade template sourcing. The country's central bank supports biotech financing through targeted credit facilities. The Rhine-Main and Upper Bavaria regions anchor GMP-grade production capacity serving domestic vaccine developers and export markets.
China
Centralized biologics manufacturing investment in Suzhou and Shanghai generates localized template procurement demand at scale. NMPA regulatory pathways for mRNA therapeutics are converging toward ICH-aligned nucleic acid standards. Yangtze River Delta biotechnology parks attract dedicated template synthesis facilities to serve domestic cell therapy pipelines.
India
Domestic vaccine developers and CDMOs seek qualified template suppliers as GMP-grade infrastructure remains underdeveloped. CDSCO regulatory frameworks for nucleic acid therapeutics are evolving toward commercial manufacturing requirements. Maharashtra and Telangana biotechnology corridors present white space for certified providers serving export and domestic markets.
Switzerland
Gene therapy developers demand scarless linear templates for clinical candidate screening and regulatory submission. Swissmedic maintains stringent nucleic acid quality standards that filter market access for template providers. The Basel biotech cluster anchors specialized procurement relationships with dedicated nucleic acid manufacturers.
In-Vitro Transcription Templates Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered supply relationships. Thermo Fisher Scientific anchors clinical-grade template supply chains through integrated reagent-to-instrument ecosystems. New England Biolabs and GenScript Biotech Corporation occupy research-grade and custom synthesis vectors respectively. Consolidation concentrates among three to five qualified providers per manufacturing cluster, while fragmentation persists in preclinical and analytical segments. Dominant competitive moves include strategic partnerships with mRNA vaccine developers and capacity expansion into GMP-certified production facilities.
Among United States-based diversified life science conglomerates, Thermo Fisher Scientific Inc. and Danaher Corporation exemplify channel-controlling archetypes that integrate template supply with analytical instrumentation and CDMO services. New England Biolabs represents the research-grade specialist tier, anchoring demand through enzymatic synthesis platforms. GenScript Biotech Corporation occupies the custom synthesis vector, competing on turnaround velocity for gene therapy developers requiring rapid template iteration.
| Leading Market Players |
|---|
| New England Biolabs |
| Bio-Rad Laboratories Inc. |
| Thermo Fisher Scientific Inc. |
| Danaher Corporation |
| GenScript Biotech Corporation |
| Promega Corporation |
| Takara Bio Inc. |
| TriLink BioTechnologies |
| Agilent Technologies Inc. |
| Others |
Supply Flow & Price Mechanics
The transatlantic pharmaceutical freight corridor connecting Rhine-Main biologics clusters to Boston mRNA manufacturers carries premium logistics costs that amplify price differentiation between GMP-certified and research-grade template tiers. This corridor's cost dynamics concentrate pricing power among ISO 13485-accredited suppliers while compressing margins for synthetic providers exposed to phosphoramidite feedstock volatility.
Pricing Analysis
The pricing gap between enzymatic synthesis platforms and legacy phosphoramidite chemistry spans approximately threefold, with next-generation hybrid workflows commanding mid-tier positioning. Three-tier pricing structure across premium GMP-grade, standard analytical-grade, and economy research-grade levels separates buyers by documentation burden and sequence fidelity requirements. Pricing pressure stems from concentrated buyer consolidation to three-to-five qualified providers per manufacturing cluster, with biotechnology companies exhibiting highest price sensitivity due to pipeline stage uncertainty while pharmaceutical firms absorb premiums for provenance documentation.
Supply Chain Analysis
Extended payment terms from large mRNA vaccine developers are forcing mid-tier suppliers to seek supply-chain finance facilities, compressing working capital cycles across the value chain. Production concentrates in the United States, Germany, and China where GMP-grade capacity clusters serve regional biologics manufacturing hubs. Phosphoramidite monomers, high-fidelity polymerases, and chromatography resins constitute critical input dependencies. Single-source vulnerability around clinical-grade polymerase supply creates structural risk. Distribution runs through specialized nucleic acid CDMOs that have unbundled from fill-finish service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward pharmaceutical firms and large biotechnology companies as these buyers consolidate supplier panels to three-to-five qualified providers per region, fragmenting pricing leverage among template manufacturers.
For Market Incumbents: Entrench GMP-grade positioning through captive backward integration into phosphoramidite manufacturing and forced degradation stability program investments that extend qualification timelines for challengers. Thermo Fisher Scientific's integrated reagent-to-instrument ecosystem demonstrates how channel control defends against enzymatic synthesis disruptors. Priority leverage sits with ISO 13485 certification depth rather than capacity scale alone. For New Entrants and Emerging Players: India's underdeveloped GMP-grade template infrastructure presents immediate white-space opportunity for qualified suppliers serving domestic vaccine developers and export markets. Target Maharashtra and Telangana biotechnology corridors where CDSCO regulatory evolution creates first-mover advantage. Self-amplifying mRNA replicon template architectures offer specialized premium segments with reduced incumbent saturation. Go-to-market positioning should emphasize rapid turnaround velocity for gene therapy developers requiring CRISPR-edited linear template iteration. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified life science conglomerates seeking to divest non-core nucleic acid synthesis capabilities. Long-term viability hinges on enzymatic synthesis platform maturation and regulatory documentation automation. Acquisition archetypes include mid-scale synthetic biology tool providers with latent GMP conversion potential. The signal to watch is FDA Chemistry, Manufacturing, and Controls guidance expansion beyond vaccines into cell therapy templates, which would inflect qualification demand.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Certification Investment | ISO 13485 and ICH Q5D compliance opens pharmaceutical partnerships with eighteen-month qualification barriers. |
| Enzymatic Synthesis Platform Development | Hybrid phosphoramidite-enzymatic workflows compress template procurement timelines for gene therapy screening. |
| Regional Capacity Expansion | India CDMO infrastructure addresses geographic supply risk for Asia-Pacific mRNA developers. |
| Stability Program Documentation | FDA-mandated forced degradation studies extend analytical development burdens onto template suppliers. |
| Supplier Panel Consolidation | Large vaccine developers reducing qualified providers per region to three-to-five intensifies competitive selection. |
Methodological Framework
Desk research of FDA Chemistry, Manufacturing, and Controls guidance documents, EMA Annex 2 GMP revision filings, and ISO 13485 certification databases preceded structured interviews with mRNA manufacturing executives, regulatory affairs leads at template suppliers, gene therapy CDMO procurement managers, and CRISPR platform development scientists. Secondary validation drew from ClinicalTrials.gov mRNA therapeutic registrations, SEC 10-K filings of listed life science conglomerates, and customs data on phosphoramidite import flows. Bottom-up template procurement volume estimates triangulated against top-down biologics manufacturing capacity projections.
Assumptions held regulatory guidance trajectories fixed at current FDA and EMA documentation standards while varying enzymatic synthesis adoption rates and CRISPR-edited linear template penetration across gene therapy applications. The analytical framework modeled segmentation across product type, grade tier, application, and end-user archetype throughout the forecast period. CAGRs derived from regression analysis of historical biologics manufacturing investment cycles and nucleic acid therapeutic pipeline advancement rates. Industry-specific inputs included polymerase error rate improvement curves and GMP certification timeline distributions.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by enzymatic synthesis specialists or accelerated WHO mRNA technology transfer hub deployment would shift outcomes. Macroeconomic deviation in specialty chemical feedstock markets, regulatory expansion of template provenance requirements, or breakthroughs in long linear template fidelity would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Middle East and Africa Exosome Research Products Market
Biomedical Technology
Immunoprecipitation Market
Biomedical Technology
PD L1 Biomarker Testing Market
Biomedical Technology
Cell Tracing and Tracking Test Market
Biomedical Technology
Global Peptide Microarray Market
Biomedical Technology
Global Oncology Based in-Vivo CRO Market
Biomedical Technology
Custom Nucleic Acid Market
Biomedical Technology
Particle-Enhanced Turbidimetric Immunoassays Market
Biomedical Technology
Global Protein Characterization and Quantification Market
Biomedical Technology
Cell Cryopreservation Market
Biomedical Technology
Drug Discovery Enzymes Market
Biomedical Technology
Cell Isolation Market
Biomedical Technology
Asia-Pacific Digital PCR Market
Biomedical Technology
Fluoro Enzymatic Assays Market
Biomedical Technology
Global Glycobiology Market
Biomedical Technology
Rat and Mouse Model Market