
 Cell Penetrating Peptide Market | 2026-2036
Cell Penetrating Peptide Market Size, Share, and Industry Trends Forecast 2026-2036
Cell Penetrating Peptide Market Analytics
EU MDR is shifting the cost-of-entry calculus for peptide-based therapeutic developers seeking CE-marked status in Europe. Bachem leverages its manufacturing scale to dominate GMP peptide production for clinical-stage programs. Sarepta Therapeutics anchors its competitive position through specialized expertise in genetic disease applications where CPPs enable oligonucleotide delivery across biological membranes.
Cell penetrating peptides are short amino acid sequences, typically 5-30 residues, that facilitate translocation of cargo molecules across plasma membranes without permanent membrane disruption; they function through energy-independent mechanisms including direct penetration and endocytosis-mediated uptake, primarily serving biopharmaceutical research and therapeutic development. Peptide-based therapeutics occupy the largest value share among product types due to established clinical pipelines, while drug delivery systems represent the fastest-expanding category as developers engineer next-generation CPP-conjugated nanoparticles for targeted intracellular release. Cancer therapy leads application demand given the imperative for intracellular delivery of chemotherapeutic and immunomodulatory payloads, whereas gene therapy applications sustain the highest R&D intensity as viral vector alternatives face manufacturing and immunogenicity constraints.
FDA, EMA, and ISO 13485 collectively govern CPP product development through divergent pathways: FDA's Center for Biologics Evaluation and Research oversees gene therapy INDs employing peptide vectors, while EMA's Committee for Medicinal Products for Human Use evaluates quality attributes for synthetic peptide APIs under its MDR framework. Stakeholders must monitor evolving pharmacopeial standards for synthetic peptide impurities and characterize immunogenicity profiles early in development to preempt regulatory objections during pivotal trials.
Market Dynamics
Biopharmaceutical developers face intensifying pressure to demonstrate intracellular delivery efficiency ahead of first-in-human trials, as FDA's evolving guidance on nucleic acid vectors elevates mechanistic proof-of-concept to a gating requirement for IND approval.
Growth Catalysts
- EMA MDR pathway clarity:The Medical Device Regulation framework now explicitly addresses peptide-drug conjugate classification, reducing regulatory ambiguity for developers seeking CE-marked status in Europe.
- Oncology intracellular targeting imperative:Chemotherapeutic payloads require membrane penetration that small molecules cannot achieve, creating durable demand for CPP-enabled delivery systems in solid tumor programs.
- Non-viral vector substitution:Viral immunogenicity and manufacturing bottlenecks are accelerating peptide-based alternatives for gene therapy cargo transport.
Market Restraints
- API synthesis cost concentration:Solid-phase peptide synthesis consumes high-purity amino acid feedstocks whose pricing volatility tracks agricultural commodity markets.
- GMP manufacturing capacity bottleneck:Multi-ton peptide production capability concentrates among Swiss and German contract manufacturers, creating single-source risk for clinical-stage sponsors.
- Endosomal escape limitation:CPP-cargo complexes frequently remain trapped in endosomal compartments, reducing cytosolic bioavailability below therapeutic thresholds.
Strategic Opportunities
- Japan's regenerative medicine commercialization:PMDA's accelerated approval pathways for nucleic acid therapeutics create first-mover advantage for CPP developers establishing local partnerships.
- Brain delivery application white space:Blood-brain barrier penetration remains the critical unmet need in neurodegenerative disease, with CPPs demonstrating preclinical transport of antisense oligonucleotides.
- ISO 13485 certification differentiation:Medical device-grade quality management systems enable dual-track positioning as both therapeutic and diagnostic delivery platforms.
Industry Challenges
- Peptide chemist talent scarcity:Synthetic expertise for complex cyclic and stapled peptide architectures concentrates among a narrow cohort of academic laboratories and specialized CROs.
- Immunogenicity characterization burden:Preclinical assessment of anti-peptide antibody responses requires extended toxicology timelines that compress development schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cell Penetrating Peptide Market |
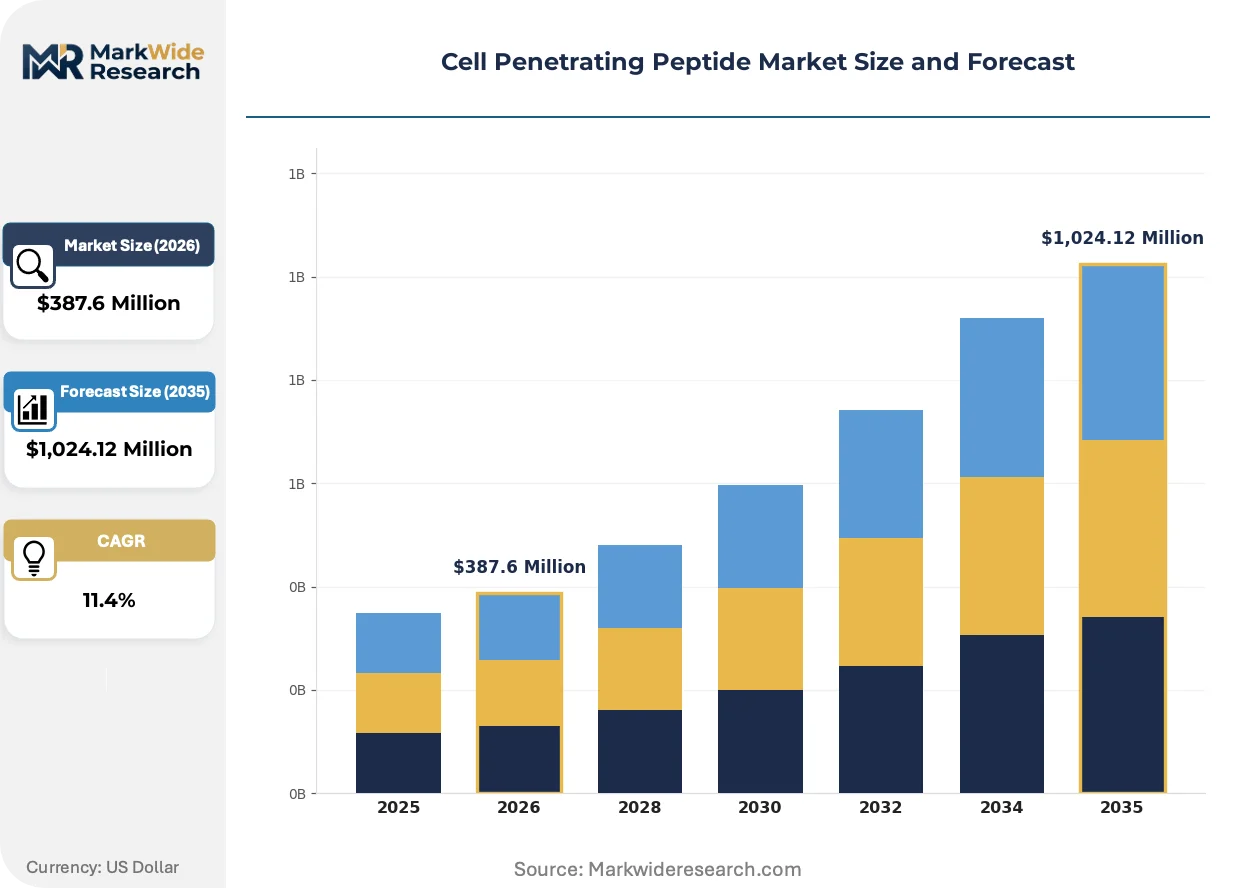
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Peptide-Based Therapeutics, Diagnostics, Research Reagents, Drug Delivery Systems Application: Cancer Therapy, Gene Therapy, Vaccine Development, Antibody Fragment Delivery End User: Pharmaceutical Companies, Academic Institutions, Research Organizations, Biotechnology Firms Technology: Non-Covalent Delivery, Covalent Delivery, Nanoparticle-Based Delivery, Electroporation |
| Companies Covered | AnaSpec, Peptomyc, BioAlps, Sarepta Therapeutics, Revance Therapeutics, PolyPeptide Group, Bachem, Pepscan, Creative Peptides, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cell Penetrating Peptide Market Evolving Landscape
Peptide engineering and conjugation chemistry are converging to expand the addressable cargo space for intracellular delivery, with implications spanning therapeutic modality selection and manufacturing process design.
Stapled peptide technology is electrifying the field by constraining helical secondary structures that resist proteolytic degradation while maintaining cell-penetrating capacity. Oncology developers at venture-backed biotechnology firms are advancing stapled CPPs into IND-enabling studies at compressed 18-month timelines. This structural stabilization is electrifying the competitive barrier between academic peptide chemistry groups and commercial-scale manufacturers capable of reproducible macrocyclization.
FDA's Center for Biologics Evaluation and Research issued draft guidance in 2023 clarifying chemistry, manufacturing, and controls expectations for peptide-nucleic acid conjugates, establishing impurity thresholds and characterization standards previously absent. The guidance imposes orthogonal analytical method requirements that favor developers with established mass spectrometry and chromatography capabilities. Gene therapy sponsors with peptide vector programs are responding by front-loading CMC investment ahead of clinical entry to preempt regulatory holds.
Large pharmaceutical buyers are consolidating peptide API procurement through preferred supplier agreements that bundle GMP manufacturing with analytical development services. This channel compression displaces transactional spot purchasing that previously dominated clinical-stage supply relationships. The concentration is most visible in the United States, where top-20 biopharmaceutical firms now account for the majority of outsourced peptide synthesis volume.
Cell Penetrating Peptide Market Segmentation
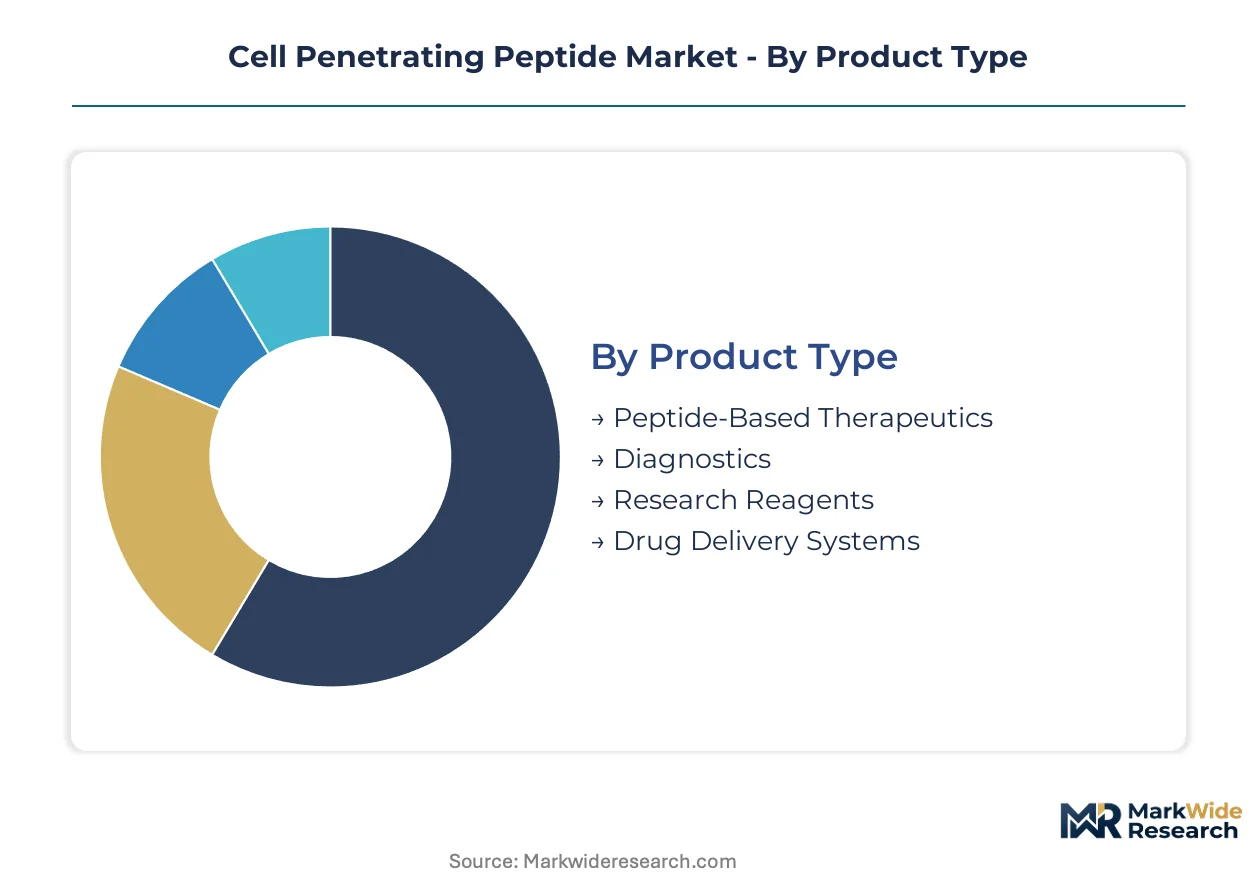
Cell penetrating peptide markets segment across functional roles and technical modalities that determine development timelines, regulatory pathways, and manufacturing requirements. Understanding these divisions reveals where capital concentrates and which technical approaches command premium positioning.
Product Type:
Peptide engineering specifications and clinical maturity separate product categories by development risk and revenue concentration.
- Peptide-Based Therapeutics:Synthetic amino acid sequences engineered for direct pharmacological activity or as targeting ligands conjugated to cytotoxic payloads. Cancer programs at biotechnology firms in the United States consume the majority of GMP-grade material as they advance stapled peptide architectures through IND-enabling studies.
- Drug Delivery Systems:CPP-conjugated nanoparticles and liposomal formulations engineered for endosomal escape and controlled intracellular release. Venture-backed gene therapy developers in Switzerland and Germany are scaling cGMP manufacturing for peptide-nucleic acid complexes as alternatives to viral vectors.
- Diagnostics:Peptide probes for intracellular imaging and biomarker detection, primarily serving preclinical research workflows.
- Research Reagents:Catalog-grade CPPs and conjugation kits for laboratory-scale membrane transport studies.
Peptide-Based Therapeutics leads on scale; Drug Delivery Systems leads on momentum.
Application:
Clinical indication drives specification requirements and partnership structures across the value chain.
- Cancer Therapy:Intracellular delivery of chemotherapeutic agents and immunomodulatory payloads that small molecules cannot access. Solid tumor programs at United States biopharmaceutical companies command priority investment due to the imperative for membrane-penetrating delivery mechanisms.
- Gene Therapy:Peptide-mediated transport of antisense oligonucleotides, mRNA, and CRISPR components across biological membranes. Japanese regenerative medicine developers under PMDA accelerated pathways are establishing first-mover positions for non-viral nucleic acid delivery.
- Vaccine Development:CPP-adjuvanted antigen delivery for intracellular immune presentation.
- Antibody Fragment Delivery:Transport of nanobodies and single-chain variable fragments across membrane barriers.
Cancer Therapy anchors current procurement volume; Gene Therapy commands the steepest expansion trajectory.
End User:
Customer type determines order scale, quality specifications, and technical support requirements.
- Pharmaceutical Companies:Large-scale GMP procurement with integrated analytical development and regulatory filing support. Top-20 United States biopharmaceutical firms now consolidate peptide API purchasing through preferred supplier agreements bundling manufacturing with CMC services.
- Biotechnology Firms:Clinical-stage sponsors with compressed timelines requiring rapid scale-up from milligram to kilogram quantities. Swiss and German contract manufacturers dominate relationships with these venture-backed developers.
- Academic Institutions:Research-grade peptide synthesis for mechanistic studies and proof-of-concept publications.
- Research Organizations:Non-profit and government laboratories focused on target validation and delivery optimization.
Pharmaceutical Companies dominate contract value; Biotechnology Firms drive specification innovation.
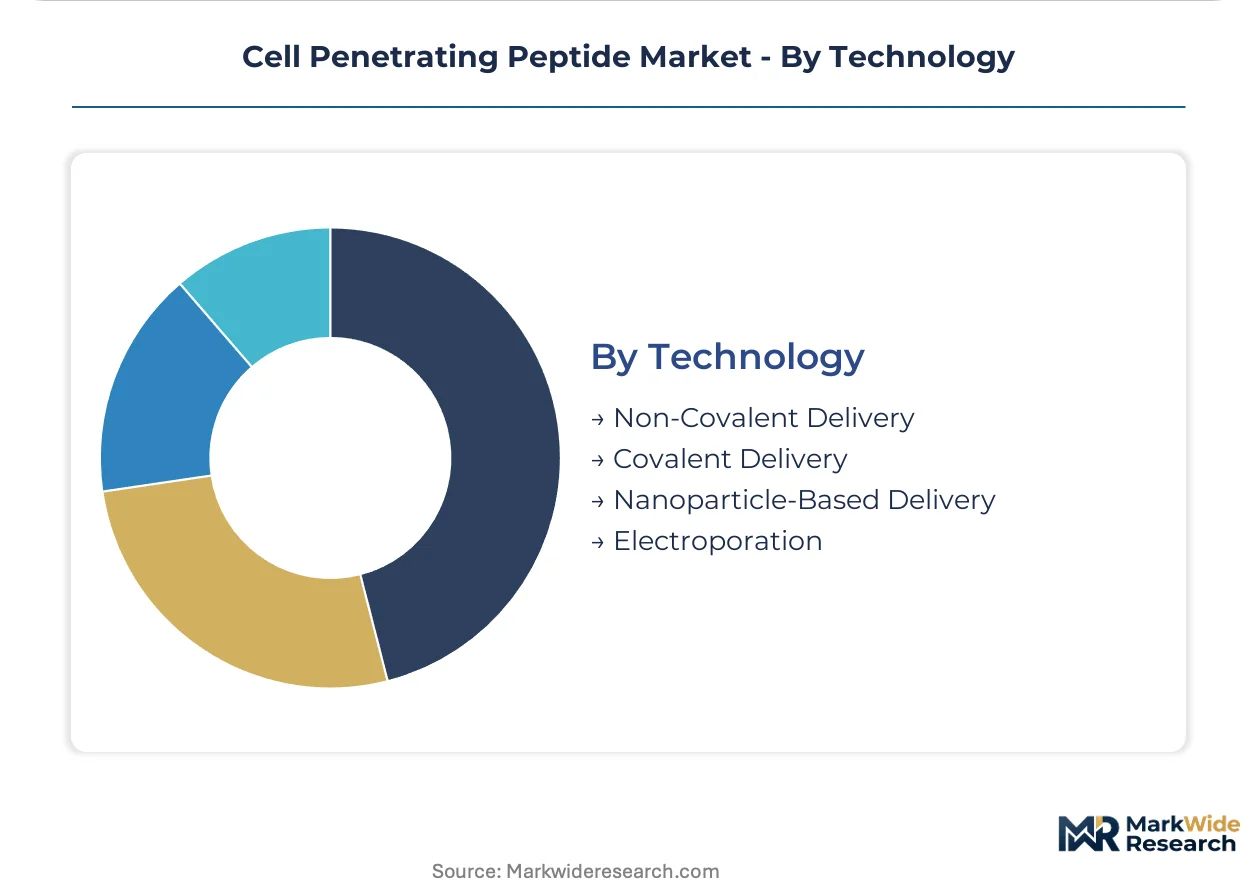
Technology:
Delivery mechanism selection constrains cargo compatibility, manufacturing complexity, and regulatory classification.
- Covalent Delivery:Stable peptide-cargo conjugates formed through amide, disulfide, or click chemistry linkages enabling precise stoichiometry. FDA's Center for Biologics Evaluation and Research imposed orthogonal analytical requirements for these constructs in recent guidance, favoring developers with established mass spectrometry capabilities.
- Nanoparticle-Based Delivery:CPP-functionalized lipid and polymer nanoparticles for encapsulating nucleic acids and small molecules. German manufacturers are scaling multi-ton production capacity for clinical-stage programs seeking alternatives to viral vectors.
- Non-Covalent Delivery:Electrostatic complexes formed between cationic peptides and anionic cargo without permanent chemical bonds.
- Electroporation:Physical membrane permeabilization combined with peptide co-delivery for enhanced uptake efficiency.
Covalent Delivery commands premium pricing; Nanoparticle-Based Delivery is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peptide chemist talent concentrates in Swiss and German manufacturing clusters, while United States biotechnology hubs drive clinical-stage demand. FDA, EMA, and PMDA pathways are diverging in their nucleic acid delivery guidance, fragmenting regulatory strategy across development programs. Venture capital deployment tracks these workforce and policy concentrations.
United States
Biotechnology firms in Greater Boston and San Francisco Bay Area anchor clinical-stage peptide therapeutic development. FDA's Center for Biologics Evaluation and Research issued 2023 draft guidance imposing orthogonal analytical requirements for peptide-nucleic acid conjugates. Massachusetts and California command priority investment from venture-backed sponsors advancing stapled peptide architectures through IND-enabling studies.
Switzerland
Multi-ton GMP peptide production capability concentrates among Basel and Zurich contract manufacturers serving global pharmaceutical procurement. Swissmedic oversees quality standards for synthetic peptide APIs exported to European and Asian markets. Bachem leverages its manufacturing scale to dominate clinical-stage supply relationships with United States and Japanese gene therapy developers.
Germany
German manufacturers are scaling cGMP capacity for peptide-nucleic acid complexes as alternatives to viral vectors. EMA's Committee for Medicinal Products for Human Use evaluates impurity thresholds under evolving MDR frameworks. Bavarian and Baden-Württemberg industrial clusters house specialized CROs supporting mass spectrometry and chromatography capabilities now required by FDA guidance.
Japan
PMDA's accelerated approval pathways for nucleic acid therapeutics are attracting CPP developers establishing local partnerships. Regenerative medicine commercialization programs create first-mover positioning for non-viral delivery platforms. Tokyo and Osaka metropolitan areas concentrate preclinical research infrastructure for blood-brain barrier penetration applications.
United Kingdom
Academic peptide chemistry expertise concentrates at Cambridge and Oxford laboratories advancing cyclic and stapled architectures. MHRA post-Brexit regulatory frameworks are diverging from EMA MDR pathways, creating dual-track compliance requirements. London biotechnology clusters specialize in diagnostic probe development for intracellular imaging applications.
Cell Penetrating Peptide Market Competitive Landscape
The competitive structure tilts toward manufacturing-scale specialists with integrated analytical development capabilities. Contract manufacturers in Switzerland and Germany command pricing premiums through bundled GMP production and regulatory filing support. Two strategic archetypes dominate: multi-ton peptide API producers with captive amino acid supply chains, and boutique CROs specializing in complex macrocyclization chemistry. Capacity expansion and preferred supplier agreement consolidation represent the dominant competitive moves as large pharmaceutical buyers compress procurement channels.
Within the manufacturing-scale tier, Bachem and PolyPeptide Group exemplify European producers leveraging geographic concentration of peptide synthesis expertise. Sarepta Therapeutics occupies a position among United States-based gene therapy developers deploying specialized CPP capabilities for genetic disease applications. These three entities represent the divergence between supply-side manufacturing concentration and demand-side therapeutic development specialization that defines competitive positioning in this market.
| Leading Market Players |
|---|
| AnaSpec |
| Peptomyc |
| BioAlps |
| Sarepta Therapeutics |
| Revance Therapeutics |
| PolyPeptide Group |
| Bachem |
| Pepscan |
| Creative Peptides |
| Others |
Value Network & Pricing Analysis
Amino acid feedstock price volatility tracked through agricultural commodity indices cascades into solid-phase peptide synthesis costs, compressing margins for clinical-grade manufacturers while amplifying pricing power for Swiss and German contract producers with captive amino acid supply chains.
Pricing Analysis
Bundled GMP manufacturing with analytical development services commands 40-60% premiums over unbundled transactional procurement. Three-tier pricing structure across premium, standard, and economy levels separates multi-ton API producers from boutique CROs and catalog-grade suppliers. Pricing pressure stems from large pharmaceutical buyers consolidating procurement through preferred supplier agreements. Biotechnology firms with compressed IND timelines show lowest price sensitivity; academic institutions exhibit highest.
Supply Chain Analysis
Domestic-content mandates under Japan's PMDA accelerated pathways and evolving FDA localization preferences are reshaping sourcing strategies for peptide-nucleic acid conjugates. Multi-ton GMP capacity concentrates in Switzerland, Germany, and the United States. Raw material dependencies center on high-purity Fmoc-protected amino acids, specialized resins, and chromatography solvents. Single-source vulnerability runs through Swiss contract manufacturers serving global gene therapy sponsors. Distribution runs through direct long-term offtake agreements rather than spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EMA MDR compliance costs in Europe diverge from PMDA accelerated pathways in Japan, creating 18-24 month regulatory timeline differentials for identical peptide-vector programs.
For Market Incumbents: To counter viral vector substitution threats from peptide-based alternatives, Bachem and PolyPeptide Group should deepen backward integration into amino acid feedstock production while expanding multi-ton capacity in Basel and Zurich manufacturing clusters. ISO 13485 certification investment creates defensive moats against emerging CRO competitors. For New Entrants and Emerging Players: Launch via specialized CRO partnerships targeting blood-brain barrier penetration applications in Japanese regenerative medicine programs. Stapled peptide engineering for neurodegenerative disease represents the most penetrable white space. Gene therapy developers under PMDA pathways offer the clearest go-to-market angle through local partnership structures. For Investors and Strategic Acquirers: Asymmetric upside sits with boutique macrocyclization CROs possessing stapled peptide expertise and established FDA CMC relationships. Five-to-ten year viability hinges on non-viral vector substitution rates in gene therapy. Watch for FDA final guidance on peptide-nucleic acid conjugates as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Multi-ton GMP capacity expansion in Swiss clusters secures preferred supplier status with top-20 biopharmaceutical buyers. |
| Regulatory Approval Pathway | PMDA accelerated approval navigation in Japan creates first-mover positioning for non-viral nucleic acid delivery platforms. |
| Backward Integration | Captive amino acid feedstock production insulates margin structures from agricultural commodity price volatility. |
| Clinical Trial Advancement | IND-enabling studies for stapled peptide architectures in oncology compress development timelines to 18 months. |
| Licensing Agreement | Peptide-vector technology out-licensing to gene therapy sponsors displaces viral immunogenicity constraints. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with peptide chemistry directors, regulatory affairs leads at gene therapy sponsors, GMP manufacturing executives, and hospital procurement specialists with secondary validation through FDA CBER guidance documents, EMA MDR framework updates, PMDA accelerated pathway filings, and ClinicalTrials.gov peptide-vector program tracking. Bottom-up synthesis of manufacturer capacity and top-down demand modeling from therapeutic pipeline analysis were triangulated against contract manufacturing procurement databases.
Comparable-period anchoring aligned the projection horizon against historical GMP peptide production volumes and venture capital deployment patterns across biotechnology clusters. Segmentation dimensions spanned product type, application, end user, and technology modality with regional regulatory cluster differentiation. CAGRs were derived through regression analysis of procurement volume trajectories and capacity expansion announcements. Forecast inputs incorporated endosomal escape efficiency improvements and stapled peptide clinical progression rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA guidance finalization delays or amino acid supply disruptions. Assumptions reflect current regulatory frameworks and therapeutic pipeline compositions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
High-End Cellomics Market
Biomedical Technology
Polymerase Chain Reaction (PCR) Market
Biomedical Technology
Global Nicotinamide Adenine Dinucleotide (NAD) Market
Biomedical Technology
Exosomes Market
Biomedical Technology
Global Immunofluorescence Assay Market
Biomedical Technology
Global Exosome Research Products Market
Biomedical Technology
Bioadhesive Microspheres Market
Biomedical Technology
Global Bifida Ferment Lysate Market
Biomedical Technology
Brain Biomarkers Market
Biomedical Technology
Global Primary Cell Culture Market
Biomedical Technology
Strand Displacement Amplification (SDA) Market
Biomedical Technology
Nano-Silicon Drug Delivery Platform Market
Biomedical Technology
Global Cell Signaling Market
Biomedical Technology
Immunoprecipitation Market
Biomedical Technology
Reverse Transcriptase Enzymes Market
Biomedical Technology
Bead-Based Flow Cytometry Market