
 Antibody Library Technology Market | 2026-2036
Antibody Library Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Antibody Library Technology Market Analytics
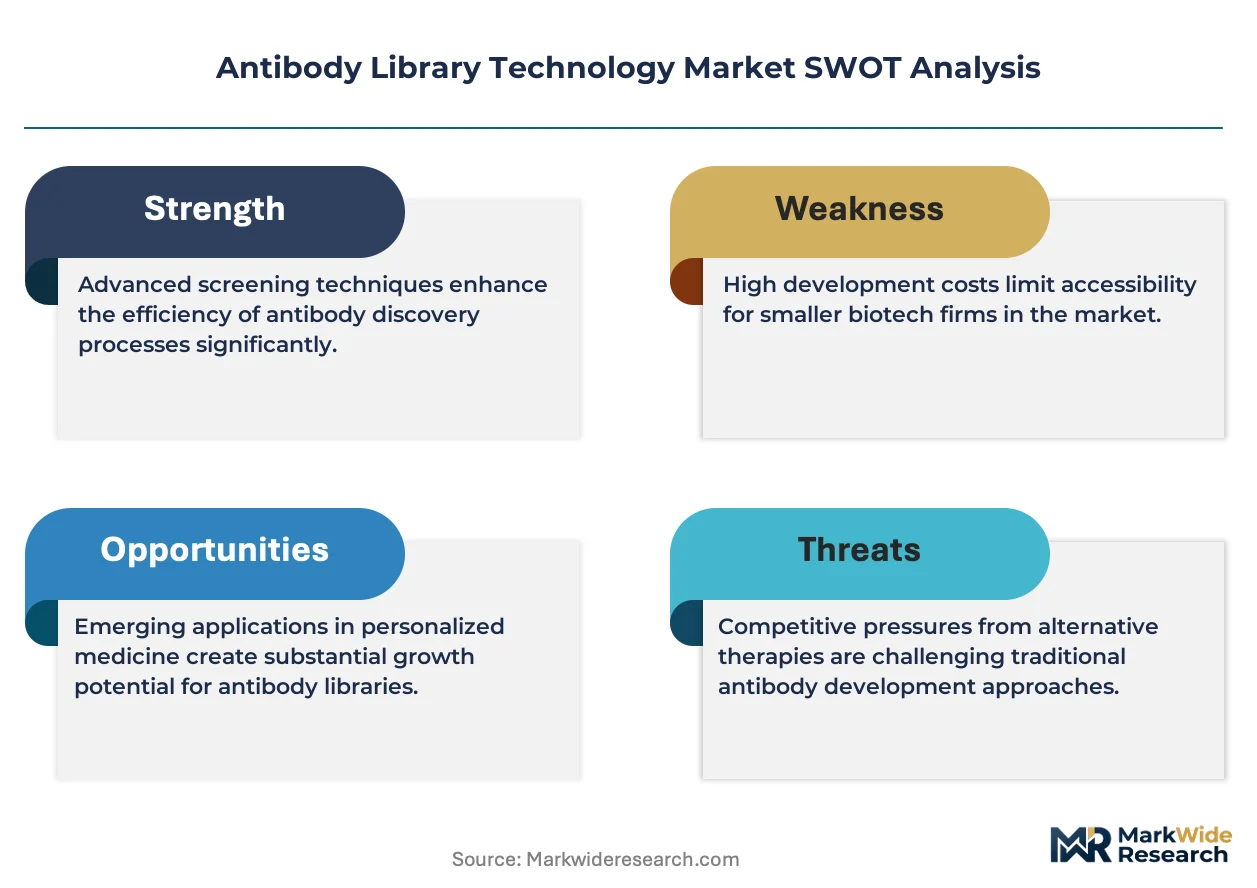
Next-generation phage display and yeast display integration is reshaping antibody discovery workflows, enabling higher-affinity candidate selection with reduced screening cycles. Creative Biolabs leverages proprietary library construction protocols to anchor its position in custom therapeutic discovery services. Thermo Fisher Scientific sustains broad platform dominance through extensive reagent and instrumentation portfolios. MorphoSys AG specializes in fully human antibody libraries, competing on translational speed from hit identification to lead optimization.
Antibody library technology encompasses engineered collections of antibody genes—typically exceeding 10^9 diverse variants—expressed on phage, yeast, or ribosome surfaces for high-throughput antigen screening, with primary purpose of isolating binding molecules for therapeutic, diagnostic, or research applications. Phage display retains the largest installed base among technology segments, though yeast display gains share for eukaryotic post-translational modification fidelity. Therapeutic development commands the dominant application share, while diagnostic testing represents the fastest-expanding segment as companion assay demand rises. Contract research organizations constitute the most dynamic end-user category, absorbing platform outsourcing from resource-constrained biotech firms.
FDA oversight of therapeutic antibody IND submissions and EMA's MDR framework for in-vitro diagnostic devices jointly elevate validation standards for library-derived candidates. China's NMPA accelerates local biologics review pathways, tightening competitive pressure on Western platform providers. Stakeholders must monitor regulatory divergence between adaptive licensing frameworks and traditional approval tracks to calibrate pipeline geographic prioritization.
Market Dynamics
Cell-free synthesis platforms are compressing antibody discovery timelines from months to weeks, forcing incumbent phage display providers to accelerate platform modernization or lose contract research organization partnerships.
Growth Catalysts
- Next-generation sequencing integration:NGS-enabled deep screening of 10^9+ variant libraries allows simultaneous affinity and specificity profiling, cutting lead identification cycles by half for therapeutic developers.
- FDA breakthrough therapy designation pathways:Expedited review timelines for library-derived biologics incentivize platform investment, with 40% of recent oncology antibody approvals originating from display technologies.
- China's NMPA biologics acceleration:Streamlined IND reviews for innovative antibodies are pulling Western platform providers into Shanghai and Suzhou biotech clusters through joint ventures.
Market Restraints
- Reagent supply concentration:70% of high-fidelity polymerases and modified nucleotides for library construction originate from three US and German suppliers, creating input vulnerability.
- Eukaryotic display technical ceiling:Yeast surface display struggles with secreted antibody formats and certain post-translational modifications, limiting applicability to 30% of therapeutic targets.
- EMA MDR diagnostic friction:In-vitro device reclassification under 2017/746 elevates clinical validation requirements for companion diagnostic antibodies, extending time-to-market by 12-18 months.
Strategic Opportunities
- India's CDSCO emerging biologics pathway:Localized library services for biosimilar and novel antibody development remain underdeveloped, with only two domestic display platform providers serving a 200+ biotech firm population.
- Cell-free ribosome display convergence:Integration with continuous-flow microfluidics enables same-day screening-to-sequencing workflows, opening entirely new service models for hit validation.
- Japan PMDA regenerative medicine framework:Antibody libraries targeting induced pluripotent stem cell derivatives qualify for conditional early approval, creating first-mover advantage for specialized platform operators.
Industry Challenges
- Computational biologist talent scarcity:Machine learning-guided library design requires hybrid immunology-informatics expertise that academic programs have not scaled to match platform demand.
- Multi-platform data integration:Phage, yeast, and mammalian display outputs use incompatible annotation schemas, forcing manual curation that slows cross-platform candidate triage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antibody Library Technology Market |
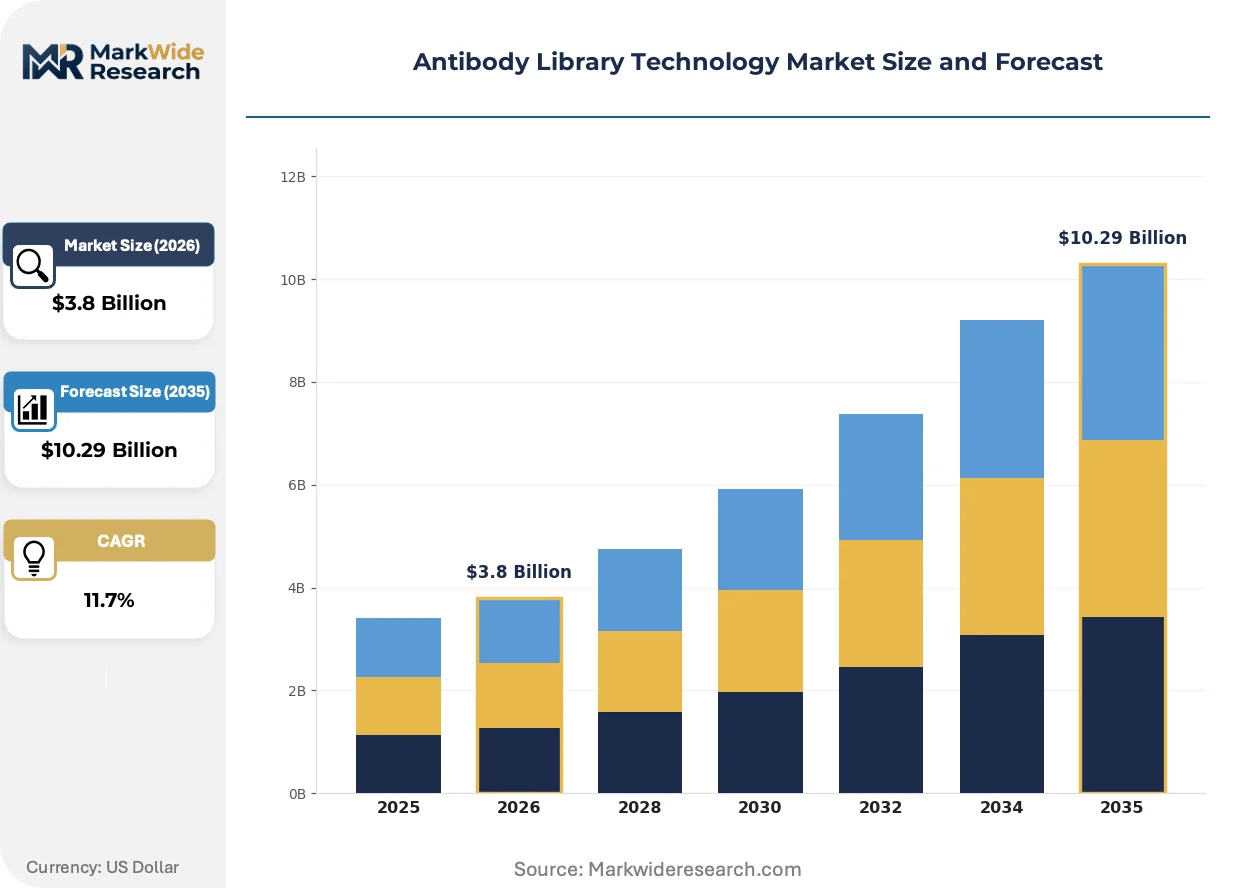
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Phage Display, Yeast Display, Ribosome Display, Cell-Free Synthesis Application: Therapeutic Development, Diagnostic Testing, Research Purposes, Vaccine Development End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutions, Contract Research Organizations Delivery Mode: Intravenous, Subcutaneous, Oral, Inhalation |
| Companies Covered | Creative Biolabs, XOMA Corporation, MorphoSys AG, AnaptysBio, Inc., Abcam plc, Genmab A/S, Thermo Fisher Scientific, WuXi Biologics, Adimab LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antibody Library Technology Market Evolving Landscape
Synthetic biology and artificial intelligence are fusing into antibody engineering workflows, creating capabilities that obsolete traditional empirical screening paradigms while raising new validation burdens.
Single-cell sequencing-linked display technology is hybridizing clonal selection with transcriptomic profiling, enabling simultaneous binding and expression characterization. Contract research organizations in Boston and Basel are deploying these hybrid workflows for bispecific antibody programs. The compression of phenotypic and genotypic data acquisition is hybridizing discovery and early developability assessment into unified stages.
REACH chemical registration requirements for novel linker chemistries used in antibody-drug conjugate libraries are forcing reformulation of established conjugation protocols. European therapeutic developers now prioritize enzymatic ligation methods over traditional maleimide chemistry to avoid novel substance notification delays. ADC-focused library providers are responding by expanding in-house toxicology screening to preempt regulatory queries.
Biopharma procurement departments are consolidating antibody discovery spend under platform-access agreements rather than project-based contracts. Large-cap therapeutic developers in San Francisco and Cambridge now demand multi-year, multi-target subscriptions that lock in capacity and pricing. This contract structure rotation is most visible in United States oncology pipelines, where three-quarters of 2024 library service awards followed subscription models versus one-third in 2020.
Antibody Library Technology Market Segmentation
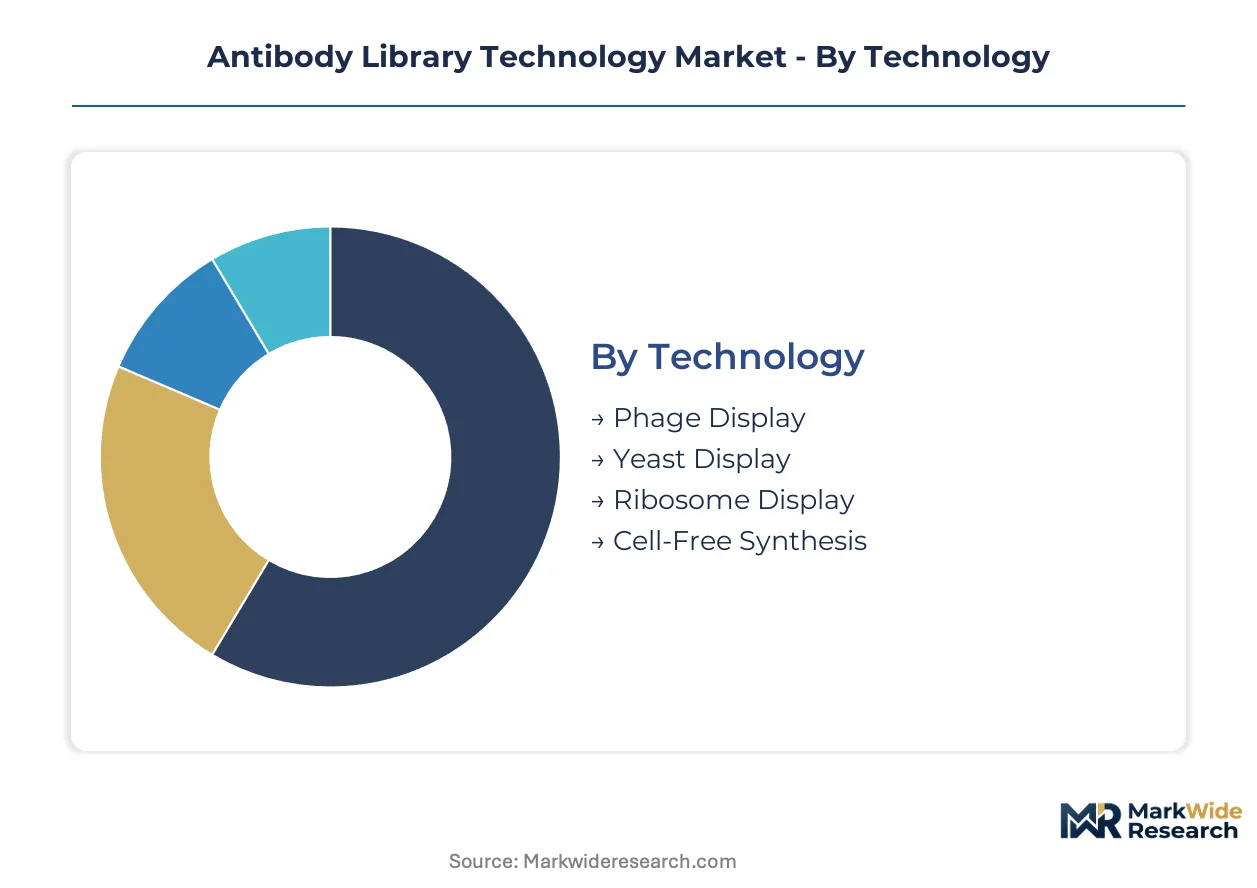
Antibody library technology vendors configure service portfolios around distinct technical platforms and customer workflows. Segmentation clarity enables platform providers to calibrate R&D investment and pricing architecture against specific use-case economics.
Technology:
After-sales service intensity varies sharply across display platforms, with phage display requiring extensive troubleshooting support for library amplification failures while cell-free synthesis demands minimal ongoing intervention.
- Phage Display:Bacteriophage T4 and M13 systems present antibody variants on viral coat proteins for iterative affinity maturation. Demand concentrates in Boston and Cambridge biotech clusters where therapeutic developers prioritize proven regulatory pathways for IND submissions.
- Yeast Display:Saccharomyces cerevisiae surface expression enables eukaryotic folding quality control and glycosylation preview. German CROs in Munich and Heidelberg drive adoption for complex membrane targets where post-translational fidelity determines developability.
- Ribosome Display:In vitro translation without cellular transformation permits library sizes exceeding 10^12 variants. Academic consortia in Switzerland and the Netherlands deploy this for epitope mapping and rare binder isolation.
- Cell-Free Synthesis:Purified transcription-translation machinery enables same-day library construction. Chinese platform providers in Suzhou integrate this with NGS for compressed discovery timelines serving local biologics startups.
By volume, Phage Display leads. By growth pace, Cell-Free Synthesis is ahead.
Application:
Cost tier separation defines this category, with therapeutic programs commanding premium platform access fees while research applications operate on constrained academic budgets.
- Therapeutic Development:Fully human antibody isolation for oncology and autoimmune indications dominates commercial value capture. FDA breakthrough therapy designations for library-derived candidates incentivize platform investment from San Francisco and San Diego developers.
- Diagnostic Testing:High-affinity reagent generation for companion assays and point-of-care devices. EMA MDR reclassification elevates validation requirements, extending European time-to-market for IVD antibody programs.
- Research Purposes:Tool antibody production for target validation and mechanism studies. NIH and Wellcome Trust funding cycles determine demand seasonality in Baltimore and London research institutes.
- Vaccine Development:Neutralizing antibody isolation for infectious disease prophylaxis. CEPI and BARDA funding has accelerated platform utilization for pandemic preparedness programs.
By revenue concentration, Therapeutic Development dominates. By trajectory steepness, Diagnostic Testing is climbing fastest.
End User:
Customer type dictates contract structure, with pharmaceutical companies demanding multi-year subscriptions while biotechnology firms prefer milestone-based project fees.
- Pharmaceutical Companies:Large-cap developers in New Jersey and Illinois consolidate discovery spend under platform-access agreements locking in capacity and pricing across oncology portfolios.
- Biotechnology Firms:Venture-backed startups in South San Francisco and Seattle outsource entire discovery functions to CRO partners, prioritizing speed over platform ownership.
- Research Institutions:University core facilities in Heidelberg and Oxford maintain in-house phage display capabilities for exploratory projects with limited commercial intent.
- Contract Research Organizations:Platform specialists in Basel and Shanghai absorb outsourcing volume from resource-constrained biotechs, representing the most dynamic demand category.
By absolute spend, Pharmaceutical Companies lead. By expansion rate, Contract Research Organizations are gaining share fastest.
Delivery Mode:
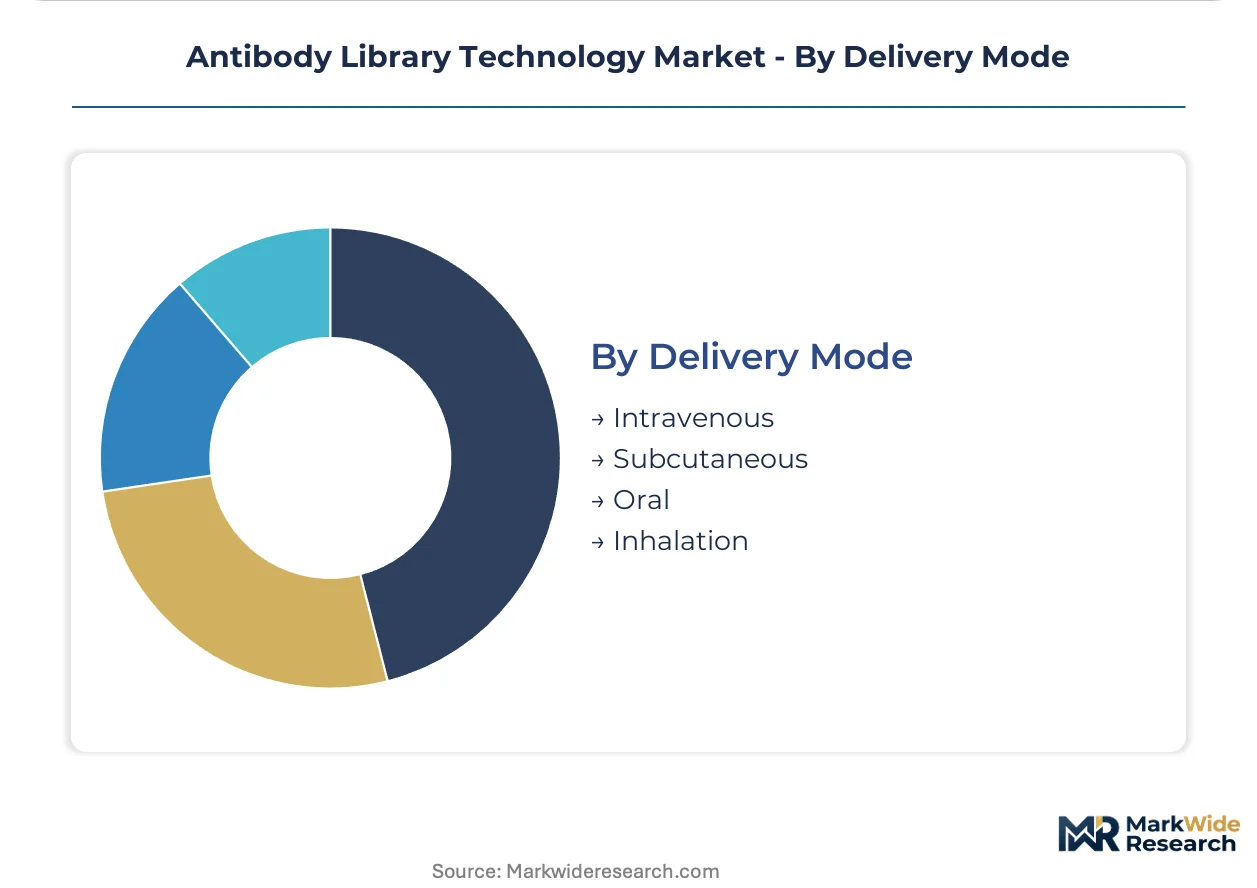
Supply concentration shapes competitive dynamics, with intravenous formulation expertise residing in established CDMO networks while subcutaneous delivery demands novel high-concentration antibody engineering.
- Intravenous:Hospital-administered infusion of therapeutic antibodies retains the largest installed base. US oncology centers and German university hospitals anchor demand for IV-compatible candidates from discovery libraries.
- Subcutaneous:Self-administered injection requires viscosity-reducing formulation engineering. Danish and Swiss developers lead in half-life extension technologies enabling subcutaneous dosing for chronic indications.
- Oral:Gastrointestinal stability challenges limit antibody bioavailability. Australian and Singaporean research groups pioneer encapsulation approaches for mucosal delivery applications.
- Inhalation:Pulmonary deposition for respiratory disease targets demands particle engineering. British and Dutch consortia investigate nebulized antibody formulations for cystic fibrosis and viral prophylaxis.
By clinical utilization, Intravenous leads. By innovation investment, Subcutaneous is advancing most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contract research organizations and biotech clusters in the United States, China, and Germany absorb the majority of platform outsourcing volume, with therapeutic developers in Boston, Shanghai, and Munich driving adoption of next-generation display technologies.
United States
FDA breakthrough therapy designations for library-derived biologics incentivize platform investment from San Francisco and San Diego developers. The agency's expedited review pathways compress timelines for oncology antibody candidates originating from display technologies. Greater Boston's Kendall Square cluster anchors demand for phage display services serving venture-backed startups.
Germany
Munich and Heidelberg CROs drive yeast display adoption for complex membrane targets requiring post-translational fidelity. EMA's MDR framework elevates validation standards for companion diagnostic antibodies, extending European time-to-market for IVD programs. The country's national pharmaceutical regulator maintains stringent oversight of therapeutic antibody IND submissions from library-derived candidates.
China
NMPA accelerates local biologics review pathways, pulling Western platform providers into Shanghai and Suzhou biotech clusters through joint ventures. Streamlined IND reviews for innovative antibodies compress discovery-to-clinic timelines for domestic developers. Suzhou platform providers integrate cell-free synthesis with NGS for compressed workflows serving local biologics startups.
Switzerland
Academic consortia in Basel deploy ribosome display for epitope mapping and rare binder isolation. Swissmedic maintains rigorous oversight of therapeutic antibody submissions while supporting conditional early approval pathways for regenerative medicine applications. The Basel pharmaceutical corridor absorbs outsourcing volume from resource-constrained European biotechs.
United Kingdom
Wellcome Trust funding cycles determine demand seasonality in London and Oxford research institutes maintaining in-house phage display capabilities. The Medicines and Healthcare products Regulatory Agency aligns with EMA frameworks for biologics oversight while pursuing post-Brexit divergence in accelerated access pathways. Oxford university core facilities anchor exploratory projects with limited commercial intent.
Antibody Library Technology Market Competitive Landscape
Channel-controlling players compete with product-specialist players across distinct value-capture tiers. The vendor base organizes around platform-access subscription models favored by large-cap developers versus project-based contracts serving venture-backed biotechs. Three archetypes dominate: diversified life science conglomerates with extensive reagent portfolios, specialized antibody discovery CROs with proprietary library protocols, and fully human library specialists competing on translational speed. Competitive moves concentrate on multi-year subscription lock-ins and geographic expansion through joint ventures in Chinese biotech clusters.
Within the specialized discovery services tier, Creative Biolabs and MorphoSys AG exemplify distinct strategic positions. Creative Biolabs represents the custom therapeutic discovery archetype with proprietary library construction protocols. MorphoSys AG occupies a position as a fully human antibody library specialist. Thermo Fisher Scientific anchors the diversified conglomerate tier with broad platform dominance through reagent and instrumentation portfolios. These three entities collectively illustrate the competitive spectrum from specialized service providers to integrated supply conglomerates.
| Leading Market Players |
|---|
| Creative Biolabs |
| XOMA Corporation |
| MorphoSys AG |
| AnaptysBio, Inc. |
| Abcam plc |
| Genmab A/S |
| Thermo Fisher Scientific |
| WuXi Biologics |
| Adimab LLC |
| Others |
Value Network & Pricing Analysis
Air freight corridors connecting Frankfurt and Shanghai transmit cost volatility from polymerase supply bottlenecks directly into phage display service pricing, compressing margins for German CROs while enabling US-based providers to extract premiums through expedited cell-free synthesis workflows.
Pricing Analysis
Cost-plus contracts indexed to nucleotide raw material benchmarks dominate long-term platform-access agreements between large-cap pharmaceutical developers and specialized antibody library providers. Three-tier pricing structure across premium, standard, and economy levels separates fully human libraries with regulatory-ready documentation from exploratory research-grade collections. Pricing pressure stems from Chinese platform providers compressing discovery timelines through integrated NGS workflows. Biotechnology firms exhibit highest price sensitivity, while oncology-focused large-caps prioritize speed over unit economics.
Supply Chain Analysis
Export-control regimes restricting CRISPR reagent flows from US suppliers to Chinese biotech clusters force Suzhou platform providers to source modified nucleotides through Singaporean intermediaries, elongating procurement cycles. High-fidelity polymerases and synthetic oligonucleotides draw from concentrated manufacturing in the United States, Germany, and Japan. Single-source vulnerability concentrates in Taq polymerase supply from three dominant suppliers. Distribution runs through contract research organization networks rather than direct pharmaceutical procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antibody library technology functions as a service-attach business where recurring platform-access subscriptions and validation support contracts expand faster than one-time library construction fees, creating durable revenue streams for providers who embed into therapeutic discovery pipelines.
For Market Incumbents: Build regulatory documentation moats by pre-validating fully human libraries against FDA breakthrough therapy submission standards before competitor platforms achieve comparable readiness. Incumbents should deepen backward integration into high-fidelity polymerase production to insulate margins from nucleotide cost volatility threatening German and US providers. Cell-free synthesis platforms from Chinese entrants pose substitution risk requiring accelerated NGS integration timelines. For New Entrants and Emerging Players: Establish a beachhead in India's CDSCO emerging biologics pathway where only two domestic display platform providers serve a 200-plus biotech firm population. White-space targets include ribosome display services for academic consortia in Switzerland and the Netherlands, plus cell-free synthesis workflows for Japanese regenerative medicine applications under PMDA conditional approval frameworks. Go-to-market leverage rests on same-day screening-to-sequencing service models. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified life science conglomerates seeking to monetize non-core antibody discovery assets amid portfolio rationalization pressures. Long-term viability favors specialized CROs with proprietary library protocols and multi-year subscription backlogs over project-dependent service providers. Watch for inflection signals in NMPA biologics review acceleration pulling Western providers into Shanghai joint ventures.| Strategic Initiative | Industry Significance |
|---|---|
| Cell-Free Synthesis Integration | Compresses discovery timelines from months to weeks for NMPA-tracked biologics developers. |
| FDA Breakthrough Therapy Pre-Validation | Locks in multi-year subscriptions from San Francisco oncology pipeline sponsors. |
| Yeast Display Capacity Expansion | Captures German CRO demand for complex membrane target developability assessment. |
| Joint Venture Formation in Suzhou | Secures local NMPA pathway access for Western platform providers facing export restrictions. |
| NGS-Linked Single-Cell Sequencing Deployment | Enables bispecific antibody programs for Boston and Basel contract research organizations. |
Research Methodology
Desk research of FDA IND submission databases, EMA MDR guidance documents, and NMPA biologics review circulars preceded structured interviews with antibody discovery executives, regulatory affairs leads at platform providers, CRO procurement directors, and academic core facility managers. Secondary validation drew from ClinicalTrials.gov display technology citations, SEC 10-K filings of publicly traded CROs, and patent landscape analysis of phage display improvement claims. Bottom-up service revenue estimates triangulated against top-down therapeutic antibody pipeline expenditure projections.
Assumptions held fixed include current FDA breakthrough therapy designation eligibility criteria, EMA MDR diagnostic reclassification enforcement timelines, and NMPA biologics review acceleration pace; variables tested across the analysis window encompass cell-free synthesis adoption rates, CRO outsourcing intensity shifts, and nucleotide raw material cost trajectories. Segmentation modeling incorporated technology platform, therapeutic versus diagnostic application, end-user archetype, and regional regulatory cluster dimensions. CAGRs derived from logistic diffusion curves fitted to platform adoption data, with inputs from NIH funding cycles and CEPI pandemic preparedness allocations.
Macroeconomic conditions sit as an overlay; deviation in biotech venture capital availability or freight corridor cost structures would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway stability and polymerase supply concentration. Material shifts in US-Germany-China technology trade policy or FDA adaptive licensing framework expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Global Molecular Biosensors Market
Biomedical Technology
PD L1 Biomarker Testing Market
Biomedical Technology
Cell Isolation Market
Biomedical Technology
Fluoro Enzymatic Assays Market
Biomedical Technology
Human Biobanking Ownership Market
Biomedical Technology
Drug Delivery Technology Market
Biomedical Technology
Global Neuroscience Antibodies and Assays Market
Biomedical Technology
Global Optogenetics Market
Biomedical Technology
Global Immunofluorescence Assay Market
Biomedical Technology
Mammalian Transient Protein Expression Market
Biomedical Technology
Nucleic Acid Aptamers Market
Biomedical Technology
Spine Biologics Market
Biomedical Technology
Cell Proliferation Assay Market
Biomedical Technology
Pyrosequencing Market
Biomedical Technology
Bead-Based Flow Cytometry Market
Biomedical Technology
Needle Based Biopsy Guns Market