
 Hairy Cell Leukemia Market | 2026-2036
Hairy Cell Leukemia Market Size, Share, and Industry Trends Forecast 2026-2036
Hairy Cell Leukemia Market Intelligence
The integration of comprehensive patient support programs is broadening the value proposition beyond the initial drug sale for Hairy Cell Leukemia treatments. Pharmaceutical companies are increasingly bundling drug access with services that assist with reimbursement navigation and adherence. F. Hoffmann-La Roche Ltd leverages its extensive research pipeline to develop novel therapeutic combinations. AbbVie Inc specializes in targeted oncology treatments, securing a significant position in the hematological malignancy space. Meanwhile, Johnson & Johnson utilizes its vast commercial infrastructure to support market access for its specialized medicines.
Hairy cell leukemia is a rare, indolent B-cell lymphoproliferative disorder. The disease is characterized by the accumulation of abnormal lymphocytes with distinctive hair-like projections in the bone marrow, blood, and spleen. The primary goal of therapeutic intervention is to induce durable remissions and manage disease-related symptoms like splenomegaly and cytopenias. Monoclonal antibodies now constitute a critical component of treatment strategies, especially for relapsed cases. Purine analogues, however, continue to be a foundational therapy for most patients with untreated HCL, representing a mature but essential market segment.
The regulatory environment is governed by agencies such as the United States FDA, the European Medicines Agency (EMA), and Japan's Pharmaceuticals and Medical Devices Agency (PMDA). These bodies mandate rigorous clinical trial evidence for new drug approvals, often granting orphan drug designations that provide market exclusivity incentives. Future success for drug developers depends on effectively navigating the distinct reimbursement and evidence requirements across different national healthcare systems for high-cost targeted therapies.
Market Dynamics
The market's central dynamic is the acceleration of targeted therapies, a trend spurred by regulatory frameworks like orphan drug designations. These incentives de-risk investment in rare diseases and encourage the development of novel treatments beyond traditional chemotherapy.
Growth Catalysts
- Orphan Drug Incentives:The U.S. FDA's Orphan Drug Act provides market exclusivity and tax credits, directly stimulating research and development activities for new Hairy Cell Leukemia treatments.
- Advanced Diagnostics:The growing use of flow cytometry and genetic sequencing enables more precise diagnosis and patient stratification, facilitating the appropriate use of targeted therapies.
- Specialized Treatment Centers:The expansion of dedicated oncology and hematology centers improves patient access to complex therapies, clinical trial participation, and expert disease management.
Market Restraints
- High Treatment Cost:The substantial price of novel monoclonal antibodies and targeted agents creates significant reimbursement hurdles and access challenges for healthcare systems and patients.
- Small Patient Population:The inherent rarity of Hairy Cell Leukemia limits the potential market size for any single therapeutic, discouraging R&D investment outside of high-margin orphan drugs.
- Dominance of Purine Analogues:The established efficacy of purine analogues as a first-line therapy creates a high clinical barrier for newer agents to displace them in the treatment-naive setting.
Strategic Opportunities
- Relapsed and Refractory Segment:A significant unmet need exists for effective, well-tolerated treatments for patients who have failed or are intolerant to initial purine analogue therapy.
- Combination Regimens:Investigating the synergistic effects of combining purine analogues with monoclonal antibodies or other targeted agents presents a clear path to improving remission durability.
- European Market Access:Systematically navigating the distinct evidence and reimbursement requirements of national payers within the European Union can unlock new revenue streams for approved therapies.
Industry Challenges
- Clinical Trial Recruitment:The low incidence of HCL makes it operationally difficult to enroll a sufficient number of patients for robust clinical trials, delaying drug development timelines for regulatory bodies.
- Payer Evidence Demands:Health technology assessment bodies across different countries require extensive real-world evidence of long-term efficacy, a significant data-generation challenge for rare disease therapies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hairy Cell Leukemia Market |
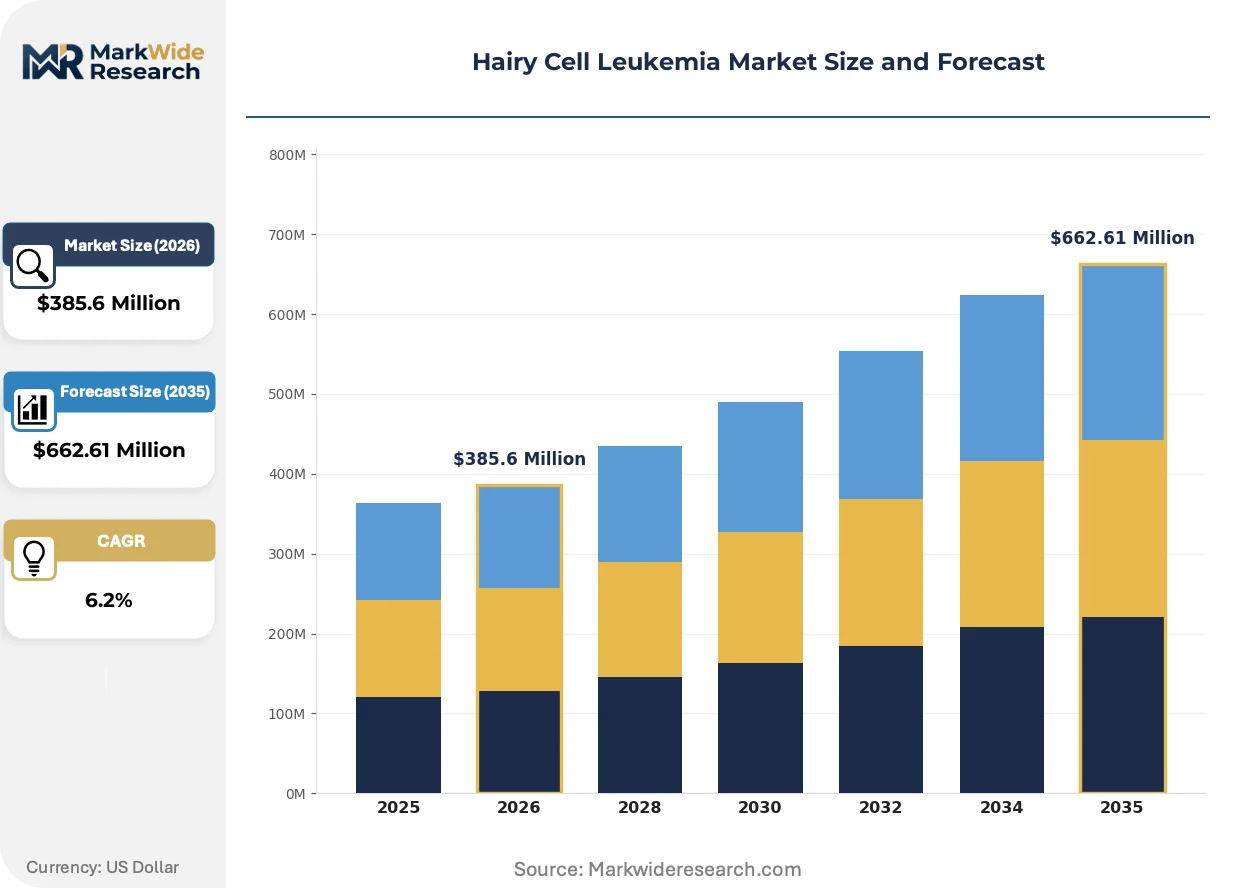
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $662.61 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Purine Analogues, Chemotherapy Agents, Targeted Therapy, Immunotherapy Therapy Area: Relapsed/Refractory HCL, Untreated HCL, Minimal Residual Disease, Secondary HCL End User: Oncology Centers, Hematology Clinics, Research Institutes, Specialty Hospitals Delivery Mode: Intravenous, Subcutaneous, Oral, Intramuscular, Transdermal |
| Companies Covered | Gilead Sciences, Merck & Co Inc, AstraZeneca PLC, AbbVie Inc, Pfizer Inc, F. Hoffmann-La Roche Ltd, Astellas Pharma, Johnson & Johnson, Amgen Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hairy Cell Leukemia Market Strategic Shifts & Innovations
A fundamental shift is underway from broad cytotoxic agents toward precision medicine. This evolution is driven by a deeper understanding of HCL's molecular biology, enabling more tailored and effective interventions that improve patient outcomes while managing toxicity.
BRAF inhibitors represent a key targeted therapy class, designed to block the activity of the mutated BRAF V600E protein found in many HCL cases. Specialized oncologists are increasingly adopting these agents for patients with confirmed mutations, often in the relapsed setting. This kinase inhibition approach is converging with immunotherapy, creating novel strategies for combination treatments that target distinct oncogenic pathways.
The European Medicines Agency's orphan medicinal product designation provides powerful incentives for HCL drug development. This framework offers protocol assistance, reduced fees, and a decade of market exclusivity post-approval, mitigating the financial risks of developing drugs for small patient populations. Consequently, biopharmaceutical firms targeting hematological malignancies prioritize clinical trial designs that meet EMA criteria to secure these benefits.
Pharmaceutical commercial models are evolving beyond the simple sale of a drug to include integrated patient support services. This model disrupts traditional distribution by bundling reimbursement navigation, financial assistance, and adherence programs with the core therapeutic product. This shift is most pronounced in the United States, where navigating the complex payer landscape is a critical factor for ensuring patient access to high-cost specialty medicines.
Hairy Cell Leukemia Market Segmentation
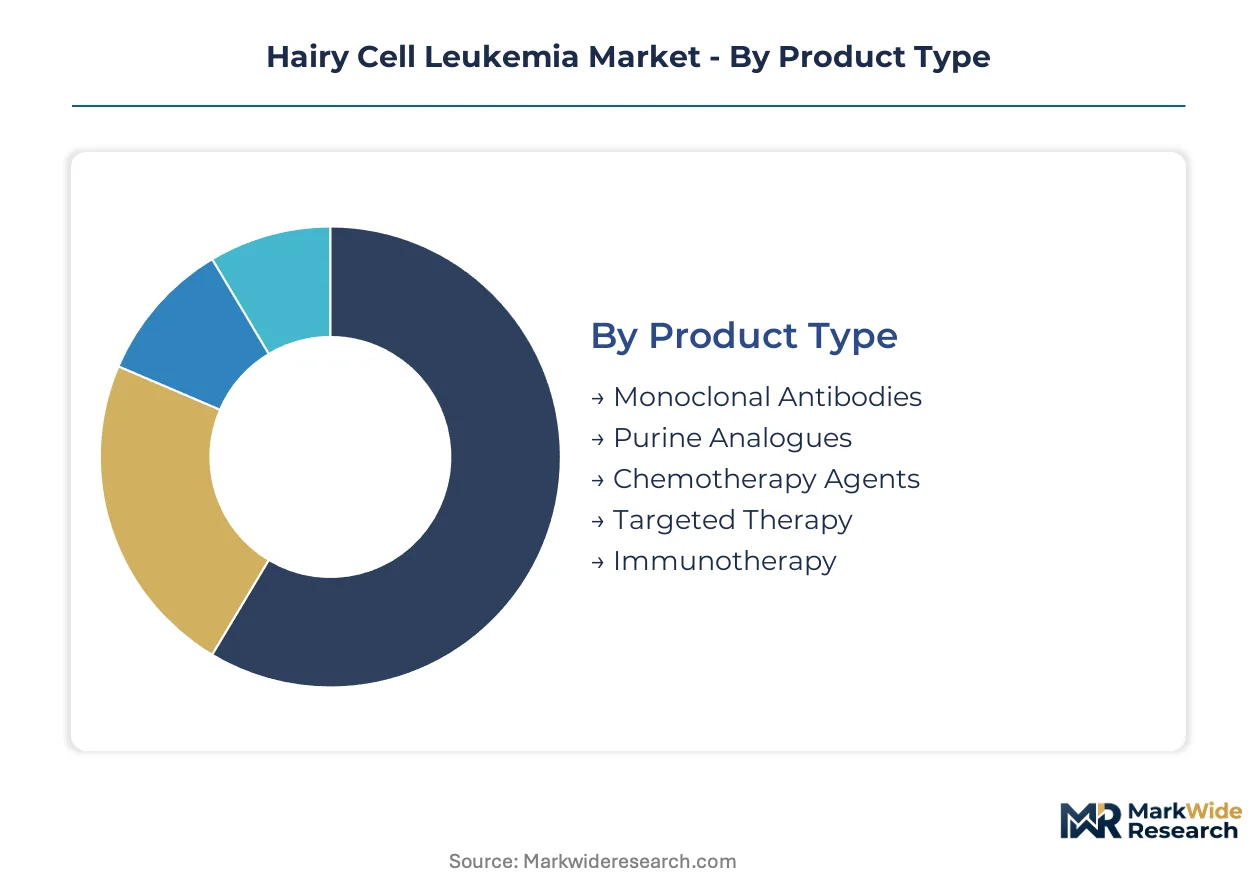
Understanding the Hairy Cell Leukemia market through segmentation reveals the diverse therapeutic approaches and specialized care pathways for patients. This granular analysis highlights where innovation is concentrated and how different treatment modalities serve distinct patient populations and clinical needs.
Product Type:
Navigating the Hairy Cell Leukemia product landscape requires understanding the varying regulatory certification burdens for each therapeutic class.
- Monoclonal Antibodies:These biologic agents selectively target specific cell surface proteins on HCL cells, minimizing off-target effects. Demand for these highly specific treatments is concentrating in the United States, driven by robust clinical trial activities and favorable reimbursement policies.
- Targeted Therapy:This class includes small molecule inhibitors that block specific molecular pathways, such as BRAF V600E mutations, crucial for HCL cell proliferation. European market access for these innovative therapies depends on navigating distinct evidence and reimbursement requirements across national healthcare systems.
- Purine Analogues:These antimetabolite drugs, like cladribine and pentostatin, remain foundational first-line therapy for most HCL patients due to their established efficacy.
- Chemotherapy Agents:Traditional cytotoxic chemotherapy agents are occasionally used in HCL, particularly in cases resistant to other treatments, though their role is diminishing.
- Immunotherapy:Novel immunotherapeutic approaches, beyond monoclonal antibodies, are under investigation to harness the body's immune system against HCL cells.
Monoclonal Antibodies sits at the top of the volume ranking, with Targeted Therapy climbing the fastest.
Therapy Area:
Differentiation across therapy areas reflects distinct patient needs and disease progression stages within Hairy Cell Leukemia.
- Relapsed/Refractory HCL:This segment addresses patients whose disease has returned or not responded to initial treatments, representing a significant unmet medical need. Pharmaceutical companies are focusing research and development efforts here, particularly for novel combination regimens.
- Untreated HCL:This category includes newly diagnosed patients who have not yet received therapeutic intervention, where purine analogues remain a foundational therapy. Market stability in this segment relies on the established efficacy and long-term safety profiles of conventional agents.
- Minimal Residual Disease:This area focuses on detecting and treating very low levels of HCL cells after initial therapy, aiming to prevent disease recurrence.
- Secondary HCL:This rare sub-segment involves HCL developing after treatment for another hematological malignancy, presenting unique diagnostic and therapeutic challenges.
Relapsed/Refractory HCL demonstrates the most significant unmet need, while Untreated HCL maintains a stable patient base.
End User:
The distribution of Hairy Cell Leukemia treatments flows through specialized healthcare facilities equipped for complex oncological care.
- Oncology Centers:These large, multidisciplinary facilities provide comprehensive cancer care, including diagnosis, treatment, and follow-up for HCL patients. They represent the primary point of access for advanced targeted therapies and clinical trial participation.
- Hematology Clinics:Specialized clinics focus specifically on blood disorders, offering expert diagnosis and management of HCL, often serving as referral centers. These clinics often manage outpatient treatment regimens and long-term disease monitoring.
- Research Institutes:These institutions are crucial for advancing HCL understanding and developing new therapies through basic science and clinical investigations.
- Specialty Hospitals:Hospitals with specialized departments cater to complex medical conditions, including HCL, providing inpatient care for severe cases or specific procedures.
Oncology Centers process the largest volume of complex HCL cases, with Hematology Clinics providing essential specialized care.
Delivery Mode:
Patient convenience and clinical efficacy dictate the preferred delivery modes for Hairy Cell Leukemia therapies.
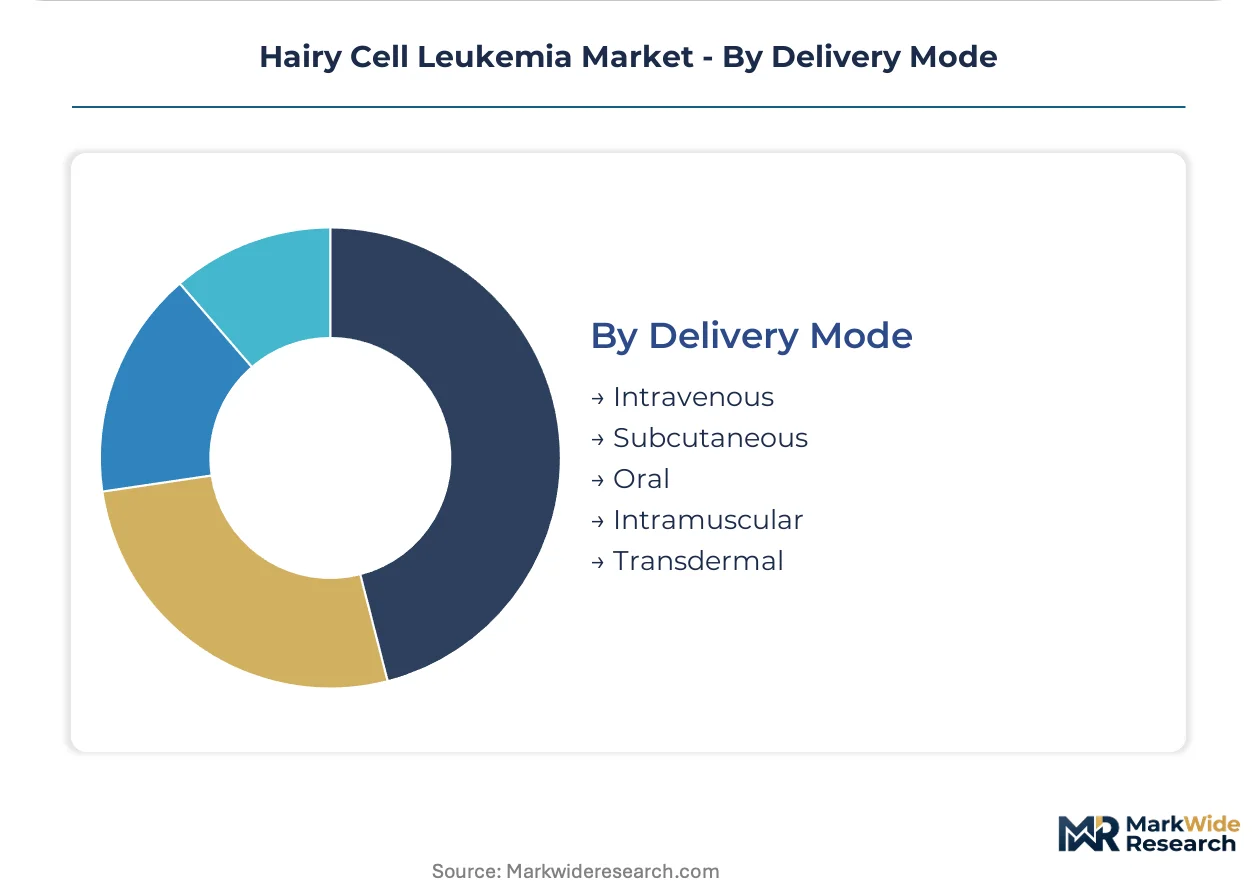
- Intravenous:This mode involves administering drugs directly into the bloodstream, ensuring rapid and complete bioavailability, particularly for monoclonal antibodies and chemotherapy agents. It remains the standard for many high-dose or immediate-action HCL treatments in specialized settings.
- Oral:Oral formulations offer significant patient convenience for long-term maintenance therapies, reducing the need for frequent clinic visits. The development of new oral targeted therapies is expanding patient adherence and quality of life.
- Subcutaneous:Subcutaneous injections provide an alternative to intravenous administration for some biologic agents, allowing for easier outpatient or home administration.
- Intramuscular:Intramuscular injections are less common for HCL treatments but may be used for certain supportive care medications.
- Transdermal:Transdermal delivery, through patches, is generally not applicable for current HCL therapies due to the nature of the active pharmaceutical ingredients.
Intravenous administration continues as the dominant delivery method, while oral options are gaining patient preference for convenience.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States market demonstrates robust demand for novel Hairy Cell Leukemia treatments, driven by significant clinical research, while Germany focuses on specialized oncology centers and European market access strategies. Both nations prioritize advanced therapeutic options, though their regulatory and reimbursement landscapes differ. This creates distinct pathways for drug developers to navigate.
United States
Demand for HCL therapies in the United States is spurred by advanced diagnostic capabilities and the rapid adoption of targeted therapy options. The U.S. FDA's Orphan Drug Act provides crucial market exclusivity incentives, stimulating research and development. The Boston-Cambridge biotech hub remains a critical center for clinical trials and pharmaceutical innovation in oncology.
Germany
Germany's HCL market benefits from a strong network of specialized oncology centers and a focus on high-quality patient care. The European Medicines Agency (EMA) plays a central role in drug approvals, while national health technology assessment bodies evaluate new therapies. Pharmaceutical research clusters in cities like Munich and Berlin contribute significantly to therapeutic advancements.
Japan
Japan exhibits a steady demand for high-cost targeted therapies, influenced by an aging population and a sophisticated healthcare system. The Pharmaceuticals and Medical Devices Agency (PMDA) rigorously evaluates new drug candidates for safety and efficacy. Major pharmaceutical companies in Tokyo and Osaka drive innovation in hematological malignancies.
United Kingdom
Clinical research participation and a well-established healthcare infrastructure underpin the HCL treatment landscape in the United Kingdom. The Medicines and Healthcare products Regulatory Agency (MHRA) oversees drug approvals, alongside the National Institute for Health and Care Excellence (NICE) for reimbursement recommendations. London and Cambridge host significant biotech and academic medical centers focused on rare diseases.
China
China's HCL market is expanding due to increasing healthcare access and substantial investment in oncology research and treatment. The National Medical Products Administration (NMPA) regulates drug approvals, with a growing focus on innovative therapies for unmet needs. Major pharmaceutical manufacturing and R&D activities are concentrated in Shanghai and Beijing.
Hairy Cell Leukemia Market Key Industry Players
Top-tier vendors anchor the Hairy Cell Leukemia market, while smaller biopharmaceutical firms introduce niche innovations. The market structure exhibits consolidation, with established players leveraging extensive research pipelines. Strategic archetypes include large pharmaceutical conglomerates, specialized oncology biotechs, and generic drug manufacturers. Companies engage in portfolio diversification and strategic partnerships to strengthen their market presence.
Among established pharmaceutical companies, F. Hoffmann-La Roche Ltd exemplifies a research-driven approach, leveraging its extensive pipeline to develop novel therapeutic combinations for HCL. AbbVie Inc. occupies a significant position within the hematological malignancy space, specializing in targeted oncology treatments. Johnson & Johnson represents a global pharmaceutical entity, utilizing its vast commercial infrastructure to support market access for specialized medicines across various regions. These entities anchor the high-value segment, focusing on advanced therapies and integrated patient support programs.
| Leading Market Players |
|---|
| Gilead Sciences |
| Merck & Co Inc |
| AstraZeneca PLC |
| AbbVie Inc |
| Pfizer Inc |
| F. Hoffmann-La Roche Ltd |
| Astellas Pharma |
| Johnson & Johnson |
| Amgen Inc |
| Others |
Cost & Logistics Intelligence
The distinct regulatory pathways for orphan drugs versus established generics create a significant divergence in both pricing power and supply chain complexity for Hairy Cell Leukemia treatments. This bifurcation influences manufacturing scale and distribution networks across key markets.
Pricing Analysis
Capacity additions in specialized biopharmaceutical manufacturing hubs are reshaping price floors for complex HCL therapies. The dominant pricing model for novel agents is value-based, reflecting clinical efficacy and improved patient outcomes. Price differentiation stems from specific regulatory approval status, like orphan drug designation, and the level of integrated patient support services. Pricing pressure intensifies for purine analogues due to their mature market status, making patients with untreated HCL more price sensitive than those seeking relapsed/refractory treatments.
Supply Chain Analysis
Workforce availability in key biopharmaceutical manufacturing geographies like the United States, Europe, and India significantly influences the HCL drug supply chain. Production of complex monoclonal antibodies and targeted therapy APIs primarily draws from facilities in the United States and Germany, creating dependencies on specialized active pharmaceutical ingredients and specific excipients. Single-source vulnerability for certain rare disease APIs represents a structural risk, impacting supply continuity. Distribution runs through specialized pharmaceutical distributors directly serving oncology centers and hematology clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Hairy Cell Leukemia market functions as a regulatory compounder, with the U.S. FDA's Orphan Drug Act significantly driving demand for novel therapeutic development. This incentive framework fosters investment in rare disease treatments.
For Market Incumbents: Hedge against the threat of emerging biosimilars by continuously investing in next-generation targeted therapies and novel combination regimens. Incumbents should also reinforce their market presence through strategic partnerships with specialized oncology centers to control distribution channels. Deepening vertical integration into specialized API manufacturing can mitigate supply chain vulnerabilities. This strategy defends against margin pressure from generic purine analogues.
For New Entrants and Emerging Players: Specialized oncology distributors represent a key channel partner type for new entrants to penetrate the HCL market. Focus on the relapsed/refractory HCL segment, which presents a significant unmet medical need and lower clinical barriers to entry for novel agents. A go-to-market angle involves demonstrating superior tolerability profiles for targeted therapies. The European market, with its distinct reimbursement requirements, offers white-space opportunities for agile biotechs.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized oncology biotechs possessing advanced clinical pipelines for HCL. Long-term viability hinges on successful navigation of complex regulatory pathways and securing orphan drug designations for novel compounds. Acquisition targets should be companies with late-stage assets addressing unmet needs in relapsed/refractory HCL. A signal to watch is the successful completion of Phase 3 trials for combination regimens.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates regulatory approval processes for novel HCL therapies. |
| Regulatory Approval Pathway | Secures market exclusivity and premium pricing for orphan drugs. |
| Licensing Agreement | Expands product portfolios and geographic reach for specialized treatments. |
| Manufacturing Scale-Up | Ensures consistent supply of complex biologics and targeted agents. |
| Pipeline Diversification | Reduces reliance on single therapeutic classes within hematological malignancies. |
Research Approach
Direct dialogue with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists provided critical qualitative insights. This primary research was rigorously combined with secondary validation from sources like FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. A robust bottom-up and top-down triangulation approach ensured data consistency and accuracy.
A bottom-up analytical framework, validated by top-down market sizing, underpinned the Hairy Cell Leukemia market forecast across the analysis window. Segmentation dimensions modeled included product type, therapy area, end user, delivery mode, and regional regulatory clusters. Compound Annual Growth Rates were derived from historical trends and projected market dynamics, incorporating patient incidence rates and regulatory approval timelines as key inputs.
Revisions become necessary when unexpected clinical trial failures or major healthcare policy shifts materialize. Forecasts reflect assumptions documented at the time of publication, acknowledging inherent market uncertainties. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Chronic Granulomatous Disease Market
Rare Diseases
Europe Rett Syndrome Market
Rare Diseases
Skeletal Dysplasia Market
Rare Diseases
Alzheimer Disease Market
Rare Diseases
Pompe Disease Market
Rare Diseases
Aicardi Syndrome Market
Rare Diseases
Menkes Syndrome Market
Rare Diseases
Byler Disease Market
Rare Diseases
Andersen-Tawil Syndrome Market
Rare Diseases
Fragile X Syndrome Market
Rare Diseases
Rare Inflammatory Disease Treatment Market
Rare Diseases
Niemann Pick Disease Market
Rare Diseases
Global Hemoglobinopathies Market
Rare Diseases
Methylmalonic Acidemia Market
Rare Diseases
Metachromatic Leukodystrophy Market
Rare Diseases
Hemophagocytic Lymphohistiocytosis Market