
 Hutchinson-Gilford Progeria Syndrome Market | 2026-2036
Hutchinson-Gilford Progeria Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Hutchinson-Gilford Progeria Syndrome Market Insights
Capital-intensity divergence between gene therapy platforms and small-molecule developers is rotating competitive investment toward biologics manufacturing infrastructure. Eiger BioPharmaceuticals leverages its rare disease regulatory experience to anchor clinical development timelines. Pfizer sustains broad therapeutic portfolio diversification while competing in orphan indications through established pediatric networks. Novartis differentiates via integrated cell and gene therapy manufacturing capabilities that occupy a narrow but critical supply position.
Hutchinson-Gilford Progeria Syndrome constitutes an ultra-rare autosomal dominant genetic disorder driven by LMNA gene mutations producing progerin, a toxic lamin A variant that destabilizes nuclear architecture and accelerates cellular senescence. The condition's primary commercial purpose centers on developing disease-modifying therapies that extend survival beyond the typical mid-teens life expectancy. Gene therapy segments attract concentrated R&D investment due to their potential for durable correction of the underlying LMNA defect, while small molecule drug categories maintain near-term revenue visibility through more predictable regulatory pathways. Antisense oligonucleotides represent an emerging structural opportunity where delivery technology maturation could reshape competitive positioning.
The FDA orphan drug program and EMA's rare disease designation framework jointly shape trial design incentives and extended market exclusivity timelines for developers in this space. Pediatric Research Equity Act requirements and international harmonization through ICH E11 guidelines further constrain formulation and dosing strategies to age-appropriate standards. Stakeholders must monitor biomarker validation progress and payer willingness to absorb gene therapy pricing for ultra-small patient cohorts.

Market Dynamics
Gene therapy manufacturing scale-up is compressing clinical development timelines for Hutchinson-Gilford Progeria Syndrome while small-molecule programs compete for near-term regulatory priority. This tension between platform investment horizons defines current capital allocation across the competitive landscape.
Growth Catalysts
- FDA Orphan Drug Designation:The framework accelerates trial initiation and extends market exclusivity timelines for developers targeting ultra-rare indications with fewer than 200,000 patients.
- Pediatric Research Equity Act:Mandated pediatric study requirements create dedicated funding streams and trial infrastructure that directly benefit progeria drug development programs.
- Antisense Oligonucleotide Delivery:Advances in lipid nanoparticle chemistry and conjugation chemistry are opening new therapeutic modalities for nuclear envelope disorders previously considered undruggable.
Market Restraints
- Patient Cohort Miniscule:The global prevalence of approximately 400 diagnosed cases fragments revenue potential and complicates payer negotiation leverage for any single therapy.
- Gene Therapy Manufacturing Concentration:Contract development and manufacturing organizations with viral vector capability cluster in Massachusetts and North Carolina, creating geographic supply risk.
- Biomarker Validation Gaps:The absence of surrogate endpoints accepted by both FDA and EMA forces reliance on hard clinical outcomes that extend trial duration.
Strategic Opportunities
- Japan's Sakigake Designation:Japan's PMDA priority review pathway offers accelerated approval for regenerative medicines and gene therapies, creating an early commercialization foothold in Asia-Pacific.
- Convergent Gene Editing:The intersection of base editing and in vivo delivery vectors could enable permanent LMNA correction without the immunogenicity risks of viral approaches.
- Academic Medical Center Networks:Specialized progeria clinics at Boston Children's Hospital and the National Institutes of Health are evolving into integrated trial sites with embedded patient registries.
Industry Challenges
- Gene Therapy Talent Scarcity:The specialized skill set combining viral vector process development and regulatory strategy concentrates at a handful of institutions and contract manufacturers.
- Multi-Year Certification Timelines:Current Good Manufacturing Practice validation for patient-specific autologous therapies requires 18-24 months of facility qualification before commercial release.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hutchinson-Gilford Progeria Syndrome Market |
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $227.22 Million |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gene Therapy, Small Molecule Drugs, Protein Inhibitors, Antisense Oligonucleotides Therapy Area: Genetic Disorders, Rare Diseases, Premature Aging, Cardiovascular Complications End User: Specialized Clinics, Pediatric Institutes, Genetic Research Centers, Clinical Trial Organizations Delivery Mode: Intravenous, Oral, Subcutaneous, Inhalation |
| Companies Covered | Eiger BioPharmaceuticals, The Progeria Research Foundation, PRG Science & Technology, Pfizer, Novartis, Amgen, Sarepta Therapeutics, REGENXBIO, Ultragenyx Pharmaceutical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hutchinson-Gilford Progeria Syndrome Market Trends and Innovations
Antisense oligonucleotide platforms are gaining traction as intermediate-term therapeutic options while gene therapy developers resolve manufacturing bottlenecks. This dual-track innovation pattern is reshaping competitive timelines and partnership structures across the development ecosystem.
Antisense oligonucleotide chemistry is bifurcating between gapmer architectures for nuclear retention and splice-switching designs for exon skipping. Pediatric progeria clinics in the United States and Europe are prioritizing these programs for near-term patient access. The technology is enabling sponsors to generate proof-of-concept data while awaiting viral vector manufacturing capacity expansion.
EMA's PRIME designation and FDA's Breakthrough Therapy pathway are converging on harmonized evidentiary standards for ultra-rare diseases. Developers now face parallel but increasingly aligned requirements for natural history data and biomarker qualification across both jurisdictions. Gene therapy sponsors targeting Hutchinson-Gilford Progeria Syndrome are responding by establishing transatlantic trial protocols with unified endpoints.
Patient advocacy organizations are consolidating procurement influence through centralized referral networks and registry-controlled trial access. The Progeria Research Foundation maintains exclusive relationships with diagnosed families worldwide, effectively gatekeeping clinical recruitment. This channel concentration is most visible in the United States, where foundation-directed care protocols determine which therapeutic candidates reach pivotal study enrollment targets.
Hutchinson-Gilford Progeria Syndrome Market Segmentation
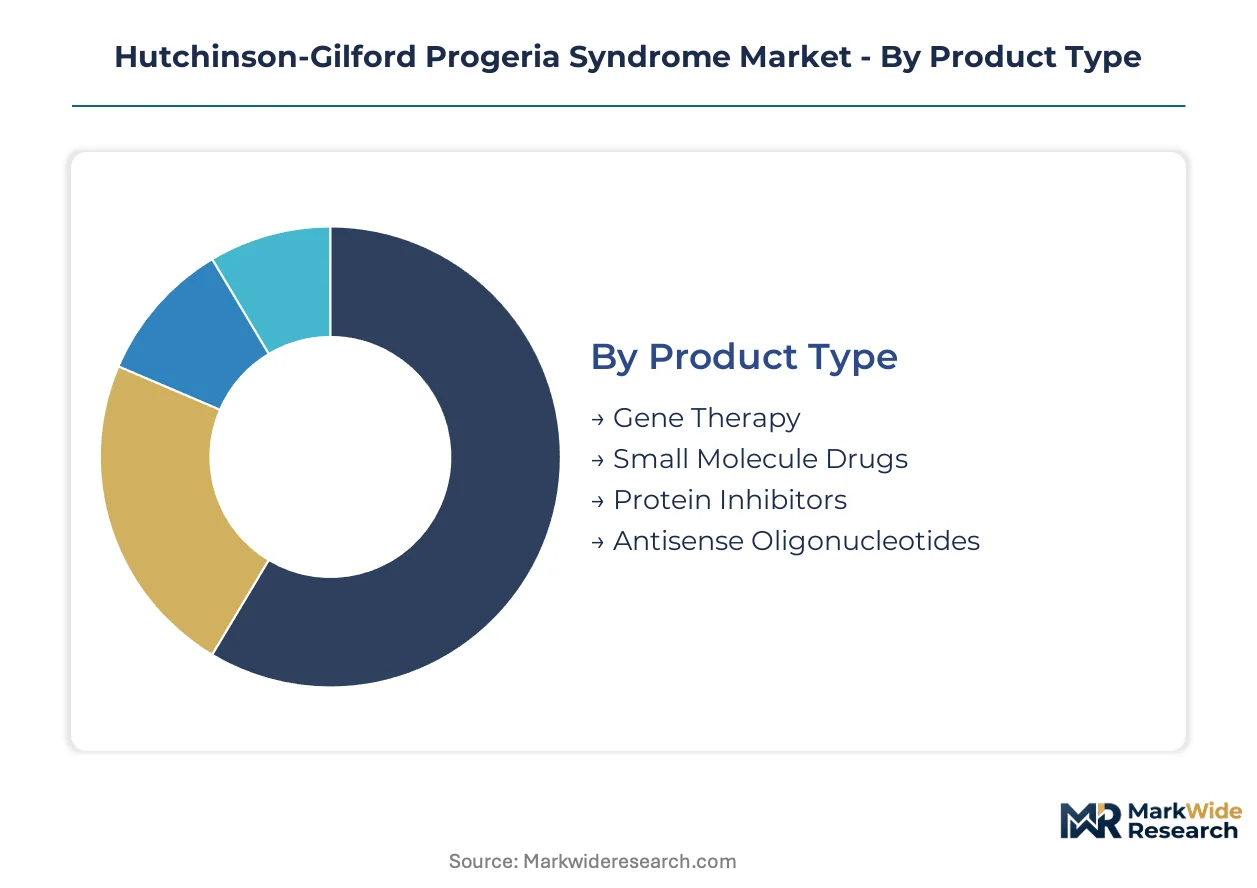
Segmentation in the Hutchinson-Gilford Progeria Syndrome market reveals how ultra-rare disease economics concentrate investment around platform technologies with scalable manufacturing potential. Each dimension—product type, therapy area, end user, and delivery mode—carries distinct margin profiles and regulatory pathway implications that shape developer prioritization.
Product Type:
Gene therapy platforms command premium valuation multiples due to their curative potential, while small-molecule developers compete on speed-to-market certainty.
- Gene Therapy:Viral vector-based LMNA correction delivers durable nuclear envelope restoration through single-administration protocols. Manufacturing scale-up at Massachusetts and North Carolina CDMO clusters is compressing clinical timelines for Boston Children's Hospital and NIH-affiliated trial sites.
- Small Molecule Drugs:Farnesyltransferase inhibitors and related compounds target progerin processing with established oral bioavailability. Near-term revenue visibility attracts capital from sponsors seeking predictable FDA orphan drug exclusivity timelines.
- Protein Inhibitors:Direct progerin-neutralizing biologics require parenteral administration but offer mechanistic precision.
- Antisense Oligonucleotides:Splice-switching gapmers represent an intermediate-risk modality with lipid nanoparticle delivery maturation.
Gene therapy holds installed capacity. Antisense oligonucleotides are rotating up the share rankings.
Therapy Area:
Cardiovascular complication management absorbs the largest share of palliative spending, while genetic disorder correction attracts transformative R&D allocation.
- Genetic Disorders:LMNA mutation correction addresses root nuclear architecture instability through permanent genomic intervention. FDA Breakthrough Therapy and EMA PRIME designations are converging on unified evidentiary standards for sponsors pursuing this category.
- Rare Diseases:Orphan drug economics with patient populations below 400 diagnosed cases globally necessitate pricing models that absorb manufacturing fixed costs across minimal volume bases.
- Premature Aging:Senescence pathway modulation offers mechanistic insights applicable beyond progeria to broader geroscience indications.
- Cardiovascular Complications:Atherosclerosis and stroke prevention dominate near-term clinical endpoints and payer reimbursement negotiations.
Cardiovascular complications hold installed capacity. Genetic disorders are climbing the fastest in developer pipeline priority.
End User:
Pediatric institutes anchor procurement concentration through foundation-directed referral networks, while specialized clinics control trial site certification.
- Specialized Clinics:Boston Children's Hospital and NIH Clinical Center operate integrated progeria programs with embedded patient registries and natural history databases that gatekeep pivotal study access.
- Pediatric Institutes:The Progeria Research Foundation's exclusive family relationships concentrate treatment-seeking behavior at designated centers in the United States and Europe.
- Genetic Research Centers:Academic laboratories at Johns Hopkins and University of Pennsylvania drive biomarker validation and surrogate endpoint development.
- Clinical Trial Organizations:Pediatric Research Equity Act-mandated study infrastructure creates dedicated funding streams for ultra-rare indication execution.
Pediatric institutes hold installed capacity. Specialized clinics are gaining share fastest through vertical integration into patient identification.
Delivery Mode:
Intravenous administration dominates gene therapy deployment, while oral routes sustain small-molecule commercial viability.
- Intravenous:Viral vector infusion enables liver-targeted LMNA transgene expression with systemic progerin reduction. Massachusetts-based manufacturing clusters supply vector batches for transatlantic trial protocols.
- Oral:Farnesyltransferase inhibitors maintain patient compliance advantages for chronic administration in pediatric populations.
- Subcutaneous:Antisense oligonucleotide depot formulations are emerging through lipid nanoparticle chemistry advances.
- Inhalation:Pulmonary delivery remains exploratory for vascular-targeted progerin reduction.
Intravenous holds installed capacity. Subcutaneous is expanding most quickly through formulation technology maturation.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Patient recruitment protocols and regulatory incentive structures diverge sharply between the United States and other markets, with specialized clinic density and orphan drug designation frameworks driving differential access patterns for ultra-rare disease therapies.
United States
Boston Children's Hospital and the NIH Clinical Center anchor specialized progeria care networks that gatekeep clinical trial enrollment. The FDA's orphan drug designation framework accelerates review timelines and extends market exclusivity for developers. Massachusetts-based viral vector manufacturing clusters supply gene therapy batches for transatlantic protocols.
Germany
Heidelberg University Hospital and Charité Berlin operate integrated pediatric genetics programs with natural history registry capabilities. EMA's PRIME designation pathway offers accelerated assessment for gene therapies targeting ultra-rare indications. Bavarian CDMO infrastructure supports viral vector process development for European trial sites.
United Kingdom
Great Ormond Street Hospital maintains dedicated laminopathy referral pathways that concentrate diagnosed patients. The MHRA's Innovative Licensing and Access Pathway aligns with FDA breakthrough standards for pediatric rare diseases. London-Oxford-Cambridge biotech clusters host antisense oligonucleotide chemistry development.
Japan
Tokyo Medical and Dental University and Osaka University Hospital coordinate national patient identification through the Japanese Progeria Network. PMDA's Sakigake designation prioritizes regenerative medicine and gene therapy reviews for early commercialization. Kanto-region manufacturing partnerships with US vector suppliers are expanding.
Switzerland
University Hospital Zurich and Geneva University Hospital anchor French-German cross-border patient flows for specialized progeria consultations. Swissmedic's pediatric investigational plan requirements align with ICH E11 harmonized standards. Basel-area biologics manufacturing infrastructure supports protein inhibitor development programs.
Hutchinson-Gilford Progeria Syndrome Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in this ultra-rare disease space. Large-cap pharmaceutical developers with established pediatric rare disease networks compete against mid-cap gene therapy platforms and dedicated biotechnology specialists. Two strategic archetypes dominate: diversified rare disease portfolio builders and single-asset gene therapy developers. Competitive moves concentrate on regulatory exclusivity capture through orphan drug designation and manufacturing capacity reservation at qualified viral vector facilities.
Within the diversified pharmaceutical tier, Pfizer and Novartis exemplify platform breadth strategies that leverage existing pediatric networks for ultra-rare indication access. Eiger BioPharmaceuticals occupies a specialist position representing regulatory experience concentration in rare disease development pathways. These three entities anchor the competitive structure without exclusive territorial claims, as the miniscule patient cohort necessitates collaborative trial site sharing and foundation-mediated referral coordination.
| Leading Market Players |
|---|
| Eiger BioPharmaceuticals |
| The Progeria Research Foundation |
| PRG Science & Technology |
| Pfizer |
| Novartis |
| Amgen |
| Sarepta Therapeutics |
| REGENXBIO |
| Ultragenyx Pharmaceutical |
| Others |
Pricing and Supply Chain Analysis
Viral vector manufacturing scale economies at Massachusetts and North Carolina CDMO clusters compress per-dose cost floors for gene therapy developers while simultaneously concentrating supply-side bargaining power among a handful of qualified facilities. This dual compression shapes pricing trajectories across both curative and chronic administration modalities in Hutchinson-Gilford Progeria Syndrome.
Pricing Analysis
Post-treatment monitoring and long-term follow-up contracts generate lifetime value that exceeds initial administration revenue for gene therapy sponsors. Pricing stratifies across premium single-administration protocols, standard antisense oligonucleotide regimens, and economy small-molecule maintenance tiers. Cost compression in small-molecule categories intensifies as farnesyltransferase inhibitors face generic erosion pressures. Pediatric institutes demonstrate lowest price sensitivity due to foundation-directed procurement, while European hospital systems exhibit highest sensitivity to budget impact thresholds.
Supply Chain Analysis
Massachusetts-based viral vector production capacity functions as the primary chokepoint for LMNA-targeting gene therapies, with batch release timelines determining clinical trial initiation schedules. Manufacturing draws from US and Swiss biologics infrastructure, with lipid nanoparticle chemistry inputs sourced from specialized German and Japanese suppliers. Single-source vulnerability concentrates at fill-finish operations for patient-specific autologous products. Distribution runs through foundation-coordinated referral networks that gatekeep patient access to qualified treatment centers.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power in this market consolidates through the Progeria Research Foundation's exclusive patient registry relationships, which concentrate treatment-seeking behavior at designated pediatric institutes and specialized clinics. This channel control restructures procurement leverage toward foundation-directed care protocols.
For Market Incumbents: Fortify regulatory exclusivity positions through accelerated FDA Breakthrough Therapy and EMA PRIME designation capture before rival sponsors establish natural history data partnerships. Secure captive supply agreements at Massachusetts viral vector CDMOs to defend against emerging antisense oligonucleotide competitors seeking manufacturing capacity. Prioritize biomarker validation investments that could shorten pivotal trial duration and extend effective patent protection windows. For New Entrants and Emerging Players: Differentiate on splice-switching gapmer chemistry platforms that bypass current viral vector manufacturing bottlenecks while gene therapy sponsors resolve scale-up constraints. Target Japan's Sakigake designation pathway for early Asia-Pacific commercialization footholds before US market saturation. Pursue academic medical center licensing arrangements that embed novel delivery technologies within established progeria clinic networks at Boston Children's Hospital and NIH sites. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors antisense oligonucleotide platforms with near-term revenue visibility over gene therapy developers facing 18-24 month cGMP qualification timelines. Long-term viability rests on permanent genomic correction modalities that eliminate chronic administration burdens. Acquisition targets should demonstrate exclusive foundation relationships or proprietary lipid nanoparticle delivery IP. Watch for FDA acceptance of progerin reduction as a surrogate endpoint as the critical inflection signal for platform valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Capture | FDA exclusivity extension secures revenue protection for ultra-rare indication developers against late entrants. |
| Viral Vector Manufacturing Scale-Up | Massachusetts CDMO capacity expansion compresses clinical trial initiation timelines for gene therapy sponsors. |
| Biomarker Validation Consortium | Academic partnerships with Johns Hopkins and University of Pennsylvania accelerate surrogate endpoint qualification. |
| Foundation Registry Integration | Progeria Research Foundation data partnerships gatekeep pivotal study enrollment and natural history benchmarks. |
| Antisense Chemistry Platform Development | Lipid nanoparticle delivery maturation enables intermediate-term therapeutic options during gene therapy manufacturing constraints. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA orphan drug filings, EMA PRIME designation records, ClinicalTrials.gov protocols, and foundation-published natural history databases. Primary inputs drew from regulatory affairs leads at gene therapy developers, pediatric institute procurement directors, viral vector manufacturing executives, and payer access specialists at US and European health technology assessment bodies. Bottom-up patient cohort sizing and top-down revenue potential triangulation validated segment-level estimates across the analysis window.
Segmentation dimensions modeled include product type, therapy area, end user category, and delivery mode, with cross-tabulation against regional regulatory clusters. CAGRs derived from epidemiological prevalence projections, treatment penetration assumptions, and pricing trajectory analysis for each modality. Forecast inputs incorporated biomarker validation timelines, manufacturing capacity expansion schedules, and foundation-directed referral network evolution.
Material uncertainties — regulatory rejection of proposed surrogate endpoints, viral vector manufacturing batch failures, foundation partnership exclusivity shifts — sit outside the modeled envelope. Forecasts reflect stated assumptions regarding FDA and EMA harmonization progress and payer willingness to absorb gene therapy pricing for sub-400 patient populations. Practitioners should keep alternative scenarios live as evidentiary standards for ultra-rare disease approval evolve across jurisdictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Fragile X Syndrome Market
Rare Diseases
Sanfilippo Syndrome Market
Rare Diseases
Behcets Disease Market
Rare Diseases
Europe Down Syndrome Market
Rare Diseases
Dystrophic Epidermolysis Bullosa Management Market
Rare Diseases
Zellweger Spectrum Disorders Market
Rare Diseases
Andersen-Tawil Syndrome Market
Rare Diseases
Parry-Romberg Syndrome Market
Rare Diseases
Erdheim-Chester Disease Market
Rare Diseases
Rare Disease Clinical Trials Market
Rare Diseases
Global Tyrosine Hydroxylase Deficiency Market
Rare Diseases
Rosai-Dorfman Disease (RDD) Therapeutics Market
Rare Diseases
Pompe Disease Market
Rare Diseases
Global Gaucher Disease Market
Rare Diseases
Atypical Hemolytic Uremic Syndrome (Ahus) Treatment Market
Rare Diseases
Chronic Granulomatous Disease Market