
 Kounis Syndrome Market | 2026-2036
Kounis Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Kounis Syndrome Market Foresight
The EU Green Deal's healthcare decarbonization targets are decoupling procurement criteria from pure cost metrics in European hospital systems. Johnson & Johnson leverages its interventional cardiology portfolio to anchor allergy-triggered cardiac event protocols. Sanofi S.A. differentiates through antihistamine and epinephrine combinations that address mast cell-mediated coronary vasospasm. Pfizer Inc. competes on manufacturing scale for acute coronary syndrome therapeutics with rapid-response formulations.
Kounis syndrome denotes acute coronary events triggered by allergic or hypersensitivity reactions, including mast cell degranulation releasing histamine, leukotrienes, and platelet-activating factor that induce coronary artery spasm or plaque rupture; diagnostic confirmation requires elevated serum tryptase alongside cardiac troponins and electrocardiographic ischemic changes. Medications dominate current revenue as beta-blockers and antihistamines form first-line acute management, while Diagnostic Tools represent the fastest-expanding segment due to multiplex allergy-immunoassay integration into emergency workflows. Emergency Care Units capture disproportionate margin pools given the time-critical nature of distinguishing Type I from Type II Kounis presentations.
The FDA's post-market surveillance requirements for combination drug-device products shape development timelines for emergency auto-injectors with cardiac monitoring features, while EMA's MDR implementation demands enhanced clinical evidence for diagnostic platforms used in acute settings. Japan's PMDA accelerates reviews for devices addressing anaphylaxis-cardiology overlap conditions under its Sakigake priority review framework. Stakeholders must monitor regulatory divergence between FDA 510(k) pathways and EU MDR Class III designation rules for integrated diagnostic-therapeutic systems.
Market Dynamics
The diagnostic-therapeutic boundary in emergency cardiology is dissolving as multiplex immunoassay platforms integrate with acute coronary syndrome protocols, forcing device manufacturers and pharmaceutical suppliers to coordinate development cycles around combined regulatory submissions rather than sequential approvals.
Growth Catalysts
- Emergency Department Protocol Harmonization:Tertiary hospitals in the United States, Germany, and Japan are standardizing tryptase-troponin dual-testing pathways. This institutional adoption creates pull-through demand for integrated diagnostic systems.
- EU MDR Implementation:The Medical Device Regulation's enhanced clinical evidence requirements for Class III devices is accelerating investment in prospective registry data collection. Manufacturers building these datasets now capture preferential positioning in European procurement.
- Mast Cell Biology Advances:Improved understanding of histamine receptor subtypes in coronary vasospasm is expanding addressable patient populations. Research institutions are translating this mechanistic insight into targeted therapeutic development programs.
Market Restraints
- Serum Tryptase Assay Cost Volatility:Reagent supply concentration among three specialized diagnostic manufacturers creates input price instability. Hospital laboratories face margin compression when contract renegotiations coincide with volume spikes.
- Regulatory Divergence Friction:FDA's 510(k) pathway for diagnostic-therapeutic combinations operates on substantially different evidentiary standards than EU MDR Class III designation. Developers must maintain parallel submission strategies that extend time-to-market.
- Epinephrine Auto-Injector Substitution:Generic emergency anaphylaxis devices commoditize the acute response segment. Differentiation requires costly cardiac monitoring feature integration that many purchasers decline to fund.
Strategic Opportunities
- Underpenetrated Japanese Emergency Networks:PMDA's Sakigake priority review framework for anaphylaxis-cardiology overlap conditions remains underutilized. Early entrants capture accelerated pathway benefits before competitor saturation.
- Allergy-Cardiology Convergence:Multiplex platforms combining specific IgE profiling with high-sensitivity troponin detection represent unclaimed white space. Technology holders can define category standards before incumbent diagnostic players pivot.
- EU Green Deal Procurement Tailwinds:Healthcare decarbonization targets are rewriting European hospital purchasing criteria. Suppliers with verified lifecycle emissions data access decision-maker attention previously reserved for lowest-cost bidders.
Industry Challenges
- Cross-Disciplinary Talent Scarcity:Clinical specialists fluent in both mast cell immunology and interventional cardiology remain exceptionally rare. Recruitment competition intensifies as academic medical centers expand dedicated Kounis syndrome units.
- Legacy EHR Integration Complexity:Emergency department information systems require substantial customization to accommodate dual-pathway diagnostic workflows. Implementation timelines frequently exceed contractual delivery commitments.
- CE-IVD to IVDR Transition Certification Bottlenecks:Diagnostic platform recertification under the In Vitro Diagnostic Regulation is consuming technical resources that would otherwise support product line extensions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kounis Syndrome Market |
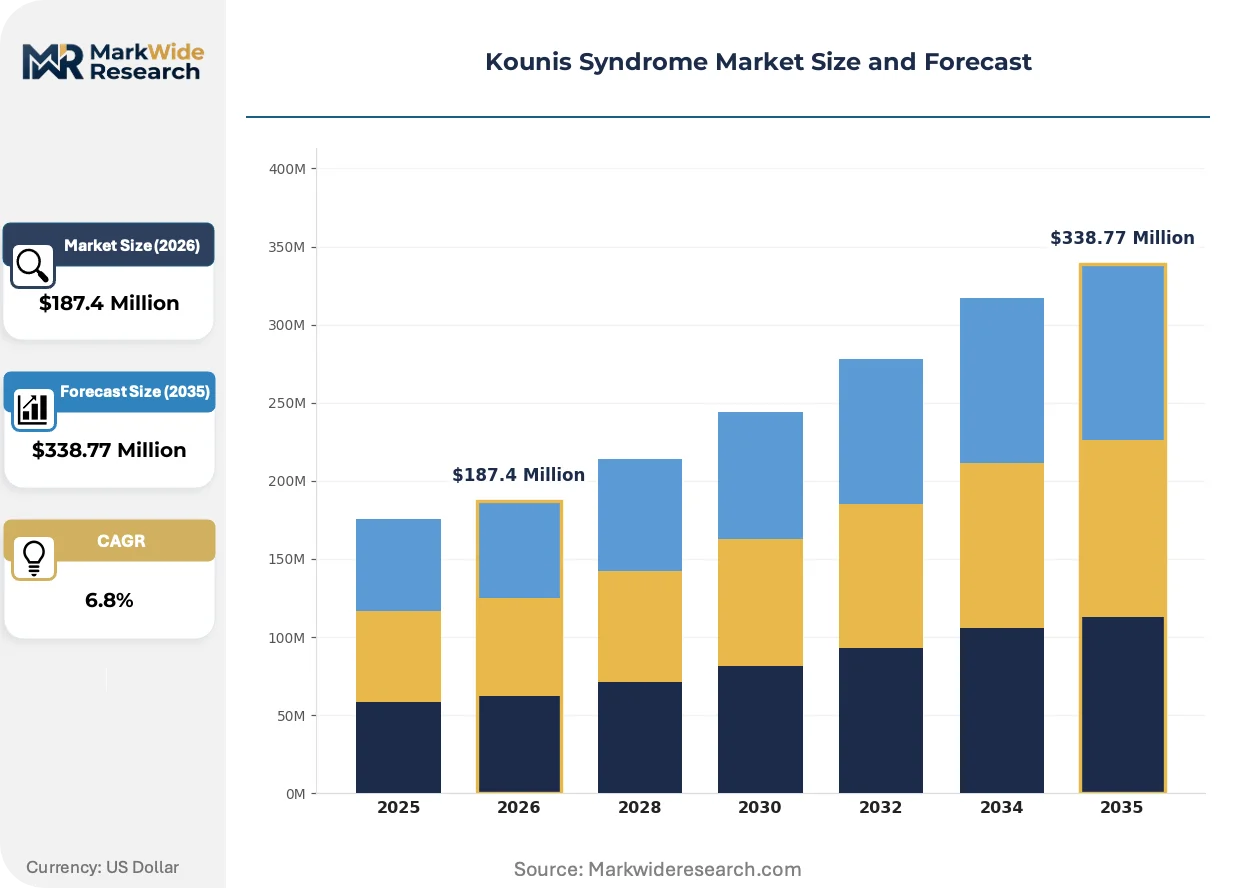
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Diagnostic Tools, Medical Devices, Treatment Kits End User: Hospitals, Clinics, Laboratories, Emergency Care Units Delivery Mode: Oral, Injectable, Intravenous, Topical Service Type: Outpatient Care, Inpatient Care, Telehealth Services, Preventive Care |
| Companies Covered | Johnson & Johnson, Sanofi S.A., Roche, AstraZeneca plc, GlaxoSmithKline plc, Novartis AG, Merck & Co., Inc., Bristol-Myers Squibb Company, Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kounis Syndrome Market Shifts & Advancements
Point-of-care biosensor platforms are compressing the diagnostic window for allergic myocardial ischemia from laboratory turnaround times to bedside minutes, restructuring emergency department resource allocation and specialist consultation patterns.
Multiplex allergy-immunoassay technology is converging with portable electrocardiographic monitoring systems. Emergency medicine departments in tertiary hospitals are deploying these integrated platforms to distinguish Type I from Type II Kounis presentations without cardiology consultation delays. The structural consequence is a compression of diagnostic decision timelines that previously required serial testing across separate laboratory and cardiology workflows.
Japan's PMDA has operationalized its Sakigake priority review framework for devices addressing anaphylaxis-cardiology overlap conditions. This regulatory pathway compresses premarket review timelines for qualifying submissions by approximately fifty percent compared to standard device approvals. Manufacturers with Japanese emergency care partnerships are restructuring development priorities to access this accelerated channel, redirecting clinical trial investment toward Japanese sites.
Hospital procurement committees are unbundling after-sales service contracts from diagnostic platform purchases. German university hospitals pioneered this separation, negotiating standalone service agreements with third-party technical specialists rather than captive manufacturer teams. This behavioral shift is most visible in European markets where EU Green Deal transparency requirements expose total cost of ownership disparities between integrated and disaggregated supply arrangements.
Kounis Syndrome Market Segmentation
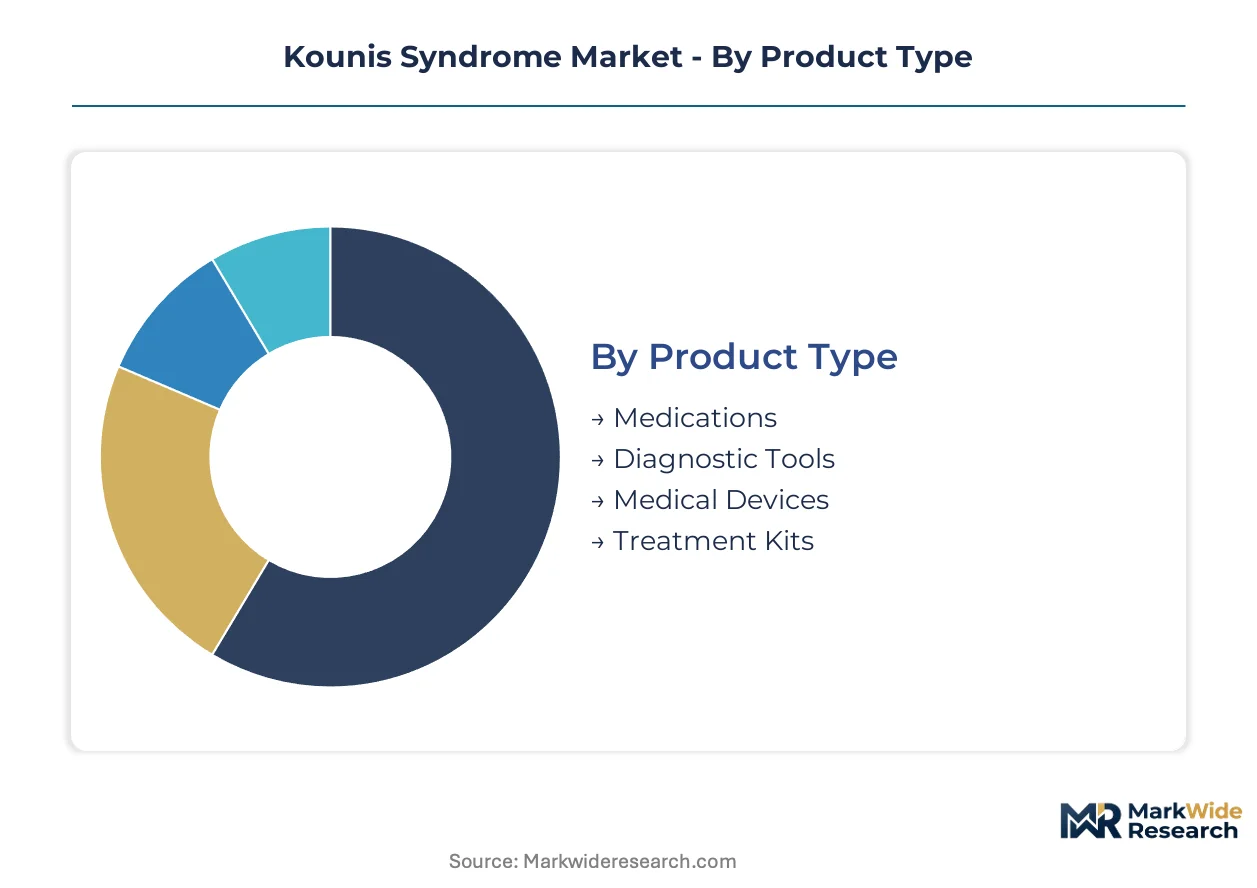
Kounis syndrome management requires precise matching of diagnostic and therapeutic modalities to acute presentation types. Segmentation reveals where standard protocols dominate versus where customized emergency workflows command premium positioning.
Product Type:
Standardization prevails in acute therapeutics while diagnostic platforms fragment across customization tiers.
- Medications:Beta-blockers, antihistamines, and epinephrine formulations constitute first-line acute management. Demand concentrates in tertiary hospital emergency departments across the United States, Germany, and Japan where anaphylaxis-related acute coronary syndrome registries are most developed. Reagent supply concentration among specialized manufacturers creates input price instability.
- Diagnostic Tools:Multiplex allergy-immunoassay platforms integrate with emergency workflows to detect elevated serum tryptase alongside cardiac troponins. Point-of-care biosensor deployment is compressing diagnostic windows from laboratory turnaround times to bedside minutes in tertiary hospitals.
- Medical Devices:Implantable cardiac devices and emergency auto-injectors with cardiac monitoring features face tightening EU MDR post-market surveillance requirements.
- Treatment Kits:Pre-configured emergency response bundles standardize acute protocol execution for emergency care units.
Leading the category by volume: Medications. Growing fastest: Diagnostic Tools.
End User:
Margin concentration tracks acuity intensity and protocol complexity across facility types.
- Hospitals:Cardiology departments in tertiary institutions anchor allergy-cardiology crossover protocol expansion. EU Green Deal healthcare decarbonization targets are decoupling procurement criteria from pure cost metrics in European hospital systems.
- Emergency Care Units:Capture disproportionate margin pools given time-critical presentation differentiation between Type I and Type II Kounis syndrome. Emergency department information systems require substantial customization to accommodate dual-pathway diagnostic workflows.
- Clinics:Outpatient allergy specialists serve as referral gatekeepers for suspected mast cell-mediated coronary events.
- Laboratories:Hospital laboratories face margin compression when serum tryptase assay contract renegotiations coincide with volume spikes.
Highest margin capture: Emergency Care Units. Fastest workflow transformation: Hospitals.
Delivery Mode:
Speed-to-effectiveness determines adoption hierarchy in acute settings.
- Intravenous:Routes of administration for beta-blockers and antihistamines in acute coronary event management. Emergency department protocols favor IV delivery for rapid hemodynamic stabilization.
- Injectable:Epinephrine auto-injectors for immediate mast cell-mediated response interruption. Generic device substitution pressures commoditize this segment without cardiac monitoring feature integration.
- Oral:Maintenance antihistamine regimens post-acute stabilization.
- Topical:Adjunctive administration for localized allergic manifestations.
Dominant acute protocol share: Intravenous. Feature differentiation battleground: Injectable.
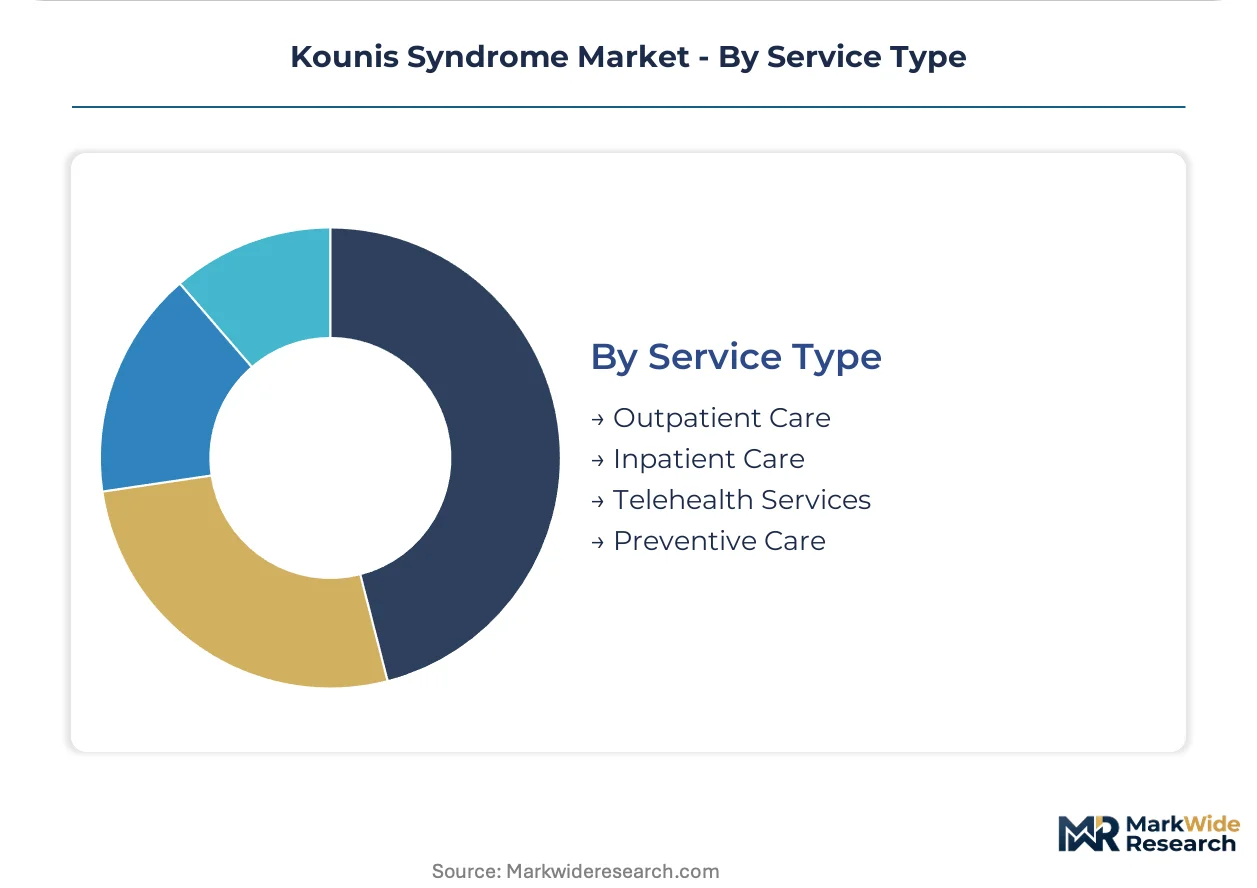
Service Type:
Revenue stability inversely correlates with episode acuity across care continuums.
- Inpatient Care:Comprehensive monitoring for Type II Kounis presentations with plaque rupture requiring interventional cardiology consultation. Academic medical centers are expanding dedicated Kounis syndrome units.
- Outpatient Care:Follow-up allergist-cardiologist co-management for stabilized patients. Mast cell biology advances are expanding addressable patient populations for targeted therapeutic development programs.
- Telehealth Services:Remote consultation platforms for emergency department diagnostic support.
- Preventive Care:Specific IgE profiling to identify trigger avoidance strategies.
Largest revenue base: Inpatient Care. Expanding most quickly: Telehealth Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic platform production clusters in Germany and Japan while consumption concentrates in tertiary hospital networks across the United States. Supply chains for serum tryptase reagents and multiplex immunoassay systems remain concentrated among specialized manufacturers in these three markets.
United States
Emergency department protocol harmonization drives demand for integrated tryptase-troponin dual-testing systems. FDA post-market surveillance requirements for combination drug-device products shape development timelines for emergency auto-injectors with cardiac monitoring features. Tertiary hospitals in Boston and New York anchor allergy-cardiology crossover protocol expansion.
Germany
University hospitals pioneer unbundling of after-sales service contracts from diagnostic platform purchases. EU MDR implementation demands enhanced clinical evidence for Class III diagnostic platforms used in acute settings. The Rhine-Ruhr and Baden-Württemberg clusters concentrate multiplex allergy-immunoassay manufacturing capacity.
Japan
PMDA's Sakigake priority review framework accelerates device approvals for anaphylaxis-cardiology overlap conditions by approximately fifty percent. Japanese emergency networks remain underpenetrated relative to regulatory pathway availability. Tokyo and Osaka academic medical centers expand dedicated Kounis syndrome units.
United Kingdom
NHS procurement committees integrate EU Green Deal healthcare decarbonization targets into hospital system purchasing criteria. MHRA operates transitional recognition arrangements for EU-authorized diagnostic platforms post-Brexit. London and Manchester tertiary institutions lead emergency department information system customization for dual-pathway workflows.
Switzerland
Swissmedic maintains alignment with EU MDR standards while offering streamlined pathways for innovative diagnostic-therapeutic combinations. Basel and Zurich clusters concentrate mast cell biology research translation into targeted therapeutic development. Swiss university hospitals serve as referral hubs for complex Type II Kounis presentations requiring interventional cardiology consultation.
Kounis Syndrome Market Competitive Landscape
The competitive structure tilts toward diversified pharmaceutical conglomerates with emergency medicine portfolios. Three to five integrated healthcare conglomerates dominate acute therapeutic supply while specialized diagnostic manufacturers fragment across multiplex immunoassay niches. Strategic archetypes include emergency medicine generalists, mast cell biology specialists, and point-of-care platform integrators. Portfolio diversification and regulatory pathway optimization constitute the dominant competitive moves.
Among diversified healthcare conglomerates, Johnson & Johnson and Sanofi S.A. exemplify the emergency medicine generalist archetype through interventional cardiology and anaphylaxis response portfolios respectively. Pfizer Inc. occupies a position within the scale-driven acute coronary syndrome therapeutics tier. These three companies anchor different vectors of the allergy-cardiology convergence space without overlapping specialization.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Sanofi S.A. |
| Roche |
| AstraZeneca plc |
| GlaxoSmithKline plc |
| Novartis AG |
| Merck & Co., Inc. |
| Bristol-Myers Squibb Company |
| Pfizer Inc. |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between Class III EU MDR devices and standard 510(k) diagnostics splits pricing power along regulatory investment lines, with premium-tier manufacturers commanding 40-60% markups over commodity assay suppliers while absorbing parallel submission costs across divergent evidentiary standards.
Pricing Analysis
Cost-down pressure on emergency auto-injectors accelerates because generic substitution erodes cardiac monitoring feature premiums. Three-tier pricing structure across premium, standard, and economy levels separates integrated diagnostic-therapeutic systems from standalone tryptase assays and commodity epinephrine devices. Price differentiation hinges on EU MDR Class III certification status and after-sales service bundling. Hospital laboratories exhibit highest price sensitivity due to reagent contract volatility, while emergency care units prioritize rapid turnaround over unit economics.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and the United States coordinate hub-and-spoke delivery of multiplex immunoassay platforms to tertiary hospital networks. Manufacturing concentrates among specialized diagnostic reagent producers in the Rhine-Ruhr cluster and Osaka prefecture. Raw material dependencies include monoclonal antibodies, high-sensitivity troponin reagents, and biosensor substrates. Single-source vulnerability in serum tryptase assay supply creates procurement risk for hospital laboratories. Distribution runs through manufacturer-direct channels and third-party technical service specialists in European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory divergence friction is forcing subscale diagnostic manufacturers toward exit or acquisition, consolidating competitive position around conglomerates with parallel FDA-EMA submission capabilities.
For Market Incumbents: Deploy backward integration into monoclonal antibody production to secure reagent supply against contract volatility. Capture preferential EU procurement positioning by building prospective registry datasets ahead of MDR clinical evidence requirements. Generic epinephrine substitution and IVDR transition certification bottlenecks threaten margin sustainability without captive supply chains. For New Entrants and Emerging Players: Telehealth-enabled emergency department diagnostic support represents the most penetrable white space, with Japanese Sakigake pathway access offering accelerated regulatory positioning. Target underpenetrated Japanese emergency networks before competitor saturation. Pursue hospital system partnerships for dual-pathway workflow customization rather than direct platform sales. For Investors and Strategic Acquirers: Exit pathways concentrate in diversified healthcare conglomerates seeking mast cell biology specialization. Long-term viability favors targets with integrated allergy-cardiology protocol development capabilities and established Japanese regulatory relationships. Watch PMDA Sakigake qualification rates as inflection indicator for accelerated pathway utility.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Class III Certification Investment | Unlocks premium procurement positioning in German and UK hospital systems under enhanced clinical evidence requirements. |
| PMDA Sakigake Pathway Qualification | Compresses premarket review timelines for anaphylaxis-cardiology devices in Japanese emergency networks. |
| Multiplex Platform-Hospital EHR Integration | Reduces implementation timeline risk for dual-pathway diagnostic workflows in tertiary emergency departments. |
| Third-Party Service Contract Unbundling | Aligns with German university hospital procurement separation of technical service from platform purchase. |
| Monoclonal Antibody Supply Captive Integration | Insulates against reagent price volatility from concentrated specialized diagnostic manufacturers. |
Research Methodology
FDA 510(k) filings, EMA MDR submission databases, and ClinicalTrials.gov records formed the secondary backbone, cross-referenced against primary interviews with emergency department directors, hospital procurement managers, biomedical engineers, and regulatory affairs leads specializing in combination drug-device products. Bottom-up triangulation across device approval timelines and top-down validation through tertiary hospital protocol adoption rates anchored segmentation modeling.
Historical trendline analysis of diagnostic platform deployment tracked institutional adoption curves across the analysis window. Segmentation dimensions included product type, end-user facility acuity tier, delivery mode, and regional regulatory cluster. CAGRs derived from weighted average of equipment replacement cycles and protocol harmonization penetration rates. Forecast inputs incorporated PMDA Sakigake qualification velocity and EU Green Deal procurement criteria implementation timelines.
The model holds under stable regulatory divergence conditions; deviation in FDA-EMA evidentiary standard convergence or IVDR transition deadline extensions would shift competitive positioning timelines. Forecasts reflect documented assumptions around emergency department information system upgrade budgets and mast cell biology research translation rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Von Hippel-Lindau Market
Rare Diseases
Spina Bifida Market
Rare Diseases
Orphan Diseases Market
Rare Diseases
Dystrophic Epidermolysis Bullosa Management Market
Rare Diseases
Hemophagocytic Lymphohistiocytosis Market
Rare Diseases
Middle East and Africa Down Syndrome Market
Rare Diseases
Aarskog Scott Syndrome Treatment Market
Rare Diseases
Niemann-Pick Disease Type C Therapeutics Market
Rare Diseases
Fabry Disease Market
Rare Diseases
Creutzfeldt-Jakob Disease (CJD) Market
Rare Diseases
Dystrophic Epidermolysis Bullosa Treatment Market
Rare Diseases
Turner Syndrome Market
Rare Diseases
Chaple Syndrome Market
Rare Diseases
Global Gaucher Disease Market
Rare Diseases
Dravet Syndrome Market
Rare Diseases
Erdheim-Chester Disease Market