
 Neuromyelitis Optica Market | 2026-2036
Neuromyelitis Optica Market Size, Share, and Industry Trends Forecast 2026-2036
Neuromyelitis Optica Market Outlook
Aftermarket patient support programs is reconfiguring how manufacturers capture lifetime value per neuromyelitis optica patient. Hoffmann-La Roche anchors its position through integrated diagnostic-to-treatment platforms that reduce time to therapy initiation. Alexion Pharmaceuticals differentiates via deep specialization in complement inhibition for autoimmune neurological indications. TG Therapeutics competes through aggressive development of B-cell targeting mechanisms with broader autoimmune applicability.
Neuromyelitis optica is an autoimmune astrocytopathy characterized by pathogenic immunoglobulin G antibodies against aquaporin-4 water channels, producing inflammatory demyelination of the optic nerves and spinal cord with diagnostic reliance on cell-based serum assays and MRI lesion patterns. Monoclonal antibodies command the dominant margin pool as first-line maintenance therapy, while immunotherapies represent the fastest-growing category as novel B-cell and complement pathway inhibitors expand the treatable patient population. Intravenous delivery dominates acute phase intervention, though subcutaneous formulations are gaining traction in maintenance settings where patient convenience drives adherence.
FDA orphan drug exclusivity provisions and EMA's priority medicines scheme have shaped development incentives, accelerating biologic approvals for small patient populations while imposing stringent post-market safety surveillance obligations. The EU AI Act and evolving FDA guidance on real-world evidence are reshaping how manufacturers demonstrate long-term efficacy for chronic immunosuppressive regimens. Stakeholders must monitor how Health Technology Assessment bodies in Germany, France, and England evaluate cost-effectiveness thresholds for combination biologic protocols versus sequential monotherapy approaches.
Market Dynamics
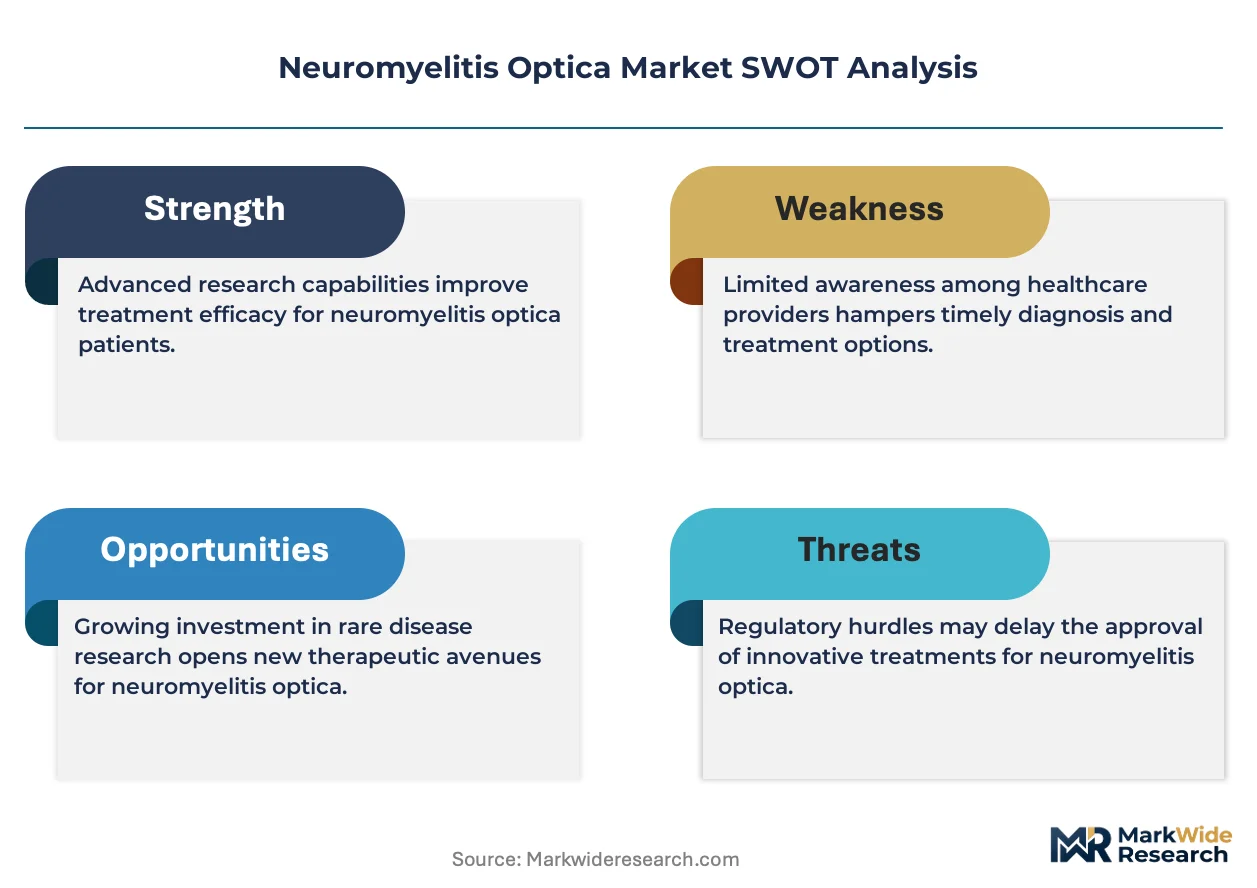
Orphan drug incentives from FDA and EMA are compressing development timelines for aquaporin-4 targeted biologics, reshaping competitive entry patterns and pricing power distribution among manufacturers.
Growth Catalysts
- EMA Priority Medicines Scheme:Accelerated assessment pathways reduce time-to-market for complement inhibitors and B-cell depleting agents in European markets.
- Cell-Based Assay Diffusion:Diagnostic laboratories in the United States, Germany, and Japan are expanding serum testing capacity, shortening time from symptom onset to definitive diagnosis.
- Specialty Clinic Networks:Tertiary neurology centers are establishing dedicated neuroimmune service lines with integrated infusion capabilities.
Market Restraints
- Plasma-Derived Input Volatility:Immunoglobulin supply constraints and fractionation capacity limitations create batch-to-batch availability uncertainty for acute rescue therapy.
- Biologic Cold Chain Concentration:Maintenance monoclonal antibodies require uninterrupted temperature-controlled distribution, with logistics infrastructure concentrated in metropolitan hospital clusters.
- Diagnostic Assay Complexity:Cell-based aquaporin-4 antibody testing demands specialized laboratory infrastructure unavailable in secondary care settings, creating geographic access gaps.
Strategic Opportunities
- Subcutaneous Formulation Migration:Self-administered maintenance dosing reduces infusion center burden and expands treatable population beyond urban hospital catchments.
- Real-World Evidence Frameworks:FDA guidance on electronic health record-derived efficacy data enables label expansion for chronic immunosuppressive regimens without prospective trial requirements.
- Pediatric Indication White Space:Current approvals concentrate in adult populations, with mechanistic rationale supporting development in adolescent neuroimmune presentations.
Industry Challenges
- Neuroimmunology Specialist Scarcity:Fellowship-trained clinicians capable of distinguishing neuromyelitis optica from multiple sclerosis remain concentrated in academic medical centers.
- Post-Market Surveillance Infrastructure:Long-term safety monitoring for chronic B-cell depletion requires registry participation and pharmacovigilance investment exceeding standard autoimmune indications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neuromyelitis Optica Market |
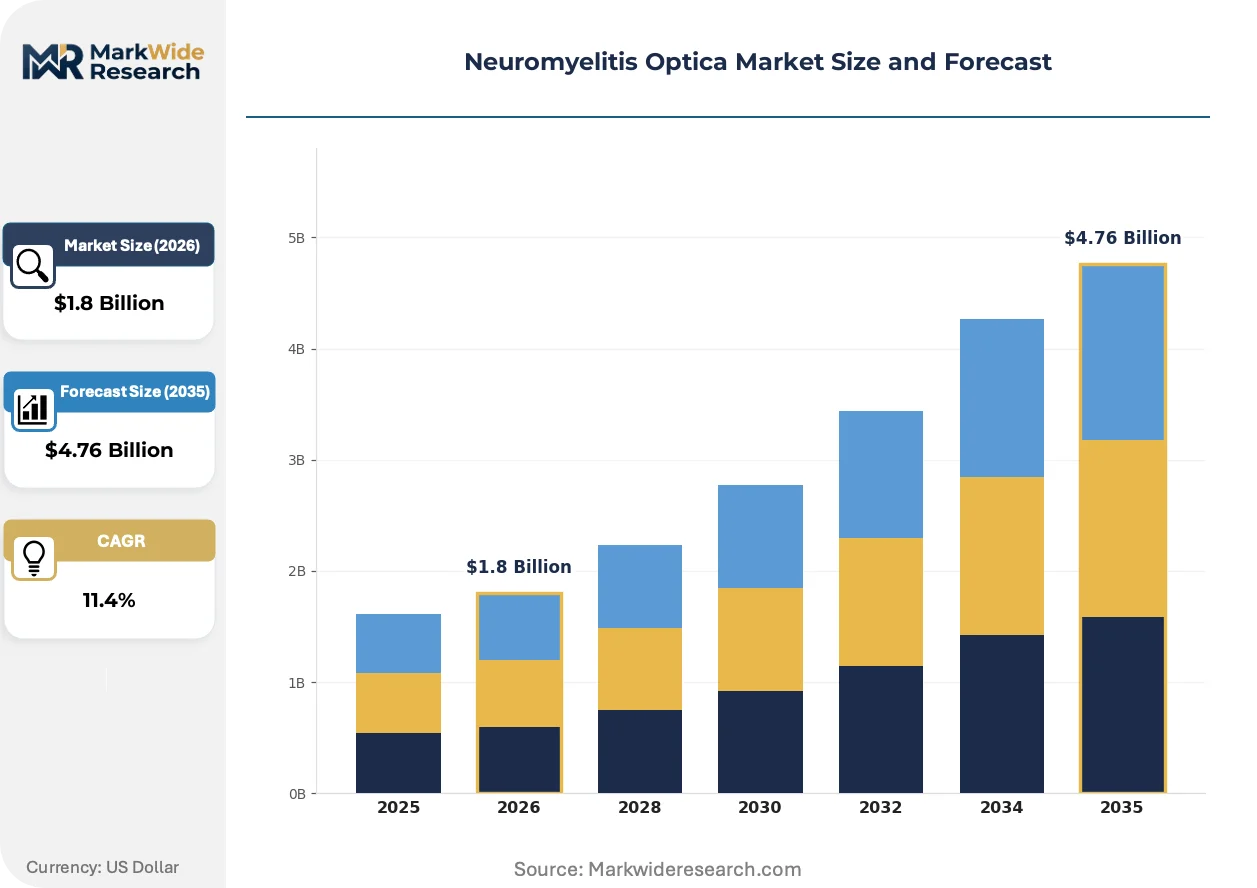
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Immunotherapies, Corticosteroids, Plasma Exchange End User: Hospitals, Research Institutes, Specialty Clinics, Home Care Settings Delivery Mode: Intravenous, Subcutaneous, Oral, Intramuscular Treatment Phase: Acute Phase, Maintenance Therapy, Relapse Prevention, Long-term Management |
| Companies Covered | AstraZeneca, TG Therapeutics, Alexion Pharmaceuticals, Teva Pharmaceutical Industries, Opexa Therapeutics, Horizon Therapeutics, Mitsubishi Tanabe Pharma, RemeGen, Hoffmann-La Roche, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neuromyelitis Optica Market Strategic Shifts
Treatment protocols are pivoting from episodic acute management toward continuous maintenance suppression, with diagnostic and therapeutic modalities converging around patient stratification by antibody status and lesion topography.
Subcutaneous monoclonal antibody delivery systems are virtualizing the maintenance phase care model. Patients with stable disease are adopting home administration platforms with remote nursing support. This shift is virtualizing infusion center capacity constraints and redistributing value capture toward device and adherence service providers.
The EU AI Act's risk classification framework for clinical decision support is reshaping diagnostic software deployment. Algorithm-assisted MRI lesion interpretation tools face heightened conformity assessment requirements. German and French radiology departments are prioritizing CE-marked solutions with embedded explainability features for aquaporin-4 seronegative case identification.
Integrated diagnostic-to-treatment platforms are compressing referral pathway friction. Health systems in the United States are contracting with manufacturers for bundled testing and first-line biologic access. This procurement consolidation concentrates volume with platforms demonstrating shortest time from antibody confirmation to therapy initiation.
Neuromyelitis Optica Market Segmentation
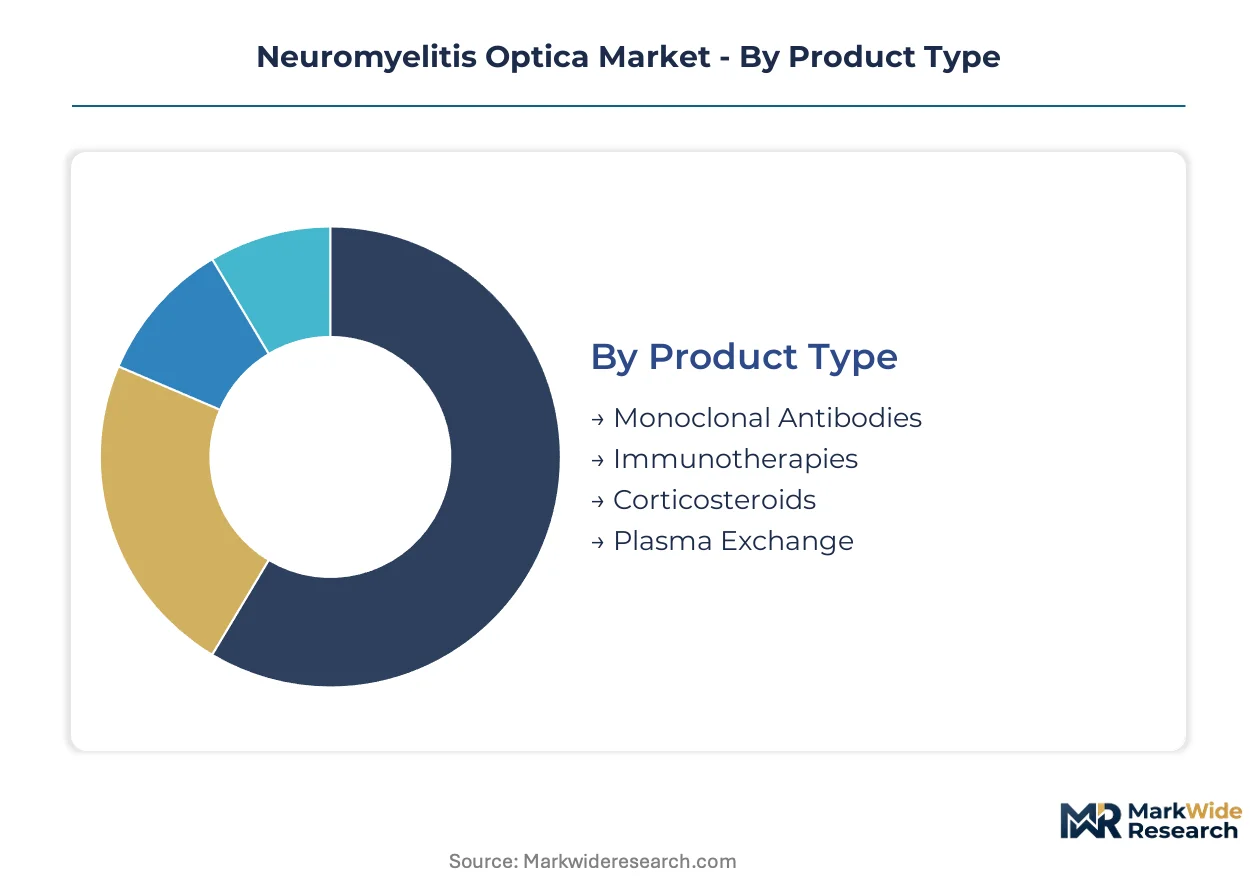
Neuromyelitis optica treatment pathways diverge sharply across product mechanisms, care settings, and disease phases. Manufacturers configure development portfolios around antibody-mediated disease biology while distribution strategies must reconcile acute rescue logistics with chronic maintenance convenience.
Product Type:
Cost tier differentiation separates biologic maintenance therapies from commoditized acute interventions, with margin structures reflecting development complexity and manufacturing scale.
- Monoclonal Antibodies:Engineered immunoglobulins targeting CD19, CD20, or complement C5 proteins interrupt pathogenic B-cell signaling or terminal complement activation. Demand concentrates in tertiary neurology centers across the United States, Germany, and Japan where infusion infrastructure and reimbursement for chronic biologic administration are established.
- Immunotherapies:Small-molecule and fusion protein modalities modulating T-cell activation or cytokine cascades offer alternative mechanism classes for patients with inadequate response to B-cell depletion. German university hospitals are piloting combination protocols pairing complement inhibition with selective immunosuppression, driving protocol diversification.
- Corticosteroids:High-dose methylprednisolone remains the first-line acute rescue standard where biologic access is delayed or contraindicated.
- Plasma Exchange:Extracorporeal antibody removal addresses catastrophic attacks refractory to pharmacologic intervention, constrained by apheresis center availability.
Monoclonal antibodies command the established base. The steepest expansion runs through immunotherapies as novel targets advance through clinical pipelines.
End User:
Application concentration varies by disease severity and therapy mechanism, with site-of-care decisions governed by infusion risk profiles and monitoring requirements.
- Hospitals:Academic medical centers manage acute attacks requiring intensive monitoring, apheresis capability, and multidisciplinary neuroimmune teams. United States health systems are consolidating NMO service lines into designated centers of excellence to capture bundled episode payments.
- Specialty Clinics:Dedicated neuroimmune ambulatory centers coordinate maintenance infusion schedules, antibody titers, and MRI surveillance. Japan's neurology specialist clinics are expanding satellite infusion capacity in Osaka and Fukuoka to reduce Tokyo patient travel burden.
- Research Institutes:Clinical trial sites and translational centers drive biomarker discovery and novel mechanism validation.
- Home Care Settings:Subcutaneous self-administration platforms are extending maintenance therapy beyond traditional infusion centers, contingent on nursing support infrastructure and patient training protocols.
Hospitals anchor the acute intervention base. Specialty clinics are capturing the fastest volume migration as maintenance protocols extend treatment duration.
Delivery Mode:
Volume distribution across administration routes reflects the tension between acute efficacy requirements and chronic patient convenience optimization.
- Intravenous:Infusion delivery achieves rapid bioavailability for acute rescue and loading doses of maintenance biologics, requiring hospital or infusion center infrastructure with cardiac monitoring capability.
- Subcutaneous:Prefilled syringe and autoinjector formats for maintenance monoclonal antibodies enable home administration with remote nursing oversight. German reimbursement authorities are expanding ambulatory subcutaneous coverage to reduce hospital day costs.
- Oral:Small-molecule immunosuppressants and corticosteroid taper regimens offer patient-administered chronic management, though bioavailability variability complicates dosing precision.
- Intramuscular:Depot corticosteroid formulations provide bridging therapy in resource-limited settings where infusion access is intermittent.
Intravenous delivery retains the acute-phase dominance. Subcutaneous administration is climbing the fastest as formulation innovation enables home-based maintenance.
Treatment Phase:
Customer type stratification separates episodic acute purchasers from chronic maintenance subscribers, with lifetime value calculations favoring long-term suppression strategies.
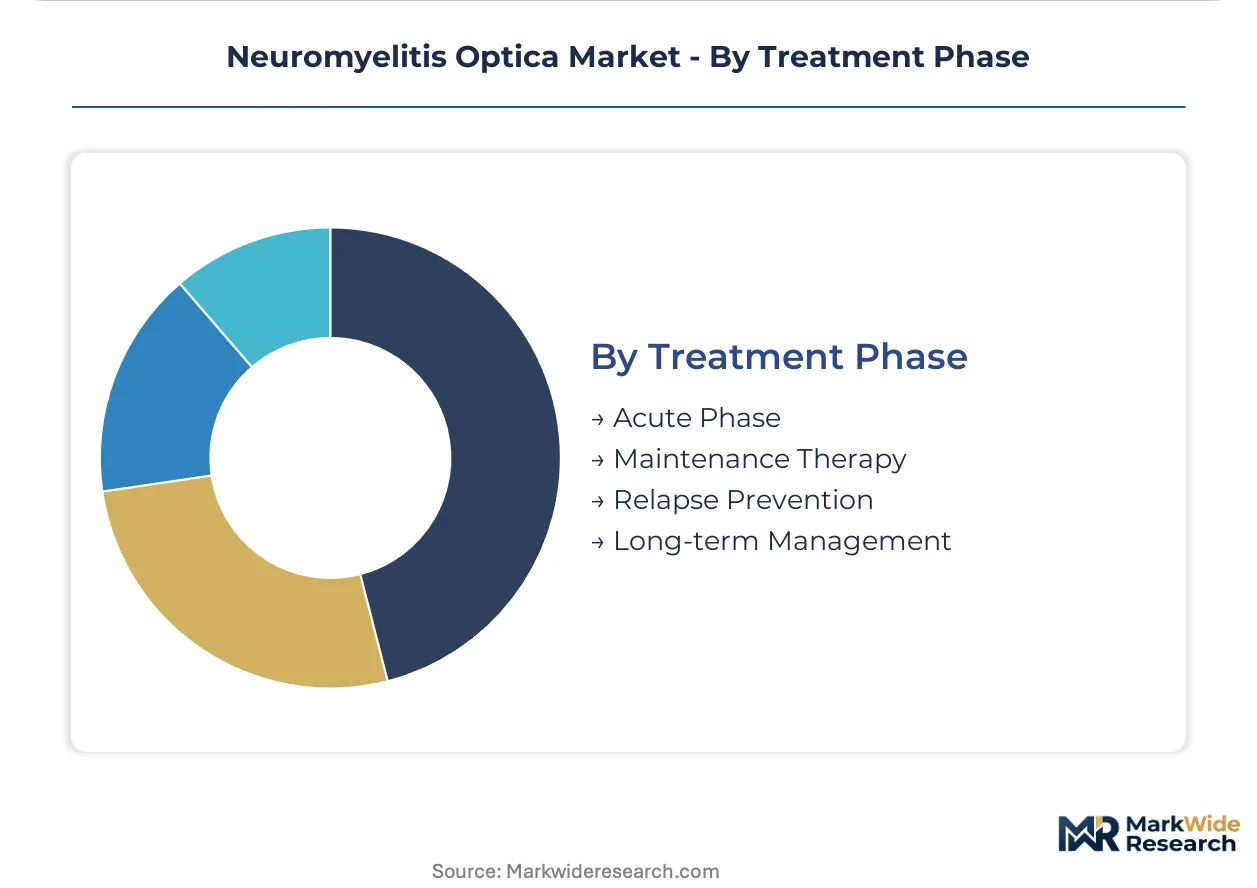
- Acute Phase:Attack management demands immediate high-dose intervention to limit optic nerve and spinal cord injury, with treatment windows measured in hours to days from symptom onset.
- Maintenance Therapy:Continuous immunosuppression prevents relapse and cumulative disability, with therapy persistence measured in years rather than months. United States commercial payers are implementing indication-specific prior authorization criteria to guide first-line biologic selection.
- Relapse Prevention:Escalation protocols and biomarker-guided therapy switches address breakthrough disease activity on initial maintenance agents.
- Long-term Management:Rehabilitation coordination, fertility preservation counseling, and vaccine scheduling integrate neuromyelitis optica into comprehensive chronic disease management.
Maintenance therapy represents the revenue concentration point. Long-term management is gaining strategic attention as manufacturers develop integrated patient support platforms extending beyond drug supply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. United States buyers absorb premium biologic pricing through commercial insurance channels, while Japanese reimbursement authorities impose stringent cost-effectiveness thresholds that compress manufacturer margins.
United States
Academic medical centers in Boston, Baltimore, and Houston drive diagnostic-to-treatment platform adoption. FDA orphan drug exclusivity provisions accelerate biologic approvals for small patient populations. Mayo Clinic's Rochester campus coordinates multi-site neuroimmune registries that generate real-world evidence for chronic immunosuppressive regimens.
Germany
University hospitals in Munich and Heidelberg pilot combination protocols pairing complement inhibition with selective immunosuppression. EMA's priority medicines scheme reduces assessment timelines for novel B-cell depleting agents. Berlin's Charité hospital network consolidates apheresis capacity to address plasma exchange demand volatility.
Japan
Neurology specialist clinics in Osaka and Fukuoka expand satellite infusion capacity to reduce Tokyo patient travel burden. PMDA's sakigake designation system accelerates review for innovative mechanisms in rare diseases. Keio University Hospital anchors biomarker discovery programs for aquaporin-4 seronegative subtypes.
United Kingdom
NHS England's specialized commissioning framework concentrates NMO care in designated tertiary centers across London, Oxford, and Liverpool. NICE technology appraisals impose cost-per-QALY thresholds that filter biologic access. The Walton Centre in Liverpool coordinates national relapse registry participation for post-market surveillance.
China
Tertiary hospitals in Beijing and Shanghai establish neuroimmune service lines with imported diagnostic assay platforms. NMPA's breakthrough therapy designation streamlines review for complement inhibitors. Peking Union Medical College Hospital leads multi-center trials for domestic B-cell targeting biologics.
Neuromyelitis Optica Market Competitive Environment
Capability concentration sits with integrated diagnostic-to-treatment platform operators; scale advantage sits with diversified biologic manufacturers with cross-indication manufacturing infrastructure. The market structures around three tiers: orphan disease specialists with deep neuroimmunology focus, large-cap biopharmaceuticals with autoimmune portfolios, and emerging biotechs with novel mechanism assets. Competitive moves center on diagnostic partnership consolidation and subcutaneous formulation migration to capture home administration value.
Within the orphan disease specialist tier, Alexion Pharmaceuticals and Horizon Therapeutics occupy positions defined by complement pathway expertise and rare neuroimmune concentration respectively. Among diversified biopharmaceuticals, Hoffmann-La Roche anchors integrated platform strategies spanning diagnostic assay development through maintenance therapy delivery. AstraZeneca represents the large-cap archetype with cross-portfolio immunology capabilities that extend into neuroimmune indications. TG Therapeutics exemplifies the emerging biotech pattern with B-cell mechanism focus and aggressive development timelines.
| Leading Market Players |
|---|
| AstraZeneca |
| TG Therapeutics |
| Alexion Pharmaceuticals |
| Teva Pharmaceutical Industries |
| Opexa Therapeutics |
| Horizon Therapeutics |
| Mitsubishi Tanabe Pharma |
| RemeGen |
| Hoffmann-La Roche |
| Others |
Value Chain & Pricing Dynamics
Fractionation capacity utilization at European and North American plasma collection centers sits below optimal thresholds, compressing immunoglobulin spot pricing while biologic manufacturers absorb fixed cold-chain infrastructure costs through long-term offtake structures. This utilization asymmetry rewards integrated diagnostic-to-treatment platform operators with volume commitments while spot purchasers in secondary markets face availability uncertainty.
Pricing Analysis
Long-term offtake agreements dominate biologic procurement, with United States academic medical centers locking multi-year supply contracts for complement inhibitors and B-cell depleting agents. Price differentiation separates premium-tier orphan-designated monoclonal antibodies from standard immunoglobulin replacement therapies, with certification by FDA orphan drug exclusivity and EMA priority medicines status commanding substantial brand premiums. Cost compression in acute rescue therapies intensifies as plasma-derived input volatility forces fractionators to prioritize contracted volumes over spot sales. Hospital procurement committees demonstrate highest price sensitivity for maintenance biologics facing therapeutic interchange pressure, while specialty clinics absorb premium pricing for subcutaneous formulations that reduce nursing overhead.
Supply Chain Analysis
Tariff exposure between United States and Chinese diagnostic assay component suppliers dominates supply chain risk planning, with cell-based aquaporin-4 antibody testing platforms drawing from German optical sensor manufacturers and Japanese precision fluid handling systems. Raw material dependencies center on pharmaceutical-grade monoclonal antibody cell lines, medical-grade silicone for prefilled syringes, and temperature-stabilizing excipients for cold-chain distribution. Single-source vulnerability concentrates in plasma collection network capacity for immunoglobulin fractionation, with batch release testing creating bottleneck risk at centralized quality control laboratories. Distribution runs through specialty pharmacy channels with hub-and-spoke infusion center networks, requiring continuous temperature monitoring from manufacturing through patient administration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Neuromyelitis optica treatment protocols sit in early-cycle expansion, with subcutaneous formulation adoption and pediatric indication development representing substantial untapped penetration vectors. Diagnostic assay diffusion and specialty clinic network buildout create durable tailwinds for maintenance therapy volume growth.
For Market Incumbents: Entrench diagnostic partnership exclusivities with tertiary neurology centers to secure antibody testing-to-treatment referral pathways. Acquire or in-license subcutaneous delivery device capabilities to capture home administration value before biosimilar entry erodes infusion-center margins. Defend against emerging B-cell mechanism competitors by deepening real-world evidence generation through patient registry participation that supports label expansion. For New Entrants and Emerging Players: Pursue aquaporin-4 seronegative patient stratification as the most penetrable white space, where mechanistic rationale for novel targets remains clinically unvalidated. Target German university hospital combination protocol pilots as entry points for complement inhibition adjuncts. Deploy health economics outcomes research capabilities to navigate NICE and German IQWiG cost-effectiveness thresholds where incumbent pricing has created access friction. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across subcutaneous formulation manufacturing as prefilled autoinjector platforms achieve scale economies. Long-term viability favors assets with demonstrated regulatory acceleration through FDA orphan drug and EMA priority medicines pathways. Acquisition targets should display integrated diagnostic assay development capabilities or exclusive specialty clinic distribution partnerships. Monitor FDA real-world evidence guidance implementation as the critical signal for label expansion valuation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Reduces infusion center dependency and expands treatable geography beyond urban hospital catchments. |
| Diagnostic Assay Partnership Consolidation | Compresses time from antibody confirmation to therapy initiation, capturing bundled episode value. |
| Pediatric Indication Expansion | Addresses white space in adolescent neuroimmune presentations with mechanistic rationale support. |
| Real-World Evidence Registry Investment | Enables FDA label expansion without prospective trial requirements under evolving guidance. |
| Specialty Clinic Network Saturation | Captures maintenance therapy volume migration through dedicated neuroimmune service lines. |
Study Parameters
Two parallel data streams informed the analysis: primary intelligence collection and secondary source triangulation. Primary interviews engaged drug development executives at complement inhibition and B-cell targeting biologic developers, regulatory affairs leads navigating FDA orphan drug and EMA priority medicines pathways, formulary directors at United States commercial payers, hospital procurement managers consolidating NMO service lines, and payer access specialists managing prior authorization criteria. Secondary validation drew from FDA orphan drug designation filings, EMA accelerated assessment submissions, ClinicalTrials.gov pipeline tracking, and formulary database surveillance across Medicare, Medicaid, and commercial channels. Bottom-up patient flow modeling and top-down biologic revenue triangulation anchored market sizing.
Forecast inputs incorporated treatment phase migration from acute rescue toward continuous maintenance suppression, mechanism-of-action share shifts between complement inhibition and B-cell depletion, and administration route substitution from intravenous to subcutaneous delivery. Segmentation dimensions spanned product type, end user setting, delivery mode, and treatment phase progression. CAGRs derived from patient prevalence projections, diagnosis rate improvement curves, and therapy persistence assumptions across the projection horizon. Industry-specific inputs included plasma fractionation capacity expansion schedules and diagnostic assay laboratory accreditation timelines.
Sensitivities concentrate around regulatory guidance evolution on real-world evidence acceptance, plasma supply disruption scenarios, and biosimilar entry timing for reference monoclonal antibodies. Forecasts reflect documented assumptions on patient identification improvement rates and reimbursement stability for chronic immunosuppressive regimens. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Cryptococcosis Treatment Market
Specialty Medicine
Ulcerated Necrobiosis Lipoidica Management Market
Specialty Medicine
Epistaxis Market
Specialty Medicine
Global Axial Spondyloarthritis (Axspa) Market
Specialty Medicine
Irritable Bowel Syndrome (IBS) Treatment Market
Specialty Medicine
Asia Pacific Liver Cancer Market
Specialty Medicine
Enzyme Replacement Therapy Market
Specialty Medicine
Parathyroid Disorders Market
Specialty Medicine
Rumination Syndrome Market
Specialty Medicine
Vertigo Market
Specialty Medicine
Global Photodynamic Therapy Market
Specialty Medicine
Cryptococcosis Market
Specialty Medicine
Alcoholic Liver Diseases Treatment Market
Specialty Medicine
Hemifacial Spasm Market
Specialty Medicine
Neurodegenerative Disorder Market
Specialty Medicine
Global Breast Cancer Therapeutics Market