
 Allergic Rhinitis Drugs Market | 2026-2036
Allergic Rhinitis Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Allergic Rhinitis Drugs Market Analysis
Demand from pediatric allergy clinics is shifting toward intranasal corticosteroid formulations as first-line intervention for moderate-to-severe perennial rhinitis. Sanofi leverages its established immunology franchise to sustain brand loyalty among allergists prescribing combination therapies. Teva Pharmaceutical Industries Ltd. anchors its position through generic antihistamine portfolios that compete aggressively on formulary access. GlaxoSmithKline plc dominates the nasal spray segment with manufacturing scale that controls distribution across European and North American hospital networks.
Allergic rhinitis drugs comprise pharmacological agents designed to antagonize histamine H1 receptors, modulate leukotriene pathways, or suppress local nasal inflammation through corticosteroid receptor agonism, with bioavailability parameters varying by administration route and molecular formulation. These therapeutics serve the primary commercial purpose of symptom control in IgE-mediated nasal mucosa inflammation, reducing rhinorrhea, sneezing, and congestion to restore functional capacity in occupational and educational settings. Corticosteroid nasal sprays occupy the largest margin pool due to their superior efficacy in persistent cases and extended prescription durations. Antihistamine tablets maintain volume leadership in the self-medicated adult segment where convenience drives pharmacy selection. Leukotriene modifiers represent the fastest-expanding drug class as allergists identify responder subsets among patients with comorbid asthma.
The FDA bioequivalence standards for nasal spray generics shape competitive entry timelines and pricing trajectories for corticosteroid products, while the EMA's MDR requirements impose clinical documentation burdens on European market participants seeking device-drug combination approvals. Health Canada and the TGA enforce comparable but non-identical stability testing protocols that fragment regulatory submission strategies for multinational sponsors. Stakeholders must monitor evolving pharmacovigilance obligations for long-acting injectable antihistamines as these formulations gain traction beyond specialist settings.
Market Dynamics
Pediatric allergy clinics are consolidating formulary decisions around intranasal corticosteroid first-line protocols, compressing the window for antihistamine monotherapy and reshaping prescriber incentives across outpatient networks.
Growth Catalysts
- FDA Streamlined Bioequivalence:The FDA's accelerated generic nasal spray approval pathways compress substitution timelines for corticosteroid products, expanding accessible therapeutic options.
- Pollen Burden Intensification:Extended seasonal pollen cycles in the United States sustain elevated prescription volumes through direct-to-consumer advertising channels.
- Leukotriene Modifier Responder Identification:Allergist protocols now stratify asthma-comorbid patients for targeted leukotriene pathway modulation, expanding addressable populations.
Market Restraints
- Device-Drug Combination Documentation:The EMA's MDR requirements impose substantial clinical validation burdens on European sponsors seeking combination product approvals.
- Stability Testing Fragmentation:Health Canada and TGA non-identical protocols force redundant submission strategies, inflating regulatory compliance costs for multinational portfolios.
- Long-Acting Injectable Surveillance:Evolving pharmacovigilance obligations for extended-release antihistamine formulations constrain specialist-to-primary care expansion.
Strategic Opportunities
- Generic Corticosteroid Manufacturing Scale:Nasal spray production capacity concentration in India and China creates white space for regional supply base diversification.
- Self-Medication Channel Expansion:Pharmacy-direct antihistamine tablet purchasing is displacing prescription workflows in convenience-oriented adult segments.
- Biologic-Adjunct Protocol Development:Allergen immunotherapy combination regimens with intranasal corticosteroids open specialist clinic revenue streams.
Industry Challenges
- Formulation Scientist Talent Scarcity:Nasal spray bioequivalence expertise concentrates among a limited pool of regulatory consultants, constraining sponsor pipeline velocity.
- Legacy Inhaler Device Integration:Corticosteroid spray platforms require compatibility with evolving connected health ecosystems, complicating R&D roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Allergic Rhinitis Drugs Market |
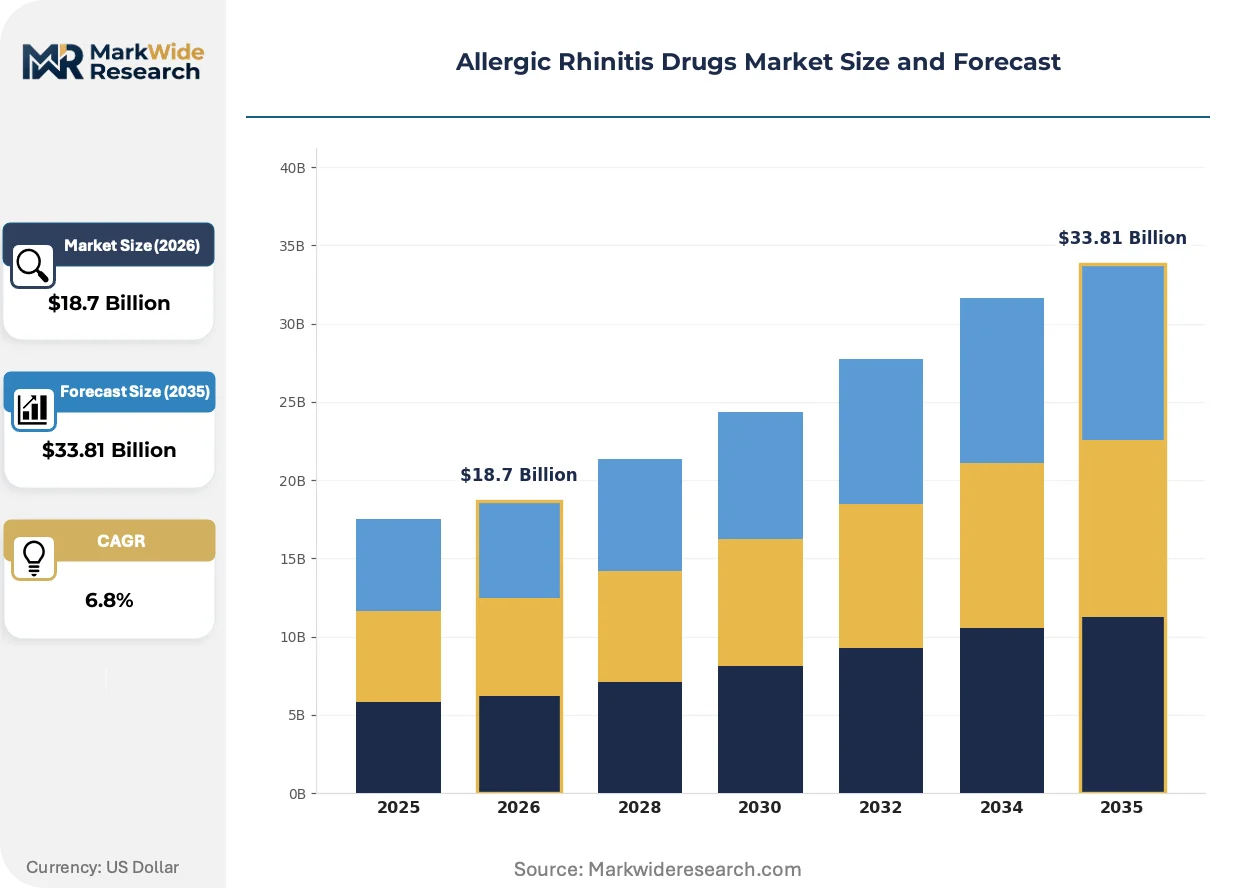
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Class: Antihistamines, Corticosteroids, Decongestants, Leukotriene Modifiers Formulation: Tablets, Nasal Sprays, Solutions, Inhalers Administration Route: Oral, Nasal, Injectables, Sublingual Age Group: Pediatric, Adult, Geriatric, Adolescents |
| Companies Covered | Sanofi, Teva Pharmaceutical Industries Ltd., GlaxoSmithKline plc, Pfizer Inc., Johnson & Johnson, Bayer AG, Merck & Co., Boehringer Ingelheim International GmbH, Glenmark Pharmaceuticals Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Allergic Rhinitis Drugs Market Emerging Trajectories
Formulation science and regulatory science are converging to compress development cycles for complex nasal delivery systems, while prescriber behavior shifts toward combination protocols and patient self-management tools.
Long-acting intranasal corticosteroid depot formulations are electrifying adherence outcomes in pediatric populations where daily dosing compliance fails. Allergy specialists in US academic medical centers are piloting these platforms for moderate-to-severe perennial cases. The technology is electrifying competitive positioning around duration-of-action claims rather than onset speed alone.
The FDA's refined bioequivalence standards for locally-acting nasal sprays are compressing ANDA review timelines for generic sponsors. This regulatory recalibration accelerates price erosion in the corticosteroid segment while preserving reference product market access through device differentiation. European sponsors face asymmetric pressure as the EMA's MDR maintains stricter clinical evidence thresholds.
Direct-to-consumer telehealth platforms are fragmenting the traditional allergist-prescription-pharmacy chain for antihistamine access. US-based digital health startups now capture initial diagnosis and medication fulfillment in unified workflows, bypassing specialist referral requirements. This channel shift concentrates volume in self-medicated adult segments where convenience overrides clinical consultation preferences.
Allergic Rhinitis Drugs Market Segmentation
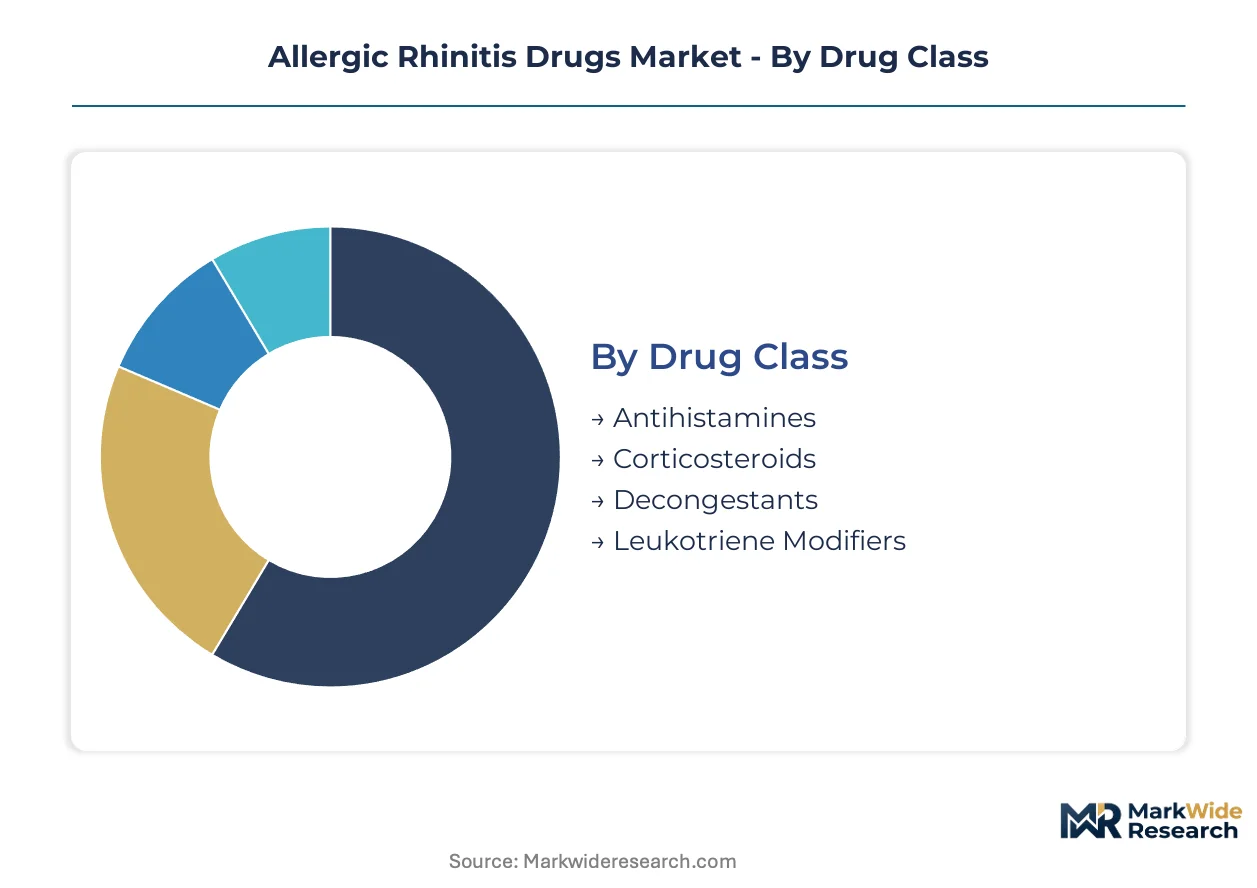
Allergic rhinitis drug segmentation reveals how formulation science and prescriber protocols fragment commercial opportunity across distinct patient populations and therapeutic modalities. Understanding these divisions exposes where R&D investment concentrates and which channels capture margin.
Drug Class:
Prescriber protocols are consolidating around efficacy hierarchies that favor corticosteroid dominance while leukotriene pathways gain traction in comorbid populations.
- Antihistamines:These H1-receptor antagonists block histamine-mediated symptoms through competitive inhibition at peripheral nerve endings. First-generation compounds retain OTC volume leadership in the United States, where pharmacy-direct purchasing displaces prescription workflows for seasonal self-medicators.
- Corticosteroids:Intranasal glucocorticoid formulations suppress local inflammation through nuclear receptor translocation and cytokine gene transcription inhibition. Pediatric allergy clinics in academic medical centers are consolidating first-line protocols around these agents for moderate-to-severe perennial cases.
- Decongestants:Alpha-adrenergic agonists provide rapid nasal patency through vascular constriction of sinusoidal capacitance vessels. Rebound congestion risk limits prescription duration in chronic management settings.
- Leukotriene Modifiers:Cysteinyl leukotriene receptor antagonists and 5-lipoxygenase inhibitors modulate inflammatory eicosanoid pathways. Allergist protocols now stratify asthma-comorbid patients for targeted pathway modulation, expanding specialist clinic adoption.
Corticosteroids sit at the top of the volume ranking, with leukotriene modifiers climbing the fastest.
Formulation:
Patient adherence patterns and manufacturing complexity create divergent margin structures across physical delivery formats.
- Tablets:Oral solid dosage forms offer dose precision and stability advantages that sustain pharmacy shelf presence. Convenience-oriented adult segments in direct-to-consumer channels drive volume concentration here.
- Nasal Sprays:Metered-dose pump systems deliver topical corticosteroid deposition to nasal mucosa with particle size distributions optimized for anterior cavity retention. FDA bioequivalence standard refinements are compressing ANDA review timelines for generic sponsors.
- Solutions:Liquid formulations enable dose flexibility in pediatric populations where tablet swallowing fails. Ophthalmic and nasal irrigation adjuncts occupy niche positioning.
- Inhalers:Pressurized and breath-actuated devices extend delivery to lower respiratory targets in patients with overlapping asthma pathology. Device-drug combination documentation burdens under EMA MDR constrain European sponsor entry.
Tablets capture the largest prescription count, though nasal sprays are expanding most quickly in pediatric formulary adoption.
Administration Route:
Route selection trade-offs between onset speed, systemic exposure, and patient compliance reshape competitive positioning across care settings.
- Oral:Systemic absorption through gastrointestinal tract enables convenient self-administration without device training. Antihistamine tablets dominate this channel for adult seasonal symptom control.
- Nasal:Topical mucosal deposition maximizes local drug concentration while minimizing systemic bioavailability. Intranasal corticosteroids anchor this route with superior efficacy in persistent inflammation.
- Injectables:Subcutaneous and intramuscular depot formulations extend duration through sustained-release polymer matrices. Long-acting antihistamine injections are gaining traction beyond specialist settings, though evolving pharmacovigilance obligations constrain primary care expansion.
- Sublingual:Oral mucosal absorption bypasses hepatic first-pass metabolism for rapid systemic entry. Allergen immunotherapy tablets utilize this route for disease-modifying protocols.
Nasal administration leads in specialist clinic preference, while injectables are gaining share fastest among biologic-adjunct protocols.
Age Group:
Developmental pharmacology and regulatory pediatric study requirements fragment product development priorities across life stages.
- Pediatric:Patients under 12 years require age-appropriate formulations with demonstrated safety in growing airways. Long-acting intranasal corticosteroid depot formulations are electrifying adherence outcomes where daily dosing compliance fails.
- Adult:Working-age populations between 18 and 65 drive self-medication channel volume through convenience-seeking pharmacy behavior. Direct-to-consumer telehealth platforms now capture diagnosis and fulfillment in unified workflows.
- Geriatric:Elderly patients present polypharmacy challenges and altered drug metabolism that necessitate dose adjustments. First-generation antihistamine anticholinergic burdens limit formulary acceptance.
- Adolescents:Transitional age patients between 12 and 17 years require bridging studies that extrapolate adult efficacy while monitoring growth velocity. Peer influence on adherence creates distinct counseling requirements.
Adults command the largest prescription volume, with pediatric applications showing the steepest expansion trajectory as allergy clinic protocols consolidate around intranasal first-line standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost-of-compliance gaps between jurisdictions are redirecting generic nasal spray manufacturing toward South and East Asian production bases while branded innovators retain European and North American formulation science capabilities.
United States
Extended pollen seasons and direct-to-consumer advertising sustain prescription volume concentration. FDA streamlined bioequivalence pathways for nasal spray generics accelerate substitution timelines. Research Triangle Park in North Carolina anchors clinical trial infrastructure for intranasal corticosteroid depot development.
Germany
Pediatric allergy clinic networks in Bavaria and Baden-Württemberg consolidate formulary adoption around corticosteroid first-line protocols. EMA MDR device-drug combination requirements impose clinical documentation burdens distinct from FDA standards. Frankfurt-Rhine-Main corridor hosts pharmacovigilance operations for extended-release antihistamine surveillance.
India
Contract manufacturing scale for metered-dose pump systems concentrates in Gujarat and Maharashtra. CDSCO stability testing protocols diverge from Health Canada and TGA requirements, fragmenting submission strategies. Hyderabad-Visakhapatnam pharmaceutical cluster specializes in generic corticosteroid active pharmaceutical ingredient production.
Japan
Aging demographics expand geriatric polypharmacy management protocols limiting first-generation antihistamine use. PMDA seasonal review cycles for combination products extend market entry timelines versus FDA benchmarks. Kansai region Osaka-based manufacturers control regional distribution for preservative-free nasal spray formulations.
United Kingdom
Self-medication channel growth through pharmacy-direct antihistamine purchasing displaces prescription workflows. MHRA post-Brexit regulatory autonomy enables divergence from EMA MDR implementation timelines. London-Southeast corridor concentrates telehealth platform development for unified diagnosis-to-fulfillment workflows.
Allergic Rhinitis Drugs Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with innovator portfolios commanding margin in pediatric and specialist settings while generic houses capture volume through formulary access. The vendor base concentrates around three strategic archetypes: multinational immunology franchises with established allergist relationships, vertically integrated generic manufacturers with nasal spray production scale, and regional pharmaceutical houses with distribution control in emerging markets. Competitive moves center on M&A for device technology capabilities and capacity expansion in South Asian production bases.
Among the branded multinational tier, Sanofi and GlaxoSmithKline plc exemplify immunology franchise operators with sustained allergist channel presence. Teva Pharmaceutical Industries Ltd. represents the generic manufacturing archetype with aggressive formulary positioning. These three anchors illustrate how competitive positioning diverges between innovation-driven and access-driven strategies.
| Leading Market Players |
|---|
| Sanofi |
| Teva Pharmaceutical Industries Ltd. |
| GlaxoSmithKline plc |
| Pfizer Inc. |
| Johnson & Johnson |
| Bayer AG |
| Merck & Co. |
| Boehringer Ingelheim International GmbH |
| Glenmark Pharmaceuticals Ltd |
| Others |
Supply Flow & Price Mechanics
Patent-protected intranasal corticosteroid depot formulations command substantial premia over commodity antihistamine tablets, with this bifurcation manifesting in divergent supply chain footprints—branded innovators retaining formulation science capabilities in the United States and Germany while generic manufacturers concentrate metered-dose pump production in Gujarat and Maharashtra.
Pricing Analysis
Retailer markup layers in the United States sustain wide spreads between pharmacy-direct OTC antihistamines and prescription corticosteroid sprays. Three-tier pricing structure across premium, standard, and economy levels separates long-acting depot formulations from conventional nasal sprays from private-label tablets. Pricing pressure stems from FDA accelerated ANDA approvals compressing generic substitution timelines. Self-medicated adult segments exhibit highest price sensitivity, while pediatric allergy clinics prioritize efficacy over acquisition cost.
Supply Chain Analysis
Workforce availability for nasal spray bioequivalence expertise concentrates in Hyderabad-Visakhapatnam and Research Triangle Park, constraining sponsor pipeline velocity elsewhere. Active pharmaceutical ingredient production draws from India and China, with finished dose formulation in the United States and Germany. Single-source vulnerability sits with concentrated metered-dose pump device manufacturing. Distribution runs through hospital networks for corticosteroid prescriptions and pharmacy-direct channels for antihistamine tablets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a geographic-arbitrage play where CDSCO stability testing divergence from Health Canada and TGA requirements fragments submission strategies, inflating compliance costs for sponsors lacking South Asian regulatory affairs capabilities.
For Market Incumbents: Extend manufacturing scale in Gujarat and Maharashtra to capture generic corticosteroid volume as FDA bioequivalence pathways accelerate substitution. Extend device differentiation investments to preserve reference product access against ANDA compression. Vertical integration into nasal spray pump production hedges single-source device vulnerability.
For New Entrants and Emerging Players: Launch via direct-to-consumer telehealth platforms that unify diagnosis and fulfillment workflows for adult self-medicators. Target leukotriene modifier responder identification protocols in asthma-comorbid populations where allergist adoption climbs fastest. White space concentrates in biologic-adjunct combination regimens for specialist clinic revenue capture.
For Investors and Strategic Acquirers: Consolidation pressure builds where formulation scientist scarcity constrains pipeline velocity for mid-cap sponsors lacking bioequivalence expertise. Five-to-ten year viability favors vertically integrated manufacturers with captive nasal spray device capabilities. Acquisition target archetype: regional pharmaceutical houses with distribution control in emerging markets plus underutilized CDSCO submission capacity. Signal to watch: FDA refinement of locally-acting nasal spray standards accelerating ANDA review timelines further.
| Strategic Initiative | Industry Significance |
|---|---|
| Generic Corticosteroid Manufacturing Scale-Up | Captures volume as FDA ANDA pathways accelerate substitution timelines for nasal sprays. |
| Long-Acting Depot Formulation Development | Electrifies adherence outcomes in pediatric populations where daily dosing compliance fails. |
| Telehealth Platform Integration | Fragments traditional allergist-prescription-pharmacy chain for adult self-medication segments. |
| Device Technology Acquisition | Preserves branded market access through pump differentiation against generic bioequivalence. |
| Biologic-Adjunct Protocol Partnership | Opens specialist clinic revenue streams through allergen immunotherapy combination regimens. |
Methodological Framework
Coverage spans the United States, Germany, India, Japan, and the United Kingdom, with primary inputs from each market combined with secondary validation. Interviews engaged drug development executives at multinational immunology franchises, regulatory affairs leads navigating FDA and EMA submission divergence, formulary directors at pediatric allergy clinic networks, and payer access specialists managing reimbursement for long-acting injectables. Secondary sources included FDA ANDA filing databases, EMA MDR submission records, ClinicalTrials.gov protocol registries, and hospital procurement databases tracking intranasal corticosteroid adoption. Bottom-up prescription volume modeling triangulated against top-down market value estimates.
Granularity-level framing applied drug class, formulation, administration route, and patient age group dimensions at the country level, with regulatory cluster overlays capturing FDA, EMA, CDSCO, PMDA, and MHRA pathway divergence. CAGRs derived from segment-level volume trajectories calibrated to pollen burden intensification patterns and pediatric formulary consolidation trends. Forecast inputs incorporated direct-to-consumer advertising expenditure flows and generic substitution elasticity parameters.
Several conditions sit outside the modeled scope, including unforeseen pharmacovigilance obligations for extended-release antihistamines, abrupt EMA MDR enforcement shifts, and climate-driven pollen cycle disruption beyond historical variance bands. Forecasts reflect assumptions about prescriber protocol stability and regulatory pathway continuity. Material deviation in FDA bioequivalence standard refinement pace or CDSCO-Health Canada-TGA harmonization progress warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Brazil Diabetes Drugs Market
Pharmaceuticals
Iron Deficiency Injectables Market
Pharmaceuticals
Global Online Pharmacy Market
Pharmaceuticals
Inhaled Nitric Oxide Market
Pharmaceuticals
Enteric Empty Capsules Sales Market
Pharmaceuticals
Xerostomia Therapeutics Market
Pharmaceuticals
MRI Contrast Media Agents Market
Pharmaceuticals
Pharmaceuticals Lipids Market
Pharmaceuticals
Structured Product Label Management Market
Pharmaceuticals
Amoxicillin Drugs Market
Pharmaceuticals
Ceftriaxone Market
Pharmaceuticals
Global Compounding Pharmacy Market
Pharmaceuticals
Telmisartan Market
Pharmaceuticals
Oral Anti-Diabetic Drugs Market
Pharmaceuticals
Saudi Arabia Diabetes Drugs Market
Pharmaceuticals
GLP-1 Receptor Agonist Market