
 Bone Degeneration Therapeutics Market | 2026-2036
Bone Degeneration Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Bone Degeneration Therapeutics Market Analysis
The FDA's accelerated approval framework for biologics is decoupling clinical trial requirements from traditional endpoints, raising the cost of entry for new osteoclast inhibitors. Amgen Inc. leverages its established manufacturing scale for denosumab production across North American facilities. Medtronic Plc anchors its position through orthopedic implant integration with pharmaceutical delivery systems. Stryker Corporation differentiates via surgeon training networks that lock in hospital purchasing decisions.
Bone degeneration therapeutics comprise pharmacological agents that modulate osteoclast and osteoblast activity to restore skeletal density and structural integrity, typically formulated as monoclonal antibodies, synthetic peptides, or bisphosphonate salts requiring precise dosing calibrated to bone mineral density T-scores. These therapeutics serve primarily to prevent fragility fractures in metabolically compromised skeletal tissue. Injectable delivery modes dominate revenue contribution due to superior bioavailability of biologics like denosumab and teriparatide, while oral bisphosphonates retain volume leadership in emerging markets where cold-chain infrastructure remains limited. The osteoporosis application segment commands the deepest margin pools as chronic administration protocols generate recurring prescription revenue streams.
FDA, EMA, and Japan's PMDA enforce divergent post-market surveillance requirements for bone-modifying agents, with the FDA mandating extended cardiovascular safety monitoring that extends development timelines. The EU's MDR reclassification of certain drug-device combination products for spinal delivery has triggered conformity assessment bottlenecks. Stakeholders must monitor evolving pharmacovigilance mandates that threaten to reshape commercialization strategies for next-generation anabolic therapies.
Market Dynamics
The FDA's accelerated approval framework for biologics is decoupling clinical trial requirements from traditional endpoints, fundamentally restructuring how osteoclast inhibitors enter commercial distribution and raising capital barriers for new molecular entities.
Growth Catalysts
- Biologic Delivery Systems:Injectable formulations of monoclonal antibodies command superior bioavailability compared to oral bisphosphonates, pulling orthopedic clinics toward biologic-first protocols for fracture prevention.
- Medicare Reimbursement:Sustained coverage for osteoporotic interventions under Part B and Part D sustains high procedure volumes across United States ambulatory surgical centers.
- EMA Biosimilar Pathway:Streamlined market authorization for follow-on biologics in European Union member states is expanding patient access to denosumab alternatives.
Market Restraints
- Cold-Chain Infrastructure Gaps:Limited refrigerated distribution networks in emerging markets constrain biologic penetration, forcing reliance on oral bisphosphonates with inferior efficacy profiles.
- Extended Safety Monitoring:FDA-mandated cardiovascular surveillance for bone-modifying agents extends development timelines by 18-24 months and inflates post-market pharmacovigilance costs.
- Manufacturing Concentration:Monoclonal antibody production clusters in North American and Western European contract manufacturing organizations, creating supply vulnerability during regional disruptions.
Strategic Opportunities
- Underpenetrated Rural Markets:United States secondary and tertiary care markets outside major metropolitan corridors show significant gaps in bone mineral density screening and treatment initiation.
- Drug-Device Convergence:Integration of pharmaceutical delivery systems with orthopedic implants creates recurring revenue streams through surgeon training lock-in and hospital purchasing agreements.
- Japan PMDA Anabolic Pathway:Japan's distinct regulatory framework for next-generation anabolic therapies offers faster market entry for novel osteoblast-stimulating compounds compared to FDA timelines.
Industry Challenges
- Specialized Manufacturing Talent:Biologic production requires rare expertise in mammalian cell culture and aseptic processing, constraining capacity expansion for denosumab and teriparatide analogs.
- MDR Conformity Bottlenecks:EU Medical Device Regulation reclassification of spinal drug-device combinations has triggered extended conformity assessment timelines, delaying commercial launches.
- Legacy System Integration:Hospital purchasing departments struggle to reconcile biologic inventory management with existing ERP platforms designed for small-molecule pharmaceuticals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bone Degeneration Therapeutics Market |
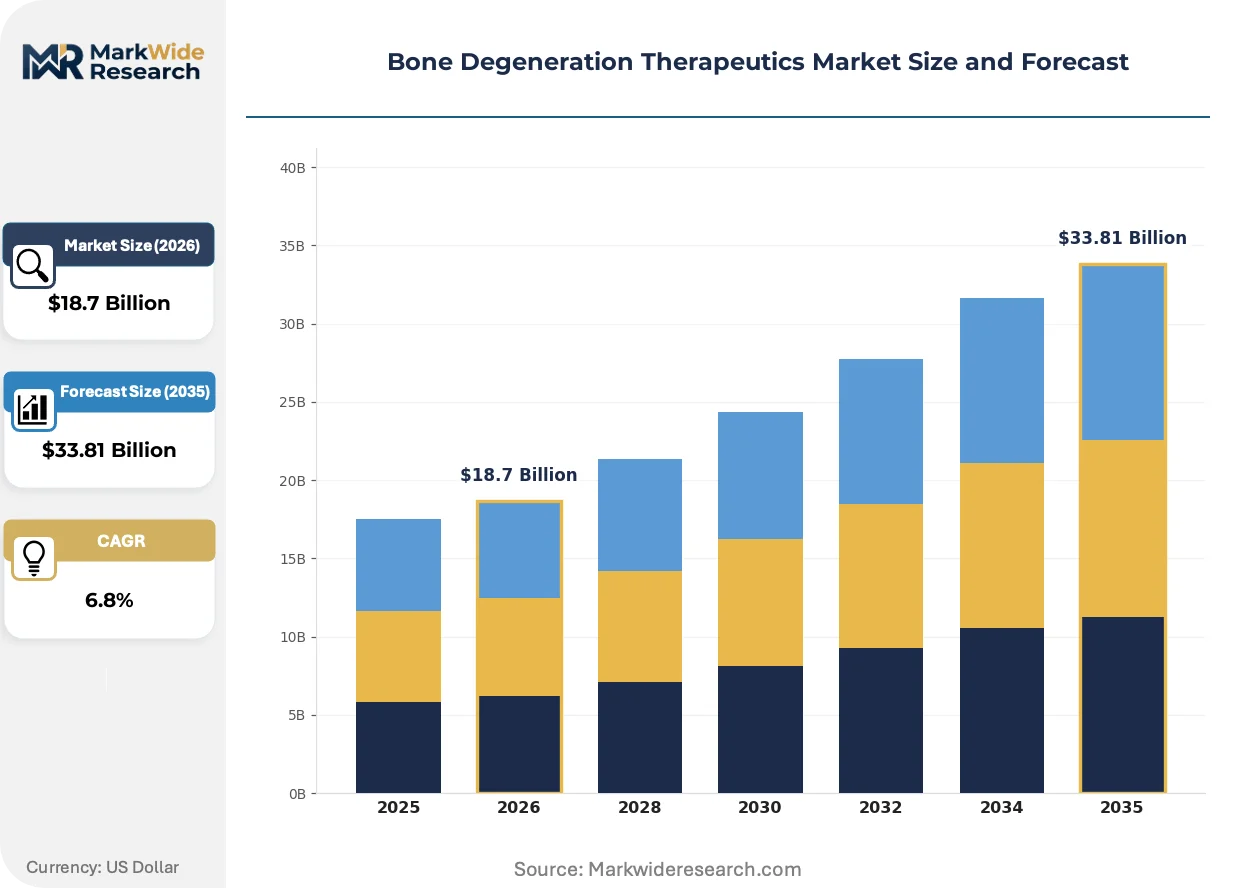
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bisphosphonates, Teriparatide, Denosumab, Calcitonin Application: Osteoporosis, Osteopenia, Paget's Disease, Hypercalcemia End User: Hospitals, Clinics, Homecare, Pharmacies Delivery Mode: Injectable, Oral, Intranasal, Transdermal |
| Companies Covered | Amgen Inc., Medtronic Plc, Stryker Corporation, Zimmer Biomet, Fate Therapeutics Inc., Juventus Therapeutics Inc., Se-cure Pharmaceuticals Ltd., Kaken Pharmaceutical Co. Ltd., NuVasive Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bone Degeneration Therapeutics Market Emerging Trajectories
Biologic manufacturing scale and regulatory science are converging to compress development cycles, while demand-side purchasing consolidation is rewriting commercial access strategies across institutional channels.
Long-acting injectable formulations are absorbing the chronic administration burden previously managed through monthly or quarterly patient visits. Large hospital systems and orthopedic clinic chains are adopting these extended-interval therapies at accelerating pace to reduce infusion center overhead. This absorption of care delivery into fewer touchpoints is compressing revenue per patient while expanding total addressable volume through improved adherence.
Europe's MDR implementation is forcing structural reorganization of spinal delivery system classifications. Drug-device combinations previously regulated as pharmaceuticals now face dual conformity assessment under both EMA and notified body oversight. Spinal fusion applications incorporating pharmaceutical elution are experiencing the most severe timeline extensions, with several manufacturers pivoting toward pure pharmaceutical strategies to bypass device classification.
Hospital procurement departments are consolidating vendor relationships to reduce therapeutic complexity and capture volume discounts. Group purchasing organizations are replacing individual hospital formulary decisions with centralized biologic contracting across integrated delivery networks. This concentration is most visible in United States Medicare Advantage populations, where risk-bearing entities prioritize therapies with demonstrable fracture-reduction outcomes over mechanism-of-action differentiation.
Bone Degeneration Therapeutics Market Segmentation
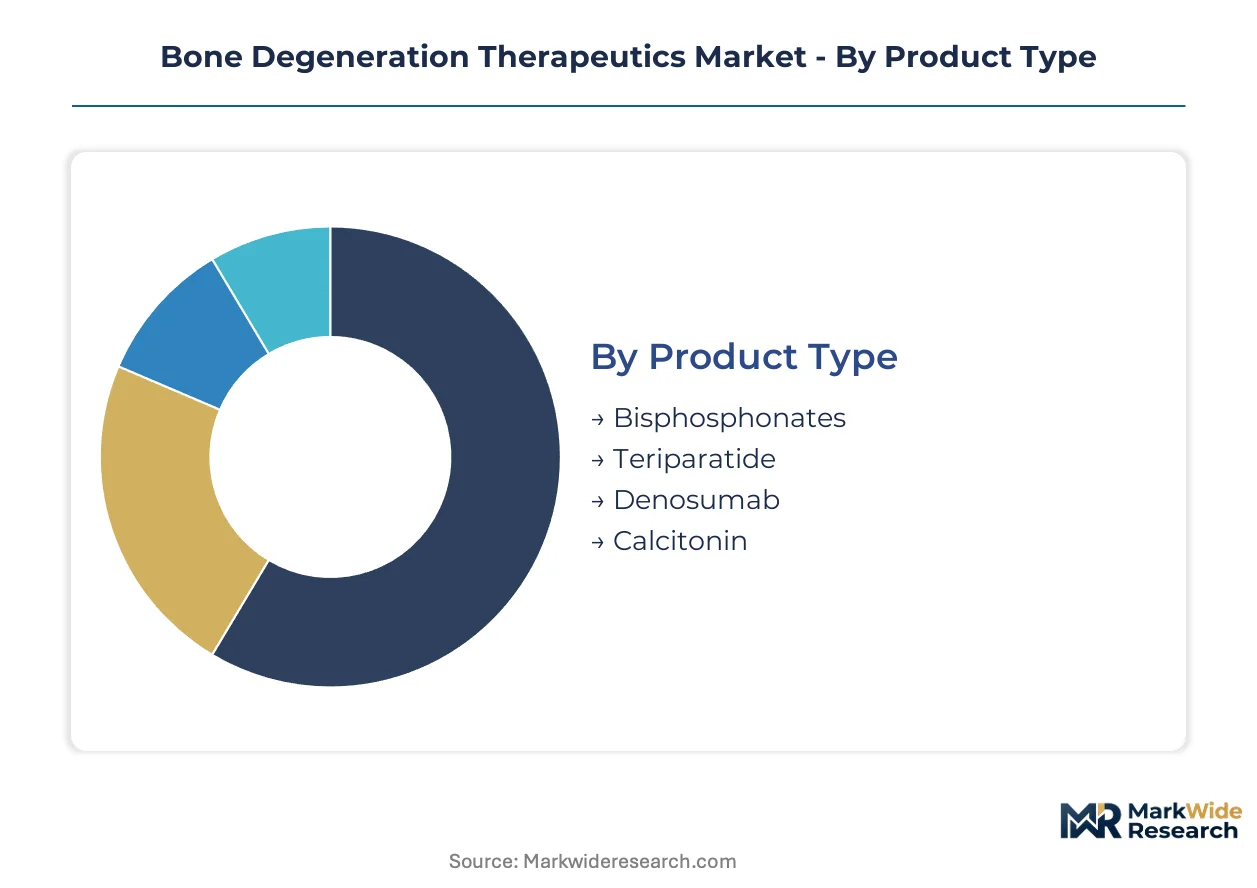
Therapeutic modality and delivery infrastructure dictate margin structures across bone degeneration treatments. Injectable biologics command premium positioning where cold-chain logistics exist, while oral formulations retain volume dominance in infrastructure-constrained settings.
Product Type:
Manufacturing concentration clusters around mammalian cell culture capabilities for monoclonal antibody production, with small-molecule synthesis offering geographic diversification.
- Bisphosphonates:Synthetic pyrophosphate analogs that bind hydroxyapatite and inhibit osteoclast-mediated bone resorption. United States Medicare Part D reimbursement sustains high prescription volumes for alendronate and risedronate salts in ambulatory settings. Cold-chain independence allows distribution through retail pharmacy networks lacking refrigerated storage.
- Denosumab:Fully human monoclonal antibody targeting RANKL that suppresses osteoclast differentiation and activation. Demand concentrates in orthopedic clinic chains across Germany, France, and the United Kingdom where biologic administration infrastructure is embedded. Manufacturing scale requirements limit production to North American and Western European contract manufacturing organizations.
- Teriparatide:Recombinant human parathyroid hormone analog stimulating osteoblast activity through intermittent administration. Daily injectable protocols require patient adherence support programs.
- Calcitonin:Polypeptide hormone suppressing osteoclast activity through calcitonin receptor modulation. Intranasal and injectable formulations serve niche populations with bisphosphonate intolerance.
Today's leader: Bisphosphonates. Tomorrow's challenger: Denosumab.
Application:
Clinical endpoints and reimbursement coding create distinct revenue durability across metabolic bone disorders, with chronic conditions generating recurring prescription streams.
- Osteoporosis:Systemic skeletal disorder characterized by low bone mass and microarchitectural deterioration. United States orthopedic clinics and fracture liaison services drive screening-to-treatment conversion in Medicare-eligible populations. Chronic administration protocols generate the deepest margin pools through recurring revenue structures.
- Osteopenia:Reduced bone mineral density below normal peak levels without reaching osteoporosis threshold. Preventive intervention demand is climbing the fastest in Japanese and South Korean markets where BMD screening penetration exceeds Western benchmarks.
- Paget's Disease:Localized disorder of bone remodeling producing enlarged and weakened bone. Specialist endocrinology practices manage limited patient volumes with intermittent bisphosphonate courses.
- Hypercalcemia:Elevated serum calcium often secondary to malignancy or hyperparathyroidism. Acute hospital-based administration dominates with single-dose or short-course bisphosphonate protocols.
Revenue durability peaks in chronic administration settings, with acute intervention segments offering lower lifetime value per patient.
End User:
Procurement authority and reimbursement pathway determine channel economics, with institutional purchasing consolidation reshaping vendor access strategies.
- Hospitals:Inpatient and outpatient departments managing acute fracture care and complex metabolic bone disease. United States integrated delivery networks leverage group purchasing organization contracts to consolidate biologic procurement across multi-hospital systems.
- Clinics:Ambulatory orthopedic and endocrinology practices delivering chronic osteoporosis management. Specialty clinic chains in Texas, Florida, and California concentrate infusion center capacity for parenteral biologic administration.
- Homecare:Self-administered subcutaneous injections supported by nursing visit protocols. Patient adherence programs and remote monitoring infrastructure determine therapy persistence.
- Pharmacies:Retail and mail-order dispensing for oral bisphosphonate prescriptions. Generic substitution policies and formulary tier placement drive margin compression.
Institutional channels anchor biologic revenue, with retail pharmacy maintaining oral generic volume leadership.
Delivery Mode:
Bioavailability requirements and patient convenience trade-offs segment the market by infrastructure dependency and administration frequency.
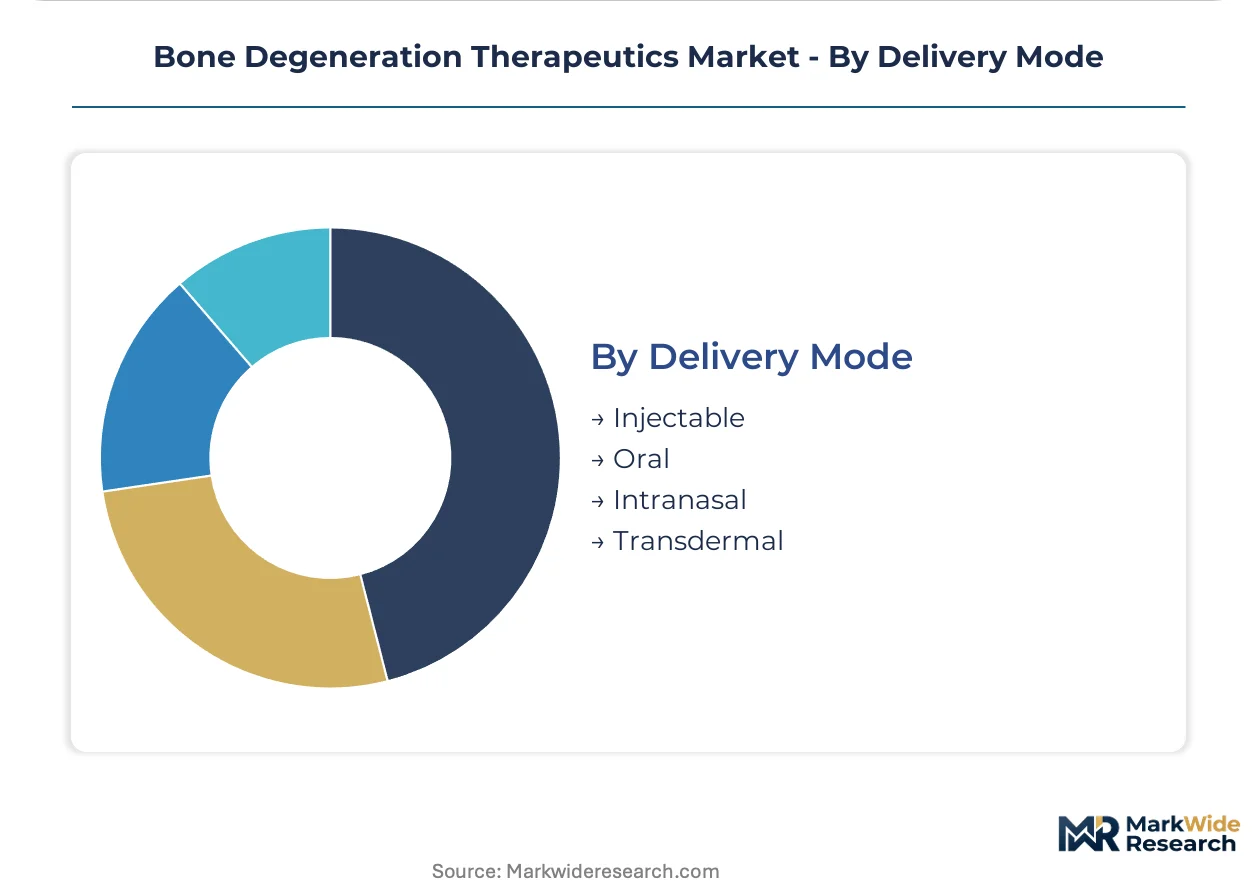
- Injectable:Subcutaneous and intravenous formulations achieving superior bioavailability for large-molecule therapeutics. Six-monthly denosumab and daily teriparatide injections dominate United States orthopedic clinic prescribing.
- Oral:Weekly or monthly bisphosphonate tablets requiring fasting protocols and esophageal safety precautions. India, Brazil, and Mexico retail pharmacy volumes rely on ambient storage distribution.
- Intranasal:Calcitonin spray formulations offering non-invasive administration for specific patient populations. Limited efficacy data constrains formulary placement.
- Transdermal:Experimental patch delivery systems under development for peptide hormone analogs. No commercial products currently approved by FDA or EMA.
Injectable modalities capture biologic premium, with oral administration retaining emerging market penetration advantage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The bone degeneration therapeutics industry traces its commercial origins to Swiss pharmaceutical innovation in calcitonin extraction during the 1960s, with subsequent scale-up occurring through North American biotechnology corridors and Japanese peptide synthesis clusters.
United States
Medicare Part B and Part D reimbursement sustains high procedure volumes for osteoporotic interventions across ambulatory surgical centers. FDA's accelerated approval framework for biologics reshapes how osteoclast inhibitors enter commercial distribution. Orthopedic clinic chains in Texas, Florida, and California concentrate infusion center capacity for parenteral biologic administration.
Germany
Biologic administration infrastructure embedded in orthopedic clinic chains drives demand for denosumab across the country's statutory health insurance system. EMA biosimilar pathway streamlines market authorization for follow-on biologics and expands patient access. Manufacturing scale requirements limit monoclonal antibody production to Western European contract manufacturing organizations clustered in the Rhine-Ruhr region.
Japan
Bone mineral density screening penetration exceeds Western benchmarks, driving preventive intervention demand for osteopenia treatments. PMDA's distinct regulatory framework for next-generation anabolic therapies offers faster market entry for novel osteoblast-stimulating compounds. Kaken Pharmaceutical Co. Ltd. anchors domestic peptide synthesis capabilities in Tokyo-Osaka pharmaceutical corridors.
United Kingdom
Fracture liaison services drive screening-to-treatment conversion in National Health Service-eligible populations. NHS England's specialized commissioning frameworks determine biologic access through integrated care systems. London and Manchester orthopedic networks prioritize therapies with demonstrable fracture-reduction outcomes.
India
Retail pharmacy volumes rely on ambient storage distribution of oral bisphosphonates where cold-chain infrastructure remains limited. CDSCO regulatory pathways for biosimilar monoclonal antibodies are evolving to accommodate domestic manufacturing scale-up. Mumbai and Hyderabad pharmaceutical clusters expand generic alendronate production for emerging market export.
Bone Degeneration Therapeutics Market Vendor Landscape
The competitive structure tilts toward integrated pharmaceutical-device conglomerates with manufacturing scale advantages. Large-cap biologics manufacturers and orthopedic implant specialists form a tiered vendor base with divergent margin structures. Three archetypes dominate: mammalian cell culture scale players, drug-device convergence specialists, and peptide synthesis innovators. Capacity expansion and strategic partnerships constitute the dominant competitive moves as firms seek to lock in hospital purchasing decisions.
Among North American biologics manufacturers, Amgen Inc. exemplifies the scale-driven archetype through established manufacturing infrastructure. Medtronic Plc and Stryker Corporation occupy positions within the drug-device convergence tier, anchoring competitive positioning through orthopedic implant integration with pharmaceutical delivery systems. These three entities represent distinct strategic vectors within a market where manufacturing concentration and surgeon training networks determine commercial access.
| Leading Market Players |
|---|
| Amgen Inc. |
| Medtronic Plc |
| Stryker Corporation |
| Zimmer Biomet |
| Fate Therapeutics Inc. |
| Juventus Therapeutics Inc. |
| Se-cure Pharmaceuticals Ltd. |
| Kaken Pharmaceutical Co. Ltd. |
| NuVasive Inc. |
| Others |
Supply Flow & Price Mechanics
Biologic-oral divergence separates premium monoclonal antibody therapies from commodity bisphosphonate salts, with this bifurcation manifesting in both reimbursement-tier pricing and cold-chain dependency across distribution networks. Injectable denosumab commands hospital formulary placement through bundled administration fees, while ambient-storage alendronate penetrates retail pharmacy channels where infrastructure constraints preclude refrigerated logistics.
Pricing Analysis
Biologic administration bundles versus unbundled pharmaceutical-only reimbursement create the dominant pricing split across institutional buyers. Three-tier pricing structure across premium, standard, and economy levels aligns with FDA approval pathway, manufacturing origin, and clinical endpoint differentiation. Pricing pressure stems from Medicare Advantage risk-bearing entities prioritizing fracture-reduction outcomes over mechanism premiums. Hospital procurement departments exhibit highest price sensitivity through GPO consolidation, while specialty orthopedic clinics retain willingness to pay for surgeon training lock-in.
Supply Chain Analysis
Domestic-content mandates in India's PLI scheme and China's biopharmaceutical self-sufficiency policies are reshaping mammalian cell culture sourcing for contract manufacturing organizations. Active pharmaceutical ingredient production draws from India, China, and Ireland, while fill-finish capacity clusters in the United States, Germany, and Singapore. Supply chain risk centers on single-source vulnerability for recombinant protein production in North American facilities. Distribution runs through cold-chain logistics partners serving hospital infusion centers and specialty clinic chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bone degeneration therapeutics market functions as a stable compounder anchored by irreversible demographic shifts toward aging populations requiring chronic skeletal intervention. Medicare reimbursement durability and recurring administration protocols generate predictable revenue streams resistant to cyclical disruption.
For Market Incumbents: Anticipate biosimilar entry by securing manufacturing scale advantages in North American mammalian cell culture facilities and deepening surgeon training network lock-in across integrated delivery networks. EMA biosimilar pathway acceleration in European Union member states threatens originator pricing power; defend through orthopedic implant-pharmaceutical convergence and extended-interval formulation patents.
For New Entrants and Emerging Players: Enter via Japan PMDA anabolic pathway for novel osteoblast-stimulating compounds, leveraging faster regulatory timelines versus FDA cardiovascular safety monitoring requirements. Rural United States secondary care markets show significant bone mineral density screening gaps; penetrate through remote patient adherence platforms and telemedicine-supported home injection protocols.
For Investors and Strategic Acquirers: Consolidation pressure builds where drug-device combination capabilities fragment across pure pharmaceutical and pure orthopedic implant vendors. Five-to-ten year viability favors integrated platforms with captive biologic manufacturing and spinal delivery system integration. Watch FDA pharmacovigilance mandate expansion as inflection signal for development timeline compression or extension.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Amgen's North American mammalian cell culture infrastructure secures denosumab supply continuity against regional disruption. |
| Regulatory Approval Pathway | Japan PMDA anabolic framework accelerates novel osteoblast stimulator entry versus FDA extended cardiovascular monitoring. |
| Hospital System Partnership | Medtronic's orthopedic implant integration locks in pharmaceutical delivery system purchasing across GPO contracts. |
| Pipeline Diversification | Long-acting injectable formulations reduce infusion center overhead while expanding adherence-driven volume capture. |
| Licensing Agreement | EMA biosimilar pathway enables follow-on biologic authorization expanding European patient access to RANKL inhibitors. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare reimbursement databases. Bottom-up patient-volume modeling and top-down pharmaceutical revenue triangulation cross-verified segment-level estimates.
Segment-weighting approaches distributed value across therapeutic modality, delivery infrastructure dependency, application severity, and end-user procurement authority. Treatment line, administration route, and regional regulatory cluster dimensions structured the analytical framework across the projection horizon. CAGRs derived from patient population growth, procedure volume trends, and pricing trajectory assumptions specific to biologic versus small-molecule competitive dynamics.
Inputs from FDA, EMA, and PMDA regulatory filings were available through the study window; gaps in real-time biosimilar approval timelines and post-market surveillance outcome data introduce uncertainty bands around competitive share shift assumptions. Forecasts reflect documented assumptions regarding Medicare reimbursement stability and cold-chain infrastructure expansion rates. A small set of triggers—pharmacovigilance mandate expansion, MDR conformity assessment timeline resolution, and PLI scheme manufacturing scale-up—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Drug-Induced Dyskinesia Market
Pharmaceuticals
Recombinant Plasma Protein Therapeutics Market
Pharmaceuticals
Trisenox Market
Pharmaceuticals
Testosterone Nasal Gels Market
Pharmaceuticals
Japan Generic Drug Market
Pharmaceuticals
Stye Drug Market
Pharmaceuticals
Propofol Market
Pharmaceuticals
Non-Alcoholic Steatohepatitis (NASH) Therapeutics and Diagnostics Market
Pharmaceuticals
North America Glucagon-Like Peptide-1 Agonists Market
Pharmaceuticals
Brain Tumor Drugs Market
Pharmaceuticals
Australia Pharmaceuticals Market
Pharmaceuticals
Meperidine Market
Pharmaceuticals
Global Postpartum Depression Drugs Market
Pharmaceuticals
Carbetocin Injection Market
Pharmaceuticals
Asia-Pacific Fatty Bases for Suppositories Market
Pharmaceuticals
Global Rotavirus Vaccine Market