
 Opioid Analgesics Market | 2026-2036
Opioid Analgesics Market Size, Share, and Industry Trends Forecast 2026-2036
Opioid Analgesics Market Outlook
The FDA's Risk Evaluation and Mitigation Strategy for extended-release and long-acting opioids is repositioning how manufacturers structure distribution and prescriber education programs. Purdue Pharma L.P. leverages its historical dominance in extended-release oxycodone formulations to sustain formulary access despite litigation headwinds. Hikma Pharmaceuticals PLC anchors its competitive position through generic injectable opioid portfolios across regulated markets. Pfizer Inc. differentiates via its hospital-channel focus and controlled-substance logistics infrastructure.
Opioid analgesics are synthetic and semi-synthetic compounds that bind to mu, kappa, or delta opioid receptors to modulate nociceptive signaling, with potency varying from weak agonists like codeine to high-potency synthetic fentanyl analogues measured in microgram doses. These agents serve as foundational therapy for moderate-to-severe pain management across surgical, oncologic, and palliative care settings where non-opioid modalities prove inadequate. Morphine retains the largest volume share among product types due to its established WHO Essential Medicines status and universal reimbursement, while fentanyl transdermal patches command premium positioning in chronic cancer pain where patient compliance drives selection. Intravenous administration routes dominate hospital revenue pools, though sublingual and buccal formulations are gaining traction in ambulatory and home-based palliative care where oral intake is compromised.
The Drug Enforcement Administration's production quota system for Schedule II substances directly constrains annual manufacturing volumes and creates allocation scarcity that shapes competitive dynamics. The European Medicines Agency's pharmacovigilance requirements and the FDA's class-wide labeling updates for neonatal opioid withdrawal syndrome impose escalating post-market surveillance burdens on all marketed products. Stakeholders must monitor how the Centers for Medicare and Medicaid Services' opioid prescribing limits for Medicare Part D beneficiaries will reshape demand patterns for long-acting formulations versus short-acting alternatives.
Market Dynamics
The FDA's Risk Evaluation and Mitigation Strategy for extended-release opioids is compressing prescriber autonomy and forcing manufacturers to rebuild distribution infrastructure around closed pharmacy networks and patient registries.
Growth Catalysts
- Palliative care expansion:Hospital systems across the United States are embedding dedicated pain management units into oncology and hospice services, creating institutional demand for controlled-release morphine and transdermal fentanyl.
- DEA Schedule II quota mechanics:The Drug Enforcement Administration's annual production allotment system creates predictable scarcity that sustains pricing power for manufacturers with secured raw material streams.
- Home-based care migration:Discharge protocols favoring sublingual and buccal formulations over intravenous delivery are opening ambulatory revenue pools previously captured by infusion centers.
Market Restraints
- Active pharmaceutical ingredient concentration:Synthetic opioid precursor manufacturing clusters in a narrow band of Indian and Chinese chemical producers, exposing supply chains to single-point disruption.
- Neonatal opioid withdrawal syndrome labeling:The FDA's class-wide boxed warning mandates impose costly post-market surveillance obligations and restrict promotional claims for obstetric applications.
- Non-opioid analgesic substitution:Gabapentinoids and selective nerve blocks are capturing post-surgical pain management protocols previously dominated by short-acting oxycodone.
Strategic Opportunities
- Abuse-deterrent formulation mandates:State-level prescription drug monitoring program integration with electronic health records creates procurement preference for tablets with physical or chemical barriers to manipulation.
- Long-acting injectable platforms:Depot formulations extending dosing intervals to monthly or quarterly intervals address compliance gaps in chronic cancer pain where oral regimens fail.
- Canada's controlled substance exemption pathways:Health Canada's streamlined access mechanisms for palliative patients present regulatory arbitrage potential for manufacturers with established REMS infrastructure.
Industry Challenges
- Specialized pharmacovigilance staffing:REMS compliance requires dedicated teams capable of adverse event signal detection and prescriber re-education, creating talent competition with broader biopharma safety operations.
- Cold chain integrity for transdermal patches:Fentanyl matrix stability demands temperature-controlled logistics that strain distribution networks serving rural and remote dispensing sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Opioid Analgesics Market |
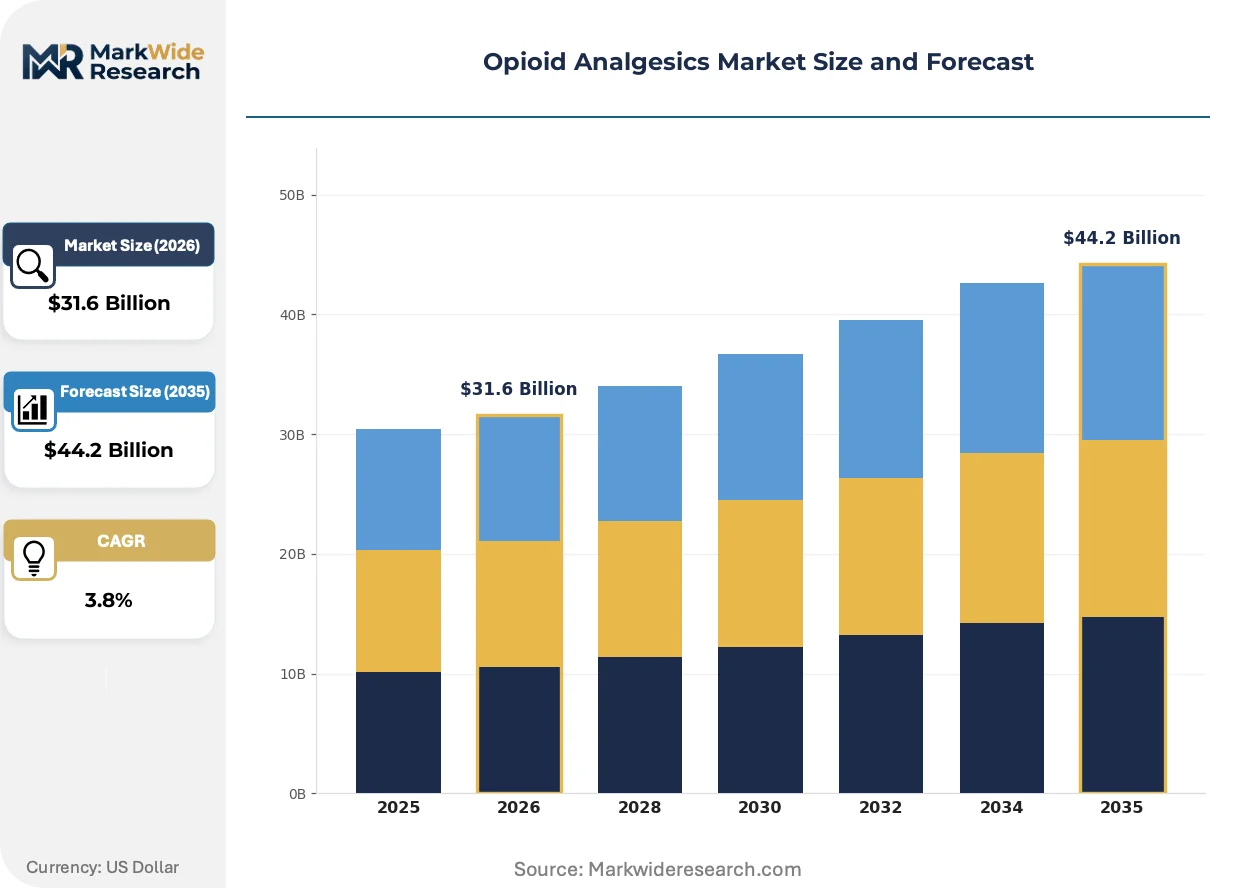
| Market Size in 2026 | $31.6 Billion |
| Market Size in 2035 | $44.2 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Morphine, Oxycodone, Fentanyl, Codeine Administration Route: Oral, Transdermal, Intravenous, Sublingual Indication: Post-Surgical Pain, Cancer Pain, Chronic Pain, Acute Pain Patient Type: Geriatric, Pediatric, Adult, Oncology |
| Companies Covered | Purdue Pharma L.P., Hikma Pharmaceuticals PLC, Pfizer Inc., AbbVie Inc., Sanofi, Sun Pharmaceutical Industries Ltd, Mallinckrodt Pharmaceuticals, Amneal Pharmaceuticals Inc., Teva Pharmaceuticals Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Opioid Analgesics Market Strategic Shifts
Formulation science and regulatory architecture are converging to reshape how opioid analgesics reach patients, with three distinct vectors altering competitive positioning.
Implantable drug delivery systems are decentralizing chronic pain management from institutional settings to ambulatory environments. These reservoir-based devices release morphine or hydromorphone at programmed rates over months. Pain management clinics in the United States are adopting them for refractory cancer patients with compromised gastrointestinal function. The technology is decentralizing hospital revenue capture and compressing margins for infusion service lines.
REACH authorization requirements for synthetic opioid precursors are tightening documentation burdens on European manufacturers. The European Chemicals Agency's substance evaluation process now demands full lifecycle environmental assessments for fentanyl analogues. German and French formularies are responding by narrowing preferred product lists to suppliers with verified green chemistry credentials. This regulatory friction is advantaging integrated manufacturers with in-house active pharmaceutical ingredient synthesis.
Hospital purchasing consortiums are consolidating procurement authority for controlled substances under centralized pharmacy and therapeutics committees. These bodies now mandate therapeutic interchange protocols that override individual prescriber preferences for specific brands. The concentration of buying power is most visible in United States health systems exceeding five hundred beds, where generic morphine sulfate has displaced branded extended-release alternatives through mandatory substitution algorithms.
Opioid Analgesics Market Segmentation
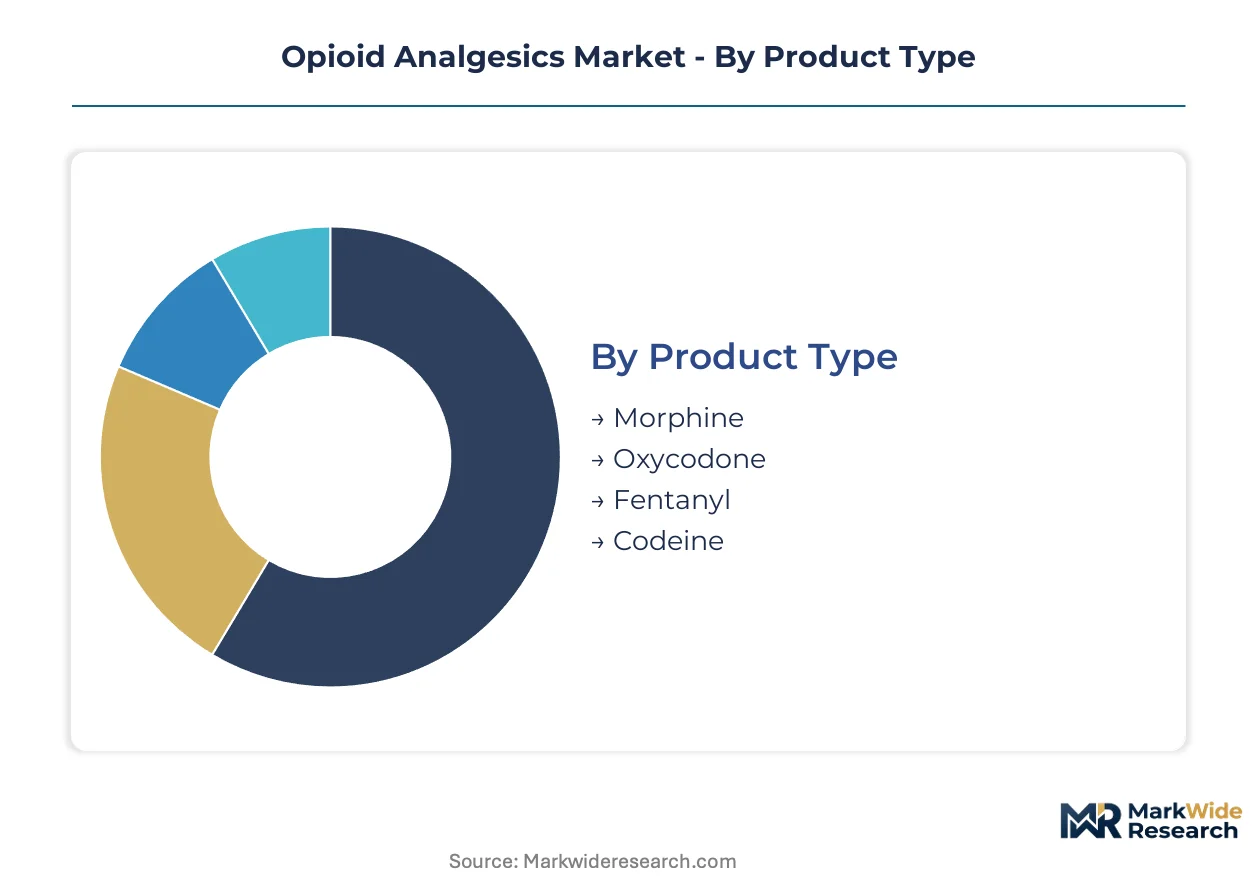
Opioid analgesics demand fragments across pharmacological potency tiers, delivery mechanisms, and care settings where reimbursement rules and prescriber training determine formulary access. Understanding how these dimensions intersect reveals where manufacturers must align formulation investments with institutional procurement protocols.
Product Type:
Standardization dominates at the commodity end while specialized synthesis commands premium positioning in high-potency synthetics.
- Morphine:The WHO Essential Medicines anchor binds to mu-opioid receptors with established equianalgesic dosing protocols. United States hospital formularies favor morphine sulfate for general medical floors where nursing familiarity reduces medication errors. DEA production quotas for thebaine-derived alkaloids constrain supply elasticity.
- Fentanyl:Synthetic phenylpiperidine structure delivers analgesia at microgram potency requiring precision manufacturing infrastructure. Transdermal matrix patches dominate palliative home care in Germany and France where patient compliance outweighs acquisition cost. Cold chain requirements limit rural distribution reach.
- Oxycodone:Semi-synthetic thebaine derivative with higher oral bioavailability than morphine, driving extended-release tablet development for chronic non-malignant pain protocols.
- Codeine:Weak mu-agonist prodrug metabolized by CYP2D6, restricting utility in populations with genetic polymorphism prevalence above 10 percent.
Leading the category by volume: Morphine. Expanding most quickly: Fentanyl transdermal systems in European palliative networks.
Administration Route:
Cost tier separation emerges between institutional infusion services and ambulatory self-administration platforms.
- Intravenous:Direct plasma concentration control in perioperative and critical care settings where titration speed determines safety margins. United States academic medical centers anchor demand through surgical volume concentration in metropolitan hospital systems. Anesthesiology department formulary control limits manufacturer switching costs.
- Transdermal:Reservoir or matrix patches bypass first-pass hepatic metabolism for steady-state plasma levels over 72-hour intervals. Oncology outpatient clinics in Canada prioritize fentanyl patches for patients with compromised gastrointestinal absorption. Health Canada's special access program streamlines palliative exemptions.
- Oral:Immediate and extended-release tablets dominate prescription volume through pharmacy benefit manager tiered formularies with prior authorization gates.
- Sublingual:Buccal absorption addresses breakthrough pain in patients unable to tolerate oral intake, gaining traction in hospice discharge protocols.
Highest revenue per dose: Transdermal systems. Steepest volume expansion: Sublingual formulations in home-based palliative transitions.
Indication:
Application severity determines whether reimbursement supports branded extended-release or mandates generic substitution.
- Cancer Pain:WHO analgesic ladder mandates opioid escalation for moderate-to-severe malignant pain, securing reimbursement protection for long-acting formulations. United States National Comprehensive Cancer Network guidelines drive institutional prescribing patterns. Oncology practice consolidation strengthens group purchasing organization negotiating leverage.
- Post-Surgical Pain:Acute episode duration limits therapy to short-acting agents with discharge protocols increasingly favoring multimodal non-opioid regimens. Enhanced Recovery After Surgery protocols in German university hospitals reduce opioid consumption per procedure. Payer bundled payment models compress per-case analgesic budgets.
- Chronic Pain:Non-malignant indications face prescriber registration requirements and prescription drug monitoring program integration that slow initiation rates.
- Acute Pain:Emergency department and trauma settings prioritize rapid onset intravenous agents with short half-lives for titration safety.
Defending branded pricing: Cancer Pain through guideline-protected status. Facing substitution pressure: Post-Surgical Pain from protocol-driven non-opioid alternatives.
Patient Type:
Maturity differentiation separates established adult protocols from specialized pediatric and geriatric pharmacokinetic requirements.
- Geriatric:Reduced hepatic clearance and polypharmacy interaction risks demand dose reduction algorithms and active metabolite monitoring. Medicare Part D opioid prescribing limits in the United States reshape long-acting versus short-acting selection. Medication therapy management programs mandate pharmacist review for beneficiaries exceeding defined daily doses.
- Oncology:Disease progression and treatment toxicity create dynamic pain trajectories requiring rapid regimen adjustment. Palliative care embedded within United States cancer centers drives coordinated pain management with dedicated nurse navigator support. Hospice election triggers distinct Medicare reimbursement for comfort-focused analgesia.
- Adult:General population protocols balance efficacy against abuse potential through prescription drug monitoring program checks and pill quantity limits.
- Pediatric:Neonatal opioid withdrawal syndrome labeling restrictions and limited formulation availability constrain market development outside specialized children's hospitals.
Concentrating regulatory scrutiny: Geriatric through federal benefit program limits. Requiring specialized infrastructure: Oncology via embedded palliative service integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of synthetic opioid precursors clusters in Indian and Chinese chemical manufacturing zones, while consumption concentrates in North American and European hospital systems with established palliative care infrastructure.
United States
Oncology treatment volumes and chronic pain prevalence sustain the world's largest consumption base for extended-release formulations. The FDA's Risk Evaluation and Mitigation Strategy for transmucosal fentanyl products mandates closed pharmacy networks and patient registries that reshape distribution protocols. Academic medical centers in Boston and Houston anchor demand through embedded palliative care units.
Germany
Hospital purchasing consortiums concentrate procurement authority under centralized pharmacy and therapeutics committees exceeding five hundred beds. The EMA's pharmacovigilance requirements for neonatal opioid withdrawal syndrome impose post-market surveillance burdens on all marketed products. University hospitals in Bavaria and North Rhine-Westphalia drive therapeutic interchange protocols favoring generic morphine sulfate.
Canada
Health Canada's streamlined access mechanisms for palliative patients present regulatory arbitrage potential for manufacturers with established REMS infrastructure. The special access program accelerates fentanyl patch approvals for oncology outpatients with compromised gastrointestinal absorption. Toronto and Vancouver hospital systems lead formulary adoption of sublingual formulations for home-based care transitions.
France
ANSM oversight of controlled substance distribution maintains strict allocation tracking that limits parallel trade. The country's pharmacovigilance network mandates adverse event signal detection for all long-acting opioid prescriptions exceeding defined daily doses. Parisian cancer centers coordinate with regional hospice networks to standardize breakthrough pain protocols.
India
Active pharmaceutical ingredient manufacturing for thebaine-derived alkaloids concentrates in Hyderabad and Ahmedabad chemical zones. CDSCO regulation of Schedule II substance quotas constrains annual manufacturing volumes and creates allocation scarcity. Domestic consumption remains limited by restricted palliative care infrastructure outside major metropolitan hospital systems.
Opioid Analgesics Market Competitive Environment
The competitive structure tilts toward litigation-exposed originators defending formulary access against generic injectable specialists and hospital-channel logistics operators. Three archetypes dominate: extended-release formulation patent holders, vertically integrated API-to-dosage manufacturers, and controlled-substance distribution infrastructure providers. Competitive moves concentrate on REMS compliance infrastructure rebuilding and abuse-deterrent formulation development.
Among litigation-facing originators, Purdue Pharma L.P. occupies a position exemplifying extended-release oxycodone formulary defense. Hikma Pharmaceuticals PLC and Pfizer Inc. anchor the generic injectable and hospital-channel logistics archetypes respectively. These three represent the dominant competitive vectors shaping procurement authority consolidation and closed-network distribution requirements.
| Leading Market Players |
|---|
| Purdue Pharma L.P. |
| Hikma Pharmaceuticals PLC |
| Pfizer Inc. |
| AbbVie Inc. |
| Sanofi |
| Sun Pharmaceutical Industries Ltd |
| Mallinckrodt Pharmaceuticals |
| Amneal Pharmaceuticals Inc. |
| Teva Pharmaceuticals Inc. |
| Others |
Value Chain & Pricing Dynamics
Implantable drug delivery systems are displacing hospital infusion services and simultaneously compressing margins for institutional suppliers while elevating pricing power for manufacturers with reservoir-based platform control. This technology transition concentrates procurement authority in pain management clinics that negotiate directly with device suppliers, bypassing traditional pharmacy and therapeutics committees.
Pricing Analysis
Cost-down pressure on extended-release formulations accelerates because hospital purchasing consortiums mandate therapeutic interchange protocols favoring generic morphine sulfate. Three-tier pricing structure across abuse-deterrent branded tablets, standard generic equivalents, and economy-tier injectables reflects FDA REMS compliance costs and DEA quota scarcity. Price differentiation hinges on certification tier for closed distribution networks and cold chain logistics capability. Oncology outpatient clinics demonstrate lowest price sensitivity due to guideline-protected reimbursement, while post-surgical acute care segments face maximum substitution pressure from multimodal non-opioid protocols.
Supply Chain Analysis
Single-source vulnerability sits with Chinese and Indian chemical manufacturers controlling synthetic fentanyl precursor production. Active pharmaceutical ingredient synthesis draws from thebaine-derived alkaloid streams concentrated in Hyderabad and Ahmedabad chemical zones, with finished dosage form manufacturing anchored in United States and German facilities. Tariff exposure on Schedule II substance imports from Asia threatens raw material cost stability. Distribution runs through DEA-registered closed pharmacy networks with patient registry integration for transmucosal products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The opioid analgesics sector is transitioning from oral tablet dominance toward long-acting injectable and implantable platforms that alter how manufacturers capture value across care settings.
For Market Incumbents: Deepen backward integration into active pharmaceutical ingredient synthesis to secure DEA quota allocations and buffer against Indian and Chinese supply concentration. Invest in REMS-compliant logistics infrastructure to defend formulary access against generic injectable specialists. Litigation-exposed originators must prioritize abuse-deterrent formulation pipelines to sustain procurement preference under state-level prescription drug monitoring program integration. For New Entrants and Emerging Players: Enter via Health Canada's special access program for palliative care exemptions, leveraging streamlined regulatory pathways that reward established REMS infrastructure. Target sublingual and buccal formulation gaps in home-based hospice discharge protocols where oral intake is compromised. Pursue hospital system partnerships for embedded pain management unit contracts rather than pharmacy benefit manager tiered formulary battles. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated manufacturers with in-house API synthesis given REACH authorization tightening and ECHA environmental assessment requirements for fentanyl analogues. Long-term viability favors archetypes controlling both precursor supply and finished dosage form REMS compliance infrastructure. Monitor Health Canada exemption approval velocity as inflection indicator for ambulatory care transition momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Abuse-Deterrent Formulation Development | FDA REMS mandates drive procurement preference for physical barrier tablets in United States hospital systems. |
| Long-Acting Injectable Platform Launch | Depot formulations address compliance gaps in oncology palliative care where oral regimens fail. |
| REMS Infrastructure Investment | Closed pharmacy networks and patient registries satisfy FDA distribution controls for transmucosal fentanyl. |
| Backward Integration into API Synthesis | In-house thebaine-derived alkaloid production secures DEA quota allocation against supply scarcity. |
| Canada Special Access Program Entry | Health Canada streamlined mechanisms reward manufacturers with established risk evaluation infrastructure. |
Study Parameters
FDA filings, EMA pharmacovigilance databases, and ClinicalTrials.gov formed the secondary backbone, supplemented by DEA production quota records and hospital procurement database analysis. Primary interviews with formulary directors, pain management clinicians, regulatory affairs leads, and controlled-substance distribution specialists combined with secondary validation through bottom-up and top-down triangulation approaches.
Bottom-up modeling aggregated segment-level demand across product type, administration route, indication severity, and patient population dimensions, while top-down cross-checks validated aggregate market scale against macro healthcare expenditure trends. CAGRs were derived from fitted growth curves across the projection horizon, incorporating oncology treatment volume trajectories, palliative care expansion rates, and regulatory enforcement intensity as opioid-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under DEA quota policy shifts, REACH authorization delays for synthetic precursors, and accelerated non-opioid substitution in post-surgical protocols. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Viscosupplementation Market
Pharmaceuticals
Global Rotavirus Vaccine Market
Pharmaceuticals
Lipid Injectable Market
Pharmaceuticals
Oral Antibiotics Market
Pharmaceuticals
Global DNA Repair Drugs Market
Pharmaceuticals
Global Oxytocic Pharmaceuticals Market
Pharmaceuticals
Middle-East and Africa Meglitinide Market
Pharmaceuticals
Global Lyophilized Injectable Drugs Market
Pharmaceuticals
Chronic Obstructive Pulmonary Disease Drugs Market
Pharmaceuticals
Global Colorectal Cancer Therapeutics Market
Pharmaceuticals
Global Fluorouracil (5FU) Market
Pharmaceuticals
Anti-Inflammatory Drugs Market
Pharmaceuticals
Global Immune Checkpoint Inhibitors Market
Pharmaceuticals
Antithrombin Market
Pharmaceuticals
Middle-East and Africa Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Methylphenidate Hydrochloride Market