
 Mexico Dimenhydrinate Market | 2026-2036
Mexico Dimenhydrinate Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Dimenhydrinate Market Foresight
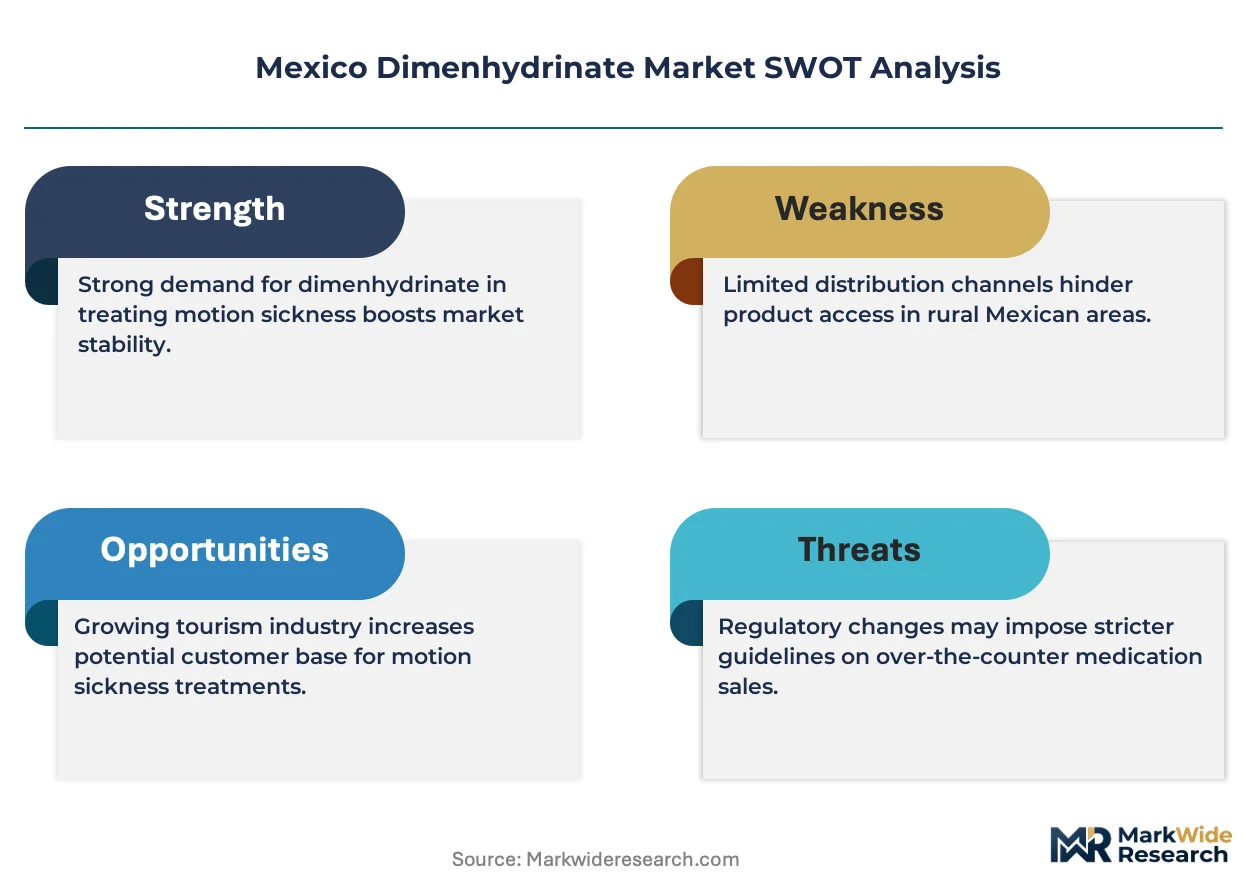
COFEPRIS updated Good Manufacturing Practice guidelines is repositioning the cost-of-entry calculus for dimenhydrinate suppliers seeking Mexican market access. Pfizer leverages its established manufacturing footprint to sustain bulk tablet supply contracts with public hospital networks. Bayer anchors its position through brand recognition in the over-the-counter motion sickness segment. PISA competes aggressively on price in the generic injectable category, particularly for clinic-based vertigo treatment protocols.
Dimenhydrinate is a first-generation ethanolamine antihistamine composed of diphenhydramine and 8-chlorotheophylline in a 1:1 salt ratio, manufactured through direct compression or wet granulation methods for oral solid dosage forms, with primary commercial purpose as an antiemetic and antivertigo agent. Tablet formulations dominate hospital and pharmacy channels due to dosing precision and extended shelf stability, while liquid forms serve pediatric and geriatric populations where swallowing difficulties limit solid dosage adoption. Injectable dimenhydrinate occupies a narrower but higher-margin niche in emergency departments and surgical recovery units where rapid onset is clinically essential.
COFEPRIS maintains centralized control over pharmaceutical registration, import licensing, and post-market surveillance, with specific bioequivalence requirements for generic dimenhydrinate variants that filter substandard products from institutional tenders. Mexico's Secretaría de Salud procurement frameworks prioritize suppliers demonstrating uninterrupted cold-chain documentation and validated stability data under tropical climate conditions. Stakeholders must monitor evolving pharmacovigilance reporting obligations and local production incentives as determinants of long-term competitive positioning in this market.
Market Dynamics
COFEPRIS bioequivalence enforcement is compressing supplier margins while elevating quality thresholds for dimenhydrinate registration, forcing reformulation investments and documentation upgrades across the Mexican pharmaceutical value chain.
Growth Catalysts
- Hospital Infrastructure Modernization:Mexico's Secretaría de Salud procurement frameworks prioritize antiemetic therapies for expanded surgical capacity in tertiary care centers.
- COFEPRIS GMP Harmonization:Updated manufacturing guidelines align Mexican standards with ICH protocols, accelerating approval timelines for compliant API suppliers.
- Motion Sourism Corridors:Coastal tourism routes through Cancún and Los Cabos sustain over-the-counter demand for vertigo and nausea prophylaxis.
Market Restraints
- API Import Dependency:Active pharmaceutical ingredient supply concentrates in Asian manufacturing clusters, exposing Mexican formulators to freight volatility and customs delays.
- Substitution by 5-HT3 Antagonists:Ondansetron and granisetron encroach on post-operative antiemetic protocols in insured patient populations.
- Cold-Chain Validation Costs:Tropical climate stability requirements demand accelerated degradation studies that extend registration timelines by 8-14 months.
Strategic Opportunities
- Pediatric Liquid Formulation Gap:Underpenetrated segments in rural Jalisco and Puebla states lack age-appropriate dosing alternatives to adult tablets.
- Vertigo Clinic Networks:Specialized neurology outpatient centers in Monterrey and Tijuana create pull for injectable dimenhydrinate protocols.
- Local Production Incentives:PROSEC and IMMEX programs reduce tariff exposure for manufacturers establishing formulation facilities in Baja California or Querétaro.
Industry Challenges
- Pharmacovigilance Reporting Capacity:Post-market adverse event documentation requirements strain quality assurance teams at mid-sized generic houses.
- Legacy ERP Integration:Serialization mandates for track-and-trace compliance collide with outdated inventory management systems in regional distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Dimenhydrinate Market |
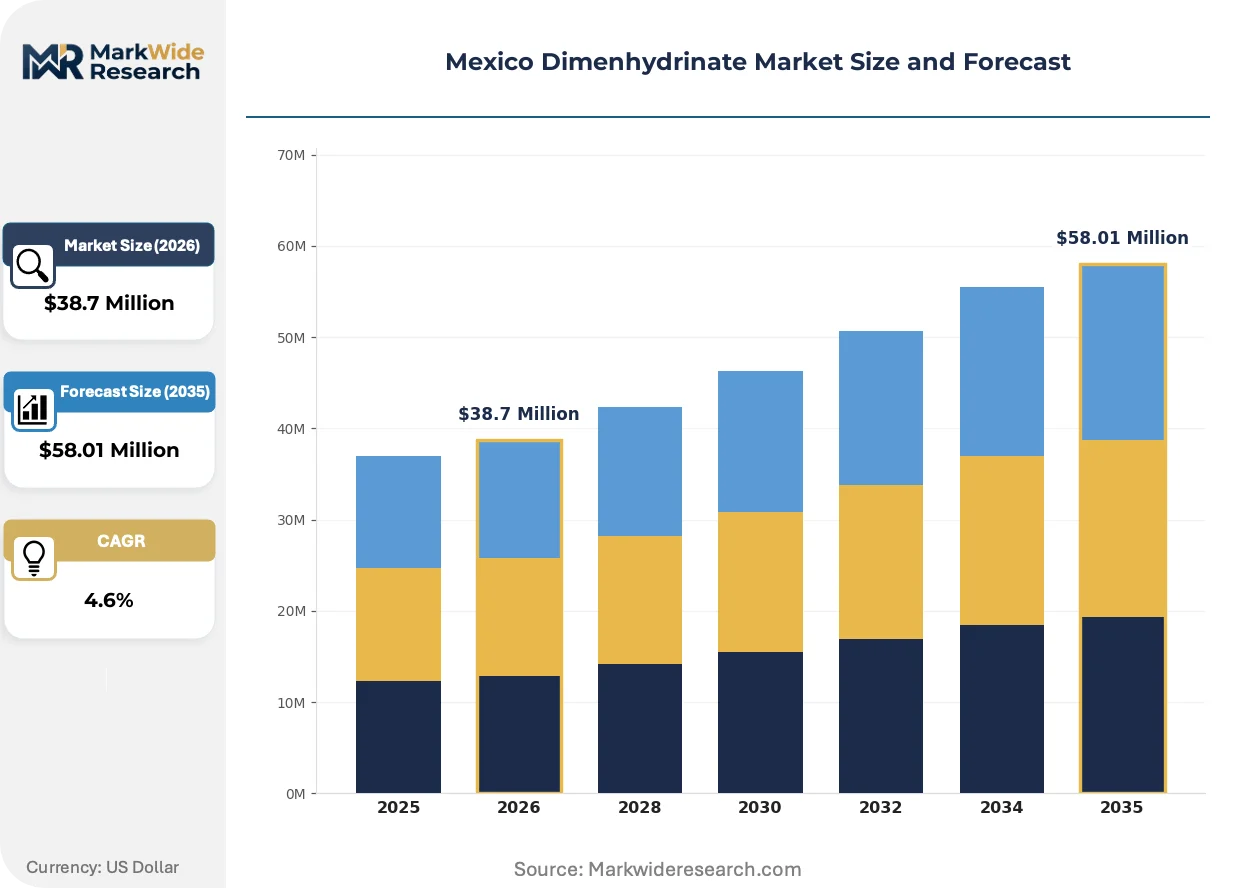
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $58.01 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Liquid Form, Injectable End User: Hospitals, Pharmacies, Clinics, Home Care Distribution Channel: Online, Retail, Wholesale, Direct Sales Application: Nausea Relief, Motion Sickness, Vertigo, Allergy Treatment |
| Companies Covered | Johnson & Johnson SA de CV, Pfizer, Bristol-Myers Squibb, Bayer, Novartis, Teva, Fresenius, Apotex, PISA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Dimenhydrinate Market Shifts & Advancements
Reformulation science and regulatory digitization are converging to reshape competitive positioning in Mexican antiemetic supply, with quality infrastructure investments separating sustainable operators from registration-dependent traders.
Orally disintegrating tablet technology is expanding into pediatric and geriatric care pathways where swallowing dysfunction limits conventional solid dosage adoption. Hospital pharmacies in Mexico City metropolitan clusters are piloting these formulations for pre-operative anxiety protocols. The technology is expanding into home-care discharge bundles, compressing the addressable market for standard coated tablets in chronic vertigo management.
COFEPRIS centralized pharmacovigilance database mandates real-time adverse event reporting through digital portals, eliminating paper-based submission pathways. Generic manufacturers face elevated compliance infrastructure costs while gaining faster signal detection capabilities for batch-specific quality deviations. Injectable dimenhydrinate suppliers encounter the steepest adaptation curve due to higher-risk classification and expedited reporting thresholds.
Institutional procurement consolidation concentrates purchasing authority within state-level Secretaría de Salud tendering bodies, displacing fragmented hospital-by-hospital contracting. Group purchasing organizations in Jalisco and Nuevo León aggregate volume across multiple facilities, extracting price concessions in exchange for sole-source or dual-source supply commitments. This pattern is most visible in the ISSSTE and IMSS networks, where centralized formularies restrict approved supplier lists to three or fewer qualified manufacturers per therapeutic category.
Mexico Dimenhydrinate Market Segmentation
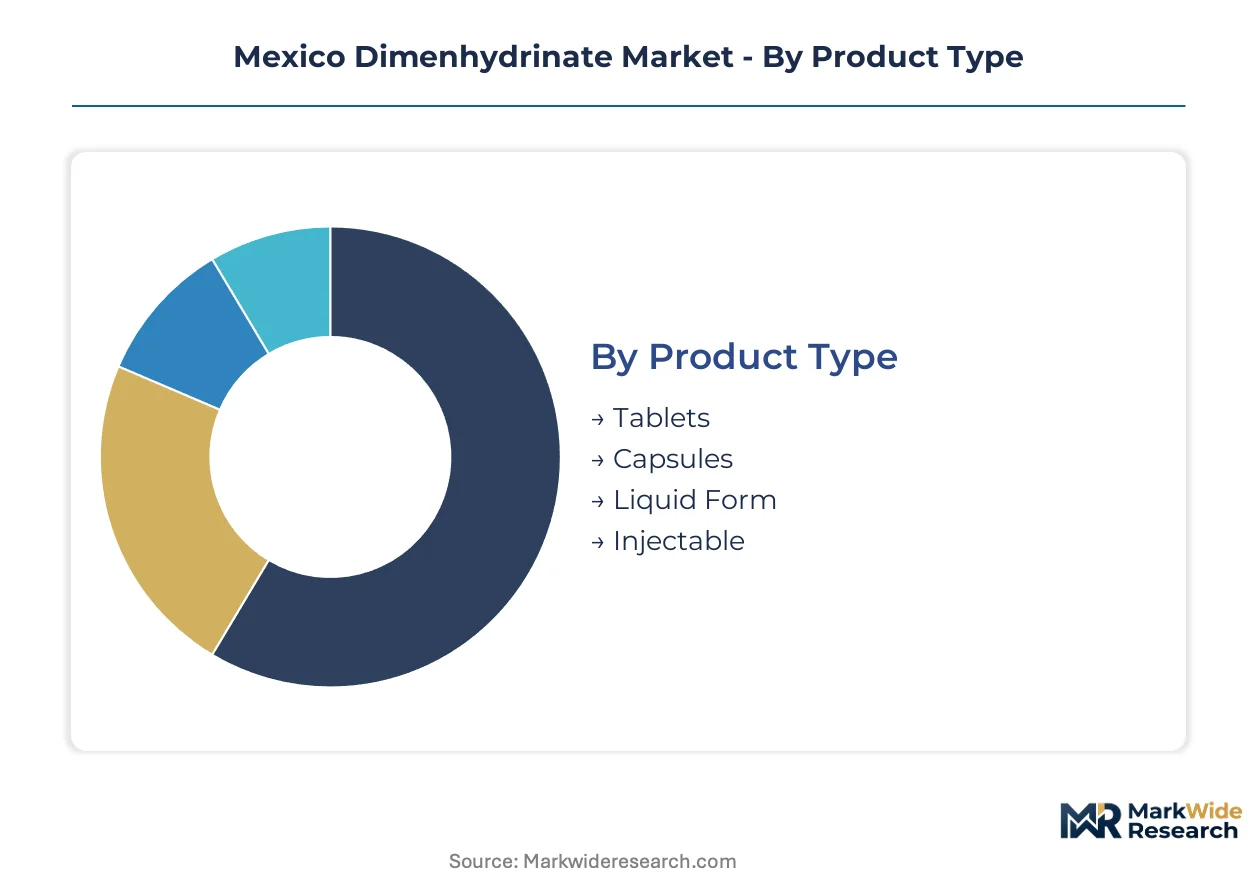
Dimenhydrinate demand fragments across formulation types, care settings, and therapeutic applications that each carry distinct regulatory and margin profiles. Understanding these segment boundaries clarifies where COFEPRIS compliance investments yield the highest returns versus where price competition dominates.
Product Type:
Standalone oral formulations serve chronic vertigo and routine antiemetic needs, while injectable and liquid variants embed into acute care protocols where rapid onset or swallowing limitations apply.
- Tablets:Compressed diphenhydramine-8-chlorotheophylline salts in 50mg standard doses dominate hospital formularies and retail pharmacy shelves across Mexico City and Guadalajara. Procurement consolidation within IMSS networks favors tablet suppliers with validated tropical stability data and uninterrupted cold-chain documentation.
- Liquid Form:Suspension and syrup presentations address pediatric populations in Jalisco and Puebla states where tablet administration fails. COFEPRIS bioequivalence requirements for generic liquids extend registration timelines, creating a formulation gap that branded manufacturers exploit.
- Capsules:Gelatin-encased variants offer taste masking for geriatric patients in home care settings. Demand concentrates in Monterrey's private clinic corridors.
- Injectable:Intravenous and intramuscular solutions occupy emergency departments and surgical recovery units. Higher-risk classification triggers expedited pharmacovigilance reporting thresholds.
Tablets lead volumes today; liquid form is gaining share fastest as pediatric protocols expand.
End User:
Institutional procurement authority concentrates purchasing decisions, while retail and home care channels fragment across regional distributor networks.
- Hospitals:Tertiary care centers in Mexico City metropolitan clusters anchor dimenhydrinate consumption through centralized Secretaría de Salud tenders. Surgical capacity expansion drives antiemetic protocol standardization.
- Clinics:Specialized neurology and gastroenterology outpatient centers in Monterrey and Tijuana generate pull for injectable protocols. Vertigo clinic networks prefer rapid-onset formulations.
- Pharmacies:Community and hospital pharmacy channels handle prescription fulfillment and over-the-counter motion sickness prophylaxis. ISSSTE centralized formularies restrict approved supplier lists.
- Home Care:Post-discharge bundles and chronic vertigo management shift dosing responsibility to patients and caregivers. Orally disintegrating tablet pilots are compressing standard coated tablet demand.
Hospitals anchor current procurement volumes; clinics show the steepest expansion trajectory as specialized outpatient networks proliferate.
Distribution Channel:
Channel selection determines serialization compliance burdens and working capital intensity, with digital pathways disrupting traditional wholesale hierarchies.
- Wholesale:Regional distributors with legacy ERP systems struggle against COFEPRIS track-and-trace mandates. Inventory management upgrades strain mid-sized generic houses.
- Retail:Pharmacy chains and independent dispensaries handle the majority of over-the-counter motion sickness sales along Cancún and Los Cabos tourism corridors.
- Direct Sales:Manufacturers with established manufacturing footprints in Baja California or Querétaro bypass distributor margins through institutional contracting.
- Online:Digital portals for adverse event reporting are eliminating paper-based pathways; e-commerce for patient-direct supply remains underdeveloped due to prescription requirements.
Wholesale channels dominate transaction volumes today; direct sales are climbing the fastest as PROSEC and IMMEX incentives attract local production.
Application:
Therapeutic positioning determines reimbursement pathways and competitive substitution risk from newer antiemetic classes.
- Vertigo:Inner ear disorder management in specialized neurology clinics sustains premium pricing for injectable dimenhydrinate. Protocol standardization lags behind 5-HT3 antagonist adoption in insured populations.
- Motion Sickness:Coastal tourism routes through Cancún and Los Cabos sustain over-the-counter demand. Brand recognition anchors Bayer's position in this segment.
- Nausea Relief:Post-operative and chemotherapy-induced vomiting protocols face encroachment from ondansetron and granisetron in tertiary care centers.
- Allergy Treatment:Antihistamine properties drive limited demand compared to dedicated H1 antagonists; this application sits at the margin of dimenhydrinate prescribing.
Vertigo applications command the highest margins today; motion sickness is expanding most quickly as domestic tourism recovers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico's pharmaceutical industry traces its modern foundations to mid-20th century state-led industrialization programs that established domestic API synthesis and formulation capabilities. Regional dimenhydrinate demand clusters reflect this legacy, with production and consumption concentrating in historically industrialized zones where health infrastructure investment has deepened over successive decades.
Mexico City Metro
The capital's tertiary hospital networks anchor national dimenhydrinate procurement through centralized IMSS and ISSSTE tenders. COFEPRIS headquarters proximity accelerates registration timelines for compliant suppliers. The metropolitan corridor hosts the densest concentration of specialized gastroenterology and neurology clinics driving prescription volumes.
Nuevo León
Monterrey's private healthcare infrastructure generates premium demand for injectable antivertigo protocols in specialized outpatient centers. The state's manufacturing incentives under PROSEC frameworks attract formulation facilities seeking tariff advantages. Vertigo clinic networks in the metropolitan area sustain higher-margin product positioning compared to national averages.
Jalisco
Guadalajara's pharmaceutical distributor ecosystem channels tablet formulations into Pacific Coast markets and interior states. Group purchasing organizations aggregate volume across multiple facilities, extracting price concessions through sole-source commitments. Rural pediatric populations in surrounding municipalities create unmet demand for liquid formulation alternatives.
Bajío Region
Querétaro's emerging pharmaceutical manufacturing cluster benefits from IMMEX program incentives for export-oriented production. The region's logistics connectivity to Mexico City and Guadalajara distribution hubs positions it for contract manufacturing growth. Temperature-controlled warehousing infrastructure addresses tropical climate stability requirements for API storage.
Northern Border States
Baja California's maquiladora pharmaceutical operations leverage cross-border supply chain integration with California distribution networks. Customs efficiency at Tijuana-San Diego corridors reduces freight volatility exposure for imported active pharmaceutical ingredients. The region serves as a staging point for products entering broader Latin American markets.
Mexico Dimenhydrinate Market Competitive Landscape
The competitive structure tilts toward multinational incumbents with established manufacturing footprints and institutional contracting relationships. Market access depends heavily on COFEPRIS registration history and validated stability documentation under tropical conditions. Three archetypes dominate: legacy pharmaceutical conglomerates with diversified portfolios, regional generic specialists competing on price, and vertically integrated hospital suppliers. Capacity expansion and strategic partnerships with state-level procurement bodies represent the primary competitive moves reshaping supplier positioning.
Among multinational incumbents, Pfizer and Bayer exemplify contrasting strategic positions. Pfizer occupies the institutional supply tier through sustained bulk tablet contracts with public hospital networks. Bayer anchors consumer-facing positioning through brand recognition in over-the-counter motion sickness segments. PISA represents the regional generic specialist archetype, competing aggressively on price in injectable categories for clinic-based vertigo treatment protocols.
| Leading Market Players |
|---|
| Johnson & Johnson SA de CV |
| Pfizer |
| Bristol-Myers Squibb |
| Bayer |
| Novartis |
| Teva |
| Fresenius |
| Apotex |
| PISA |
| Others |
Supply & Pricing Matrix
COFEPRIS tropical stability validation requirements gate both qualified supply and premium-tier pricing access, as manufacturers bearing accelerated degradation study costs capture institutional tender preference while price-competitive generics without cold-chain documentation face margin compression in Mexico City and Guadalajara procurement clusters.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies dimenhydrinate procurement, with COFEPRIS bioequivalence certification and validated tropical stability data driving price differentiation between branded injectables and unvalidated generic tablets. Pricing pressure stems from 5-HT3 antagonist substitution in insured populations, compressing antiemetic protocol margins. Public hospital networks exhibit highest price sensitivity through centralized ISSSTE and IMSS tenders, while private vertigo clinics in Monterrey show lowest sensitivity for rapid-onset injectable formulations.
Supply Chain Analysis
PROSEC and IMMEX local-content incentives are reshaping sourcing patterns, drawing API procurement toward Baja California and Querétaro formulation facilities to capture tariff advantages. Active pharmaceutical ingredient supply rests on manufacturing clusters in India and China, with diphenhydramine base and 8-chlorotheophylline as critical chemical inputs. Single-source vulnerability concentrates in Asian API synthesis, exposing Mexican formulators to freight volatility and customs delays at Manzanillo and Lázaro Cárdenas ports. Distribution runs through regional wholesalers with legacy ERP systems struggling against COFEPRIS serialization mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Mexico dimenhydrinate market represents a late-cycle quality story, as institutional procurement consolidation shifts demand toward suppliers with demonstrated tropical stability documentation and uninterrupted cold-chain compliance.
For Market Incumbents: Anticipate 5-HT3 antagonist encroachment in post-operative protocols by deepening backward integration into API sourcing and accelerating orally disintegrating tablet registration for pediatric discharge bundles. Prioritize PROSEC-compliant manufacturing footprint expansion in Querétaro to defend margin position against tariff-exposed competitors. COFEPRIS pharmacovigilance digitization demands quality infrastructure investment that mid-sized generic houses cannot match. For New Entrants and Emerging Players: Orally disintegrating tablet technology offers a technology-first wedge into underpenetrated rural Jalisco and Puebla pediatric segments where liquid formulation gaps persist. Target specialized neurology outpatient centers in Tijuana with rapid-onset injectable protocols for vertigo clinic networks. Pursue direct institutional contracting with state-level Secretaría de Salud tendering bodies rather than fragmented wholesale distribution. For Investors and Strategic Acquirers: Roll-up economics work for vertically integrated pharmaceutical specialists because COFEPRIS registration history and validated stability documentation create durable competitive moats that generic traders cannot replicate. Focus acquisition screening on manufacturers with established Baja California or Querétaro production assets and existing IMSS network relationships. Monitor 5-HT3 antagonist formulary inclusion rates as the critical signal for dimenhydrinate demand inflection in tertiary care centers.| Strategic Initiative | Industry Significance |
|---|---|
| COFEPRIS Bioequivalence Certification | Accelerated registration timelines differentiate compliant API suppliers in institutional tenders. |
| Orally Disintegrating Tablet Launch | Pediatric and geriatric protocols in Mexico City hospitals drive formulation premium capture. |
| PROSEC Manufacturing Relocation | Tariff reduction for Baja California facilities improves cost position against Asian imports. |
| Vertigo Clinic Network Partnership | Specialized neurology centers in Monterrey and Tijuana sustain injectable margin pools. |
| Pharmacovigilance Infrastructure Investment | Real-time adverse event reporting compliance filters substandard competitors from approved supplier lists. |
Research Methodology
Coverage spans Mexico City, Guadalajara, Monterrey, and Baja California pharmaceutical clusters, with primary inputs from each combining formulary directors at IMSS and ISSSTE networks, regulatory affairs leads navigating COFEPRIS registration pathways, hospital procurement managers at tertiary care centers, and distribution channel partners with legacy ERP systems. Secondary validation draws from COFEPRIS registration databases, Secretaría de Salud tender documentation, tropical stability study filings, and customs import records for API shipments through Manzanillo and Lázaro Cárdenas. Bottom-up volume modeling triangulates against top-down pharmaceutical market sizing.
Granularity-level modeling disaggregates demand across formulation type, end-user setting, and distribution channel, with therapeutic application and regional regulatory cluster as cross-cutting dimensions. CAGRs derive from segment-level volume trajectories calibrated to institutional procurement expansion and tourism corridor recovery patterns. Industry-specific forecast inputs include COFEPRIS approval timeline distributions and PROSEC program utilization rates for manufacturing relocation.
The model holds under stable COFEPRIS regulatory enforcement and continued Secretaría de Salud procurement centralization; deviation in 5-HT3 antagonist reimbursement policy or API import tariff structures would shift volume and value trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Radioligand Therapy (RLT) Market
Pharmaceuticals
Global Treatment-Resistant Depression Market
Pharmaceuticals
Oxycodone Market
Pharmaceuticals
Migraine Drugs Market
Pharmaceuticals
Global Inhaled Antibiotics Market
Pharmaceuticals
Asia-Pacific Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Global Lyophilized Injectable Drugs Market
Pharmaceuticals
Migraine Nasal Spray Market
Pharmaceuticals
North America Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
Exocrine Pancreatic Insufficiency Therapeutics Market
Pharmaceuticals
Global Loperamide Hcl Market
Pharmaceuticals
Global Cyclosporine Market
Pharmaceuticals
Non-Alcoholic Steatohepatitis Drugs Pipeline Market
Pharmaceuticals
Antidiuretic Drugs Market
Pharmaceuticals
Diuretic Drugs Market
Pharmaceuticals
Nasal Vaccines Market