
 Global Hedgehog Pathway Inhibitors Market | 2026-2036
Global Hedgehog Pathway Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hedgehog Pathway Inhibitors Market Foresight
Capital-intensity divergence between large pharmaceutical conglomerates and emerging biotech specialists is bifurcating competitive dynamics in the hedgehog pathway inhibitors landscape. Novartis AG leverages its established oncology infrastructure to sustain commercial scale across multiple therapy areas. BridgeBio Pharma, Inc. anchors its position through targeted development in genetically defined patient populations. F. Hoffmann-La Roche Ltd. dominates clinical trial execution with its integrated diagnostics-therapeutics platform.
Hedgehog pathway inhibitors constitute a class of targeted therapeutics that antagonize the Smoothened (SMO) receptor or downstream signaling components to interrupt oncogenic hedgehog signaling cascades, with vismodegib and sonidegib representing first-generation SMO antagonists requiring daily oral administration. These agents primarily serve to treat basal cell carcinoma and medulloblastoma by blocking aberrant pathway activation that drives tumor proliferation and survival. Small molecule inhibitors occupy the largest commercial footprint given their established manufacturing scalability and oral bioavailability, while monoclonal antibodies represent the fastest-expanding segment due to emerging interest in combination immunotherapy protocols. Basal cell carcinoma therapy generates the most mature revenue stream, though pancreatic cancer applications attract intensifying R&D investment as investigators explore stromal modulation mechanisms.
FDA oncology drug approval frameworks and EMA's conditional marketing authorization pathways shape clinical development strategies and market access timelines for hedgehog-targeted agents. The EU AI Act and evolving GDPR provisions around clinical data processing increasingly influence trial design and real-world evidence collection methodologies across European development programs. Stakeholders must monitor how payer value-assessment criteria evolve for targeted oncology therapies as health technology assessment bodies recalibrate cost-effectiveness thresholds for rare and ultra-rare cancer indications.
Market Dynamics
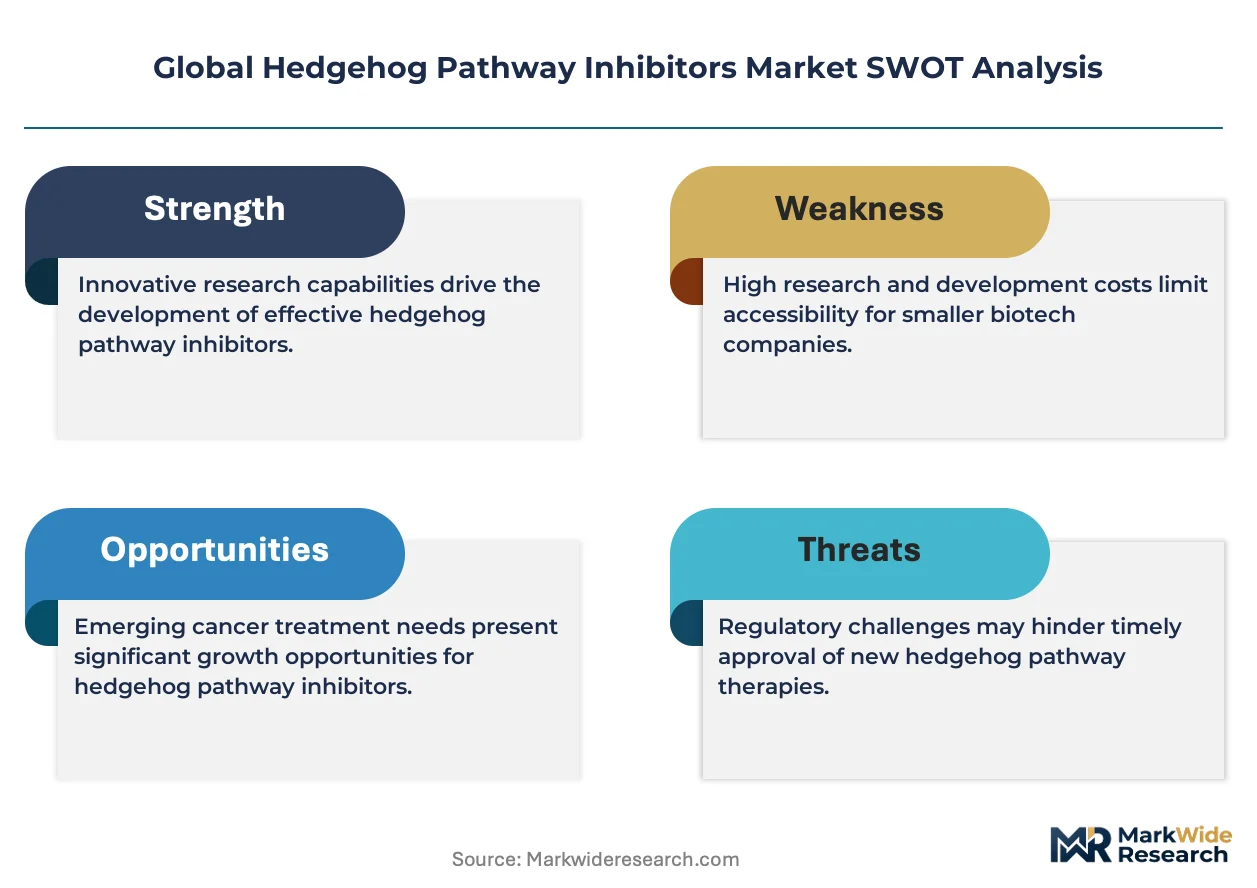
FDA and EMA accelerated approval pathways for rare cancers are compressing commercialization timelines while fragmenting payer value-assessment criteria across oncology centers. This regulatory velocity is reshaping how hedgehog pathway inhibitors reach specialized treatment settings.
Growth Catalysts
- EMA Conditional Marketing Authorization:The framework enables earlier patient access for medulloblastoma therapies, reducing time-to-revenue for developers targeting ultra-rare pediatric indications.
- Stromal Modulation Research:Pancreatic cancer applications are attracting intensifying R&D investment as investigators explore tumor microenvironment mechanisms beyond basal cell carcinoma.
- Japan's PMDA Sakigake Designation:Priority review incentives accelerate regulatory timelines for first-in-class SMO antagonists, concentrating early-launch advantages in Tokyo-Osaka cancer center clusters.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Specialized heterocyclic chemistry manufacturing concentrates among contract suppliers in Switzerland and India, creating single-source vulnerability for small-molecule production.
- Resistance Mutation Frequency:SMO receptor mutations in relapsed basal cell carcinoma patients limit durable response rates, compressing effective therapy duration and retreatment economics.
- Health Technology Assessment Stringency:Germany's IQWiG and England's NICE impose stringent cost-per-QALY thresholds for targeted oncology agents, delaying reimbursement for therapies above benchmark pricing.
Strategic Opportunities
- Combination Immunotherapy Protocols:Monoclonal antibody formats enable pairing with checkpoint inhibitors, opening addressable markets in solid tumors with stromal hedgehog activation.
- EU AI Act Compliance Infrastructure:Automated clinical data processing systems create first-mover advantages for sponsors building real-world evidence platforms across European multi-center networks.
- Brazil's ANVISA Priority Review:Latin America's largest oncology patient pool remains underpenetrated by targeted therapies, offering volume expansion for oral SMO antagonists with localized manufacturing partnerships.
Industry Challenges
- Companion Diagnostic Integration:Pathway biomarker testing requires coordination with centralized laboratories, creating logistical friction for community oncology practices without in-house molecular pathology.
- Pharmacovigilance Scale-Up:Rare adverse event monitoring for pediatric medulloblastoma indications demands specialized safety databases that strain emerging biotech resource constraints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hedgehog Pathway Inhibitors Market |
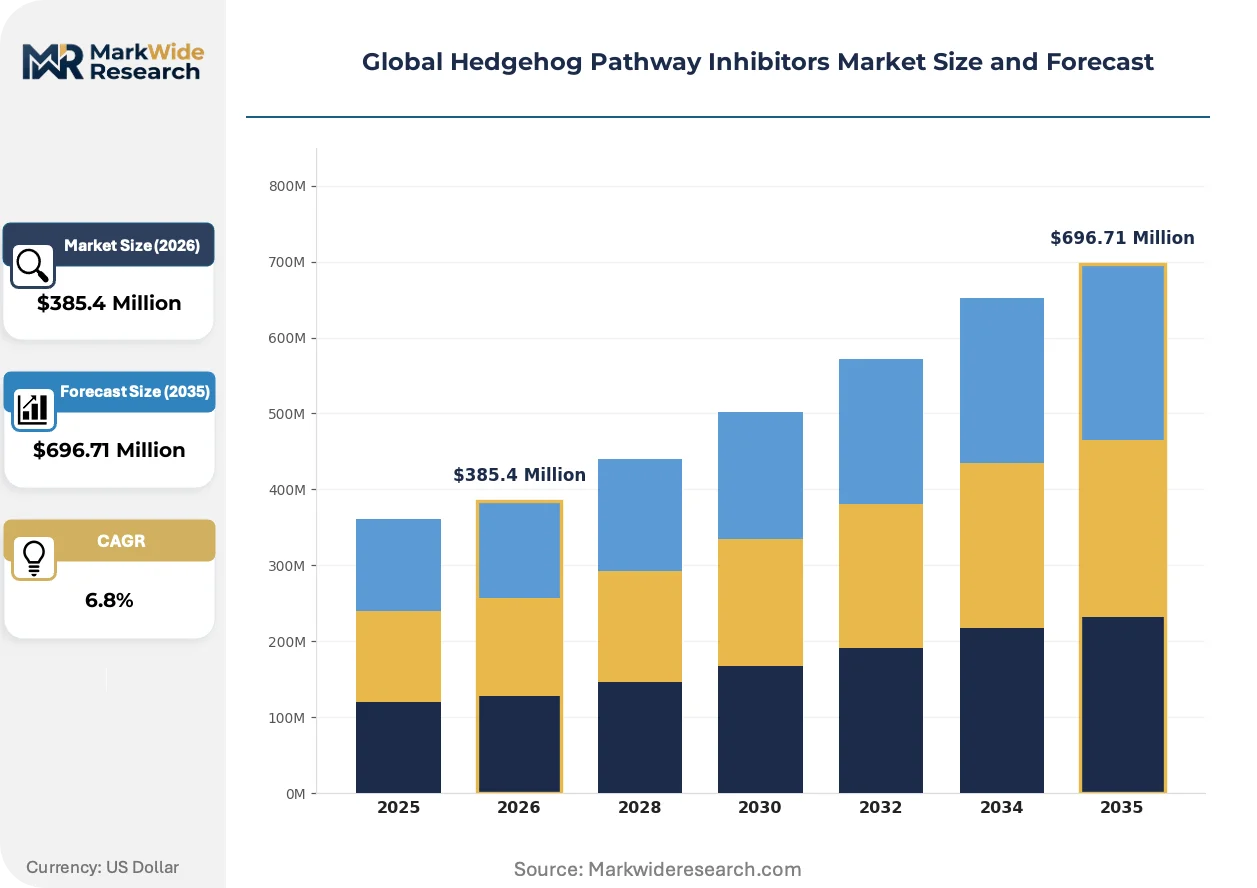
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small Molecule Inhibitors, Monoclonal Antibodies, RNA Interference Agents, Peptide Therapeutics Therapy Area: Basal Cell Carcinoma, Medulloblastoma, Pancreatic Cancer, Lung Cancer, Glioblastoma Delivery Mode: Oral, Intravenous, Subcutaneous, Topical End User: Oncology Clinics, Research Institutes, Specialized Hospitals, Contract Research Organizations |
| Companies Covered | F. Hoffmann-La Roche Ltd., Novartis AG, Pfizer Inc., Sun Pharmaceutical Industries Ltd., BridgeBio Pharma, Inc., Sanofi, Genentech, Inc., MAX BioPharma, Inc., Sol-Gel Technologies Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hedgehog Pathway Inhibitors Market Shifts & Advancements
Next-generation hedgehog pathway modulation is fragmenting across multiple mechanistic approaches, with drug developers pursuing targets downstream of SMO to circumvent resistance mutations. This technological diversification is reshaping competitive positioning and clinical trial design.
Second-generation inhibitors targeting GLI transcription factors and SUFU regulatory proteins are fragmenting the therapeutic landscape beyond first-generation SMO antagonists. Oncology biotech specialists in Boston and Basel are advancing these programs through Phase I trials at accelerated pace. The shift is fragmenting addressable patient populations into biomarker-defined subsegments requiring distinct companion diagnostic strategies.
The EU AI Act's risk-classification framework for clinical decision-support software is restructuring trial data management protocols across European development programs. Sponsors must now embed algorithmic transparency documentation into regulatory submissions for AI-enabled patient stratification tools. Germany's university hospital networks are responding by consolidating data governance functions to meet GDPR-aligned processing requirements.
Specialized cancer centers in the United States, Germany, and Japan are consolidating procurement authority for targeted oncology agents under pharmacy-benefit administrators. Community oncology practices are losing direct purchasing discretion as integrated delivery networks centralize formulary decisions. This concentration is most visible in Texas and Bavaria, where large health systems now control access decisions for high-cost molecular therapies.
Global Hedgehog Pathway Inhibitors Market Segmentation
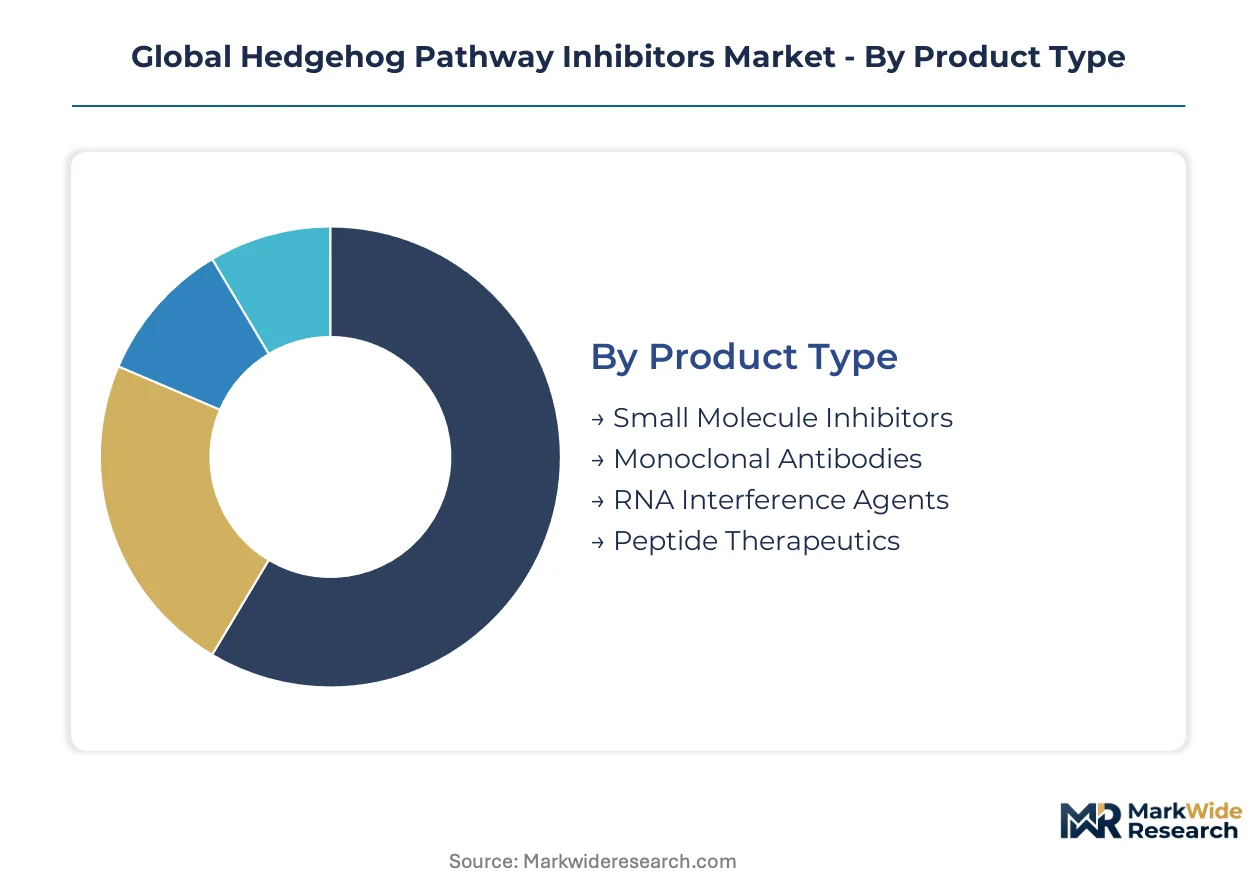
Hedgehog pathway inhibitors fragment across four distinct classification axes, each reshaping how developers allocate R&D resources and commercial infrastructure. Product format dictates manufacturing complexity and pricing architecture. Therapy area concentration determines regulatory pathway selection and payer negotiation leverage.
Product Type:
Small molecule inhibitors dominate domestic manufacturing footprints in Switzerland and the United States, while monoclonal antibodies and RNA agents rely heavily on export-led biologics capacity in Ireland and Singapore.
- Small Molecule Inhibitors:These orally bioavailable compounds antagonize the Smoothened receptor through heterocyclic chemistry platforms. Demand concentrates in Germany and Japan where outpatient oncology dispensing networks favor pill-based regimens for basal cell carcinoma maintenance therapy.
- Monoclonal Antibodies:Large-format biologics targeting pathway components downstream of SMO require cold-chain distribution infrastructure. Export-led production from Irish biologics hubs supplies specialized cancer centers in the United States and United Kingdom seeking combination immunotherapy protocols.
- RNA Interference Agents:siRNA constructs silence GLI transcription factor expression through intracellular delivery mechanisms. Emerging clinical programs in Boston and Basel are advancing these candidates through early-phase trials.
- Peptide Therapeutics:Short-chain amino acid sequences modulate protein-protein interactions within the hedgehog cascade. Niche applications target pediatric medulloblastoma populations with limited therapeutic alternatives.
Small molecule inhibitors hold the largest share; momentum sits with monoclonal antibodies.
Therapy Area:
Cost tier stratification separates mature indications with established reimbursement from experimental applications requiring substantial out-of-pocket investment or grant funding.
- Basal Cell Carcinoma:First-generation SMO antagonists secured FDA approval for advanced and metastatic forms, creating the most mature commercial segment. Community oncology practices in Texas and Florida generate concentrated prescription volume for vismodegib and sonidegib.
- Medulloblastoma:Pediatric neuro-oncology applications command premium pricing through orphan drug designation pathways. European reference pricing systems in France and Italy impose distinct negotiation constraints versus United States buy-and-bill reimbursement.
- Pancreatic Cancer:Stromal modulation hypotheses drive investigator-sponsored trials exploring hedgehog inhibition in desmoplastic tumor microenvironments. Academic medical centers in Tokyo and Heidelberg lead enrollment for these experimental protocols.
- Lung Cancer:Squamous cell histologies with stromal hedgehog activation represent a biomarker-defined subset requiring companion diagnostic coordination.
- Glioblastoma:Blood-brain barrier penetration challenges limit systemic agent efficacy, prompting localized delivery investigations at specialized neuro-oncology centers.
Basal cell carcinoma generates the most revenue; steepest expansion trajectory sits with pancreatic cancer applications.
Delivery Mode:
Volume concentration aligns with patient treatment setting preferences, separating ambulatory oral regimens from hospital-based infusion requirements.
- Oral:Daily tablet administration enables home-based therapy for chronic basal cell carcinoma management. United States Medicare Part D and German statutory health insurance cover these agents under pharmacy benefit structures.
- Intravenous:Hospital infusion requirements concentrate utilization in specialized cancer centers with pharmacy-compounding capabilities. Japanese designated cancer hospitals in Osaka and Nagoya anchor demand for biologic formulations.
- Subcutaneous:Self-administration potential for monoclonal antibodies is reshaping patient flow from infusion centers to home health settings.
- Topical:Localized skin cancer applications avoid systemic exposure but face formulation stability challenges in tropical climates.
Oral delivery commands the greatest volume; subcutaneous formats are gaining share fastest.
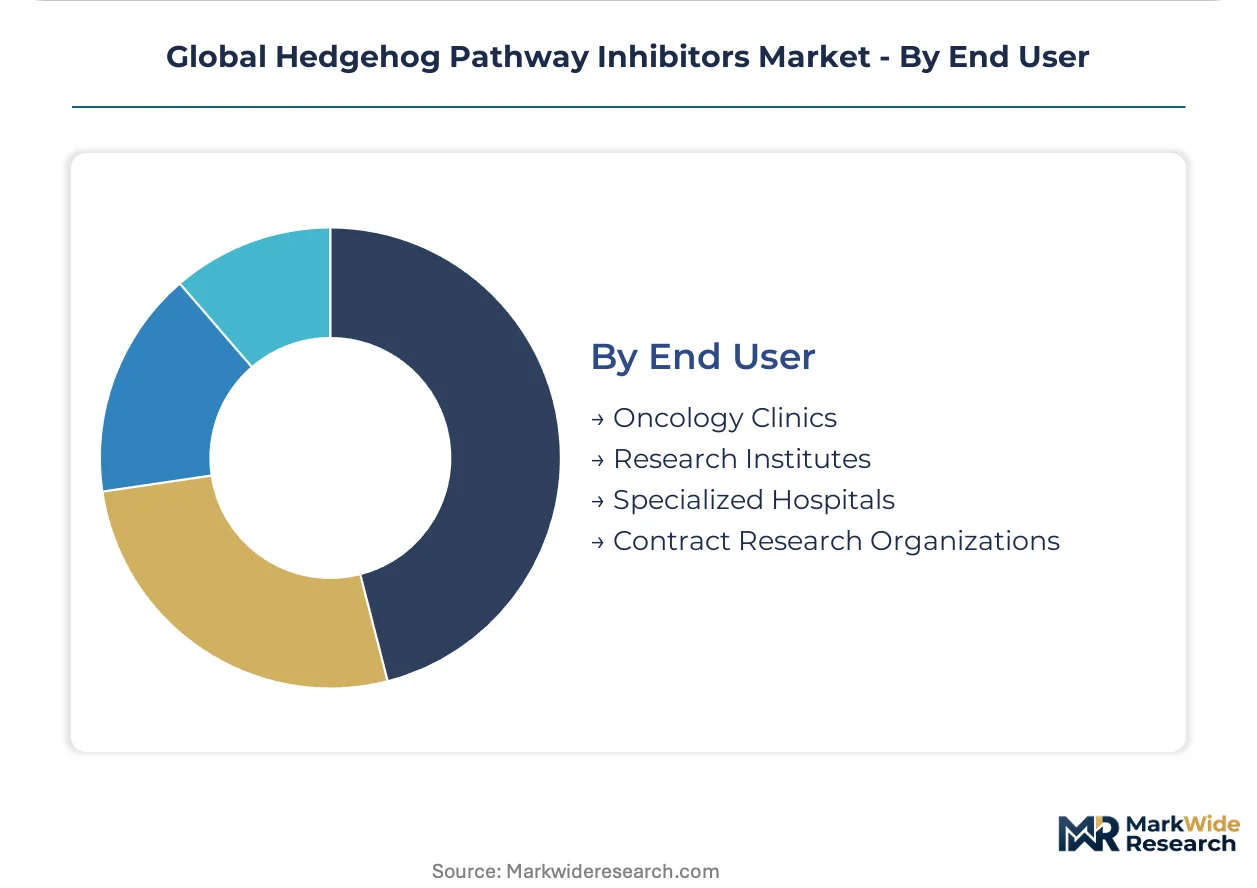
End User:
Customer type determines procurement authority concentration, distinguishing integrated delivery networks from independent research facilities.
- Oncology Clinics:Community-based practices in the United States are losing direct purchasing discretion as pharmacy-benefit administrators consolidate formulary control. Large groups in Texas and California now negotiate centralized contracts for targeted therapies.
- Specialized Hospitals:German university hospitals and Japanese designated cancer centers maintain independent procurement authority for experimental protocols. These institutions anchor early-adoption demand for next-generation SMO antagonists.
- Research Institutes:Academic laboratories in Boston, Basel, and Singapore drive preclinical pipeline expansion through grant-funded investigator-initiated studies.
- Contract Research Organizations:Outsourced clinical trial execution concentrates among global operators with multi-regional regulatory expertise.
Oncology clinics represent the largest addressable base; specialized hospitals show the steepest adoption curve for novel agents.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States while cost-containment pressures dominate German statutory health insurance negotiations. This asymmetry fragments commercialization strategies across Atlantic markets.
United States
Specialized cancer centers in Houston and Boston drive adoption of next-generation SMO antagonists through investigator-sponsored trials. FDA accelerated approval pathways compress time-to-market for rare pediatric indications. Texas Medical Center anchors the highest prescription volume for basal cell carcinoma maintenance therapy.
Germany
IQWiG cost-per-QALY thresholds delay reimbursement for therapies exceeding benchmark pricing in Bavaria and North Rhine-Westphalia. EMA conditional marketing authorization enables earlier patient access for medulloblastoma treatments. Heidelberg University Hospital leads European enrollment for pancreatic cancer stromal modulation protocols.
Japan
PMDA Sakigake designation accelerates regulatory timelines for first-in-class hedgehog inhibitors targeting desmoplastic tumors. Designated cancer hospitals in Osaka and Nagoya concentrate procurement authority for biologic formulations. Tokyo's oncology clusters generate premium pricing for orphan pediatric neuro-oncology indications.
Switzerland
Specialized heterocyclic chemistry manufacturing for small-molecule API concentrates among contract suppliers in Basel and Zurich. Swissmedic approval pathways align with EMA frameworks while maintaining distinct pricing autonomy. The country's pharmaceutical infrastructure anchors European supply security for oral SMO antagonists.
Brazil
ANVISA priority review incentives attract sponsors seeking volume expansion in Latin America's largest oncology patient pool. São Paulo's hospital networks remain underpenetrated by targeted therapies relative to incidence burden. Localized manufacturing partnerships for oral formulations are reshaping access economics in Southeast Brazil.
Global Hedgehog Pathway Inhibitors Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the hedgehog pathway inhibitors landscape. Large pharmaceutical conglomerates leverage integrated diagnostics-therapeutics platforms and established oncology infrastructure to sustain commercial scale. Emerging biotech specialists anchor positions through targeted development in genetically defined patient populations. Dominant competitive moves include strategic partnerships for companion diagnostic integration and geographic expansion through localized manufacturing alliances.
Within the large-cap pharmaceutical tier, Novartis AG and F. Hoffmann-La Roche Ltd. exemplify scale-driven archetypes with diversified oncology portfolios. BridgeBio Pharma, Inc. occupies a position among emerging biotech specialists focused on rare disease indications. These three entities collectively represent the competitive spectrum from integrated platform operators to targeted development boutiques.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd. |
| Novartis AG |
| Pfizer Inc. |
| Sun Pharmaceutical Industries Ltd. |
| BridgeBio Pharma, Inc. |
| Sanofi |
| Genentech, Inc. |
| MAX BioPharma, Inc. |
| Sol-Gel Technologies Ltd. |
| Others |
Supply & Pricing Matrix
Contract manufacturing substitution for captive API production simultaneously redistributes supply geography toward Swiss and Indian heterocyclic chemistry specialists and compresses pricing premiums for first-generation SMO antagonists. This shift fragments procurement leverage across sponsor organizations while concentrating margin capture among specialized CMOs with FDA-inspected facilities.
Pricing Analysis
The customization-premium spread separates standard oral formulations from patient-stratified dosing protocols requiring companion diagnostic bundling. Three-tier pricing structure across premium orphan indications, standard basal cell carcinoma maintenance, and economy-tier volume contracts for emerging markets defines the dominant model. Price differentiation hinges on FDA breakthrough designation status and cold-chain distribution requirements. Pricing pressure stems from Germany's IQWiG cost-per-QALY benchmarks, which delay reimbursement above threshold levels. Community oncology practices in Texas and Florida exhibit highest price sensitivity; Japanese designated cancer centers show least sensitivity due to orphan drug premium acceptance.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Mumbai ports constrain just-in-time API delivery for clinical trial supply, particularly for temperature-sensitive biologic formulations. Manufacturing concentrates in Switzerland, India, and Ireland, with heterocyclic chemistry platforms anchored in Basel and Zurich while biologics capacity clusters around Dublin and Singapore. Raw material dependencies include specialized pyridine derivatives, palladium catalysts, and single-use bioreactor components. Single-source vulnerability concentrates among Swiss contract suppliers for SMO antagonist intermediates. Distribution runs through specialized oncology distributors with cold-chain credentials in the United States and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biomarker-defined patient segmentation fragments addressable populations into discrete niches, creating entry points for developers with targeted mechanistic approaches beyond first-generation SMO inhibition.
For Market Incumbents: Secure companion diagnostic integration partnerships to defend formulary positioning against emerging GLI-targeted competitors. Consolidate manufacturing scale in Swiss CMO networks to offset API concentration risk. Lock in long-term offtake agreements for palladium catalysts before commodity volatility intensifies. For New Entrants and Emerging Players: Differentiate on stromal modulation mechanisms for pancreatic cancer applications, where incumbent presence remains limited to exploratory protocols. Brazil's ANVISA priority review pathway offers the most penetrable regulatory entry point for oral SMO antagonists with localized manufacturing. Pursue investigator-sponsored trial partnerships at Heidelberg and Tokyo academic centers to generate clinical evidence without full sponsor burden. For Investors and Strategic Acquirers: The market sits at a mechanistic diversification phase that favors platform-agnostic biotech specialists with downstream pathway expertise. Long-term viability over the next decade rests on resistance-mutation circumvention capabilities rather than incremental SMO affinity improvements. Acquisition targets should demonstrate GLI or SUFU program advancement plus European regulatory filing readiness. The signal to watch is EMA conditional marketing authorization frequency for pediatric medulloblastoma indications as inflection indicator for premium pricing sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Integration | FDA-aligned biomarker testing secures formulary access at Texas Medical Center and Bavarian university hospitals. |
| EU AI Act Compliance Infrastructure | Automated data governance platforms enable real-world evidence collection across German multi-center networks. |
| Localized Manufacturing Partnership | ANVISA-registered Brazilian production reduces import dependency for Southeast Latin American patient access. |
| Resistance-Mutation Surveillance Program | Centralized SMO mutation tracking at Heidelberg and Osaka centers informs retreatment protocol development. |
| Stromal Modulation Trial Expansion | Pancreatic cancer investigator-sponsored studies at Tokyo and Heidelberg academic centers diversify indication footprint. |
Research Methodology
The analysis maps small-molecule inhibitors, monoclonal antibodies, RNA interference agents, and peptide therapeutics, each validated through regulatory affairs directors, hospital formulary managers, and payer access specialists. Primary interviews with drug development executives at emerging biotech firms and established pharmaceutical oncology divisions combined with secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up prescription volume modeling and top-down epidemiological incidence estimates provided cross-check triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled therapy area concentration, delivery mode preference, product format manufacturing complexity, and regional regulatory cluster segmentation. CAGRs derived from patient population growth, approval pathway velocity, and pricing trajectory assumptions incorporated stromal modulation research investment intensity and resistance mutation frequency as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside EMA conditional marketing authorization frequency assumptions or IQWiG reimbursement threshold stability would require recalibration. Forecasts reflect documented assumptions regarding FDA accelerated approval pathway continuity and Japanese PMDA Sakigake designation persistence. Regulatory pathway disruption, API supply concentration events, or health technology assessment threshold recalibration could revise trajectory expectations. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Antipyretic Drugs for Children Market
Pharmaceuticals
Germany Opioids Market
Pharmaceuticals
Global Pharmaceuticals Market
Pharmaceuticals
Mtor Inhibitors Market
Pharmaceuticals
Pantoprazole Market
Pharmaceuticals
Adapalene Market
Pharmaceuticals
Czech Republic Pharmaceutical Market
Pharmaceuticals
Osteoarthritis Drugs Market
Pharmaceuticals
Oral Anti-Diabetic Drugs Market
Pharmaceuticals
Global Desmopressin Market
Pharmaceuticals
US Transdermal Drug Delivery System Market
Pharmaceuticals
Extended Release Drugs Market
Pharmaceuticals
Compound Potassium Hydrogen Phosphate Injection Market
Pharmaceuticals
OTC Analgesic Market
Pharmaceuticals
Buprenorphine and Naloxone Market
Pharmaceuticals
Otic Drugs Market