
 Global Hepatitis a Vaccine Market | 2026-2036
Global Hepatitis a Vaccine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hepatitis a Vaccine Market Foresight
Aluminum hydroxide adjuvant substitution with newer immunostimulant formulations is realigning cost structures across hepatitis A vaccine production. GSK plc leverages its established adjuvant science platform to sustain manufacturing efficiency at scale. Sanofi anchors its competitive stance through differentiated pediatric dosing regimens. Merck & Co., Inc. specializes in combination vaccine development, occupying a distinct position in the hepatitis A and B co-formulation segment.
Hepatitis A vaccine comprises inactivated or live attenuated viral preparations administered intramuscularly to induce protective antibodies against the hepatitis A virus, with formulations typically containing purified antigen adsorbed to aluminum salts and stabilized with buffers to ensure potency during cold-chain distribution. The primary commercial purpose centers on preventing infection in travelers, children, and occupational risk groups in endemic regions. Inactivated vaccines dominate procurement volumes due to established safety profiles and WHO prequalification status, while combination hepatitis A and B formulations capture premium positioning in adult traveler clinics. Pediatric vaccination through government health programs represents the largest volume channel, whereas private clinic distribution of travel-focused doses commands higher per-dose margins.
FDA, EMA, and WHO prequalification standards govern antigen purity, potency assays, and stability requirements that determine market access for hepatitis A vaccines across regulated jurisdictions. India's CDSCO and China's NMPA enforce parallel national standards that shape local manufacturing compliance costs and registration timelines for domestic and imported products. Stakeholders must monitor evolving combination vaccine guidelines and cold-chain infrastructure investments as determinants of competitive positioning in emerging procurement markets.
Market Dynamics
Aluminum hydroxide adjuvant substitution is compressing manufacturing cost structures while forcing reformulation investments across hepatitis A vaccine production networks. Cold-chain infrastructure gaps in tropical distribution corridors remain the binding constraint on volume expansion.
Growth Catalysts
- WHO Prequalification Pathway:Accelerated product registration timelines are unlocking procurement access for manufacturers targeting government immunization programs across Southeast Asia.
- Pediatric Dosing Regimens:Expanded national immunization schedules in India are scaling procurement volumes through public health system channels.
- Combination Formulation Development:Hepatitis A and B co-formulation advances are capturing premium positioning in adult traveler clinic segments.
Market Restraints
- Aluminum Salt Input Volatility:Purified adjuvant material costs fluctuate with mining output concentration in Chinese and Indian supplier bases.
- Single-Source Fermentation Capacity:Viral antigen production concentrates in a limited number of bioreactor facilities across Western Europe and North America.
- EMA Stability Testing Requirements:Extended real-time potency validation protocols add twelve to eighteen months to registration timelines for new entrants.
Strategic Opportunities
- Sub-Saharan Africa Coverage Gaps:Underpenetrated routine immunization programs in Nigeria and Ethiopia present volume expansion potential for prequalified suppliers.
- Microneedle Patch Delivery:Needle-free intradermal administration technologies are converging with thermostable formulation advances to eliminate cold-chain dependence.
- India PLI Scheme Incentives:Production-linked incentive frameworks for pharmaceutical manufacturing are attracting domestic capacity expansion investments.
Industry Challenges
- Bioprocess Engineering Talent Scarcity:Viral antigen fermentation and downstream purification expertise concentrates in legacy vaccine hubs, constraining new facility staffing.
- Multi-Jurisdiction Certification Burden:Parallel FDA, EMA, and WHO prequalification submissions require duplicative clinical data packages and analytical method transfers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hepatitis a Vaccine Market |
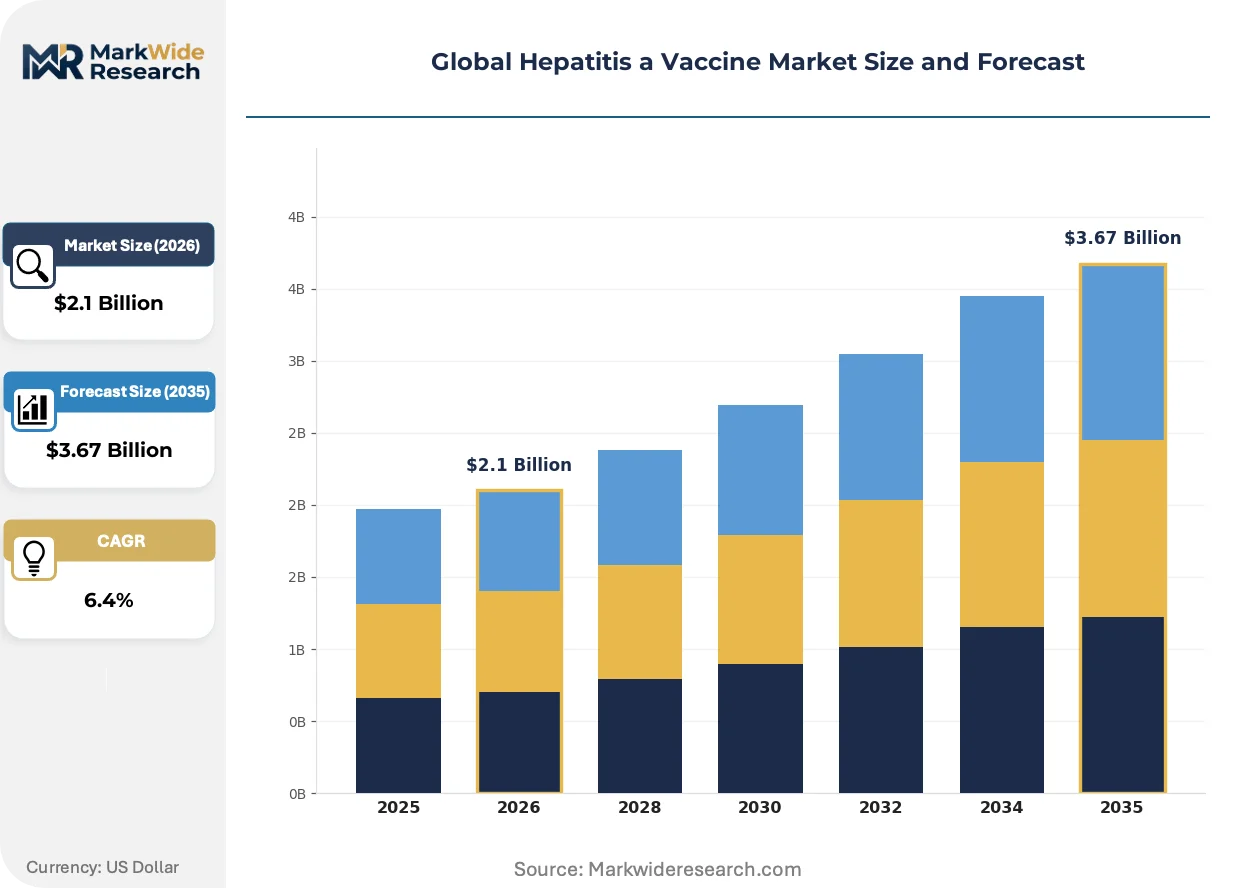
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vaccine Type: Inactivated, Live Attenuated, Combined Hepatitis A & B, Recombinant, Others Application: Travel Immunization, Pediatric Vaccination, Post-Exposure Prophylaxis, Adult Immunization, Workforce Protection End User: Hospitals, Immunization Clinics, Government Health Programs, Private Clinics, Community Health Centers Distribution Channel: Hospital Pharmacy, Retail Pharmacy, Online Sales, Public Health Centers, Wholesale Distributors |
| Companies Covered | GSK plc, Sanofi, Merck & Co., Inc., Indian Immunologicals Ltd., Instituto Butantan, KM Biologics, SINOVAC, Biological E Limited, SK bioscience, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hepatitis a Vaccine Market Shifts & Advancements
Reformulation science and delivery mechanism advances are compressing the traditional trade-off between thermostability and immunogenicity in hepatitis A vaccines. Adjuvant platform diversification and distribution model experimentation are unlocking access in infrastructure-constrained settings.
Immunostimulant adjuvant platforms are displacing aluminum hydroxide in next-generation hepatitis A formulations, with saponin-based and lipid nanoparticle systems inducing superior T-cell responses at reduced antigen doses. Pediatric program procurement offices in Brazil and Mexico are piloting these formulations for birth-cohort campaigns. Thermostable presentation is decentralizing distribution reach into last-mile cold-chain gaps across equatorial zones.
EMA's revised guideline on combined vaccines now mandates head-to-head non-inferiority trials against licensed monovalent comparators for hepatitis A component inclusion. This regulatory elevation is extending development timelines for combination candidates targeting traveler clinic segments. Manufacturers are responding with adaptive trial designs and surrogate endpoint negotiations to preserve commercialization schedules.
Travel medicine clinics are consolidating purchasing through specialized vaccine distributors, displacing direct manufacturer relationships that dominated pre-pandemic procurement. Corporate occupational health programs and study-abroad coordinators are channeling demand through these intermediaries, compressing price transparency and shifting volume discounts upstream. This concentration is most visible in Australia and Canada, where TGA and Health Canada licensing requirements favor established distributor networks over direct import arrangements.
Global Hepatitis a Vaccine Market Segmentation
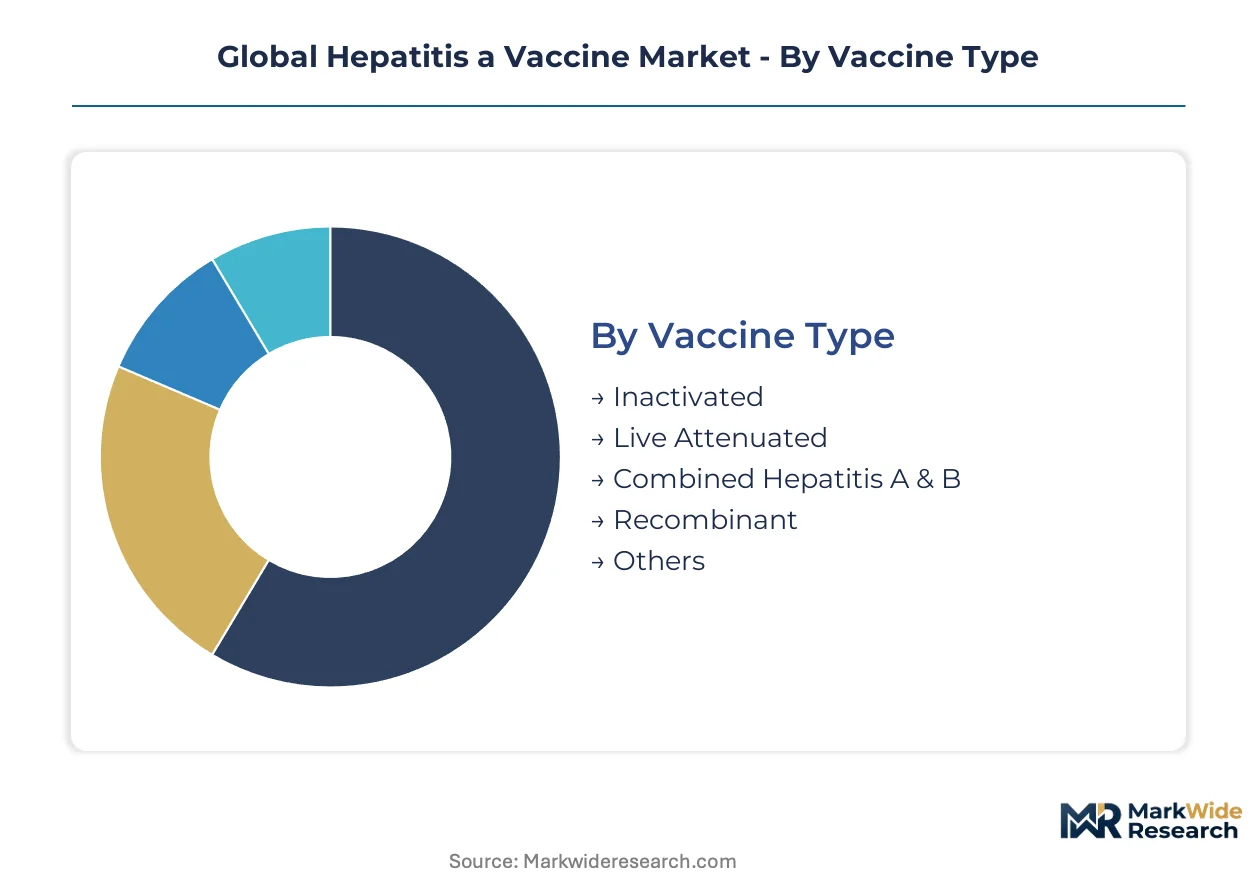
Vaccine type segmentation determines manufacturing investment priorities and regulatory pathway complexity across hepatitis A production networks. Application and end-user splits reveal divergent margin structures between public procurement and private clinic channels.
Vaccine Type:
Upgrade cycles from aluminum-adjuvanted legacy formulations to immunostimulant platforms are redefining competitive positioning across hepatitis A vaccine categories.
- Inactivated:Viral antigen inactivated by formalin and adsorbed to aluminum hydroxide or phosphate adjuvants, delivering established immunogenicity profiles with WHO prequalification status. Procurement concentrates in India's Universal Immunization Programme and Brazil's national health system, where CDSCO and ANVISA registrations anchor tender eligibility.
- Combined Hepatitis A & B:Co-formulation containing both viral antigens in single-dose presentation, commanding premium positioning in adult traveler clinics and occupational health programs. Demand clusters in Germany, Australia, and Canada where corporate vaccination mandates and study-abroad requirements sustain higher per-dose margins.
- Live Attenuated:Temperature-sensitive formulation requiring stringent cold-chain maintenance throughout distribution.
- Recombinant:Yeast-derived antigen expression systems under clinical evaluation for thermostable presentation.
- Others:Investigational mRNA and virus-like particle platforms in early-stage development pipelines.
Inactivated formulations sit at the top of the volume ranking, with combined hepatitis A and B climbing the fastest.
Application:
Cost tier differentiation separates high-volume pediatric campaigns from premium-priced traveler clinic segments with divergent procurement mechanisms.
- Pediatric Vaccination:Routine immunization schedules targeting birth cohorts through government health systems, with two-dose regimens typically administered at 12 and 18 months. India's expansion of hepatitis A inclusion in national programs and Mexico's birth-cohort campaigns drive procurement scale, with UNICEF tender participation determining manufacturer access.
- Travel Immunization:Pre-departure prophylaxis for tourists, business travelers, and expatriate workers visiting endemic regions, with single-dose accelerated schedules available for adults. Demand concentrates in UK, France, and US travel medicine clinics where corporate occupational health contracts and university study-abroad programs sustain price premiums.
- Post-Exposure Prophylaxis:Emergency administration following confirmed exposure events, utilizing accelerated dosing protocols.
- Adult Immunization:Catch-up vaccination for unvaccinated adults in risk categories including men who have sex with men and persons with chronic liver disease.
- Workforce Protection:Occupational health programs targeting healthcare workers, food handlers, and sanitation employees in endemic settings.
Pediatric vaccination dominates absolute procurement volumes, with travel immunization delivering the steepest margin expansion trajectory.
End User:
Customer type fragmentation creates distinct service requirements between centralized government procurement and decentralized private clinic administration.
- Government Health Programs:National immunization schedules and outbreak response stockpiles managed through centralized tender processes, with WHO prequalification status as mandatory entry criteria. India's state-level procurement offices and Brazil's Ministry of Health contracts anchor volume concentration, with multi-year supply agreements favoring established manufacturers.
- Private Clinics:Fee-for-service vaccination services targeting insured populations and corporate contracts, with flexible scheduling and combination product preferences. Demand concentrates in urban India, Thailand, and South Africa where middle-class expansion and private health insurance penetration sustain out-of-pocket payment channels.
- Hospitals:Inpatient and outpatient departments managing high-risk patient populations and pre-surgical screening protocols.
- Immunization Clinics:Dedicated vaccination facilities often affiliated with travel medicine or occupational health services.
- Community Health Centers:Primary care access points in underserved areas bridging public and private delivery models.
Government health programs capture the largest procurement volumes, with private clinics gaining share fastest in emerging economy urban centers.
Distribution Channel:
Supply concentration in wholesale distributor networks is displacing direct manufacturer relationships across temperate and tropical distribution corridors.
- Wholesale Distributors:Specialized vaccine logistics providers managing cold-chain integrity from manufacturer to point of administration, with temperature monitoring and batch traceability systems. Australia's CSL Seqirus distribution network and Canada's established pharmaceutical wholesalers dominate channel control, with Health Canada and TGA licensing requirements favoring intermediary relationships over direct import.
- Public Health Centers:Government-operated distribution nodes for national immunization program supply, with centralized cold storage and last-mile delivery to rural clinics. India's state vaccine stores and Nigeria's zonal cold stores anchor volume throughput, with Gavi and UNICEF procurement channels determining manufacturer allocation.
- Hospital Pharmacy:Captive distribution within integrated health systems for inpatient and employee vaccination programs.
- Retail Pharmacy:Community-based access points for travel and adult immunization in deregulated markets.
- Online Sales:Direct-to-consumer channels emerging in select markets with prescription verification requirements.
Wholesale distributors command the highest channel share, with public health centers expanding most quickly in Gavi-eligible countries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's government immunization infrastructure anchors procurement volume concentration for hepatitis A vaccines, with CDSCO registration pathways and state-level tender systems determining manufacturer access across tropical distribution corridors.
United States
FDA stability testing requirements govern traveler clinic procurement through specialized vaccine distributors. Corporate occupational health programs in Texas and California sustain demand for adult hepatitis A and B co-formulations. Boston's biotech corridor houses viral antigen fermentation expertise that supports contract manufacturing relationships.
Germany
EMA combination vaccine guidelines mandate head-to-head non-inferiority trials for hepatitis A component licensing. Adult immunization campaigns in Bavaria and North Rhine-Westphalia drive premium pricing for accelerated dosing regimens. Frankfurt's pharmaceutical logistics hub manages cold-chain distribution across Central European travel medicine networks.
Brazil
ANVISA registration timelines shape tender eligibility for national health system procurement. São Paulo's state immunization program anchors volume demand for pediatric hepatitis A inclusion in routine schedules. The Butantan Institute's manufacturing presence exemplifies domestic capacity development for regional supply security.
Australia
TGA licensing requirements favor established distributor networks over direct manufacturer import arrangements. Travel medicine clinics in Sydney and Melbourne consolidate purchasing through CSL Seqirus distribution channels. Corporate vaccination mandates for mining and resource sector workers sustain occupational health program volumes.
China
NMPA enforces parallel national standards that shape local manufacturing compliance costs for domestic and imported products. SINOVAC's Beijing-based production capacity serves both government immunization programs and private clinic distribution. Yangtze River Delta cold-chain infrastructure investments are reducing last-mile distribution constraints in tropical southern provinces.
Global Hepatitis a Vaccine Market Competitive Landscape
Adjuvant platform diversification dominates the current landscape as manufacturers reformulate legacy aluminum-hydroxide products. The vendor base concentrates around three strategic archetypes: multinational pharmaceutical conglomerates with established WHO prequalification status, regional vaccine specialists leveraging domestic regulatory relationships, and emerging biologics developers pursuing thermostable presentation technologies. Capacity expansion in Indian and Chinese manufacturing zones and strategic partnerships for combination formulation development represent the dominant competitive moves reshaping procurement access.
Within the multinational tier, GSK plc, Sanofi, and Merck & Co., Inc. occupy positions defined by prequalified product portfolios and established cold-chain distribution relationships. These entities exemplify the regulatory scale archetype, with CDSCO, FDA, and EMA registrations anchoring tender eligibility across divergent procurement channels. Their positioning reflects the structural premium attached to combination hepatitis A and B formulations in adult traveler segments versus monovalent pediatric program volumes.
| Leading Market Players |
|---|
| GSK plc |
| Sanofi |
| Merck & Co., Inc. |
| Indian Immunologicals Ltd. |
| Instituto Butantan |
| KM Biologics |
| SINOVAC |
| Biological E Limited |
| SK bioscience |
| Others |
Supply & Pricing Matrix
Immunostimulant adjuvant platform transitions are simultaneously compressing per-dose manufacturing economics and redistributing supply concentration toward biologics-specialized fermentation networks. Aluminum hydroxide substitution with saponin-based and lipid nanoparticle systems forces parallel reformulation investments that favor scaled manufacturers with captive adjuvant science capabilities.
Pricing Analysis
Input-cost pass-through from aluminum salt mining volatility in Chinese and Indian supplier bases is compressing margins on legacy formulations. Three-tier pricing structure across premium combination products, standard inactivated monovalents, and economy pediatric program tenders separates traveler clinic segments from government procurement channels. Pricing pressure stems from UNICEF tender aggregation and state-level volume consolidation in India. Government health programs exhibit highest price sensitivity; private travel medicine clinics sustain lowest sensitivity due to corporate reimbursement and study-abroad bundling.
Supply Chain Analysis
Reverse-logistics for temperature-excursion product returns and cold-chain remediation flows through specialized vaccine distributors with batch traceability systems. Antigen production concentrates in Western European and North American bioreactor facilities; formulation and fill-finish capacity clusters in India and China. Purified viral antigen, aluminum hydroxide adjuvant, and pharmaceutical-grade buffers constitute critical input dependencies. Single-source fermentation vulnerability creates supply concentration risk. Distribution runs through wholesale distributor networks with temperature-monitoring infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where WHO prequalification status gates procurement access across Gavi-eligible and national immunization programs. EMA's revised combination vaccine guidelines mandating head-to-head non-inferiority trials represent the pivotal regulatory milestone accelerating consolidation.
For Market Incumbents: Hedge aluminum adjuvant exposure through accelerated immunostimulant platform transitions and captive fermentation capacity expansion in Indian PLI-eligible zones. Threats from thermostable presentation developers and microneedle delivery entrants require defensive patent positioning around formulation science. Certification investment in WHO prequalification maintenance anchors tender eligibility. For New Entrants and Emerging Players: Capture sub-Saharan Africa routine immunization gaps in Nigeria and Ethiopia where prequalified supplier scarcity creates procurement bottlenecks. Microneedle patch delivery convergence with thermostable formulations eliminates cold-chain dependence as the most penetrable white-space. Go-to-market through Gavi and UNICEF procurement channels leverages established demand aggregation. For Investors and Strategic Acquirers: Valuations sit cheapest among regional vaccine specialists with domestic regulatory relationships but limited WHO prequalification progress. Long-term viability centers on combination formulation pipelines and thermostable presentation platforms. Acquisition target archetype: mid-scale manufacturers with CDSCO or ANVISA registrations and adjuvant platform diversification capability. Signal to watch: adaptive trial design negotiations with EMA for combination vaccine timelines.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway Advancement | Unlocks Gavi and UNICEF procurement access for emerging manufacturers targeting government immunization programs. |
| Immunostimulant Adjuvant Platform Transition | Reduces aluminum salt input dependence while improving T-cell response profiles for next-generation formulations. |
| Microneedle Patch Delivery Development | Eliminates cold-chain infrastructure requirements and expands last-mile distribution reach in tropical corridors. |
| Combination Hepatitis A and B Formulation Investment | Captures premium positioning in adult traveler clinics and occupational health program segments. |
| Domestic Manufacturing Capacity Expansion | Leverages India's PLI scheme incentives to reduce import dependence and shorten registration timelines. |
Research Methodology
Bottom-up pediatric and traveler immunization modeling reconciled against top-down manufacturer capacity and procurement tracking forms the analytical core. Primary interviews with vaccine development executives, regulatory affairs leads at CDSCO and ANVISA, UNICEF procurement officers, and hospital pharmacy directors combined with secondary validation against WHO prequalification listings, EMA combination vaccine guidelines, ClinicalTrials.gov entries, and national immunization program tender databases. Triangulation across these sources ensures demand-side and supply-side convergence.
Input-output matrices mapping antigen fermentation capacity, adjuvant material flows, and distribution channel throughput anchor the analytical framework across the projection horizon. Segmentation dimensions include vaccine type, application, end user, and distribution channel with regional regulatory cluster overlays. CAGRs derive from regression-based trending of procurement volumes against immunization schedule expansion and pricing trajectories. Forecast inputs incorporate cold-chain infrastructure investment rates and prequalification pathway throughput.
Regulatory guideline revisions, adjuvant platform transition timelines, and cold-chain infrastructure deployment delays are the dominant revision risks. Forecasts reflect documented assumptions regarding WHO prequalification participation rates and national immunization program expansion schedules. Practitioners should monitor EMA adaptive trial guidance, UNICEF tender aggregation patterns, and thermostable formulation clinical milestones for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Neuroprotective Agents Market
Pharmaceuticals
Chemotherapy-Induced Nausea and Vomiting (CINV) Treatment Market
Pharmaceuticals
Global BHK Rabies Vaccine Market
Pharmaceuticals
Middle East and Africa Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Pregabalin Market
Pharmaceuticals
Rosuvastatin Market
Pharmaceuticals
Eperisone Hcl Market
Pharmaceuticals
Throat Sprays Market
Pharmaceuticals
Europe Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
Nicotine Replacement Therapy (NRT) Market
Pharmaceuticals
Proton Pump Inhibitors Market
Pharmaceuticals
Botulinum Toxin Market
Pharmaceuticals
Japan Generic Drug Market
Pharmaceuticals
Demerol (Meperidine) Market
Pharmaceuticals
Carbapenem Market
Pharmaceuticals
Alprazolam Powder Market