
 Global Nasal Drug Delivery Market | 2026-2036
Global Nasal Drug Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nasal Drug Delivery Market Foresight
Migraine therapeutics is decoupling from oral tablets as neurologists and pain specialists prioritize faster onset kinetics. GlaxoSmithKline leverages its respiratory device heritage to dominate metered-dose nasal platforms. AstraZeneca sustains R&D intensity across biologic-compatible atomizer architectures. Pfizer anchors its portfolio in hospital-administered acute pain formulations where regulatory familiarity accelerates formulary placement.
Nasal drug delivery encompasses pharmaceutical systems engineered to administer active compounds via the nasal mucosa for local or systemic action, typically achieving plasma concentrations within minutes through the highly vascularized respiratory epithelium and olfactory region. The technology exploits particle size optimization, generally targeting 10-50 microns for deposition in the nasal cavity while avoiding pulmonary diversion, to enable rapid absorption bypassing hepatic first-pass metabolism. Nasal sprays and pump devices command the largest installed base among product categories, though powder nasal formulations represent the fastest-expanding segment due to improved thermostability for vaccine and biologic candidates. Homecare settings emerge as the highest-growth end-user channel, displacing hospital-centric administration as self-administration training protocols mature and disposable device designs reduce contamination risk.
FDA 505(b)(2) provisions and EMA centralized assessment procedures shape development economics by permitting reference to existing safety data for reformulated products, compressing timelines for nasal iterations of approved molecules. The EU MDR and ISO 10993 biocompatibility standards enforce escalating device-material testing burdens that favor manufacturers with captive toxicology and polymer characterization capabilities. Stakeholders must monitor olfactory-targeting platform advances and evolving pharmacovigilance expectations for CNS-active nasal therapies as regulators scrutinize direct-to-brain exposure pathways.
Market Dynamics
FDA 505(b)(2) reformulation pathways and EMA centralized procedures compress development timelines for nasal iterations of approved molecules, while patient preference for non-invasive administration pulls capital toward device-integrated platforms.
Growth Catalysts
- 505(b)(2) Pathway Expansion:The FDA's streamlined framework permits reference to existing safety data for nasal reformulations, halving clinical trial burdens for acute migraine and pain therapeutics.
- Homecare Self-Administration:Disposable pump designs with contamination-resistant nozzles enable patient training protocols that shift administration from hospital infusion centers to domestic settings.
- Biologic Thermostability Demands:Powder nasal formulations eliminate cold-chain dependencies for peptide and vaccine candidates, opening distribution to tropical and remote geographies.
Market Restraints
- Device-Material Testing Burdens:EU MDR and ISO 10993 biocompatibility standards mandate escalating toxicology validation for polymer nasal actuators, favoring manufacturers with captive laboratory infrastructure.
- Input Concentration Risk:Precision-molded polypropylene reservoirs and silicone valve components concentrate among German and Swiss polymer processors, exposing supply chains to single-source fragility.
- Olfactory Route Uncertainty:Direct-to-brain exposure pathways via the cribriform plate trigger heightened pharmacovigilance scrutiny from EMA and FDA for CNS-active nasal therapies, extending approval timelines.
Strategic Opportunities
- Japan's Aging Demographics:METI reimbursement incentives for geriatric-friendly delivery modalities position nasal platforms as alternatives to injectable dementia and Parkinson's therapeutics.
- Emerging Market Cold-Chain Gaps:Thermostable dry powder nasal vaccines address distribution infrastructure limitations across India and Southeast Asia where refrigeration coverage remains uneven.
- Digital Health Convergence:Bluetooth-enabled dose-counters and adherence-tracking apps paired with nasal devices create adherence data streams valued by payers in Germany's DiGA framework.
Industry Challenges
- Specialized Formulation Talent Scarcity:Nasal mucoadhesive polymer science and particle engineering expertise concentrates among academic laboratories in the Netherlands and Denmark, constraining workforce scaling.
- Legacy Inhaler Integration Complexity:Hospital formularies with entrenched nebulizer and pressurized metered-dose inhaler protocols resist nasal device procurement without parallel cost-effectiveness modeling.
- Cross-Jurisdictional Certification Lag:Divergent FDA-EMA requirements for nasal spray plume geometry and droplet size distribution force redundant testing protocols, inflating registration costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nasal Drug Delivery Market |
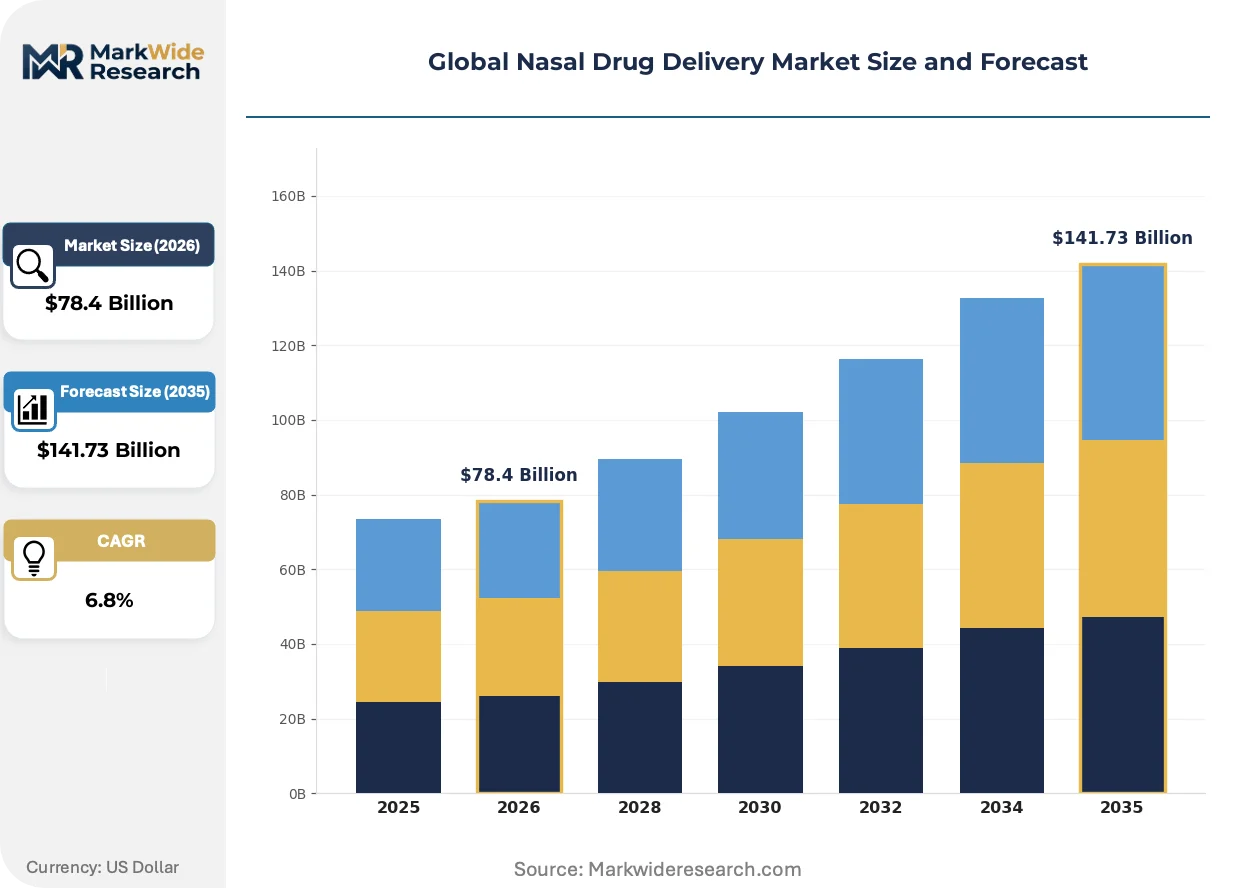
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nasal Sprays, Powder Nasal Formulations, Gel Formulations, Liquid Nasal Solutions End User: Hospitals, Clinics, Homecare Settings, Pharmacies Application: Allergy Treatment, Pain Management, Hormonal Therapy, Vaccination Delivery Device: Atomizers, Pump Devices, Metered-Dose Inhalers, Disposable Devices |
| Companies Covered | GlaxoSmithKline, AstraZeneca, Johnson & Johnson, Pfizer, Novartis, Merck & Co., Roche Holding, Sanofi, Bristol-Myers Squibb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nasal Drug Delivery Market Shifts & Advancements
Device miniaturization and connected health architectures are restructuring how nasal therapeutics integrate into patient workflows, with regulatory harmonization efforts attempting to keep pace.
Precision powder atomization technology is converging with electrostatic dosing controls to enable peptide delivery through the nasal mucosa with bioavailability approaching subcutaneous injection. Biopharmaceutical developers in acute pain and migraine categories are adopting these platforms at accelerated cadences. The technology is converging with hospital-at-home programs that demand reliable systemic absorption without vascular access.
EMA's MDR transition and FDA's evolving guidance on combination product classification are forcing device manufacturers to maintain dual regulatory submission capabilities. The industrial consequence fragments vendor bases between those with captive quality management systems and contract organizations struggling with notified body backlogs. Nasal spray devices with electronic dose-counters face the steepest compliance ramps, with manufacturers in Ireland and Switzerland expanding regulatory affairs headcount to manage parallel FDA-EMA tracks.
Patient switching patterns now favor self-administered acute therapies that eliminate pharmacy wait times and clinical travel burdens. Migraine sufferers in the United States and Germany are abandoning oral triptan prescriptions for nasal spray alternatives that promise 15-minute onset kinetics. This behavioral pivot concentrates prescription volume among neurologists and pain specialists who prioritize speed-to-relief metrics over historical formulary loyalty.
Global Nasal Drug Delivery Market Segmentation
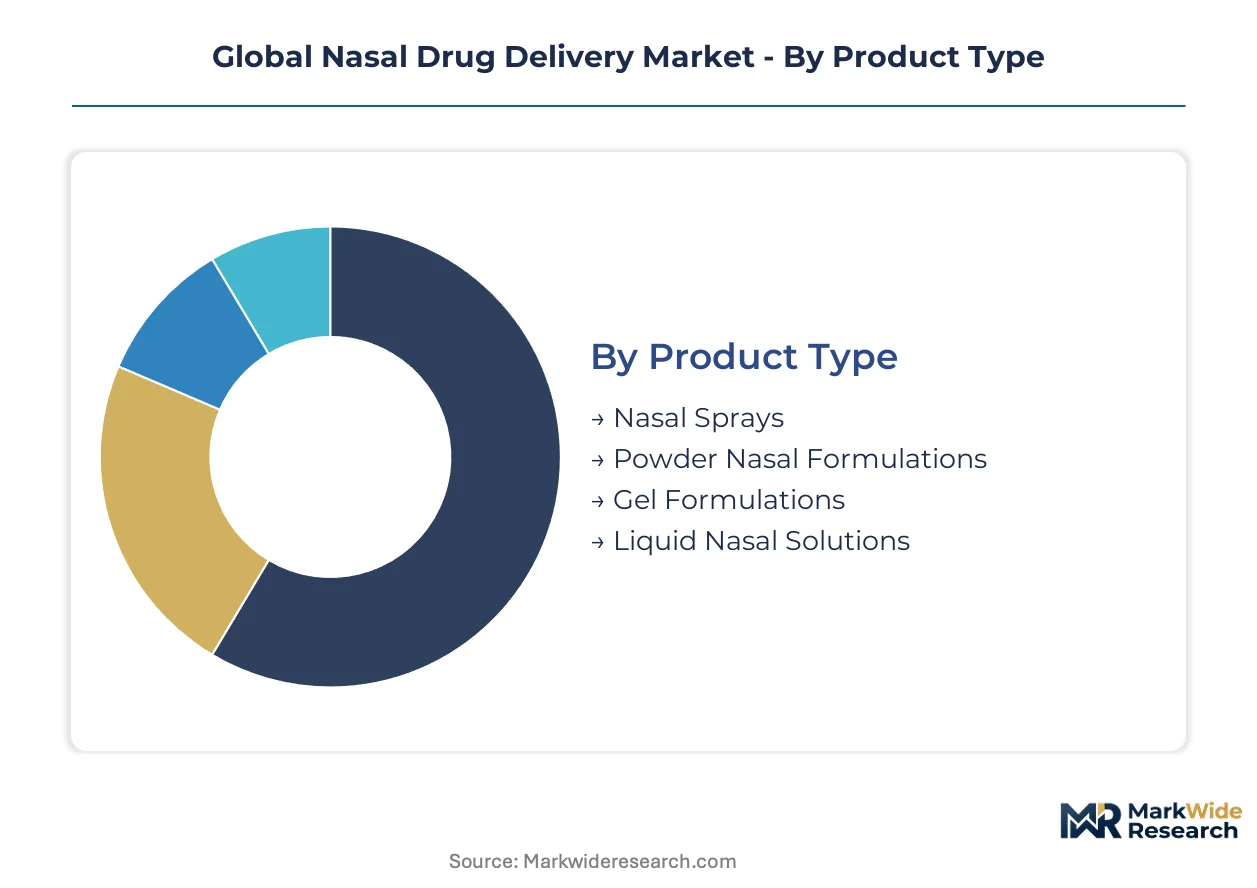
Segmentation in nasal drug delivery maps divergent regulatory pathways against formulation physics and patient self-administration readiness. Each category reveals distinct certification intensities and margin structures that shape portfolio prioritization.
Product Type:
FDA combination product rules and EMA MDR device classifications impose tiered validation burdens that scale with formulation complexity and sterility requirements.
- Nasal Sprays:Aqueous or suspension formulations delivered via mechanical pump actuators dominate prescription volumes for allergic rhinitis and acute migraine. Demand concentrates in the United States where FDA 505(b)(2) pathways accelerate generic substitution of branded liquid formulations.
- Powder Nasal Formulations:Engineered particle sizes between 10-50 microns enable thermostable biologic delivery without cold-chain infrastructure. German and Swiss manufacturers lead device integration for peptide vaccines targeting tropical distribution gaps.
- Gel Formulations:Mucoadhesive polymer matrices extend residence time on the nasal epithelium for hormonal delivery applications.
- Liquid Nasal Solutions:Simple saline-based vehicles for decongestion and irrigation occupy the lowest regulatory tier with minimal stability testing requirements.
Leading the category by volume: Nasal Sprays. Growing fastest: Powder Nasal Formulations.
End User:
Reimbursement coding and patient training infrastructure determine which settings capture margin versus volume.
- Hospitals:Acute care protocols for post-operative pain and emergency migraine administration require crash cart availability and nursing validation. Japanese tertiary centers anchor demand under METI incentives for non-injectable alternatives.
- Homecare Settings:Disposable pump designs with tamper-evident seals enable self-administration of chronic therapies including hormone replacement and prophylactic migraine regimens.
- Clinics:Specialist administration of depot formulations and vaccination campaigns in outpatient settings.
- Pharmacies:Over-the-counter distribution of decongestant and saline irrigation products with minimal counseling requirements.
Volume leadership sits with Hospitals. Steepest expansion trajectory: Homecare Settings.
Application:
Clinical endpoint validation requirements and competitive generic penetration create divergent development economics across therapeutic categories.
- Allergy Treatment:Seasonal and perennial allergic rhinitis indications command the largest patient populations with established corticosteroid and antihistamine spray formulations. United States prescription volumes reflect year-round demand in southern states and seasonal spikes in northern climates.
- Pain Management:Acute migraine and breakthrough cancer pain indications prioritize speed-to-onset metrics over duration, favoring nasal absorption kinetics over oral administration in German and Japanese hospital formularies.
- Hormonal Therapy:Replacement regimens for hypogonadism and menopausal symptoms leverage nasal pulsatile delivery to mimic physiological secretion patterns.
- Vaccination:Mucosal immune response induction for respiratory pathogens exploits nasal-associated lymphoid tissue targeting.
Allergy Treatment generates the highest prescription volumes. Pain Management is climbing the fastest on migraine therapeutic shifts.
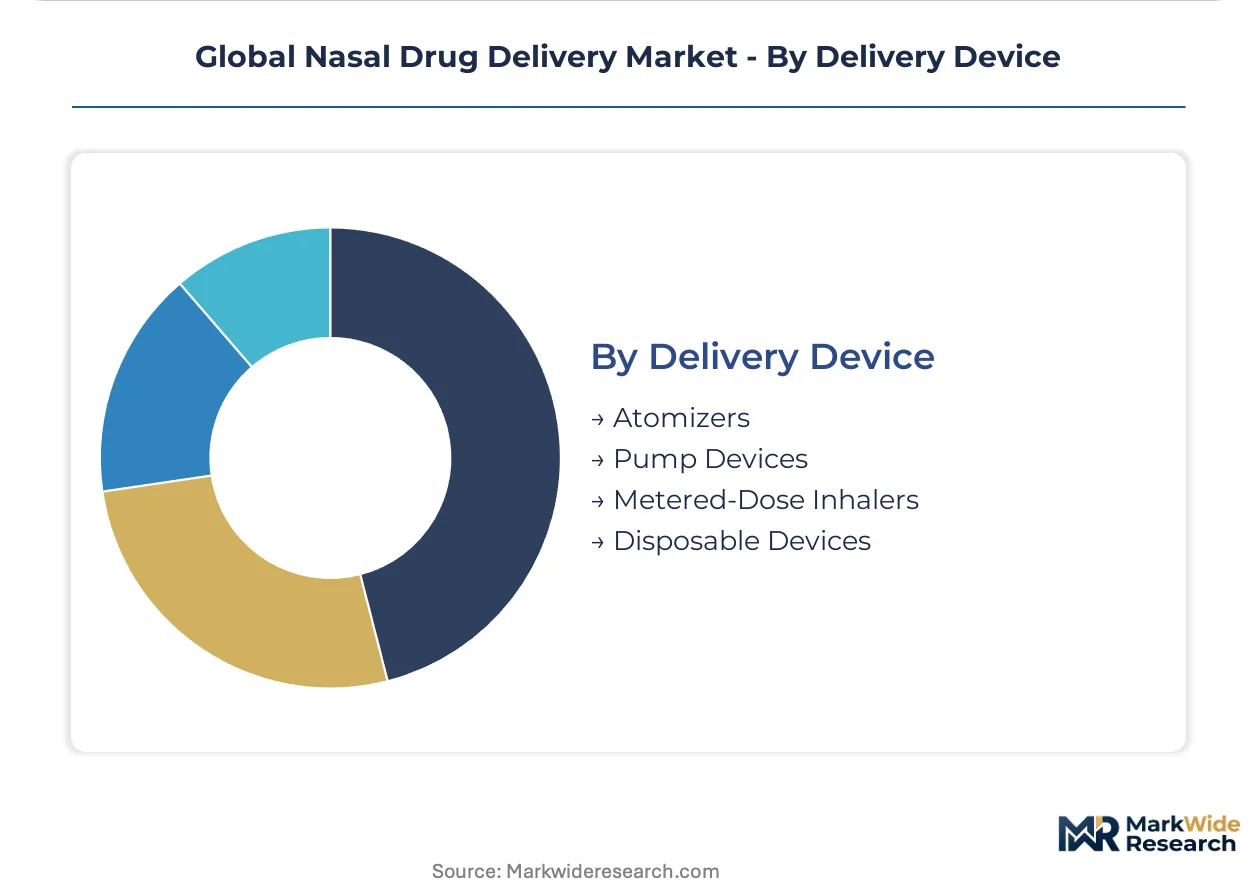
Delivery Device:
Polymer characterization and plume geometry testing requirements fragment the supplier base between captive manufacturers and contract organizations.
- Pump Devices:Mechanical actuators with precision-molded polypropylene reservoirs and silicone valves deliver metered volumes across viscosity ranges. Swiss and German polymer processors concentrate supply of critical valve components.
- Disposable Devices:Single-use designs with integrated dose-counters eliminate cross-contamination risk in homecare settings and hospital-at-home programs.
- Atomizers:Compressed gas or breath-actuated systems for emergency naloxone and sedative reversal in pre-hospital settings.
- Metered-Dose Inhalers:Pressurized propellant systems adapted from respiratory heritage with modified actuators for nasal deposition.
Pump Devices dominate unit volumes. Disposable Devices are gaining share fastest on infection control priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturing concentrates in German and Swiss polymer clusters, while prescription volume growth concentrates in aging societies with reimbursement frameworks favoring non-invasive administration. Consumption patterns diverge sharply between mature markets with established neurologist networks and emerging markets seeking cold-chain-independent distribution.
United States
FDA 505(b)(2) reformulation pathways accelerate migraine therapeutic launches as neurologists prioritize 15-minute onset kinetics over oral triptan loyalty. Medicare Part D and commercial payer formularies increasingly cover self-administered nasal devices for homecare settings. Boston and San Francisco biotech corridors host formulation specialists developing biologic-compatible powder platforms.
Germany
German hospital formularies anchor European demand for acute pain nasal formulations under EMA centralized assessment procedures. DiGA framework reimbursement for digital health convergence creates adherence-tracking partnerships between device manufacturers and health app developers. Bavarian and Baden-Württemberg polymer processors supply precision-molded polypropylene reservoirs to device integrators.
Japan
METI reimbursement incentives for geriatric-friendly delivery modalities position nasal platforms as alternatives to injectable dementia and Parkinson's therapeutics. Japanese tertiary centers drive hospital-administered acute migraine volume under national health insurance price listings. Tokyo-Osaka pharmaceutical corridors concentrate biologic nasal formulation R&D for aging population needs.
Switzerland
Swissmedic regulatory expertise and ISO 10993 biocompatibility testing infrastructure attract device manufacturers seeking dual FDA-EMA submission capabilities. Basel and Zurich polymer characterization laboratories serve as regional hubs for toxicology validation of silicone valve components. Precision manufacturing heritage supports metered-dose nasal platform development for peptide delivery.
India
CDSCO streamlined approval pathways for reformulated products attract multinational sponsors seeking tropical distribution for thermostable dry powder nasal vaccines. Cold-chain infrastructure gaps across rural geographies favor powder formulations eliminating refrigeration dependencies. Mumbai and Hyderabad manufacturing clusters assemble disposable pump devices for export to Southeast Asian markets.
Global Nasal Drug Delivery Market Competitive Landscape
Top-tier vendors anchor respiratory device heritage and pharmaceutical scale, while mid-tier specialists concentrate on polymer engineering and regional regulatory expertise. The vendor base stratifies between integrated pharmaceutical-device combinations and contract manufacturing organizations with captive toxicology capabilities. Strategic archetypes include respiratory platform extenders, biologic formulation specialists, and disposable device fabricators. Competitive moves center on M&A for polymer characterization assets and strategic partnerships for digital health convergence.
Within the respiratory heritage tier, GlaxoSmithKline and AstraZeneca exemplify platform extension strategies leveraging inhaled drug delivery expertise into nasal administration modalities. Pfizer occupies a position representing pharmaceutical scale applied to acute care hospital formularies. These three anchors illustrate divergent competitive vectors: device-integrated platforms, biologic-compatible architectures, and regulatory familiarity in institutional procurement channels.
| Leading Market Players |
|---|
| GlaxoSmithKline |
| AstraZeneca |
| Johnson & Johnson |
| Pfizer |
| Novartis |
| Merck & Co. |
| Roche Holding |
| Sanofi |
| Bristol-Myers Squibb |
| Others |
Supply & Pricing Matrix
Formulation chemists and polymer engineers in Bavaria and Baden-Württemberg command wage premiums that widen pricing spreads between premium metered-dose platforms and economy pump devices. Labor-cost differentials between Swiss precision manufacturers and Indian assembly operations create three-tier pricing dynamics that stratify across certification-grade boundaries.
Pricing Analysis
Margin tightening in economy pump devices traces to Indian contract manufacturers absorbing polymer cost volatility to maintain hospital formulary contracts. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated combination products from CE-marked devices and unregulated over-the-counter alternatives. Pricing pressure intensifies in standard-tier pump segments as German polymer processors pass through propylene feedstock fluctuations. Hospital procurement committees exhibit lowest price sensitivity due to bundled reimbursement codes, while pharmacy OTC buyers drive cost-down negotiations.
Supply Chain Analysis
Single-source vulnerability sits with Swiss silicone valve processors supplying precision-molded components to metered-dose nasal platforms. Device manufacturing concentrates in Germany, Switzerland, and India, with polymer characterization laboratories anchoring European supply and disposable assembly feeding Asian export markets. Raw material dependencies span medical-grade polypropylene, platinum-cured silicone elastomers, and electrostatic-grade thermoplastics. Tariff exposure on Chinese-sourced electronic dose-counters threatens connected device cost structures. Distribution runs through hospital GPO contracts in the United States, EMA centralized procurement in Germany, and METI-authorized distributors in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized nasal formulation talent scarcity in Dutch and Danish academic laboratories props pricing for captive device-integrated platforms. Capacity bottlenecks in ISO 10993 biocompatibility testing create margin protection for manufacturers with in-house toxicology infrastructure.
For Market Incumbents: Anchor market position through backward integration into polymer characterization capabilities and expansion of regulatory affairs headcount for parallel FDA-EMA submission tracks. Defend against emerging biologic formulation specialists by locking exclusive supply agreements with Swiss silicone valve processors. Prioritize certification investment in combination product pathways to extend 505(b)(2) development timelines. For New Entrants and Emerging Players: Begin with thermostable dry powder vaccine platforms targeting India's cold-chain infrastructure gaps and Southeast Asian distribution networks. White-space opportunity concentrates in geriatric-friendly delivery modalities for Japan's aging demographics under METI reimbursement incentives. Go-to-market angle should emphasize hospital-at-home program partnerships with Bluetooth-enabled adherence tracking. For Investors and Strategic Acquirers: The window for entry favors mid-cap device fabricators with captive toxicology capabilities and dual regulatory submission experience. Long-term viability hinges on consolidation of fragmented polymer engineering specialists in the Netherlands and Denmark. Acquisition target archetype: disposable device manufacturers with ISO 13485 quality systems and established notified body relationships. Signal to watch: EMA MDR transition completion rates and notified body capacity expansion announcements.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 505(b)(2) Submission | Accelerated approval pathways for nasal reformulations of approved migraine therapeutics compress development timelines. |
| CE Marking Pathway | EU MDR compliance for combination products opens German hospital formulary access under centralized assessment procedures. |
| Backward Integration | In-house polymer characterization capabilities reduce ISO 10993 testing bottlenecks and protect margin from contract laboratory pricing. |
| Digital Health Convergence | Bluetooth-enabled dose-counters paired with adherence apps qualify for Germany's DiGA reimbursement framework. |
| Regional Manufacturing Footprint | Indian assembly operations for disposable devices address tropical distribution gaps while maintaining Swiss component quality. |
Research Methodology
FDA 505(b)(2) filings, EMA centralized assessment records, and ISO 10993 biocompatibility test reports formed the secondary backbone for validation. Primary interviews with regulatory affairs directors, hospital formulary managers, polymer characterization specialists, and GPO contracting officers triangulated against secondary sources. Bottom-up modeling of device unit volumes and top-down validation against pharmaceutical R&D expenditure patterns anchored market sizing.
Bottom-up segmentation modeling across product type, end-user setting, therapeutic application, and delivery device architecture generated volume and value outputs. CAGRs derived from regression analysis of historical approval timelines and reimbursement code expansion patterns. Forecast inputs incorporated 505(b)(2) pathway utilization rates, METI geriatric-friendly modality incentives, and cold-chain infrastructure development trajectories across tropical geographies.
Underlying measurement precision varies by segment; established nasal spray categories carry tighter precision than emerging powder formulation platforms. Forecasts reflect assumptions regarding regulatory harmonization progress and notified body capacity expansion. Pandemic-related supply disruptions, polymer feedstock volatility, and olfactory route pharmacovigilance rulings could revise trajectory assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Iron Deficiency Injectables Market
Pharmaceuticals
Global Cardiovascular Drugs Market
Pharmaceuticals
Metastatic Cancer Treatment Drug Market
Pharmaceuticals
Intravenous (IV) Iron Drugs Market
Pharmaceuticals
Asia Pacific SGLT2 Inhibitors Market
Pharmaceuticals
Europe Oral Anti-Diabetic Drug Market
Pharmaceuticals
Estrogen Replacement Therapy (ERT) Market
Pharmaceuticals
Human Growth Hormone Treatment and Drugs Market
Pharmaceuticals
Global Montelukast Sodium Market
Pharmaceuticals
Intranasal Migraine Drugs Market
Pharmaceuticals
Denmark Pharmaceutical Market
Pharmaceuticals
Global Pulmonary Drugs Market
Pharmaceuticals
Metformin Hydrochloride Market
Pharmaceuticals
Authorized Generics Market
Pharmaceuticals
Asia-Pacific Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Europe Heparin Market