
 B7-H3 Antibody Market | 2026-2036
B7-H3 Antibody Market Size, Share, and Industry Trends Forecast 2026-2036
B7-H3 Antibody Market Insights
Antibody-drug conjugate engineering is tilting development priorities toward payload optimization and linker stability. Thermo Fisher Scientific leverages its analytical instrument and reagent ecosystem to anchor downstream workflow adoption. Merck sustains competitive pressure through its integrated CDMO and discovery reagent portfolio. Bio X Cell specializes in in vivo-grade antibody supply, occupying a defensible niche in preclinical research demand.
B7-H3 antibodies are immunoglobulin-based reagents that bind the B7-H3 surface protein, a member of the B7 superfamily implicated in immune checkpoint modulation and tumor immune evasion; these reagents typically function through Fc-mediated effector mechanisms or as targeting moieties for cytotoxic payloads in oncology applications. Monoclonal antibodies dominate current therapeutic pipelines due to their specificity and manufacturability at clinical scale. Recombinant antibodies represent the fastest-growing product category as phage display and transgenic platform technologies displace hybridoma-dependent methods. Oncology commands the largest therapy area share, while autoimmune disease applications remain exploratory with limited Phase II evidence.
FDA oversees IND-enabling toxicology and BLA review pathways that determine antibody therapeutic market access timelines. EMA's MDR and ATMP frameworks impose additional manufacturing and clinical evidence standards for European commercialization. China's NMPA has aligned its antibody technical review guidelines with ICH standards, reducing regulatory friction for multi-regional trials. Stakeholders must monitor evolving FDA guidance on ADC immunogenicity assessment and NMPA biologics master file requirements as these will determine which development programs advance to pivotal studies.
Market Dynamics
Antibody-drug conjugate payload optimization is compressing development timelines and forcing CMC teams to front-load analytical characterization before IND filing. This structural pressure favors developers with integrated discovery-to-manufacturing platforms over asset-light biotechs dependent on external CDMOs.
Growth Catalysts
- FDA Accelerated Approval Pathways:The agency's breakthrough therapy and fast track designations for ADCs compress Phase I-to-approval timelines, pulling forward revenue recognition for B7-H3 programs targeting refractory solid tumors.
- China NMPA ICH Alignment:Harmonized technical review guidelines enable simultaneous multi-regional trials, reducing redundant toxicology studies and accelerating patient enrollment across Beijing, Shanghai, and Guangzhou clinical sites.
- Site-Specific Conjugation Chemistry:Engineered cysteine and enzymatic ligation technologies improve drug-antibody ratio homogeneity, reducing batch failure rates during GMP manufacturing scale-up.
Market Restraints
- Payload-Linker IP Thickets:Maytansinoid and auristatin derivative patents held by Seattle Genetics and ImmunoGen create licensing friction for second-generation ADC developers, elevating program costs before clinical proof-of-concept.
- Single-Source Critical Reagents:GMP-grade hygromycin and chemically defined media concentrate with three dominant suppliers, exposing manufacturing campaigns to allocation risk during demand surges.
- Tumor Heterogeneity:B7-H3 expression variability across patient samples complicates companion diagnostic development, limiting addressable populations in registrational trials.
Strategic Opportunities
- Autoimmune Indication Expansion:Preclinical data in rheumatoid arthritis and lupus models suggest Fc-engineered B7-H3 antibodies may modulate pathogenic T cell responses, opening addressable markets beyond oncology.
- India CDMO Partnerships:Contract development capacity in Hyderabad and Bangalore offers cost-advantaged GMP manufacturing for early-phase clinical supply, hedging against US and European capacity constraints.
- EMA PRIME Designation:Priority medicines status delivers accelerated assessment and enhanced regulatory dialogue, compressing European market access timelines for programs targeting unmet medical need.
Industry Challenges
- ADC Bioanalytical Talent Scarcity:Specialized skillsets spanning ligand-binding assays, immunogenicity assessment, and pharmacokinetic modeling concentrate within Boston and San Francisco talent pools, elevating compensation costs for distributed teams.
- Multi-Attribute Method Validation:Complex quality attributes including drug loading distribution, unconjugated antibody fraction, and aggregate levels require extended analytical development timelines that compress formulation stability windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | B7-H3 Antibody Market |
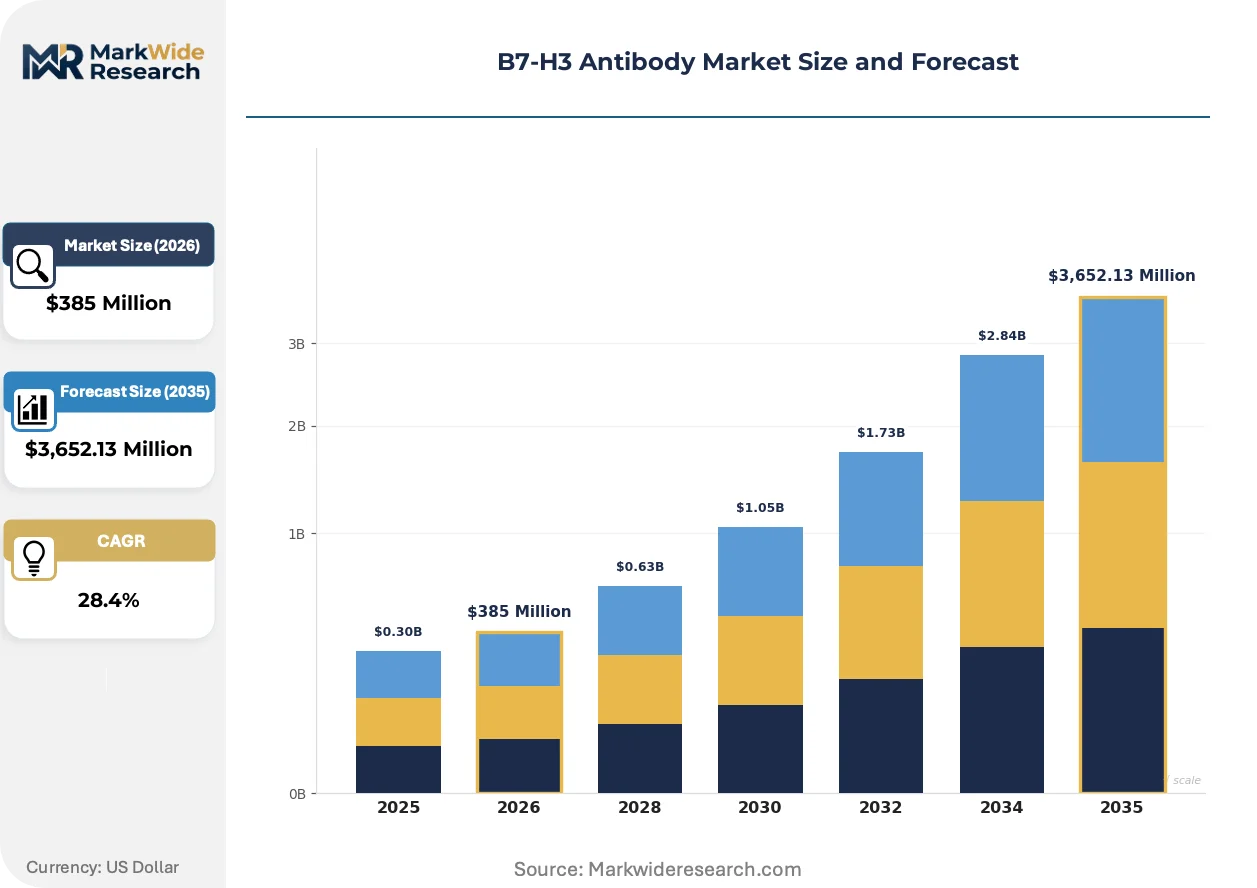
| Market Size in 2026 | $385 Million |
| Market Size in 2035 | $3,652.13 Million |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Recombinant Antibodies, Polyclonal Antibodies, Fusion Proteins Therapy Area: Oncology, Autoimmune Diseases, Infectious Diseases, Neurological Disorders Delivery Mode: Intravenous, Subcutaneous, Intramuscular, Oral End User: Hospitals, Research Laboratories, Diagnostic Centers, Biopharmaceutical Companies |
| Companies Covered | Sino Biological, Santa Cruz Biotechnology, Thermo Fisher Scientific, Boster Biological Technology, Bio X Cell, Merck, Cell Signaling Technology, LSBio, BD Biosciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
B7-H3 Antibody Market Trends and Innovations
Computational protein engineering and high-throughput screening platforms are compressing antibody optimization cycles from years to months. This acceleration is restructuring competitive advantage around data infrastructure and algorithmic prediction rather than hybridoma library depth alone.
Phage display libraries coupled with next-generation sequencing are digitizing epitope mapping and affinity maturation workflows. Large pharma antibody engineering groups deploy these platforms to exhaustively profile B7-H3 extracellular domain variants, compressing lead selection from 18-month campaigns to 4-month iterations. The resulting candidate diversity is digitizing intellectual property generation, enabling broader claim construction around paratope-specific binding modes.
EMA's updated MDR guidance on implantable and absorbable medical devices extends to ADC infusion systems, requiring biocompatibility documentation for programmable pumps used in outpatient oncology settings. Device manufacturers must submit clinical evaluation reports demonstrating material safety during extended dwell times. European oncology clinics are responding by consolidating infusion pump procurement around CE-marked platforms with pre-validated ADC compatibility dossiers.
Site-of-care manufacturing is disrupting traditional cold-chain distribution for clinical trial supply. Academic medical centers in Texas, Pennsylvania, and North Carolina now operate on-site aseptic filling suites for Phase I ADC formulation, eliminating cross-country logistics risk for temperature-sensitive payloads. This decentralization is most visible in NCI-designated cancer centers competing for early-phase investigator-initiated studies.
B7-H3 Antibody Market Segmentation
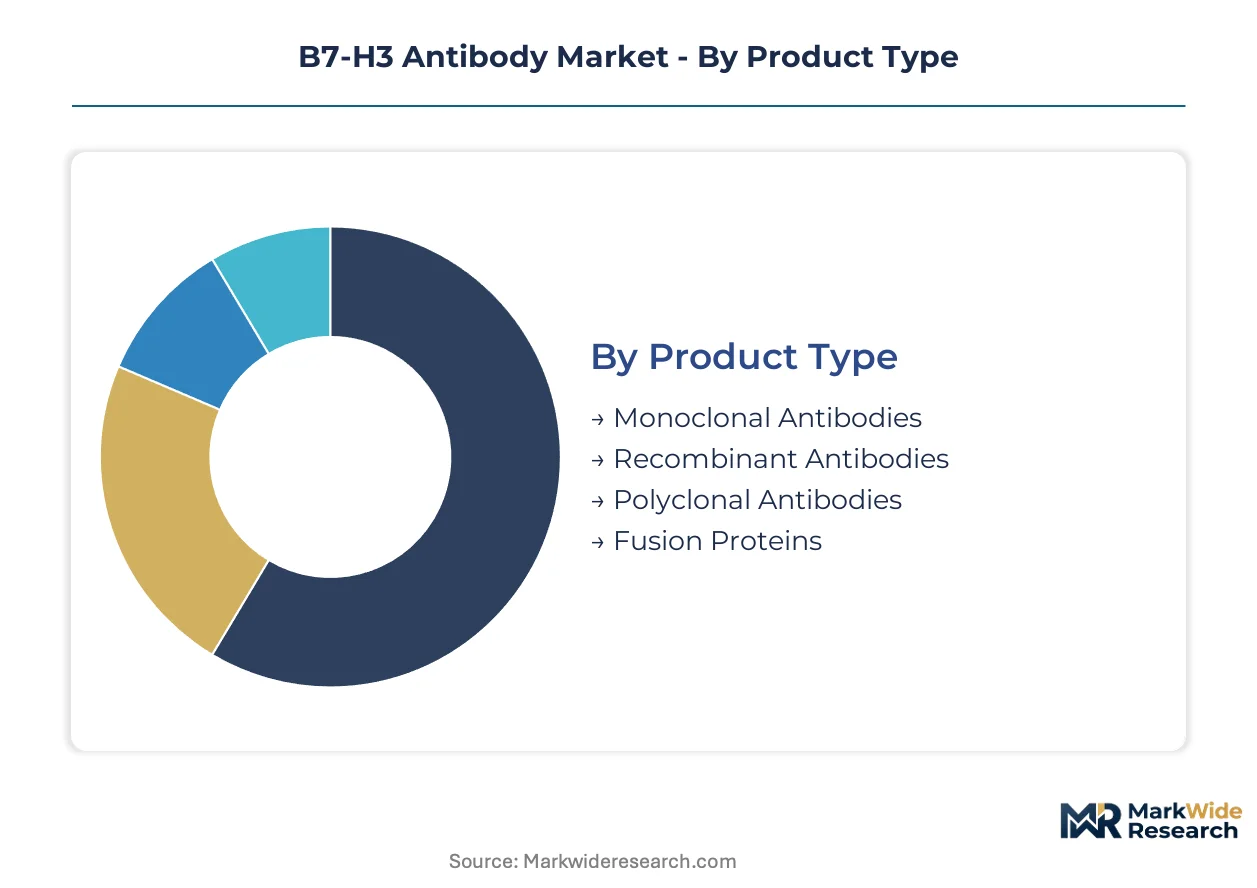
Segmentation of the B7-H3 antibody market reveals how product architecture, clinical application, and delivery logistics intersect to determine commercial viability. Each dimension carries distinct regulatory, manufacturing, and reimbursement implications that reshape competitive positioning across development stages.
Product Type:
Mature hybridoma-derived formats anchor current revenue while engineered recombinant platforms accelerate pipeline replacement.
- Monoclonal Antibodies:IgG1 and IgG4 isotypes dominate therapeutic development due to established Fc effector function engineering and GMP manufacturing protocols at 10,000-liter bioreactor scale. Demand concentrates in late-phase oncology trials across Massachusetts and California clinical research organizations, where FDA IND timelines pressure developers toward proven molecular formats with existing CMC packages.
- Recombinant Antibodies:Phage display and transgenic animal platforms enable rapid affinity maturation and humanization without hybridoma dependency, compressing lead optimization from 18 months to 4-month cycles. Chinese biotechs in Shanghai and Suzhou are deploying these technologies to bypass traditional patent thickets, capturing preclinical contract research demand from multinational pharmas seeking geographic diversification.
- Polyclonal Antibodies:Rabbit and goat-derived reagents serve diagnostic assay development and research-grade applications where epitope breadth outweighs batch consistency requirements.
- Fusion Proteins:B7-H3-Fc constructs and bispecific formats remain exploratory, with limited clinical validation outside academic investigator-initiated studies.
Monoclonal antibodies handle the majority of throughput; recombinant antibodies are expanding most quickly on share.
Therapy Area:
Oncology applications command development resources while autoimmune indications attract exploratory preclinical investment.
- Oncology:Solid tumor targeting via antibody-drug conjugates and checkpoint modulation drives Phase II and III pipeline density, with B7-H3 expression in pediatric neuroblastoma and adult lung malignancies guiding patient stratification. FDA breakthrough therapy designations for refractory indications pull forward revenue recognition timelines for developers with registrational data.
- Autoimmune Diseases:Fc-engineered B7-H3 antibodies demonstrate T cell suppression in rheumatoid arthritis and systemic lupus erythematosus mouse models, though human proof-of-concept remains limited to early academic collaborations.
- Infectious Diseases:Neutralizing antibody applications against viral pathogens remain theoretical, lacking published in vivo efficacy data.
- Neurological Disorders:Blood-brain barrier penetration challenges constrain CNS-targeting B7-H3 programs to vectorized delivery research at Stanford and University of Pennsylvania gene therapy centers.
Oncology commands the dominant revenue share; autoimmune disease applications show the steepest expansion trajectory in preclinical investment.
Delivery Mode:
Route selection determines formulation stability requirements, cold-chain infrastructure, and site-of-care staffing models.
- Intravenous:Hospital-based infusion centers with programmable pump infrastructure dominate ADC administration, requiring temperature-controlled storage at 2-8°C and validated aseptic handling protocols. EMA MDR biocompatibility requirements for infusion systems add regulatory documentation burden for European commercialization.
- Subcutaneous:Self-administration potential and reduced clinic burden position subcutaneous delivery as the preferred route for maintenance therapy in autoimmune indications, though high-concentration formulation development extends timelines.
- Intramuscular:Limited to vaccine-adjuvant applications and depot-formulation research without established B7-H3 therapeutic precedent.
- Oral:Gastrointestinal degradation and epithelial permeability barriers render oral delivery non-viable for immunoglobulin-based therapeutics.
Intravenous administration handles the majority of current patient volume; subcutaneous delivery is gaining share fastest among pipeline assets.
End User:
Customer type dictates pricing architecture, technical support intensity, and regulatory documentation depth.
- Hospitals:NCI-designated cancer centers and academic medical centers in Boston, Houston, and New York anchor therapeutic antibody procurement, with pharmacy and therapeutics committees demanding real-world evidence and budget impact models for formulary inclusion.
- Research Laboratories:University core facilities and contract research organizations in San Diego and Research Triangle Park drive demand for catalog antibodies with batch-specific certificates of analysis and lot-matching guarantees.
- Diagnostic Centers:Companion diagnostic developers require GMP-grade antibody supply with extended stability data to support PMA submissions to FDA and CE marking under IVDR.
- Biopharmaceutical Companies:Large pharma antibody engineering groups and emerging biotechs in Cambridge and South San Francisco source critical reagents for target validation, with in vivo-grade specifications and animal-origin-free certifications determining supplier selection.
Hospitals handle the majority of therapeutic throughput; biopharmaceutical companies are the fastest mover on procurement volume as pipeline assets advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic medical centers and NCI-designated cancer centers concentrate procurement power in the United States, while contract manufacturing demand clusters in Chinese biotech hubs. Biopharmaceutical R&D investment flows toward Boston, San Francisco, and Shanghai, creating distinct buyer archetypes across development-stage versus commercial-stage markets.
United States
FDA breakthrough therapy designations for B7-H3 antibody-drug conjugates accelerate Phase I-to-approval timelines, pulling forward revenue recognition for developers targeting refractory solid tumors. The agency's updated guidance on ADC immunogenicity assessment reshapes CMC package requirements before IND filing. Massachusetts and California clinical research organizations anchor therapeutic antibody demand, with pharmacy and therapeutics committees at NCI-designated centers demanding real-world evidence for formulary inclusion.
China
NMPA alignment with ICH technical review guidelines enables simultaneous multi-regional trials, reducing redundant toxicology studies and accelerating patient enrollment. The regulator's biologics master file requirements determine which development programs advance to pivotal studies. Shanghai and Suzhou biotech clusters deploy phage display and transgenic platforms to bypass traditional patent thickets, capturing preclinical contract research demand from multinational pharmas.
Germany
EMA PRIME designation delivers accelerated assessment and enhanced regulatory dialogue for priority medicines targeting unmet medical need. The agency's MDR framework imposes additional manufacturing and clinical evidence standards for European commercialization of antibody-drug conjugates. Heidelberg and Munich academic medical centers operate centralized pharmacy compounding units for clinical trial supply, consolidating regional procurement decisions.
United Kingdom
MHRA operates under retained EU law post-Brexit while diverging on ATMP framework implementation, creating regulatory navigation complexity for multi-regional trial sponsors. The agency's accelerated access collaborative routes early-stage therapies toward NHS evaluation. London and Cambridge antibody engineering groups source critical reagents for target validation, with in vivo-grade specifications determining supplier selection.
Japan
PMDA's sakigake designation system compresses review timelines for regenerative medicine and breakthrough therapies, though B7-H3 programs remain predominantly in early-phase development. The regulator's alignment with ICH E6(R2) guidelines streamlines clinical trial conduct for multinational sponsors. Tokyo and Osaka pharmaceutical clusters concentrate on licensing partnerships rather than indigenous antibody platform development.
B7-H3 Antibody Market Competitive Landscape
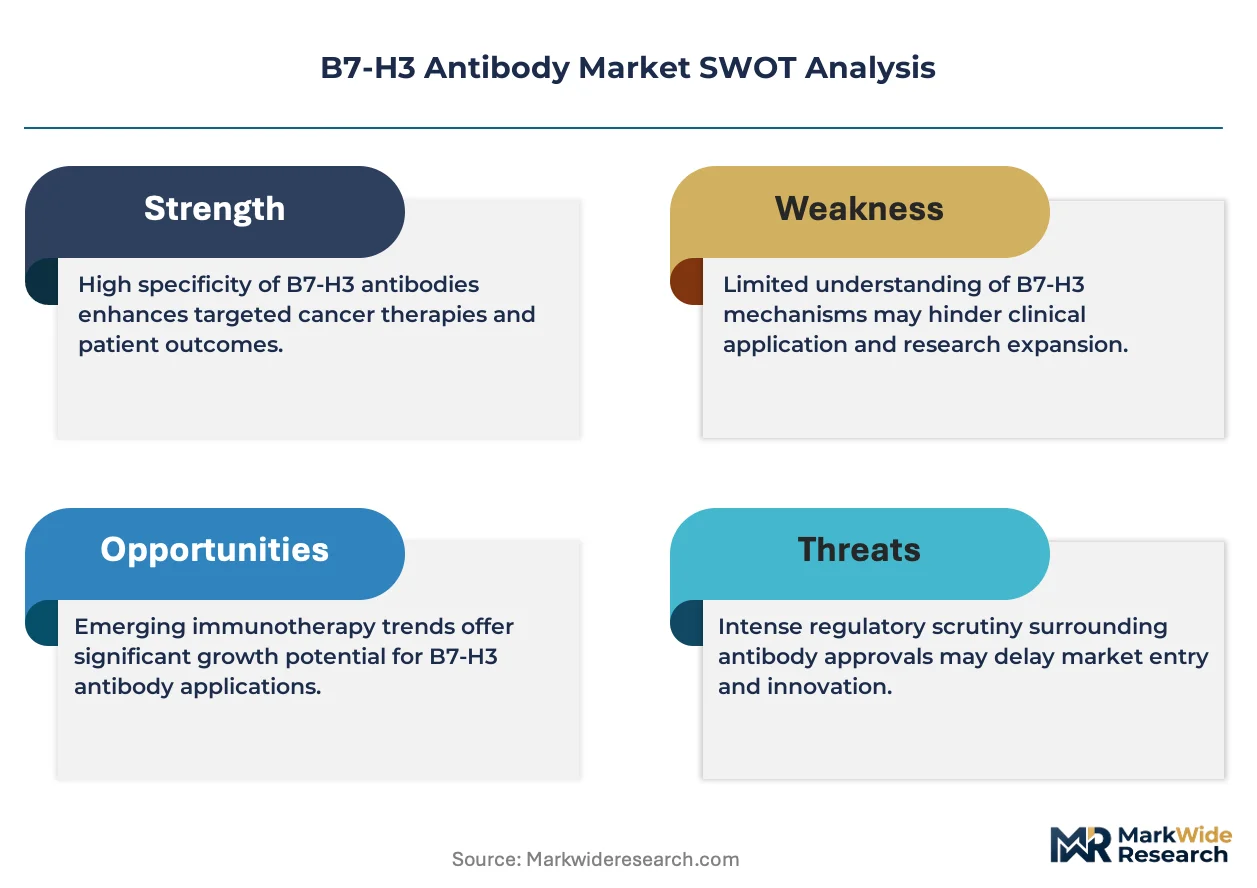
Channel-controlling players compete with product-specialist players across fragmented supply tiers. Thermo Fisher Scientific anchors the analytical instrument and reagent ecosystem, while Merck sustains pressure through integrated CDMO capabilities. Three strategic archetypes dominate: diversified life science conglomerates with workflow lock-in, specialized in vivo-grade antibody suppliers, and regional CDMOs with cost-advantaged GMP capacity. Competitive moves concentrate on strategic partnerships for payload-linker access and site-specific conjugation technology licensing.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Merck represent channel-controlling archetypes that anchor downstream workflow adoption through integrated instrument-reagent-service bundles. Bio X Cell occupies a defensible position among product specialists, exemplifying the in vivo-grade antibody supplier archetype that serves preclinical research demand with batch consistency guarantees. Sino Biological and LSBio sit within the recombinant platform specialist tier, where phage display and transgenic technologies displace hybridoma-dependent methods.
| Leading Market Players |
|---|
| Sino Biological |
| Santa Cruz Biotechnology |
| Thermo Fisher Scientific |
| Boster Biological Technology |
| Bio X Cell |
| Merck |
| Cell Signaling Technology |
| LSBio |
| BD Biosciences |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Chinese GMP bioreactor facilities is compressing contract manufacturing margins and forcing suppliers toward multi-year service agreements with price floors. This utilization dynamic shifts pricing power toward developers with integrated discovery-to-manufacturing platforms, while asset-light biotechs face escalating procurement costs for outsourced CMC packages.
Pricing Analysis
Cost-plus contracts with raw material indexation dominate CDMO relationships, insulating manufacturers from hygromycin and chemically defined media volatility. Three-tier pricing structure across premium, standard, and economy levels separates GMP-grade therapeutic supply from research-grade catalog antibodies and diagnostic reagents. Pricing pressure stems from payload-linker licensing fees concentrated with Seattle Genetics and ImmunoGen patent estates. Academic medical centers exhibit highest price sensitivity due to fixed grant funding constraints, while large pharma antibody engineering groups prioritize batch consistency over unit cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Thermo Fisher Scientific and Merck are locking in multi-year reagent procurement commitments from distributed biotechs. Manufacturing capacity concentrates in the United States, China, and Germany, with Boston, Shanghai, and Heidelberg anchoring clinical-scale production. Critical inputs include GMP-grade hygromycin, protein A chromatography resins, and single-use bioreactor bags. Single-source vulnerability for chemically defined media creates allocation risk during demand surges. Distribution runs through cold-chain logistics networks terminating at NCI-designated cancer center pharmacies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA accelerated approval pathways for antibody-drug conjugates are pulling forward commercialization timelines, creating an early-cycle expansion opportunity as B7-H3 programs transition from preclinical to registrational stages.
For Market Incumbents: Insulate GMP manufacturing margins by securing captive supply of site-specific conjugation chemistries through exclusive licensing or backward integration into enzymatic ligation technology. Lock in multi-year service agreements with NCI-designated cancer centers before site-of-care manufacturing disrupts traditional distribution. Prioritize regulatory affairs investment to navigate evolving FDA immunogenicity guidance and EMA MDR biocompatibility requirements.
For New Entrants and Emerging Players: Build out autoimmune indication capabilities ahead of human proof-of-concept data, capturing preclinical contract research demand from rheumatoid arthritis and lupus programs. Target India CDMO partnerships in Hyderabad and Bangalore for cost-advantaged early-phase clinical supply. Penetrate the fragmented diagnostic reagent segment through GMP-grade antibody supply with extended stability data for companion diagnostic developers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platform-specialist CDMOs with integrated payload-linker access and site-specific conjugation capabilities. Long-term viability hinges on regulatory navigation capacity across FDA, EMA, and NMPA jurisdictions. Target acquisition archetype: recombinant antibody platform specialists with phage display infrastructure and Chinese biotech relationships. Watch for EMA PRIME designation announcements as inflection indicators for European market access acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses Phase I-to-approval timelines for refractory solid tumor indications. |
| Manufacturing Scale-Up | Site-specific conjugation chemistry deployment reduces batch failure rates during GMP manufacturing scale-up. |
| Licensing Agreement | Payload-linker IP access from Seattle Genetics and ImmunoGen clears patent thickets for second-generation ADC developers. |
| Clinical Trial Advancement | Simultaneous multi-regional trials across FDA, EMA, and NMPA jurisdictions accelerate patient enrollment. |
| Pipeline Diversification | Fc-engineered B7-H3 antibodies for rheumatoid arthritis and lupus expand addressable markets beyond oncology. |
Research Methodology
A spread of perspectives from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers converged on the working assumptions. Primary interviews combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases anchored the evidence base. Bottom-up patient-flow modeling and top-down therapeutic antibody market sizing were triangulated to constrain variance.
Demand-supply balance dynamics across the projection horizon shaped the analytical framework. Segmentation dimensions included product architecture, therapy area, administration route, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to adoption-phase penetration data. Forecast inputs incorporated clinical trial advancement rates, regulatory designation velocity, and CDMO capacity utilization signals.
Sensitivities concentrate around clinical trial failure rates, regulatory guidance revisions, and payload-linker licensing cost inflation. Forecasts reflect documented assumptions regarding patient stratification biomarker adoption and site-of-care manufacturing penetration. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Penicillin Market
Pharmaceuticals
Global Blood Plasma Derivatives Market
Pharmaceuticals
Mitochondrial-Based Therapeutics Market
Pharmaceuticals
Tumor Necrosis Factor Alpha Inhibitors Market
Pharmaceuticals
Organ Transplant Immunosuppressant Drugs Market
Pharmaceuticals
Long-Acting Monoclonal Antibodies Market
Pharmaceuticals
Rupatadine Fumarate API Market
Pharmaceuticals
Anti-Viral Therapeutics Market
Pharmaceuticals
Global Vaccine Contract Manufacturing Market
Pharmaceuticals
Carglumic Acid Market
Pharmaceuticals
Botulinum Toxin Market
Pharmaceuticals
Anticholinergic Drugs Market
Pharmaceuticals
Global Preventive Vaccines Market
Pharmaceuticals
Middle East and Africa Laxative Market
Pharmaceuticals
Efinaconazole Market
Pharmaceuticals
Erdosteine Market