
 Indapamide Market | 2026-2036
Indapamide Market Size, Share, and Industry Trends Forecast 2026-2036
Indapamide Market Intelligence
Indian API manufacturers is pivoting toward finished-dose indapamide exports to regulated markets. Servier leverages its originator heritage in European hospital tenders. Teva Pharmaceutical Industries Ltd. anchors North American retail pharmacy supply through vertically integrated generic production. Glenmark Pharmaceuticals Ltd. competes in emerging markets with cost-optimized tablet formulations.
Indapamide is a thiazide-like diuretic containing a sulfonamide-derived indoline ring with chlorobenzene substitution, exerting antihypertensive action through inhibition of sodium reabsorption in the distal convoluted tubule. The compound serves primarily as a first-line or adjunct therapy for essential hypertension and edema management in chronic heart failure patients. Tablet formulations dominate current prescription volumes due to established bioequivalence data and payer familiarity, while extended-release tablets command premium positioning in adherence-focused therapy protocols. Therapy area demand clusters in hypertension management, with nephrology centers and cardiology clinics representing concentrated end-user channels where protocol-driven prescribing sustains volume.
The US FDA bioequivalence standards and EMA quality guidelines govern market access for generic indapamide entrants, while India's CDSCO manufacturing facility inspections shape API sourcing reliability for downstream formulators. Pricing pressure from centralized procurement in European hospital systems and US pharmacy benefit managers is compressing margin pools across distribution channels. Stakeholders must monitor regulatory inspection outcomes at key API manufacturing sites and evaluate channel consolidation risks in wholesale distribution.
Market Dynamics
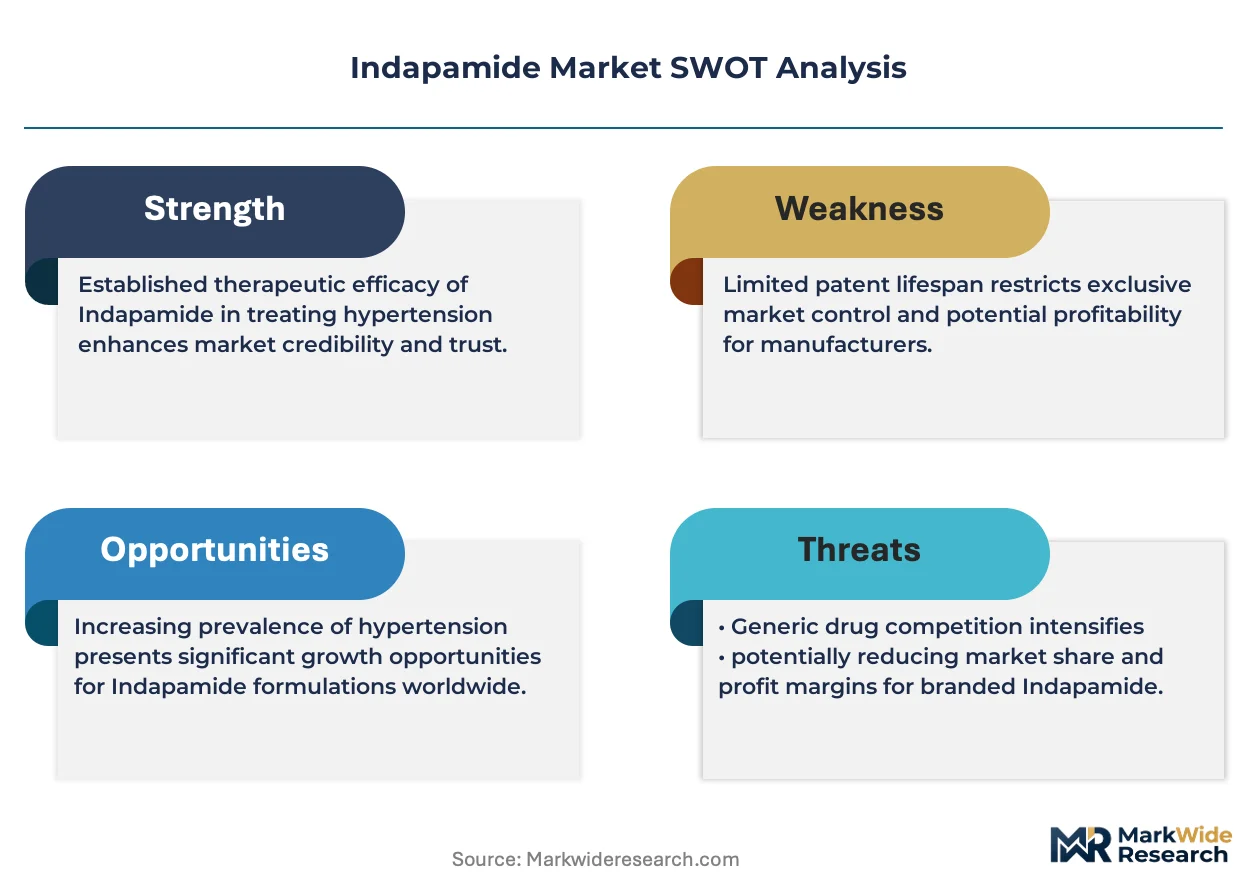
Generic substitution pressures in hospital procurement are compressing margin pools across distribution channels, forcing manufacturers to differentiate through bioequivalence data packages and vertically integrated supply chains.
Growth Catalysts
- EMA quality guidelines:Stringent European manufacturing standards create barriers to entry that reward established players with inspection-ready facilities, consolidating volume among compliant suppliers.
- Geriatric care networks:Aging patient populations in Germany, Japan, and the United States drive protocol-driven prescribing for hypertension management in institutional settings.
- Extended-release tablet technology:Modified-release formulations command premium positioning in adherence-focused therapy protocols, creating value differentiation beyond commodity tablet pricing.
Market Restraints
- API supply concentration:Indian API manufacturers dominate active pharmaceutical ingredient production, creating geographic single-source risk for downstream formulators dependent on CDSCO-inspected facilities.
- US FDA bioequivalence requirements:Complex dissolution profile matching for thiazide-like diuretics extends development timelines and elevates generic entry costs.
- Centralized procurement systems:European hospital tenders and US pharmacy benefit managers extract price concessions through volume aggregation, compressing manufacturer margins.
Strategic Opportunities
- Regulated market exports:Indian finished-dose manufacturers can pivot from API supply to direct tablet exports meeting FDA and EMA standards, capturing value currently retained by Western formulators.
- Chronic heart failure protocols:Edema management applications in nephrology centers represent underpenetrated therapy areas where protocol adoption lags hypertension prescribing.
- Direct-to-pharmacy distribution:Bypassing wholesale consolidation through direct retail pharmacy relationships preserves margin and improves inventory visibility.
Industry Challenges
- Bioanalytical method transfer:Complex chromatographic assay validation for indapamide metabolites creates bottlenecks when shifting production between manufacturing sites.
- Facility inspection alignment:Synchronizing FDA, EMA, and CDSCO inspection schedules demands specialized regulatory affairs capacity that mid-tier manufacturers struggle to maintain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indapamide Market |
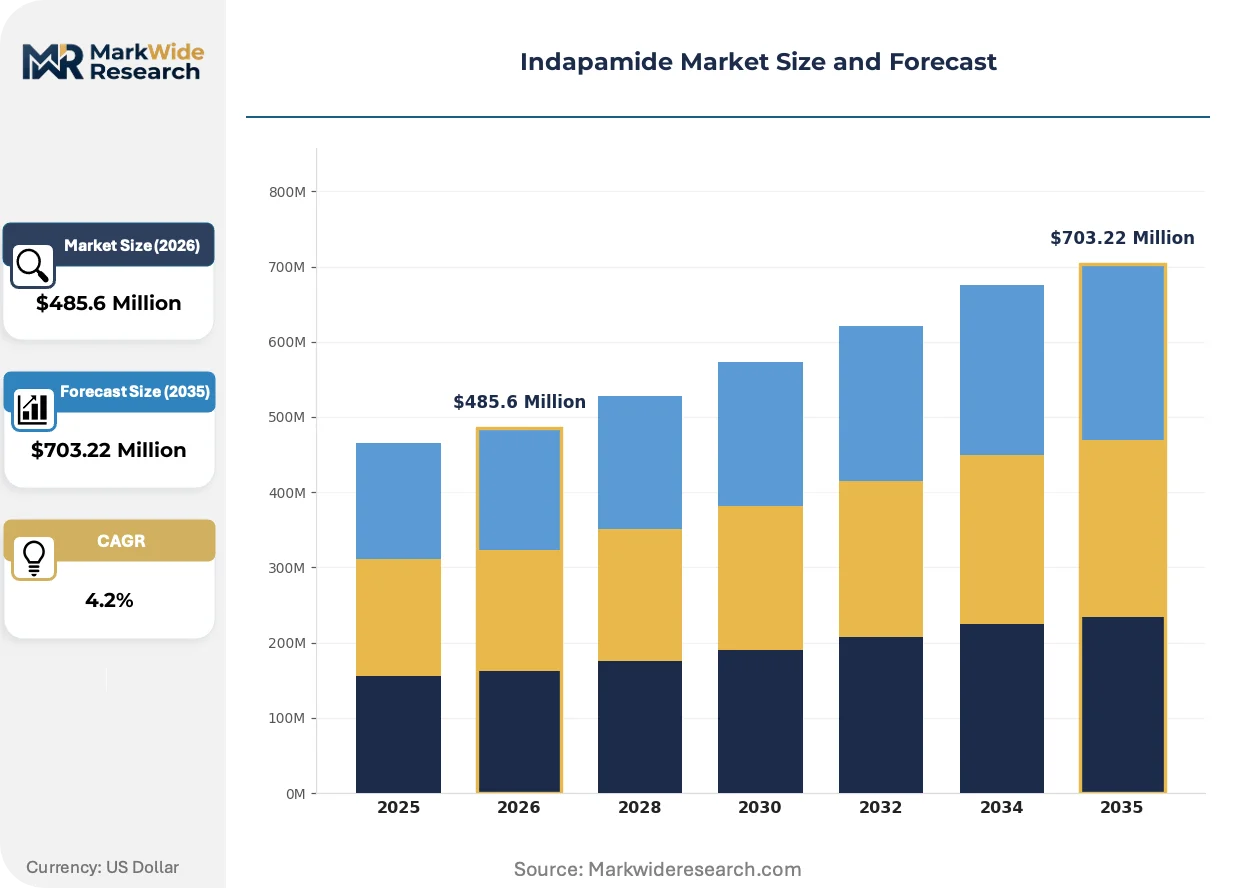
| Market Size in 2026 | $485.6 Million |
| Market Size in 2035 | $703.22 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablet, Extended-Release Tablet, Oral Suspension, Capsule Therapy Area: Hypertension, Edema, Heart Failure, Renal Disease, Cirrhosis End User: Cardiology Clinics, Nephrology Centers, Geriatric Facilities, Ambulatory Care, Specialized Clinics Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Wholesale Distributors, Direct Sales |
| Companies Covered | Servier, Sanofi S.A., Teva Pharmaceutical Industries Ltd., Mylan N.V., ANI Pharmaceuticals, Glenmark Pharmaceuticals Ltd., Apotex Inc., Sun Pharmaceutical Industries Ltd., Aurobindo Pharma Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indapamide Market Strategic Shifts & Innovations
Formulation science and regulatory data requirements are reshaping competitive positioning in thiazide-like diuretics, with differentiation shifting from molecular innovation to delivery technology and compliance infrastructure.
Modified-release polymer matrix systems are consolidating market share among manufacturers capable of demonstrating equivalent pharmacokinetic profiles to originator extended-release products. Cardiology clinics in Germany and Japan are adopting these formulations for polypharmacy patients where dosing simplicity improves adherence. The technology is consolidating volume toward integrated manufacturers with captive excipient supply and in-house dissolution testing laboratories.
REACH registration requirements for pharmaceutical excipients are tightening supply chain documentation standards across European formulation sites. Manufacturers must now trace sulfonamide-derived intermediates through multi-tier supplier networks to demonstrate compliance. Tablet producers with backward integration into excipient sourcing are capturing preferred supplier status in EMA-regulated tenders.
Hospital formulary committees are consolidating approved supplier lists to single-source or dual-source arrangements per therapeutic class. Wholesale distributors in the United States are responding by offering inventory guarantees and just-in-time replenishment to retain access. This concentration is most visible in integrated delivery networks where pharmacy benefit manager alignment drives protocol compliance.
Indapamide Market Segmentation
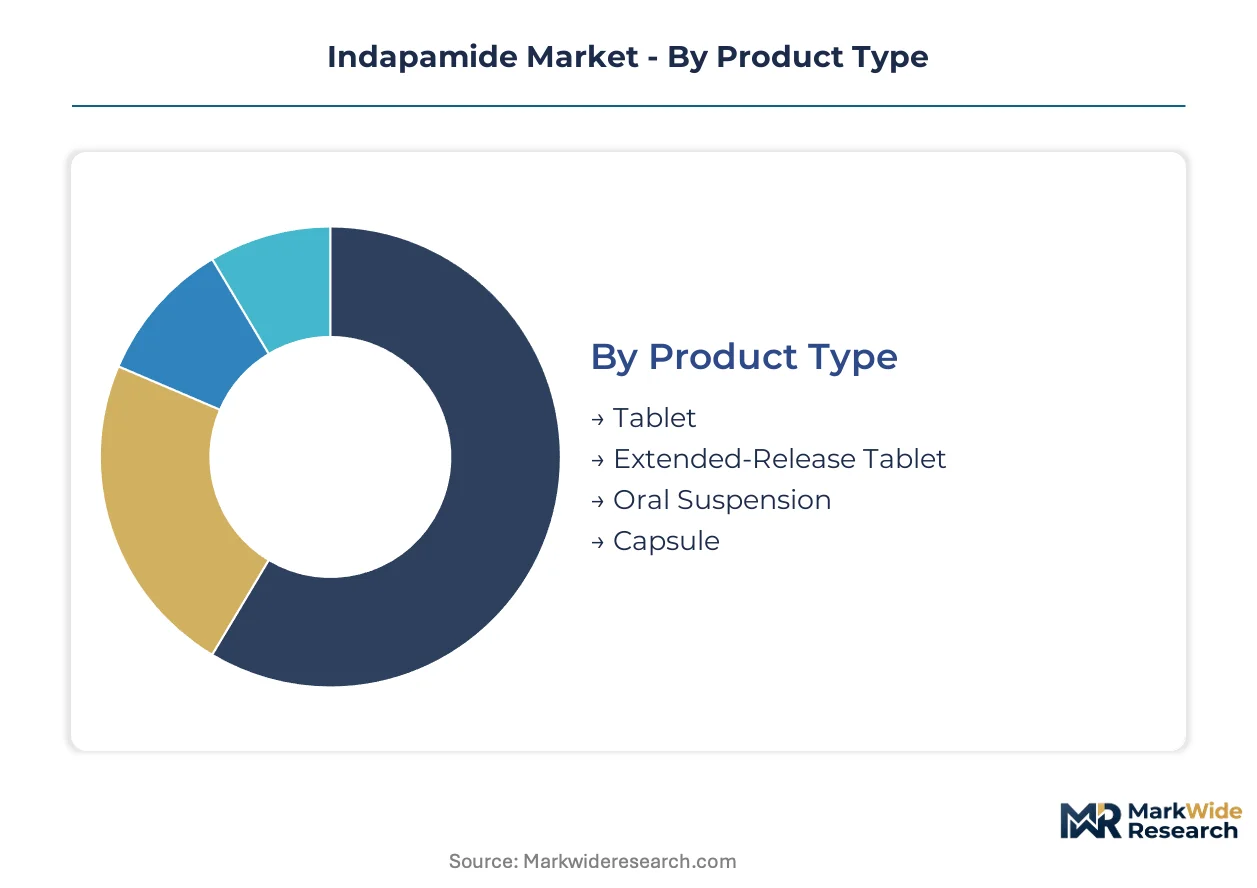
Indapamide's therapeutic positioning across hypertension and edema management creates distinct demand profiles by formulation, care setting, and procurement channel. Segmentation reveals where value concentrates versus where volume accumulates.
Product Type:
Formulation choice hinges on bioequivalence confidence and adherence economics rather than clinical efficacy alone.
- Tablet:Immediate-release tablets containing 1.25mg or 2.5mg indapamide dominate prescription volumes through established FDA bioequivalence data and payer familiarity. Demand concentrates in US retail pharmacy chains and German hospital tenders where procurement protocols favor documented interchangeability.
- Extended-Release Tablet:Modified-release formulations utilizing polymer matrix technology command premium positioning in adherence-focused protocols. Cardiology clinics in Japan and geriatric facilities in Germany are adopting these for polypharmacy patients where simplified dosing reduces hospitalization risk.
- Oral Suspension:Liquid formulations serve pediatric and dysphagia populations in specialized hospital settings.
- Capsule:Gelatin-shell alternatives occupy niche positioning where excipient sensitivity or regional manufacturing preferences dictate formulation choice.
Tablets lead on scale; extended-release tablets lead on momentum.
Therapy Area:
Clinical protocol penetration varies sharply by indication, with cardiovascular guidelines driving standardized prescribing while nephrology applications remain institution-dependent.
- Hypertension:First-line essential hypertension management accounts for the majority of indapamide prescribing, anchored by JNC-8 and ESC/ESH guideline recommendations. Volume concentrates in US ambulatory care networks and Japanese community health centers where protocol compliance is audited.
- Edema:Peripheral and pulmonary edema management in chronic conditions represents the expansion frontier. Nephrology centers in Germany and cardiology units in Japan are piloting protocol-driven diuretic rotation that elevates thiazide-like agents.
- Heart Failure:Adjunctive decongestion therapy in stable chronic heart failure patients with preserved ejection fraction.
- Renal Disease:Cautious application in early-stage chronic kidney disease under nephrologist supervision.
- Cirrhosis:Ascites management in compensated liver disease with sodium restriction protocols.
Hypertension anchors current revenue; edema applications are climbing the fastest.
End User:
Site-of-care economics and reimbursement mechanisms determine formulation preference and procurement leverage.
- Cardiology Clinics:Outpatient cardiovascular practices in the United States and Germany drive sustained tablet demand through guideline-aligned prescribing and pharmacy benefit manager formularies.
- Nephrology Centers:Dialysis and CKD-focused facilities represent concentrated volume for edema indications, with protocol adoption varying by regional nephrology society guidelines.
- Geriatric Facilities:Institutional long-term care in Japan and Germany favors extended-release formulations for adherence monitoring and reduced nursing administration burden.
- Ambulatory Care:General practice and community health settings handle routine hypertension management with cost-optimized generic procurement.
- Specialized Clinics:Hepatology and internal medicine subspecialty practices serve cirrhosis and complex edema populations.
Cardiology clinics lead on scale; geriatric facilities lead on momentum.
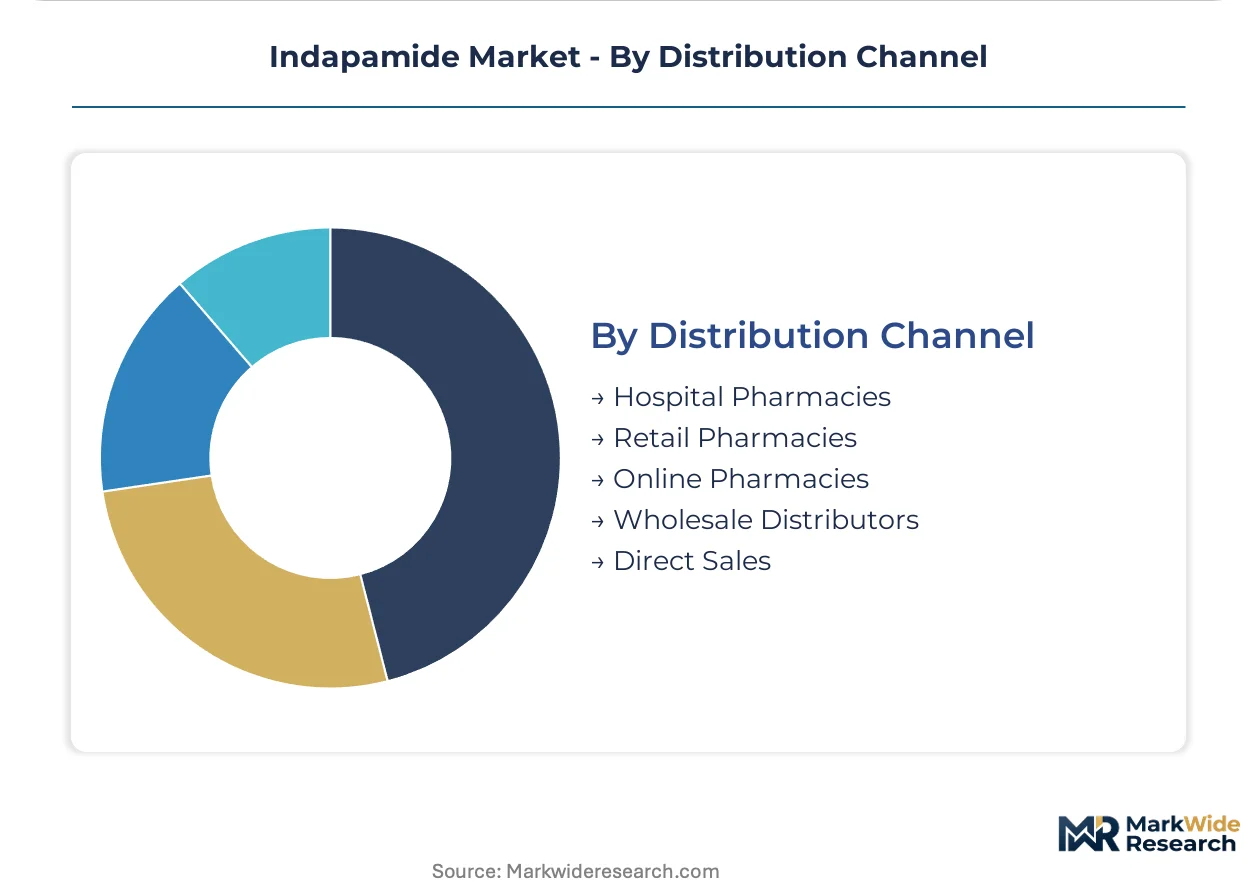
Distribution Channel:
Channel selection reflects inventory velocity requirements, margin preservation needs, and regulatory documentation standards.
- Hospital Pharmacies:Centralized procurement in European hospital systems and US integrated delivery networks aggregates volume for tender-based pricing. EMA inspection documentation and just-in-time inventory requirements favor established suppliers with multi-site manufacturing.
- Retail Pharmacies:US chain pharmacies and Japanese drugstores anchor generic substitution volumes, with pharmacy benefit manager formularies determining interchangeable product access.
- Online Pharmacies:Direct-to-patient dispensing is expanding in markets with telehealth integration and chronic disease management subscriptions.
- Wholesale Distributors:Inventory guarantees and logistics networks serve fragmented retail and institutional customers.
- Direct Sales:Manufacturer-to-institution arrangements bypass distributor margins in large health system contracts.
Hospital pharmacies lead on scale; online pharmacies lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German hospital procurement systems extract deeper price concessions than US pharmacy benefit managers, while Japanese geriatric networks prioritize adherence-optimized formulations over cost minimization.
United States
FDA bioequivalence requirements for thiazide-like diuretics extend generic development timelines, compressing margins for entrants lacking established dissolution testing infrastructure. Pharmacy benefit manager formulary consolidation concentrates volume among vertically integrated suppliers with captive API sourcing. The Midwest and Southeast corridor anchor retail pharmacy distribution networks serving Medicare-eligible hypertension populations.
Germany
EMA quality guidelines and centralized hospital tenders reward manufacturers with inspection-ready multi-site manufacturing. The country's statutory health insurance system drives protocol-driven prescribing in ambulatory cardiology practices. Baden-Württemberg and Bavaria host concentrated nephrology center networks piloting diuretic rotation protocols for edema management.
Japan
PMDA manufacturing standards and geriatric facility reimbursement policies favor extended-release formulations that reduce nursing administration burden. Community health centers in the Kanto and Kansai regions audit protocol compliance for essential hypertension management. Tokyo's integrated delivery networks are consolidating approved supplier lists to dual-source arrangements per therapeutic class.
India
CDSCO facility inspections shape API sourcing reliability for downstream formulators serving regulated markets. The country's PLI scheme for pharmaceuticals incentivizes finished-dose exports meeting FDA and EMA standards. Maharashtra and Gujarat host concentrated API manufacturing clusters pivoting toward direct tablet exports to capture value retained by Western formulators.
United Kingdom
NHS England centralized procurement and NICE hypertension guidelines drive generic substitution in primary care networks. The country's community pharmacy contract framework rewards suppliers with inventory guarantee capabilities. London and the Southeast corridor concentrate cardiology clinic demand where extended-release formulations command premium positioning.
Indapamide Market Key Industry Players
European originators anchor one tier; Indian and North American generic specialists hold volume positions through cost-optimized manufacturing and vertically integrated supply chains. The vendor base stratifies across inspection-ready integrated manufacturers, API-to-formulation exporters, and regional distribution-focused players. Two dominant competitive moves are reshaping positioning: backward integration into excipient sourcing to meet REACH documentation requirements, and direct-to-pharmacy distribution arrangements that bypass wholesale consolidation.
Within the originator heritage tier, Servier exemplifies European hospital tender leverage built on decades of clinical data packages. Among vertically integrated generic manufacturers, Teva Pharmaceutical Industries Ltd. and Glenmark Pharmaceuticals Ltd. represent contrasting geographic anchors—Israeli and Indian respectively—each occupying positions defined by regulatory compliance infrastructure rather than molecular differentiation. These companies illustrate how bioequivalence data packages and multi-site manufacturing capabilities now determine competitive standing more than patent exclusivity.
| Leading Market Players |
|---|
| Servier |
| Sanofi S.A. |
| Teva Pharmaceutical Industries Ltd. |
| Mylan N.V. |
| ANI Pharmaceuticals |
| Glenmark Pharmaceuticals Ltd. |
| Apotex Inc. |
| Sun Pharmaceutical Industries Ltd. |
| Aurobindo Pharma Limited |
| Others |
Cost & Logistics Intelligence
Modified-release polymer matrix technology is reshaping cost economics across indapamide formulation tiers while simultaneously concentrating supply among integrated manufacturers with captive excipient sourcing and in-house dissolution testing capabilities.
Pricing Analysis
Capacity additions in Maharashtra and Gujarat are reshaping price floors for immediate-release tablets as Indian API manufacturers pivot toward finished-dose exports meeting FDA and EMA standards. Three-tier pricing structure across premium extended-release, standard immediate-release, and economy generic tablet levels reflects bioequivalence data package depth and inspection readiness. Cost compression in standard tablets is intensifying because European hospital tenders extract volume-based concessions through centralized procurement. Retail pharmacy chains in the United States exhibit highest price sensitivity, while Japanese geriatric facilities prioritize adherence-optimized extended-release formulations over cost minimization.
Supply Chain Analysis
Sulfonamide-derived indoline ring intermediates rest on Indian specialty chemical producers and Chinese chlorobenzene feedstock suppliers. Active pharmaceutical ingredient production draws from India, China, and selected European facilities with EMA inspection history. Downstream formulation depends on polymer matrix excipients subject to REACH registration documentation requirements. Single-source vulnerability concentrates at CDSCO-inspected API manufacturing sites serving multiple generic formulators. Distribution runs through wholesale distributors in fragmented retail channels and direct-to-institution arrangements for consolidated hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Extended-release formulation premiums and backward integration into excipient sourcing present margin-expansion pathways as procurement consolidation intensifies price competition in commodity tablet tiers.
For Market Incumbents: Cement inspection-ready multi-site manufacturing footprints to defend European hospital tender positions against emerging Indian finished-dose exporters. Lock captive excipient supply chains to satisfy REACH documentation requirements and capture preferred supplier status in EMA-regulated procurement. Generic substitution pressures in US pharmacy benefit manager formularies threaten originator heritage positioning without bioequivalence data package differentiation. For New Entrants and Emerging Players: Modified-release polymer matrix systems offer technology-first wedge into Japanese geriatric facility networks and German cardiology clinics where adherence-focused protocols command premium positioning. Target edema management applications in nephrology centers as underpenetrated therapy areas with institution-dependent protocol adoption. Pursue direct-to-pharmacy distribution arrangements bypassing wholesale consolidation to preserve margin and improve inventory visibility. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier API-to-formulation exporters with CDSCO inspection history but lacking EMA multi-site certification. Long-term viability hinges on regulatory compliance infrastructure rather than molecular differentiation, favoring acquisition targets with captive dissolution testing laboratories and backward integration into sulfonamide-derived intermediate sourcing. Watch FDA bioequivalence requirement amendments for thiazide-like diuretics as inflection indicator for generic entry cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Excipient Sourcing | Captive polymer matrix supply satisfies REACH documentation requirements for European formulation sites. |
| Extended-Release Technology Licensing | Modified-release formulations command premium positioning in Japanese geriatric facility reimbursement protocols. |
| Direct-to-Pharmacy Distribution | Bypassing wholesale consolidation preserves margin in US retail pharmacy chain procurement. |
| Multi-Site Manufacturing Certification | EMA inspection-ready facilities capture volume in German hospital tender aggregation systems. |
| Edema Management Protocol Development | Nephrology center adoption in Germany and Japan expands indication beyond hypertension anchoring. |
Research Approach
Direct dialogue with generic pharmaceutical manufacturing executives, regulatory affairs specialists at CDSCO-inspected facilities, European hospital procurement managers, and US pharmacy benefit manager formulary directors grounded qualitative assessment. Secondary validation drew from FDA bioequivalence submission databases, EMA inspection outcome records, ClinicalTrials.gov protocol registries, and Indian pharmaceutical export customs data. Bottom-up prescription volume modeling and top-down therapeutic class allocation triangulated market sizing across formulation and indication segments.
Segment-level value outputs combined patient population epidemiology, protocol penetration rates, and pricing tier stratification across the projection horizon. Modeled dimensions spanned dosage form technology, therapy area application, end-user site-of-care economics, and regional regulatory cluster alignment. CAGRs derived from longitudinal tender price trajectory analysis and volume aggregation in consolidated procurement systems. Forecast inputs incorporated bioequivalence approval timelines and inspection schedule synchronization patterns at key manufacturing sites.
The model holds under sustained FDA and EMA regulatory stability; deviation in bioequivalence requirement stringency or CDSCO enforcement posture would shift generic entry cost curves and competitive positioning. Forecasts reflect documented assumptions regarding protocol adoption rates in nephrology centers and geriatric facility reimbursement policy continuity. A small set of named triggers—regulatory inspection outcome volatility, excipient supply documentation enforcement, and hospital formulary consolidation pace—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Antipyretic Drugs for Children Market
Pharmaceuticals
Herpes Labialis Treatment Market
Pharmaceuticals
Antidotes Market
Pharmaceuticals
Latin America Biguanide Market
Pharmaceuticals
Sodium Aescinate Market
Pharmaceuticals
Global Online Pharmacy Market
Pharmaceuticals
Mexico Dimenhydrinate Market
Pharmaceuticals
Global Pharmaceutical Warehousing Market
Pharmaceuticals
Psychedelic Drugs Market
Pharmaceuticals
Cancer Immunotherapy Drug Discovery Outsourcing Market
Pharmaceuticals
Global Gastroparesis Drug Market
Pharmaceuticals
Brazil Diabetes Drugs Market
Pharmaceuticals
Collagenase Clostridium Histolyticum Market
Pharmaceuticals
Global Intravenous Immunoglobulin Market
Pharmaceuticals
Global Anti-Infective Agents Market
Pharmaceuticals
Global Acne Medication Market