
 Gastrointestinal OTC Drugs Market | 2026-2036
Gastrointestinal OTC Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Gastrointestinal OTC Drugs Market Analysis
FDA OTC monograph reform is hardening compliance requirements for new antacid and anti-diarrheal entrants. Johnson & Johnson Services, Inc. leverages its consumer health infrastructure to sustain pharmacy shelf dominance in North American digestive care. Bayer AG anchors European market presence through established famotidine formulations and retail pharmacy partnerships. Sun Pharmaceutical Industries Limited competes on cost-efficient manufacturing of loperamide-based products across emerging markets.
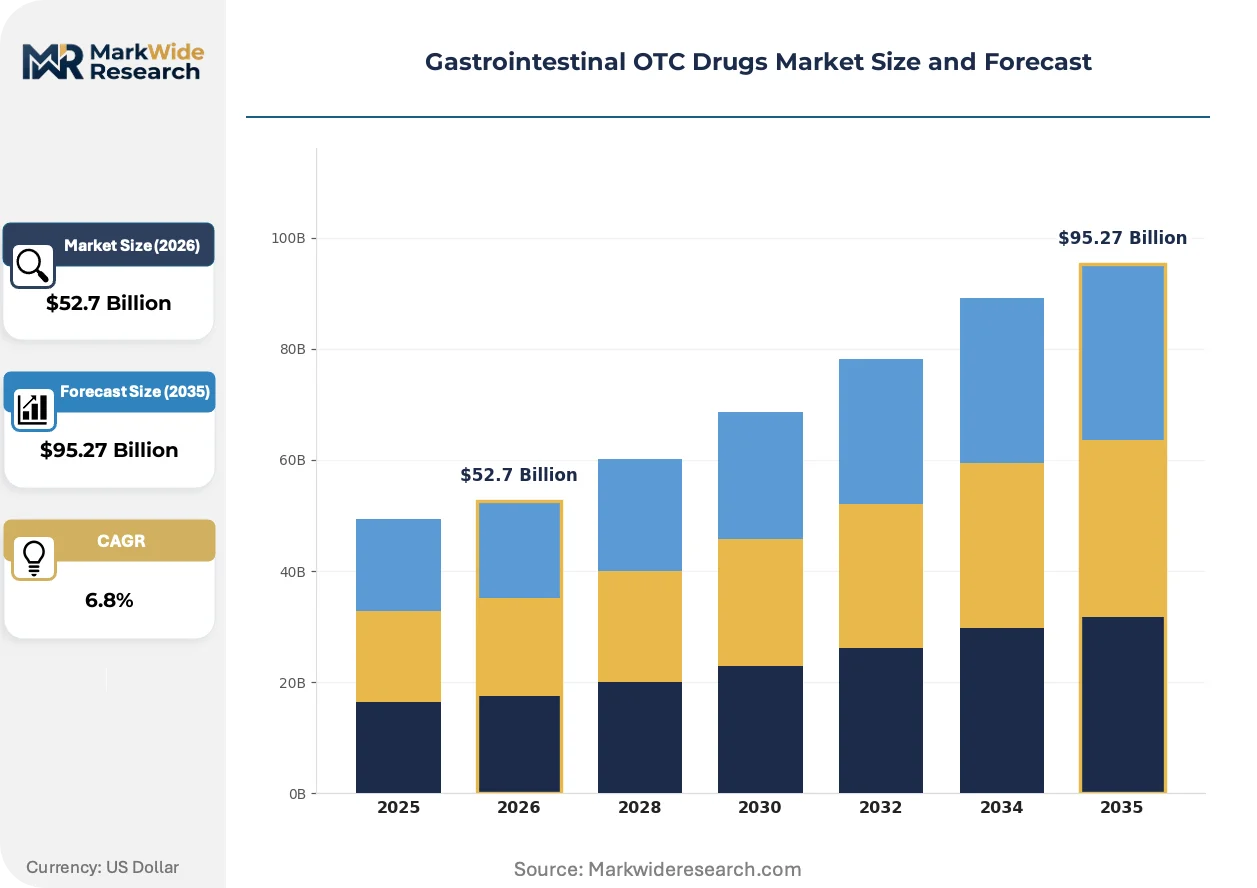
Gastrointestinal OTC drugs comprise non-prescription formulations targeting acid neutralization, motility modulation, and bowel regulation, typically manufactured through direct compression or liquid suspension processes to ensure rapid dissolution and gastric residence. These products serve consumers seeking immediate symptomatic relief without physician consultation, reducing healthcare system burden for mild-to-moderate digestive complaints. Proton pump inhibitors and antacids command the largest revenue pools due to high recurrence rates of gastroesophageal reflux conditions, while online retail distribution is expanding fastest as pharmacy e-commerce platforms capture repeat purchase behavior. Chewable tablets and liquid formulations attract pediatric and geriatric segments where swallowing difficulties limit standard tablet uptake.
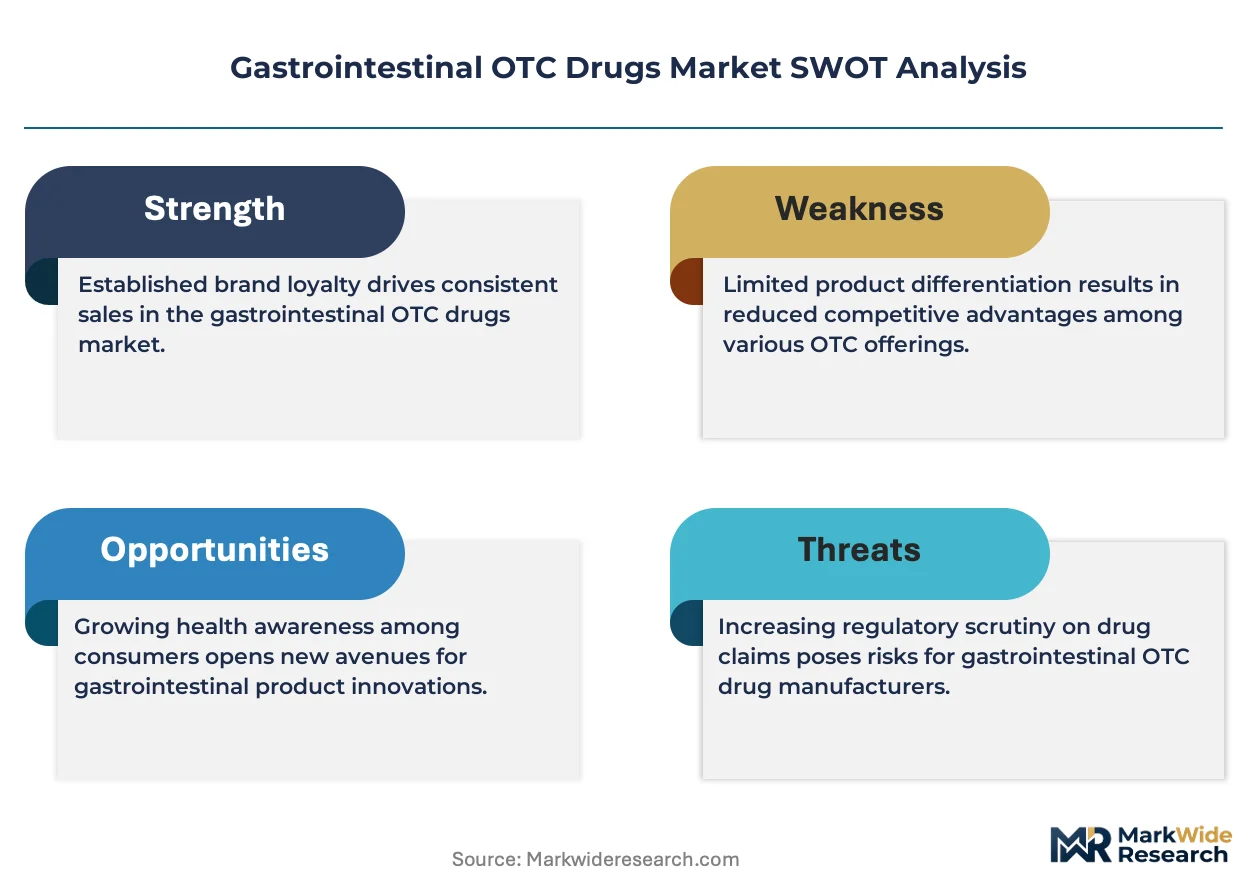
FDA OTC monograph updates, EMA self-medication guidelines, and Japan's MHLW reclassification protocols collectively determine which active ingredients transition from prescription-only to pharmacy-accessible status, directly expanding addressable markets for manufacturers. The WHO's essential medicines list inclusion criteria for basic antacids and oral rehydration salts further shape procurement priorities in low-resource settings. Stakeholders must monitor regulatory reclassification pipelines and channel migration toward digital pharmacy platforms to anticipate where volume and margin will concentrate next.
Market Dynamics
FDA OTC monograph reform is compressing time-to-market for new antacid entrants while simultaneously elevating documentation burdens. Pharmacy chains now demand real-time inventory visibility from digestive health suppliers, reshaping upstream logistics contracts.
Growth Catalysts
- EMA Self-Medication Guidelines:The European framework accelerates prescription-to-OTC switches for proton pump inhibitors, expanding pharmacy-accessible addressable markets across Germany, France, and Italy.
- Digital Pharmacy Platforms:E-commerce penetration in OTC digestive care is automating repeat purchase cycles, with subscription models capturing chronic GERD sufferers through automated replenishment algorithms.
- Aging Demographics:Japan's super-aged population sustains per-capita consumption of bowel regulators and acid suppressants at rates unmatched by younger cohorts in comparable economies.
Market Restraints
- Active Ingredient Supply Concentration:Chinese API manufacturers control over 70 percent of global omeprazole and loperamide precursor supply, exposing formulators to geopolitical logistics disruption.
- FDA Bioequivalence Documentation:The 2022 OTC monograph reform imposes clinical study requirements that smaller entrants cannot fund, consolidating shelf access for established pharmaceutical infrastructure holders.
- Herbal Digestive Remedies:Ginger-based and probiotic alternatives are capturing price-sensitive consumers seeking "clean label" positioning, eroding share for synthetic antacid formulations.
Strategic Opportunities
- Pediatric Formulation White Space:Brazil's ANVISA pathway for OTC pediatric antacids remains underdeveloped relative to adult approvals, offering first-mover positioning in a high-fertility market.
- Digital Therapeutics Convergence:Mobile symptom-tracking applications paired with OTC product recommendations are creating adherence-linked revenue streams beyond standalone pill sales.
- India PLI Scheme for APIs:The country's production-linked incentive program subsidizes domestic active pharmaceutical ingredient manufacturing, enabling cost-competitive export positioning for loperamide and ranitidine alternatives.
Industry Challenges
- Formulation Scientist Scarcity:Rapid dissolution engineering expertise for chewable antacids concentrates at a handful of contract development organizations, extending project timelines for mid-tier entrants.
- Legacy ERP Integration:Pharmacy chain EDI requirements for automated replenishment clash with decades-old manufacturing execution systems at regional generic producers, forcing costly middleware deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gastrointestinal OTC Drugs Market |
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antacids, Anti-diarrheal, Laxatives, Proton Pump Inhibitors Active Ingredient: Ranitidine, Loperamide, Psyllium, Famotidine Formulation: Tablets, Liquid, Chewable Tablets, Powder Distribution Channel: Pharmacies, Supermarkets, Online Retail, Convenience Stores |
| Companies Covered | Viatris Inc., Sandoz AG, Johnson & Johnson Services, Inc., Sun Pharmaceutical Industries Limited, Teva Pharmaceuticals Industries Ltd., Bayer AG, Pfizer Inc., Procter & Gamble, Perrigo Company plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gastrointestinal OTC Drugs Market Emerging Trajectories
Direct-to-consumer diagnostic tools are fragmenting the traditional physician-pharmacy-OTC pathway, with at-home H. pylori tests and pH monitoring devices steering symptom management decisions before retail purchase.
Continuous manufacturing technology is automating tablet compression and coating processes for antacid production, compressing batch cycle times from days to hours. Contract manufacturers in Germany and Switzerland are adopting these lines to serve pan-European pharmacy private-label programs. The capital intensity of this shift is squeezing out regional players dependent on batch equipment.
The FDA's 2023 OTC monograph reform final rule imposes standardized labeling and bioequivalence documentation for acid reducers, eliminating the prior administrative pathway that allowed market entry without pre-approval. Large pharmaceutical consumer divisions with dedicated regulatory affairs teams are absorbing these costs through economies of scale, while smaller marketers retreat to legacy categories with grandfathered status.
Subscription-based replenishment models are displacing episodic pharmacy purchases for chronic GERD sufferers, with digital health platforms capturing patient data to personalize product recommendations. This shift concentrates volume with vertically integrated pharmacy e-commerce operations in the United States and United Kingdom, marginalizing independent drugstores that lack logistics infrastructure for scheduled delivery.
Gastrointestinal OTC Drugs Market Segmentation
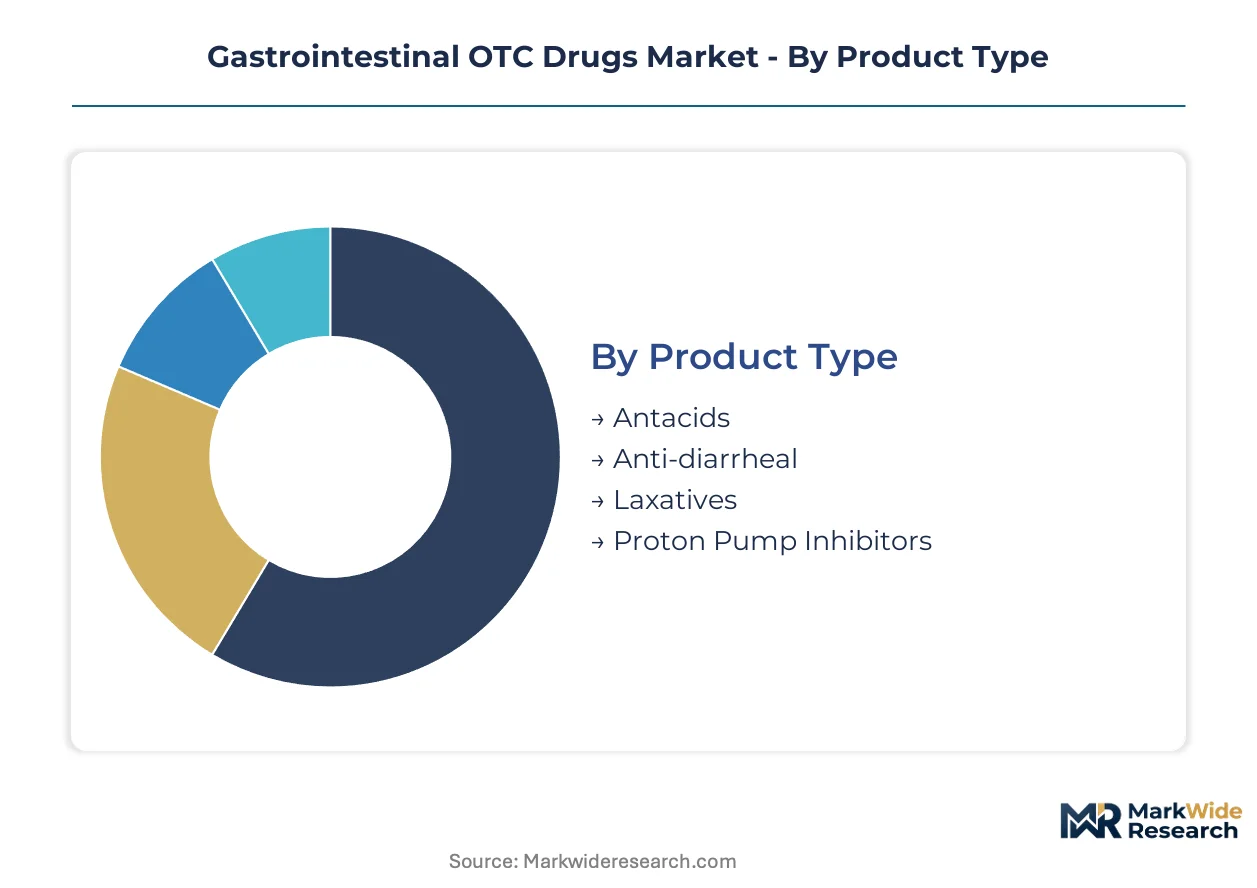
Gastrointestinal OTC drug manufacturers configure product portfolios around symptom severity, patient swallowing capability, and purchase channel preferences. Segmentation reveals where formulation investments concentrate versus where distribution economics favor private-label entry.
Product Type:
Symptom recurrence patterns and self-diagnosis confidence differentiate buyer behavior across therapeutic categories.
- Antacids:Fast-acting calcium carbonate and magnesium hydroxide formulations neutralize gastric acid within minutes. Demand concentrates among occasional heartburn sufferers in Germany and Japan where pharmacy counseling encourages trial. High impulse-purchase rates at supermarket checkout drives margin compression.
- Proton Pump Inhibitors:Delayed-release omeprazole and esomeprazole formulations suppress acid production for 24-hour intervals. Chronic GERD patients in the United States generate repeat prescription-to-OTC conversion volume. FDA monograph compliance costs favor established pharmaceutical infrastructure holders.
- Anti-diarrheal:Loperamide-based motility inhibitors address acute intestinal distress.
- Laxatives:Stimulant and osmotic variants target bowel irregularity in aging populations.
Proton pump inhibitors lead volumes today; antacids are gaining share fastest through supermarket channel expansion.
Active Ingredient:
Regulatory reclassification status and API supply geography determine which molecules command shelf space investment.
- Loperamide:Synthetic opioid receptor agonist reducing intestinal motility without CNS penetration. Indian PLI-subsidized API production enables cost-competitive export positioning into African and Southeast Asian markets. Supply concentration among Chinese manufacturers creates geopolitical exposure for Western formulators.
- Famotidine:H2 receptor antagonist delivering 12-hour acid suppression with favorable safety profile. European pharmacy chains favor famotidine for prescription-to-OTC switch protocols under EMA self-medication guidelines. Bayer AG anchors market presence through established retail partnerships.
- Ranitidine:Withdrawn from multiple markets due to NDMA contamination concerns; residual demand shifts to famotidine alternatives.
- Psyllium:Bulk-forming fiber supplement for gentle bowel regulation.
Famotidine leads volumes today; loperamide is climbing the fastest on emerging market penetration.
Formulation:
Patient age demographics and swallowing physiology dictate manufacturing process selection and packaging format.
- Liquid:Aqueous suspensions with rapid gastric dispersion for pediatric and geriatric segments. Japan's super-aged population sustains per-capita consumption unmatched by tablet-preferred younger cohorts. Higher shipping costs limit e-commerce penetration relative to solid dose forms.
- Chewable Tablets:Flavored compressed matrices breaking down through mastication before swallowing. Brazil's ANVISA pediatric pathway gaps create first-mover white space for antacid variants. Continuous manufacturing adoption in German contract facilities compresses production cycle times.
- Tablets:Standard compressed dose forms dominating adult self-medication.
- Powder:Sachet-dried formulations for precise dosing flexibility.
Tablets lead volumes today; chewable tablets are expanding most quickly on pediatric formulation investment.
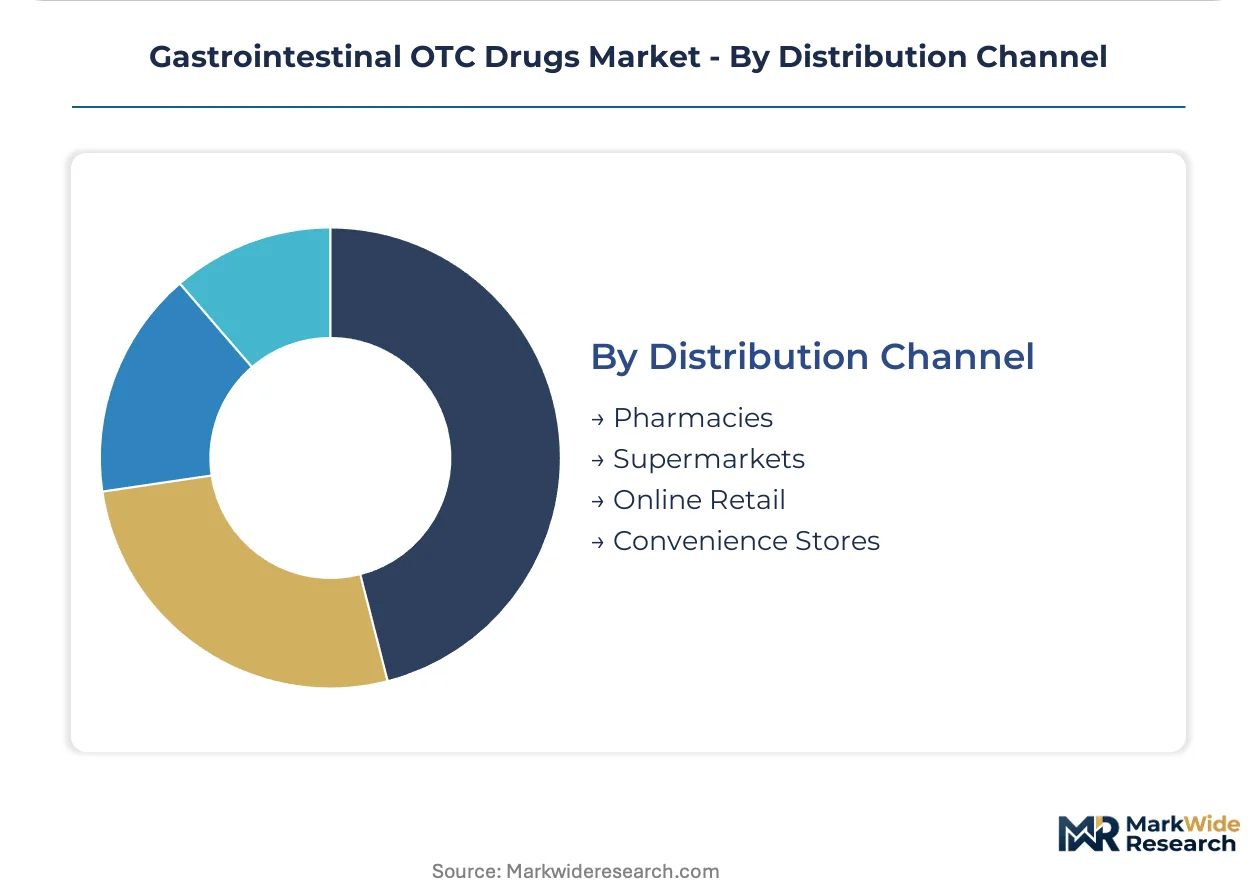
Distribution Channel:
Inventory visibility requirements and replenishment automation sophistication separate channel winners from margin-erosion casualties.
- Online Retail:Pharmacy e-commerce platforms capturing chronic GERD sufferers through subscription replenishment algorithms. United States and United Kingdom vertical integration concentrates volume with logistics-capable players. Independent drugstores lacking scheduled delivery infrastructure face marginalization.
- Pharmacies:Brick-and-mortar counseling environments sustaining premium positioning for proton pump inhibitor switches. German and French regulatory frameworks reinforce pharmacist-mediated self-medication. Real-time EDI inventory visibility demands clash with legacy ERP systems at regional generic producers.
- Supermarkets:Impulse-driven antacid and laxative placement at checkout zones.
- Convenience Stores:Emergency access positioning for travel-related digestive distress.
Pharmacies lead volumes today; online retail is gaining share fastest through adherence-linked subscription models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory pharmacists and pharmacy automation engineers concentrate in Germany, Japan, and the United States, anchoring the triad of markets where prescription-to-OTC reclassification expertise drives category expansion.
United States
Chronic GERD sufferers generate repeat purchase volume through subscription pharmacy platforms. FDA monograph reform imposes bioequivalence documentation costs that favor established pharmaceutical infrastructure holders. The New Jersey-Pennsylvania corridor hosts consumer health divisions with dedicated regulatory affairs teams absorbing compliance burdens.
Germany
Pharmacist-mediated self-medication reinforces premium positioning for proton pump inhibitor switches. EMA self-medication guidelines accelerate prescription-to-OTC transitions across famotidine formulations. The Rhine-Main cluster anchors Bayer AG's retail pharmacy partnership networks.
Japan
Super-aged demographics sustain per-capita consumption of liquid bowel regulators unmatched by tablet-preferred younger cohorts. MHLW reclassification protocols determine active ingredient pharmacy-accessible status. The Kanto region concentrates formulation scientists specializing in rapid dissolution engineering for geriatric dosage forms.
India
Cost-efficient loperamide manufacturing serves emerging market export demand. The PLI scheme subsidizes domestic active pharmaceutical ingredient production for ranitidine alternatives. Gujarat and Maharashtra host contract development organizations capturing mid-tier generic formulation volume.
Brazil
High fertility rates create pediatric formulation white space for chewable antacid entrants. ANVISA regulatory pathways for OTC pediatric approvals remain underdeveloped relative to adult categories. São Paulo anchors pharmacy chain expansion demanding real-time inventory visibility from suppliers.
Gastrointestinal OTC Drugs Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across shelf space and digital pharmacy platforms. The vendor base fragments between multinational consumer health divisions with regulatory economies of scale and regional generic producers dependent on legacy manufacturing systems. Three archetypes dominate: integrated pharmaceutical conglomerates with dedicated OTC infrastructure, API-forward Indian manufacturers competing on cost, and European specialty firms leveraging continuous manufacturing technology. M&A activity concentrates on acquiring regulatory affairs capabilities, while strategic partnerships with pharmacy e-commerce platforms secure subscription replenishment algorithms.
Among diversified pharmaceutical conglomerates, Johnson & Johnson Services, Inc. and Bayer AG exemplify the infrastructure-heavy archetype that absorbs FDA monograph compliance costs through scale. Sun Pharmaceutical Industries Limited occupies a position within the API-integrated tier, leveraging Indian production-linked incentives for cost-competitive positioning. These three anchors illustrate how regulatory capacity, geographic manufacturing advantage, and channel integration separate shelf access winners from margin-compressed challengers.
| Leading Market Players |
|---|
| Viatris Inc. |
| Sandoz AG |
| Johnson & Johnson Services, Inc. |
| Sun Pharmaceutical Industries Limited |
| Teva Pharmaceuticals Industries Ltd. |
| Bayer AG |
| Pfizer Inc. |
| Procter & Gamble |
| Perrigo Company plc |
| Others |
Supply Flow & Price Mechanics
Active pharmaceutical ingredient procurement from Chinese and Indian manufacturers flows through three distinct pricing tiers before reaching pharmacy shelves, with omeprazole and loperamide precursor costs compressing margins for formulators lacking backward integration into API production.
Pricing Analysis
Bundled subscription services for chronic GERD sufferers contrast sharply with unbundled transactional purchases at supermarket checkouts. Three-tier pricing structure across premium pharmacist-counseled proton pump inhibitors, standard retail antacids, and economy private-label laxatives reflects brand recognition and counseling service inclusion. Cost compression in the economy tier is intensifying because supermarket chains leverage volume guarantees to extract supplier concessions. Price-sensitive consumers in emerging markets gravitate toward unbranded loperamide, while insured populations in the United States show lowest sensitivity to premium-tier positioning.
Supply Chain Analysis
Formulation scientist scarcity in Germany and Switzerland constrains continuous manufacturing adoption rates for chewable antacid production. API supply concentrates in China and India, with Gujarat and Maharashtra contract facilities feeding global loperamide demand. Raw material dependencies span omeprazole precursors, magnesium hydroxide compounds, and specialized coating polymers. Single-source vulnerability from Chinese API manufacturers exposes Western formulators to geopolitical logistics disruption. Distribution runs through vertically integrated pharmacy e-commerce platforms in the United States and United Kingdom, marginalizing independent drugstores lacking automated replenishment infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gastrointestinal OTC drugs market functions as a regulatory compounder, where FDA's 2022 OTC monograph reform and EMA self-medication guidelines continuously expand pharmacy-accessible addressable markets for compliant manufacturers.
For Market Incumbents: Cement shelf access dominance by acquiring regulatory affairs capabilities in anticipation of bioequivalence documentation burdens that smaller competitors cannot fund. Absorb FDA monograph compliance costs through economies of scale while deploying continuous manufacturing technology to compress batch cycle times. Channel control through exclusive pharmacy e-commerce platform partnerships secures subscription replenishment algorithms that lock in chronic GERD patient volume. For New Entrants and Emerging Players: ANVISA's underdeveloped pediatric OTC antacid pathway in Brazil opens a window for chewable formulation first-movers in high-fertility markets. Target India's PLI-subsidized API manufacturing for cost-competitive loperamide export positioning into African and Southeast Asian markets. Digital therapeutics convergence offers a go-to-market angle through mobile symptom-tracking applications paired with product recommendations. For Investors and Strategic Acquirers: Consolidation pressure builds where FDA bioequivalence documentation requirements exceed mid-tier generic producer balance sheet capacity. Long-term viability favors vertically integrated players with captive API supply and dedicated regulatory infrastructure. Watch MHLW reclassification protocols in Japan as the signal indicating where proton pump inhibitor volume will concentrate next.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Affairs Capability Acquisition | FDA monograph compliance costs favor established infrastructure holders with dedicated teams. |
| Continuous Manufacturing Technology Deployment | German and Swiss contract facilities compress antacid production cycle times from days to hours. |
| Pediatric Formulation Development | Brazil's ANVISA pathway gaps create first-mover positioning in high-fertility chewable antacid markets. |
| Pharmacy E-Commerce Platform Integration | Subscription replenishment algorithms capture chronic GERD patient volume through automated adherence. |
| API Backward Integration | India's PLI scheme subsidizes domestic omeprazole and loperamide precursor manufacturing for export competitiveness. |
Methodological Framework
Bottom-up pharmacy channel modeling reconciled against top-down API production tracking forms the analytical core of this study. Primary interviews with regulatory affairs directors, pharmacy chain procurement managers, contract manufacturing executives, and gastrointestinal formulation scientists combined with secondary validation from FDA OTC monograph filings, EMA self-medication guideline updates, and MHLW reclassification protocols. Trade data from Indian DGFT export records and Chinese customs statistics anchored supply-side triangulation against demand signals from pharmacy e-commerce platform disclosures.
Historical trendline analysis of prescription-to-OTC conversion rates informed the projection framework across the analysis window. Segmentation dimensions modeled include therapeutic category, active ingredient regulatory status, formulation type, and distribution channel automation sophistication. CAGRs derived from volume trajectory analysis incorporating demographic aging patterns, channel migration toward digital pharmacy platforms, and regulatory reclassification pipeline visibility. Industry-specific forecast inputs captured EMA guideline acceleration effects and Japan's super-aged per-capita consumption coefficients.
Forecast precision tightens around the base case; tail outcomes carry wider variance under active ingredient supply disruption or accelerated herbal remedy substitution. Projections reflect assumptions regarding regulatory reclassification timelines, API supply geography stability, and pharmacy chain inventory visibility technology adoption. Material deviation in FDA monograph enforcement intensity or Chinese export restriction triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Europe Insulin Drugs and Glucagon-Like Peptide 1 (GLP-1) Receptor Agonist Market
Pharmaceuticals
Seropositive Rheumatoid Arthritis Drug Market
Pharmaceuticals
Hydroxycarbamide Market
Pharmaceuticals
Metastatic Cancer Treatment Drug Market
Pharmaceuticals
Performance Enhancing Drugs Market
Pharmaceuticals
Calcineurin Inhibitor Drugs Market
Pharmaceuticals
Plasma-Derived Drugs Market
Pharmaceuticals
United Kingdom (UK) Diabetes Drugs Market
Pharmaceuticals
Antiplatelet Drugs Market
Pharmaceuticals
GLP-1 Receptor Agonist Market
Pharmaceuticals
Vitiligo Drugs Market
Pharmaceuticals
Global Fibrinogen Concentrates Market
Pharmaceuticals
Tetanus Market
Pharmaceuticals
Global Aromatase Inhibitors Drug Market
Pharmaceuticals
North America Biguanide Market
Pharmaceuticals
Benzodiazepine Drugs Market