
 Global Narcolepsy Therapeutics Market | 2026-2036
Global Narcolepsy Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Narcolepsy Therapeutics Market Foresight
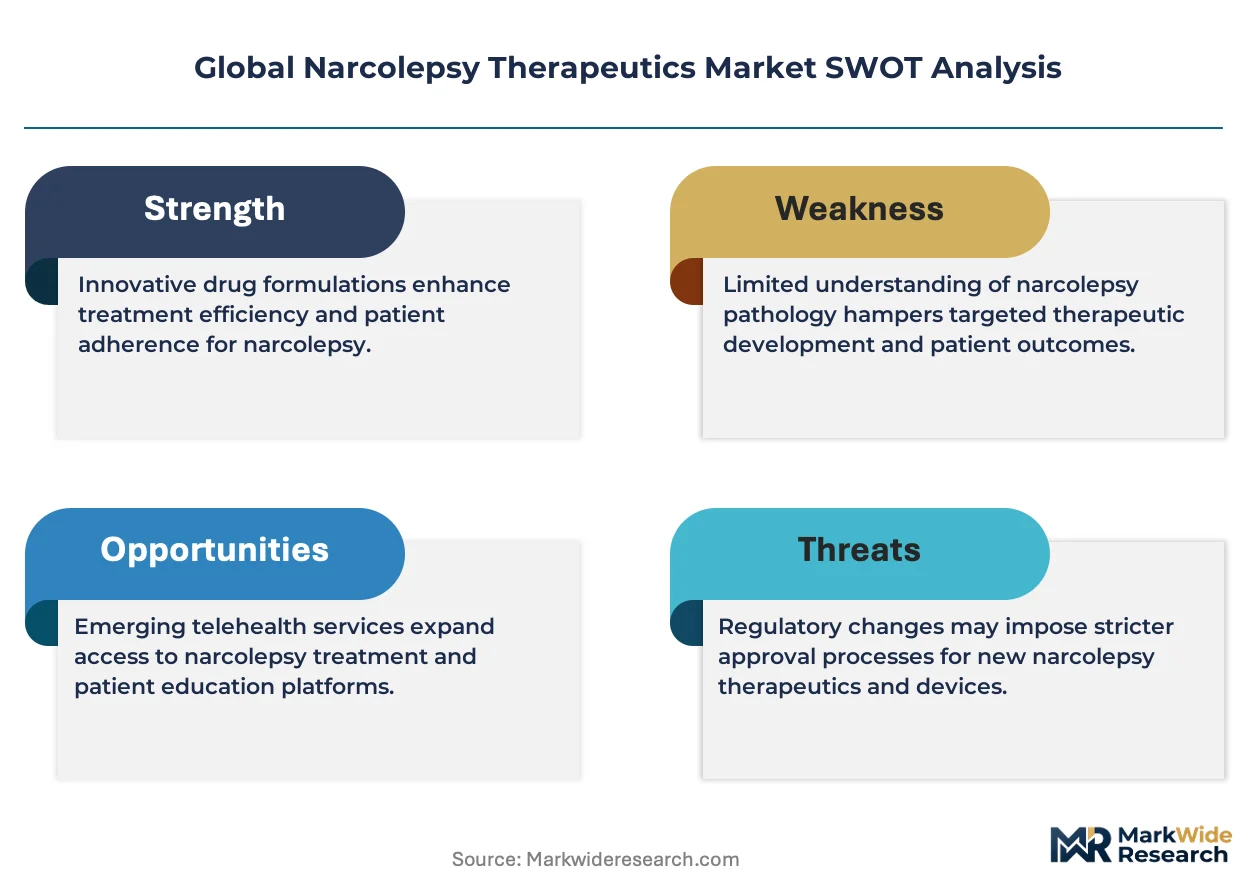
The EU Green Deal is broadening the sustainability footprint of pharmaceutical manufacturing across the narcolepsy therapeutics supply chain. Jazz Pharmaceuticals plc leverages its sodium oxybate franchise to anchor North American distribution. Takeda Pharmaceutical Company Limited dominates Japanese regulatory pathways through deep PMDA engagement. Harmony Biosciences Holdings, Inc. specializes in hospital-centric prescribing networks for daytime sleepiness indications.
Narcolepsy therapeutics comprise pharmacological agents targeting orexinergic neurotransmission, histaminergic signaling, and monoaminergic pathways to restore wakefulness architecture and suppress REM-atonia intrusion. Sodium oxybate formulations require controlled substance scheduling and specialized pharmacy dispensing infrastructure due to abuse liability profiles. The stimulants segment sustains the largest revenue pool through mature methylphenidate and modafinil prescribing, while orexin receptor agonists represent the fastest-expanding category as novel mechanisms advance through regulatory review. Oral delivery mode occupies the dominant position in volume terms, though intranasal formulations are gaining share in sleep clinic settings where rapid onset carries clinical priority.
FDA orphan drug incentives and EMA's accelerated assessment pathways shape development economics for narcolepsy drug candidates across the United States and European Union. Japan's PMDA Sakigake designation creates parallel fast-track opportunity for orexin-targeted therapies in Tokyo-Osaka clinical corridors. Stakeholders must monitor reimbursement negotiations for novel mechanisms against generic stimulant benchmarks in Germany, France, and the United Kingdom.
Market Dynamics
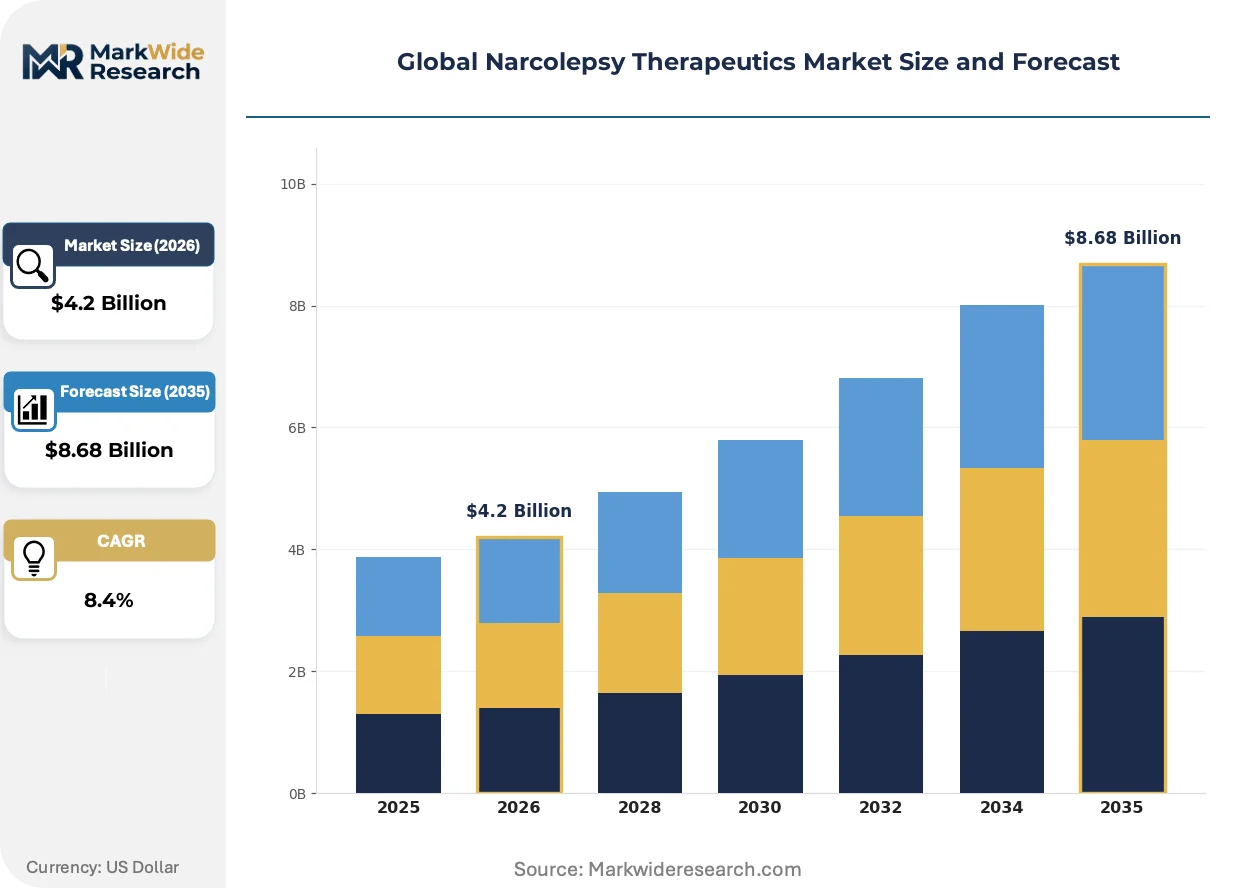
Orexin receptor agonists are compressing development timelines across the narcolepsy pipeline as FDA orphan drug incentives and EMA accelerated assessment pathways restructure clinical trial economics. This mechanism shift is redistributing R&D investment toward novel wakefulness-restoring pathways and away from incremental stimulant reformulations.
Growth Catalysts
- FDA Orphan Drug Incentives:Tax credits and seven-year market exclusivity provisions accelerate orexin-targeted therapy development timelines for rare disease indications.
- Diagnostic Infrastructure Expansion:Sleep disorder clinics in Germany and Japan are deploying polysomnography networks that identify narcolepsy cases earlier in disease progression.
- Orexin Receptor Agonists:Novel mechanisms advancing through Phase III trials are creating first-in-class therapeutic categories distinct from generic stimulant benchmarks.
Market Restraints
- Controlled Substance Scheduling:Sodium oxybate formulations carry DEA Schedule III classification that mandates specialized pharmacy dispensing infrastructure and limits prescriber pools.
- Generic Stimulant Saturation:Methylphenidate and modafinil commoditization in the United States and Western Europe compresses pricing power for new entrants against established benchmarks.
- Reimbursement Negotiation Friction:Germany's G-BA and France's HAS apply cost-effectiveness thresholds that novel mechanisms struggle to satisfy against generic comparators.
Strategic Opportunities
- PMDA Sakigake Designation:Japan's fast-track pathway for breakthrough therapies creates parallel regulatory opportunity for orexin-targeted candidates in Tokyo-Osaka clinical corridors.
- Intranasal Formulation Development:Sleep clinics are prioritizing rapid-onset delivery modes that bypass gastrointestinal absorption variability in acute sleep attack management.
- EU Green Deal Alignment:Sustainable manufacturing protocols for active pharmaceutical ingredients open preferential procurement channels within European hospital systems.
Industry Challenges
- Sleep Medicine Specialist Shortage:Board-certified somnologists remain concentrated in urban academic medical centers, creating diagnostic bottlenecks in secondary and tertiary markets.
- Controlled Substance Compliance Infrastructure:REMS program administration for sodium oxybate products demands specialized pharmacy networks that fragment distribution reach.
- Biomarker Validation Delays:CSF orexin measurement standardization across clinical laboratories remains inconsistent, complicating diagnostic confirmation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Narcolepsy Therapeutics Market |
| Market Size in 2026 | $4.2 Billion |
| Market Size in 2035 | $8.68 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stimulants, Sodium Oxybate, Orexin Receptor Agonists, Antidepressants Therapy Area: Excessive Daytime Sleepiness, Cataplexy, Hypnagogic Hallucinations, Sleep Paralysis End User: Hospitals, Sleep Disorder Clinics, Neurology Centers, Specialty Pharmacies Delivery Mode: Oral, Intranasal, Injectable, Transdermal |
| Companies Covered | Jazz Pharmaceuticals plc, Takeda Pharmaceutical Company Limited, Teva Pharmaceutical Industries Ltd., Harmony Biosciences Holdings, Inc., Novartis AG, Avadel Pharmaceuticals plc, Axsome Therapeutics, Inc., UCB S.A., Bioprojet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Narcolepsy Therapeutics Market Shifts & Advancements
Mechanism-driven therapeutic development is displacing symptom-management approaches across the narcolepsy pipeline. Three convergent developments are restructuring how wakefulness disorders are treated, diagnosed, and reimbursed.
Dual orexin receptor agonists are unifying fragmented therapeutic protocols that previously required stimulant-sodium oxybate combinations. Sleep disorder clinics in the United States and Germany are adopting these agents for patients with cataplexy plus excessive daytime sleepiness, collapsing polypharmacy regimens into single-molecule management. This convergence is compressing the addressable market for standalone stimulant prescriptions while expanding the premium therapeutic tier.
EMA's Medical Device Regulation and FDA's digital health guidance are creating parallel pathways for wearable diagnostic adjuncts. Polysomnography-equivalent home monitoring systems are securing CE marking and 510(k) clearances that enable decentralized narcolepsy screening. Device manufacturers are targeting employer wellness programs and primary care networks where specialist access remains limited.
Hospital pharmacy formularies are consolidating procurement around mechanism-based therapeutic categories rather than individual brands. Pharmacy and therapeutics committees in Japan and Germany are establishing orexin agonist, histamine H3 inverse agonist, and sodium oxybate therapeutic classes with unified prior authorization protocols. This classification is shifting prescribing influence from individual physicians to institutional protocol committees.
Global Narcolepsy Therapeutics Market Segmentation
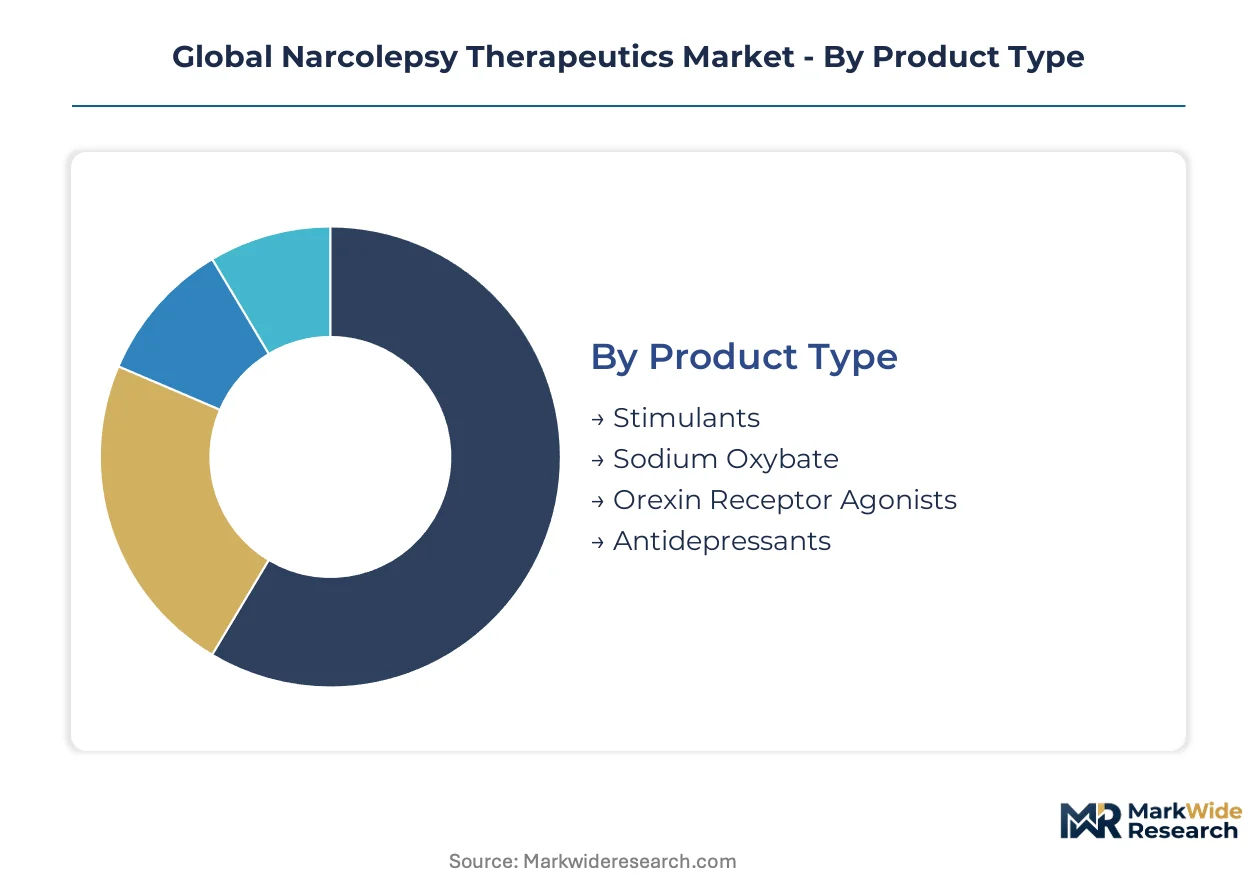
Therapeutic mechanism differentiation determines reimbursement tiers and prescriber access across narcolepsy treatment protocols. Segmentation by product type, therapy area, end user, and delivery mode reveals where development investment concentrates versus where clinical adoption lags.
Product Type:
Upgrade cycles from legacy stimulants to mechanism-driven therapies are compressing development timelines for orexin-targeted candidates.
- Stimulants:Methylphenidate and modafinil formulations dominate prescription volume through established formularies in the United States and Germany. Generic commoditization erodes pricing power while maintaining the largest patient access footprint through primary care channels.
- Sodium Oxybate:Controlled substance scheduling under DEA Schedule III and equivalent European classifications mandates REMS-compliant pharmacy networks. Deep PMDA engagement in Japan has secured orphan drug pathways that accelerate regulatory review against stimulant benchmarks.
- Orexin Receptor Agonists:Dual-receptor agonists entering Phase III trials collapse polypharmacy regimens into single-molecule protocols for cataplexy and excessive daytime sleepiness.
- Antidepressants:Venlafaxine and clomipramine serve off-label roles in REM-atonia suppression where sodium oxybate contraindications exist.
Volume placements concentrate in Stimulants; the faster expansion belongs to Orexin Receptor Agonists.
Therapy Area:
Cost tier stratification separates premium mechanism-driven therapies from generic-sustained symptom management segments.
- Excessive Daytime Sleepiness:The primary diagnostic entry point drives stimulant prescribing volume across hospital and primary care settings in Japan and the United States. FDA orphan drug incentives have accelerated orexin agonist development specifically for this indication.
- Cataplexy:Sudden muscle atonia episodes require sodium oxybate or emerging orexin-targeted protocols with REM-suppressing properties. Germany's G-BA applies stringent cost-effectiveness thresholds against generic comparators for novel mechanisms in this segment.
- Hypnagogic Hallucinations:REM intrusion phenomena respond to antidepressant modulation where orexinergic restoration remains incomplete.
- Sleep Paralysis:Transient atonia episodes at sleep-wake transitions represent the most undertreated category with limited dedicated therapeutic development.
Revenue concentration sits with Excessive Daytime Sleepiness; steepest expansion trajectory targets Cataplexy with first-in-class orexin mechanisms.
End User:
Customer type fragmentation across academic, community, and specialized dispensing settings shapes distribution infrastructure requirements.
- Hospitals:Academic medical centers in Tokyo-Osaka corridors and German university hospitals anchor diagnostic confirmation through polysomnography and CSF orexin measurement protocols. Pharmacy and therapeutics committees increasingly consolidate procurement around mechanism-based therapeutic classes.
- Sleep Disorder Clinics:Dedicated facilities in the United States and Germany deploy home monitoring equivalents and intranasal formulation trials where rapid onset carries clinical priority.
- Neurology Centers:Board-certified somnologist concentration in urban clusters creates diagnostic bottlenecks that wearable adjuncts aim to bypass.
- Specialty Pharmacies:REMS program administration for sodium oxybate products demands controlled substance compliance infrastructure that fragments distribution reach.
Patient volume flows through Sleep Disorder Clinics; margin expansion targets Specialty Pharmacies with REMS-captive dispensing.
Delivery Mode:
Maturity gradients separate established oral dominance from emerging rapid-onset alternatives in acute sleep attack management.
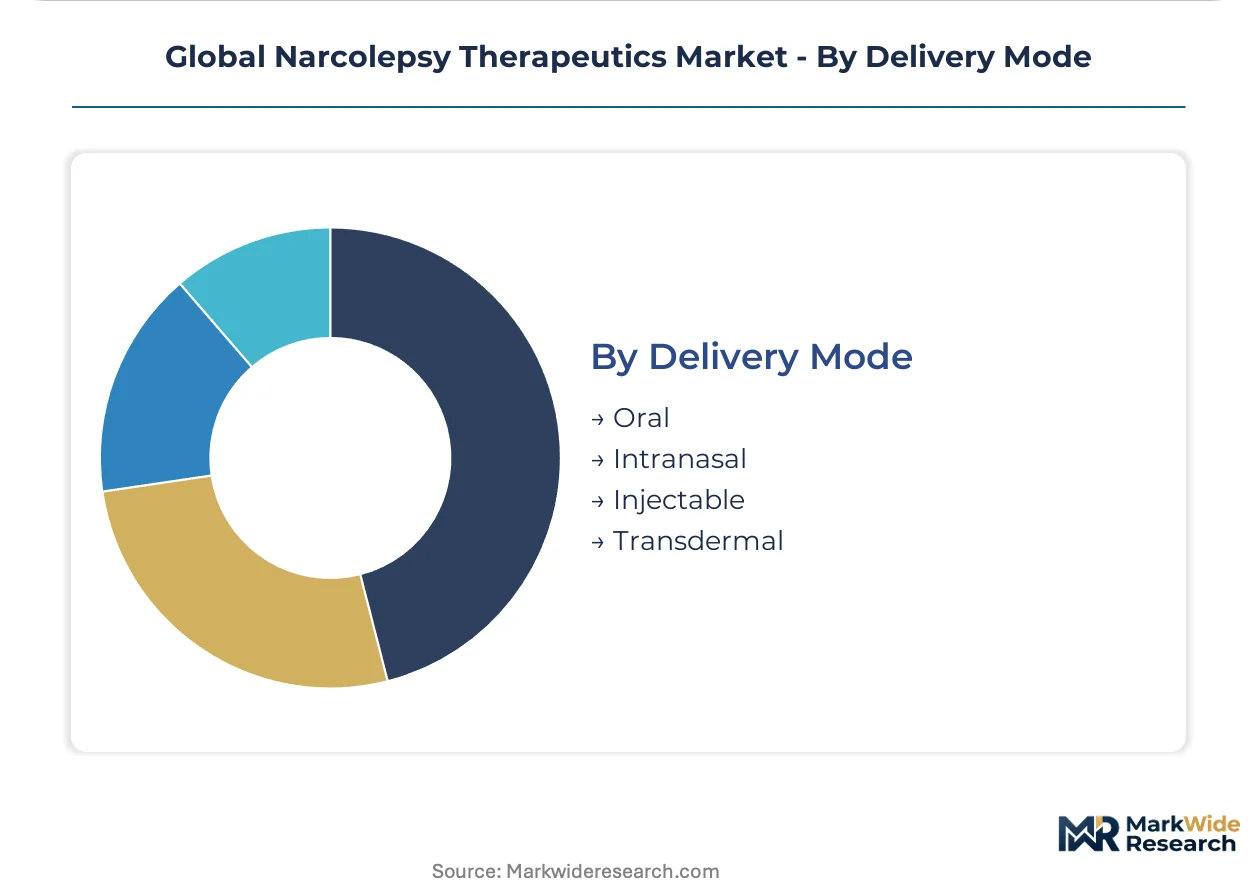
- Oral:Tablet and liquid formulations occupy dominant volume position through gastrointestinal absorption profiles suitable for maintenance therapy. Jazz Pharmaceuticals plc anchors North American distribution through this mode for sodium oxybate franchise products.
- Intranasal:Sleep clinics prioritize spray formulations that bypass first-pass metabolism for acute sleep attack interruption. Takeda Pharmaceutical Company Limited explores PMDA Sakigake pathways for intranasal orexin agonists in Japanese clinical corridors.
- Injectable:Hospital-based administration remains limited to research protocols and severe cataplexy refractory to oral options.
- Transdermal:Patch development targets pediatric and elderly populations with swallowing difficulties or medication adherence challenges.
Prescription volume concentrates in Oral delivery; Intranasal formulations are gaining share fastest in sleep clinic settings prioritizing onset speed.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo-Osaka clinical corridors anchor orexin-targeted therapy development through concentrated PMDA engagement and specialized sleep disorder infrastructure.
United States
FDA orphan drug incentives and DEA Schedule III controls shape sodium oxybate distribution through REMS-compliant specialty pharmacy networks. Sleep disorder clinics in Boston and Stanford corridors deploy polysomnography networks that compress diagnostic timelines. Hospital pharmacy formularies increasingly consolidate procurement around mechanism-based therapeutic classes rather than individual brands.
Germany
G-BA cost-effectiveness thresholds apply stringent benchmarks against generic stimulant comparators for novel mechanisms. The EU Green Deal drives sustainable manufacturing protocols for active pharmaceutical ingredients across Bavarian and North Rhine-Westphalian production clusters. University hospitals in Heidelberg and Munich anchor diagnostic confirmation through CSF orexin measurement standardization efforts.
Japan
PMDA Sakigake designation creates parallel fast-track opportunity for breakthrough orexin-targeted candidates. METI coordinates domestic pharmaceutical manufacturing incentives that reinforce Tokyo-Osaka clinical corridor concentration. Sleep medicine specialists remain concentrated in urban academic medical centers, creating diagnostic bottlenecks that wearable adjuncts aim to bypass.
United Kingdom
NICE technology appraisals evaluate novel mechanisms against generic modafinil and methylphenidate benchmarks. The MHRA post-Brexit regulatory pathway maintains alignment with EMA accelerated assessment frameworks for rare disease indications. London and Manchester sleep centers expand polysomnography capacity to address secondary market diagnostic gaps.
France
HAS cost-effectiveness thresholds challenge premium pricing for orexin receptor agonists against established stimulant formularies. ANSM oversees controlled substance scheduling harmonization with DEA and EMA classifications for sodium oxybate products. Paris and Lyon neurology centers concentrate board-certified somnologist expertise that limits rural diagnostic access.
Global Narcolepsy Therapeutics Market Competitive Landscape
The competitive structure tilts toward diversified pharmaceutical conglomerates with rare disease franchises and specialized neurology-focused biotechs. Market concentration reflects regulatory capture advantages in orphan drug pathways and controlled substance distribution infrastructure. Three archetypes dominate: sodium oxybate franchise holders, orexin-targeted development specialists, and generic stimulant portfolio managers. Competitive moves center on REMS program administration capabilities and PMDA/FDA parallel regulatory filing strategies.
Within the diversified pharmaceutical tier, Jazz Pharmaceuticals plc and Takeda Pharmaceutical Company Limited exemplify contrasting geographic anchoring strategies. Jazz Pharmaceuticals plc occupies a position tied to North American controlled substance distribution infrastructure. Takeda Pharmaceutical Company Limited sits within Japanese regulatory pathway expertise through deep PMDA engagement. Harmony Biosciences Holdings, Inc. represents the specialized biotech archetype focused on hospital-centric prescribing networks for daytime sleepiness indications.
| Leading Market Players |
|---|
| Jazz Pharmaceuticals plc |
| Takeda Pharmaceutical Company Limited |
| Teva Pharmaceutical Industries Ltd. |
| Harmony Biosciences Holdings, Inc. |
| Novartis AG |
| Avadel Pharmaceuticals plc |
| Axsome Therapeutics, Inc. |
| UCB S.A. |
| Bioprojet |
| Others |
Supply & Pricing Matrix
Active pharmaceutical ingredient spot indices for sodium oxybate precursors and controlled substance manufacturing feedstocks cascade through three pricing tiers across narcolepsy therapeutics distribution. Contract manufacturers in Bavaria and North Rhine-Westphalia pass commodity volatility into hospital formulary negotiations, while REMS-captive specialty pharmacies extract margin premiums from DEA Schedule III compliance infrastructure.
Pricing Analysis
Value-based pricing anchored to cataplexy-free days and excessive daytime sleepiness reduction scores stratifies reimbursement tiers across United States, German, and Japanese markets. Three-tier pricing separates orexin receptor agonist premiums from sodium oxybate REMS-administered mid-tier positioning and generic stimulant economy benchmarks. Cost compression in the stimulant tier intensifies as methylphenidate and modafinil commoditization erodes manufacturer pricing power against pharmacy benefit manager benchmarks. Sleep disorder clinics exhibit lowest price sensitivity due to rapid-onset clinical priorities, while primary care networks in rural United States corridors demonstrate highest sensitivity to generic substitution incentives.
Supply Chain Analysis
Orexin peptide synthesis and sodium oxybate precursor chemistry rest on Swiss and German specialty chemical producers with DEA and EMA controlled substance manufacturing licenses. Active pharmaceutical ingredient production draws from Bavarian fermentation facilities, Swiss custom synthesis houses, and Indian generic stimulant bulk manufacturers. Single-source vulnerability concentrates in sodium oxybate salt form production where DEA quota allocations create supply rigidity. Distribution runs through REMS-compliant specialty pharmacy networks for controlled substances and direct-to-hospital channels for orexin-targeted therapies in academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into orexin peptide manufacturing and REMS program administration infrastructure defines competitive positioning across the narcolepsy therapeutics landscape. Players are consolidating backward into controlled substance synthesis capacity and forward into captive specialty pharmacy dispensing to defend margin capture.
For Market Incumbents: Lock in REMS program administration capabilities through specialty pharmacy network acquisitions that fragment generic entrant distribution reach. Secure DEA manufacturing quotas for sodium oxybate precursors to create supply-side moats against emerging orexin agonist developers. Orexin-targeted mechanism displacement threatens stimulant franchise erosion, requiring incumbent investment in dual-receptor agonist pipeline assets. For New Entrants and Emerging Players: Specialty pharmacy partnerships offer the fastest channel access for intranasal formulation launches bypassing hospital formulary gatekeeping. White-space targets concentrate in sleep disorder clinic networks across German secondary cities and Japanese prefectural medical centers outside Tokyo-Osaka corridors where polysomnography infrastructure gaps persist. Go-to-market positioning around rapid-onset delivery modes for acute sleep attack management differentiates against oral maintenance therapy incumbents. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap biotechs with Phase III orexin agonist assets and established PMDA Sakigake designations in Japanese regulatory corridors. Long-term viability hinges on mechanism-based therapeutic class consolidation where hospital pharmacy and therapeutics committees displace physician-level prescribing influence. Watch FDA orphan drug exclusivity expiration timelines and EMA accelerated assessment pathway outcomes as portfolio revaluation triggers.| Strategic Initiative | Industry Significance |
|---|---|
| REMS Program Expansion | Captive distribution infrastructure locks in sodium oxybate dispensing margins against generic erosion. |
| Orexin Agonist Pipeline Advancement | Dual-receptor mechanisms collapse polypharmacy regimens and command premium reimbursement tiers. |
| Intranasal Formulation Development | Rapid-onset delivery modes bypass gastrointestinal variability in acute sleep attack management. |
| PMDA Sakigake Pathway Pursuit | Japanese fast-track designation accelerates regulatory review against stimulant benchmarks in Tokyo-Osaka corridors. |
| Specialty Pharmacy Network Acquisition | Vertical integration into controlled substance dispensing defends DEA Schedule III compliance-captured margins. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this narcolepsy therapeutics market assessment. Primary interviews with drug development executives, regulatory affairs leads, hospital formulary directors, and payer access specialists combined with FDA orphan drug designations, EMA accelerated assessment submissions, ClinicalTrials.gov entries, and PMDA Sakigake registrations. Bottom-up prescription volume modeling and top-down therapeutic class revenue triangulation validated segment-level outputs.
Data-stream reconciliation across polysomnography deployment databases, REMS program participation records, and hospital procurement system feeds structured the analytical framework over the projection horizon. Segmentation dimensions modeled include therapeutic mechanism, therapy area indication, end-user setting, and delivery mode across regional regulatory clusters. CAGRs derived from mechanism adoption curves and generic erosion timelines incorporated orexin agonist clinical trial readouts and sodium oxybate patent expiration schedules as forecast inputs.
Caveats apply where FDA scheduling reclassification, EMA cost-effectiveness threshold adjustments, or PMDA breakthrough therapy designation withdrawals could materially shift the outlook. Forecasts reflect assumptions around diagnostic infrastructure expansion rates and reimbursement negotiation outcomes in Germany, France, and the United Kingdom. A small set of triggers—orexin agonist regulatory approvals, generic stimulant pricing collapses, and REMS program regulatory modifications—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Parkinsons Disease Therapeutics Market
Neurology
CNS Treatment and Therapy Market
Neurology
White Matter Injury Treatment Market
Neurology
CNS Therapeutics Market
Neurology
Neurocutaneous Disorders Market
Neurology
Neurological Biomarkers Market
Neurology
Narcolepsy Treatment Market
Neurology
Canada Neurology Devices Market
Neurology
Chordoma Disease Market
Neurology
Traumatic Brain Injuries Assessment Market
Neurology
Spinal Cord Trauma Treatment Market
Neurology
Neuropsychiatric Disorders and Treatment Market
Neurology
North America Traumatic Brain Injuries Assessment Market
Neurology
Global Acoustic Neuroma Market
Neurology
Tourette Syndrome Market
Neurology
North America Neurology Devices Market