
 Anti-Vascular Endothelial Growth Factor Therapeutics Market | 2026-2036
Anti-Vascular Endothelial Growth Factor Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Vascular Endothelial Growth Factor Therapeutics Market Intelligence
Market Context with Strategic Players
The pricing and clinical positioning of originator biologics versus emerging biosimilars is repositioning how physicians and payers select anti-VEGF therapies for retinal diseases. F. Hoffmann-La Roche Ltd leverages its established manufacturing infrastructure to sustain global supply of ranibizumab formulations. Regeneron Pharmaceuticals, Inc. anchors its competitive stance through integrated R&D and commercial operations in ophthalmology. Bayer AG differentiates via co-promotion structures and geographic reach across European and Asian markets.
Technical Definition and Structural Segments
Anti-vascular endothelial growth factor therapeutics constitute recombinant proteins and monoclonal antibodies engineered to inhibit VEGF-A signaling, thereby suppressing pathological angiogenesis and vascular permeability in diseased tissues. These agents function by binding circulating VEGF ligands or blocking receptor activation, with intravitreal administration achieving therapeutic concentrations in ocular tissues while systemic delivery addresses oncologic indications. The indication dimension shows age-related macular degeneration commanding the largest patient volume, while diabetic macular edema represents the fastest-expanding addressable population as diabetes prevalence climbs. Among delivery modes, intravitreal injection dominates ophthalmology revenue pools, though subcutaneous formulations are gaining traction for oncology applications where patient convenience drives protocol design.
Regulatory Frame and Forward-Looking Close
The FDA, EMA, and WHO set the tripartite regulatory architecture governing anti-VEGF biologics, with each body imposing distinct purity thresholds, immunogenicity surveillance requirements, and post-market pharmacovigilance obligations that directly shape development costs and market entry feasibility. The FDA's biosimilar approval framework under the Biologics Price Competition and Innovation Act compresses exclusivity periods for reference products, intensifying price competition while demanding rigorous analytical and clinical comparability studies from entrants. Stakeholders must monitor evolving interchangeability designations and real-world evidence requirements that will determine whether biosimilar substitution gains traction in retina practices or encounters physician and payer resistance.
Market Dynamics
The transition from originator biologics to biosimilars is compressing reimbursement rates while expanding patient access, fundamentally restructuring how ophthalmology practices and hospital systems procure anti-VEGF therapies.
Growth Catalysts
- Medicare Part B reimbursement:The United States payment structure sustains physician-administered intravitreal therapy access for age-related macular degeneration patients, anchoring volume demand.
- Diabetic macular edema prevalence:Rising diabetes incidence across North America and Europe is expanding the addressable patient population faster than age-related indications.
- EMA biosimilar guidance:European regulatory clarity on analytical comparability requirements accelerates market entry timelines for follow-on biologics.
Market Restraints
- Cold-chain distribution costs:Temperature-controlled logistics for protein-based therapeutics inflate per-dose supply expenses, particularly affecting rural clinic access.
- Immunogenicity surveillance burden:Post-market pharmacovigilance requirements under FDA and EMA frameworks extend development timelines and compliance costs for biosimilar entrants.
- Physician switching inertia:Retina specialists exhibit preference persistence for established originator molecules, delaying biosimilar uptake despite price advantages.
Strategic Opportunities
- Extended-dosing formulations:Sustained-release delivery technologies reduce injection frequency burden, opening differentiation paths beyond molecule pricing.
- Real-world evidence mandates:FDA's expanding requirements for post-approval effectiveness data create competitive openings for firms with robust pharmacovigilance infrastructure.
- India's ophthalmology expansion:Private hospital chains in Mumbai and Delhi are building dedicated retina centers, creating infrastructure for anti-VEGF therapy penetration.
Industry Challenges
- Compounding pharmacy compliance:Off-label bevacizumab repackaging by hospital pharmacies faces intensifying FDA scrutiny over sterility assurance and dosing accuracy.
- Reimbursement code fragmentation:Disparate billing classifications across Medicare, Medicaid, and commercial payers complicate revenue cycle management for multisite practices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Vascular Endothelial Growth Factor Therapeutics Market |
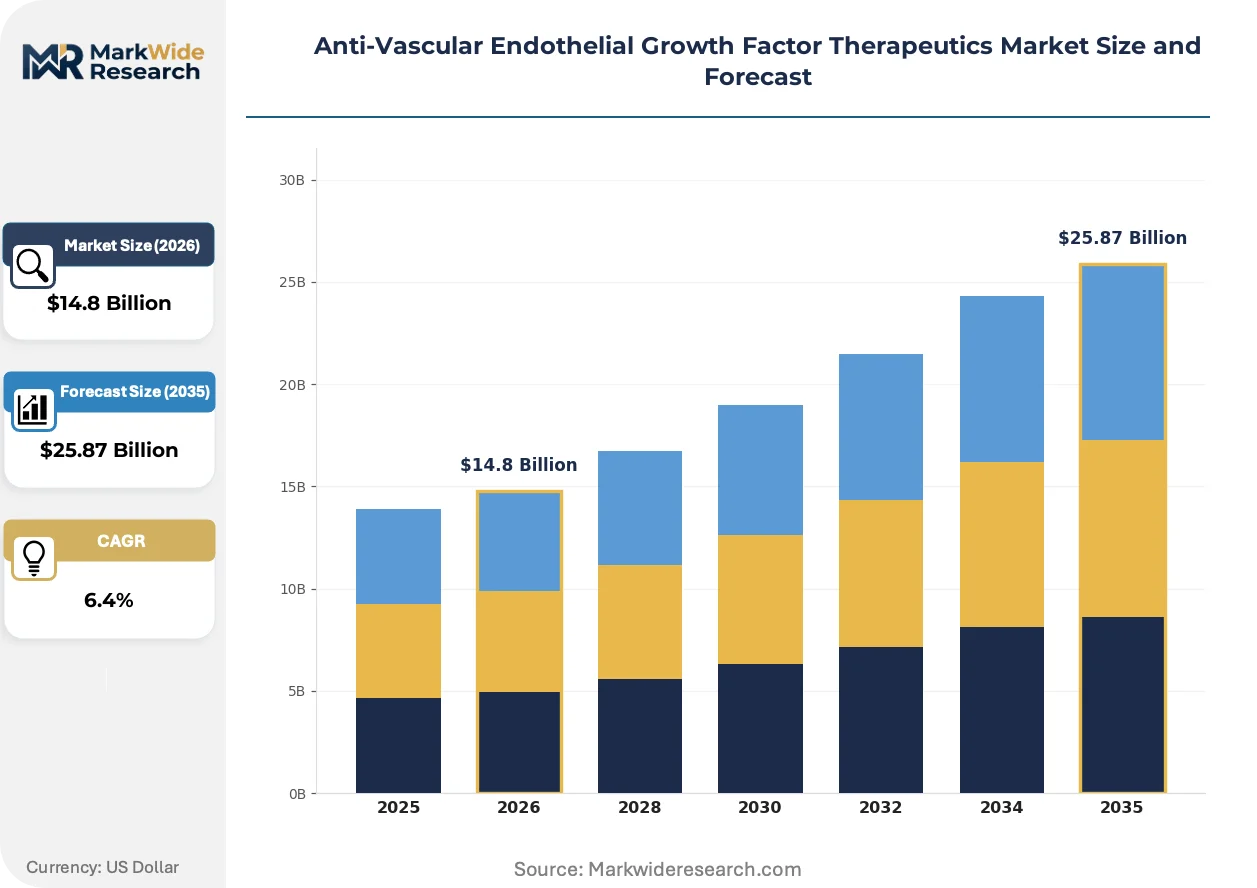
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aflibercept, Bevacizumab, Ranibizumab, Brolucizumab Indication: Age-Related Macular Degeneration, Diabetic Macular Edema, Retinal Vein Occlusion, Cancer Delivery Mode: Intravitreal Injection, Subcutaneous Injection, Intravenous Infusion, Topical Application End User: Hospitals, Clinics, Research Laboratories, Homecare Settings |
| Companies Covered | F. Hoffmann-La Roche Ltd, Regeneron Pharmaceuticals, Inc., Bayer AG, Novartis AG, Amgen Inc., Pfizer Inc., Biogen, Viatris Inc., Coherus BioSciences, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Vascular Endothelial Growth Factor Therapeutics Market Strategic Shifts & Innovations
Gene therapy and sustained-release platforms are disrupting the chronic injection model that has defined retinal disease management for two decades, forcing incumbents to defend their positions through delivery innovation rather than molecule exclusivity alone.
Port delivery systems for ranibizumab are integrating refillable reservoir technology with intravitreal implantation, enabling six-month dosing intervals. Retina specialists in the United States and Germany are adopting these devices for treatment-burdened patients, compressing the competitive advantage of conventional monthly injection protocols.
The FDA's interchangeability designation pathway under the Biologics Price Competition and Innovation Act is creating regulatory incentives for biosimilar developers to pursue switching studies. EMA's parallel guidance on extrapolation of indications is accelerating European approvals, though national pricing authorities in France and Italy retain substantial negotiation leverage.
Hospital systems are consolidating ophthalmology procurement through centralized pharmacy committees, displacing individual physician purchasing autonomy. Integrated delivery networks in Texas and Florida are negotiating system-wide anti-VEGF contracts, shifting volume toward lowest-net-cost alternatives regardless of clinician preference.
Anti-Vascular Endothelial Growth Factor Therapeutics Market Segmentation
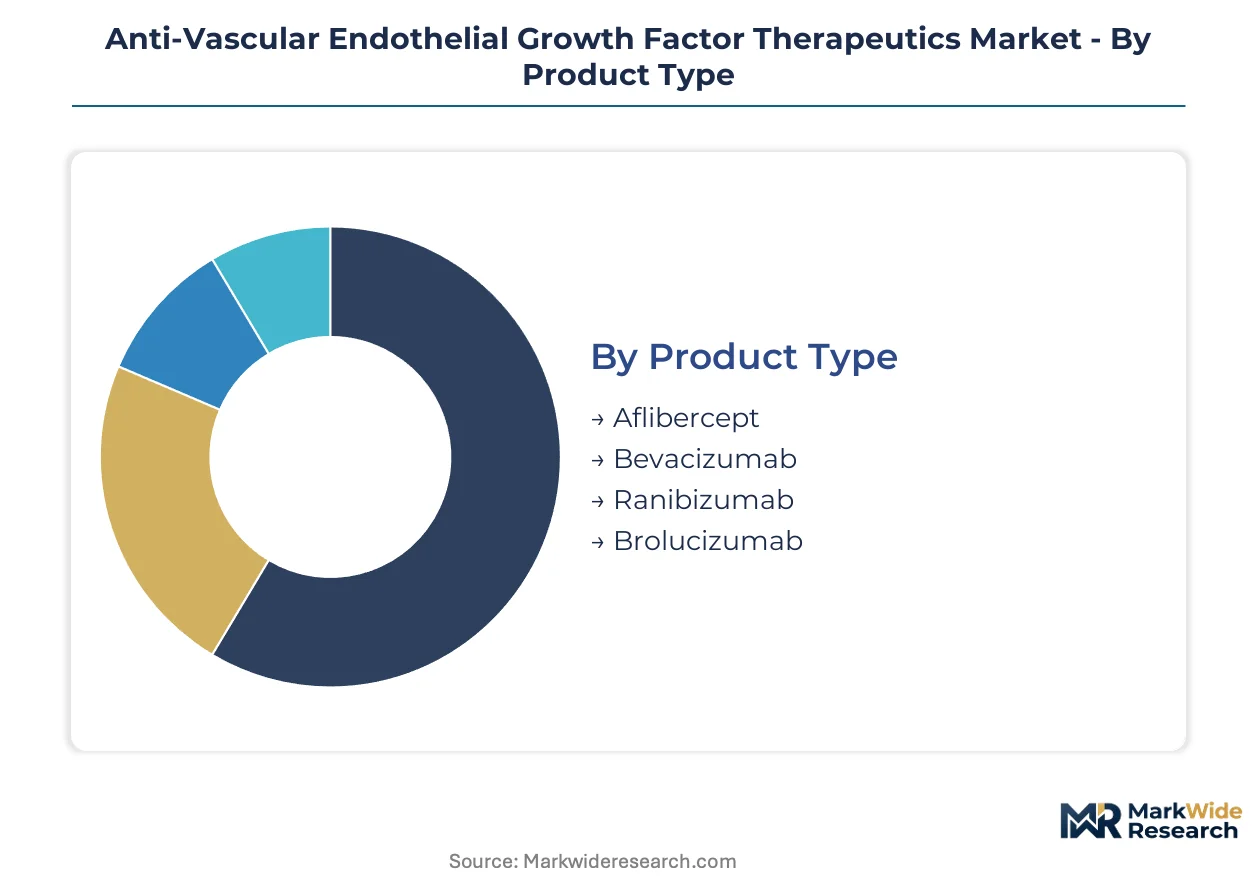
Anti-VEGF therapeutics fragment across four structural dimensions that determine pricing power, reimbursement pathways, and competitive moats. Product type and indication splits reveal where biosimilar pressure concentrates, while delivery mode and end-user channels shape distribution economics and patient access bottlenecks.
Product Type:
Capital intensity varies sharply across molecular platforms, with fusion proteins demanding more complex upstream bioprocessing than monoclonal antibodies.
- Aflibercept:This VEGF trap fusion protein binds multiple VEGF isoforms with higher affinity than antibodies, requiring sophisticated mammalian cell culture infrastructure. United States retina specialists prescribe aflibercept heavily for treatment-resistant diabetic macular edema cases where VEGF-A suppression must outlast conventional dosing intervals. Manufacturing complexity sustains premium positioning even as patent cliffs approach.
- Bevacizumab:The full-length humanized monoclonal antibody against VEGF-A originated in oncology before off-label retinal use exploded. Compounding pharmacies in India and Brazil repackage intravenous bevacizumab into intravitreal doses at one-tenth the cost of ophthalmology-approved alternatives, creating persistent pricing pressure on reimbursed originators.
- Ranibizumab:This Fab fragment lacks the Fc domain to minimize systemic exposure, purpose-engineered for ocular vascular disease. Port delivery system implants now extend its dosing interval to six months.
- Brolucizumab:A single-chain antibody fragment with enhanced tissue penetration, approved for neovascular age-related macular degeneration with every-eight-week maintenance dosing.
Aflibercept and ranibizumab absorb the bulk of installed biomanufacturing capacity; brolucizumab is expanding most quickly among newer entrants.
Indication:
Regulatory approval pathways and pricing power diverge between chronic retinal diseases and acute oncologic applications.
- Age-Related Macular Degeneration:Neovascular AMD generates the largest absolute patient volume among anti-VEGF indications, with Medicare Part B reimbursement anchoring United States demand. Germany's statutory health insurance funds cover ranibizumab and aflibercept without prior authorization, sustaining European volume concentration.
- Diabetic Macular Edema:Rising diabetes prevalence across Mexico and Indonesia is expanding addressable populations faster than aging-driven indications. Extended-dosing formulations gain traction here as injection burden compounds compliance challenges in working-age patients.
- Retinal Vein Occlusion:Macular edema secondary to branch or central retinal vein occlusion responds to anti-VEGF therapy, though treatment duration is typically shorter than chronic AMD management.
- Cancer:Systemic bevacizumab and aflibercept address metastatic colorectal cancer and other solid tumors through intravenous delivery, with oncology reimbursement governed by distinct billing codes.
Age-related macular degeneration commands the deepest revenue pool; diabetic macular edema shows the steepest expansion trajectory.
Delivery Mode:
Route of administration determines cold-chain requirements, administration setting, and patient compliance economics.
- Intravitreal Injection:Direct injection into the vitreous cavity achieves therapeutic concentrations with minimal systemic exposure, dominating ophthalmology revenue. United States ambulatory surgery centers perform millions of these procedures annually under Medicare's facility fee structure.
- Subcutaneous Injection:Self-administered dosing in oncology and emerging ophthalmology applications reduces clinic visit burden. Japan's Ministry of Health, Labour and Welfare has approved subcutaneous formulations for select anti-VEGF agents.
- Intravenous Infusion:Systemic delivery for cancer indications requires infusion center infrastructure and carries cardiovascular safety monitoring obligations.
- Topical Application:Experimental formulations aim to penetrate the corneal barrier for anterior segment neovascularization, though bioavailability remains subtherapeutic for posterior segment disease.
Intravitreal injection retains the dominant share of administration volume; subcutaneous delivery is gaining fastest as patient convenience drives protocol design.
End User:
Procurement sophistication and reimbursement capture vary across institutional settings.
- Hospitals:Academic medical centers in the United States and United Kingdom anchor clinical trial recruitment and complex case referral, with pharmacy committees increasingly consolidating anti-VEGF purchasing across ophthalmology and oncology departments.
- Clinics:Private retina practices in Florida and Texas perform high-volume intravitreal injection under office-based surgical suite models, capturing professional fees alongside drug margin.
- Research Laboratories:Contract research organizations and university labs consume anti-VEGF agents for mechanism-of-study protocols and biosimilar analytical comparability work.
- Homecare Settings:Subcutaneous oncology administration and emerging patient self-injection models shift care away from institutional settings.
Hospitals and clinics together absorb the bulk of commercial volume; homecare settings are expanding most quickly as delivery technologies enable patient-administered dosing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Basel anchors European pharmaceutical manufacturing for anti-VEGF biologics, with the Rhine corridor linking production sites to distribution networks serving retina specialists across the continent.
United States
Medicare Part B reimbursement structures sustain intravitreal injection volume at ambulatory surgery centers in Florida and Texas. The FDA's biosimilar approval pathway under the Biologics Price Competition and Innovation Act compresses exclusivity periods for reference products. Retina specialists in Miami and Houston are adopting port delivery systems that extend dosing intervals to six months.
Germany
Statutory health insurance funds cover ranibizumab and aflibercept without prior authorization, anchoring European demand concentration. EMA guidance on analytical comparability accelerates biosimilar market entry timelines for follow-on biologics. The Munich-Stuttgart medical corridor hosts specialized retina centers that drive adoption of extended-dosing formulations.
Japan
Aging demographics expand the neovascular age-related macular degeneration patient pool faster than population growth rates. PMDA approval of subcutaneous formulations for select anti-VEGF agents enables patient convenience-driven protocol design. Tokyo and Osaka medical centers anchor clinical trial recruitment for sustained-release delivery technologies.
India
Private hospital chains in Mumbai and Delhi are building dedicated retina centers that create infrastructure for anti-VEGF therapy penetration. CDSCO regulatory pathways for biosimilar biologics demand rigorous immunogenicity surveillance that extends development timelines. Compounding pharmacies in Hyderabad repackage intravenous bevacizumab into intravitreal doses at substantial cost reductions.
Brazil
Rising diabetes prevalence across São Paulo and Rio de Janeiro expands the diabetic macular edema addressable population. ANVISA imposes distinct purity thresholds and post-market pharmacovigilance obligations that shape development costs for entrants. Hospital systems in the Southeast region are consolidating ophthalmology procurement through centralized pharmacy committees.
Anti-Vascular Endothelial Growth Factor Therapeutics Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the anti-VEGF therapeutics landscape, with integrated biopharmaceutical companies maintaining captive manufacturing infrastructure while specialty biotechnology firms rely on contract manufacturing organizations for commercial supply. The market structure concentrates around originator biologics facing patent cliff pressure from emerging biosimilars. Three archetypes dominate: vertically integrated innovators with ophthalmology-focused R&D pipelines, biosimilar specialists pursuing interchangeability designations, and diversified pharmaceutical conglomerates leveraging co-promotion structures. Competitive moves center on delivery technology licensing and geographic expansion through distribution partnerships.
Among Swiss-origin integrated innovators, F. Hoffmann-La Roche Ltd occupies a position exemplifying manufacturing infrastructure depth, while Regeneron Pharmaceuticals, Inc. anchors the US-based biotechnology archetype with integrated R&D and commercial operations in ophthalmology. Bayer AG represents the diversified pharmaceutical conglomerate model, differentiating through co-promotion structures and geographic reach across European and Asian markets.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Regeneron Pharmaceuticals, Inc. |
| Bayer AG |
| Novartis AG |
| Amgen Inc. |
| Pfizer Inc. |
| Biogen |
| Viatris Inc. |
| Coherus BioSciences, Inc. |
| Others |
Cost & Logistics Intelligence
Port delivery system implants for ranibizumab and sustained-release formulation technologies are compressing per-dose manufacturing costs while concentrating production among biologics specialists with mammalian cell culture infrastructure. This dual shift simultaneously reduces price elasticity for extended-interval therapies and tightens supply control around Swiss and German production hubs.
Pricing Analysis
Medicare Part B reimbursement rates for intravitreal injections anchor value-based pricing for physician-administered anti-VEGF therapies in the United States. Pricing stratifies across originator biologics, FDA-designated biosimilars, and compounded bevacizumab alternatives, with differentiation driven by dosing interval convenience and immunogenicity surveillance documentation. Cost compression in the compounded segment intensifies as hospital pharmacies face sterility assurance scrutiny. Price sensitivity concentrates among integrated delivery networks negotiating system-wide contracts, while academic medical centers prioritize clinical outcome data over acquisition cost.
Supply Chain Analysis
Cold-chain logistics costs for protein-based therapeutics inflate per-dose expenses from Swiss and German manufacturing sites to United States and Asian distribution points. Mammalian cell culture infrastructure draws from Basel, Munich-Stuttgart, and Boston-Cambridge production clusters, with dependence on single-source bioreactor equipment and temperature-controlled freight networks. Single-source vulnerability in Fc-fusion protein purification creates bottleneck exposure. Distribution runs through specialty pharmacy channels and hospital-based compounding facilities for intravitreal preparation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The anti-VEGF therapeutics market sits in a technology-transition phase where sustained-release delivery platforms and gene therapy candidates threaten to displace chronic injection protocols that have dominated retinal disease management for two decades.
For Market Incumbents: Lock in retina specialist relationships through port delivery system training programs and real-world evidence partnerships before biosimilar interchangeability designations accelerate substitution. Vertical integration into refillable reservoir manufacturing secures supply continuity as FDA post-market surveillance requirements tighten. Defend formulary positioning by embedding pharmacovigilance data collection into electronic health record workflows at high-volume injection centers. For New Entrants and Emerging Players: Enter via diabetic macular edema indication expansion in Southeast Asian private hospital chains where diabetes prevalence outpaces infrastructure buildout. India's CDSCO pathway for biosimilar biologics presents the most penetrable regulatory entry point for firms with robust immunogenicity surveillance capabilities. Target co-promotion structures with established ophthalmology sales organizations rather than direct physician detailing. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified pharmaceutical conglomerates seeking ophthalmology therapeutic area depth. Long-term viability hinges on delivery technology differentiation rather than molecule exclusivity alone. Watch FDA interchangeability designation grants to biosimilar candidates as the inflection signal for accelerated pricing compression timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Port Delivery System Commercialization | Extends ranibizumab dosing intervals to six months, reducing treatment burden for AMD patients. |
| Biosimilar Interchangeability Pursuit | FDA switching studies enable automatic substitution at pharmacy level, compressing originator margins. |
| Extended-Dosing Formulation Development | Every-twelve-week aflibercept protocols reduce injection frequency compliance barriers in working-age DME populations. |
| Real-World Evidence Infrastructure Investment | Post-approval effectiveness databases satisfy FDA pharmacovigilance mandates and defend formulary positioning. |
| Retina Center Partnership Expansion | Exclusive supply agreements with Mumbai and Delhi hospital chains capture volume in diabetes-driven growth markets. |
Research Approach
FDA Orange Book filings, EMA assessment reports, and ClinicalTrials.gov protocol databases formed the secondary backbone for molecule-level competitive positioning and regulatory timeline reconstruction. Primary interviews with drug development executives at integrated biopharmaceutical companies, regulatory affairs leads at biosimilar specialists, formulary directors at United States integrated delivery networks, and hospital procurement managers at German statutory health insurance funds validated secondary findings. Bottom-up patient volume estimates by indication and top-down revenue triangulation across manufacturer disclosures converged on segment-level market sizing.
Bottom-up modeling anchored volume projections to neovascular AMD and diabetic macular edema epidemiology across the analysis window, with top-down cross-checks against Medicare Part B claims data and German sickness fund reimbursement statistics. Segmentation dimensions included product type, indication, delivery mode, and end-user channel. CAGRs derived from year-over-year growth rate reconciliation across these independent estimation paths. Forecast inputs incorporated PMDA subcutaneous approval timelines and CDSCO biosimilar guidance evolution.
Revisions become necessary when FDA interchangeability designations accelerate beyond modeled timelines, when sustained-release gene therapy candidates advance through Phase III, or when Medicare reimbursement structures shift toward episode-based payment. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Leflunomide Market
Pharmaceuticals
Global Ebola Virus Vaccine Market
Pharmaceuticals
Chloramphenicol Eye Drops Market
Pharmaceuticals
Respiratory Virus Vaccines Market
Pharmaceuticals
Ophthalmic Drugs Market
Pharmaceuticals
Global Polio Vaccines Market
Pharmaceuticals
Omega 3 Prescription Drugs Market
Pharmaceuticals
Intravenous (IV) Iron Drugs Market
Pharmaceuticals
Traveler's Diarrhea Treatment Market
Pharmaceuticals
Migraine Nasal Spray Market
Pharmaceuticals
Skin Cancer Drugs Market
Pharmaceuticals
Prostaglandin Analogs Market
Pharmaceuticals
Global Thyroid Cancer Drugs Market
Pharmaceuticals
Hydroxyzine Market
Pharmaceuticals
Global Thin Film Drugs Market
Pharmaceuticals
Global Eylea Market