
 Narcolepsy Treatment Market | 2026-2036
Narcolepsy Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Narcolepsy Treatment Market Outlook
Patient support and medication adherence subscription programs is rebalancing how pharmaceutical firms capture lifetime value beyond the initial prescription. Jazz Pharmaceuticals plc sustains its position through deep specialization in sleep disorder therapeutics and controlled-substance distribution infrastructure. Takeda Pharmaceutical Company Limited leverages its global neurology footprint to navigate regional regulatory complexity for orexin-targeted therapies. Harmony Biosciences anchors the mid-market with its focus on histamine H3 receptor antagonism and pediatric narcolepsy indications.
Narcolepsy treatment encompasses pharmacological interventions targeting excessive daytime sleepiness, cataplexy, and sleep architecture disruption through mechanisms affecting hypocretin/orexin signaling, monoamine reuptake, and GABA-B receptor modulation. Sodium oxybate formulations require restricted distribution systems due to their abuse potential and narrow therapeutic index, while emerging therapies target orexin receptor agonism to address underlying pathophysiology. The stimulant segment dominates current prescription volumes despite reimbursement scrutiny, whereas intranasal delivery modes represent the fastest-growing structural category as developers seek faster onset and improved patient compliance. Home care settings increasingly absorb maintenance therapy administration, shifting margin pools away from institutional infusion centers.
The FDA's REMS requirements for sodium oxybate products and the DEA's scheduling classifications for stimulant therapies create substantial compliance burdens that filter market entrants by regulatory capability. EMA's centralized pediatric investigation plans and the EU's orphan drug framework shape European development priorities and exclusivity timelines. Stakeholders must monitor orexin-targeted pipeline progress against evolving payer criteria for step-therapy protocols and biomarker-based patient stratification.
Market Dynamics
The narcolepsy treatment market is restructuring around orexin-targeted mechanisms as developers abandon incremental stimulant improvements for pathophysiology-altering approaches. This shift is compressing development timelines for first-in-class entrants while forcing established sodium oxybate franchises to defend through formulation and delivery innovations.
Growth Catalysts
- FDA Orphan Drug Incentives:Seven-year market exclusivity and tax credits for clinical trial costs accelerate investment in narcolepsy-specific development programs.
- Diagnostic Criteria Expansion:ICSD-3 refinements and biomarker validation are expanding the addressable patient population beyond historically underdiagnosed cohorts.
- Histamine H3 Receptor Antagonism:Wake-promoting mechanisms without abuse potential are capturing formulary preference in pediatric and cardiovascular-comorbid populations.
Market Restraints
- DEA Schedule II Classification:Stimulant therapies face dispensing limits, prescriber registration requirements, and inventory tracking burdens that constrain pharmacy participation.
- Sodium Oxybate Supply Concentration:Single-source API manufacturing and restricted distribution through certified pharmacies create vulnerability to manufacturing disruptions.
- Reimbursement Step-Therapy Mandates:Payers require documented failure on generic modafinil or armodafinil before approving branded alternatives, extending time-to-therapy.
Strategic Opportunities
- Intranasal Delivery Platforms:Rapid-onset formulations for cataplexy rescue address unmet need in acute episode management, bypassing gastrointestinal absorption variability.
- Home Administration Expansion:Self-injectable and sublingual formats shift care from sleep centers to residential settings, capturing margin from institutional infusion.
- EMA Pediatric Investigation Plans:Mandatory development timelines for pediatric indications create regulatory clarity and exclusivity extensions for compliant sponsors.
Industry Challenges
- REMS Compliance Infrastructure:Sodium oxybate Risk Evaluation and Mitigation Strategies require certified pharmacy networks, prescriber training programs, and patient registry maintenance that consume operational resources.
- Controlled-Substance Manufacturing Capacity:DEA quota allocations for stimulant APIs create production planning uncertainty and limit batch scale-up flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Narcolepsy Treatment Market |
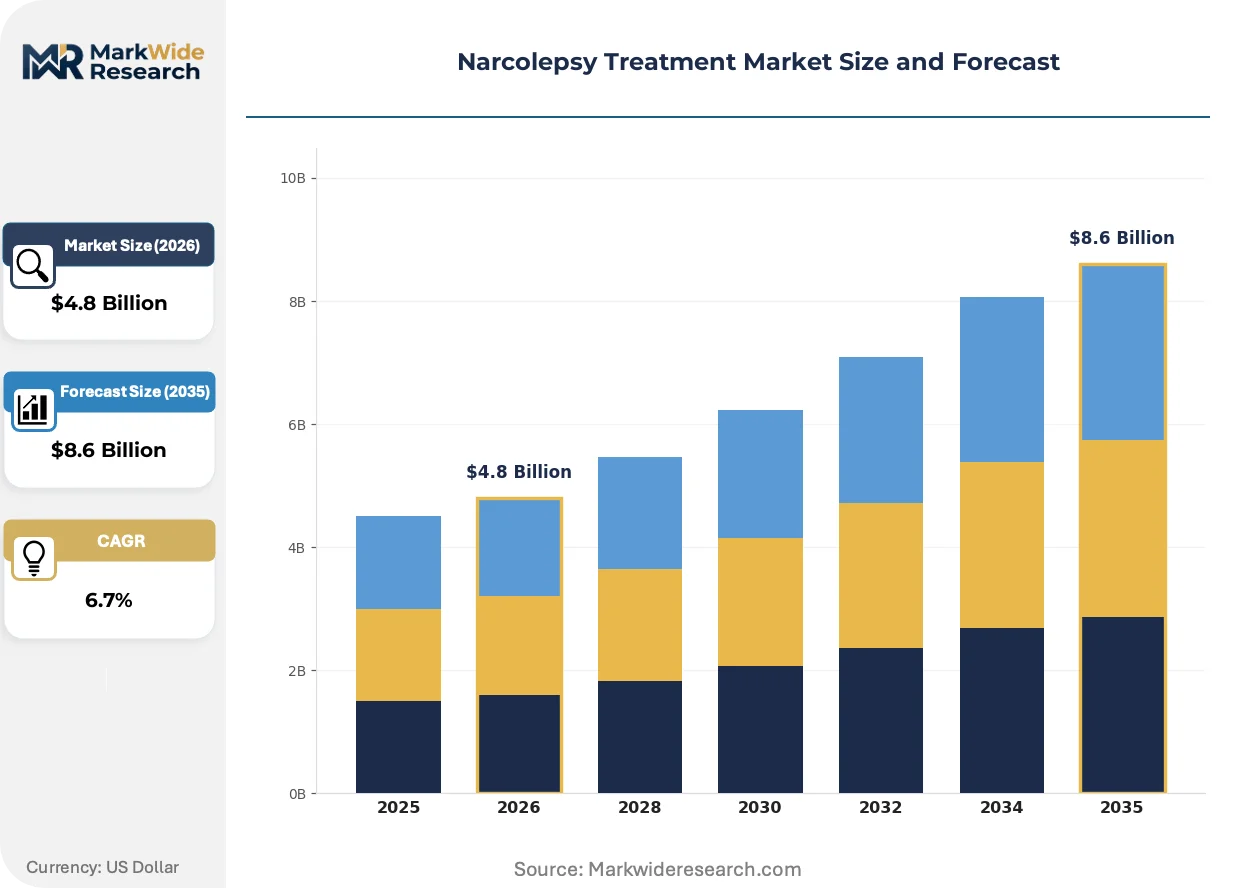
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stimulants, Antidepressants, Sodium Oxybate, Modafinil Delivery Mode: Oral, Injectable, Intranasal, Transdermal End User: Hospitals, Clinics, Home Care Settings, Specialty Centers Treatment Stage: Initial Treatment, Maintenance Therapy, Adjunct Therapy, Acute Management |
| Companies Covered | Takeda Pharmaceutical Company Limited, Axsome Therapeutics, Jazz Pharmaceuticals plc, Alkermes, NLS Pharmaceutics, Harmony Biosciences, Teva Pharmaceutical Industries Limited, Cerevel Therapeutics, Avadel Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Narcolepsy Treatment Market Strategic Shifts
Orexin receptor agonism is overtaking incremental reformulation as the dominant innovation pathway, with developers prioritizing pathophysiological correction over symptomatic management. This reorientation is attracting neurology-focused investment while compressing valuations for pure-play stimulant portfolios.
Dual orexin receptor agonists are overtaking traditional wake-promoting agents in late-stage development pipelines. Sleep disorder specialists and academic medical centers are prioritizing these mechanisms for treatment-resistant patients. The technology is overtaking conventional stimulant franchises in prescriber mindshare, forcing established players to accelerate lifecycle management investments.
EMA's centralized pediatric investigation plans are reshaping European development priorities for narcolepsy therapeutics. Sponsors must commit to age-appropriate formulation development and juvenile toxicology studies prior to marketing authorization. Pediatric neurologists in Germany, France, and Italy are gaining earlier access to investigational therapies through these mandated programs.
Subscription-based adherence programs are displacing traditional pharmacy dispensing in the sodium oxybate segment. Patients receive coordinated refill management, nurse education, and sleep diary monitoring through manufacturer-managed platforms. This model concentrates in the United States where specialty pharmacy networks and REMS requirements create infrastructure for longitudinal patient engagement.
Narcolepsy Treatment Market Segmentation
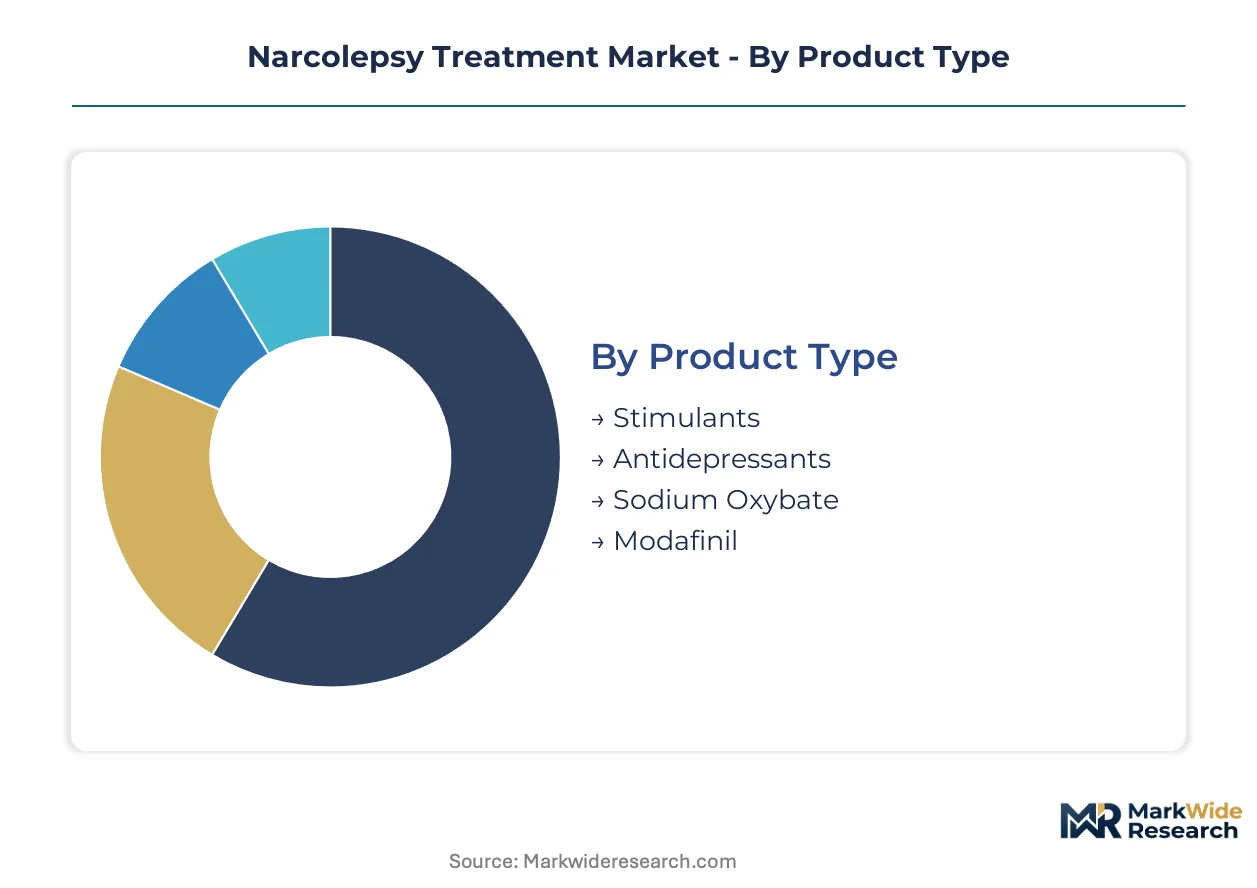
Narcolepsy treatment segmentation reveals how regulatory burden, reimbursement pathways, and care delivery settings fragment commercial opportunity. Each dimension carries distinct FDA, DEA, or REMS compliance requirements that shape go-to-market economics and patient access barriers.
Product Type:
FDA scheduling classifications and REMS mandates create tiered certification barriers across pharmacological categories, with controlled substances demanding the most intensive distribution infrastructure.
- Stimulants:Amphetamine and methylphenidate formulations classified as DEA Schedule II substances require locked storage, prescriber DEA registration, and monthly dispensing limits that constrain pharmacy participation. Demand concentrates in the United States where diagnostic expansion has outpaced European stimulant prescribing caution.
- Sodium Oxybate:GABA-B receptor agonist requiring FDA-mandated REMS with certified pharmacy networks, patient registries, and prescriber training programs. The narrow therapeutic index and abuse potential necessitate overnight dispensing through specialty channels, creating operational complexity that filters market entrants by regulatory capability.
- Modafinil:Wake-promoting agent with Schedule IV classification offering lighter compliance burden than traditional stimulants, positioned as first-line therapy in payer step-therapy protocols.
- Antidepressants:Venlafaxine and protriptyline repurposed for cataplexy management without controlled-substance scheduling, capturing preference in cardiovascular-comorbid populations where stimulant contraindications apply.
Leading the category by volume: Stimulants. Growing fastest: Sodium Oxybate.
Delivery Mode:
Route of administration determines manufacturing complexity, bioavailability consistency, and patient compliance economics across acute and chronic use cases.
- Oral:Dominant format encompassing tablets, capsules, and liquid formulations with established bioequivalence pathways and broad pharmacy coverage. Cost tier spans generic modafinil through branded sodium oxybate solutions.
- Intranasal:Rapid-onset formulations targeting cataplexy rescue bypass gastrointestinal absorption variability, expanding fastest as developers seek emergency-use differentiation and pediatric acceptance.
- Injectable:Subcutaneous and intravenous routes for hospital-based acute management and treatment-resistant cases, concentrated in academic medical centers with sleep disorder specialization.
- Transdermal:Patch-based delivery in early development for steady-state plasma levels and reduced dosing frequency, appealing to maintenance therapy adherence programs.
Highest margin concentration: Intranasal. Steepest volume climb: Oral sustained-release formulations.
End User:
Care setting determines reimbursement codes, nursing intensity, and patient monitoring infrastructure requirements that segment margin pools.
- Specialty Centers:American Academy of Sleep Medicine-accredited programs with polysomnography infrastructure and REMS-certified prescribers, commanding premium reimbursement for complex diagnosis and titration.
- Home Care Settings:Self-administered maintenance therapy with remote monitoring platforms, absorbing volume as subscription-based adherence programs displace institutional dispensing.
- Hospitals:Inpatient sleep medicine units handling acute exacerbations, diagnostic workups, and orexin-targeted therapy clinical trials.
- Clinics:Community neurology and primary care sites managing stable patients on established regimens with lighter monitoring requirements.
Volume leadership: Specialty Centers. Fastest patient shift: Home Care Settings.
Treatment Stage:
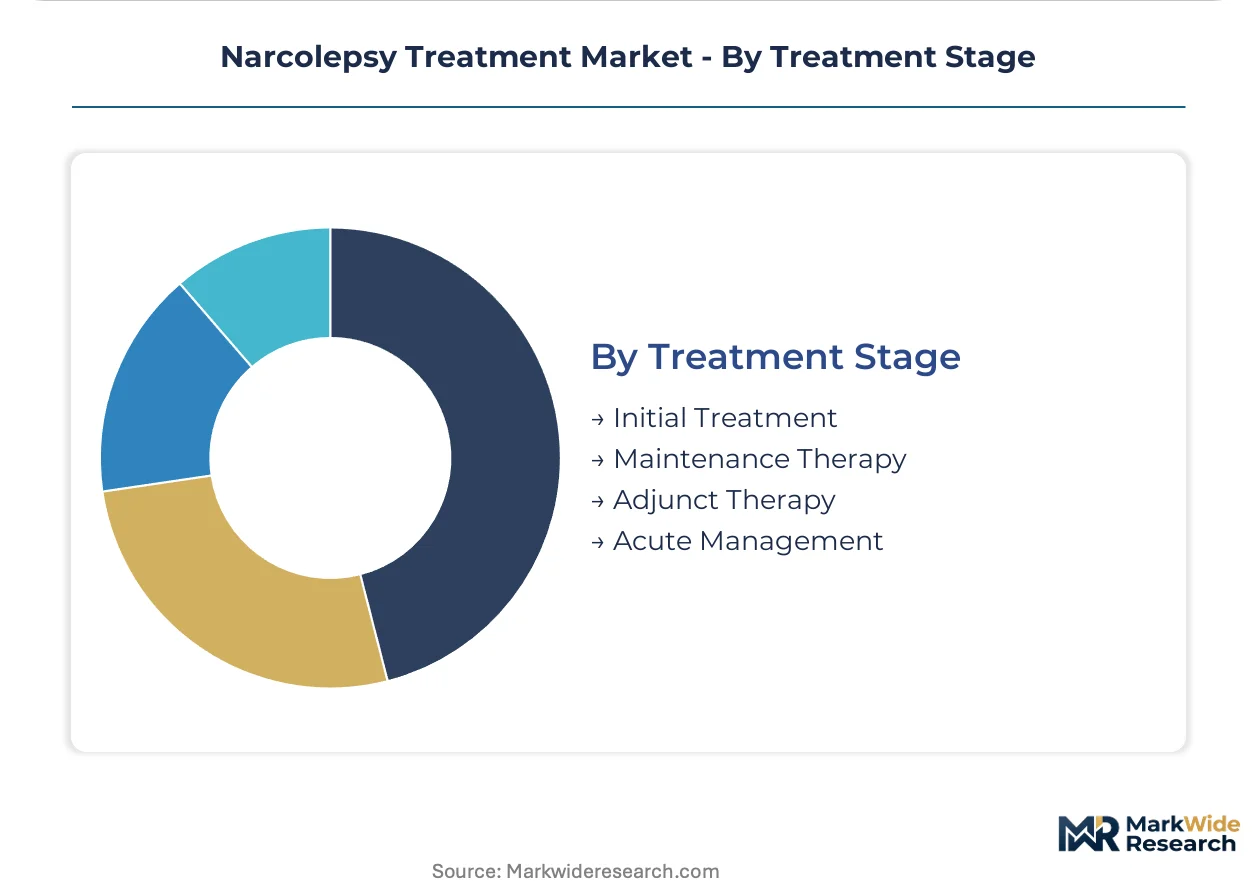
Disease progression and therapy response stratify patient journeys from diagnosis through long-term management, with each stage carrying distinct clinical and commercial characteristics.
- Initial Treatment:Diagnostic confirmation through polysomnography and multiple sleep latency testing followed by first-line wake-promoting agent selection, concentrated in academic medical centers with specialized sleep laboratories.
- Maintenance Therapy:Long-term regimen optimization with quarterly clinical monitoring and adherence tracking, representing the largest addressable population as diagnostic expansion extends treatment duration.
- Adjunct Therapy:Combination approaches for incomplete responders adding sodium oxybate or antidepressants to stimulant baselines, requiring intensive pharmacovigilance.
- Acute Management:Cataplexy episode intervention and status cataplecticus protocols, limited to emergency departments and specialized inpatient units.
Patient population depth: Maintenance Therapy. Steepest clinical investment: Adjunct Therapy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of narcolepsy APIs clusters in Switzerland and Ireland while prescription volumes concentrate in the United States and Germany. Consumption patterns diverge sharply between markets with permissive stimulant prescribing and those favoring orexin-targeted alternatives.
United States
Sleep center expansion in Boston and Stanford drives diagnostic capacity growth. FDA REMS programs for sodium oxybate formulations shape distribution infrastructure requirements. The FDA maintains stringent prescriber certification through certified pharmacy networks concentrated in specialty hubs.
Germany
EMA pediatric investigation plans mandate development timelines that accelerate pediatric narcolepsy access. German sleep medicine centers in Munich and Heidelberg lead European orexin-targeted therapy adoption. The country's national pharmaceutical regulator enforces centralized adverse event reporting for controlled substances.
Japan
PMDA orphan drug designation for narcolepsy indications attracts sponsor investment in orexin receptor agonists. Tokyo and Osaka academic medical centers conduct pivotal trials for dual orexin receptor agonists. METI funding for rare disease infrastructure expands polysomnography access beyond metropolitan cores.
Switzerland
Swissmedic's streamlined orphan drug pathways draw API manufacturing investment from global sponsors. Basel and Zurich host contract manufacturing organizations producing sodium oxybate active pharmaceutical ingredients. The country's regulatory framework permits parallel scientific advice with EMA to accelerate European market entry.
United Kingdom
NHS England's specialized commissioning for rare neurological conditions narrows treatment access to designated centers. London and Manchester sleep disorder units manage complex cataplexy cases requiring sodium oxybate titration. The MHRA's post-Brexit recognition framework preserves EMA orphan exclusivity periods for existing authorizations.
Narcolepsy Treatment Market Competitive Environment
Capital-heavy producers with integrated controlled-substance manufacturing compete with asset-light developers licensing orexin-targeted compounds. Market structure concentrates around three strategic tiers: established sleep disorder specialists with REMS infrastructure, neurology-focused multinationals leveraging global regulatory capabilities, and emerging biotechs advancing first-in-class mechanisms. Dominant competitive moves include portfolio diversification into pediatric indications and strategic partnerships for intranasal delivery platform access.
Within the established specialist tier, Jazz Pharmaceuticals plc and Harmony Biosciences occupy positions defined by deep vertical integration in sleep disorder therapeutics. Takeda Pharmaceutical Company Limited anchors the multinational neurology segment with orexin-targeted development capabilities. Axsome Therapeutics exemplifies the emerging biotech archetype advancing novel mechanisms without legacy distribution infrastructure.
| Leading Market Players |
|---|
| Takeda Pharmaceutical Company Limited |
| Axsome Therapeutics |
| Jazz Pharmaceuticals plc |
| Alkermes |
| NLS Pharmaceutics |
| Harmony Biosciences |
| Teva Pharmaceutical Industries Limited |
| Cerevel Therapeutics |
| Avadel Pharmaceuticals |
| Others |
Value Chain & Pricing Dynamics
Orexin-targeted manufacturing transitions from small-molecule synthesis to biologic production, simultaneously elevating capital requirements and concentrating API sourcing among Swiss and Irish contract manufacturers with orphan-drug certification. This dual shift compresses margin pools for generic stimulant producers while amplifying pricing power for vertically integrated specialists commanding REMS-certified distribution networks.
Pricing Analysis
Margin tightening in sodium oxybate reflects single-source API concentration and overnight specialty pharmacy dispensing requirements. Three-tier pricing structure across REMS-certified branded, authorized generic, and non-REMS stimulant alternatives separates compliance-burdened from commodity-access therapies. Cost-down pressure on modafinil accelerates because payer step-therapy mandates force pre-authorization failures before branded access. Pediatric neurologists exhibit lowest price sensitivity due to formulary carve-outs for H3 receptor antagonists without cardiovascular contraindications.
Supply Chain Analysis
Single-source vulnerability sits with Swiss sodium oxybate API manufacturers and DEA-quota-dependent stimulant producers in the United States. Active pharmaceutical ingredient production draws from Basel contract manufacturing organizations, Irish chemical synthesis facilities, and Indian generic finished-dose suppliers. Regulatory restriction risk centers on DEA production quota allocations that limit batch scale-up flexibility for Schedule II substances. Distribution runs through certified specialty pharmacy networks with patient registry maintenance, bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration races in this market center on captive orexin-receptor agonist manufacturing and REMS-certified pharmacy network ownership, with upstream API control and downstream patient-data platforms as the contested levers.
For Market Incumbents: Hedge sodium oxybate franchise erosion by accelerating intranasal rescue formulation development and securing dual-source API agreements with Swiss manufacturers. Orexin-targeted biologics from Takeda and emerging entrants threaten pathophysiology-altering substitution, making pediatric indication exclusivity extensions through EMA compliance the priority defensive lever. For New Entrants and Emerging Players: Begin with intranasal cataplexy rescue formulations in the United States, where REMS infrastructure gaps and acute episode unmet need create the most penetrable entry point. Target sleep disorder specialists at academic medical centers bypassing saturated stimulant prescribing, leveraging sublingual and self-injectable formats to capture home administration margin pools. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap biotechs with phase-ready orexin agonists and established REMS infrastructure players with pediatric exclusivity timelines. Long-term viability hinges on regulatory moat sustainability against generic modafinil pressure and orexin-mechanism substitution risk. Watch FDA breakthrough therapy designation velocity for dual orexin receptor agonists as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| REMS Infrastructure Expansion | Certified pharmacy network ownership locks in sodium oxybate dispensing exclusivity against generic erosion. |
| Pediatric Investigation Plan Compliance | EMA-mandated development timelines secure indication extensions and orphan exclusivity in European markets. |
| Intranasal Delivery Platform Licensing | Rapid-onset formulations capture cataplexy rescue market share from oral maintenance therapies. |
| Dual Orexin Receptor Agonist Advancement | Pathophysiology-targeted mechanisms displace symptomatic stimulant management in prescriber preference. |
| Home Administration Format Development | Self-injectable and sublingual dosing shifts care from sleep centers to residential settings. |
Study Parameters
FDA filings, EMA centralized procedure records, and ClinicalTrials.gov registries formed the secondary backbone, cross-referenced with formulary database audits and DEA quota allocation reports. Primary fieldwork encompassed regulatory affairs leads at orphan-drug sponsors, formulary directors at national payers, and sleep center medical directors at academic medical centers. Bottom-up patient-flow modeling and top-down pharmaceutical revenue triangulation anchored market size estimation.
Bottom-up treatment-line penetration curves and top-down therapeutic class revenue reconciliation framed analytical approach across the projection horizon. Segmentation dimensions encompassed pharmacological mechanism, DEA scheduling tier, administration route, patient age stratum, and regional regulatory cluster. CAGRs derived from epidemiological expansion rates, diagnostic criteria refinement impact, and therapy-switching probability matrices calibrated against historical analog orphan-drug adoption curves.
Regulatory approval delays, orexin-targeted clinical trial failures, and DEA manufacturing quota reductions are the dominant revision risks to modeled assumptions. Forecasts reflect documented epidemiological, regulatory, and competitive dynamics without claiming predictive certainty. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Diabetic Neuropathy Market
Neurology
Central Nervous System Lymphoma Treatment Market
Neurology
Arachnoiditis Treatment Market
Neurology
Global Acoustic Neuroma Market
Neurology
Idiopathic Intracranial Hypertension Therapeutics Market
Neurology
North America Traumatic Brain Injuries Assessment Market
Neurology
North America Neurology Devices Market
Neurology
Global Neuromarketing Market
Neurology
UAE Neurology Devices Market
Neurology
Ulnar Nerve Treatment Market
Neurology
Asia-Pacific Neurology Monitoring Market
Neurology
Hydrocephalus Market
Neurology
Nerve Repair Market
Neurology
Arachnoiditis Market
Neurology
Aneurysmal Subarachnoid Hemorrhage Market
Neurology
Cerebral Spinal Fluid (CSF) Management Market