
 Oral Antiviral Market | 2026-2036
Oral Antiviral Market Size, Share, and Industry Trends Forecast 2026-2036
Oral Antiviral Market Analysis
The FDA's Project Orbis framework for oncology and infectious disease reviews is broadening parallel submission opportunities across regulatory agencies. Gilead Sciences Inc. leverages its nucleoside analogue expertise to sustain dominance in HIV and hepatitis portfolios. Merck & Co., Inc. anchors its position through Molnupiravir manufacturing scale and government procurement relationships. F. Hoffmann-La Roche Ltd differentiates through companion diagnostic integration with antiviral prescribing protocols.
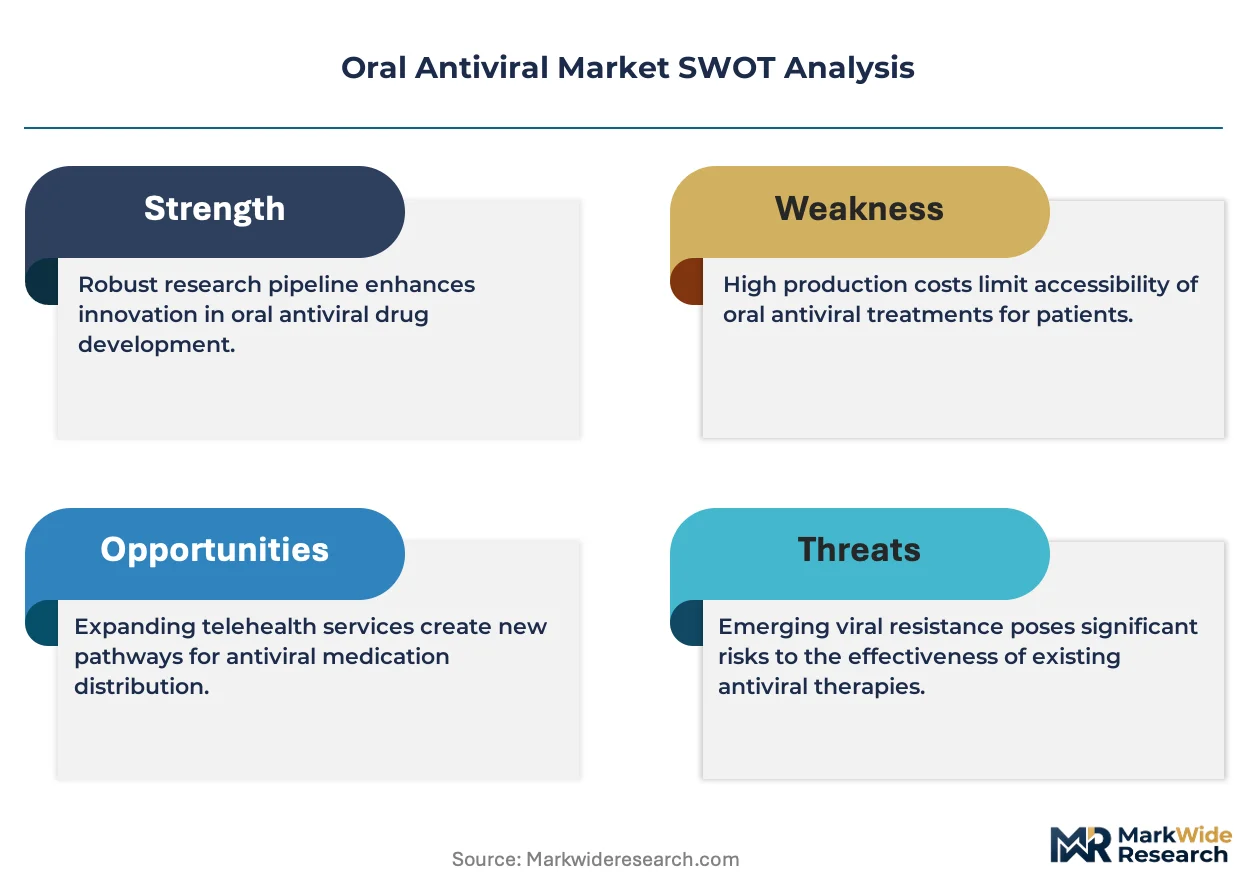
Oral antivirals are small-molecule pharmaceuticals administered per os, typically formulated as tablets or capsules with defined bioavailability thresholds and hepatic metabolism profiles, designed to inhibit viral replication through enzyme interference or genome incorporation. These agents serve primary commercial purpose in reducing hospitalization burden for chronic and acute viral infections across outpatient settings. The indication dimension shows HIV and hepatitis commanding established reimbursement infrastructure, while COVID-19 indication exhibits volatile demand patterns tied to variant emergence cycles. Among product types, protease inhibitors occupy concentrated margin pools due to formulation complexity and patent exclusivity, whereas NRTIs face accelerating generic substitution.
The FDA's accelerated approval and breakthrough therapy designations shape development prioritization, while the EMA's adaptive pathways and WHO prequalification standards govern access for lower-income country procurement. Health Canada's priority review vouchers and Japan's PMDA sakigake designation further fragment regulatory strategy requirements. Stakeholders must monitor emerging resistance surveillance networks and variant-tracking infrastructure investments to align pipeline priorities with clinical utility windows.
Market Dynamics
Hospital-to-home care migration is compressing intravenous antiviral demand while expanding outpatient oral prescription volumes, forcing manufacturers to reconfigure distribution networks around retail pharmacy and mail-order channels rather than institutional procurement.
Growth Catalysts
- Medicare reimbursement preference:The US Centers for Medicare & Medicaid Services structures outpatient drug reimbursement to favor oral formulations over infusion-based alternatives, accelerating prescriber adoption of tablet-based regimens for hepatitis C and HIV maintenance therapy.
- FDA Project Orbis:This parallel review framework allows infectious disease drug developers to submit simultaneously to multiple national regulators, compressing time-to-market for novel oral antiviral candidates by 12-18 months versus sequential filings.
- Direct-acting antiviral polymerase inhibitors:These next-generation mechanisms achieve sustained virologic response with shorter treatment durations than protease inhibitor combinations, expanding addressable patient populations in resource-limited settings.
Market Restraints
- Active pharmaceutical ingredient concentration:Over 70% of small-molecule antiviral raw materials originate from Chinese and Indian contract manufacturers, creating geographic supply vulnerability and quality audit complexity for Western formulation sites.
- Generic nucleoside analogue substitution:Patent expirations on tenofovir, emtricitabine, and lamivudine have triggered price collapse in HIV combination therapy, eroding branded revenue pools and compressing R&D reinvestment capacity.
- Hepatic metabolism variability:Cytochrome P450 polymorphisms across patient populations force dose adjustment protocols and drug-drug interaction surveillance, limiting universal dosing convenience and expanding pharmacovigilance costs.
Strategic Opportunities
- Sub-Saharan Africa procurement consolidation:The Global Fund and PEPFAR are centralizing oral antiviral purchasing through volume guarantee mechanisms, creating preferred supplier status for manufacturers with WHO prequalification and heat-stable formulation capabilities.
- Companion diagnostic integration:Resistance testing and viral load monitoring are migrating from centralized laboratories to point-of-care platforms, enabling same-day test-and-treat protocols that expand oral antiviral initiation rates in decentralized settings.
- Japan PMDA sakigake designation:This priority review pathway for innovative infectious disease therapies offers accelerated approval and extended market exclusivity, attracting pipeline investment for novel mechanisms targeting influenza and respiratory syncytial virus.
Industry Challenges
- Resistance surveillance infrastructure:Viral variant emergence outpaces phenotypic testing capacity at national reference laboratories, forcing manufacturers to maintain redundant genotypic assay development programs to support label expansion.
- Biomanufacturing talent scarcity:Contract development organizations face acute shortages of process chemists with nucleoside synthesis expertise, extending tech transfer timelines and constraining capacity for high-potency oral antiviral production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oral Antiviral Market |
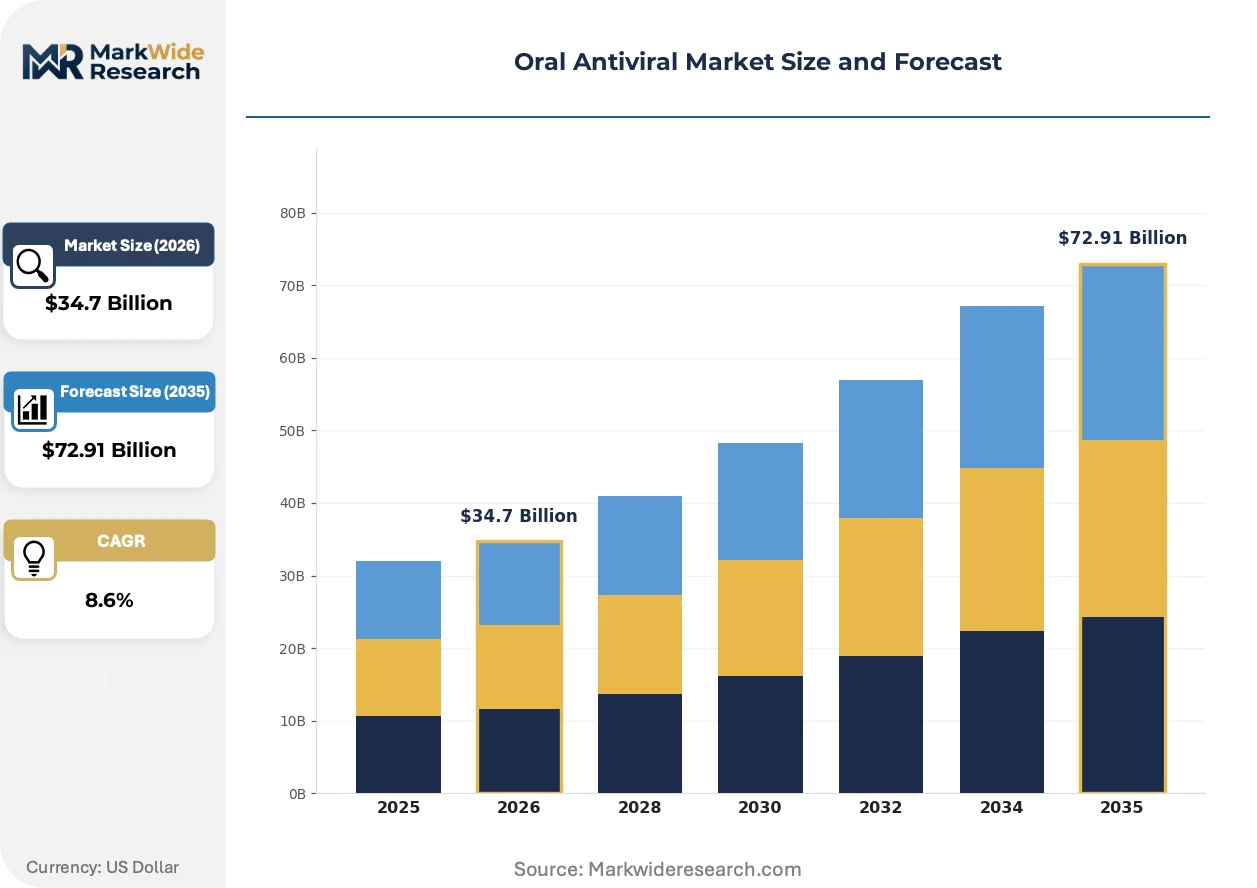
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $72.91 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: NNRTIs, NRTIs, Protease Inhibitors, Others Indication: HIV, Influenza, Hepatitis, COVID-19 End User: Hospitals, Clinics, Homecare, Pharmacy Distribution Channel: Retail, Online, Wholesaler, Direct Sales |
| Companies Covered | Gilead Sciences Inc., Merck & Co., Inc., GSK plc, AbbVie Inc., Bristol-Myers Squibb Company, F. Hoffmann-La Roche Ltd, Johnson & Johnson Services, Inc., Cipla Inc., Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oral Antiviral Market Emerging Trajectories
Digital therapeutics and real-world evidence platforms are converging with oral antiviral development, reshaping how manufacturers demonstrate clinical value and secure formulary placement beyond traditional randomized trial endpoints.
Artificial intelligence-driven molecular design is automating lead optimization for oral bioavailability and metabolic stability. Biotech startups and large pharmaceutical firms deploy generative chemistry models to screen billions of virtual compounds against viral polymerase crystal structures. This compression of discovery timelines from 24 months to under 8 months is reallocating chemistry resources toward formulation science and patient adherence technologies.
The European Medicines Agency's adaptive pathway framework now permits initial approval based on surrogate endpoints for infectious disease therapies, with confirmatory evidence collected through post-authorization safety studies. This regulatory flexibility is accelerating conditional marketing authorization for oral antivirals targeting emerging respiratory pathogens. Manufacturers must now build real-world data collection infrastructure as a core competency rather than post-market obligation.
Retail pharmacy chains are consolidating specialty oral antiviral dispensing through central fill models that bypass traditional hospital outpatient pharmacies. This channel migration concentrates purchasing power with three national pharmacy benefit managers in the United States, who now demand outcomes-based rebate structures tied to medication possession ratios and hospitalization avoidance.
Oral Antiviral Market Segmentation
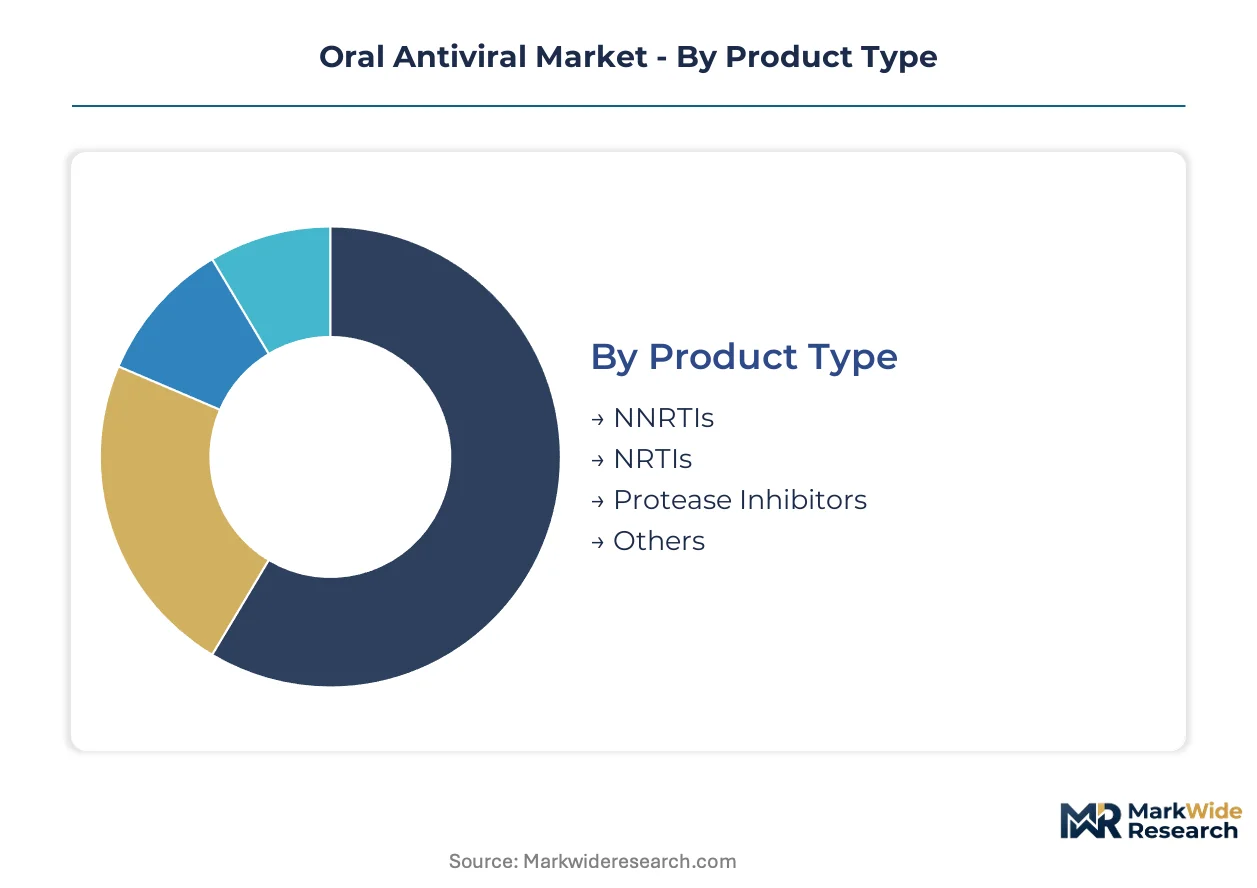
Oral antiviral procurement patterns diverge sharply across molecular classes and care settings, with reimbursement structures and resistance profiles dictating upgrade cycles for combination regimens. Manufacturers align formulation investments with the shift from hospital-based infusion to outpatient tablet dispensing.
Product Type:
Replacement dynamics favor next-generation mechanisms with improved resistance barriers and reduced pill burden over legacy nucleoside backbones.
- Protease Inhibitors:These agents require complex stereoselective synthesis and exhibit high hepatic metabolism, commanding premium pricing in HIV salvage therapy. Demand clusters in the United States where Medicare Part D covers branded boosted combinations despite generic tenofovir availability.
- NRTIs:Nucleoside reverse transcriptase inhibitors form the backbone of first-line HIV therapy, with tenofovir alafenamide displacing tenofovir disoproxil fumarate in high-income markets due to improved renal safety profiles. Volume concentrates in Sub-Saharan Africa procurement through the Global Fund.
- NNRTIs:Non-nucleoside reverse transcriptase inhibitors provide single-tablet regimen compatibility with lower manufacturing cost structures.
- Others:This category encompasses integrase strand transfer inhibitors and entry inhibitors with distinct resistance profiles.
Volume placements concentrate in NRTIs; the faster expansion belongs to protease inhibitors.
Indication:
Cost tier stratification separates chronic maintenance indications with predictable reimbursement from acute respiratory indications with volatile demand spikes.
- HIV:Chronic infection management drives sustained prescription volumes with well-established PrEP and treatment markets, anchored by WHO guidelines and PEPFAR procurement in lower-income settings.
- Hepatitis:Curative direct-acting antiviral courses for hepatitis C face contracting patient pools as elimination targets near in high-income countries, while hepatitis B maintenance therapy expands in East Asia.
- COVID-19:Pandemic-era demand for nirmatrelvir-ritonavir and molnupiravir fluctuates with variant waves and government stockpiling cycles.
- Influenza:Seasonal prophylaxis and treatment markets face competition from vaccines and neuraminidase inhibitors with established clinical utility.
Revenue stability clusters in HIV; the steepest expansion trajectory appears in COVID-19 during surge periods.
End User:
Patient type determines site-of-care economics, with risk-bearing health systems driving migration toward lower-acuity settings.
- Hospitals:Inpatient initiation of oral antivirals for severe influenza or COVID-19 requires therapeutic drug monitoring capabilities and specialist oversight.
- Homecare:Post-discharge oral antiviral completion for hepatitis C and HIV maintenance eliminates infusion center visits, reducing total cost of care for Medicare Advantage plans.
- Clinics:Federally qualified health centers and infectious disease practices handle complex resistance cases requiring genotypic testing.
- Pharmacy:Retail dispensing of 90-day HIV maintenance supplies concentrates with specialty pharmacy networks managing prior authorization workflows.
Patient volumes are shifting fastest toward homecare; hospitals retain the highest-acuity caseloads.
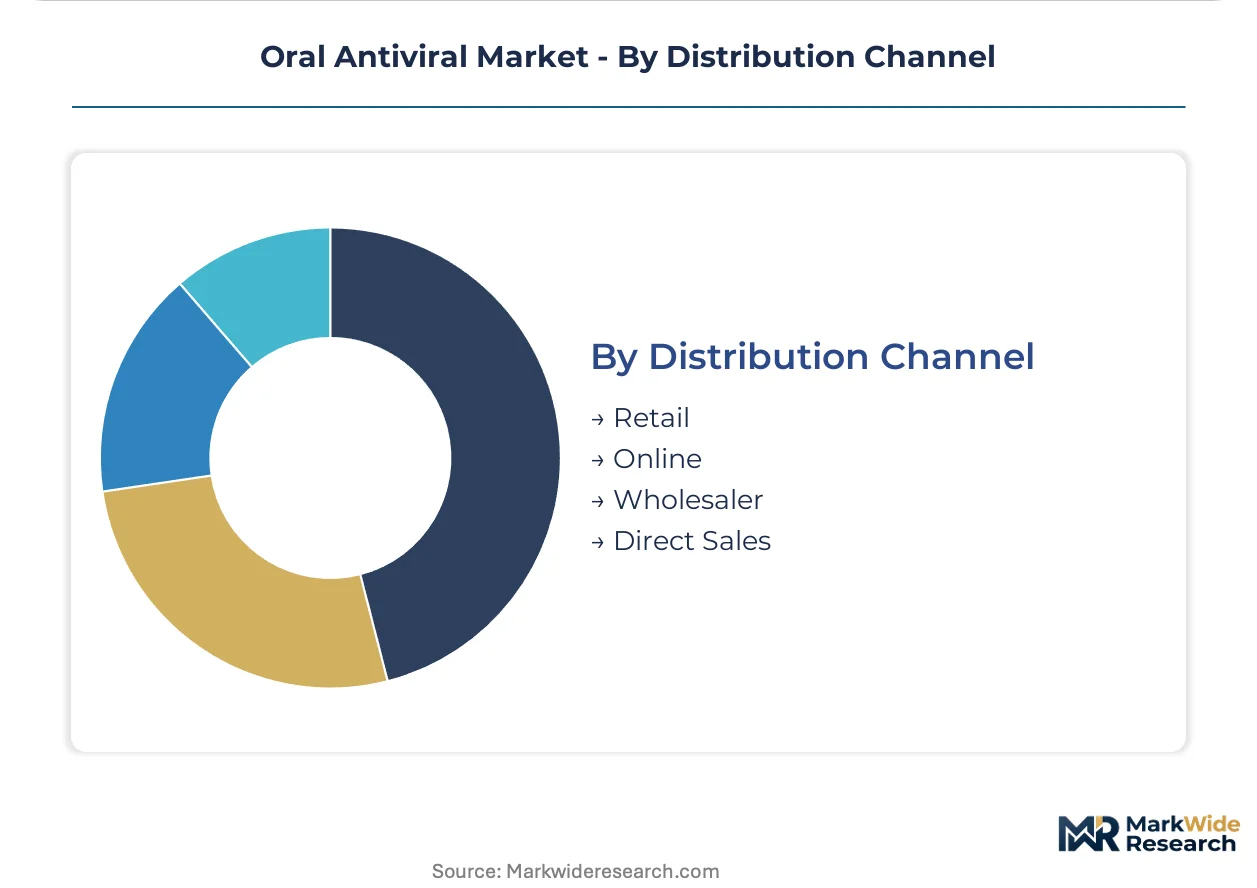
Distribution Channel:
Supply chain configuration determines formulary access speed and rebate capture for manufacturers competing on net price.
- Retail:Brick-and-mortar pharmacy networks handle acute antiviral dispensing with same-day availability, critical for influenza and COVID-19 treatment windows.
- Wholesaler:Three national distributors control hospital and retail inventory flow, demanding data exclusivity and price protection clauses in distribution agreements.
- Online:Mail-order specialty pharmacies manage 90-day HIV and hepatitis supplies with adherence packaging and refill synchronization.
- Direct Sales:Government procurement of strategic national stockpiles bypasses commercial channels for pandemic preparedness.
Wholesaler relationships dominate institutional volume; online channels are gaining share fastest in chronic disease maintenance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentration for oral antiviral active pharmaceutical ingredients clusters in China and India, while consumption and pricing power concentrate in the United States and Western Europe. This divergence creates supply chain vulnerability and regulatory complexity for formulation sites.
United States
Medicare Part D reimbursement structures favor oral formulations over intravenous alternatives, driving prescriber adoption of tablet-based regimens. The FDA's Project Orbis framework compresses approval timelines for infectious disease therapies by enabling parallel submissions to multiple regulators. Boston and San Francisco anchor clinical trial networks for novel antiviral candidates.
Germany
The EMA's centralized marketing authorization procedures position Germany as the gateway for European oral antiviral commercialization. Germany's statutory health insurance funds negotiate rebates based on real-world evidence of hospitalization avoidance. The Rhine-Main biotech corridor houses resistance surveillance laboratories supporting phenotypic testing capacity.
India
Contract manufacturing organizations in Hyderabad and Ahmedabad supply over 60% of global nucleoside analogue raw materials for HIV and hepatitis therapies. The CDSCO's accelerated approval pathways for essential medicines align with WHO prequalification standards. Gujarat's pharmaceutical clusters specialize in high-volume tenofovir and lamivudine production.
Japan
The PMDA's sakigake designation offers priority review and extended market exclusivity for innovative infectious disease therapies. Japan's aging demographic drives demand for influenza and respiratory syncytial virus oral treatments. The Kansai region concentrates formulation expertise for heat-stable tablet development.
Brazil
ANVISA's reliance on FDA and EMA approvals streamlines registration for oral antivirals already authorized in major markets. The Unified Health System procures HIV therapies through volume guarantees with domestic distributors. São Paulo's research institutes participate in global resistance surveillance networks for viral variant tracking.
Oral Antiviral Market Vendor Landscape
The competitive structure tilts toward nucleoside analogue specialists with captive manufacturing and large-cap diversified pharmaceutical firms with government procurement relationships. Consolidation pressure intensifies as generic substitution erodes branded revenue pools in HIV combination therapy. Two archetypes dominate: vertically integrated API-to-formulation manufacturers and diagnostic-integrated therapy developers. Competitive moves center on companion diagnostic partnerships and heat-stable formulation licensing for tropical markets.
Within the nucleoside specialist tier, Gilead Sciences Inc. and Merck & Co., Inc. occupy positions anchored by manufacturing scale and government stockpiling relationships. F. Hoffmann-La Roche Ltd exemplifies the diagnostic-integrated archetype through resistance testing and viral load monitoring platforms. These three firms represent distinct strategic postures: API backward integration, pandemic preparedness contracting, and precision prescribing infrastructure.
| Leading Market Players |
|---|
| Gilead Sciences Inc. |
| Merck & Co., Inc. |
| GSK plc |
| AbbVie Inc. |
| Bristol-Myers Squibb Company |
| F. Hoffmann-La Roche Ltd |
| Johnson & Johnson Services, Inc. |
| Cipla Inc. |
| Novartis AG |
| Others |
Supply Flow & Price Mechanics
PEPFAR and Global Fund procurement concentration in Sub-Saharan Africa anchors the dominant contract-based long-term offtake pricing model for oral antivirals, with volume guarantee mechanisms compressing net prices for tenofovir-containing regimens while rewarding WHO-prequalified suppliers with multi-year purchasing commitments.
Pricing Analysis
Margin tightening in branded HIV combination therapy reflects patent cliff dynamics and accelerated generic tenofovir substitution. Pricing stratifies across premium protease inhibitor salvage regimens, standard first-line NRTI backbones, and economy-tier lamivudine monotherapy for resource-limited settings. Cost-down pressure on originator formulations intensifies as Indian contract manufacturers achieve bioequivalence with heat-stable generics. Government procurement programs exhibit lowest price sensitivity; retail pharmacy cash-pay segments in emerging markets face highest elasticity.
Supply Chain Analysis
Return flows of expired antiviral stockpiles from national strategic reserves create reverse-logistics complexity for heat-sensitive formulations requiring cold-chain documentation for destruction protocols. Active pharmaceutical ingredient production concentrates in China, India, and Italy, with Hyderabad and Ahmedabad anchoring nucleoside analogue synthesis capacity. Key inputs include tenofovir disoproxil fumarate, lamivudine, and ritonavir boosting agents. Single-source vulnerability from Wuhan-area intermediate manufacturers elevates geographic risk exposure. Distribution runs through three national wholesalers controlling hospital and retail inventory flow in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA Project Orbis and EMA adaptive pathway requirements erect substantial cost-of-compliance barriers that protect incumbent manufacturers with established regulatory affairs infrastructure while filtering speculative entrants lacking phenotypic testing capabilities or post-authorization study funding.
For Market Incumbents: Anticipate resistance surveillance infrastructure investments becoming mandatory for label maintenance as variant-tracking networks expand. Consolidate manufacturing scale through backward integration into nucleoside API production to offset generic substitution pressure. Prioritize heat-stable formulation licensing for tropical markets to secure WHO prequalification status.
For New Entrants and Emerging Players: Capture white-space in influenza and respiratory syncytial virus oral therapies where resistance barriers remain underexploited. Target Japan's PMDA sakigake pathway for priority review acceleration. Pursue companion diagnostic partnerships enabling same-day test-and-treat protocols in decentralized African clinics.
For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated API-to-formulation manufacturers with captive tenofovir supply in Gujarat and Hyderabad during patent cliff troughs. Long-term viability hinges on resistance barrier durability across the analysis window. Monitor variant emergence frequency at national reference laboratories as inflection signal for pipeline prioritization shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | EMA adaptive pathway submissions compress time-to-market for respiratory antiviral candidates by enabling surrogate endpoint approval. |
| Manufacturing Scale-Up | High-volume tenofovir production in Gujarat secures Global Fund procurement preference through WHO prequalification alignment. |
| Regulatory Approval Pathway | FDA Project Orbis parallel submissions reduce regulatory lag by 12-18 months versus sequential national filings. |
| Strategic Partnership | Companion diagnostic integration with Roche viral load platforms enables precision prescribing in resistance-managed HIV salvage therapy. |
| Pipeline Diversification | Polymerase inhibitor mechanisms targeting influenza and RSV expand addressable markets beyond saturated HIV nucleoside segments. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this oral antiviral market assessment. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers supplied qualitative grounding. Secondary sources included FDA approval databases, EMA centralized procedure submissions, ClinicalTrials.gov protocol registries, and WHO prequalification listings. Bottom-up patient volume modeling and top-down pharmaceutical spending reconciliation enabled cross-validation.
Granularity-level modeling treated molecular class, indication, and end-user setting as fully specified dimensions across the projection horizon. Treatment line, dosage form, and regional regulatory cluster provided additional segmentation depth. CAGRs derived from patient population forecasts, pricing trajectory assumptions, and generic substitution curves. Resistance surveillance capacity investments and variant emergence frequency served as industry-specific forecast modifiers.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to resistance barrier durability, generic entry timing, and procurement consolidation shifts. Forecasts reflect documented assumptions about reimbursement stability and regulatory pathway continuity. Material deviation in variant tracking infrastructure funding or WHO guideline revision warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Australia Pharmaceuticals Market
Pharmaceuticals
Global Tetanus Toxoid Vaccine Market
Pharmaceuticals
Naproxen Market
Pharmaceuticals
Steroid-Free Nasal Sprays Market
Pharmaceuticals
Contract Pharmaceutical Fermentation Services Market
Pharmaceuticals
Testosterone Nasal Gels Market
Pharmaceuticals
Injectable Potassium Phosphate Market
Pharmaceuticals
Dual Antiplatelet Therapy Market
Pharmaceuticals
Global Anticoagulant Reversal Drugs Market
Pharmaceuticals
Global Pediatric Drugs Market
Pharmaceuticals
Global Online Pharmacy Market
Pharmaceuticals
Albinism Drugs Market
Pharmaceuticals
Macrolides Market
Pharmaceuticals
Systemic Antibiotics Market
Pharmaceuticals
US Over the Counter Drugs Market
Pharmaceuticals
Oral Contraceptive Pills Market