
 Latin America Meglitinide Market | 2026-2036
Latin America Meglitinide Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Meglitinide Market Foresight
Pharmacokinetic precision standards is unwinding cost-driven procurement patterns across Latin American diabetes care. Novo Nordisk leverages its insulin co-therapy portfolio to anchor hospital formulary positioning in Brazil. Glenmark competes through aggressive generic penetration of repaglinide across outpatient clinics in Mexico and Colombia. Sanofi sustains brand loyalty among endocrinologists via its established diabetes franchise presence.
Meglitinides comprise a class of short-acting insulin secretagogues that bind to ATP-dependent potassium channels on pancreatic beta cells, triggering rapid glucose-dependent insulin release with a half-life under one hour. Their primary commercial purpose centers on postprandial glycemic control for type 2 diabetes patients with erratic meal timing or sulfonylurea intolerance. Repaglinide dominates product type volume due to its broader reimbursement footprint, while nateglinide occupies the premium niche among patients prioritizing hypoglycemia avoidance. Diabetes care centers represent the fastest-growing end user channel as Latin American health systems shift chronic disease management away from general hospitals.
ANVISA governs pharmaceutical registration and bioequivalence standards for meglitinide generics entering Brazil, while COFEPRIS shapes market access pathways through Mexico's sanitary registration requirements. Both regulators tighten manufacturing site inspections, forcing multinational suppliers to upgrade active pharmaceutical ingredient sourcing documentation. Stakeholders must monitor pending harmonization between Mercosur and PAHO pharmacovigilance protocols, as alignment would streamline multi-country dossier submissions but raise compliance costs for smaller generic entrants.
Market Dynamics
ANVISA's tightened bioequivalence standards for generic meglitinides are forcing reformulation investments and supplier consolidation across Brazil's pharmaceutical procurement chains. This regulatory pressure cascades through Mexico and Colombia as regional harmonization pressures mount.
Growth Catalysts
- Postprandial glucose targeting protocols:Diabetes care centers across Brazil's Southeast region are adopting rapid-acting secretagogues for erratic meal timing patients, expanding formulary slots beyond sulfonylurea-first protocols.
- COFEPRIS accelerated sanitary registration pathways:Mexico's streamlined dossier review for established active pharmaceutical ingredients is compressing generic entry timelines for repaglinide formulations.
- Specialty clinic density concentration:Urban diabetes centers in São Paulo and Mexico City concentrate prescriber influence, creating concentrated demand pull for differentiated glucose control therapies.
Market Restraints
- Active pharmaceutical import dependency:Latin American formulators rely on Chinese and Indian API suppliers, exposing margin structures to currency volatility and shipping cost spikes.
- Sulfonylurea substitution pressure:Low-cost glibenclamide and glimepiride dominate public sector procurement tenders across Brazil and Mexico, crowding meglitinide access in price-sensitive segments.
- ANVISA manufacturing site inspection intensity:Unannounced audits of contract manufacturing organizations are disqualifying legacy suppliers and forcing costly facility upgrades.
Strategic Opportunities
- Colombia's expanding EPS coverage:Colombia's Entidades Promotoras de Salud are broadening chronic disease formularies, creating reimbursement white space for nateglinide in hypoglycemia-sensitive patient profiles.
- Continuous glucose monitoring convergence:Integration of real-time glucose data with prandial insulin secretagogues enables precision dosing protocols in private diabetes clinics.
- Direct-to-specialist distribution models:Bypassing traditional wholesale channels through authorized distributor partnerships with endocrinology networks is compressing fulfillment cycles.
Industry Challenges
- Bioanalytical method transfer complexity:Contract research organizations struggle with cross-laboratory validation of meglitinide pharmacokinetic assays under divergent national reference standards.
- Cold chain integrity for reference products:Temperature excursions during transport of innovator comparator drugs invalidate bioequivalence studies, forcing repeat trials and timeline extensions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Meglitinide Market |
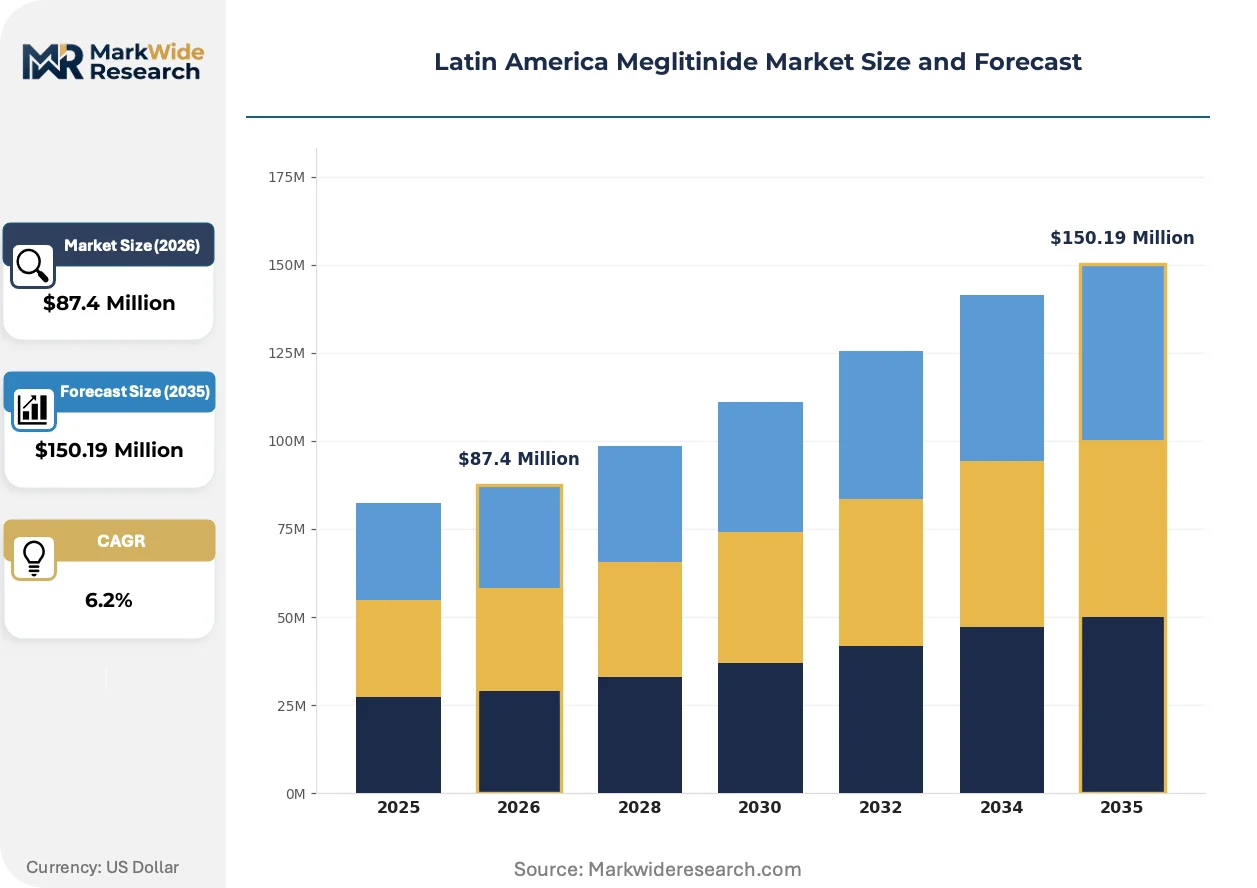
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $150.19 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Repaglinide, Nateglinide, Benfluorex, Mitiglinide, Tolimidone Therapy Area: Type 2 Diabetes, Hyperglycemia, Insulin Resistance, Beta Cell Dysfunction, Prediabetes End User: Hospitals, Outpatient Clinics, Diabetes Care Centers, Specialty Clinics, Private Clinics Distribution Channel: Pharmacies, Hospital Pharmacies, Online Pharmacies, Drugstores, Retail Chains |
| Companies Covered | Novo Nordisk, Novartis, Boehringer Ingelheim, Glenmark, Biocon, Kissei Pharmaceuticals, Sanofi, Merck & Co., Pfizer, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Meglitinide Market Shifts & Advancements
Pharmacokinetic precision tools and regulatory data requirements are fragmenting traditional procurement patterns across Latin American diabetes care. Three forces are compressing legacy commercial models while opening niche positioning opportunities.
Pharmacogenomic testing for CYP2C8 polymorphisms is fragmenting prescriber confidence in one-size-fits-all meglitinide dosing. Endocrinology networks in São Paulo and Mexico City are piloting genotype-guided repaglinide initiation protocols. This precision approach is fragmenting volume concentration away from standard-dose formulations toward customizable titration regimens.
ANVISA's updated Resolução da Diretoria Colegiada on bioequivalence study design is mandating narrower confidence intervals for generic meglitinide approvals. This tightens statistical power requirements and extends trial durations for sponsors. Brazilian generic manufacturers are responding by consolidating bioanalytical partnerships with accredited university laboratories.
Hospital formulary committees are unbundling glucose control therapy decisions from endocrinology service lines. Procurement teams in Brazil's Southeast region are establishing separate therapeutic class review boards with pharmacy-driven cost-effectiveness criteria. This behavioral shift is most visible in tertiary hospitals across Minas Gerais and Rio de Janeiro states.
Latin America Meglitinide Market Segmentation
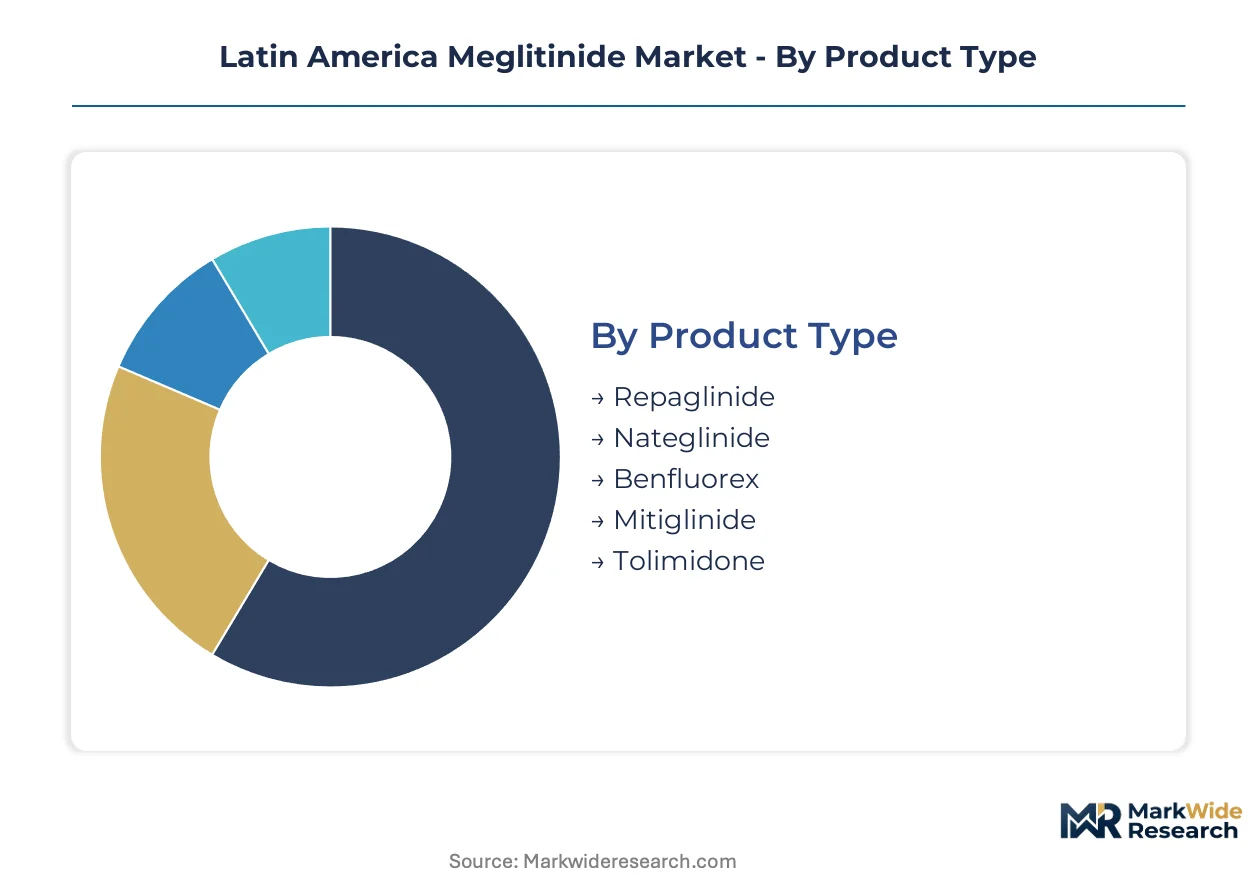
Meglitinide market dynamics fragment sharply across product chemistry, patient metabolic status, and care delivery settings. Each segmentation axis carries distinct competitive pressures from sulfonylurea substitution, reimbursement tiering, and prescriber channel influence.
Product Type:
Repaglinide faces the most intense substitution pressure from low-cost sulfonylureas in public procurement, while newer entrants battle bioequivalence hurdles and prescriber familiarity gaps.
- Repaglinide:The amino acid derivative binds pancreatic beta-cell KATP channels with rapid onset and short duration, suiting erratic meal patterns. Demand concentrates in Brazil's Southeast hospital formularies where endocrinologists retain prescribing autonomy against pharmacy cost controls.
- Nateglinide:This D-phenylalanine derivative triggers faster insulin secretion with lower hypoglycemia risk than repaglinide. Mexico City's private diabetes clinics favor nateglinide for elderly patients with cardiovascular comorbidities, though reimbursement gaps limit public sector penetration.
- Benfluorex:Serotonin and norepinephrine reuptake inhibitor properties add metabolic effects beyond glucose control.
- Mitiglinide:Shorter half-life than repaglinide enables ultra-rapid prandial dosing flexibility.
- Tolimidone:Experimental meglitinide analog with limited commercial presence in Latin American markets.
Repaglinide retains volume leadership; nateglinide holds the steepest expansion curve.
Therapy Area:
Cost tier stratification separates premium-guided therapy from commodity-managed care, with reimbursement bandwidth determining prescriber access to advanced secretagogues.
- Type 2 Diabetes:The core indication covers progressive beta-cell dysfunction requiring escalating pharmacologic intervention. Brazil's Sistema Único de Saúde concentrates volume in basic sulfonylurea protocols, while private plans in São Paulo and Rio de Janeiro enable meglitinide access for postprandial targeting.
- Hyperglycemia:Acute glucose elevation management in hospitalized settings demands rapid-acting agents with meal-flexible dosing. Colombian tertiary hospitals are expanding hyperglycemia protocols for surgical and critical care units, creating institutional demand pull.
- Insulin Resistance:Metformin-intolerant patients require alternative oral agents with complementary mechanisms.
- Beta Cell Dysfunction:Early secretagogue intervention aims to preserve residual insulin production capacity.
- Prediabetes:Preventive pharmacologic use remains off-label and reimbursement-excluded across Latin American markets.
Type 2 Diabetes dominates prescription volume; Hyperglycemia management in acute care is climbing the fastest.
End User:
Customer type fragmentation reflects Brazil and Mexico's diverging chronic disease management architectures, with specialty concentration reshaping prescriber influence patterns.
- Hospitals:Tertiary institutions in Minas Gerais and Rio de Janeiro states anchor formulary decision-making through pharmacy and therapeutics committees. ANVISA manufacturing inspections are disqualifying legacy suppliers, forcing procurement teams toward consolidated vendor relationships.
- Diabetes Care Centers:Dedicated chronic disease facilities concentrate prescriber expertise and patient volume for complex glucose management. Mexico City's expanding specialty clinic network is adopting continuous glucose monitoring integration with prandial secretagogue protocols.
- Outpatient Clinics:General practice settings face sulfonylurea-first protocol constraints in public reimbursement.
- Specialty Clinics:Endocrinology-focused practices command premium pricing power for differentiated therapies.
- Private Clinics:Cash-pay models bypass formulary restrictions but limit patient access scale.
Hospitals retain volume leadership; Diabetes Care Centers hold the steepest expansion curve.
Distribution Channel:
Supply concentration in authorized distributor networks is compressing fulfillment cycles while raising compliance costs for multi-country logistics.
- Hospital Pharmacies:Captive dispensing within integrated health systems enables formulary enforcement and protocol adherence. Brazil's Southeast regional hospital networks are consolidating procurement through centralized pharmacy distribution centers.
- Pharmacies:Independent and chain retail outlets dominate outpatient prescription fulfillment for reimbursed therapies. COFEPRIS sanitary registration pathways are accelerating generic repaglinide availability through Mexican retail pharmacy networks.
- Online Pharmacies:Digital prescription platforms face cold chain integrity requirements for temperature-sensitive formulations.
- Drugstores:Convenience-oriented retail competes on accessibility rather than clinical counseling depth.
- Retail Chains:Consolidated purchasing power drives volume discounts and generic substitution pressure.
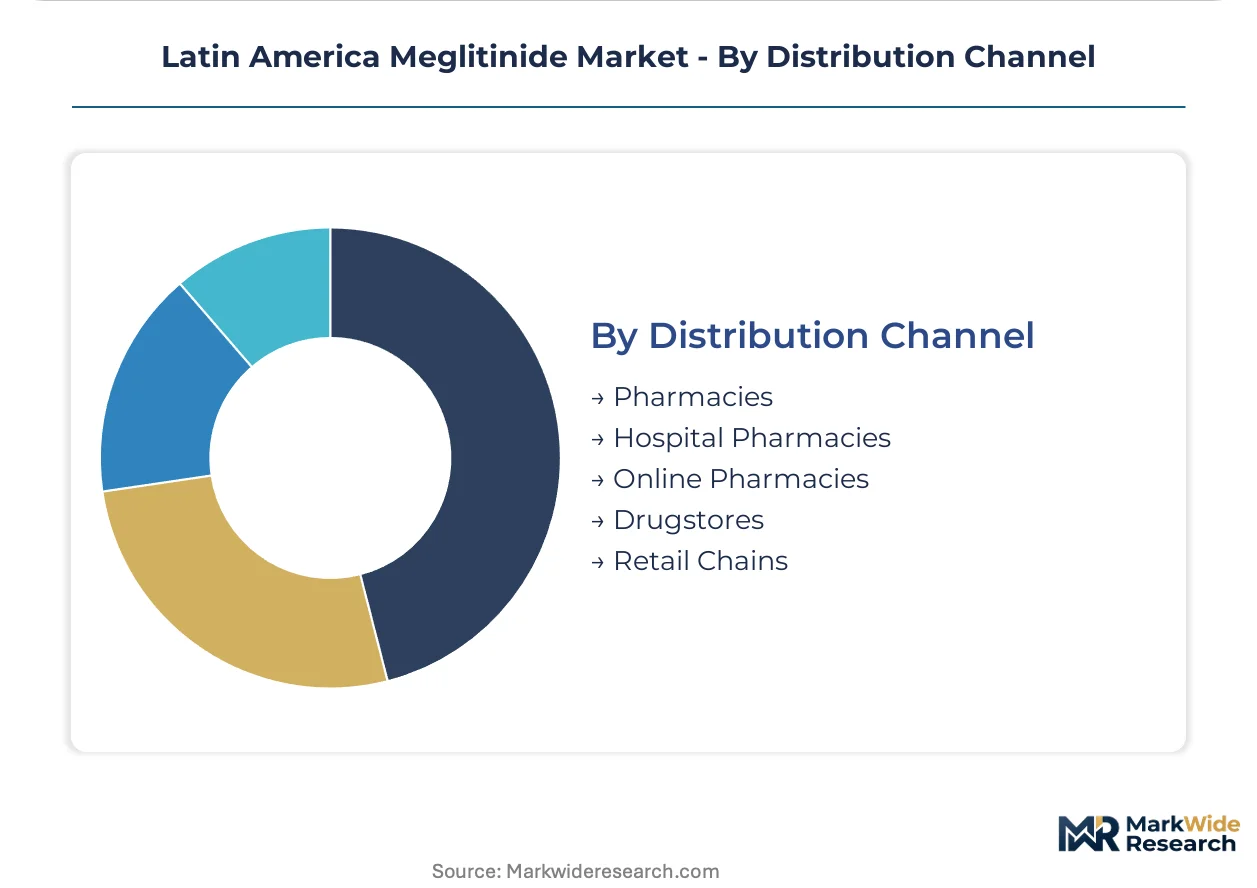
Hospital Pharmacies retain volume leadership; Online Pharmacies hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Latin America's meglitinide trade flows reveal a persistent API import dependency, with finished formulation exports trailing active pharmaceutical ingredient purchases from Asian suppliers. Currency volatility across Brazil, Mexico, and Colombia amplifies working capital pressures for regional distributors. Regulatory divergence between ANVISA and COFEPRIS compliance frameworks fragments multi-country dossier strategies.
Brazil
Southeast regional hospital networks anchor formulary decision-making for postprandial glucose therapies. ANVISA's tightened bioequivalence confidence interval requirements are extending generic repaglinide approval timelines. São Paulo's diabetes care center density concentrates prescriber influence and creates concentrated demand pull for differentiated secretagogues.
Mexico
COFEPRIS accelerated sanitary registration pathways compress generic entry timelines for established active pharmaceutical ingredients. Mexico City's private diabetes clinic network favors nateglinide for elderly cardiovascular comorbidity profiles. The Bajío Region's pharmaceutical manufacturing corridor is upgrading API sourcing documentation to meet tightened inspection protocols.
Colombia
Entidades Promotoras de Salud are broadening chronic disease formularies beyond sulfonylurea-first protocols. The national pharmaceutical regulator mandates manufacturing site inspections that disqualify legacy contract suppliers. Bogotá's tertiary hospital networks are expanding hyperglycemia management protocols for surgical and critical care units.
Argentina
Import substitution policies favor domestic formulation of diabetes therapies despite API dependency on Indian and Chinese suppliers. ANMAT bioequivalence requirements align partially with Mercosur harmonization pressures. Buenos Aires province concentrates endocrinology specialty capacity and private insurance reimbursement bandwidth for premium glucose control options.
Chile
ISAPRE private health plans enable faster formulary access for differentiated diabetes therapies than public FONASA procurement channels. The national pharmaceutical regulator enforces cold chain integrity standards that complicate bioequivalence study logistics. Santiago's hospital pharmacy consolidation is shifting procurement toward centralized therapeutic class review boards.
Latin America Meglitinide Market Competitive Landscape
Concentration sits with multinational diabetes franchise holders and aggressive generic penetrators competing across distinct reimbursement tiers. The market structure fragments between hospital formulary gatekeepers and outpatient clinic volume chasers. Two strategic archetypes dominate: insulin co-therapy portfolio integrators and API-to-formulation cost optimizers. Competitive moves center on bioanalytical partnership consolidation and direct-to-specialist distribution channel compression.
Among multinational diabetes franchise holders, Novo Nordisk and Sanofi occupy positions anchored by insulin portfolio bundling and endocrinologist relationship depth. Glenmark exemplifies the generic penetrator archetype, competing through cost-optimized repaglinide availability across outpatient channels. These three represent the competitive tension between premium formulary positioning and volume-driven substitution pressure.
| Leading Market Players |
|---|
| Novo Nordisk |
| Novartis |
| Boehringer Ingelheim |
| Glenmark |
| Biocon |
| Kissei Pharmaceuticals |
| Sanofi |
| Merck & Co. |
| Pfizer |
| Others |
Supply & Pricing Matrix
ANVISA's tightened bioequivalence confidence interval requirements gate both supplier qualification and price differentiation simultaneously, forcing Brazilian generic manufacturers toward consolidated bioanalytical partnerships that concentrate cost structures while fragmenting competitive entry timelines.
Pricing Analysis
Hospital pharmacy buyers anchor contract-based long-term offtake structures across Brazil's Southeast regional networks. Pricing stratifies across premium nateglinide for hypoglycemia-sensitive profiles, standard repaglinide for formulary-autonomous endocrinologists, and economy-tier sulfonylurea substitution in public procurement. Cost compression in the economy tier is intensifying because COFEPRIS accelerated registration pathways compress generic repaglinide margins. Public sector procurement teams exhibit highest price sensitivity; private diabetes care centers retain lowest sensitivity due to reimbursement bandwidth for differentiated glucose control.
Supply Chain Analysis
India and China anchor active pharmaceutical ingredient production for Latin American meglitinide formulators. Brazilian and Mexican finished dose manufacturers draw from Chinese KATP channel agonist intermediates and Indian repaglinide API suppliers. Single-source vulnerability concentrates in legacy contract manufacturing organizations facing ANVISA disqualification. Distribution runs through authorized distributor partnerships with endocrinology networks, compressing fulfillment cycles while raising cold chain compliance costs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin American diabetes care is approaching a platform-economics inflection as continuous glucose monitoring integration with prandial secretagogue protocols creates interoperability-dependent prescribing ecosystems.
For Market Incumbents: Secure formulary bundling through insulin co-therapy portfolio anchoring against Glenmark's aggressive generic repaglinide penetration. Consolidate bioanalytical partnerships with accredited university laboratories to preempt ANVISA manufacturing site inspection disqualification. Vertical integration into API sourcing documentation mitigates tariff exposure from Indian and Chinese supplier dependencies.
For New Entrants and Emerging Players: Lead with nateglinide positioning in Colombia's expanding EPS coverage for hypoglycemia-sensitive elderly cardiovascular comorbidity profiles. Target direct-to-specialist distribution models bypassing traditional wholesale channels in Mexico City's private diabetes clinic network. Pharmacogenomic testing partnerships for CYP2C8 genotype-guided dosing protocols offer differentiated go-to-market anchoring.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Brazilian generic manufacturers facing bioequivalence study timeline extensions. Long-term viability hinges on regulatory compliance infrastructure rather than volume scale across the analysis window. Watch ANVISA-COFEPRIS harmonization progress as inflection indicator for multi-country dossier submission economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Bioanalytical Partnership Consolidation | ANVISA's narrowed confidence intervals force validated assay transfer to accredited university laboratories. |
| Direct-to-Specialist Distribution | Authorized distributor partnerships with endocrinology networks compress fulfillment cycles in São Paulo. |
| Continuous Glucose Monitoring Integration | Real-time glucose data convergence enables precision dosing protocols in Mexico City private clinics. |
| API Sourcing Documentation Upgrade | Bajío Region manufacturers strengthen supplier qualification to meet tightened COFEPRIS inspection protocols. |
| Pharmacogenomic Testing Partnership | CYP2C8 genotype-guided repaglinide initiation fragments volume toward customizable titration regimens. |
Research Methodology
Operator-level perspectives from formulary directors at Brazil's Southeast hospital networks, COFEPRIS regulatory affairs leads, Mexican diabetes care center procurement managers, and Colombian EPS pharmacy directors anchored the qualitative base. Secondary validation drew from ANVISA Resolução da Diretoria Colegiada filings, COFEPRIS sanitary registration databases, ClinicalTrials.gov pharmacokinetic study records, and regional hospital procurement contract disclosures. Bottom-up prescription volume modeling and top-down therapeutic class expenditure analysis enabled triangulation across the Latin American meglitinide landscape.
Sensitivity analysis framed the quantitative architecture across the projection horizon. Segmentation dimensions modeled included product chemistry, therapy area progression stage, end-user facility type, and distribution channel concentration. CAGRs derived from annualized prescription growth trajectories calibrated against reimbursement bandwidth expansion and regulatory approval timeline compression. Industry-specific inputs incorporated ANVISA bioequivalence study completion rates and COFEPRIS accelerated pathway utilization patterns.
The analysis sits within stated boundaries; outcomes outside sustained ANVISA-COFEPRIS regulatory divergence or API import tariff stability would require recalibration. Forecasts reflect documented assumptions regarding diabetes prevalence trajectories, specialty clinic density expansion, and sulfonylurea substitution elasticity in public procurement. Recalibration cycles align with material shifts in pharmacovigilance protocol harmonization and continuous glucose monitoring reimbursement policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Mitochondrial-Based Therapeutics Market
Pharmaceuticals
Europe Oral Anti-Diabetic Drug Market
Pharmaceuticals
Bipolar Disorder Drugs and Treatment Market
Pharmaceuticals
US Pharmaceutical Warehousing Market
Pharmaceuticals
Oxycodone Market
Pharmaceuticals
Global Chemotherapy-Induced Neutropenia (CIN) Treatment Market
Pharmaceuticals
Europe Generic Drug Market
Pharmaceuticals
Global Dengue Vaccine Market
Pharmaceuticals
US Intravenous Immunoglobulin Market
Pharmaceuticals
Adamantane Antiviral Drugs Market
Pharmaceuticals
Atorvastatin Diepoxide Calcium Salt Market
Pharmaceuticals
Adrenocorticotropic Hormone [ACTH] Market
Pharmaceuticals
Global Antacids Market
Pharmaceuticals
Acne Drugs Market
Pharmaceuticals
Topical Acne Medication Market
Pharmaceuticals
Global Immuno Oncology Drugs Market