
 Asia-Pacific Sodium-Dependent Glucose Cotransporter 2 (SGLT-2) Market | 2026-2036
Asia-Pacific Sodium-Dependent Glucose Cotransporter 2 (SGLT-2) Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Sodium-Dependent Glucose Cotransporter 2 (SGLT-2) Market Outlook
Chronic kidney disease therapy revenue is reconfiguring competitive priorities across the Asia-Pacific SGLT-2 landscape. AstraZeneca leverages its dapagliflozin cardiovascular outcomes data to anchor hospital formulary positions in Japan and South Korea. Boehringer Ingelheim sustains empagliflozin manufacturing scale through its partnership network across Southeast Asian markets. Novo Nordisk competes by extending its GLP-1 crossover expertise into SGLT-2 combination therapy development.
Sodium-dependent glucose cotransporter 2 inhibitors are a class of oral antihyperglycemic agents that block glucose reabsorption in the proximal renal tubule by inhibiting SGLT-2 protein activity, producing glucosuria and reducing plasma glucose without insulin dependency. Their primary commercial purpose spans type 2 diabetes management, heart failure risk reduction, and renal function preservation in diabetic populations. Empagliflozin and dapagliflozin dominate prescription volumes across the therapy area dimension, while cardiovascular health applications represent the fastest-expanding indication segment as clinicians integrate cardiorenal protective protocols. Diabetes management retains the largest revenue pool, though chronic kidney disease positioning is capturing disproportionate R&D investment from manufacturers seeking differentiated labeling.
Japan's PMDA, China's NMPA, and India's CDSCO govern SGLT-2 approval standards, pharmacovigilance requirements, and pricing negotiations across the region. PMDA's stringent cardiovascular outcomes documentation shapes clinical trial investment patterns, while NMPA's national reimbursement list revisions directly determine patient access in China's public hospital system. CDSCO's accelerated approval pathways for chronic disease therapies are compressing launch timelines for multinational manufacturers. Stakeholders must monitor evolving cardiorenal outcome trial data and reimbursement negotiation precedents across Tokyo, Shanghai, and Mumbai to anticipate which indications will unlock premium pricing in the next cycle.
Market Dynamics
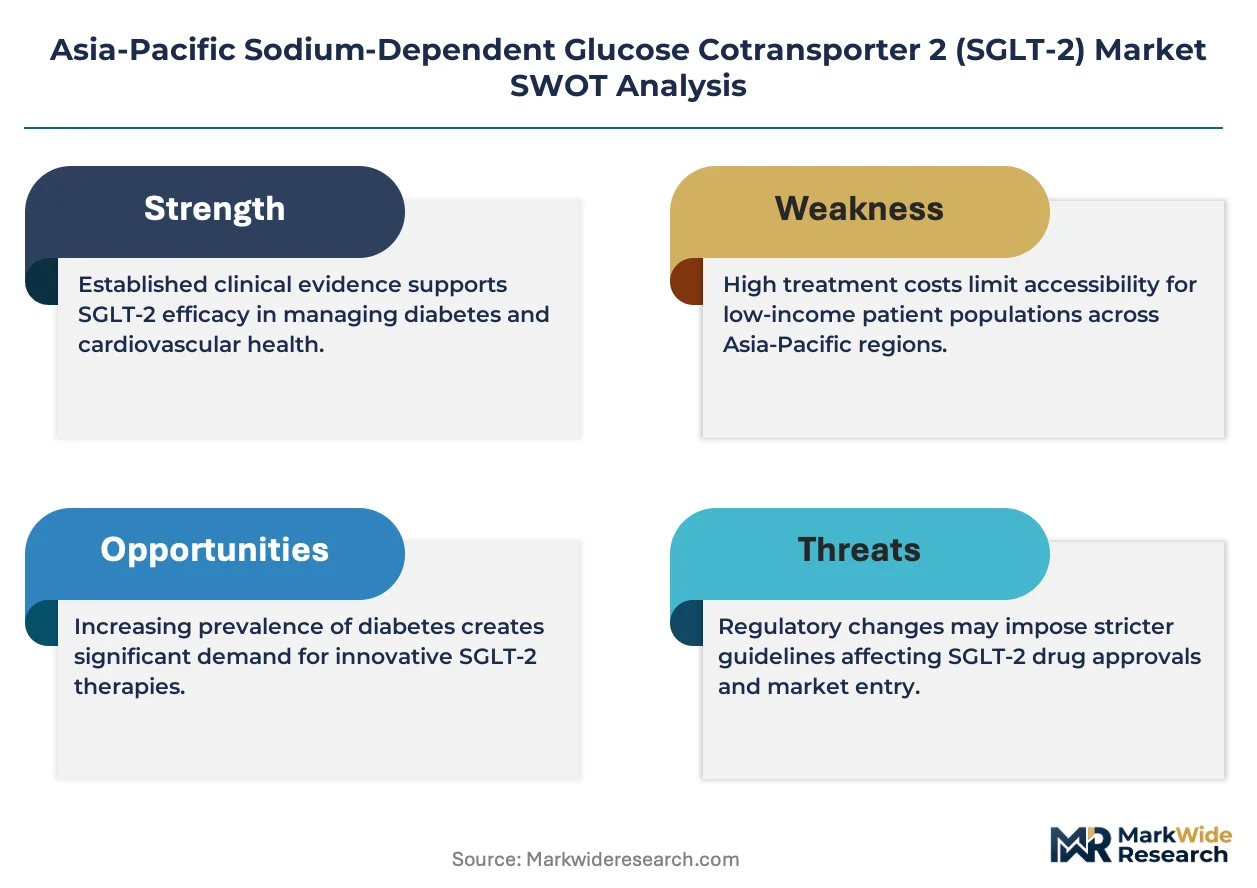
Cardiorenal outcome trial data from PMDA-mandated studies is restructuring prescriber hierarchies across Asia-Pacific hospital formularies. Manufacturers now anchor commercial strategy on cardiovascular labeling rather than glycemic endpoints alone.
Growth Catalysts
- CDSCO Accelerated Approval Pathways:India's streamlined chronic disease review compresses launch timelines for multinational SGLT-2 entrants seeking tier-1 city hospital access.
- Cardiovascular Outcome Integration:Japanese cardiology departments are embedding SGLT-2 inhibitors into heart failure protocols, expanding the prescriber base beyond endocrinology.
- NMPA National Reimbursement List Revisions:China's public hospital procurement reforms are elevating cardiorenal-protective agents to tier-A formulary status in Shanghai and Beijing networks.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Over 70% of empagliflozin API originates from Zhejiang and Jiangsu province manufacturers, creating supply vulnerability.
- PMDA Cardiovascular Outcomes Documentation Burden:Japan's requirement for extensive MACE data extends clinical trial durations and inflates development costs for new entrants.
- GLP-1 Receptor Agonist Substitution:Semaglutide and liraglutide formulations are capturing glycemic control market share among insulin-naive patients in South Korean outpatient settings.
Strategic Opportunities
- Chronic Kidney Disease Labeling Expansion:NMPA's evolving nephrology reimbursement codes create white space for SGLT-2 positioning independent of diabetes diagnosis.
- Fixed-Dose Combination Formulations:Convergence with DPP-4 inhibitors and metformin is enabling portfolio differentiation in India's metropolitan hospital procurement tenders.
- Southeast Asian Pharmacy Channel Penetration:Vietnam and Indonesia's retail pharmacy networks remain underpenetrated for cardiorenal therapeutic categories.
Industry Challenges
- Pharmacovigilance Infrastructure Scaling:Post-market safety monitoring for rare ketoacidosis events requires investment in patient registries across fragmented Asia-Pacific healthcare systems.
- Cross-Border Data Harmonization:Reconciling PMDA, NMPA, and CDSCO cardiovascular outcome datasets complicates regional label expansion strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Sodium-Dependent Glucose Cotransporter 2 (SGLT-2) Market |
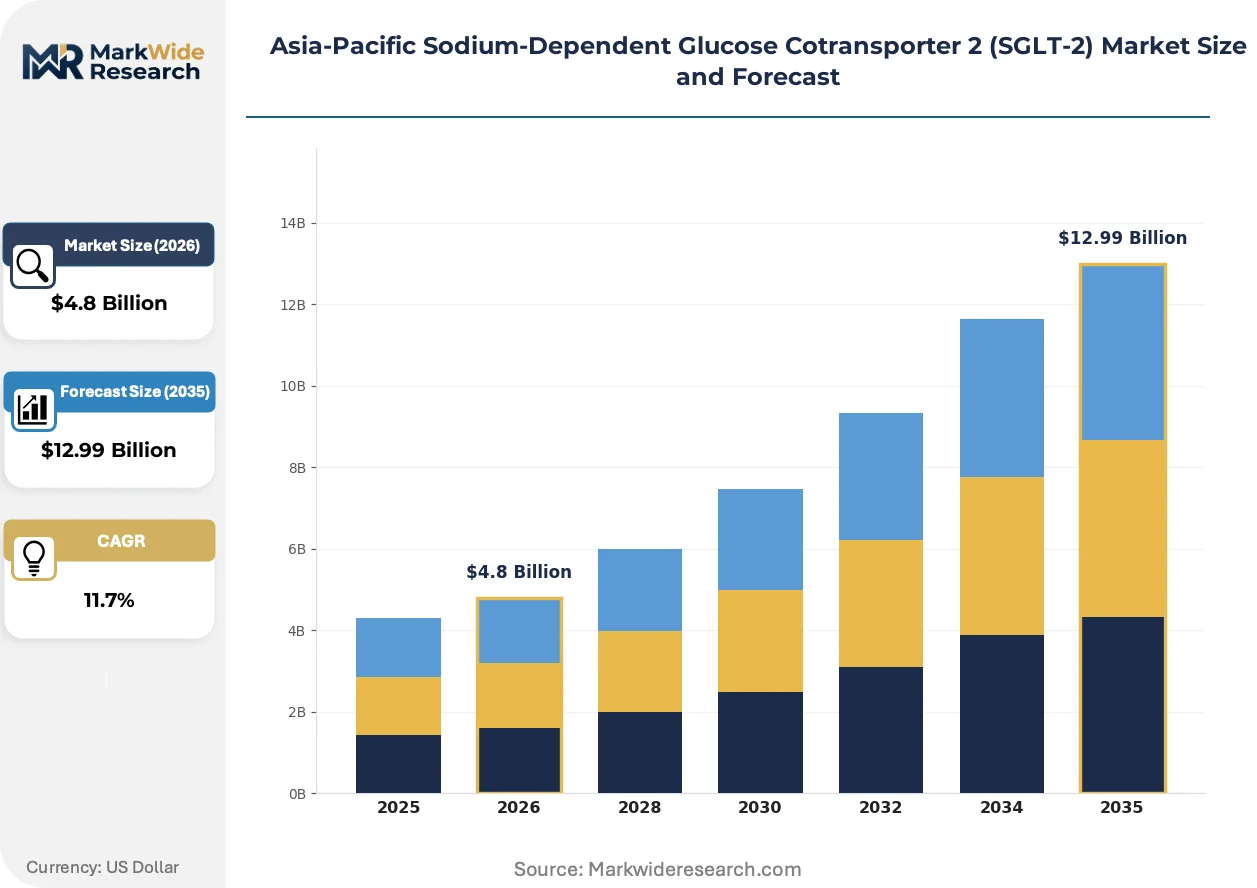
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Empagliflozin, Dapagliflozin, Canagliflozin, Ertugliflozin Therapy Area: Diabetes Management, Cardiovascular Health, Weight Management, Chronic Kidney Disease End User: Hospitals, Clinics, Home Care, Pharmacies Distribution Channel: Direct Sales, Online Pharmacy, Retail Pharmacy, Wholesalers |
| Companies Covered | Eli Lilly and Company, Boehringer Ingelheim, AstraZeneca, Johnson & Johnson Services, Inc., Bristol-Myers Squibb, Novo Nordisk, Merck & Co., Inc., Glenmark Pharmaceuticals, Lexicon Pharmaceuticals, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Sodium-Dependent Glucose Cotransporter 2 (SGLT-2) Market Strategic Shifts
Cardiorenal protective protocols are displacing glycemic-centric prescribing algorithms across Asia-Pacific academic medical centers. This shift is compressing the commercial relevance of legacy diabetes-only indications.
Oral fixed-dose combinations pairing SGLT-2 inhibitors with DPP-4 antagonists are migrating from specialty hospital dispensing to primary care clinic formularies in Japan and South Korea. General practitioners in Osaka and Busan are adopting these formulations for polypharmacy reduction. The technology is migrating from endocrinology subspecialty control toward broader cardiometabolic management.
NMPA's 2023 cardiovascular outcomes data requirements for new diabetes therapies are forcing manufacturers to design Asia-specific trial architectures. The regulation mandates MACE endpoint inclusion for premium reimbursement tier eligibility. Domestic Chinese innovators and multinational subsidiaries are restructuring clinical development budgets to accommodate these evidentiary standards.
Hospital procurement committees in tier-1 Chinese cities are unbundling device-diagnostic-pharmaceutical bundles that previously favored insulin delivery systems. Standalone SGLT-2 contracts are displacing integrated diabetes management packages in Shanghai and Shenzhen tender processes. This pattern is most visible in public hospital networks where NMPA pricing negotiations determine formulary placement.
Asia-Pacific Sodium-Dependent Glucose Cotransporter 2 (SGLT-2) Market Segmentation
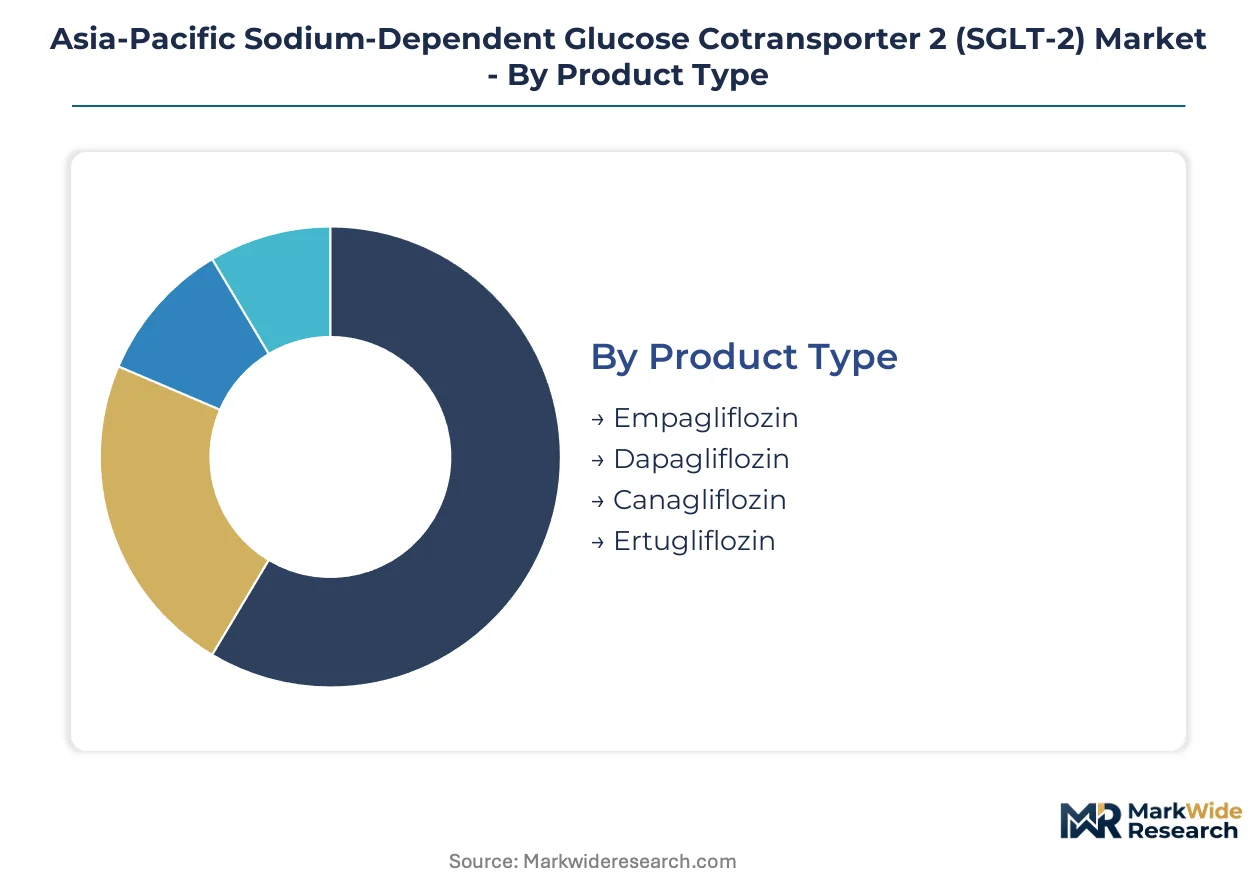
SGLT-2 inhibitor commercialization strategies diverge sharply across molecular formulations, therapeutic positioning, and procurement channels. Manufacturers must align portfolio investments with the cardiorenal pivot reshaping hospital formulary hierarchies across Asia-Pacific markets.
Product Type:
Mature molecules anchor volume while newer entrants compete on differentiated labeling profiles.
- Empagliflozin:This sodium-glucose cotransporter inhibitor demonstrates established cardiovascular outcomes data from EMPA-REG trials, securing tier-A formulary placement in Japanese cardiology departments. Boehringer Ingelheim's manufacturing partnerships across Southeast Asia sustain supply security for hospital procurement networks in Bangkok and Jakarta.
- Dapagliflozin:AstraZeneca's DAPA-HF and DAPA-CKD datasets have restructured prescriber hierarchies beyond endocrinology into nephrology and cardiology subspecialties. PMDA's recognition of heart failure indications positions this molecule for premium reimbursement in Tokyo and Osaka academic medical centers.
- Canagliflozin:Janssen's molecule carries established renal protective labeling though safety monitoring requirements for amputation risk shape prescribing caution in Australian and South Korean outpatient settings.
- Ertugliflozin:Merck's newer entrant competes through fixed-dose combination availability with sitagliptin, targeting polypharmacy reduction in Indian metropolitan diabetes clinics.
Empagliflozin retains volume leadership; dapagliflozin holds the steepest expansion curve.
Therapy Area:
Clinical application breadth determines pricing tier access and R&D investment allocation.
- Diabetes Management:Glycemic control remains the foundational indication with established reimbursement pathways across NMPA national lists and CDSCO procurement frameworks. Hospital diabetes management programs in Shanghai and Mumbai drive sustained prescription volumes.
- Cardiovascular Health:Heart failure risk reduction represents the fastest-expanding application segment as Japanese cardiology societies embed SGLT-2 inhibitors into chronic HFrEF protocols independent of diabetes status.
- Weight Management:Adjunct obesity positioning captures off-label utilization in South Korean aesthetic medicine clinics though regulatory labeling lags behind GLP-1 agonist dominance.
- Chronic Kidney Disease:Nephrology-directed prescribing is climbing the fastest as albuminuria reduction data from CREDENCE and DAPA-CKD trials reshape dialysis prevention protocols in Australian and Singaporean renal networks.
Diabetes management retains volume leadership; chronic kidney disease holds the steepest expansion curve.
End User:
Care setting determines prescription authority and procurement mechanism complexity.
- Hospitals:Academic medical centers in Beijing, Tokyo, and Seoul anchor cardiovascular outcome trial adoption and formulary committee decisions for cardiorenal protective protocols.
- Clinics:Endocrinology and cardiology specialty practices in tier-1 Chinese cities and Indian metros manage dose titration and combination therapy transitions.
- Home Care:Long-term diabetes management for stable patients concentrates in Japanese and Australian community nursing networks with remote monitoring integration.
- Pharmacies:Retail dispensing in Vietnam and Indonesia remains underdeveloped for SGLT-2 categories compared to insulin and oral hypoglycemic legacy markets.
Hospitals retain volume leadership; home care holds the steepest expansion curve.
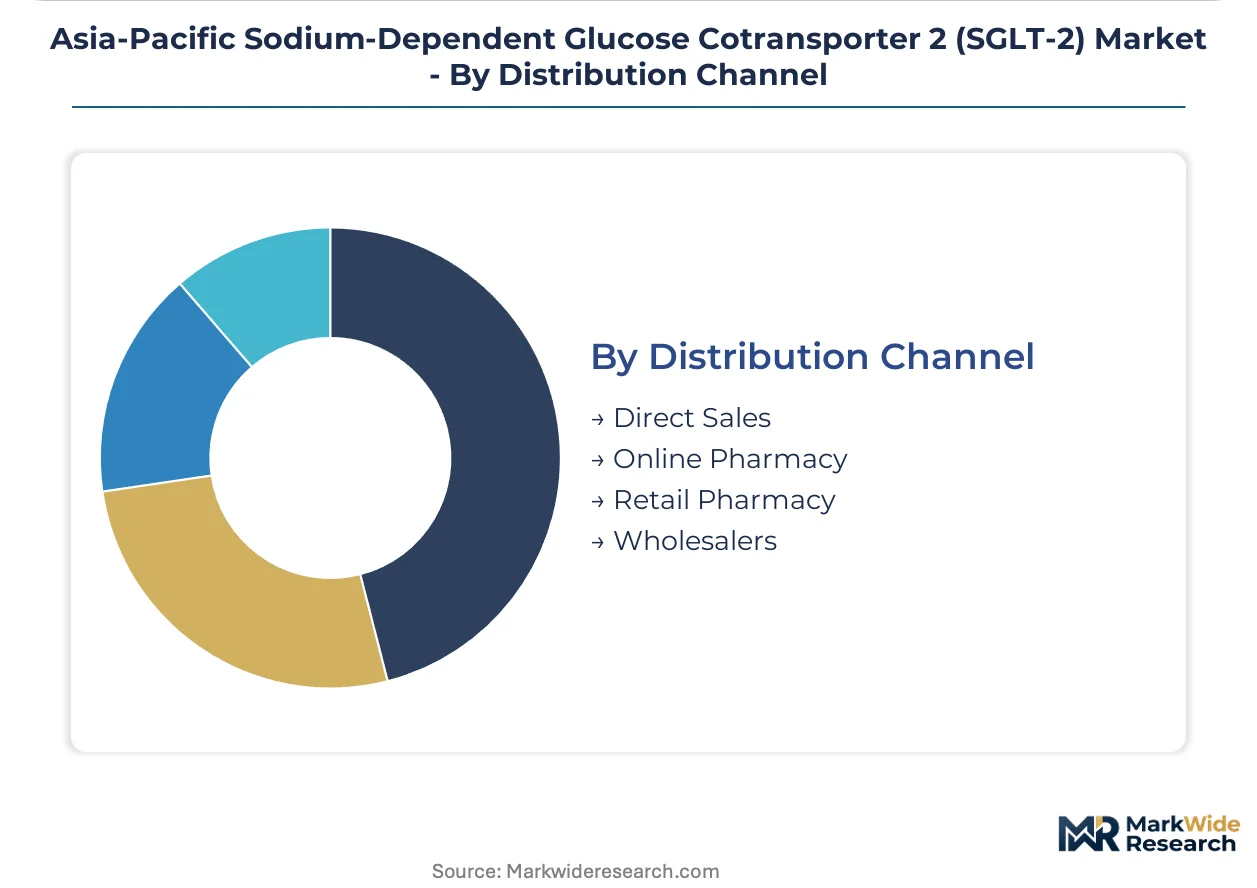
Distribution Channel:
Channel structure reflects regulatory control intensity and patient out-of-pocket exposure.
- Direct Sales:Manufacturer-to-hospital contracts dominate public procurement in China's tier-1 city networks where NMPA pricing negotiations determine formulary access.
- Online Pharmacy:E-commerce penetration for chronic disease medications is climbing the fastest in South Korean and Australian markets with established telemedicine prescription workflows.
- Retail Pharmacy:Community dispensing networks in Japan and Thailand handle stable patient refills though cardiorenal protocols favor hospital-based initiation.
- Wholesalers:Regional distributors manage inventory pooling across Southeast Asian markets with fragmented regulatory harmonization between Vietnam, Indonesia, and Philippines.
Direct sales retain volume leadership; online pharmacy holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across the Asia-Pacific SGLT-2 market diverge sharply by clinical setting and reimbursement structure. Japanese cardiologists prescribe for heart failure independent of diabetes status, while Chinese hospital formularies remain tethered to glycemic endpoints. Indian metropolitan centers blend both approaches through tiered procurement systems.
China
Shanghai and Beijing public hospital networks drive volume through NMPA tier-A formulary placements for cardiorenal indications. The national reimbursement list revision process elevates agents with cardiovascular outcome data to premium procurement tiers. Zhejiang and Jiangsu provinces anchor API manufacturing concentration, creating supply chain leverage for domestic producers.
Japan
Tokyo and Osaka academic medical centers embed SGLT-2 inhibitors into chronic HFrEF protocols through PMDA-recognized heart failure labeling. Cardiology departments now outpace endocrinology in prescription growth for this therapeutic class. PMDA's stringent MACE documentation requirements extend clinical trial timelines for new market entrants.
India
Mumbai and Delhi hospital networks expand diabetes management programs through CDSCO accelerated approval pathways for chronic disease therapies. Tier-1 city procurement committees prioritize fixed-dose combinations to reduce polypharmacy burdens. Maharashtra and Gujarat pharmaceutical clusters manufacture generic formulations for Southeast Asian export markets.
South Korea
Seoul cardiology practices integrate SGLT-2 inhibitors into renal protective protocols alongside GLP-1 receptor agonist competition. MFDS reimbursement negotiations favor agents with nephrology labeling for dialysis prevention. Busan specialty clinics drive combination therapy adoption for metabolic syndrome management.
Australia
Sydney and Melbourne renal networks prioritize albuminuria reduction data from CREDENCE and DAPA-CKD trials in dialysis prevention protocols. TGA pharmacovigilance requirements shape post-market safety monitoring for rare ketoacidosis events. Private hospital formularies lead cardiovascular indication adoption ahead of public system reimbursement.
Asia-Pacific Sodium-Dependent Glucose Cotransporter 2 (SGLT-2) Market Competitive Environment
Capability concentration sits with multinational innovators possessing cardiovascular outcome datasets; scale advantage sits with established manufacturing networks across Southeast Asia. The market structures around three tiers: originators with cardiorenal labeling, regional licensees with hospital procurement relationships, and domestic API-to-formulation integrators. Competitive moves center on fixed-dose combination development and nephrology indication expansion.
Among originator-tier pharmaceutical companies, AstraZeneca, Boehringer Ingelheim, and Eli Lilly occupy positions defined by cardiovascular trial data assets. AstraZeneca exemplifies the cardiorenal pivot through DAPA-HF and DAPA-CKD dataset leverage. Boehringer Ingelheim represents manufacturing scale sustainability through Southeast Asian partnership networks. Eli Lilly sits within the metabolic therapy convergence space bridging SGLT-2 and incretin pathway expertise.
| Leading Market Players |
|---|
| Eli Lilly and Company |
| Boehringer Ingelheim |
| AstraZeneca |
| Johnson & Johnson Services, Inc. |
| Bristol-Myers Squibb |
| Novo Nordisk |
| Merck & Co., Inc. |
| Glenmark Pharmaceuticals |
| Lexicon Pharmaceuticals |
| Others |
Value Chain & Pricing Dynamics
Zhejiang and Jiangsu province API clusters anchor empagliflozin production capacity, concentrating upstream leverage among domestic Chinese manufacturers and compressing margin structures for formulation-stage competitors across Asia-Pacific hospital procurement networks.
Pricing Analysis
Long-term offtake contracts between Boehringer Ingelheim and Southeast Asian manufacturing partners dominate volume allocation, while spot purchasing serves tier-2 Indian hospital networks facing irregular demand. Price differentiation rests on cardiovascular outcome certification tier and geographic delivery cost to Tokyo versus Jakarta. Cost compression in standard-grade formulations is intensifying because NMPA procurement reforms favor cardiorenal-labeled agents. Public hospital systems in Beijing and Shanghai exhibit lowest price sensitivity; Indonesian retail pharmacies show highest.
Supply Chain Analysis
Contract-manufacturing concentration sits with Boehringer Ingelheim's partnership network across Thailand and Malaysia, supplemented by AstraZeneca's direct production facilities in China. Active pharmaceutical ingredient supply draws from Zhejiang and Jiangsu provinces in China, with secondary sourcing from Maharashtra and Gujarat clusters in India. Single-source vulnerability concentrates in empagliflozin precursor chemicals. Distribution runs through manufacturer-to-hospital direct contracts in China's tier-1 cities, with wholesaler pooling across fragmented Southeast Asian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: PMDA, NMPA, and CDSCO cardiovascular outcome documentation requirements create decade-long switching costs for hospital formulary positioning.
For Market Incumbents: Pre-empt GLP-1 substitution threat by accelerating fixed-dose combination development with DPP-4 inhibitors for Indian metropolitan procurement tenders. Deepen backward integration into Zhejiang API supply through captive manufacturing partnerships. Secure nephrology labeling expansion ahead of NMPA reimbursement code revisions.
For New Entrants and Emerging Players: Build out chronic kidney disease positioning independent of diabetes diagnosis, exploiting white space in Australian and Singaporean renal networks where albuminuria reduction protocols remain underpenetrated. Target Vietnam and Indonesia retail pharmacy channels with cardiorenal therapeutic categories. Lead with telemedicine-integrated prescription workflows for South Korean outpatient settings.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because cardiovascular outcome datasets function as irreproducible intangible assets with hospital formulary lock-in. Acquisition target archetype: regional licensees possessing CDSCO accelerated approval track records and established Mumbai-Delhi hospital procurement relationships. Monitor PMDA heart failure labeling expansion decisions as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Cardiovascular Outcome Trial Advancement | PMDA-recognized MACE data secures tier-A formulary placement in Tokyo academic medical centers. |
| Fixed-Dose Combination Development | Pairing SGLT-2 inhibitors with DPP-4 antagonists reduces polypharmacy burdens in Osaka primary care clinics. |
| Chronic Kidney Disease Labeling Expansion | NMPA nephrology reimbursement codes unlock premium pricing independent of diabetes diagnosis. |
| API Manufacturing Scale-Up | Zhejiang and Jiangsu province capacity additions address supply vulnerability for empagliflozin production. |
| Hospital System Partnership | Direct contracts with Shanghai public hospital networks bypass wholesaler margins in NMPA procurement. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers across Tokyo, Shanghai, and Mumbai; and secondary validation through PMDA filings, NMPA submissions, ClinicalTrials.gov records, and hospital formulary databases. Bottom-up prescription volume modeling and top-down reimbursement expenditure analysis were triangulated against manufacturer-reported regional sales disclosures.
Forecast inputs considered therapy area segmentation across diabetes management, cardiovascular health, and chronic kidney disease; molecular formulation tiers; and end-user channel dynamics. CAGRs were derived from patient population epidemiology, label expansion timelines, and procurement reform implementation schedules across the projection horizon. Modeled variables included NMPA national reimbursement list revision frequency, PMDA cardiovascular outcomes documentation burden, and CDSCO accelerated approval pathway utilization rates.
Stress conditions across API supply concentration, GLP-1 substitution velocity, and cardiorenal protocol adoption curves were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory harmonization progress and hospital procurement committee composition shifts. Quarterly review of PMDA heart failure labeling decisions, NMPA tier-A formulary placements, and CDSCO chronic disease approval timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Loxoprofen Market
Pharmaceuticals
Italy Pharmaceutical Market
Pharmaceuticals
Generic Pharmaceuticals Contract Manufacturing Market
Pharmaceuticals
Global Liposome Drug Delivery Market
Pharmaceuticals
Global Doxorubicin Market
Pharmaceuticals
Global Oxytocic Pharmaceuticals Market
Pharmaceuticals
Acetylcholine Market
Pharmaceuticals
Chloramphenicol Eye Drops Market
Pharmaceuticals
Wujibaifeng Pills Market
Pharmaceuticals
Global Oxytocin Market
Pharmaceuticals
Critical Care Drugs Market
Pharmaceuticals
Ophthalmic Drugs Market
Pharmaceuticals
Global Diphenhydramine Market
Pharmaceuticals
Croatia Pharmaceutical Market
Pharmaceuticals
Stomach Cancer Drugs Market
Pharmaceuticals
Radioligand Therapy (RLT) Market