
 Global Myeloproliferative Disorders (MPD) Treatment Market | 2026-2036
Global Myeloproliferative Disorders (MPD) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Myeloproliferative Disorders (MPD) Treatment Market Foresight
Next-generation pegylated interferon formulations are repositioning cytoreductive therapy economics in polycythemia vera by extending dosing intervals and reducing injection-site toxicity. Novartis leverages its JAK inhibitor franchise to sustain leadership across myelofibrosis and polycythemia vera indications. Bristol-Myers Squibb anchors its competitive position through deep R&D investment in immuno-oncology combinations for myeloproliferative neoplasms. Incyte Corporation dominates the ruxolitinib landscape with manufacturing scale that controls global supply security for oral JAK therapy.
Myeloproliferative disorders treatment encompasses pharmacological interventions targeting clonal hematopoietic stem cell malignancies characterized by elevated blood cell counts, splenomegaly, and thrombohemorrhagic complications, with therapeutic goals centered on symptom burden reduction, thrombosis prevention, and disease modification. JAK inhibitors command the largest revenue share among product types due to their established efficacy in splenic response and symptom control, while interferons represent the fastest-expanding category as pegylated formulations gain traction in younger, treatment-naïve patients. Among therapy areas, primary myelofibrosis generates the deepest margin pools owing to limited curative options and chronic treatment duration, whereas polycythemia vera offers the broadest addressable patient base.
The FDA, EMA, and Japan's PMDA each enforce distinct evidentiary standards for MPD therapy approval, with the FDA's Breakthrough Therapy designation and EMA's PRIME scheme creating divergent market access timelines that shape regional launch sequencing. The EU's MDR and GDPR impose additional compliance layers on companion diagnostics and patient registry data collection, respectively. Stakeholders must monitor evolving regulatory divergence between accelerated approval pathways and confirmatory trial requirements to optimize portfolio allocation across the JAK inhibitor and interferon development pipelines.
Market Dynamics
FDA's accelerated approval pathways for oncology therapies are compressing development timelines for novel JAK inhibitors while hematology clinics expand specialized myelofibrosis care capacity across multiple markets.
Growth Catalysts
- Pegylated interferon formulations:Extended dosing intervals and reduced injection-site toxicity are repositioning cytoreductive therapy economics in polycythemia vera, attracting younger treatment-naïve patient cohorts.
- Japan's PMDA regulatory framework:Streamlined review processes for orphan oncology indications are shortening market access timelines for myelofibrosis therapies in East Asian markets.
- Hematology clinic networks:Specialized myeloproliferative neoplasm care centers in the United States, Germany, and Japan are concentrating diagnosis capacity and driving referral volume for advanced therapies.
Market Restraints
- Active pharmaceutical ingredient concentration:Limited global manufacturing sites for JAK inhibitor raw materials create supply vulnerability and procurement bottlenecks for oral therapy production.
- EU MDR compliance burden:Companion diagnostics for MPD subtyping face extended conformity assessment timelines and elevated documentation requirements for CE marking.
- Allogeneic stem cell transplant availability:Curative option scarcity for high-risk myelofibrosis patients limits treatment escalation pathways and compresses addressable populations for chronic pharmacotherapy.
Strategic Opportunities
- Underpenetrated polycythemia vera markets:Cytoreductive therapy adoption gaps in India and Brazil present volume expansion potential for interferon-based regimens.
- Immuno-oncology convergence:Combination protocols integrating JAK inhibition with checkpoint blockade are opening new development avenues in myelofibrosis disease modification.
- Patient registry data monetization:GDPR-compliant real-world evidence platforms in Germany and the United Kingdom are enabling outcomes-based contracting models with payers.
Industry Challenges
- Specialized hematopathology workforce scarcity:Diagnostic expertise gaps in bone marrow morphology and molecular profiling are delaying accurate MPD subtyping and treatment initiation.
- Confirmatory trial execution complexity:FDA's accelerated approval requirements mandate post-market survival studies that strain sponsor resources and extend regulatory risk exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Myeloproliferative Disorders (MPD) Treatment Market |
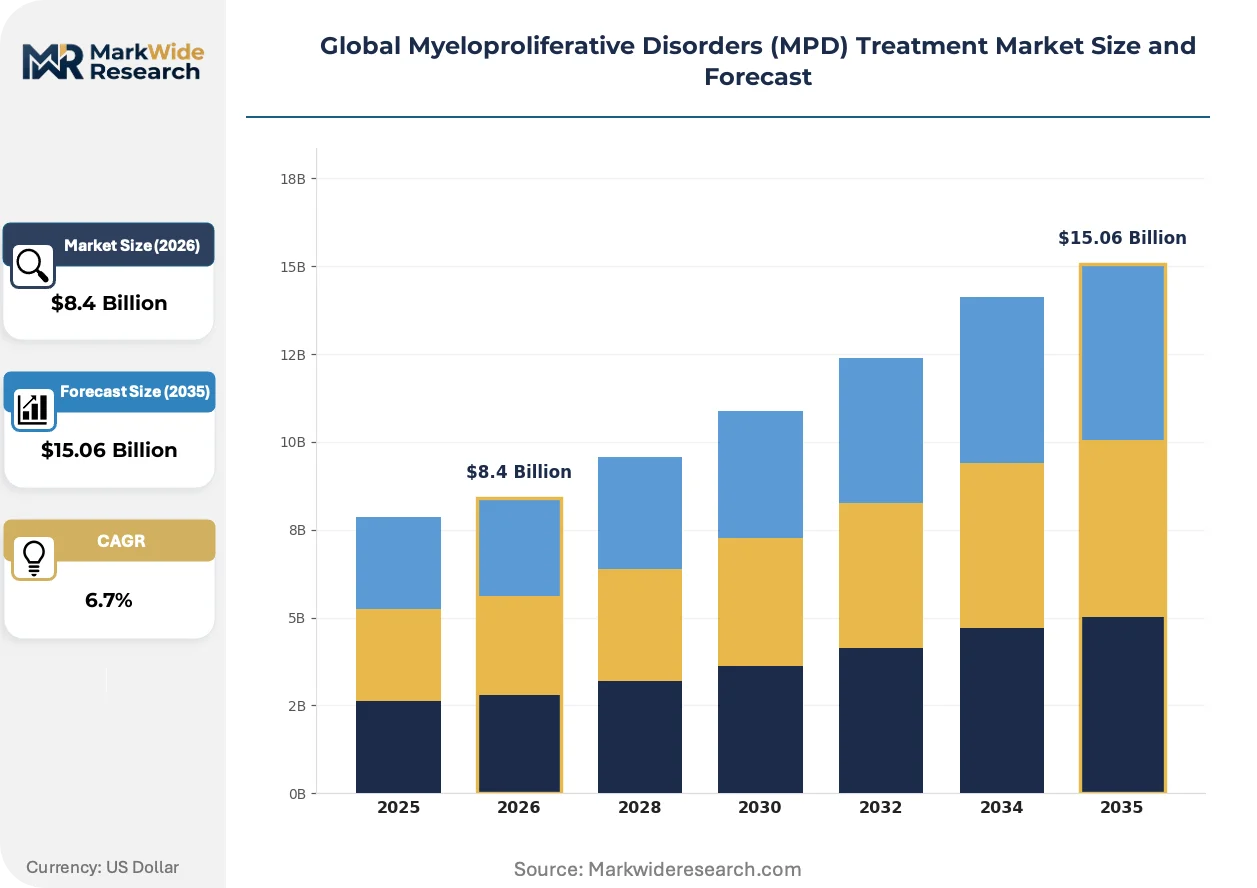
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.06 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: JAK Inhibitors, Cytoreductive Agents, Interferons, Anti-inflammatory Agents, Antithrombotic Agents Therapy Area: Polycythemia Vera, Essential Thrombocythemia, Primary Myelofibrosis, Chronic Myeloid Leukemia End User: Hematology Clinics, Oncology Centers, Research Institutions, Specialized Hospitals Delivery Mode: Oral Administration, Subcutaneous Injection, Intravenous Infusion, Transdermal Patch |
| Companies Covered | Novartis AG, Bristol-Myers Squibb, Incyte Corporation, Takeda Pharmaceutical Company Limited, AbbVie, GlaxoSmithKline, Viatris, Pfizer, Teva Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Myeloproliferative Disorders (MPD) Treatment Market Shifts & Advancements
Next-generation therapeutic modalities are restructuring competitive positioning across the MPD treatment landscape, with formulation science and regulatory science advancing in parallel.
Second-generation JAK inhibitors with improved selectivity profiles are consolidating therapeutic positioning in myelofibrosis by reducing off-target hematologic toxicity and enabling dose optimization. Hematology clinics in Germany and the United States are prioritizing these agents for intermediate-risk patient stratification. The technology is consolidating market share around agents demonstrating superior anemia management compared to first-generation standards.
EMA's PRIME scheme for priority medicines is compressing scientific advice timelines and enabling parallel development of companion diagnostics for MPD molecular subtyping. Pharmaceutical developers are leveraging this pathway to align clinical trial design with health technology assessment requirements across EU member states. The regulation most directly affects myelofibrosis indications where biomarker-driven patient selection determines reimbursement outcomes.
Integrated care models are restructuring patient journey management by embedding clinical pharmacists and nurse navigators within hematology clinic workflows. Academic medical centers in Japan and the United States are piloting these team-based approaches to improve adherence monitoring and symptom reporting. The shift is most visible in myelofibrosis populations where treatment complexity and comorbidity burden demand coordinated multidisciplinary oversight.
Global Myeloproliferative Disorders (MPD) Treatment Market Segmentation
Segmentation in the MPD treatment market reveals how regulatory pathways, patient stratification, and care delivery infrastructure shape commercial access. Each dimension exposes distinct margin structures and investment priorities for pharmaceutical developers.
Product Type:
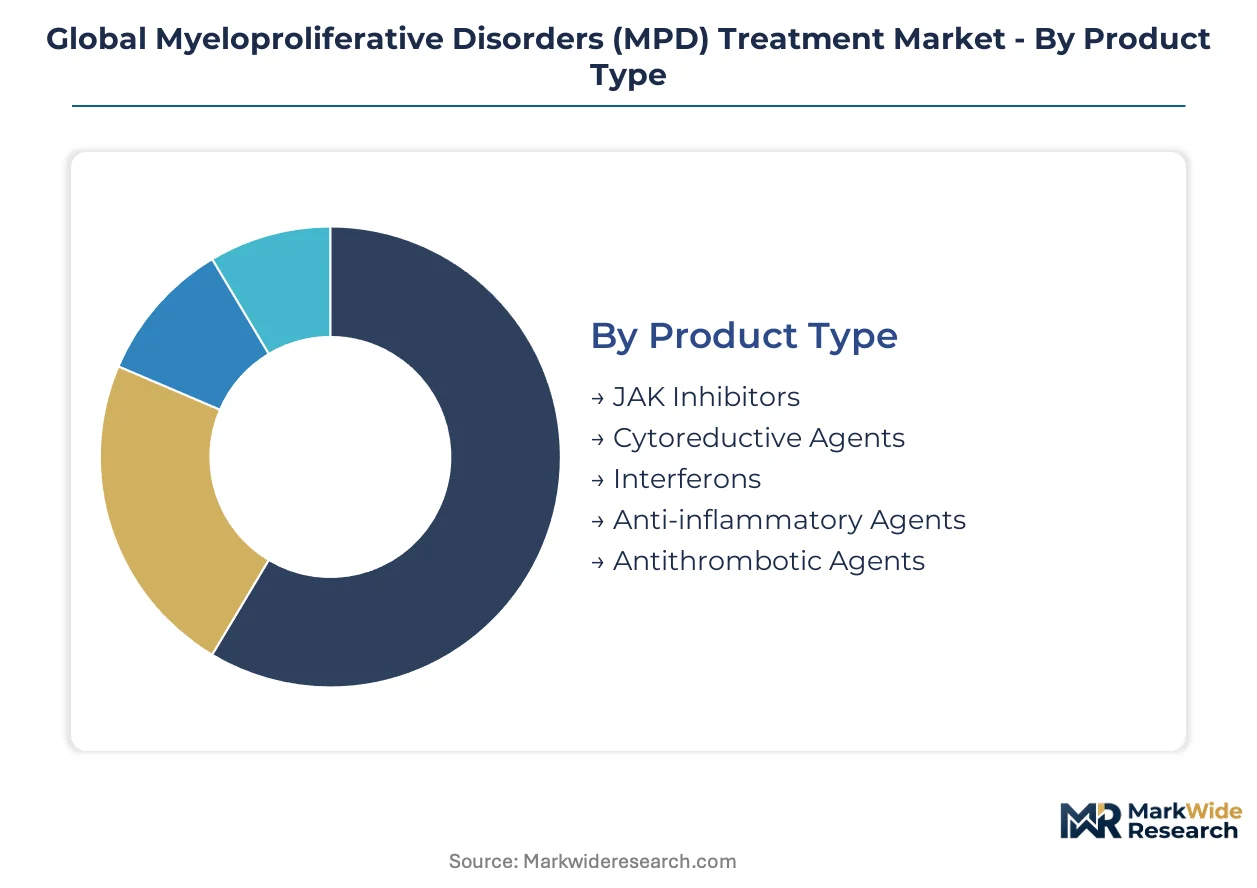
FDA Breakthrough Therapy and EMA PRIME designations concentrate on JAK inhibitors and interferons, while cytoreductive agents face standard review timelines. Anti-inflammatory and antithrombotic segments navigate abbreviated pathways as supportive care adjuncts.
- JAK Inhibitors:Small-molecule agents targeting JAK1/JAK2 kinases dominate therapeutic positioning in myelofibrosis through splenic response and symptom control. Demand concentrates in United States academic medical centers and German hematology networks where specialized diagnostic infrastructure enables molecularly-directed prescribing.
- Interferons:Pegylated formulations extend half-life and reduce injection frequency compared to standard interferon alfa. Younger, treatment-naïve polycythemia vera patients in Japan and Germany drive uptake as cytoreductive alternatives with disease-modifying potential.
- Cytoreductive Agents:Hydroxyurea and busulfan remain standard-of-care for high-risk cytoreduction in resource-constrained settings.
- Anti-inflammatory Agents:Corticosteroids and targeted cytokine modulators address constitutional symptoms and inflammatory complications.
- Antithrombotic Agents:Low-dose aspirin and anticoagulants manage thrombohemorrhagic risk across all MPD subtypes.
JAK inhibitors sit at the top of the volume ranking, with interferons climbing the fastest.
Therapy Area:
Orphan disease status varies by indication, shaping exclusivity periods and payer negotiation leverage. Primary myelofibrosis commands premium pricing due to limited alternatives, while polycythemia vera offers volume scale through broader prevalence.
- Primary Myelofibrosis:Clonal stem cell disorder characterized by bone marrow fibrosis, splenomegaly, and cytopenias generates the deepest margin pools. United States and Japan concentrate curative-intent transplant referrals, extending chronic pharmacotherapy duration for ineligible patients.
- Polycythemia Vera:Erythrocytosis-driven thrombosis risk creates the broadest addressable patient base among MPD indications. German and United Kingdom hematology clinics prioritize cytoreductive intervention for high-risk stratification.
- Essential Thrombocythemia:Platelet-predominant clonal disorder with lower transformation risk than myelofibrosis.
- Chronic Myeloid Leukemia:BCR-ABL-driven myeloproliferation now managed predominantly with tyrosine kinase inhibitors rather than traditional MPD protocols.
Polycythemia vera captures the largest patient volume, with primary myelofibrosis demonstrating the steepest expansion trajectory in revenue per treated patient.
End User:
Site-of-care certification requirements diverge between infusion-capable centers and oral therapy dispensing clinics. Research institutions maintain separate IRB and biospecimen governance frameworks.
- Hematology Clinics:Specialized myeloproliferative neoplasm centers concentrate diagnostic expertise and longitudinal care coordination. Networks in Boston, Heidelberg, and Tokyo drive referral patterns for advanced therapy access.
- Oncology Centers:Comprehensive cancer centers integrate MPD management within broader hematologic malignancy portfolios. United States NCI-designated centers and Japan's cancer core hospitals anchor regional treatment capacity.
- Research Institutions:Academic medical centers with active clinical trial portfolios manage investigational therapy protocols.
- Specialized Hospitals:Transplant-capable facilities provide allogeneic stem cell therapy for high-risk myelofibrosis escalation.
Hematology clinics retain the highest patient throughput, with oncology centers gaining share fastest through integrated cancer network expansion.
Delivery Mode:
Formulation technology determines distribution infrastructure requirements and patient adherence monitoring protocols. Parenteral modalities demand cold-chain integrity and healthcare professional administration.
- Oral Administration:Small-molecule JAK inhibitors and hydroxyurea enable outpatient self-management with pharmacy dispensing. United States specialty pharmacy networks and German community pharmacy chains control fulfillment for chronic oral regimens.
- Subcutaneous Injection:Pegylated interferon formulations require patient or caregiver training for home administration. Japanese home healthcare services and United States visiting nurse programs support injection competence development.
- Intravenous Infusion:Investigational agents and supportive care require infusion center capacity.
- Transdermal Patch:Emerging delivery technologies aim to reduce injection burden for interferon-based therapy.
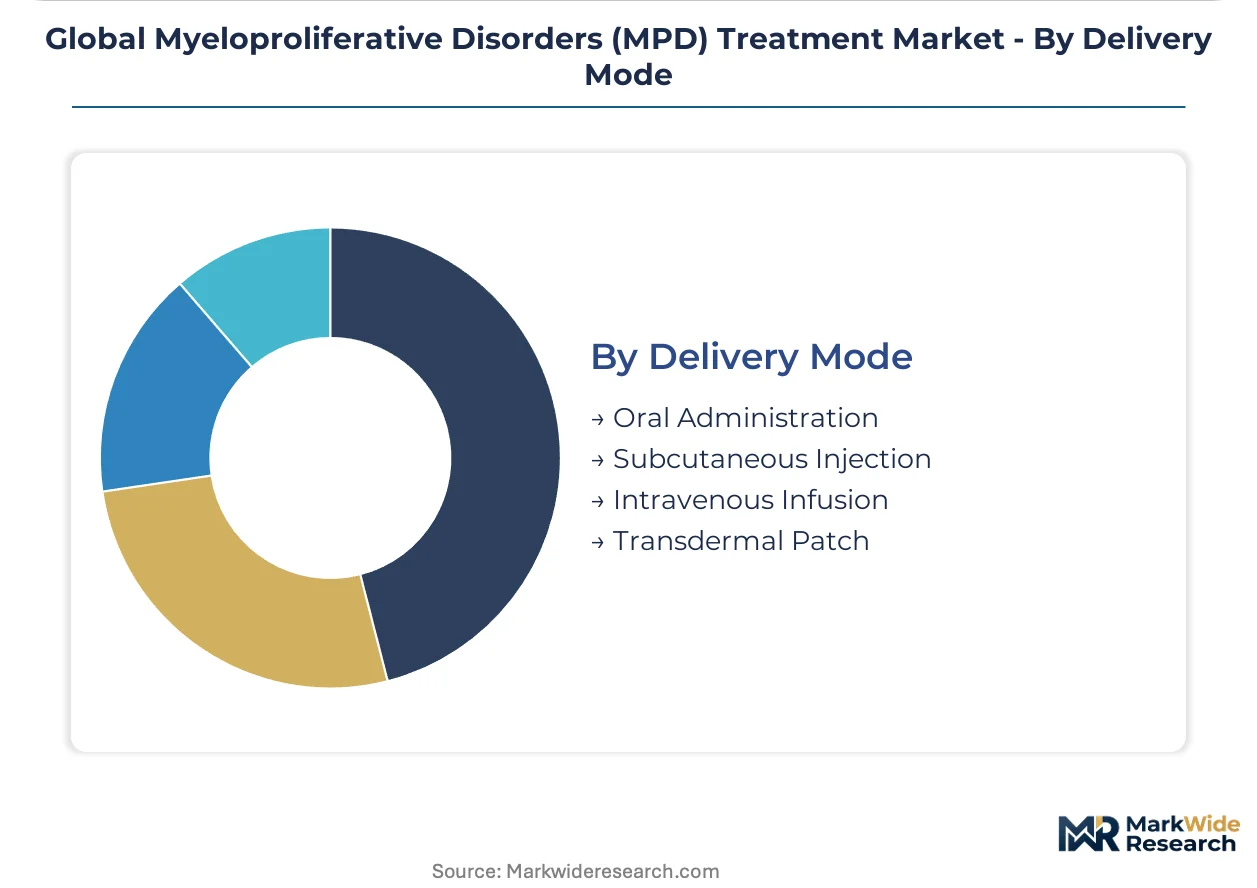
Oral administration dominates prescription volume, with subcutaneous injection expanding most quickly through interferon formulation advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized hematology networks in Boston, Heidelberg, and Tokyo concentrate global MPD treatment capacity. These clusters anchor referral patterns for advanced JAK inhibitor therapy and transplant-eligible patient triage. National regulatory frameworks diverge sharply in approval timelines and companion diagnostic requirements.
United States
FDA's Breakthrough Therapy designation compresses review timelines for novel myelofibrosis agents. The IRA's drug pricing provisions reshape negotiation dynamics for chronic oral JAK therapy. Boston's Dana-Farber Cancer Institute and Houston's MD Anderson anchor specialized MPN care networks that drive investigator-initiated trial enrollment.
Germany
EMA's PRIME scheme accelerates scientific advice for orphan oncology indications. Heidelberg University Hospital and Munich's LMU Klinikum concentrate molecular diagnostic capacity for CALR-mutated patient stratification. GDPR-compliant disease registries enable outcomes-based contracting with statutory health insurers.
Japan
PMDA's Sakigake designation streamlines priority review for innovative hematology therapies. Tokyo's National Cancer Center Hospital and Osaka University Hospital integrate JAK inhibitor prescribing with allogeneic transplant coordination. Home healthcare services support subcutaneous interferon administration in aging patient cohorts.
United Kingdom
NICE's highly specialized technologies pathway enables premium pricing for ultra-rare MPD indications. London's Royal Free Hospital and Manchester's Christie NHS Foundation Trust anchor regional MPN multidisciplinary teams. Real-world evidence platforms support post-market surveillance for accelerated approvals.
Switzerland
Swissmedic's adaptive licensing framework permits iterative evidence generation for novel mechanisms. Basel's University Hospital and Zurich's USZ concentrate pharmaceutical-sponsored phase III trial infrastructure. Pricing negotiations with compulsory health insurance funds reference German and French reimbursement outcomes.
Global Myeloproliferative Disorders (MPD) Treatment Market Competitive Landscape
Global majors compete with regional champions across regulatory science and hematology clinic network access. The vendor base stratifies into three tiers: integrated pharmaceutical conglomerates with JAK inhibitor franchises, mid-cap immuno-oncology specialists, and generic manufacturers of hydroxyurea and supportive care agents. Strategic archetypes include therapy-area consolidators pursuing indication expansion, precision medicine players developing companion diagnostics, and biosimilar entrants targeting interferon alfa commoditization. Dominant competitive moves encompass M&A for pipeline augmentation and strategic partnerships with academic medical centers for real-world evidence generation.
Within the integrated pharmaceutical tier, Novartis AG and Bristol-Myers Squibb occupy anchor positions through established hematology franchises. Novartis exemplifies the therapy-area consolidator archetype with cross-indication JAK inhibitor positioning. Bristol-Myers Squibb represents the immuno-oncology convergence strategy through checkpoint combination development. Incyte Corporation sits within the precision medicine tier as a specialized oral therapy manufacturer controlling ruxolitinib supply security.
| Leading Market Players |
|---|
| Novartis AG |
| Bristol-Myers Squibb |
| Incyte Corporation |
| Takeda Pharmaceutical Company Limited |
| AbbVie |
| GlaxoSmithKline |
| Viatris |
| Pfizer |
| Teva Pharmaceuticals |
| Others |
Supply & Pricing Matrix
JAK inhibitor selectivity tiers bifurcate the MPD market into premium second-generation agents and commoditized first-generation standards, with this divergence manifesting in both reimbursement contracting complexity and active pharmaceutical ingredient sourcing concentration across Swiss and German manufacturing nodes.
Pricing Analysis
Input-cost pass-through from limited-source JAK inhibitor raw materials anchors pricing stratification across premium, standard, and economy tiers. Price differentiation hinges on FDA Breakthrough Therapy designation and EMA PRIME scheme certification, with branded second-generation agents commanding substantial premiums over hydroxyurea generics. Pricing pressure stems from the IRA's Medicare negotiation provisions compressing chronic oral therapy margins. Oncology centers demonstrate lowest price sensitivity due to bundled reimbursement, while community hematology clinics in India and Brazil face acute budget constraints.
Supply Chain Analysis
Single-source vulnerability sits with Swiss and German API manufacturers for JAK inhibitor kinase domains. Raw material dependencies encompass pyrazole core structures, pyrrolopyrimidine scaffolds, and specialized palladium catalysts. Supply chain risk centers on EMA MDR compliance timelines delaying companion diagnostic kit releases. Distribution runs through United States specialty pharmacy networks and German hospital pharmacy consortia for cold-chain parenteral interferon formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities emerge between Japan's Sakigake fast-track reimbursement and the United States' IRA-driven price compression, enabling portfolio optimization across divergent regulatory cost structures.
For Market Incumbents: Extend manufacturing scale advantages into pegylated interferon formulation capacity to preempt biosimilar erosion. Defensive positioning demands backward integration into JAK inhibitor API production given single-source vulnerability in Swiss supply nodes. Reinforce hematology clinic network lock-in through real-world evidence partnerships with Heidelberg and Tokyo academic centers.
For New Entrants and Emerging Players: FDA's accelerated approval pathway for oncology therapies opens a window for myelofibrosis disease-modification claims with streamlined confirmatory trial designs. White-space concentration exists in polycythemia vera cytoreductive therapy across Indian and Brazilian markets where interferon penetration lags diagnostic capacity. Go-to-market execution should leverage contract research organization partnerships for rapid site activation in underpenetrated geographies.
For Investors and Strategic Acquirers: Consolidation pressure builds where specialized hematopathology workforce scarcity constrains diagnostic throughput and delays treatment initiation. Long-term viability favors precision medicine platforms with companion diagnostic capabilities and orphan disease exclusivity positioning. Acquisition targets should demonstrate JAK inhibitor pipeline depth or interferon formulation differentiation. The signal to watch is FDA confirmatory trial failure rates for accelerated approvals, which would reshape risk-adjusted return calculations across the sector.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA Breakthrough Therapy designation compresses myelofibrosis therapy review timelines versus standard oncology pathways. |
| Manufacturing Scale-Up | API production expansion in Swiss and German nodes secures supply continuity for oral JAK inhibitor global demand. |
| Pipeline Diversification | Interferon-JAK inhibitor combination protocols open disease-modification claims beyond symptomatic management. |
| Strategic Partnership | Academic medical center alliances in Boston and Heidelberg generate real-world evidence for payer negotiations. |
| Geographic Expansion | Polycythemia vera market development in India and Brazil addresses cytoreductive therapy adoption gaps. |
Research Methodology
Bottom-up hematology clinic capacity modeling reconciled against top-down pharmaceutical shipment tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers were cross-validated against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. This dual-layer approach ensures demand-side prescription patterns align with supply-side manufacturing and distribution disclosures.
Input-output matrices linking patient volume projections to therapy area revenue pools drive the forecast framework. Segmentation dimensions encompass product type, therapy area, end user, and delivery mode, with patient population stratification and regional regulatory clusters as cross-cutting variables. CAGRs were derived from spline interpolation across historical volume trends and forward-looking patent expiry and pipeline entry assumptions. JAK inhibitor selectivity profiles and interferon formulation half-life extensions serve as key technology levers in the projection model.
Revisions become necessary when FDA confirmatory trial outcomes diverge from accelerated approval endpoints, EMA MDR compliance timelines extend companion diagnostic market access, or allogeneic stem cell transplant capacity expansions alter chronic pharmacotherapy duration assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Growth Hormone Deficiency Market
Specialty Medicine
Mental Retardation Treatment Market
Specialty Medicine
Global Phenylketonuria Treatment Market
Specialty Medicine
Synovial Sarcoma Market
Specialty Medicine
Germ Cell Tumors Market
Specialty Medicine
Pleurisy Market
Specialty Medicine
Chordoma Disease Therapeutics Market
Specialty Medicine
Hidradenitis Suppurativa (HS) Treatment Market
Specialty Medicine
Papillary Thyroid Cancer Market
Specialty Medicine
Nephrogenic Systemic Fibrosis (NSF) Treatment Market
Specialty Medicine
Balantidiasis Treatment Market
Specialty Medicine
Acute Hepatic Porphyria (AHP) Treatment Market
Specialty Medicine
Post-Traumatic Stress Disorder Treatment Market
Specialty Medicine
Lipoprotein Metabolism Disorders Treatment Market
Specialty Medicine
Listeriosis Treatment Market
Specialty Medicine
Global Addison's Disease Treatment Market