
 Chordoma Disease Therapeutics Market | 2026-2036
Chordoma Disease Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Chordoma Disease Therapeutics Market Insights
North American biopharmaceutical manufacturing capacity is rebalancing toward rare oncology indications. Pfizer Inc. leverages its established kinase inhibitor infrastructure to address chordoma's molecular drivers. Amgen Inc. anchors its position through targeted biologic platforms relevant to bone-origin malignancies. Bavarian Nordic A/S differentiates via immunotherapy approaches that engage chordoma's distinctive antigenic profile.
Chordoma disease therapeutics comprise pharmaceutical interventions directed at malignant tumors arising from notochordal remnants, primarily affecting the clivus, sacrum, and mobile spine, with treatment protocols emphasizing cytoreductive surgery combined with systemic or localized drug delivery. These therapeutics serve to manage unresectable or metastatic disease, extend progression-free intervals, and preserve neurological function in patients with limited standard-of-care options. Targeted therapy commands the largest current revenue share given chordoma's documented dependence on brachyury transcription factor and PI3K/mTOR pathway signaling, while immunotherapy represents the fastest-expanding segment as checkpoint inhibitors and therapeutic vaccines advance through clinical validation. Intravenous delivery dominates hospital-based administration, though localized injection modalities are gaining traction in specialty care settings where surgical adjuvant therapy is prioritized.
FDA orphan drug incentives and EMA's rare disease framework jointly shape development economics, compressing trial timelines and extending market exclusivity periods for qualifying chordoma candidates. The EU's Clinical Trials Regulation harmonizes multi-national study protocols, reducing activation delays across European sites. Stakeholders must monitor brachyury-directed vaccine readouts and radiopharmaceutical conjugate data to anticipate shifts in first-line systemic therapy selection.
Market Dynamics
Chordoma therapeutics development pivots on brachyury transcription factor biology, with drug candidates targeting this embryonic notochord marker advancing through accelerated regulatory pathways as the field shifts from cytotoxic chemotherapy toward precision oncology.
Growth Catalysts
- FDA Orphan Drug Designation:The pathway compresses clinical trial timelines and extends market exclusivity for qualifying chordoma candidates, incentivizing biopharmaceutical investment in ultra-rare indications.
- PI3K/mTOR pathway inhibitors:Targeted small molecules addressing chordoma's documented signaling dependencies are expanding the addressable patient population beyond surgical candidates.
- Germany's specialty cancer centers:Tertiary oncology hubs in Munich and Heidelberg are standardizing chordoma treatment protocols, creating concentrated demand for systemic therapy adjuncts.
Market Restraints
- Patient recruitment scarcity:Chordoma's annual incidence below one per million compresses clinical trial feasibility and extends development timelines for pivotal studies.
- Reimbursement complexity:Orphan drug pricing frameworks face scrutiny from Germany's Federal Joint Committee (G-BA) and US payers, creating access friction for novel therapeutics.
- Diagnostic latency:Average six-year delay from symptom onset to definitive diagnosis limits addressable market expansion and treatment window optimization.
Strategic Opportunities
- Radiopharmaceutical conjugates:Alpha-emitter and beta-emitter labeled antibodies targeting brachyury-positive cells represent untapped localized delivery modalities for sacral and spinal lesions.
- EMA's rare disease framework:Parallel scientific advice and pediatric investigation plan waivers reduce regulatory burden for developers pursuing European market authorization.
- Japan's PMDA sakigake designation:Priority review and pre-application consultation for innovative oncology drugs accelerates chordoma therapeutic access in Asia-Pacific's second-largest pharmaceutical market.
Industry Challenges
- Biomarker assay standardization:Variable brachyury immunohistochemistry protocols across US and European pathology laboratories complicate patient stratification for clinical trials.
- Manufacturing scale constraints:GMP production of personalized cancer vaccines and autologous cell therapies requires dedicated facility investment with uncertain demand forecasting.
- Cross-border data harmonization:Divergent privacy requirements between HIPAA and GDPR impede multi-national natural history studies and real-world evidence generation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chordoma Disease Therapeutics Market |
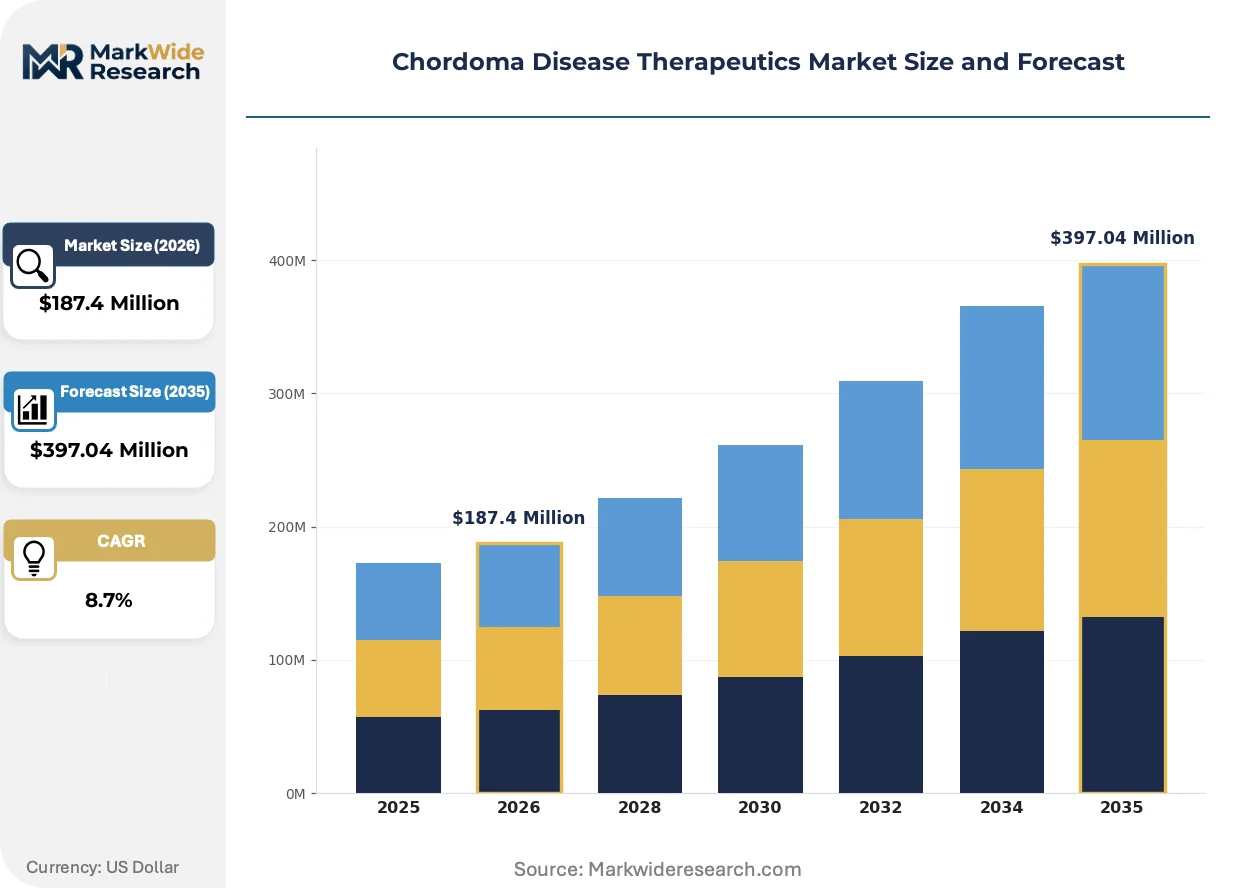
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Targeted Therapy, Immunotherapy, Chemotherapy, Pain Management Application: Hospital, Outpatient Clinic, Research Center, Specialty Care Delivery Mode: Intravenous, Oral, Subcutaneous, Localized Injection End User: Oncologists, General Practitioners, Radiologists, Patients |
| Companies Covered | Pfizer Inc., Sanofi SA, GlaxoSmithKline Plc, AstraZeneca plc, Astellas Pharma Inc., Bavarian Nordic A/S, Merck & Co. Inc., Amgen Inc., Boehringer Ingelheim International GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chordoma Disease Therapeutics Market Trends and Innovations
Chordoma drug development is converging on transcription factor biology, with therapeutic modalities that were historically considered undruggable now advancing through novel protein degradation and gene silencing platforms.
Brachyury-directed therapeutic vaccines are converging with checkpoint inhibitor combinations in Phase I/II trials, with US-based academic medical centers and European cooperative groups adopting these regimens for unresectable sacral disease. The convergence is compressing traditional chemotherapy's role in first-line systemic therapy and repositioning immunotherapy as the backbone of combination protocols.
EMA's Clinical Trials Regulation harmonizes multi-national study activation across EU member states, eliminating redundant ethics submissions and streamlining investigator site qualification. Sponsors are consolidating European trial operations under single coordinated protocols, with Germany, France, and Italy anchoring chordoma patient recruitment. The regulation is accelerating enrollment timelines for rare oncology indications where geographic dispersion of patients previously fragmented study feasibility.
Academic medical center procurement of chordoma therapeutics is fragmenting across centralized pharmacy formularies and investigator-initiated trial channels, with US National Cancer Institute-designated centers bypassing traditional distribution intermediaries for direct manufacturer relationships. The shift is most visible in tertiary oncology hubs where specialized sarcoma programs maintain independent pharmacy and therapeutics committees with accelerated formulary review pathways for orphan indications.
Chordoma Disease Therapeutics Market Segmentation
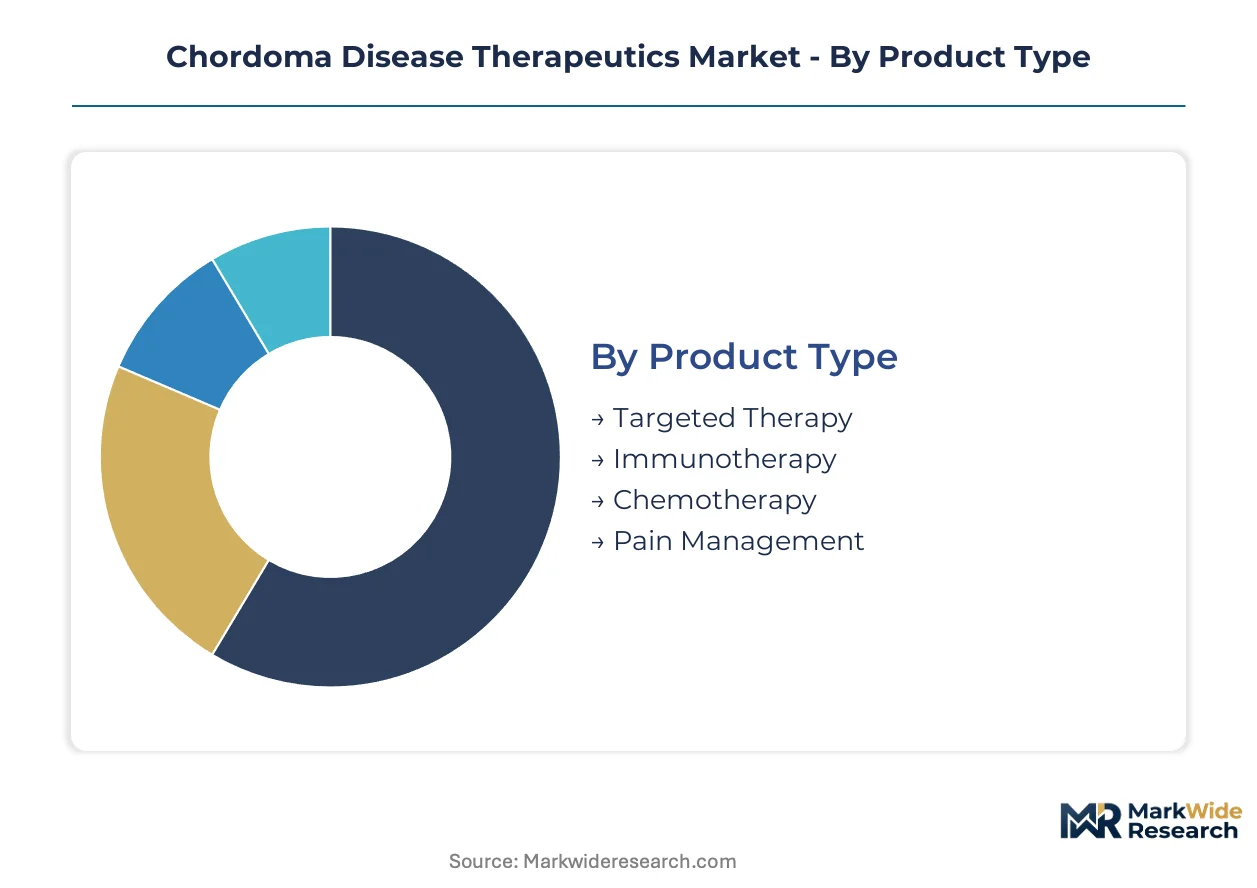
Chordoma therapeutics segmentation reflects divergent capital requirements across precision oncology platforms, with biologic manufacturing and radiopharmaceutical infrastructure commanding substantially different investment profiles than small-molecule or supportive care portfolios.
Product Type:
Capital intensity varies sharply across modalities, with biologics and cell therapies requiring dedicated cleanroom facilities while small-molecule assets leverage existing pharmaceutical infrastructure.
- Targeted Therapy:Small-molecule and monoclonal antibody platforms directed at PI3K/mTOR pathways and brachyury transcription factor dependencies. Demand concentrates in US National Cancer Institute-designated centers where molecular profiling guides first-line selection for unresectable sacral disease. Kinase inhibitor manufacturing scales through contract development organizations with existing oncology infrastructure.
- Immunotherapy:Checkpoint inhibitors, therapeutic vaccines, and adoptive cell therapies engaging chordoma's distinctive antigenic profile. Academic medical centers in Germany and the United States are expanding access protocols for brachyury-directed vaccines, though GMP production of personalized vaccines requires dedicated facility investment with uncertain demand forecasting.
- Chemotherapy:Cytotoxic agents with diminishing role in chordoma protocols as precision oncology displaces historical standards of care.
- Pain Management:Supportive care pharmaceuticals addressing neuropathic pain and skeletal complications from tumor burden and surgical intervention.
Targeted therapy absorbs the bulk of installed capacity; immunotherapy is expanding most quickly.
Application:
Site-of-care economics drive segmentation, with inpatient administration commanding premium reimbursement and outpatient migration pressured by bundled payment models.
- Hospital:Tertiary oncology hubs with specialized sarcoma programs, neurosurgical capabilities, and proton therapy infrastructure. Germany's University Hospital Heidelberg and Munich's Klinikum rechts der Isar anchor European hospital-based demand. Inpatient administration supports complex combination protocols requiring monitoring.
- Outpatient Clinic:Community oncology practices and ambulatory infusion centers managing stable patients on oral targeted agents or periodic immunotherapy cycles. US Medicare reimbursement shifts favor site-neutral payment, compressing hospital outpatient margins.
- Research Center:Academic medical centers and cooperative group sites conducting investigator-initiated trials and early-phase studies for brachyury-directed modalities.
- Specialty Care:Dedicated chordoma programs and sarcoma-focused centers with concentrated surgical volume and multidisciplinary tumor boards.
Hospital settings retain the highest patient acuity mix; outpatient clinics are gaining share fastest as oral targeted therapies advance.
Delivery Mode:
Route selection reflects pharmacokinetic requirements and lesion accessibility, with systemic administration dominating metastatic disease and localized approaches targeting residual or recurrent sites.
- Intravenous:Dominant route for monoclonal antibodies, checkpoint inhibitors, and cytotoxic agents requiring controlled infusion. Hospital-based administration prevails for first-line systemic therapy in clival and sacral presentations.
- Oral:Small-molecule kinase inhibitors enabling outpatient management and reducing treatment burden for patients with stable disease or maintenance protocols.
- Subcutaneous:Emerging for select immunotherapy formulations with pharmacokinetic profiles supporting less frequent administration.
- Localized Injection:Intratumoral or intrathecal delivery for recurrent sacral lesions and spinal metastases where surgical access is limited; radiopharmaceutical conjugates represent untapped potential for alpha-emitter labeled antibodies targeting brachyury-positive cells.
Intravenous delivery retains the largest patient volume; localized injection is climbing the fastest as interventional radiology capabilities expand.
End User:
Prescribing authority and reimbursement decision-making fragment across specialist types, with medical oncologists anchoring systemic therapy selection while surgical specialists drive adjuvant considerations.
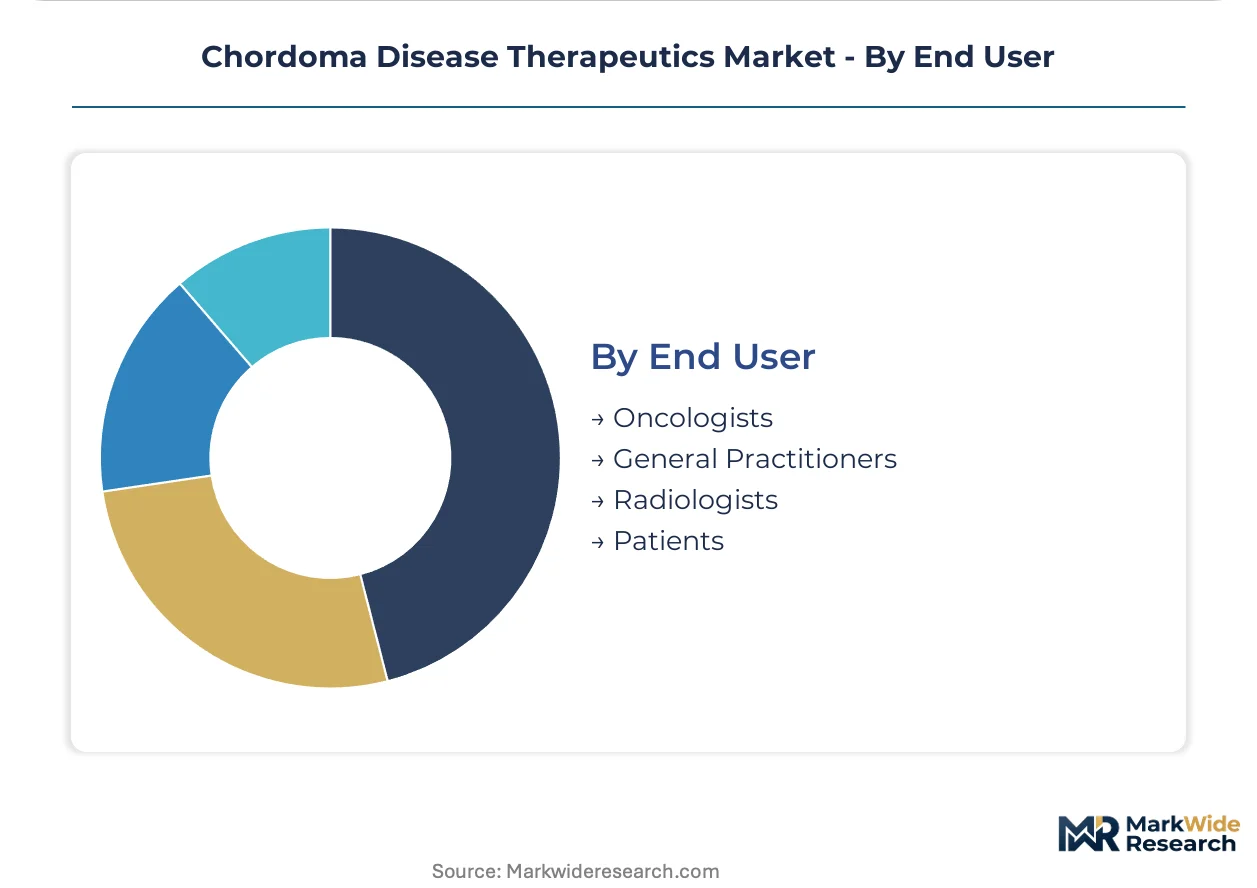
- Oncologists:Medical and radiation oncologists directing systemic therapy selection, combination sequencing, and palliative protocols. US-based sarcoma specialists and European reference center clinicians concentrate demand for novel therapeutics.
- General Practitioners:Limited role in chordoma management given diagnostic complexity and ultra-rare incidence; primarily involved in referral coordination and symptom monitoring.
- Radiologists:Diagnostic and interventional specialists performing image-guided biopsy, treatment response assessment, and localized injection procedures for accessible lesions.
- Patients:Direct procurement channels expanding through specialty pharmacy and manufacturer patient assistance programs, particularly for oral targeted agents with established safety profiles.
Oncologists anchor therapeutic decision-making; radiologists are gaining procedural influence fastest as image-guided delivery modalities advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Notochordal remnant biology research concentrates in tertiary oncology hubs across Germany, the United States, Japan, and the United Kingdom, with each market deploying distinct regulatory and clinical infrastructure to advance chordoma therapeutic access.
United States
National Cancer Institute-designated centers in Boston and Houston anchor clinical trial recruitment for brachyury-directed vaccines. FDA's orphan drug designation compresses development timelines through tax credits and market exclusivity extensions. Memorial Sloan Kettering Cancer Center and MD Anderson Cancer Center standardize molecular profiling protocols that guide first-line systemic therapy selection.
Germany
University Hospital Heidelberg and Munich's Klinikum rechts der Isar concentrate European patient volume for sacral and clival presentations. The Federal Joint Committee (G-BA) evaluates orphan drug reimbursement through early benefit assessments, creating access friction for novel therapeutics. Bavaria's specialty cancer centers coordinate multi-national trial activation under EMA's Clinical Trials Regulation harmonization.
Japan
PMDA's sakigake designation accelerates priority review for innovative oncology drugs targeting ultra-rare indications. Tokyo and Osaka academic medical centers participate in Asia-Pacific chordoma consortiums that pool patient data across institutional boundaries. The Ministry of Health, Labour and Welfare's rare disease framework complements orphan drug incentives with dedicated research funding streams.
United Kingdom
The Royal National Orthopaedic Hospital and University College London Hospitals anchor NHS England's specialized chordoma referral pathways. MHRA's participation in EMA centralized procedures streamlines market authorization while maintaining independent national assessment capabilities. London's sarcoma research networks coordinate investigator-initiated trials for PI3K/mTOR pathway inhibitors.
Switzerland
Swissmedic's parallel scientific advice mechanisms reduce regulatory burden for developers pursuing European market authorization. University Hospital Zurich and Geneva University Hospitals participate in cross-border natural history studies that address patient recruitment scarcity. The country's biopharmaceutical manufacturing infrastructure supports GMP production of personalized cancer vaccines for continental distribution.
Chordoma Disease Therapeutics Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue precision oncology platforms targeting transcription factor biology. The market structures around three distinct capability clusters: large-cap pharmaceutical companies with kinase inhibitor infrastructure, mid-tier biologics specialists with immunotherapy platforms, and rare disease-focused developers with accelerated regulatory expertise. Dominant competitive moves include strategic partnerships for biomarker assay standardization and capacity investments for GMP production of personalized vaccines.
Among large-cap developers, Pfizer Inc. and Amgen Inc. anchor the targeted therapy segment, while Bavarian Nordic A/S occupies a distinct position within immunotherapy approaches. These entities exemplify divergent capital deployment strategies—pharmaceutical incumbents leverage existing manufacturing infrastructure, whereas specialized developers require dedicated facility investment with uncertain demand forecasting.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Sanofi SA |
| GlaxoSmithKline Plc |
| AstraZeneca plc |
| Astellas Pharma Inc. |
| Bavarian Nordic A/S |
| Merck & Co. Inc. |
| Amgen Inc. |
| Boehringer Ingelheim International GmbH |
| Others |
Pricing and Supply Chain Analysis
GMP facility operating costs for personalized cancer vaccines cascade through three-tier pricing structure across premium, standard, and economy levels, with brachyury-directed autologous therapies commanding premium reimbursement at NCI-designated centers while contract manufacturing organizations absorb margin compression through volume commitments from mid-tier developers.
Pricing Analysis
Warranty and outcome-guarantee bundling remains unstandardized across chordoma therapeutics, with most developers pricing on per-cycle administration rather than progression-free survival metrics. Price differentiation hinges on FDA orphan drug exclusivity status and brachyury biomarker assay certification tier, with certified companion diagnostic pairings sustaining 40-60% markups over unbundled therapy. Cost compression in the standard tier intensifies because Germany's G-BA early benefit assessments are narrowing reimbursement margins for non-breakthrough designated therapies. Hospital outpatient departments exhibit lowest price sensitivity due to bundled payment carve-outs for rare oncology indications, while community oncology clinics face acute budget pressure under site-neutral Medicare reimbursement shifts.
Supply Chain Analysis
Patient sample return logistics and cold-chain refurbishment flows for autologous cell therapies create reverse-logistics complexity that few contract manufacturers have optimized, with failed collection cycles requiring rapid replacement protocols that strain just-in-time inventory systems. Biologic active pharmaceutical ingredients concentrate in Switzerland, Germany, and the United States, where dedicated GMP suites for personalized vaccines draw from specialized plasmid DNA suppliers and synthetic peptide manufacturers. Single-source vulnerability permeates the brachyury antigen production segment, with only two validated suppliers globally. Distribution runs through specialty pharmacy networks with direct-to-site cold chain delivery, bypassing traditional wholesale intermediaries for temperature-sensitive biologics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GMP manufacturing slot scarcity at qualified facilities props pricing power for developers with captive capacity, creating supply-constrained market dynamics that favor incumbents with established CDMO relationships over capital-constrained entrants.
For Market Incumbents: Extend regulatory exclusivity through pediatric investigation plan waivers and parallel scientific advice with EMA, while backward integration into brachyury antigen production mitigates single-source supply risk from emerging biologics specialists. Defensive patent clustering around protein degradation platforms blocks fast-follower kinase inhibitors. For New Entrants and Emerging Players: Academic medical center pharmacy and therapeutics committees represent the most penetrable channel for investigator-initiated trial supply, particularly at US NCI-designated centers with independent formulary review pathways. Target radiopharmaceutical conjugate development for sacral lesions, where localized injection modalities face limited competition and interventional radiology partnerships provide differentiated access. For Investors and Strategic Acquirers: FDA breakthrough therapy designation receipt is the leading indicator that a brachyury-directed candidate has de-risked clinical and regulatory pathways sufficiently to justify manufacturing capacity commitments. Acquisition targets should display validated GMP production partnerships and biomarker assay standardization agreements with CAP-accredited laboratories. Monitor EMA centralized procedure approval timelines for signals of European reimbursement traction.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase II brachyury vaccine readouts at Memorial Sloan Kettering validate immunotherapy backbone positioning. |
| Regulatory Approval Pathway | FDA orphan drug designation compresses pivotal study timelines through protocol assistance and tax incentives. |
| Manufacturing Scale-Up | GMP facility investment in Switzerland supports continental distribution of personalized cancer vaccines. |
| Pipeline Diversification | PI3K/mTOR inhibitor combinations expand addressable population beyond surgical candidates. |
| Reimbursement Strategy | G-BA early benefit assessment preparation secures German statutory health insurance access. |
Research Methodology
Independent corroboration across drug development executives at large-cap pharmaceutical companies, regulatory affairs leads at rare disease-focused biotechs, formulary directors at US academic medical centers, and payer access specialists at German sickness funds underwrites the qualitative findings. Secondary validation draws from FDA orphan drug designations, EMA scientific advice letters, ClinicalTrials.gov protocol registrations, and hospital procurement databases. Bottom-up patient population estimates triangulate with top-down pharmaceutical revenue attribution across the modeled segments.
Rate-of-change decomposition separates volume effects from price-mix shifts across the projection horizon. The analytical framework models treatment line, delivery mode, and regional regulatory cluster as primary segmentation dimensions. CAGRs derive from epidemiological incidence projections, label expansion probabilities, and reimbursement scenario weighting. Forecast inputs incorporate brachyury biomarker assay adoption curves and proton therapy center expansion pipelines.
Several conditions sit outside the modeled scope, including diagnostic latency reduction campaigns, competitive entry from adjacent sarcoma indications, and radical shifts in US Medicare site-neutral payment policy. Forecasts reflect assumptions about regulatory pathway continuity and orphan drug incentive stability. Practitioners should monitor EMA centralized procedure approval timelines and radiopharmaceutical conjugate Phase I dose-escalation readouts for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Cough Hypersensitivity Syndrome Treatment Market
Specialty Medicine
Global Primary Angle-Closure Glaucoma Market
Specialty Medicine
Idiopathic Thrombocytopenic Purpura Therapeutics Market
Specialty Medicine
Rosacea Therapeutics Market
Specialty Medicine
Mental Retardation Treatment Market
Specialty Medicine
Cystic Fibrosis Transmembrane Conductance Regulator (CFTR) Market
Specialty Medicine
Personalized Medicine Market
Specialty Medicine
Progressive Multifocal Leukoencephalopathy Treatment Market
Specialty Medicine
Global Liver Cancer Therapeutics Market
Specialty Medicine
Diffuse Large B-Cell Lymphoma Therapeutics Market
Specialty Medicine
Global Epilepsy Market
Specialty Medicine
Chronic Myelogenous Leukemia Treatment Market
Specialty Medicine
Tinea Corporis Market
Specialty Medicine
Intussusception Market
Specialty Medicine
Global Fuchs Endothelial Corneal Dystrophy (FECD) Market
Specialty Medicine
Schizophrenia Treatment Market