
 Balantidiasis Treatment Market | 2026-2036
Balantidiasis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Balantidiasis Treatment Market Outlook
Treatment procurement is shifting between premium branded antiprotozoals and commodity generic antibiotics as payers tighten formularies. Pfizer Inc. leverages its manufacturing scale to sustain supply contracts across Latin American hospital networks. Sanofi anchors its position through nitroimidazole specialization in tropical medicine portfolios. Sandoz AG competes aggressively on cost, dominating oral tetracycline volumes in outpatient settings.
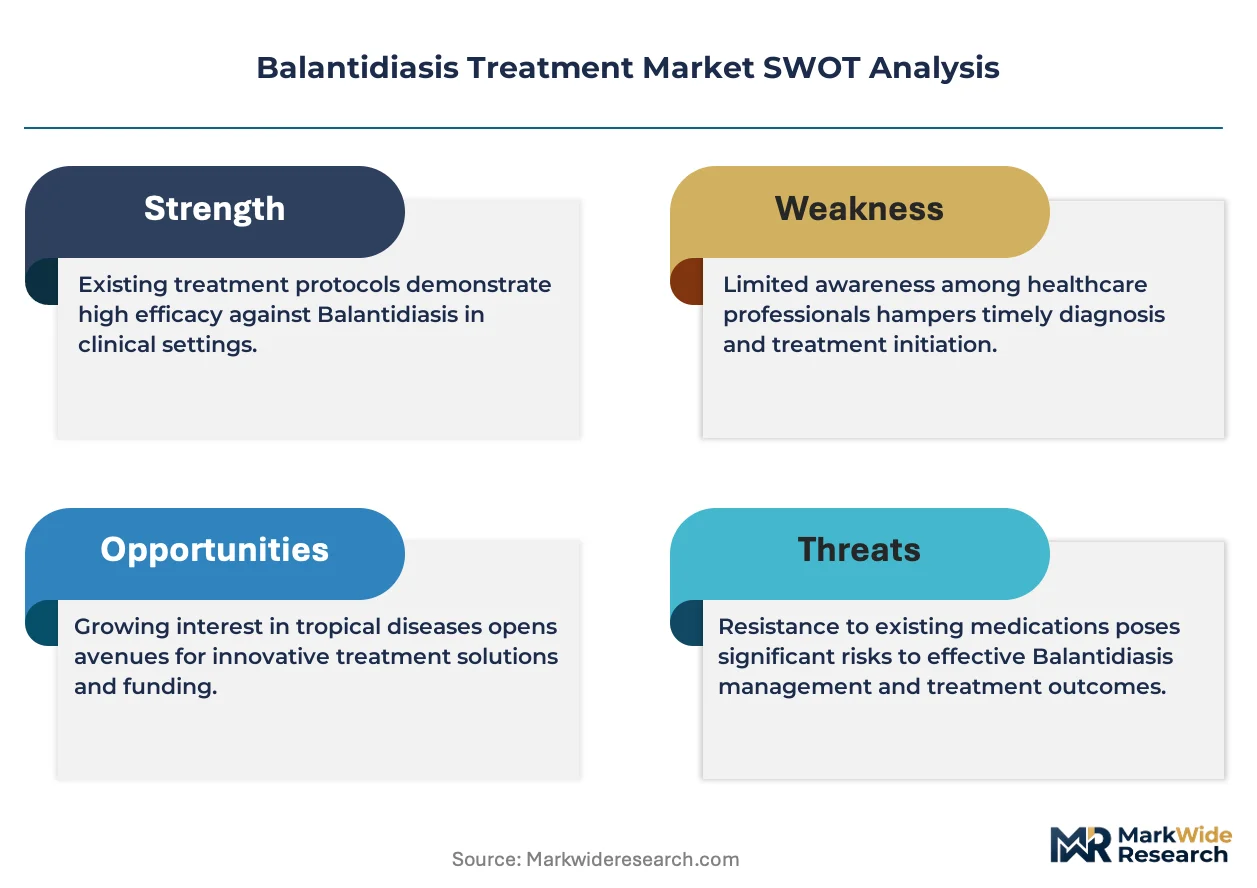
Balantidiasis treatment encompasses antimicrobial and supportive therapeutic protocols targeting Balantidium coli infection, a ciliated protozoan pathogen transmitted via fecal-oral contamination; standard regimens employ tetracycline derivatives or metronidazole analogs administered orally over seven-to-ten-day courses to eradicate colonic trophozoites and cysts. Antimicrobials command the largest revenue share among product types due to entrenched WHO essential medicine status, while combination therapy protocols represent the fastest-expanding treatment segment as resistance surveillance intensifies across endemic regions. Oral delivery mode retains structural dominance over intravenous alternatives where infusion infrastructure remains limited.
FDA bioequivalence standards and WHO prequalification requirements govern antiprotozoal manufacturing quality, directly determining which manufacturers access institutional procurement channels in endemic countries. EPA environmental discharge rules and national pharmaceutical regulators in Brazil and India shape active pharmaceutical ingredient sourcing constraints for metronidazole and tetracycline producers. Stakeholders must monitor evolving resistance patterns and prequalification status changes to anticipate shifts in preferred protocol design and supplier positioning.
Market Dynamics
Hospital procurement of tetracycline-class and nitroimidazole protocols is shifting upward as clinicians encounter Balantidium coli in immunocompromised populations, with WHO neglected tropical disease programs and national CDC screening mandates in endemic zones directly shaping prescription volumes and supplier contract structures.
Growth Catalysts
- WHO Essential Medicine Status:Tetracycline derivatives and metronidazole analogs retain entrenched placement on WHO essential medicine lists, securing institutional procurement channel access across Southeast Asian hospital networks and Latin American public health systems.
- Immunocompromised Population Expansion:Rising HIV/AIDS prevalence and organ transplant volumes in endemic regions create persistent reservoirs of susceptible hosts requiring antimicrobial intervention against opportunistic protozoan infections.
- Sanitation Infrastructure Gaps:Fecal-oral transmission reservoirs persist across Southeast Asian and Latin American geographies where water treatment deficits sustain Balantidium coli environmental presence and drive recurrent clinical demand.
Market Restraints
- API Sourcing Concentration:Active pharmaceutical ingredient production for metronidazole and tetracycline concentrates in Indian and Chinese manufacturing clusters, exposing formulators to export restriction risks and geopolitical supply interruptions.
- FDA Bioequivalence Barriers:Stringent FDA bioequivalence standards and WHO prequalification requirements limit manufacturer eligibility for institutional procurement channels in endemic countries, compressing viable supplier pools.
- Generic Substitution Pressure:Commodity oral tetracycline volumes dominate outpatient settings where Sandoz AG and similar cost-focused competitors erode branded antiprotozoal margin structures through aggressive pricing.
Strategic Opportunities
- Combination Therapy Protocol Expansion:Resistance surveillance intensification across endemic regions positions multidrug regimens as the fastest-expanding treatment segment, creating formulation differentiation opportunities beyond single-agent commoditization.
- Intravenous Delivery Infrastructure:Limited infusion infrastructure in rural endemic zones presents white space for oral bioavailability-enhanced formulations that match IV efficacy without cold chain or clinical administration requirements.
- EPA Environmental Compliance Services:EPA environmental discharge rules governing metronidazole manufacturing effluent create adjacent revenue streams for treatment technology providers serving API producers in regulated jurisdictions.
Industry Challenges
- Resistance Surveillance Capability Gaps:Clinical microbiology laboratories in endemic regions lack standardized susceptibility testing protocols for Balantidium coli, forcing empiric therapy selection and complicating outcome measurement for new regimen introductions.
- Prequalification Timeline Compression:WHO prequalification status changes alter preferred protocol design and supplier positioning unpredictably, requiring manufacturers to maintain parallel regulatory track investments across multiple national pharmaceutical regulators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Balantidiasis Treatment Market |
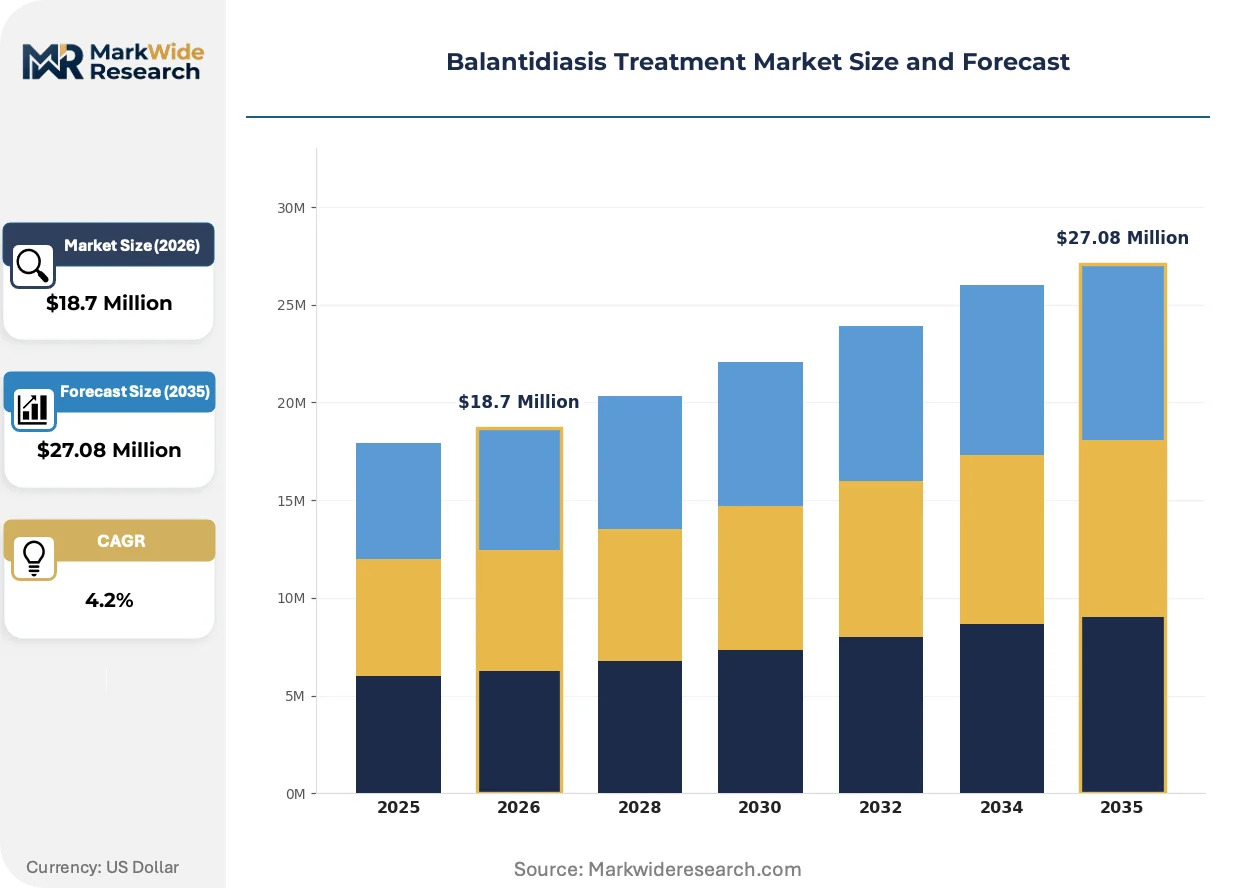
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $27.08 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antimicrobials, Antibiotics, Antiprotozoals, Supportive Therapies Delivery Mode: Oral, Intravenous, Topical, Inhalation End User: Hospitals, Outpatient Clinics, Homecare, Research Laboratories Treatment Protocol: Monotherapy, Combination Therapy, Symptomatic Treatment, Preventive Care |
| Companies Covered | Pfizer Inc., Abbott, Johnson & Johnson Services, Inc., GlaxoSmithKline plc, Sandoz AG, Sanofi, 3M, Koninklijke Philips N.V., Siemens Healthcare Private Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Balantidiasis Treatment Market Strategic Shifts
Antimicrobial stewardship pressures and resistance surveillance intensification are actively reshaping protocol design in balantidiasis treatment, with clinicians and procurement officers demanding greater evidence granularity to justify regimen selection beyond historical empiric practice patterns.
Pharmacokinetic modeling platforms are unifying dosing optimization across immunocompromised patient subpopulations with altered drug metabolism. Hospital pharmacy departments in Thai and Vietnamese tertiary centers are adopting these tools to reduce treatment failure rates in HIV-coinfected cases. This technology is unifying previously fragmented specialty society guidelines into algorithmic decision support embedded in electronic health record systems.
REACH registration requirements and EU Green Deal pharmaceutical manufacturing sustainability mandates are tightening active pharmaceutical ingredient environmental release standards. European formulators sourcing metronidazole from Indian subcontractors now face extended supplier qualification timelines and third-party audit obligations. Oral tetracycline product categories face the steepest compliance cost escalation as effluent treatment investments concentrate in high-volume generic manufacturing sites.
Institutional procurement officers in Brazilian and Colombian hospital networks are consolidating antiprotozoal purchasing through centralized ministry of health tenders that bundle balantidiasis therapeutics within broader antimicrobial category contracts. This channel compression displaces traditional distributor intermediaries and forces direct manufacturer engagement with national regulatory authorities for prequalification maintenance. The behavioral shift is most visible in Andean public health systems where fiscal austerity measures accelerate procurement centralization.
Balantidiasis Treatment Market Segmentation
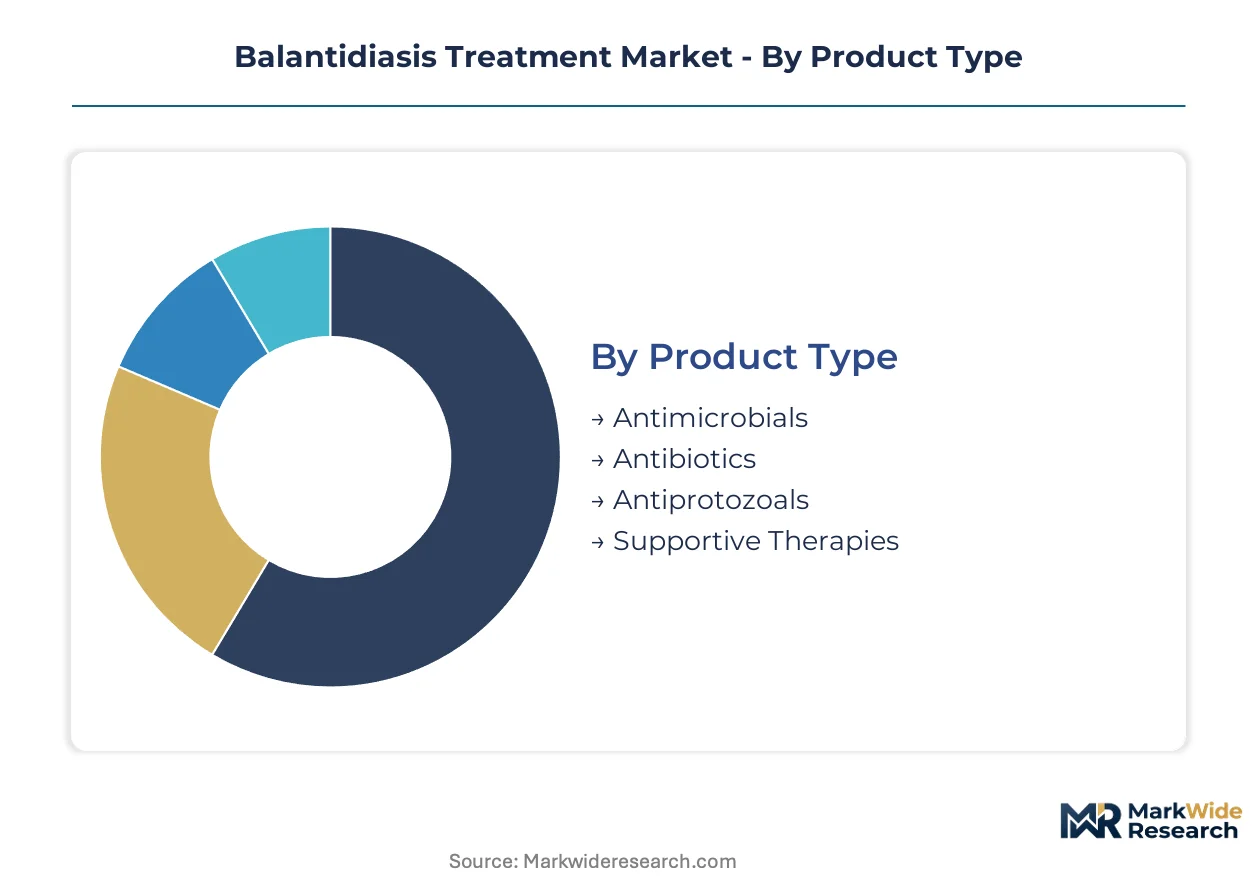
Segmentation in the balantidiasis treatment market reveals how procurement patterns diverge between high-volume commodity antibiotics and premium antiprotozoal formulations. Understanding these splits enables manufacturers to align R&D investment and regulatory strategy with channel-specific margin structures.
Product Type:
Volume concentrates in established antibiotic classes, while premium positioning clusters around specialized antiprotozoal agents with WHO prequalification status.
- Antimicrobials:Broad-spectrum agents targeting bacterial co-infections alongside primary protozoan eradication. Demand concentrates in Southeast Asian hospital networks where empiric therapy protocols dominate due to limited laboratory diagnostic capacity.
- Antibiotics:Tetracycline derivatives and nitroimidazole analogs form the backbone of standard care regimens. Oral formulations drive outpatient volumes across Latin American public health systems confronting sanitation infrastructure gaps.
- Antiprotozoals:Targeted agents with specific Balantidium coli activity profiles command institutional procurement premiums where resistance surveillance has intensified.
- Supportive Therapies:Electrolyte replacement and anti-diarrheal adjuncts complete treatment courses in severe dysentery presentations.
Today's leader: Antibiotics. Tomorrow's challenger: Antiprotozoals.
Delivery Mode:
Route selection tracks healthcare infrastructure maturity, with oral dominance yielding to intravenous alternatives only where infusion capacity exists.
- Oral:Bioavailable tablets and capsules enable outpatient completion of seven-to-ten-day eradication courses. Homecare adoption accelerates in Brazilian and Colombian municipalities with community health worker programs.
- Intravenous:Hospital-confined administration for severe colitis cases requiring inpatient monitoring. Thai tertiary centers maintain cold chain infrastructure supporting IV metronidazole stocking.
- Topical:Limited application in cutaneous manifestations of disseminated infection.
- Inhalation:Experimental delivery exploration for respiratory complication management.
Oral delivery retains structural dominance where rural clinic networks lack infusion infrastructure.
End User:
Procurement authority concentrates in institutional buyers, with homecare emerging as a cost-containment channel for stable patients.
- Hospitals:Tertiary centers in Vietnam and the Philippines anchor volume through centralized pharmacy formulary decisions. CDC screening mandates in endemic zones directly shape prescription patterns.
- Outpatient Clinics:Primary care gatekeepers in urban Latin American districts manage uncomplicated cases with generic tetracycline protocols.
- Homecare:Community-based administration programs expand in Brazilian favela districts with documented transmission reservoirs.
- Research Laboratories:Reference facilities in Bangkok and São Paulo maintain susceptibility testing capabilities for resistance surveillance protocols.
Hospital procurement commands the largest revenue share; homecare represents the steepest expansion trajectory as payers push cost downward.
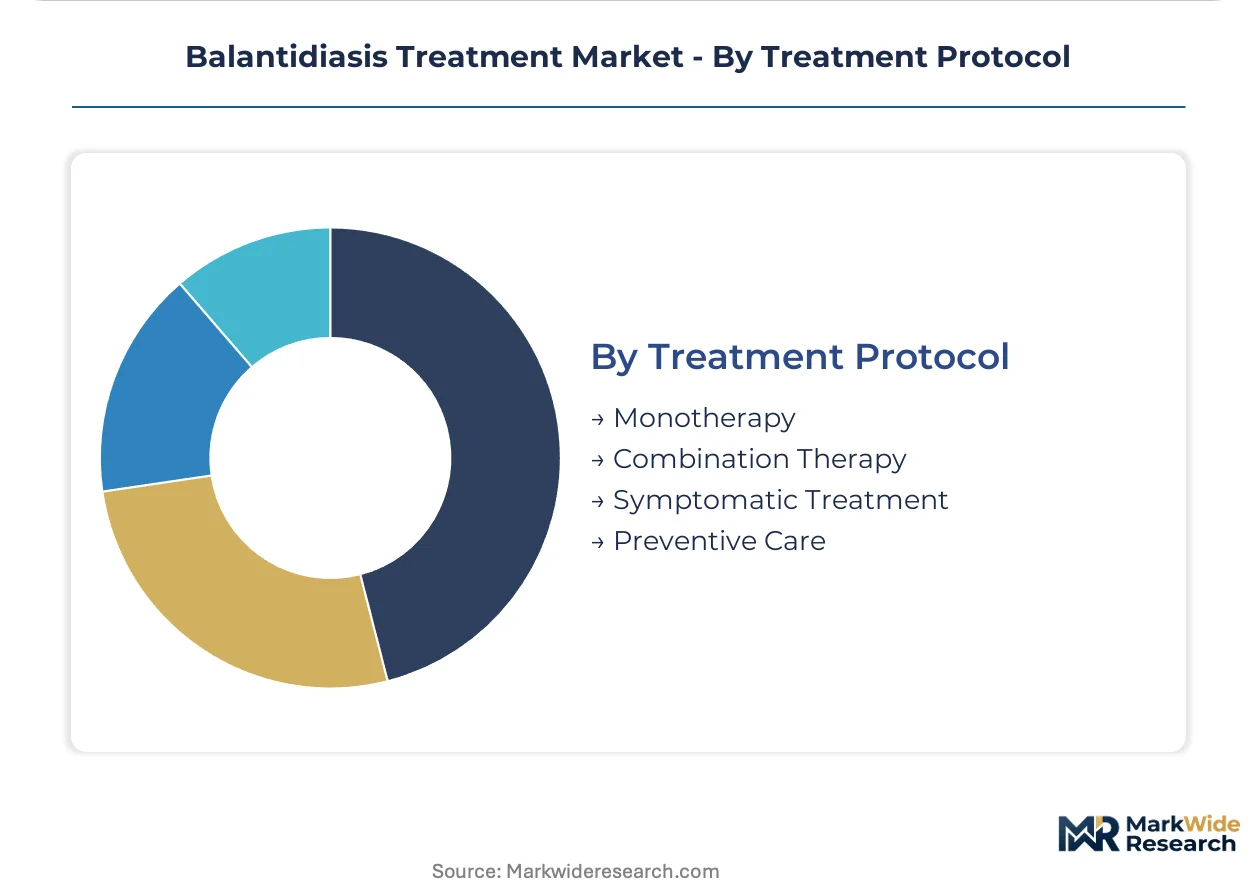
Treatment Protocol:
Protocol complexity escalates as resistance surveillance intensifies, shifting clinical practice from historical empiricism toward evidence-based multidrug regimens.
- Monotherapy:Single-agent tetracycline or metronidazole courses retain dominance in resource-constrained settings with limited diagnostic confirmation.
- Combination Therapy:Multidrug regimens pairing nitroimidazoles with tetracycline derivatives gain traction where treatment failure rates have climbed. Vietnamese infectious disease specialists increasingly favor sequential administration protocols.
- Symptomatic Treatment:Rehydration and nutritional support for patients deferring or unable to access antimicrobial therapy.
- Preventive Care:Mass drug administration pilots in hyperendemic Philippine barangays test community-level interruption strategies.
Monotherapy maintains volume leadership; combination therapy is gaining share fastest among academic medical centers with microbiology laboratory support.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Infectious disease specialists concentrate in Southeast Asian hospital networks and Latin American public health systems where Balantidium coli transmission persists through sanitation infrastructure deficits. Clinical demand clusters where WHO neglected tropical disease programs intersect with national CDC screening mandates.
Philippines
Community health workers in hyperendemic barangays drive mass drug administration pilots targeting fecal-oral transmission reservoirs. The Department of Health integrates balantidiasis screening into existing intestinal parasite control programs. Metro Manila hospital networks anchor institutional procurement volumes for tetracycline-class protocols.
Vietnam
HIV-coinfected patients in Ho Chi Minh City tertiary centers create persistent demand for antimicrobial intervention against opportunistic protozoan infections. Pharmacokinetic modeling platforms unify dosing optimization across immunocompromised subpopulations. Vietnamese infectious disease specialists increasingly favor sequential combination therapy administration protocols.
Brazil
Fiscal austerity measures accelerate procurement centralization through Ministry of Health tenders bundling antiprotozoals within broader antimicrobial category contracts. ANVISA registration requirements govern metronidazole manufacturing quality for institutional channel access. São Paulo and Rio de Janeiro hospital networks displace traditional distributor intermediaries through direct manufacturer engagement.
Thailand
Bangkok reference laboratories maintain standardized susceptibility testing capabilities for resistance surveillance protocols. Thai tertiary centers adopt algorithmic decision support embedded in electronic health record systems. Cold chain infrastructure in Bangkok hospital networks supports IV metronidazole stocking for severe colitis presentations.
Balantidiasis Treatment Market Competitive Environment
Top-tier vendors anchor institutional procurement channels, while cost-focused generics compete for outpatient volume share. The vendor base spans multinational pharmaceutical conglomerates with tropical medicine portfolios and specialized antiprotozoal manufacturers. Three archetypes dominate: scale-driven essential medicine suppliers, nitroimidazole specialists, and broad-spectrum antibiotic formulators. Competitive moves concentrate on WHO prequalification maintenance and direct engagement with centralized ministry tenders.
Among diversified pharmaceutical conglomerates, Pfizer Inc. and Sanofi occupy positions reflecting manufacturing scale and tropical medicine specialization respectively. Sandoz AG exemplifies the cost-competitive archetype dominating oral tetracycline volumes in outpatient settings. Johnson & Johnson Services, Inc. represents the diversified health science structure spanning therapeutic and diagnostic capabilities. These three anchors illustrate how regulatory compliance capacity and procurement channel access separate viable competitors from marginal participants.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Abbott |
| Johnson & Johnson Services, Inc. |
| GlaxoSmithKline plc |
| Sandoz AG |
| Sanofi |
| 3M |
| Koninklijke Philips N.V. |
| Siemens Healthcare Private Limited |
| Others |
Value Chain & Pricing Dynamics
Captive API manufacturing in Indian and Chinese chemical parks anchors both supply security and pricing power for metronidazole and tetracycline formulators. This backward integration choice insulates institutional contract holders from spot-market volatility while compressing margins for pure-play distributors lacking upstream control.
Pricing Analysis
Bundled ministry tenders in Brazil and Colombia package balantidiasis therapeutics within broader antimicrobial category contracts, eroding standalone product premiums. Price differentiation rests on WHO prequalification status and cold-chain delivery capability. Cost compression in oral generic tetracyclines is intensifying because Sandoz AG and similar volume competitors prioritize market share over margin. Outpatient clinics in Latin American municipalities exhibit the highest price sensitivity; tertiary hospital networks in Southeast Asia demonstrate lowest sensitivity due to formulary lock-in.
Supply Chain Analysis
Reverse-logistics flows for temperature-compromised IV metronidazole shipments remain underdeveloped across Southeast Asian rural clinic networks, forcing write-offs rather than refurbishment. Active pharmaceutical ingredient production concentrates in India, China, and select European specialist facilities. Finished formulation draws from tetracycline fermentation feedstocks and nitroimidazole chemical synthesis precursors. Single-source vulnerability in Indian API clusters exposes formulators to export restriction risks. Distribution runs through centralized ministry procurement channels that displace traditional pharmaceutical distributors in Brazilian and Colombian public health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in balantidiasis treatment rests on the shift toward combination therapy protocols that command premium positioning over commoditized single-agent regimens. Cost-down pressure from generic substitution simultaneously compresses outpatient antibiotic margins.
For Market Incumbents: Deploy pharmacokinetic modeling platforms to differentiate dosing optimization services for HIV-coinfected patient subpopulations. Secure ANVISA and WHO prequalification status across multiple tetracycline and nitroimidazole SKUs to defend against emerging Indian API-to-formulation integrators. Channel control through direct ministry engagement in Brazil and Colombia insulates against distributor displacement. For New Entrants and Emerging Players: Resistance surveillance technology-first wedges open procurement doors at Vietnamese and Thai academic medical centers seeking algorithmic decision support. Target oral bioavailability-enhanced formulation development as the most penetrable white space where rural endemic zones lack IV infrastructure. Pursue joint development agreements with Bangkok reference laboratories to embed susceptibility testing capabilities into commercial protocols. For Investors and Strategic Acquirers: Consolidation pressure builds where WHO prequalification timelines compress viable supplier pools below sustainable fragmentation levels. Long-term viability favors manufacturers with captive API supply and tropical medicine portfolio diversification. Acquisition target archetypes include mid-cap antiprotozoal specialists with existing Southeast Asian hospital network contracts. Monitor ANVISA registration queue velocity as an early signal of competitive access shifts in Latin America's largest public health market.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway | Unlocks institutional procurement channels in endemic country ministry tenders. |
| Combination Therapy Formulation Development | Positions multidrug regimens as premium alternatives to single-agent commoditization. |
| Backward Integration into API Manufacturing | Insulates margin structure from Indian and Chinese export restriction volatility. |
| Pharmacokinetic Platform Licensing | Captures value from HIV-coinfected dosing optimization demand in Thai and Vietnamese centers. |
| Centralized Ministry Partnership | Secures volume commitments through Brazilian and Colombian antimicrobial category bundling. |
Study Parameters
Multiple input streams — infectious disease specialist interviews, hospital pharmacy procurement data, and regulatory filing analysis — were reconciled to construct segment-level demand estimates. Primary discussions engaged formulary directors at Vietnamese and Filipino tertiary centers, ANVISA regulatory affairs leads, and Brazilian Ministry of Health tender administrators. Secondary validation drew from WHO prequalification listings, FDA bioequivalence determinations, and national pharmaceutical trade statistics. Bottom-up prescription volume modeling and top-down public health expenditure allocation were cross-referenced for convergence.
Historical resistance surveillance trends were cross-referenced against specialist panel input to anchor protocol shift assumptions across the projection horizon. Segmentation dimensions modeled include product type, delivery mode, end user channel, and treatment protocol complexity. CAGRs were derived from trend extrapolation moderated by procurement centralization timelines. Forecast inputs incorporated HIV prevalence trajectories in endemic regions and EPA environmental compliance cost escalation for API manufacturers.
The model holds under sustained WHO essential medicine list placement and stable Indian API export policies; deviation in prequalification timeline compression or geopolitical trade restriction intensity would shift supplier competitive positioning. Practitioners should monitor ANVISA registration approval velocities and Thai susceptibility testing protocol standardization for early signals of market access restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Idiopathic Thrombocytopenic Purpura Therapeutics Market
Specialty Medicine
Premature Ejaculation Treatment Market
Specialty Medicine
Vitiligo Treatment Market
Specialty Medicine
Chronic Idiopathic Constipation Treatment Market
Specialty Medicine
Cellulitis Management Market
Specialty Medicine
Cirrhosis Management Market
Specialty Medicine
Multiple Sclerosis Market
Specialty Medicine
Musculoskeletal System Disorders Market
Specialty Medicine
Global Scleroderma Therapeutics Market
Specialty Medicine
Severe Combined Immunodeficiency Market
Specialty Medicine
Hereditary Angioedema Market
Specialty Medicine
Anaplastic Astrocytoma Market
Specialty Medicine
US Actinic Keratosis Treatment Market
Specialty Medicine
Gingivostomatitis Market
Specialty Medicine
Cerebral Vein Thrombosis Treatment Market
Specialty Medicine
Parathyroid Disorders Market