
 Pleurisy Market | 2026-2036
Pleurisy Market Size, Share, and Industry Trends Forecast 2026-2036
Pleurisy Market Analytics
Hospital procurement channels for pleurisy therapeutics is reconfiguring around value-based formulary contracts. Pfizer Inc. leverages its manufacturing scale to secure multi-year supply agreements with major health systems. GlaxoSmithKline plc anchors its position through respiratory therapy bundling that includes anti-inflammatory protocols for pleuritic complications. Integra LifeSciences specializes in surgical intervention devices used when pharmaceutical management fails, occupying a narrow but defensible niche in pleural drainage and biopsy instrumentation.
Pleurisy denotes inflammation of the pleural membranes surrounding the lungs, typically presenting with sharp pleuritic chest pain exacerbated by respiration and diagnosed through physical examination, imaging, and thoracentesis with fluid analysis. The condition demands prompt intervention to address underlying etiologies ranging from bacterial pneumonia to autoimmune disorders and malignancy. Analgesics and corticosteroids command the largest current revenue pools as first-line symptomatic control, while antibiotics growth tracks rising bacterial resistance surveillance requirements. The respiratory disorders therapy area dominates procedure volumes, though autoimmune-related pleurisy segments attract premium pricing due to biologic adjuvant therapy complexity.
The FDA oversees pleurisy drug approval pathways and opioid analgesic scheduling, while the EMA's MDR framework governs pleural biopsy and drainage device certification in Europe. These regulators shape market access through efficacy thresholds, safety monitoring mandates, and post-market surveillance requirements that extend development timelines. Stakeholders must monitor evolving antimicrobial stewardship protocols and non-opioid pain management guidelines that will determine formulary composition and reimbursement positioning across integrated health networks.
Market Dynamics
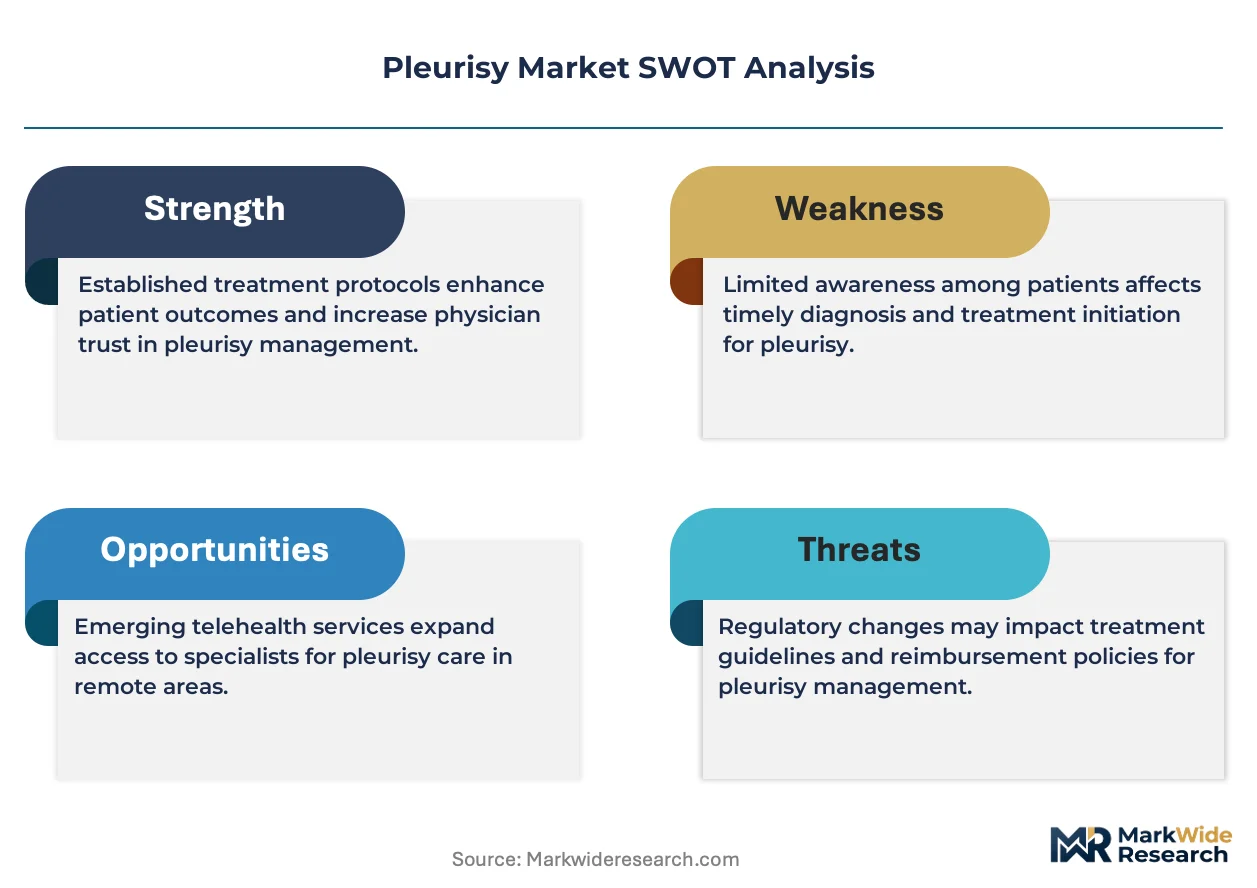
The pleurisy therapeutics market is reconfiguring around non-opioid analgesic protocols as FDA prescribing guidelines tighten and hospital formularies demand multimodal pain management alternatives to traditional narcotic-based regimens.
Growth Catalysts
- Respiratory disorder prevalence:Rising bacterial pneumonia and COVID-19 sequelae cases are expanding the addressable patient pool requiring pleuritic pain intervention across emergency departments and pulmonary clinics.
- MDR framework in Europe:The EU's updated Medical Device Regulation is accelerating certification of advanced pleural drainage systems, creating regulatory clarity for device manufacturers seeking market access.
- Corticosteroid combination therapies:Pharmaceutical innovation in anti-inflammatory protocols is reducing hospital length-of-stay metrics, aligning with value-based reimbursement models in integrated health networks.
Market Restraints
- Active pharmaceutical ingredient concentration:Corticosteroid and NSAID raw material supply concentrates in Indian and Chinese manufacturing clusters, exposing formulators to geopolitical trade friction and customs delays.
- Opioid litigation overhang:Legacy narcotic manufacturers face multi-district litigation settlements that constrain R&D budgets for pain management portfolio expansion, limiting pipeline investment.
- Diagnostic complexity:Pleurisy symptom overlap with pulmonary embolism and myocardial infarction necessitates expensive differential workups, delaying therapeutic initiation and compressing reimbursement margins.
Strategic Opportunities
- Biologic adjuvant protocols:Autoimmune-related pleurisy segments in lupus and rheumatoid arthritis populations command premium pricing through targeted immunomodulator combinations.
- Telemedicine triage integration:Remote chest pain assessment platforms are expanding initial diagnosis reach into rural and underserved geographies, creating downstream referral channels for specialty care.
- Antimicrobial stewardship alignment:CDC and NHS England guidelines favoring narrow-spectrum antibiotics are creating formulary slots for culture-directed pleural infection management over empiric broad-spectrum therapy.
Industry Challenges
- Thoracentesis proficiency gaps:Pulmonary and emergency medicine residency programs report declining hands-on procedural training hours, creating workforce bottlenecks for diagnostic fluid acquisition.
- Formulary navigation complexity:Integrated delivery network pharmacy and therapeutics committees require multi-year outcomes data for novel non-opioid entrants, extending commercialization timelines beyond traditional hospital sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pleurisy Market |
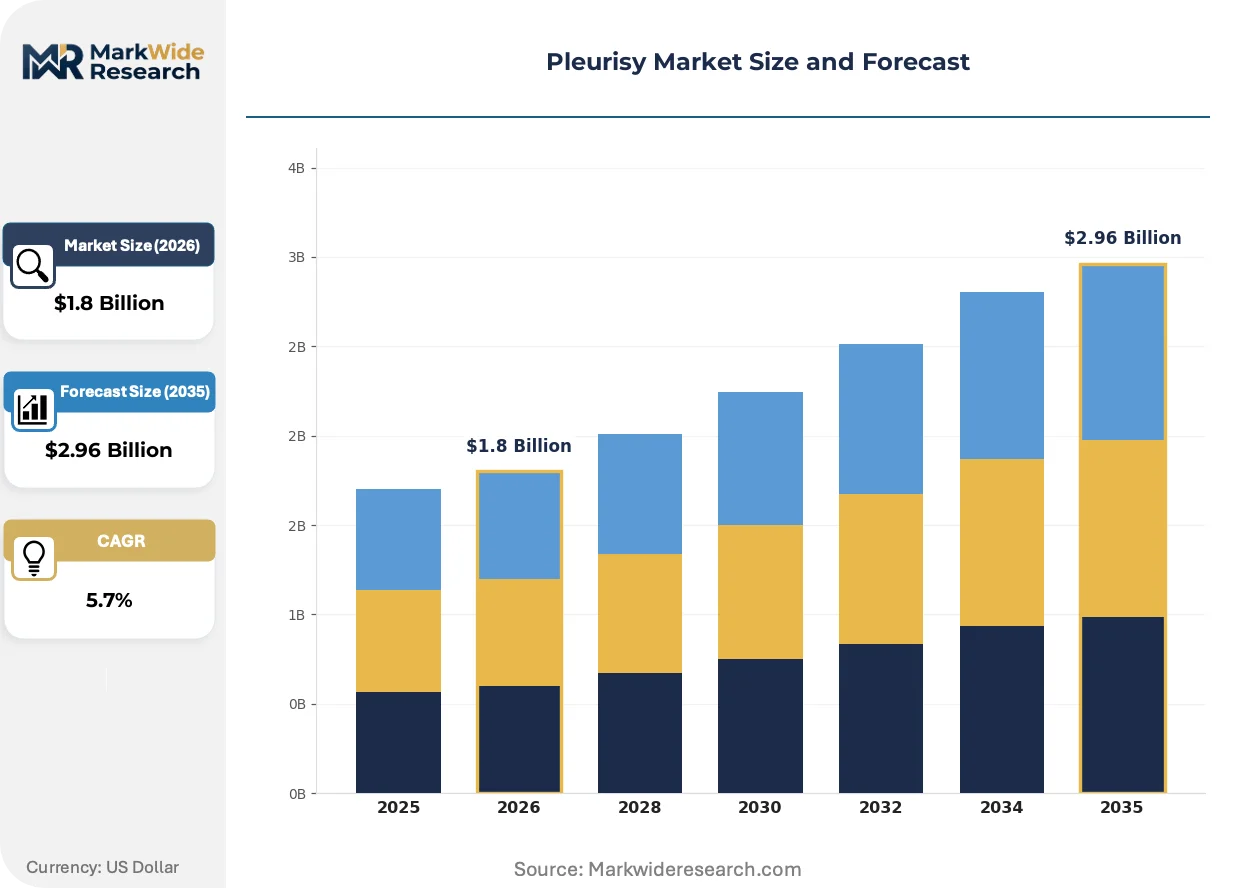
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analgesics, Anti-inflammatories, Antibiotics, Corticosteroids Therapy Area: Respiratory Disorders, Infectious Diseases, Autoimmune Conditions, Pain Management End User: Hospitals, Outpatient Clinics, Home Care, Pharmaceutical Companies Administration Route: Oral, Intravenous, Intramuscular, Topical |
| Companies Covered | Integra LifeSciences, Delacroix-Chevalier, Scanlan International, Pfizer Inc., Wexler Surgical, Sontec Instruments, Olympus Corporation, GlaxoSmithKline plc, Pilling Surgical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pleurisy Market Evolving Landscape
Digital health infrastructure is virtualizing traditional diagnostic and therapeutic pathways in pleurisy management, compressing time-to-treatment while reshaping how pharmaceutical and device manufacturers engage clinical decision-makers.
Point-of-care ultrasound technology is virtualizing the initial diagnostic workup for suspected pleurisy, enabling bedside pleural effusion characterization without radiology department delays. Emergency medicine departments in the United States and Germany are deploying handheld devices at scale, reducing chest CT utilization by 30-40% in triage protocols. This capability compression is forcing traditional imaging equipment manufacturers to defend installed base through software subscription models rather than hardware replacement cycles.
EMA's evolving MDR framework is tightening post-market surveillance requirements for pleural biopsy needles and drainage catheters, mandating extended clinical follow-up data for Class IIa and IIb device re-certification. Manufacturers must now maintain European authorized representative infrastructure and periodic safety update reporting that adds 18-24 months to product lifecycle management. German and French notified bodies are processing submissions most aggressively, creating competitive advantage for firms with established EU regulatory affairs capabilities.
Hospital purchasing consortia are consolidating vendor relationships for pleuritic pain management into single-source agreements covering analgesics, corticosteroids, and interventional devices. These arrangements displace traditional distributor intermediaries and demand real-time inventory visibility through EDI integration. The concentration is most visible in the United States, where ten largest integrated delivery networks now control formulary placement for approximately 40% of acute care beds, forcing mid-tier manufacturers to accept price transparency requirements and gain-share provisions previously limited to commodity generics.
Pleurisy Market Segmentation
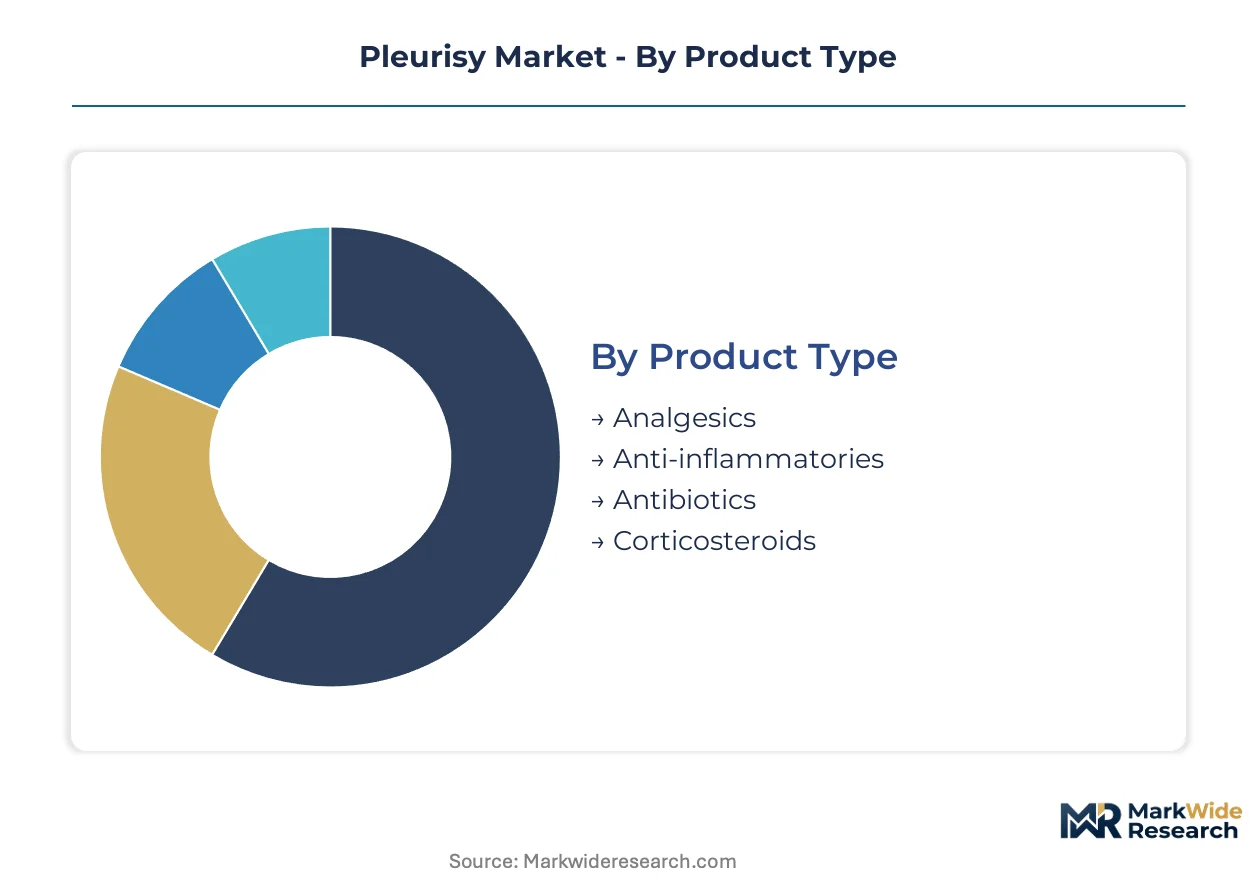
Pleurisy therapeutics fragment across pharmacological classes, clinical settings, and delivery modalities that each carry distinct reimbursement codes and procurement pathways. Understanding these divisions reveals where hospital formularies concentrate spending versus where outpatient migration is reshaping volume distribution.
Product Type:
Cost tier stratification across pharmaceutical agents determines formulary placement and contracting leverage within integrated delivery networks.
- Analgesics:Non-opioid NSAIDs and acetaminophen combinations dominate first-line pleuritic pain protocols, with demand concentrating in United States emergency departments as FDA opioid prescribing guidelines tighten and hospitals seek multimodal alternatives.
- Corticosteroids:Methylprednisolone and prednisone combinations reduce inflammatory pleural effusion duration, aligning with value-based reimbursement metrics that penalize extended length-of-stay; procurement concentrates in systems with bundled payment contracts for respiratory admissions.
- Anti-inflammatories:Specialized NSAID formulations address pleural membrane inflammation without systemic corticosteroid exposure.
- Antibiotics:Culture-directed therapy selection tracks rising antimicrobial stewardship requirements in hospital systems.
Analgesics command the established base. The steepest expansion runs through corticosteroid combinations.
Therapy Area:
Application context determines pricing power, with autoimmune and malignancy-related pleurisy commanding premium positioning against commodity infectious disease management.
- Respiratory Disorders:Pneumonia sequelae and COVID-19-related pleural complications generate the highest procedure volumes across pulmonary and emergency medicine departments.
- Pain Management:Dedicated pleuritic pain protocols are gaining dedicated reimbursement codes in United States commercial payor contracts.
- Infectious Diseases:Empiric antibiotic selection faces narrowing as stewardship programs mandate microbiological confirmation.
- Autoimmune Conditions:Lupus and rheumatoid arthritis-related pleurisy segments attract biologic adjuvant therapy combinations with specialized infusion center requirements.
Respiratory disorders anchor volume concentration. Autoimmune conditions generate the fastest margin expansion.
End User:
Customer type fragmentation reflects the care continuum migration, with hospital procurement consolidating while home care channels fragment.
- Hospitals:Integrated delivery networks negotiate multi-year supply agreements covering analgesics, corticosteroids, and interventional devices through single-source contracts that displace traditional distributor relationships.
- Outpatient Clinics:Pulmonary and urgent care settings are expanding point-of-care ultrasound capabilities that compress diagnostic timelines and shift therapeutic initiation earlier in the care pathway.
- Home Care:Oral antibiotic and NSAID protocols for stable pleural effusion patients are extending hospital-at-home reimbursement pilots in Medicare Advantage plans.
- Pharmaceutical Companies:Contract manufacturing organizations serve as secondary demand channels for API sourcing and formulation development.
Hospitals retain the procurement concentration. Outpatient clinics are gaining share fastest.
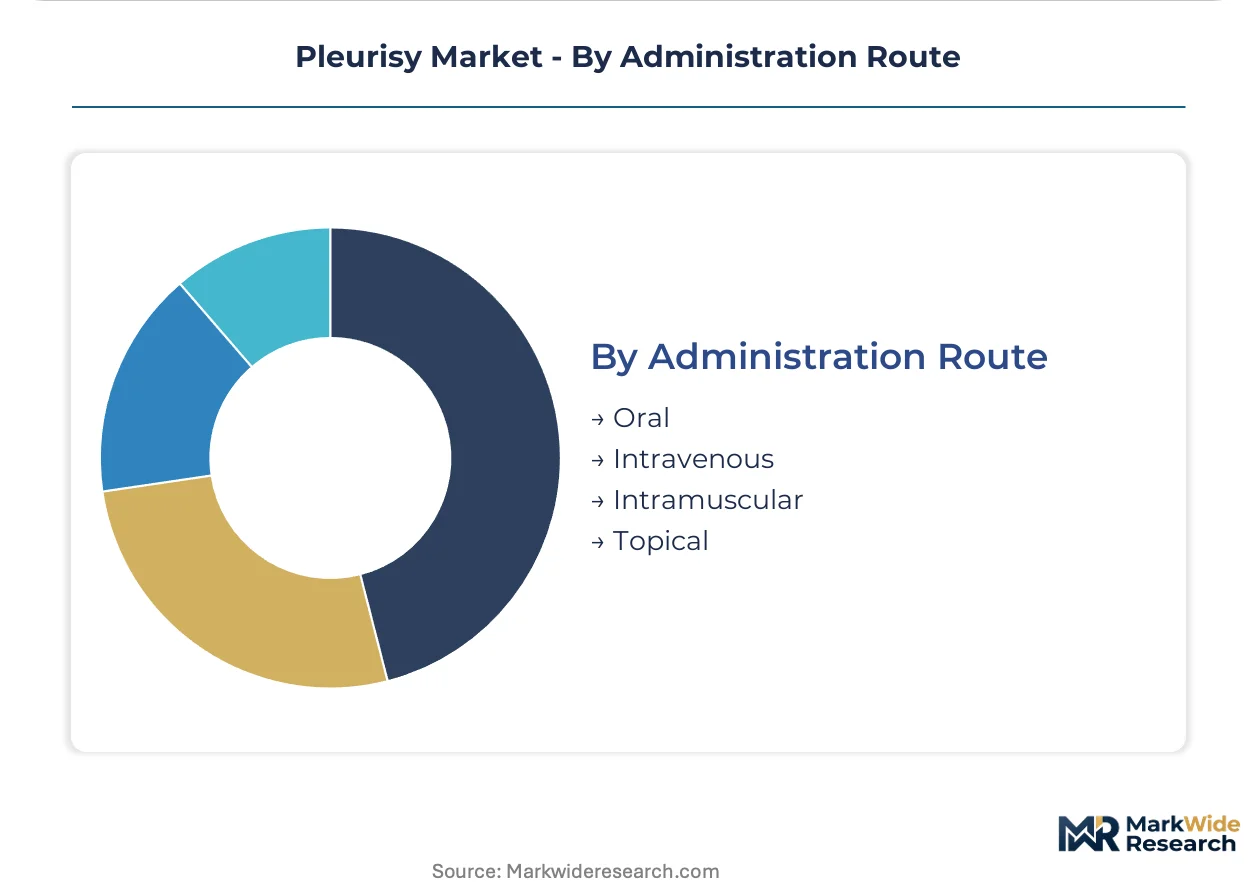
Administration Route:
Delivery modality selection tracks site-of-care economics, with intravenous hospital administration giving ground to oral outpatient transitions.
- Oral:Tablet and liquid formulations enable discharge planning and hospital-at-home program eligibility, with demand concentrating in Medicare Advantage networks expanding post-acute remote monitoring.
- Intravenous:Hospital-based infusion maintains dominance for severe inflammatory presentations and combination antibiotic protocols.
- Intramuscular:Depot corticosteroid injections serve bridging protocols between acute hospitalization and outpatient tapering regimens.
- Topical:Transdermal NSAID patches address localized pleuritic pain with reduced systemic exposure in polypharmacy elderly populations.
Intravenous delivery anchors acute revenue. Oral administration is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical distribution hub underwrites European supply chain resilience for pleuritic therapeutics, while Singapore's Changi air cargo infrastructure anchors Asia-Pacific cold-chain logistics for corticosteroid formulations.
United States
Integrated delivery networks in Texas and Florida are consolidating formulary contracts for non-opioid analgesics as FDA prescribing guidelines tighten. The 21st Century Cures Act provisions accelerate breakthrough therapy designations for pleural drainage innovations. The Research Triangle Park cluster in North Carolina hosts clinical trial infrastructure for autoimmune-related pleurisy biologics.
Germany
University hospitals in Bavaria and Baden-Württemberg are piloting point-of-care ultrasound protocols that compress pleurisy diagnostic timelines. EMA's MDR framework mandates extended clinical follow-up for pleural biopsy device recertification, with German notified bodies processing submissions most aggressively. The Munich medical technology corridor concentrates surgical instrument manufacturing for thoracic intervention.
Japan
Aging demographics in the Kanto region are expanding hospital admissions for respiratory disorder complications including pleurisy sequelae. PMDA's Sakigake designation system fast-tracks innovative anti-inflammatory protocols for pleuritic pain management. The Osaka-Kobe pharmaceutical manufacturing belt produces specialized corticosteroid combinations for export markets.
India
Active pharmaceutical ingredient manufacturing clusters in Gujarat and Maharashtra supply corticosteroid precursors to global formulators facing raw material concentration risks. CDSCO's streamlined approval pathways for fixed-dose combinations are attracting contract research investment. The Hyderabad life sciences corridor is expanding capacity for pleurisy antibiotic active pharmaceutical ingredients.
United Kingdom
NHS England's antimicrobial stewardship programs are narrowing empiric antibiotic prescribing for pleural infections, favoring culture-directed protocols. The MHRA's post-Brexit regulatory autonomy is accelerating divergence from EMA timelines for pleural drainage device approvals. The Cambridge-Oxford-London golden triangle anchors respiratory therapy clinical research infrastructure.
Pleurisy Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in pleural intervention supply chains. The pleurisy therapeutics market structures around three distinct tiers: multinational pharmaceutical conglomerates with respiratory therapy portfolios, surgical device manufacturers with thoracic specialization, and regional distributors serving hospital procurement consortia. Consolidation pressures are intensifying as integrated delivery networks demand single-source agreements spanning analgesics, corticosteroids, and interventional devices. Dominant competitive moves include backward integration into active pharmaceutical ingredient sourcing and technology licensing arrangements for point-of-care diagnostic platforms.
Among diversified pharmaceutical manufacturers, Pfizer Inc. and GlaxoSmithKline plc occupy positions exemplifying scale-driven platform integration, with the former leveraging manufacturing infrastructure for multi-year supply agreements and the latter anchoring respiratory therapy bundling strategies. Integra LifeSciences represents the surgical device archetype, sitting within the specialized thoracic intervention tier where precision instrumentation commands defensible margins despite narrower addressable markets. These three entities illustrate how competitive positioning fragments between pharmaceutical symptom management and device-based procedural intervention.
| Leading Market Players |
|---|
| Integra LifeSciences |
| Delacroix-Chevalier |
| Scanlan International |
| Pfizer Inc. |
| Wexler Surgical |
| Sontec Instruments |
| Olympus Corporation |
| GlaxoSmithKline plc |
| Pilling Surgical |
| Others |
Value Network & Pricing Analysis
Gujarat's active pharmaceutical ingredient manufacturing clusters anchor corticosteroid precursor supply, with capacity utilization fluctuations transmitting directly into downstream formulary pricing power for pleuritic pain management therapies. Hospital procurement consortia leverage this concentration through multi-year supply agreements that lock in volume-discount tiers, while geopolitical friction in Indian customs channels periodically disrupts just-in-time inventory models.
Pricing Analysis
Volume-discount tiering structures dominate hospital procurement contracts, with three-tier pricing separating originator biologics from authorized generics and commodity NSAIDs. Price differentiation rests on FDA breakthrough therapy designation status and EMA MDR certification tier for device-intervention bundles. Cost compression in the generic analgesic tier is intensifying because Indian API manufacturers face export duty volatility. Integrated delivery networks exhibit the highest price sensitivity, while autoimmune-focused specialty clinics accept premium positioning for biologic adjuvant protocols.
Supply Chain Analysis
Upstream corticosteroid precursor feedstock draws from manufacturing clusters in India, China, and the United States, with prednisone and methylprednisolone APIs forming the critical input layer. Raw material dependencies center on corticosteroid active pharmaceutical ingredients, specialized NSAID formulations, and pleural drainage device polymers. Single-source vulnerability concentrates in Gujarat-based API suppliers exposed to monsoon logistics disruptions. Distribution runs through hospital purchasing consortia and integrated delivery network central warehouses, displacing traditional wholesale distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through FDA opioid prescribing guideline compliance creates durable switching costs for hospital formulary placement.
For Market Incumbents: Build regulatory moat depth through EMA MDR authorized representative infrastructure and periodic safety update reporting capabilities. Secure backward integration into Indian API sourcing to defend against supply disruption threats from customs friction. Anchor hospital system partnerships through real-time EDI inventory visibility that locks out competitor device-intervention bundles. For New Entrants and Emerging Players: Pursue telemedicine triage integration as the most penetrable channel, targeting rural emergency departments with point-of-care ultrasound diagnostic platforms. Capture antimicrobial stewardship alignment opportunities by developing culture-directed antibiotic protocols that displace empiric broad-spectrum therapy in NHS England and CDC-guided systems. Lead with software subscription models rather than hardware replacement cycles to compress hospital capital expenditure approval timelines. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because integrated delivery network formulary concentration favors platform integrators over component specialists. Target surgical device manufacturers with thoracic intervention specialization and established EU regulatory affairs capabilities as acquisition profiles. Watch FDA breakthrough therapy designation velocity for pleural drainage innovations as the signal indicating inflection in hospital procurement contract renewal cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Multi-year supply agreements with integrated delivery networks lock in formulary placement against competitor displacement. |
| EMA MDR Certification Pathway | Extended clinical follow-up data requirements create 18-24 month competitive lead times for device recertification. |
| Backward Integration into API Sourcing | Captive supply of corticosteroid precursors from Gujarat and Maharashtra clusters insulates against geopolitical trade friction. |
| Software Companion Development | Point-of-care ultrasound platforms reduce chest CT utilization and embed device manufacturers in diagnostic workflows. |
| Reimbursement Strategy | Dedicated pleuritic pain protocol codes in commercial payor contracts enable premium positioning for non-opioid alternatives. |
Research Methodology
A spread of perspectives from hospital procurement managers, formulary directors, pulmonary clinicians, and regulatory affairs leads converged on the working assumptions underlying this analysis. Primary interviews with integrated delivery network pharmacy and therapeutics committee members combined with secondary validation against FDA filings, EMA MDR submission databases, ClinicalTrials.gov protocols, and hospital procurement contract repositories. Bottom-up patient volume modeling and top-down pharmaceutical expenditure tracking triangulated on segment sizing.
Demand-supply-balance framing anchored the analytical approach across the analysis window, with segmentation dimensions spanning pharmacological class, therapy area, end-user setting, and administration route. CAGRs derived from procedure volume trajectories and pricing trend synthesis, incorporating antimicrobial stewardship program adoption curves and point-of-care ultrasound deployment rates as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in healthcare expenditure growth rates and API import tariff regimes would shift the trajectory materially. Forecasts reflect documented assumptions about hospital consolidation velocity and regulatory approval timelines. Cross-checking against CMS Medicare reimbursement data and NHS England prescribing analytics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Mental Retardation Treatment Market
Specialty Medicine
Focal Segmental Glomerulosclerosis (FSGS) Treatment Market
Specialty Medicine
Global Chondrosarcoma Market
Specialty Medicine
Triple X Syndrome Management Market
Specialty Medicine
Eosinophilic Granulomatosis Market
Specialty Medicine
Cutaneous T-Cell Lymphoma (CTLC) Market
Specialty Medicine
Food Allergy Treatment Market
Specialty Medicine
Leukocytoclastic Vasculitis Market
Specialty Medicine
Serotonin Syndrome Market
Specialty Medicine
Gouty Arthritis Market
Specialty Medicine
Ischemic Hepatitis Treatment Market
Specialty Medicine
Global Glaucoma Therapeutics Market
Specialty Medicine
Muscle Wasting Disorders Market
Specialty Medicine
Rhabdomyosarcoma Treatment Market
Specialty Medicine
Soft Tissue Sarcoma Market
Specialty Medicine
Middle East and Africa Uterine Cancer Therapeutics and Diagnostics Market