
 Myelofibrosis Treatment Market | 2026-2036
Myelofibrosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Myelofibrosis Treatment Market Intelligence
Aftermarket service revenue from patient support programs and companion diagnostics is fragmenting as manufacturers build direct-to-provider channels. Incyte Corporation dominates the JAK inhibitor landscape through its first-mover position in ruxolitinib development. Novartis AG competes by extending its oncology portfolio into combination regimens. Bristol-Myers Squibb Company anchors its presence through sustained investment in immuno-oncology platforms applicable to myeloproliferative neoplasms.
Myelofibrosis treatment encompasses therapeutic interventions targeting a myeloproliferative neoplasm characterized by bone marrow fibrosis, splenomegaly, and constitutional symptoms, with JAK inhibitors functioning through JAK1/JAK2 pathway blockade to reduce spleen volume and symptom burden. The primary commercial purpose centers on modifying disease trajectory while managing transfusion-dependent anemia and improving quality of life in intermediate and high-risk patients. JAK Inhibitors command the dominant revenue share as the established standard of care, while Targeted Therapies represent the fastest-expanding category as novel agents address ruxolitinib-resistant populations. Oral administration routes sustain the largest patient volume due to convenience advantages, though Intravenous delivery retains importance in hospital-based chemotherapy protocols for transformed disease.
The FDA's accelerated approval framework shapes oncology drug development timelines, while EMA's centralized marketing authorization process governs European commercial access. REACH compliance requirements influence the manufacturing supply chain for small-molecule active pharmaceutical ingredients. Stakeholders must monitor emerging Phase III readouts from novel mechanism classes to anticipate shifts in the treatment algorithm and reimbursement positioning.
Market Dynamics
FDA accelerated approval pathways are compressing development timelines for novel mechanism classes, while academic medical centers concentrate Phase III trial capacity in select metropolitan clusters.
Growth Catalysts
- JAK inhibitor protocol expansion:Specialty clinics are building dedicated myeloproliferative neoplasm units to administer ruxolitinib-based regimens. This infrastructure investment pulls patient volume from general oncology practices.
- REACH compliance harmonization:Standardized manufacturing requirements for small-molecule active pharmaceutical ingredients are reducing cross-border regulatory friction. European suppliers are consolidating quality certification processes.
- Companion diagnostic integration:Biomarker-driven patient stratification is improving trial enrollment efficiency. Academic medical centers in Boston and Houston are deploying next-generation sequencing panels to identify JAK2-mutant candidates.
Market Restraints
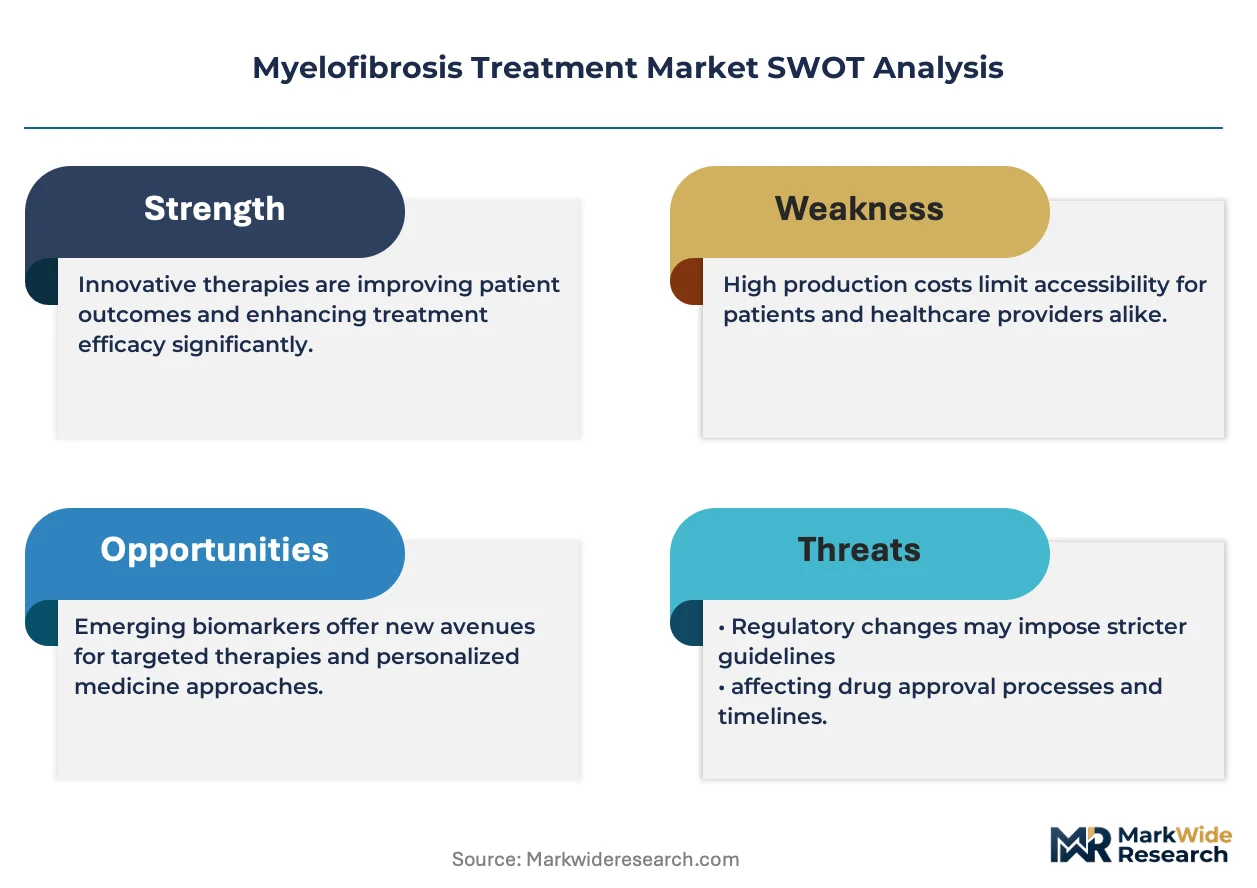
- API supply concentration:Small-molecule manufacturing for JAK inhibitors depends on a limited supplier base in India and China. Disruptions at single-source facilities create bottleneck risk.
- Transfusion dependency burden:Anemia management requires sustained red blood cell support. Hospital-based infusion capacity constraints limit outpatient treatment expansion.
- Resistance mechanism complexity:Secondary mutations in the JAK-STAT pathway drive treatment failure. Salvage options for ruxolitinib-resistant populations remain clinically limited.
Strategic Opportunities
- Underpenetrated European markets:Central and Eastern European countries show diagnostic gap versus Western benchmarks. EMA centralized authorization enables rapid market access post-approval.
- Combination regimen development:Pairing JAK inhibitors with BET inhibitors or PI3K pathway blockers addresses resistance. Early-phase trials at MD Anderson and Memorial Sloan Kettering are generating mechanistic data.
- Direct-to-provider distribution:Manufacturers are bypassing wholesale channels to ship specialty pharmaceuticals directly to infusion centers. This channel innovation captures margin and improves cold-chain control.
Industry Challenges
- Cellular therapy manufacturing scale-up:Allogeneic stem cell transplant programs require GMP-compliant expansion facilities. Capex intensity for cleanroom infrastructure exceeds community hospital capacity.
- Biomarker assay standardization:CALR and MPL mutation testing lacks inter-laboratory harmonization. Diagnostic discordance complicates clinical trial eligibility and reimbursement documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Myelofibrosis Treatment Market |
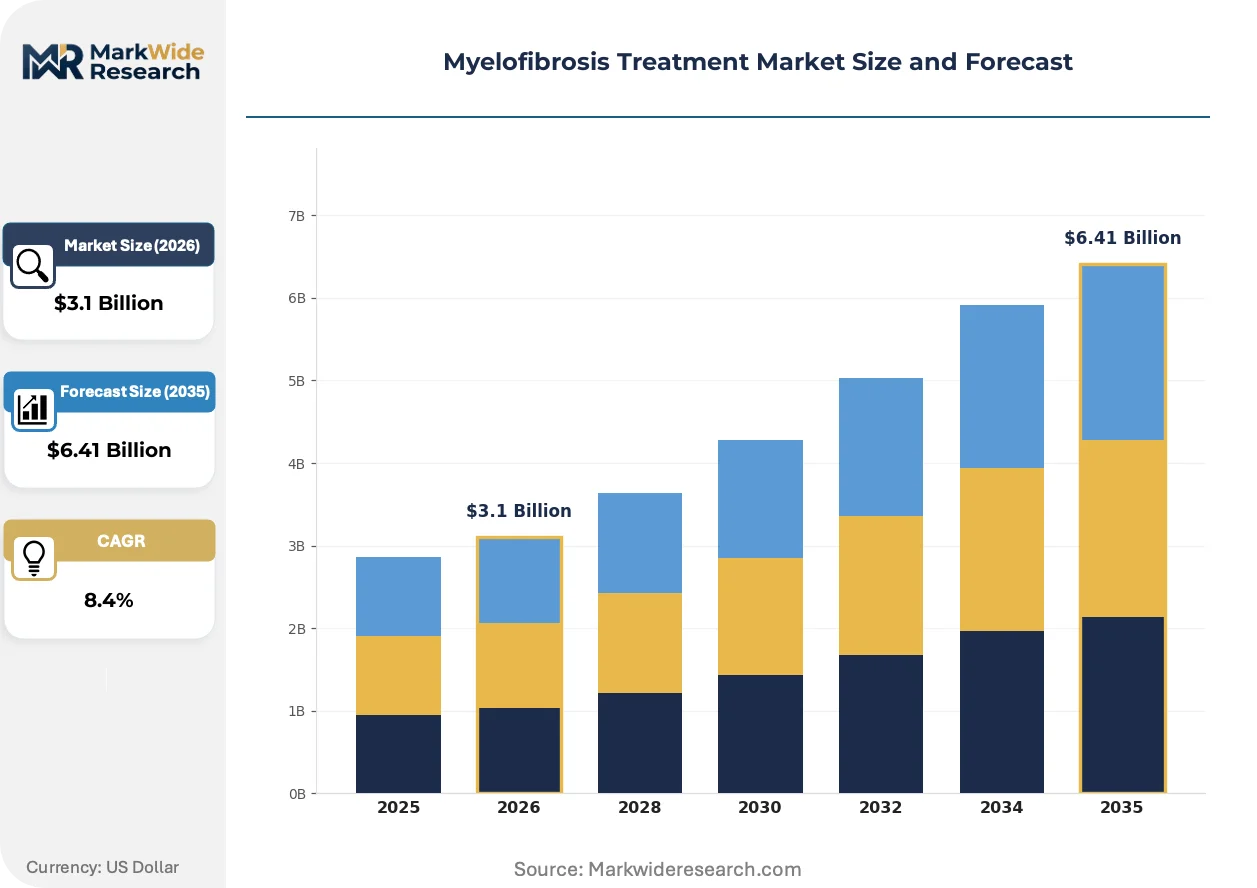
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $6.41 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: JAK Inhibitors, Chemotherapy Agents, Immunotherapy, Targeted Therapies End User: Hospitals, Specialty Clinics, Ambulatory Surgical Centers, Home Healthcare Administration Route: Oral, Intravenous, Subcutaneous, Intramuscular Stage: Preclinical, Phase I, Phase II, Phase III |
| Companies Covered | Incyte Corporation, Novartis AG, Bristol-Myers Squibb Company, Pfizer Inc, GSK, Roche, CTI BioPharma Corp, AbbVie Inc, Merck & Co, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Myelofibrosis Treatment Market Strategic Shifts & Innovations
Novel mechanism classes are disrupting the JAK inhibitor monopoly, while regulatory frameworks adapt to accommodate accelerated evidence generation for rare oncology indications.
Next-generation JAK2-selective inhibitors with reduced myelosuppression profiles are collapsing the safety-tolerability tradeoff that has constrained ruxolitinib dosing. Community oncology practices are adopting these agents for transfusion-dependent patients previously excluded from standard therapy. The therapeutic window expansion is enabling outpatient-first treatment models that reduce hospital admission rates.
EMA's adaptive licensing pathways are creating conditional market access contingent on real-world evidence collection. Pharmaceutical developers are structuring post-authorization study commitments to satisfy both European and FDA requirements simultaneously. Intermediate-risk patient populations benefit most from this regulatory flexibility, as trial designs historically excluded this heterogeneous group.
Specialty pharmacy consolidation is reshaping how oral oncolytics reach patients. Large distributors are acquiring independent oncology pharmacies to control prior authorization workflows and patient adherence monitoring. This channel concentration is most visible in the United States, where pharmacy benefit manager integration creates captive distribution networks for high-cost oral therapies.
Myelofibrosis Treatment Market Segmentation
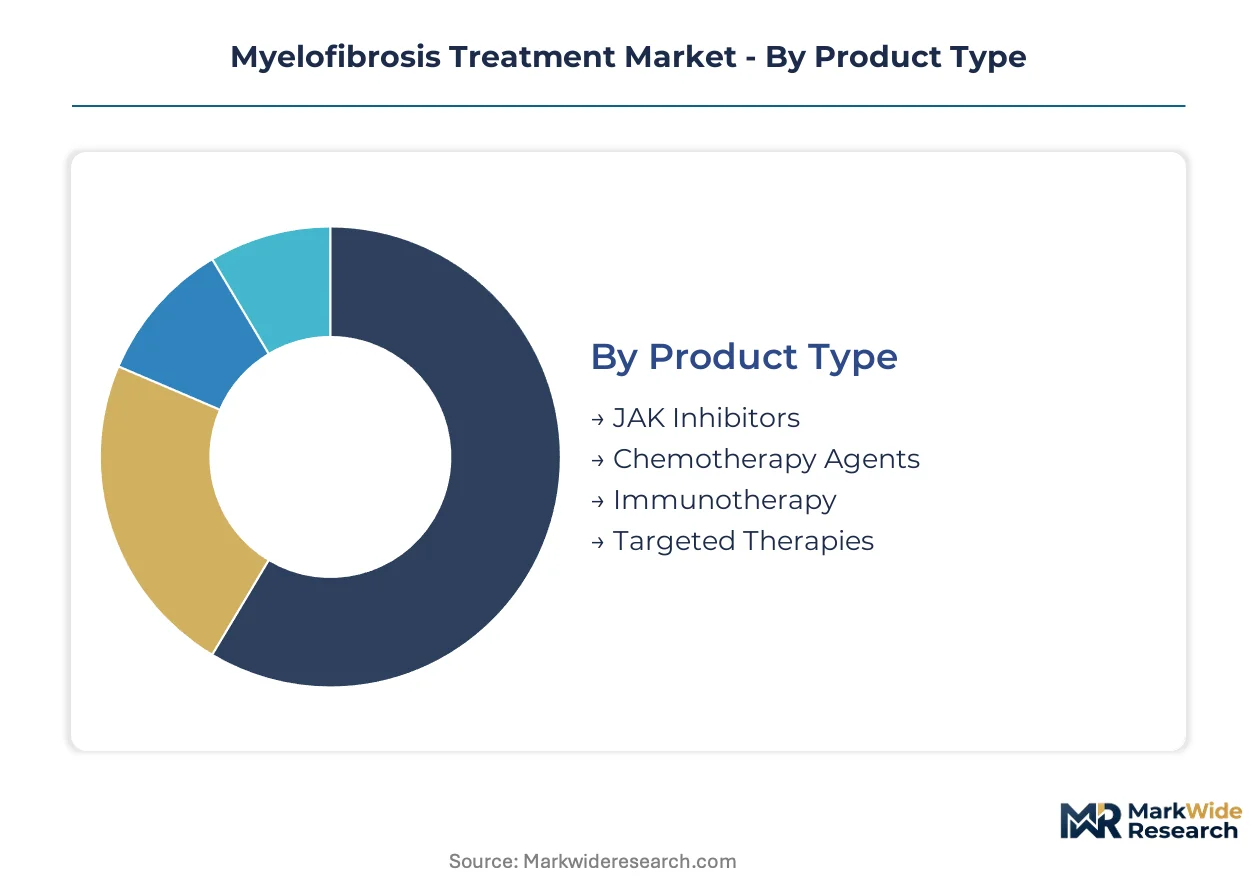
Therapeutic modality selection in myelofibrosis directly shapes after-sales service architecture. Patient support programs, biomarker monitoring infrastructure, and resistance management protocols vary substantially across product categories and care settings.
Product Type:
After-sales service intensity diverges sharply across mechanism classes, with chronic oral therapies demanding sustained adherence monitoring and acute interventions requiring infusion logistics support.
- JAK Inhibitors:Small-molecule agents blocking JAK1/JAK2 signaling dominate current prescribing patterns. Demand concentrates in United States academic medical centers running combination trials, driven by established reimbursement pathways and specialty pharmacy networks.
- Chemotherapy Agents:Cytotoxic regimens retain utility for transformed disease states. Hydroxyurea and cladribine formulations see residual demand in Eastern European markets where JAK inhibitor access remains constrained by payer budgets.
- Immunotherapy:Checkpoint inhibitors and monoclonal antibodies targeting immune evasion mechanisms. Trials at MD Anderson and Memorial Sloan Kettering are evaluating PD-1 blockade in combination with JAK inhibition for resistant populations.
- Targeted Therapies:BET inhibitors, PI3K pathway blockers, and mutant-selective JAK2 inhibitors. These agents are expanding most quickly as salvage options for ruxolitinib-resistant patients with secondary mutations.
JAK Inhibitors hold the largest share; momentum sits with Targeted Therapies.
End User:
Site-of-care economics determine margin capture, with hospital-based infusion centers commanding premium pricing for intravenous regimens while outpatient channels optimize oral therapy fulfillment.
- Hospitals:Academic medical centers anchor Phase III trial enrollment and transplant referral pathways. Transfusion-dependent anemia management requires sustained infusion capacity that community settings rarely replicate.
- Specialty Clinics:Dedicated myeloproliferative neoplasm units are proliferating in metropolitan clusters. Boston and Houston facilities deploy next-generation sequencing panels to stratify JAK2-mutant candidates for protocol enrollment.
- Ambulatory Surgical Centers:Limited penetration due to chemotherapy administration licensing constraints. These sites capture minor volume for diagnostic bone marrow biopsies rather than therapeutic delivery.
- Home Healthcare:Oral JAK inhibitor administration enables remote monitoring models. Specialty pharmacies coordinate directly with patients for adherence tracking and adverse event reporting.
Hospitals retain the dominant share; Specialty Clinics are gaining share fastest.
Administration Route:
Delivery modality shapes cold-chain requirements, with oral formulations permitting decentralized distribution and parenteral routes demanding temperature-controlled logistics.
- Oral:Ruxolitinib and fedratinib tablets sustain the largest patient volume through convenience advantages. United States pharmacy benefit manager networks prioritize oral oncolytics for prior authorization efficiency.
- Intravenous:Essential for chemotherapy protocols and monoclonal antibody delivery. Hospital infusion centers in Germany and France maintain GMP-compliant handling for temperature-sensitive biologics.
- Subcutaneous:Emerging delivery format for investigational agents. Early-phase trials are evaluating patient-administered options to reduce clinic visit burden.
- Intramuscular:Minimal current utilization in myelofibrosis protocols. Reserved for supportive care agents rather than disease-modifying therapy.
Oral administration commands the largest share; Subcutaneous delivery shows the steepest expansion trajectory.
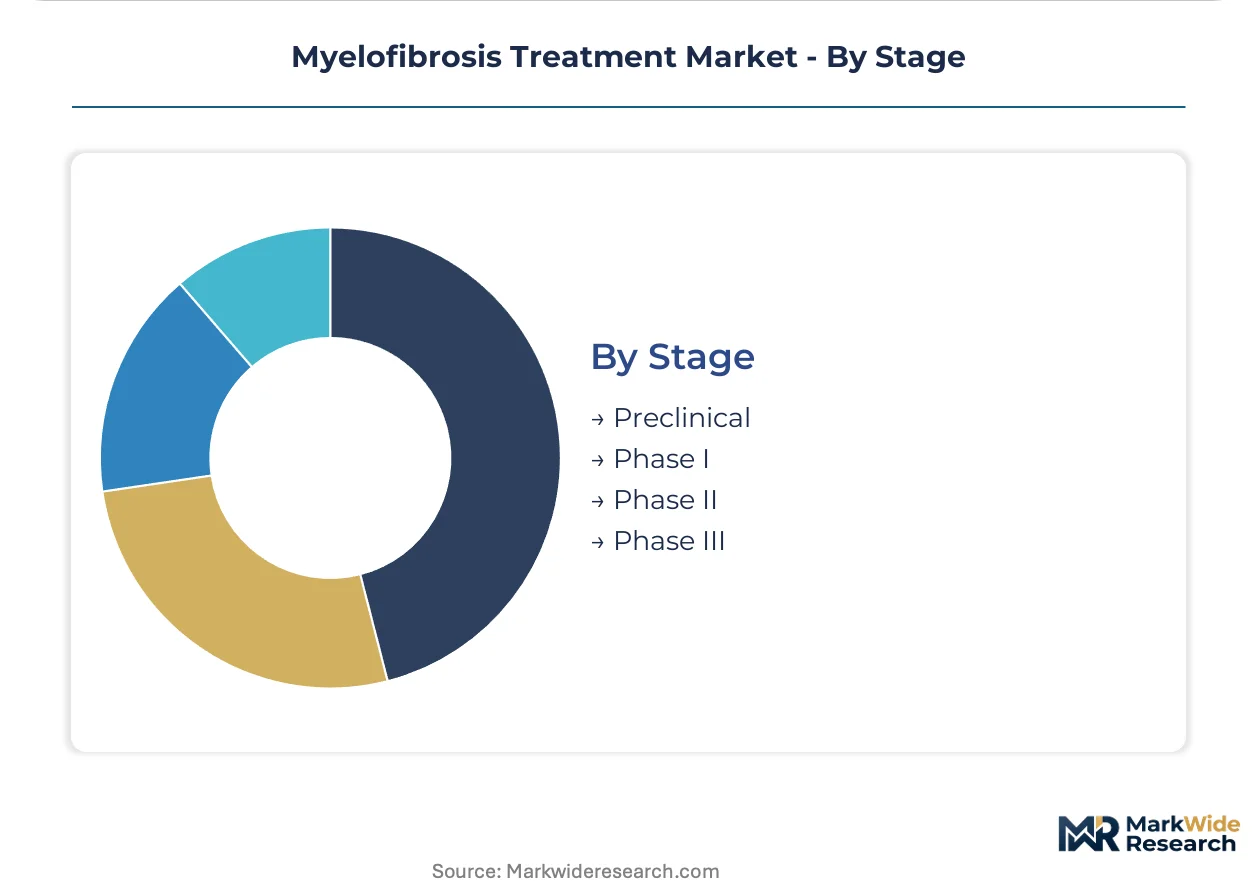
Stage:
Development phase determines commercial accessibility, with late-stage assets commanding valuation premiums and early-phase programs shaping pipeline optionality.
- Preclinical:Novel mechanism classes including LSD1 inhibitors and menin disruptors. Academic laboratories at Johns Hopkins and University of Texas are generating mechanistic data for combination hypotheses.
- Phase I:First-in-human studies for next-generation JAK2-selective agents. Dose-escalation cohorts focus on myelosuppression profiles to differentiate from ruxolitinib tolerability constraints.
- Phase II:Expansion cohorts for BET inhibitor and PI3K blocker combinations. Single-arm efficacy signals inform go/no-go decisions for registrational investment.
- Phase III:Registrational trials for JAK inhibitor successors and novel mechanism classes. FDA accelerated approval pathways compress timelines for spleen volume and symptom burden endpoints.
Phase III assets hold the largest near-term revenue exposure; momentum concentrates in Phase II combination programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for myelofibrosis therapies varies sharply across geographies. United States patients access JAK inhibitors through established specialty pharmacy networks with minimal price sensitivity, while Central and Eastern European markets face budget-constrained formulary restrictions that prioritize hydroxyurea.
United States
FDA accelerated approval pathways compress commercialization timelines for novel mechanism classes. The IRA's Medicare price negotiation provisions reshape long-term revenue projections for oral oncolytics. Academic medical centers in Boston and Houston anchor Phase III trial enrollment for combination regimens.
Germany
Hospital-based infusion centers maintain GMP-compliant handling for temperature-sensitive biologics in transformed disease protocols. EMA centralized authorization enables rapid market access post-approval. The Heidelberg and Munich metropolitan clusters concentrate myeloproliferative neoplasm specialist capacity.
France
ANSM oversight governs compassionate use programs for ruxolitinib-resistant populations awaiting novel agent approval. The country's national pharmaceutical regulator maintains strict pharmacovigilance requirements for JAK inhibitor adverse event reporting. Paris and Lyon academic hospitals deploy next-generation sequencing panels for JAK2-mutant stratification.
United Kingdom
NICE technology appraisals determine NHS reimbursement for high-cost oral therapies. The MHRA's post-Brexit regulatory autonomy enables accelerated access schemes for rare oncology indications. London and Manchester treatment centers participate in international combination trial networks.
Japan
PMDA's Sakigake designation system prioritizes review for next-generation JAK2-selective inhibitors. METI industrial policy supports domestic manufacturing of small-molecule active pharmaceutical ingredients. Tokyo and Osaka academic medical centers generate real-world evidence for EMA adaptive licensing pathways.
Myelofibrosis Treatment Market Key Industry Players
Capability concentration sits with first-mover innovators holding established JAK inhibitor platforms; scale advantage sits with diversified oncology majors leveraging portfolio breadth. The market structure reflects a tiered dynamic where specialized myeloproliferative neoplasm developers compete against broad-based immuno-oncology players. Two strategic archetypes dominate: JAK pathway specialists and combination regimen integrators. Competitive moves center on direct-to-provider distribution channel capture and companion diagnostic co-development partnerships.
Within the JAK inhibitor specialist tier, Incyte Corporation and CTI BioPharma Corp occupy positions defined by mechanism-class depth rather than portfolio diversification. Among diversified oncology majors, Novartis AG and Bristol-Myers Squibb Company exemplify scale-driven strategies that extend existing platforms into myelofibrosis combination protocols. These groupings represent how competitive positioning splits between depth-first and breadth-first market approaches.
| Leading Market Players |
|---|
| Incyte Corporation |
| Novartis AG |
| Bristol-Myers Squibb Company |
| Pfizer Inc |
| GSK |
| Roche |
| CTI BioPharma Corp |
| AbbVie Inc |
| Merck & Co |
| Others |
Cost & Logistics Intelligence
Indian and Chinese API suppliers anchor JAK inhibitor manufacturing, concentrating upstream margin capture in generic small-molecule production while downstream value pools in United States specialty pharmacy networks and European hospital infusion centers. This geographic asymmetry shapes pricing power distribution across the myelofibrosis treatment value chain.
Pricing Analysis
After-sales revenue from patient support programs and companion diagnostic services drives lifetime value for JAK inhibitor manufacturers. Three-tier pricing structure across premium branded, authorized generic, and economy hydroxyurea alternatives segments the market by risk stratification and reimbursement tier. Cost compression in the economy segment intensifies as Central and Eastern European payers prioritize budget-constrained formulary placement. Academic medical centers show lowest price sensitivity due to trial enrollment incentives, while community oncology practices face highest prior authorization friction.
Supply Chain Analysis
Contract manufacturing for small-molecule APIs concentrates at Indian facilities in Hyderabad and Ahmedabad plus Chinese producers in Zhejiang and Jiangsu provinces. Active pharmaceutical ingredient production draws from acetone, palladium catalyst, and specialized solvent feedstocks. Single-source vulnerability at individual FDA-inspected facilities creates bottleneck exposure for JAK inhibitor supply continuity. Distribution runs through direct-to-provider channels that bypass wholesale intermediaries for cold-chain oral oncolytics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The myelofibrosis treatment market functions as a defensive-moat arena where FDA accelerated approval entrenchment and companion diagnostic switching costs protect incumbent positioning against generic erosion.
For Market Incumbents: Insulate JAK inhibitor franchises by deepening backward integration into API manufacturing to reduce Indian and Chinese supplier dependency. Secure companion diagnostic co-development partnerships that lock in biomarker-driven patient stratification protocols, raising switching costs for ruxolitinib-resistant populations seeking next-generation alternatives. For New Entrants and Emerging Players: Pursue Central and Eastern European markets where diagnostic gaps and budget-constrained reimbursement create white-space opportunity for novel mechanism classes. Target specialty clinic partnerships in Boston and Houston metropolitan clusters where next-generation sequencing infrastructure enables rapid trial enrollment and protocol adoption. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed JAK pathway specialists possessing Phase II combination data but lacking commercial infrastructure. Five-to-ten year viability hinges on successful navigation of Medicare price negotiation provisions and EMA adaptive licensing pathways. Watch FDA breakthrough therapy designation grants to next-generation JAK2-selective inhibitors as inflection signal for portfolio reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | Biomarker integration with JAK2 mutation panels at Memorial Sloan Kettering and MD Anderson secures trial enrollment. |
| Direct-to-Provider Distribution | Bypassing wholesale channels captures margin and ensures cold-chain integrity for oral ruxolitinib formulations. |
| API Manufacturing Backward Integration | In-house production of small-molecule inputs reduces dependency on Hyderabad and Zhejiang supplier concentration. |
| EMA Adaptive Licensing Pathway | Conditional market access with real-world evidence commitments accelerates European commercialization timelines. |
| Combination Regimen Pipeline Expansion | BET inhibitor and PI3K blocker pairings address resistance mechanisms in ruxolitinib-failed populations. |
Research Approach
Desk research of FDA accelerated approval filings, EMA centralized authorization records, and ClinicalTrials.gov registry data preceded structured interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Secondary validation drew from SEC 10-K oncology segment disclosures, CMS Medicare Part D utilization data, and GPO contract databases. Bottom-up patient volume modeling and top-down revenue triangulation converged on segment-level estimates.
Assumptions held fixed include FDA accelerated approval pathway continuity, REACH compliance harmonization for small-molecule APIs, and specialty pharmacy network consolidation trends. Variables included Phase III readout timing for novel mechanism classes, IRA Medicare price negotiation implementation scope, and EMA adaptive licensing adoption rates. Segmentation dimensions spanned therapeutic modality, administration route, end-user site of care, and regional regulatory cluster. CAGRs derived from log-linear trend fitting across the projection horizon, with inputs from academic medical center expansion rates and diagnostic testing penetration curves.
Macroeconomic conditions sit as an overlay; deviation in biopharmaceutical R&D tax credit policy or cross-border API tariff regimes would shift the trajectory. Forecasts reflect these documented assumptions and risk factors including transfusion dependency burden escalation and resistance mechanism complexity. Quarterly review of FDA oncology advisory committee calendars and EMA CHMP opinion schedules is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Global Hematologic Malignancies Treatment Market
Hematology
Heparin-Induced Thrombocytopenia (HIT) Treatment Market
Hematology
Global Hemoglobin Meter Market
Hematology
Blood Disorder Therapeutics Market
Hematology
Radiation-Induced Myelosuppression Treatment Market
Hematology
Lymphoma Treatment Market
Hematology
Hypereosinophilic Syndrome Market
Hematology
Follicular Lymphoma Treatment Market
Hematology
Graft vs Host Disease Market
Hematology
Pancytopenia Market
Hematology
Multiple Myeloma Therapeutics Market
Hematology
Patient Blood Management Market
Hematology
Global Sickle Cell Disease Treatment Market
Hematology
Chemotherapy-Induced Myelosuppression Treatment Market
Hematology
Hemoglobin Testing Systems Market
Hematology
Acute Myeloid Leukemia Treatment Market