
 Nephrogenic Systemic Fibrosis (NSF) Treatment Market | 2026-2036
Nephrogenic Systemic Fibrosis (NSF) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Nephrogenic Systemic Fibrosis (NSF) Treatment Market Analytics
Single-source reliance on gadolinium-based contrast agents for MRI imaging is restructuring procurement patterns across radiology departments and dialysis networks. Pfizer leverages its established chelation therapy portfolio to sustain presence in symptomatic management protocols. Novartis competes through immunosuppressant development programs, while Sanofi anchors distribution networks across hospital and specialty clinic channels.
Nephrogenic Systemic Fibrosis constitutes a rare systemic fibrosing disorder triggered by gadolinium exposure in patients with impaired renal function, characterized by collagen deposition in skin and visceral organs that necessitates immunomodulatory and chelation-based intervention. Chelation agents currently dominate the product type landscape due to their mechanistic alignment with gadolinium removal, though biologics represent the segment where pipeline investment is concentrating fastest. Intravenous delivery mode occupies the largest share of administered therapies, reflecting the acute care setting where most NSF cases are initially managed.
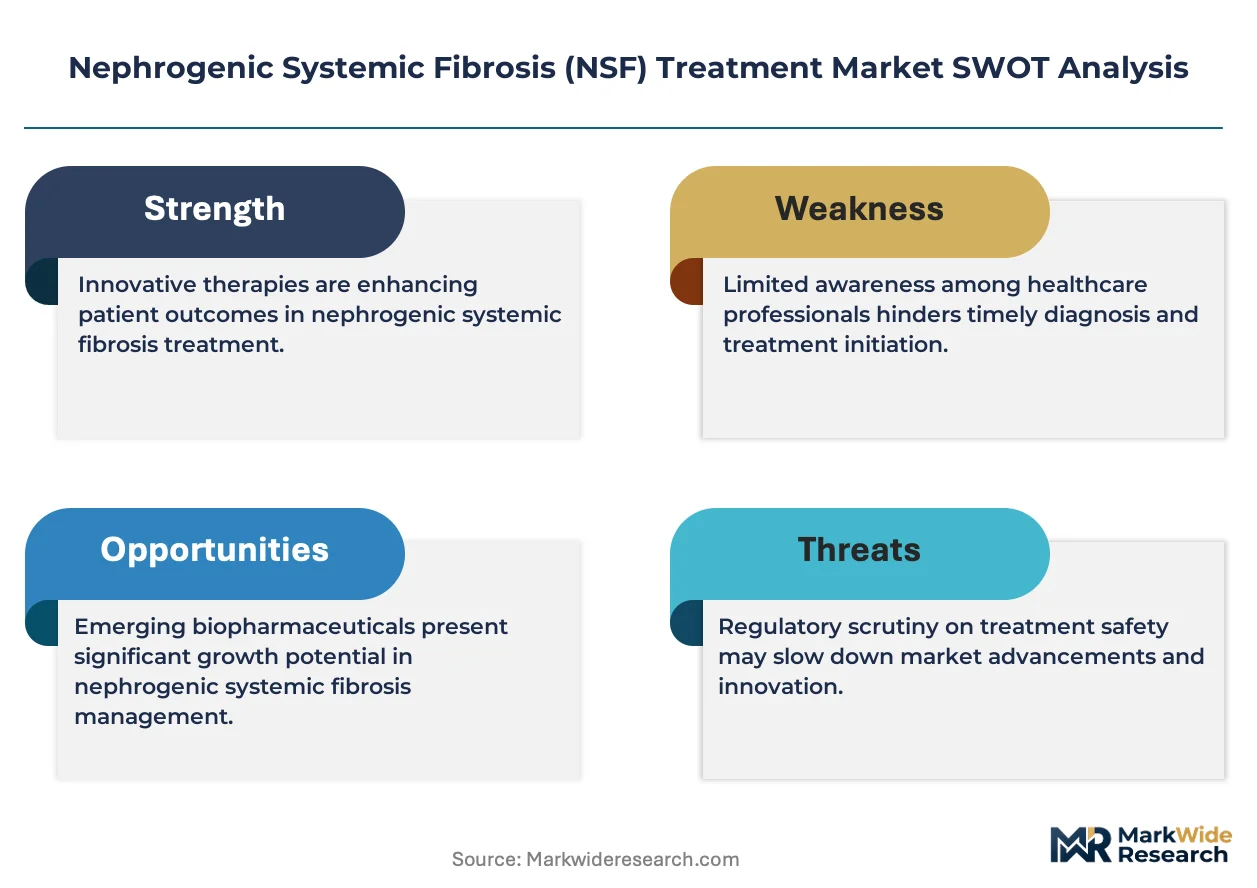
The FDA maintains stringent post-market surveillance requirements for gadolinium-based contrast agents through its boxed warning system, while the EMA's PRAC recommendations have driven parallel restrictions across European imaging practices. These regulatory frameworks directly constrain new case incidence and reshape demand toward management of existing patient pools rather than acute intervention. Stakeholders must monitor evolving renal replacement therapy protocols and contrast agent formulation shifts to calibrate portfolio emphasis between chelation and immunosuppressive approaches.
Market Dynamics
FDA boxed warnings on gadolinium-based contrast agents have permanently altered diagnostic imaging workflows, redirecting clinical attention toward chelation protocols and immunomodulatory management of established NSF cases rather than acute intervention.
Growth Catalysts
- Renal Replacement Therapy Expansion:Dialysis center networks in the United States are formalizing NSF screening protocols, creating standardized pathways for chelation therapy referral and longitudinal patient monitoring.
- EMA PRAC Recommendations:Parallel European restrictions on high-risk gadolinium agents have reduced new case incidence while concentrating treatment demand among existing patient pools requiring ongoing management.
- Biologics Pipeline Investment:Immunosuppressant development programs are attracting capital allocation toward fibrosis-modifying therapies targeting collagen deposition mechanisms.
Market Restraints
- Input Concentration Risk:Chelating agent raw material supply depends on concentrated specialty chemical manufacturers in Germany and Switzerland, exposing formulation costs to single-source vulnerability.
- Technical Efficacy Ceiling:Current chelation protocols demonstrate incomplete gadolinium clearance from deep tissue compartments, limiting symptomatic improvement in advanced fibrosis stages.
- Regulatory Friction:FDA post-market surveillance requirements for contrast agents impose documentation burdens that slow diagnostic throughput and compress reimbursement margins for imaging centers.
Strategic Opportunities
- Underpenetrated Dialysis Integration:United States-based integrated kidney care networks offer captive channels for embedded NSF screening and chelation therapy administration.
- Technology Convergence:Combination regimens pairing chelation with targeted immunosuppression represent white space for protocol development in academic medical center settings.
- Distribution Innovation:Specialty pharmacy direct-to-patient models for chronic immunosuppressant delivery bypass traditional hospital outpatient infrastructure.
Industry Challenges
- Rare Disease Trial Design:NSF patient scarcity complicates endpoint validation and recruitment for novel therapeutic candidates, extending development timelines.
- Legacy Imaging Infrastructure:Hospital radiology departments face capital constraints in replacing gadolinium-dependent MRI protocols with alternative contrast modalities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nephrogenic Systemic Fibrosis (NSF) Treatment Market |
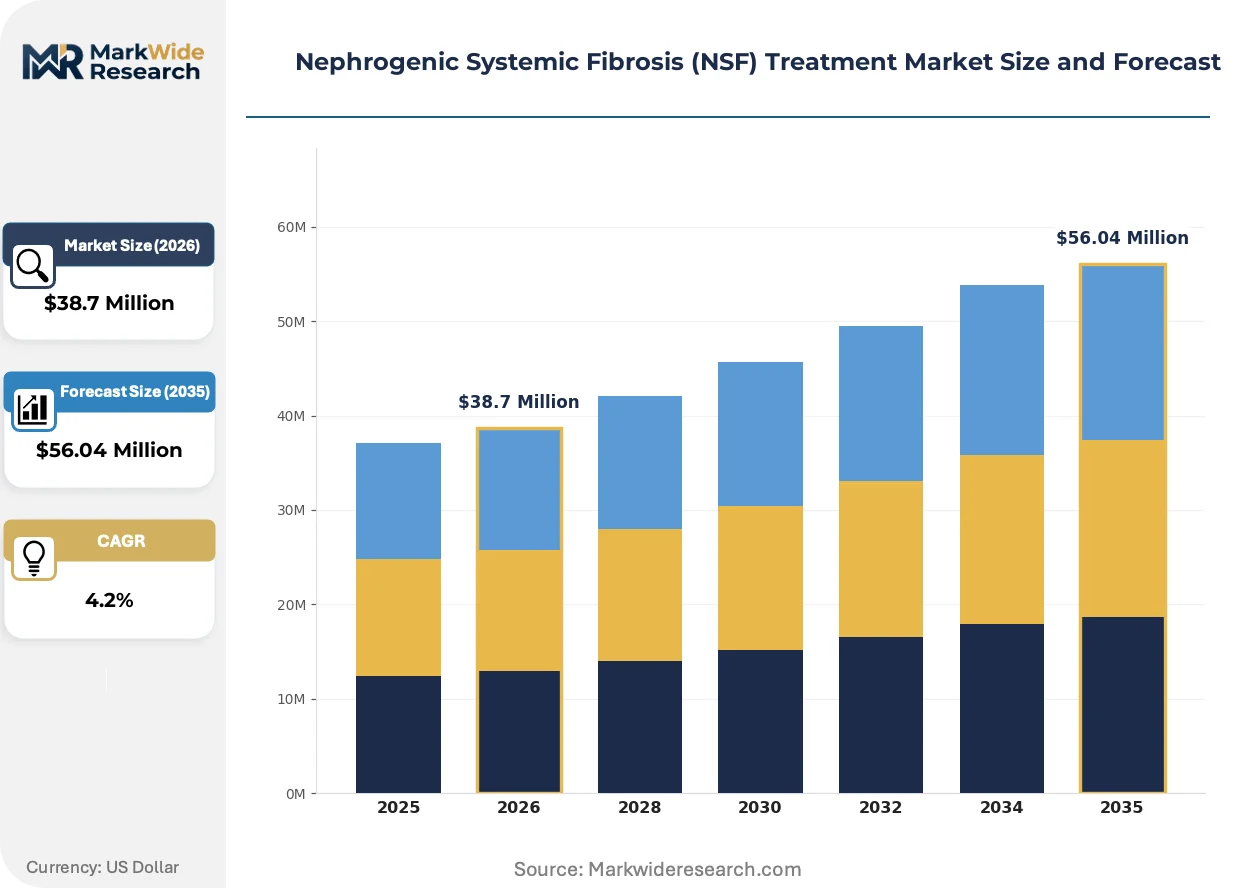
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $56.04 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chelation Agents, Corticosteroids, Immunosuppressants, Biologics Delivery Mode: Intravenous, Oral, Subcutaneous, Topical End User: Hospitals, Specialty Clinics, Outpatient Facilities, Homecare Application: Symptomatic Relief, Patient Management, Clinical Trial, Research |
| Companies Covered | Pfizer, Sanofi, Allergan, Novartis, Johnson & Johnson, Bausch Health, Merck, Teva, Teva Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nephrogenic Systemic Fibrosis (NSF) Treatment Market Evolving Landscape
Chelation-based therapeutic protocols are gaining protocol standardization across nephrology and radiology departments, while regulatory surveillance frameworks and procurement models for contrast agents undergo parallel restructuring.
Multidentate chelating agents with enhanced gadolinium binding affinity are consolidating their position as first-line intervention in symptomatic NSF management. Academic medical centers in the United States are adopting these formulations at accelerating pace for patients with confirmed gadolinium retention. The technology is consolidating demand around agents demonstrating superior thermodynamic stability profiles compared to earlier generations.
EMA pharmacovigilance requirements for macrocyclic versus linear gadolinium agents have hardened formulation preferences across European imaging practices. The industrial consequence is a supply shift toward macrocyclic alternatives with lower NSF risk profiles. Dialysis networks in France and Germany are responding by retraining procurement specifications and revising contrast administration protocols for renal-impaired populations.
Hospital system purchasing cooperatives are consolidating contrast agent procurement through centralized tenders with outcome-based utilization clauses. Traditional distributor relationships are compressing as direct manufacturer agreements gain share in large integrated delivery networks. This restructuring is most visible in United States metropolitan markets where health system consolidation has concentrated buying power among three to five dominant entities per region.
Nephrogenic Systemic Fibrosis (NSF) Treatment Market Segmentation
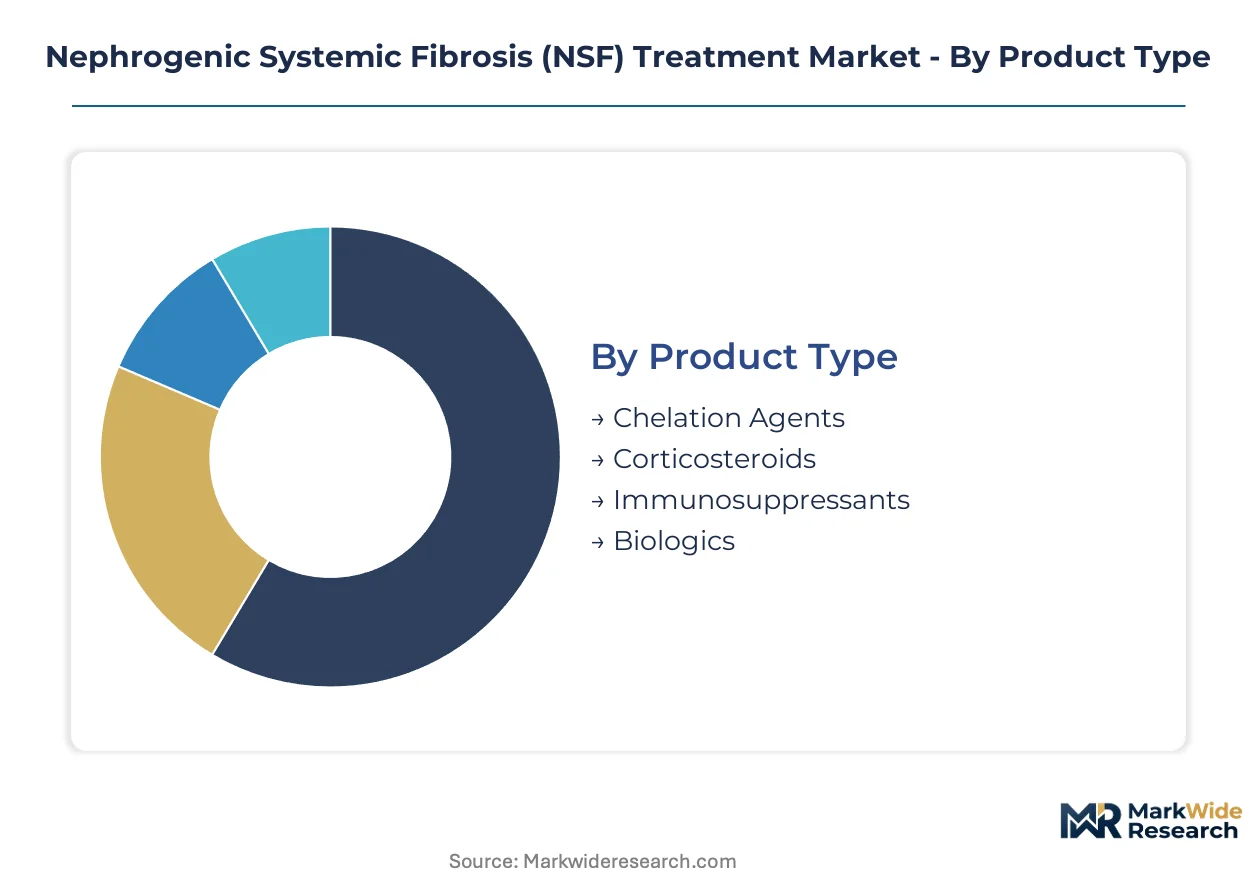
Treatment protocols for Nephrogenic Systemic Fibrosis diverge sharply across clinical settings and patient severity profiles. Segmentation reveals where chelation therapy dominates versus where immunomodulatory approaches gain protocol traction.
Product Type:
Cost tier differentiation separates acute intervention from chronic management strategies across the therapeutic spectrum.
- Chelation Agents:Multidentate formulations with enhanced gadolinium binding affinity serve as first-line intervention for confirmed retention cases. Dialysis centers in the United States standardize these protocols for symptomatic patients with measurable tissue deposition.
- Biologics:Fibrosis-modifying therapies targeting collagen deposition mechanisms attract accelerating pipeline investment. Academic medical centers pilot these agents for advanced visceral organ involvement where chelation proves insufficient.
- Corticosteroids:Anti-inflammatory regimens address early-stage skin fibrosis manifestations in outpatient nephrology settings.
- Immunosuppressants:Chronic modulation of immune-mediated fibrotic pathways supports long-term disease stabilization in specialty clinic populations.
Volume sits with Chelation Agents; growth tilts toward Biologics.
Delivery Mode:
Application urgency and tissue penetration requirements determine route selection across care settings.
- Intravenous:Acute care administration dominates initial NSF diagnosis and severe symptom management. Hospital infusion centers coordinate these deliveries alongside dialysis schedules for renal-impaired patients.
- Oral:Chronic maintenance regimens enable outpatient disease control without facility-based care. Specialty pharmacy networks in the United States expand direct-to-patient distribution for immunosuppressant maintenance.
- Subcutaneous:Intermediate-severity cases receive targeted dosing through clinic-administered injection protocols.
- Topical:Localized skin symptom management addresses superficial fibrosis in early-stage presentations.
Intravenous captures the largest administered volume; Oral delivery gains share fastest in integrated kidney care networks.
End User:
Patient acuity and protocol complexity concentrate demand across facility types with varying reimbursement structures.
- Hospitals:Acute diagnosis and initial chelation therapy administration occur in inpatient and emergency settings. FDA boxed warning documentation requirements embed NSF screening within radiology-nephrology coordination workflows.
- Specialty Clinics:Longitudinal management of established cases with biologics and immunosuppressants centers on nephrology and rheumatology practices. These facilities coordinate with dialysis networks for integrated care.
- Outpatient Facilities:Intermediate care settings handle stable patients transitioning from acute to chronic management.
- Homecare:Self-administered oral regimens and nursing-supported subcutaneous delivery reduce facility utilization for stabilized populations.
Hospitals anchor diagnostic volume; Specialty Clinics drive the steepest expansion trajectory for chronic therapy administration.
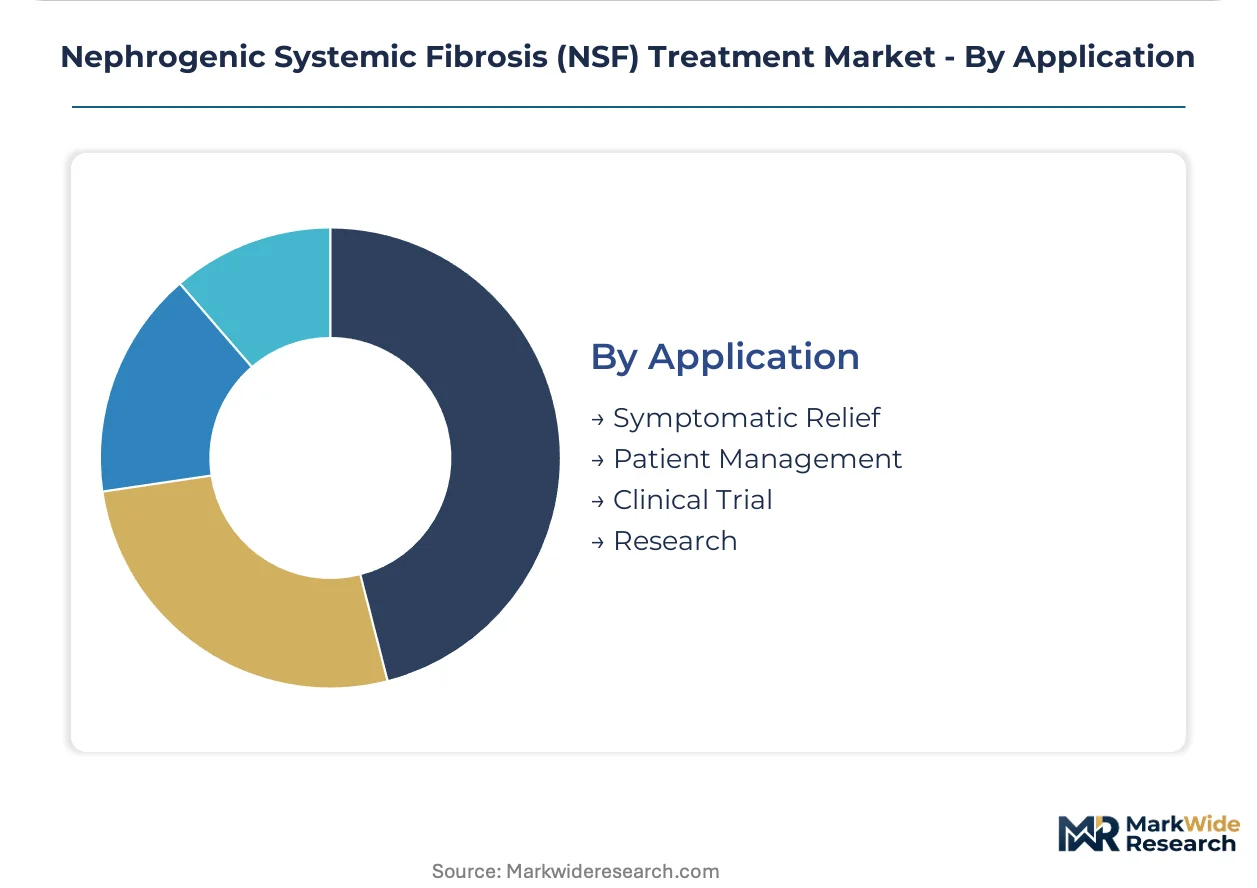
Application:
Clinical purpose separates revenue-generating treatment from non-commercial research activity across the value chain.
- Symptomatic Relief:Immediate intervention for skin tightening, joint contracture, and mobility impairment constitutes the primary reimbursable indication. Chelation protocols in United States dialysis centers target measurable quality-of-life endpoints.
- Patient Management:Longitudinal protocols combining chelation with immunosuppression address progressive visceral involvement. Academic medical centers develop these combination regimens for advanced cases.
- Clinical Trial:Biologics development programs recruit from established NSF patient registries for novel therapeutic validation.
- Research:Gadolinium retention mechanisms and fibrosis biomarker studies occur in non-commercial laboratory settings.
Symptomatic Relief commands current spending; Patient Management represents the fastest-climbing application as chronic protocols standardize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for NSF treatment concentrates heavily in the United States, where dialysis center networks and FDA regulatory frameworks have created the most mature management infrastructure for gadolinium-exposed renal patients.
United States
Dialysis center networks in the United States standardize NSF screening protocols and chelation therapy referrals for symptomatic patients. FDA boxed warnings on gadolinium-based contrast agents mandate radiology-nephrology coordination workflows that embed treatment access within renal replacement therapy settings. Major academic medical centers in Boston and New York pilot combination regimens pairing chelation with immunosuppression for advanced visceral involvement.
Germany
German dialysis networks retrain procurement specifications toward macrocyclic contrast alternatives with lower NSF risk profiles. EMA PRAC recommendations drive formulation preferences across European imaging practices, reducing new case incidence while concentrating chronic management demand. Industrial clusters in Baden-Württemberg and Bavaria host specialty chemical manufacturers supplying chelating agent raw materials to formulation companies.
France
French hospital systems consolidate contrast agent procurement through centralized tenders with outcome-based utilization clauses. ANSM pharmacovigilance requirements parallel EMA restrictions on high-risk gadolinium agents. Paris and Lyon academic medical centers develop longitudinal patient management protocols for established NSF cases requiring ongoing immunomodulatory intervention.
Japan
Japanese nephrology practices integrate NSF screening within existing renal replacement therapy protocols. PMDA maintains stringent post-market surveillance for gadolinium-based contrast agents that shapes diagnostic imaging workflows. Tokyo and Osaka medical centers concentrate expertise in chelation therapy administration for confirmed gadolinium retention cases.
United Kingdom
UK nephrology and rheumatology specialty clinics coordinate chronic NSF management with regional dialysis networks. MHRA guidance aligns with EMA restrictions on linear gadolinium agents. London teaching hospitals and Manchester renal units anchor the country's treatment infrastructure for progressive fibrosis cases.
Nephrogenic Systemic Fibrosis (NSF) Treatment Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbents calibrate between chelation and immunosuppressive therapeutic vectors. The vendor base separates into three tiers: multinational pharmaceutical conglomerates with established rare disease infrastructure, mid-cap specialty firms with concentrated nephrology positioning, and emerging biologics developers targeting fibrosis-modifying mechanisms. Two strategic archetypes predominate: chelation therapy specialists leveraging established nephrology distribution channels, and immunomodulatory developers pursuing biologics pipeline advancement. Competitive intensity centers on M&A activity targeting fibrosis-focused biotech assets and strategic partnerships with integrated kidney care networks.
Within the multinational pharmaceutical tier, Pfizer and Novartis exemplify divergent strategic positioning. Pfizer anchors its presence through established chelation therapy portfolios aligned with symptomatic management protocols in dialysis settings. Novartis occupies a position emphasizing immunosuppressant development programs targeting collagen deposition mechanisms. Sanofi, a French-based conglomerate, represents the distribution-centric archetype with anchored hospital and specialty clinic channel relationships.
| Leading Market Players |
|---|
| Pfizer |
| Sanofi |
| Allergan |
| Novartis |
| Johnson & Johnson |
| Bausch Health |
| Merck |
| Teva |
| Teva Pharmaceuticals |
| Others |
Value Network & Pricing Analysis
Backward integration into specialty chemical manufacturing anchors pricing power for chelating agent formulators serving United States dialysis networks, while outsourced biologics production constrains margin capture for immunomodulatory developers competing in academic medical center channels.
Pricing Analysis
Service bundling separates acute chelation protocols from chronic immunosuppressant management, with dialysis centers absorbing infusion administration costs within bundled renal replacement therapy reimbursement while specialty clinics unbundle biologics dosing from physician consultation fees. Three-tier pricing structure across macrocyclic chelators, multidentate alternatives, and corticosteroid regimens reflects FDA certification tiers and thermodynamic stability profiles. Cost compression in standard-grade chelators is intensifying because German and Swiss raw material suppliers face energy input volatility. Dialysis network procurement committees demonstrate highest price sensitivity, whereas academic medical centers purchasing fibrosis-modifying biologics prioritize clinical efficacy metrics over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from United States integrated kidney care networks require qualified suppliers for both macrocyclic contrast alternatives and chelating agent active pharmaceutical ingredients, forcing procurement teams to maintain relationships with German specialty chemical manufacturers and Swiss fine chemical producers alongside domestic formulation facilities. Critical inputs include gadolinium oxide precursors, diethylenetriaminepentaacetic acid derivatives, and sterile manufacturing capacity. Single-source vulnerability concentrates in Baden-Württemberg industrial clusters where thermodynamic stability testing infrastructure is scarce. Distribution runs through hospital system purchasing cooperatives consolidating contrast agent and therapeutic procurement under centralized tender structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industry consolidation accelerates as FDA post-market surveillance requirements and rare disease trial complexity force subscale biologics developers toward strategic exit, concentrating viable therapeutic innovation among multinational pharmaceutical infrastructure holders.
For Market Incumbents: Extend chelation therapy portfolio depth through captive supply agreements with German specialty chemical manufacturers, securing thermodynamic stability testing capacity that emerging competitors cannot replicate. Anchor distribution control through exclusive partnerships with United States integrated kidney care networks formalizing NSF screening protocols, insulating against biologics developers encroaching on chronic management segments.
For New Entrants and Emerging Players: Specialty pharmacy direct-to-patient digital channels offer the lowest barrier entry point for oral immunosuppressant maintenance regimens, bypassing hospital outpatient infrastructure dominated by established players. Target underpenetrated dialysis networks in metropolitan United States markets where health system consolidation has concentrated buying power among three to five entities per region. Pursue white-space combination regimen development pairing chelation with targeted immunosuppression in academic medical center pilot settings.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational pharmaceutical conglomerates seeking rare disease infrastructure, with biologics developers targeting collagen deposition mechanisms commanding premium positioning. Long-term viability favors assets with demonstrated Phase II efficacy in visceral organ fibrosis applications and established investigator relationships at Boston and New York academic medical centers. Watch EMA PRAC recommendation expansions beyond macrocyclic versus linear distinctions as the signal for accelerated formulation preference shifts and stranded linear agent inventory risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase II programs in visceral fibrosis indications attract priority investigator access at major academic medical centers. |
| Regulatory Approval Pathway | FDA breakthrough therapy designation for biologics targeting collagen deposition accelerates development timelines and reimbursement negotiations. |
| Manufacturing Scale-Up | Captive sterile formulation capacity in United States dialysis corridor reduces dependency on European specialty chemical suppliers. |
| Pipeline Diversification | Combination regimens pairing chelation with immunosuppression address efficacy ceilings in advanced fibrosis stages. |
| Strategic Partnership | Exclusive distribution agreements with integrated kidney care networks lock in chronic therapy administration volume. |
Research Methodology
Independent corroboration across nephrology practice administrators, dialysis network procurement directors, radiology department heads, and biologics development executives underwrites the qualitative findings, with secondary validation drawing from FDA boxed warning documentation, EMA PRAC recommendation archives, ClinicalTrials.gov enrollment records, and hospital system purchasing cooperative tender disclosures. Bottom-up patient volume estimates from United States renal replacement therapy registries triangulate against top-down pharmaceutical shipment data to anchor market sizing.
Rate-of-change decomposition across the projection horizon isolates volume drivers from price effects, with segmentation modeling spanning product type, delivery mode, end user facility type, and clinical application purpose. CAGRs derive from log-linear trend fitting adjusted for regulatory inflection points and contrast agent formulation shifts. Forecast inputs incorporate dialysis center network expansion trajectories, gadolinium retention screening protocol adoption curves, and biologics pipeline advancement milestones.
The model holds under stable FDA surveillance requirements and EMA restriction continuity; deviation in macrocyclic versus linear agent risk stratification or accelerated biologics approval timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Abetalipoproteinemia Management Market
Specialty Medicine
Hunter Syndrome Treatment Market
Specialty Medicine
Asia-Pacific Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Oral Cancer Treatment Market
Specialty Medicine
Sjogrens Syndrome Market
Specialty Medicine
Ulcerative Colitis Market
Specialty Medicine
Endometrial Cancer Treatment Market
Specialty Medicine
Infantile Spasms Therapeutics Market
Specialty Medicine
Tinnitus Management Market
Specialty Medicine
Strep Throat Treatment Market
Specialty Medicine
Global Melanoma Diagnostics and Therapeutics Market
Specialty Medicine
Acute Lymphocytic-Lymphoblastic Leukemia (ALL) Therapeutics Market
Specialty Medicine
Progressive Pulmonary Fibrosis (PPF) Treatment Market
Specialty Medicine
Chronic Lymphocytic Leukemia Market
Specialty Medicine
Autism Spectrum Disorder Management Market
Specialty Medicine
Myelofibrosis Market