
 Papillary Thyroid Cancer Market | 2026-2036
Papillary Thyroid Cancer Market Size, Share, and Industry Trends Forecast 2026-2036
Papillary Thyroid Cancer Market Analytics
Adjuvant radioactive iodine therapy revenue is fragmenting between branded isotope suppliers and hospital-based compounding pharmacies. Novartis anchors its position through vertical control of radiopharmaceutical manufacturing networks. Bristol Myers Squibb differentiates via R&D intensity in immuno-oncology combinations for refractory disease. Eisai competes through geographic dominance in Asian markets with differentiated kinase inhibitor portfolios.
Papillary thyroid carcinoma, the most common differentiated thyroid malignancy, originates from follicular epithelial cells and typically presents as a well-circumscribed, slow-growing neoplasm with characteristic nuclear features including grooves, pseudoinclusions, and orphan annie nuclei. The disease serves industrial and commercial purposes primarily through surgical resection followed by risk-stratified adjuvant therapy to reduce recurrence and enable long-term disease monitoring. Surgery and radioactive iodine therapy together command the dominant share of treatment expenditure, while external beam radiation occupies a narrower niche for locally advanced or unresectable cases. Diagnostic methods show ultrasound and fine needle aspiration biopsy as the established frontline pathway, with molecular testing emerging as a higher-margin adjunct for indeterminate cytology specimens.
The FDA oversees oncology drug approval and post-market surveillance through its Office of Oncologic Diseases, while the Nuclear Regulatory Commission governs radioactive iodine handling and administration protocols in clinical settings. The European Medicines Agency's Committee for Medicinal Products for Human Use shapes parallel access pathways through centralized marketing authorization procedures. Stakeholders must monitor how regulator positioning on biomarker-driven patient selection criteria will reshape clinical trial design and commercial targeting across treatment settings.
Market Dynamics
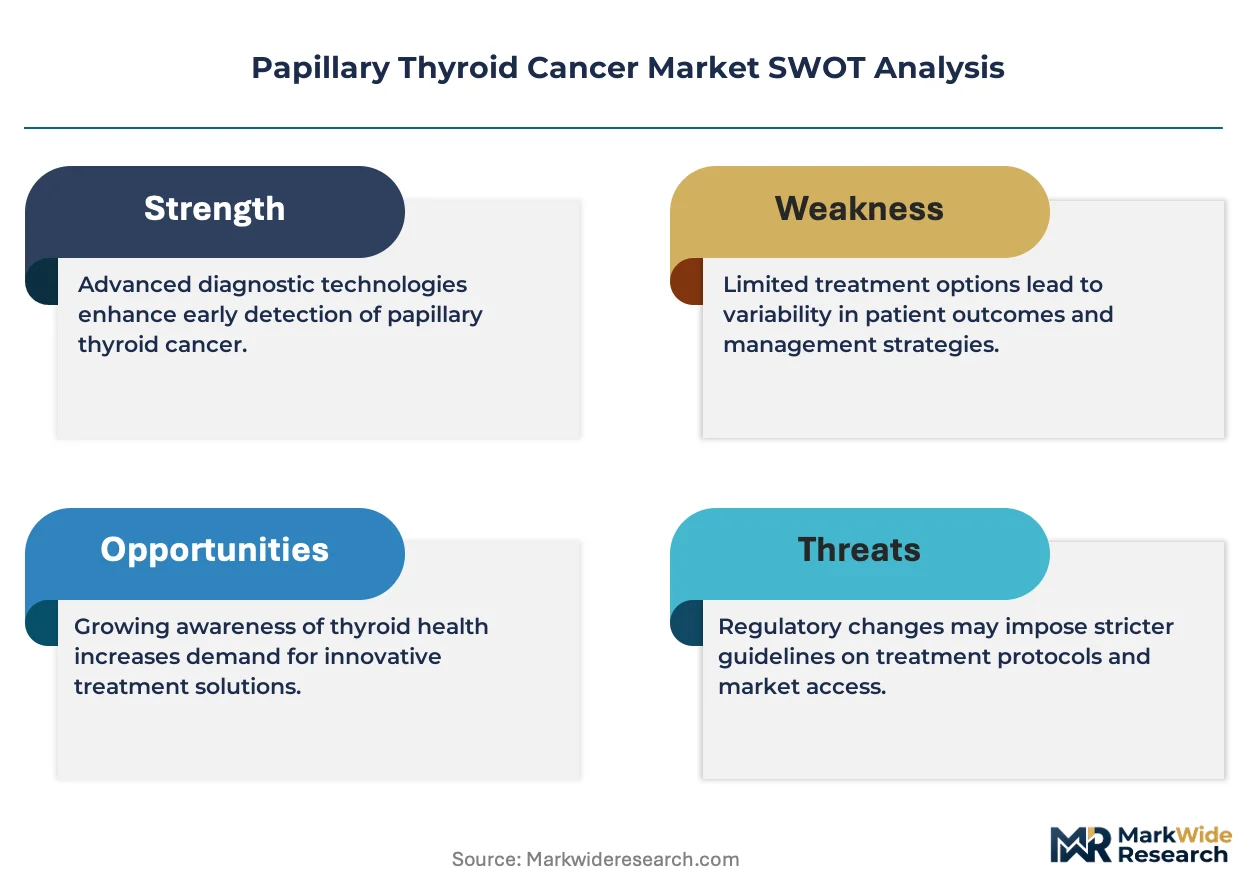
The FDA's breakthrough therapy designation pathway is compressing clinical development timelines for targeted kinase inhibitors, forcing incumbent radiopharmaceutical suppliers to accelerate manufacturing scale-up or risk displacement by oral systemic therapies.
Growth Catalysts
- Molecular diagnostic expansion:Academic medical centers in the United States are deploying next-generation sequencing panels for indeterminate thyroid nodules, expanding addressable testing volume beyond cytology-negative cases.
- Targeted therapy access:The FDA's breakthrough therapy designation creates expedited review pathways for RET and NTRK inhibitors, shortening time-to-market for precision oncology agents in refractory disease settings.
- Radioisotope infrastructure:Hospital-based nuclear medicine departments are investing in on-site iodine-131 compounding capabilities, reducing dependency on centralized radiopharmaceutical distributors.
Market Restraints
- Isotope supply concentration:High-specific-activity iodine-131 production concentrates at fewer than six North American reactors, creating vulnerability to unplanned maintenance outages.
- Reimbursement compression:Medicare's hospital outpatient prospective payment system bundles radioactive iodine administration with diagnostic workup, squeezing margin for standalone isotope suppliers.
- Diagnostic substitution:Molecular testing for BRAF V600E and RAS mutations is displacing repeat fine needle aspiration biopsies in indeterminate nodule management.
Strategic Opportunities
- Asian market penetration:Japan's PMDA has established abbreviated approval pathways for drugs with prior FDA or EMA authorization, enabling faster commercial entry for kinase inhibitor portfolios.
- Immuno-oncology convergence:Combination protocols pairing anti-PD-1 antibodies with radioactive iodine are opening addressable segments in radioiodine-refractory differentiated thyroid carcinoma.
- Telemedicine integration:Virtual endocrinology consultations are expanding access to specialist thyroid nodule assessment in rural and underserved U.S. counties.
Industry Challenges
- Nuclear medicine specialist shortage:Fellowship-trained radiopharmaceutical physicians are concentrating at academic medical centers, limiting community hospital capacity for complex iodine-131 therapy administration.
- Quality assurance complexity:NRC-mandated dosimetry verification and patient release criteria impose documentation burdens that extend treatment scheduling cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Papillary Thyroid Cancer Market |
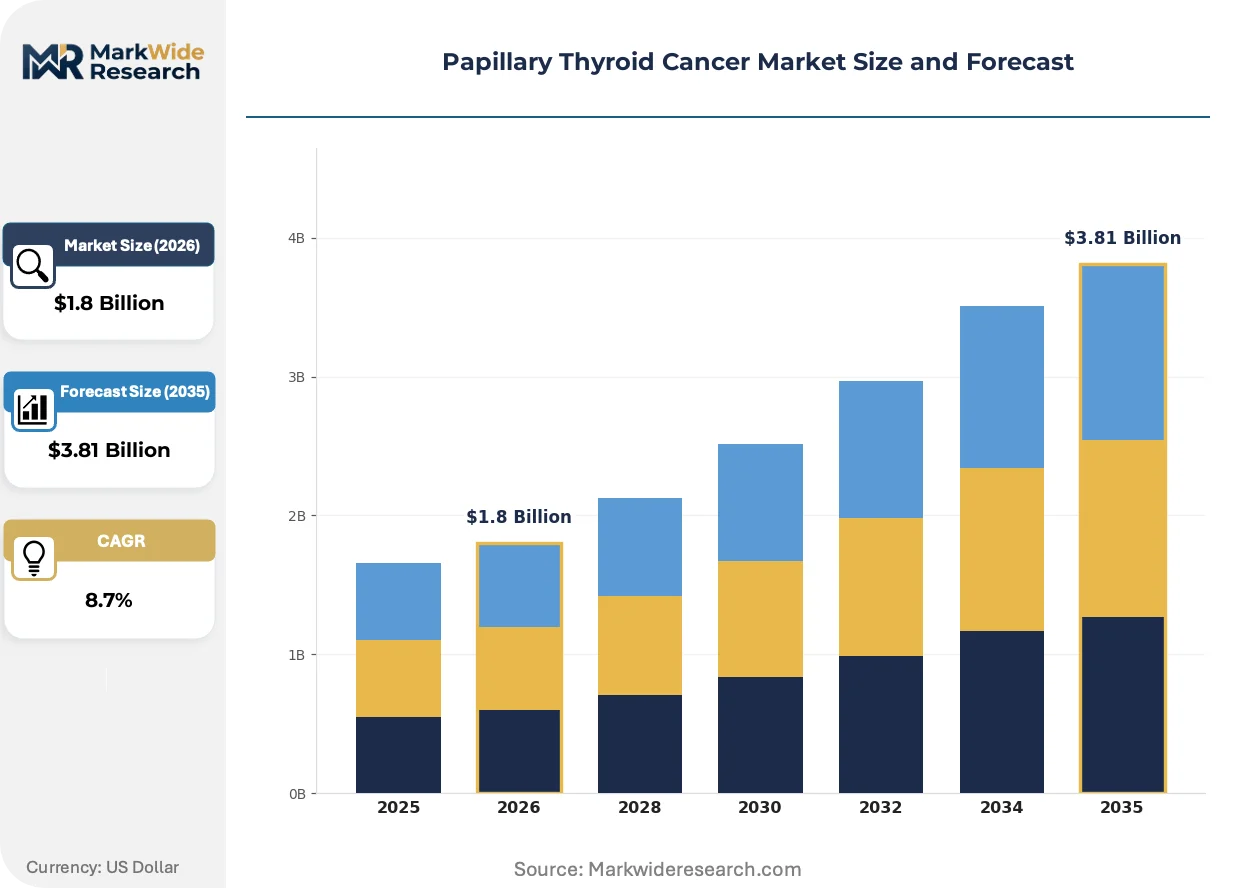
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Surgery, Radioactive Iodine Therapy, Thyroid Hormone Therapy, External Beam Radiation Diagnostic Method: Ultrasound, Fine Needle Aspiration, CT Scan, MRI End User: Hospitals, Oncology Clinics, Ambulatory Surgical Centers, Research Institutions Stage of Disease: Localized, Regional, Distant Metastasis, Recurrent |
| Companies Covered | AstraZeneca, Bristol Myers Squibb, Eisai, Novartis, Pfizer, Sanofi, Bayer, Takeda Pharmaceutical Company, Teva Pharmaceutical Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Papillary Thyroid Cancer Market Evolving Landscape
Technology convergence between molecular diagnostics and systemic therapy selection is restructuring how clinicians sequence treatment modalities, with diagnostic results increasingly determining eligibility for targeted rather than radioactive interventions.
Next-generation sequencing-based gene expression classifiers are migrating from adjunctive confirmatory tools to frontline decision support in thyroid nodule management. Community endocrinology practices in the United States are adopting these platforms to reduce diagnostic surgery rates. The technology is enabling risk stratification that redirects low-malignancy-risk patients toward active surveillance protocols.
The European Medicines Agency's Committee for Medicinal Products for Human Use has tightened evidentiary requirements for conditional marketing authorization in oncology, demanding mature progression-free survival data rather than surrogate endpoints. This regulatory posture is extending development timelines for novel kinase inhibitors. Sponsors are responding by prioritizing U.S. FDA submissions ahead of European dossier preparation.
Academic medical centers are consolidating radioactive iodine therapy referrals through dedicated thyroid cancer centers of excellence, displacing fragmented community-based administration. Hospital systems are capturing these cases through bundled payment arrangements that include surgery, pathology, and adjuvant therapy. This concentration is visible across major U.S. metropolitan markets where vertically integrated delivery networks dominate regional case volume.
Papillary Thyroid Cancer Market Segmentation
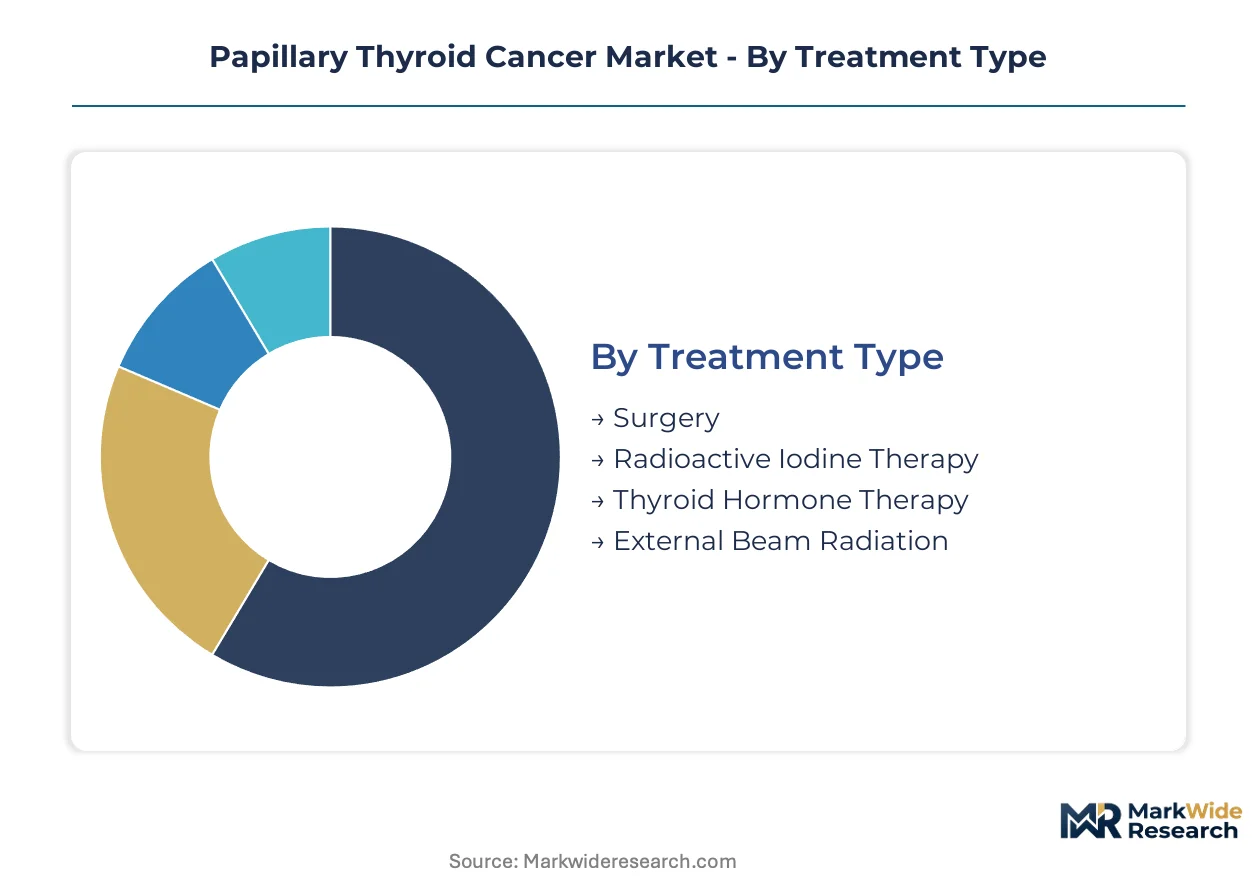
Treatment sequencing decisions in papillary thyroid carcinoma depend heavily on post-procedure monitoring intensity and long-term hormone replacement protocols. Segment boundaries reflect where clinical workflows bifurcate between curative intent and palliative management, with reimbursement pathways diverging accordingly.
Treatment Type:
Aftercare service requirements vary dramatically across modalities, with radioactive iodine demanding specialized radiation safety protocols and extended follow-up scheduling.
- Surgery:Total or partial thyroidectomy represents the foundational curative intervention, with robotic-assisted platforms gaining traction at high-volume academic centers. Demand clusters in the United States where bundled payment models incentivize comprehensive preoperative workup and postoperative surveillance. The procedure generates substantial downstream revenue through lifelong levothyroxine monitoring and periodic neck ultrasound surveillance.
- Radioactive Iodine Therapy:Adjuvant ablation or treatment of residual disease requires NRC-licensed facilities with dedicated isolation rooms and trained nuclear medicine personnel. Concentration of qualified administration sites in major metropolitan areas creates access barriers for rural patients. Supply chain fragility for high-specific-activity isotope production amplifies scheduling uncertainty.
- Thyroid Hormone Therapy:Suppression of TSH to reduce recurrence risk demands precise dose titration and cardiovascular monitoring over decades.
- External Beam Radiation:Reserved for unresectable or radioiodine-refractory cases with localized progression.
By volume, Surgery leads. By growth pace, Targeted kinase inhibitors (emerging within systemic therapy) are expanding most quickly.
Diagnostic Method:
Cost tier stratification separates high-complexity molecular assays from standard imaging, with pricing power concentrated in indeterminate nodule adjudication.
- Ultrasound:First-line structural assessment with elastography and contrast enhancement expanding capability at tertiary centers. Penetration is deepest in Japan where screening protocols detect subclinical nodules in younger populations. Operator dependency limits standardization across community radiology practices.
- Fine Needle Aspiration:Cytologic evaluation via ultrasound-guided sampling remains the decisive triage tool for nodule characterization. Academic medical centers in the United States are integrating rapid on-site adequacy assessment to reduce nondiagnostic rates. Bethesda classification standardization enables consistent risk stratification.
- CT Scan:Staging evaluation for extrathyroidal extension or distant metastasis, particularly in postoperative restaging.
- MRI:Reserved for problematic neck recurrences or iodine-negative metastatic disease characterization.
By procedure count, Ultrasound dominates. By margin expansion, Molecular testing (adjunct to FNA) shows the steepest trajectory.
End User:
Customer type determines purchasing authority, with hospital systems centralizing procurement for high-cost isotopes while clinics retain autonomy for molecular test selection.
- Hospitals:Integrated delivery networks capture the complete care episode from diagnosis through adjuvant therapy, leveraging scale for radiopharmaceutical contracting. Major systems in the United States are establishing dedicated thyroid cancer centers of excellence to consolidate regional referral volume.
- Oncology Clinics:Community-based practices drive molecular diagnostic adoption for nodule risk stratification, reducing unnecessary surgical referrals. Payer contracts increasingly bundle molecular testing with specialist consultation fees.
- Ambulatory Surgical Centers:Low-complexity thyroidectomies migrate to outpatient settings where anesthesia protocols and same-day discharge criteria are met.
- Research Institutions:Academic centers conduct biomarker-driven clinical trials for refractory disease, accessing FDA breakthrough therapy pathways.
By patient volume, Hospitals absorb the majority. By technology uptake velocity, Oncology clinics are gaining share fastest.
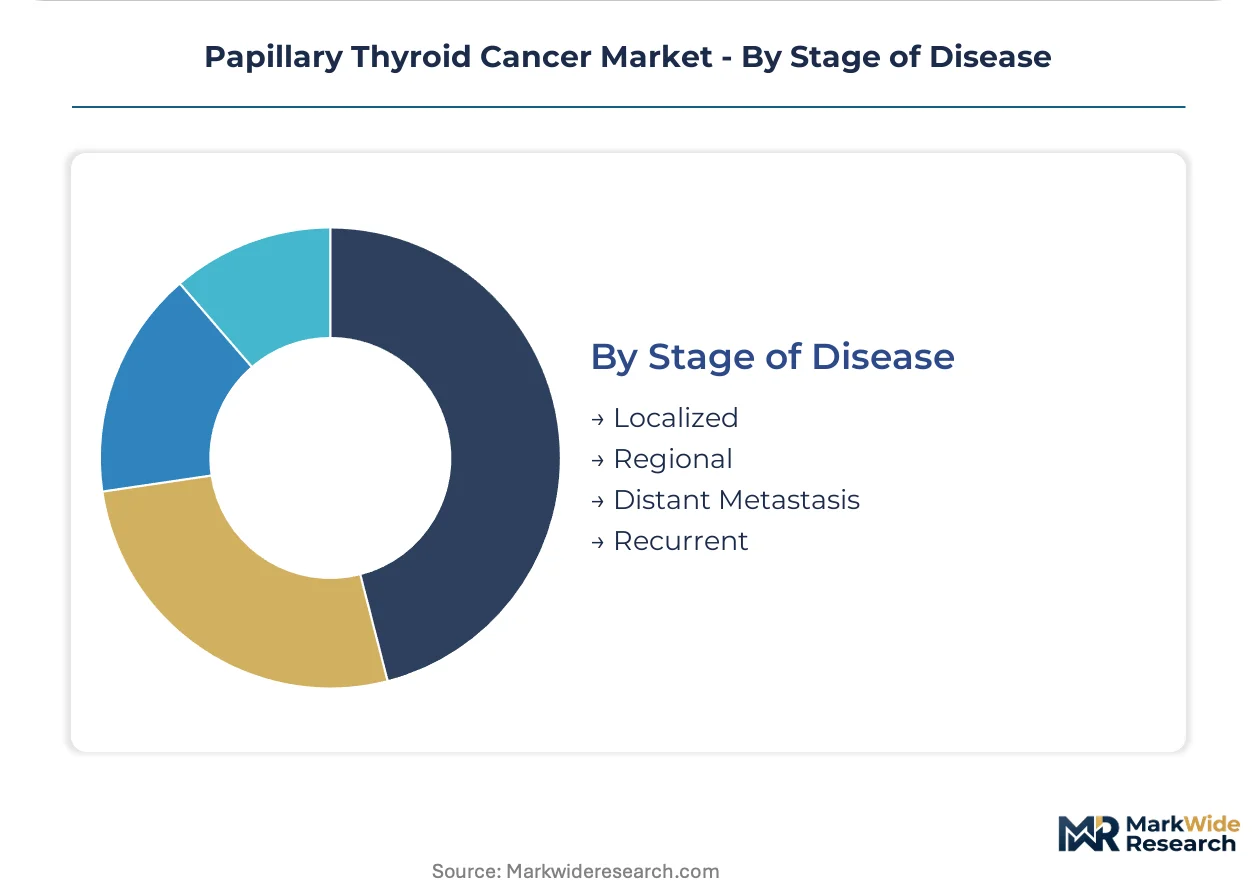
Stage of Disease:
Maturity of clinical evidence and guideline penetration varies sharply, with early-stage management standardized while metastatic protocols remain investigational.
- Localized:Confined to thyroid parenchyma with excellent prognosis under active surveillance or limited surgery. Risk stratification tools identify candidates for hemithyroidectomy versus total thyroidectomy, reducing overtreatment in low-risk cohorts.
- Regional:Lymph node involvement triggers modified neck dissection with selective central compartment clearance. Recurrence patterns in this segment drive demand for postoperative radioactive iodine decision frameworks.
- Distant Metastasis:Pulmonary or osseous spread shifts management toward systemic therapy with molecular target identification.
- Recurrent:Salvage surgery or targeted radiotherapy requires multidisciplinary tumor board coordination.
By incidence, Localized disease predominates. By unmet need intensity, Distant metastasis commands the most rapid therapeutic innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between geographies that emphasize surgical resection with radioactive iodine adjuvant therapy and those pivoting toward molecular-guided targeted interventions. Academic medical centers in the United States drive precision oncology adoption, while Japan and Germany maintain stronger reliance on established radioisotope protocols.
United States
Academic medical centers in Boston, Houston, and San Francisco anchor demand for next-generation sequencing panels in indeterminate nodule management. The FDA's breakthrough therapy designation pathway accelerates commercial entry for RET and NTRK inhibitors in refractory settings. Major hospital systems in the Northeast Corridor are consolidating thyroid cancer referrals through vertically integrated centers of excellence.
Japan
PMDA abbreviated approval pathways enable faster market entry for kinase inhibitors with prior FDA authorization, compressing development-to-commercialization timelines. Screening protocols detect subclinical nodules in younger demographics, expanding addressable diagnostic volume. Tokyo and Osaka metropolitan areas concentrate specialized nuclear medicine capacity for complex iodine-131 therapy administration.
Germany
EMA centralized marketing authorization procedures shape parallel access pathways for novel systemic therapies. The country's statutory health insurance system maintains preference for established radioiodine protocols in differentiated disease. Munich and Heidelberg academic clusters drive biomarker-driven clinical trial enrollment for refractory carcinoma.
China
NMPA oncology drug reviews are accelerating for agents with mature progression-free survival data from multinational trials. Tier-1 cities including Beijing, Shanghai, and Guangzhou are deploying molecular diagnostic platforms for thyroid nodule risk stratification. Hospital-based nuclear medicine departments are investing in captive iodine-131 compounding capabilities.
United Kingdom
NICE technology appraisals determine reimbursement access for targeted therapies in radioiodine-refractory disease. London and Manchester academic centers concentrate multidisciplinary tumor board capacity for complex case management. The NHS is piloting gene expression classifier integration into primary care referral pathways for incidentally detected nodules.
Papillary Thyroid Cancer Market Competitive Landscape
Capability concentration sits with large-cap pharmaceutical developers possessing integrated radiopharmaceutical manufacturing networks; scale advantage sits with diversified oncology portfolios spanning multiple solid tumor indications. The market structure reflects a bifurcated competitive environment where vertical control of isotope supply chains competes against R&D intensity in precision medicine. Three archetypes dominate: radiopharmaceutical-integrated conglomerates, kinase inhibitor specialists, and immuno-oncology diversifiers. Competitive moves center on manufacturing scale-up acceleration and biomarker-driven patient selection partnerships with diagnostic platform developers.
Among the radiopharmaceutical-integrated tier, Novartis anchors position through captive production networks for high-specific-activity isotopes. Bristol Myers Squibb and Eisai exemplify contrasting strategic vectors—one through immuno-oncology combination development, the other through geographic concentration in Asian markets with differentiated kinase inhibitor portfolios. These three entities represent the dominant competitive archetypes shaping investment patterns across surgery-adjuvant and refractory disease settings.
| Leading Market Players |
|---|
| AstraZeneca |
| Bristol Myers Squibb |
| Eisai |
| Novartis |
| Pfizer |
| Sanofi |
| Bayer |
| Takeda Pharmaceutical Company |
| Teva Pharmaceutical Industries |
| Others |
Value Network & Pricing Analysis
Single-source dependency on North American reactor infrastructure for high-specific-activity iodine-131 determines both the three-tier pricing structure across premium, standard, and economy levels and the geographic concentration of qualified administration sites. Contract structures bifurcate between long-term offtake agreements anchoring hospital system procurement and spot purchases by community oncology practices facing scheduling uncertainty.
Pricing Analysis
Long-term offtake agreements dominate hospital system procurement, with price differentiation resting on volume scale and vertical integration into captive compounding capabilities. Premium tiers command margin through NRC-licensed isolation infrastructure and specialized nuclear medicine personnel, while economy tiers face cost compression from Medicare's bundled payment bundling diagnostic workup with isotope administration. Community oncology clinics exhibit highest price sensitivity due to reimbursement lag and capital constraints on radiation safety infrastructure.
Supply Chain Analysis
Contract-manufacturing concentration for radiopharmaceutical production sits with Novartis's captive networks and specialized isotope suppliers operating under NRC jurisdiction. Geographic supply concentration centers on the United States, Canada, and Belgium for reactor-based iodine-131 production, with raw material dependencies spanning uranium fuel cycles, specialized reactor targets, and pharmaceutical-grade sodium iodide. Single-source vulnerability runs through unplanned maintenance outages at aging reactor infrastructure. Distribution runs through hospital-based nuclear medicine departments consolidating away from centralized radiopharmaceutical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward integrated hospital systems consolidating regional referral volume through thyroid cancer centers of excellence, fragmenting purchasing authority previously held by standalone community practices.
For Market Incumbents: Build regulatory moats through NRC licensure expansion into underserved metropolitan markets. Deepen backward integration into isotope production networks to offset supply vulnerability from reactor concentration. Prioritize biomarker-driven patient selection partnerships with molecular diagnostic platforms to defend against kinase inhibitor displacement in refractory settings. For New Entrants and Emerging Players: Establish a beachhead in telemedicine-integrated thyroid nodule assessment for rural and underserved U.S. counties. Target molecular testing for indeterminate cytology specimens as the most penetrable segment given lower capital barriers and faster reimbursement pathways. Pursue go-to-market angles through payer contracts bundling diagnostic testing with specialist consultation fees. For Investors and Strategic Acquirers: FDA breakthrough therapy designation for RET and NTRK inhibitors reshapes the acquisition landscape toward precision oncology platform targets. Long-term viability favors developers with biomarker-driven trial infrastructure spanning curative-intent and refractory disease settings. Acquisition target archetypes include molecular diagnostic firms with thyroid-specific gene expression classifiers and kinase inhibitor specialists with Asian regulatory dossiers. Monitor PMDA abbreviated approval pathway utilization rates as inflection indicator for geographic portfolio prioritization.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Captive isotope production networks reduce dependency on concentrated North American reactor infrastructure. |
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses development timelines for targeted kinase inhibitors in refractory settings. |
| Hospital System Partnership | Vertically integrated delivery networks consolidate regional thyroid cancer referral volume through centers of excellence. |
| Pipeline Diversification | Immuno-oncology combinations pairing anti-PD-1 antibodies with radioactive iodine address radioiodine-refractory segments. |
| Geographic Expansion | PMDA abbreviated approval pathways enable faster commercial entry for kinase inhibitor portfolios in Japanese markets. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with nuclear medicine physicians, hospital procurement managers, formulary directors, and regulatory affairs specialists; and secondary validation through FDA filings, NRC licensing databases, ClinicalTrials.gov entries, and CMS reimbursement schedules. Bottom-up segmentation modeling triangulated against top-down market sizing from radiopharmaceutical production records and hospital discharge data.
Forecast inputs considered treatment sequencing patterns across surgery, radioactive iodine, and emerging systemic therapy modalities; diagnostic method adoption curves for molecular testing versus standard cytology; and end-user concentration trends among integrated delivery networks. CAGRs were derived from patient volume projections, procedure reimbursement trajectories, and therapy mix shifts across the analysis window. Industry-specific inputs included NRC licensing capacity expansion timelines and PMDA abbreviated approval pathway utilization rates.
Sensitivities concentrate around reactor maintenance schedules, Medicare bundling policy revisions, and molecular diagnostic reimbursement determinations. Forecasts reflect documented assumptions regarding regulatory pathway efficiency and isotope supply continuity. Quarterly review of NRC licensing issuance rates, PMDA approval velocity, and hospital system consolidation announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Lung Transplant Therapeutics Market
Specialty Medicine
Global Scleroderma Therapeutics Market
Specialty Medicine
Psoriatic Arthritis (Psa) Treatment Market
Specialty Medicine
Global Cryptococcosis Treatment Market
Specialty Medicine
South America Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Chemotherapy Induced Peripheral Neuropathy Treatment Market
Specialty Medicine
Metabolic Disorders Therapeutics Market
Specialty Medicine
Neuromuscular Disorders Treatment Market
Specialty Medicine
Global Epilepsy Market
Specialty Medicine
Polymyalgia Rheumatica Treatment Market
Specialty Medicine
Klinefelter Syndrome Treatment Market
Specialty Medicine
Osteomyelitis Market
Specialty Medicine
Major Depressive Disorder (MDD) Treatment Market
Specialty Medicine
Atopic Dermatitis Market
Specialty Medicine
Global Fungal Keratitis Treatment Market
Specialty Medicine
Food Allergy Treatment Market