
 Lithium Chloride Market | 2026-2036
Lithium Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Chloride Market Outlook
Long-term supply contracts with embedded price-adjustment mechanisms is pivoting how lithium chloride gets monetized, shifting value capture from spot transactions to structured service relationships. Albemarle Corporation leverages its Chilean brine assets to sustain multi-year offtake agreements with cathode producers. Ganfeng Lithium anchors its competitive position through backward integration into spodumene and brine resources across multiple continents. Tianqi Lithium differentiates via vertical control over the Greenbushes hard-rock operation, securing feedstock priority for its chloride conversion facilities.
Lithium chloride is an inorganic salt with the formula LiCl, typically produced at purity levels ranging from technical grade to battery grade exceeding 99.5 percent lithium content through solar evaporation of brine or acid leaching of spodumene concentrate; its primary industrial purpose centers on serving as a precursor for lithium metal and specialized electrolyte formulations in next-generation batteries. Battery grade material commands the most concentrated margin pool as cathode and solid-state battery developers enforce stringent particle-size and impurity specifications. Industrial grade applications in desiccants and refrigerants represent a mature volume base with steadier but lower-margin demand profiles. The automotive end-user segment is pulling disproportionate volume growth as OEMs qualify lithium-metal anodes for extended-range platforms.
China's SAMR enforces GB/T standards for battery-grade lithium salts that determine market access for domestic and imported material alike. The EU REACH framework and emerging Battery Regulation criteria are restricting heavy-metal thresholds in lithium chemicals sold across European member states. The US EPA oversees wastewater discharge limits at brine processing facilities, influencing where domestic conversion capacity can locate. Stakeholders must monitor how jurisdictional purity standards diverge and whether dual-certification strategies become necessary for cross-border supply security.
Market Dynamics
Long-term offtake agreements with embedded price-adjustment clauses are restructuring how lithium chloride flows from brine processors to cathode manufacturers, compressing spot-market liquidity and elevating supplier qualification to a strategic bottleneck.
Growth Catalysts
- EU Battery Regulation:Mandatory recycled-content thresholds and carbon-footprint declarations for lithium salts sold across member states are pulling battery-grade chloride demand toward certified European supply chains.
- Solid-state electrolyte development:Lithium-metal anode architectures are absorbing chloride-derived lithium metal at accelerating rates as automotive OEMs qualify extended-range platforms.
- Qinghai brine cluster scale:Solar evaporation infrastructure in China's high-altitude salt lakes has achieved unit-cost parity with Chilean operations, redirecting investment toward domestic conversion capacity.
Market Restraints
- Spodumene concentrate volatility:Hard-rock lithium ore prices swing with electric-vehicle production schedules, transmitting cost instability into acid-leaching chloride operations.
- Chilean-Argentine brine dominance:Two South American salt-flat systems control roughly two-thirds of economically recoverable lithium reserves, concentrating geopolitical and drought-exposure risk.
- Technical impurity floors:Battery-grade specifications for sodium, potassium, and magnesium content sit below 50 parts per million, requiring multi-stage crystallization that caps throughput at existing facilities.
Strategic Opportunities
- US Inflation Reduction Act:Critical mineral sourcing requirements for electric-vehicle tax credits are incentivizing domestic chloride conversion investments outside traditional brine jurisdictions.
- Direct lithium extraction:Selective sorbent and membrane technologies are converging with renewable geothermal brine operations, enabling production from previously subeconomic feedstocks.
- Industrial desiccant premiumization:Humidity-control applications in pharmaceutical packaging and electronics manufacturing are absorbing technical-grade chloride at widening purity spreads.
Industry Challenges
- Process engineer scarcity:Brine chemistry expertise concentrated in Chile, Argentina, and China's Qinghai province cannot scale with announced greenfield projects, inflating compensation and delaying commissioning.
- Dual-certification timelines:Simultaneous compliance with China's GB/T standards and EU REACH documentation requires parallel laboratory testing programs that extend product qualification by twelve to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Chloride Market |
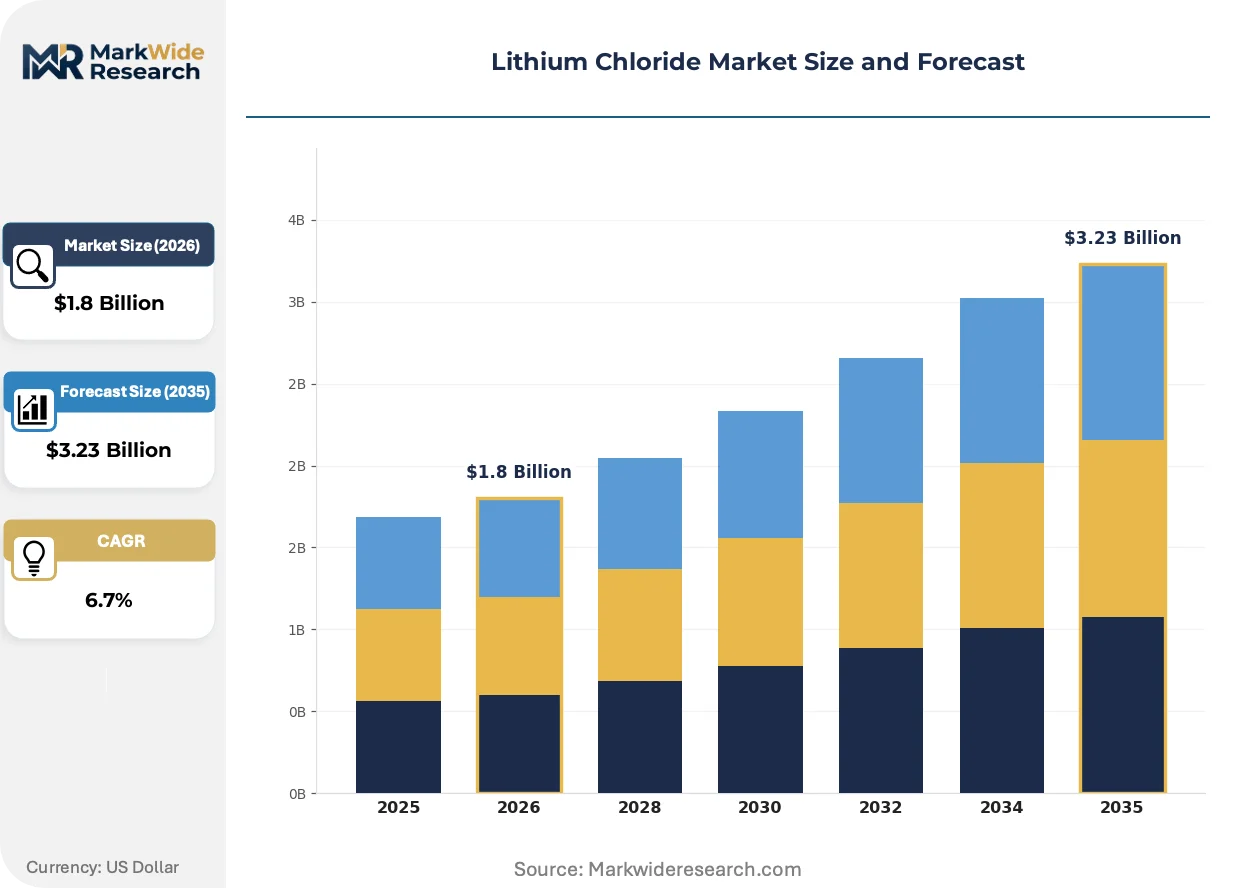
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Technical Grade, Industrial Grade, Battery Grade, Food Grade Application: Refrigerants, Desiccants, Fertilizers, Pharmaceuticals End User: Aerospace, Automotive, Chemicals, Electronics Distribution Channel: Online, Distributors, Direct Sales, Retail |
| Companies Covered | Albemarle Corporation, Ganfeng Lithium, Tianqi Lithium, SQM, Nippon Chemical Industrial, Leverton, Shenzhen Chengxin Lithium Group, Jiangxi Ganfeng Lithium, Qinghai Salt Lake Industry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Chloride Market Strategic Shifts
Electrolyte chemistry evolution and regulatory stringency are jointly compressing the acceptable impurity window for lithium chloride, forcing processors to retrofit crystallization trains and secure multi-jurisdictional certification ahead of product qualification cycles.
Solid-state battery architectures are absorbing chloride-derived lithium metal at accelerating rates. Automotive OEMs in South Korea and Japan have advanced lithium-metal anode pilot lines from laboratory to pre-production scale. This chemistry is absorbing technical talent and capital allocation that previously flowed toward liquid-electrolyte incremental improvements.
China's SAMR enforcement of GB/T 26008-2022 purity specifications for battery-grade lithium salts is tightening market access for imported material. Domestic processors in Jiangsu province have retrofitted solar evaporation ponds with automated impurity-monitoring systems. European cathode manufacturers are now dual-sourcing from Qinghai-certified and Chilean-certified supply chains to mitigate compliance risk.
Long-term contracting is displacing spot-market volume for battery-grade material. Cathode producers in Germany and Japan are negotiating five-year offtake agreements with fixed-volume, floating-price mechanisms indexed to lithium carbonate benchmarks. This pattern is most visible among tier-one automotive suppliers qualifying solid-state electrolyte precursors, where supply security outweighs price optimization in procurement criteria.
Lithium Chloride Market Segmentation
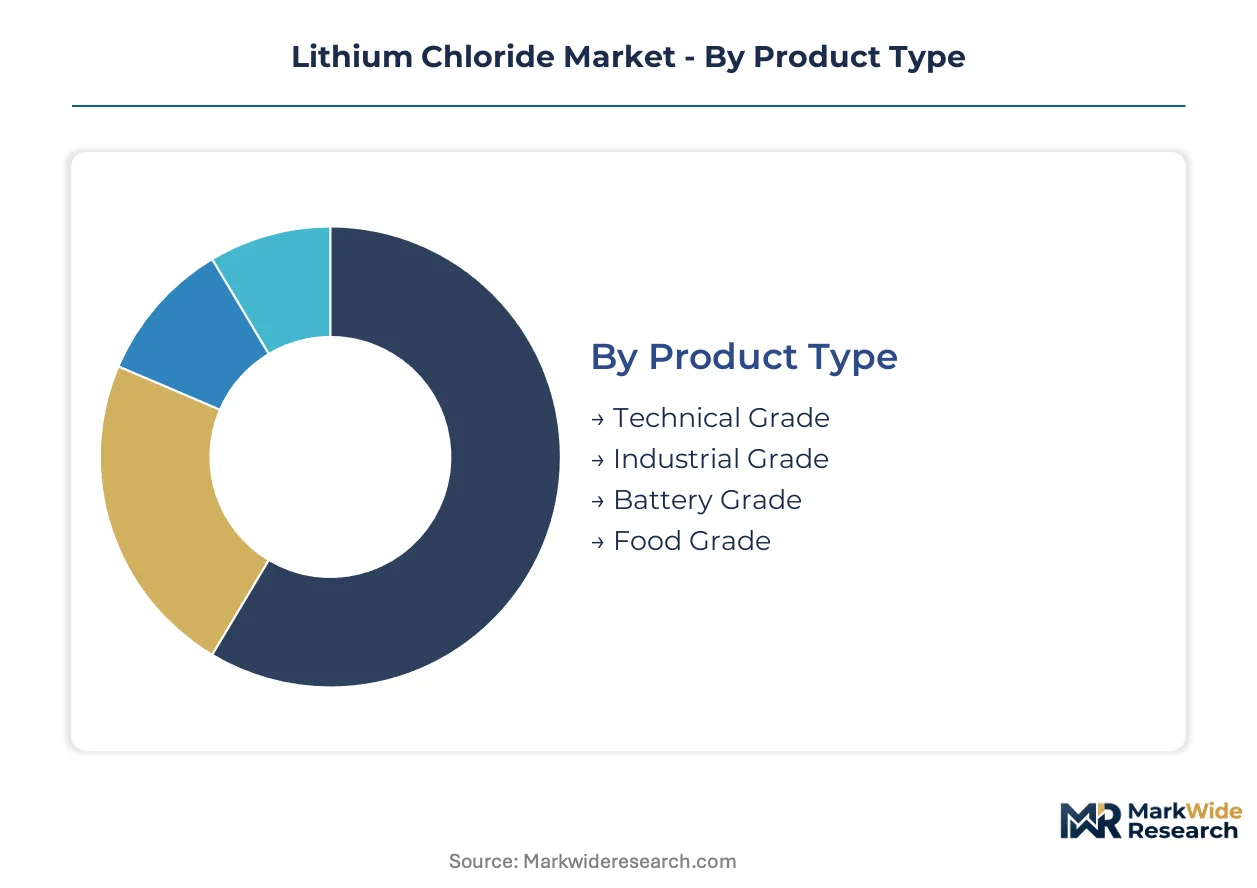
Lithium chloride procurement patterns diverge sharply across purity grades and end-use specifications, with battery-grade material commanding qualification-intensive supply relationships while industrial grades flow through commodity channels. Understanding these segment boundaries clarifies where margin pools concentrate and which technical thresholds determine market access.
Product Type:
Buyers in this category differentiate primarily by impurity tolerance and certification requirements, with battery-grade purchasers enforcing sub-50 ppm sodium thresholds that reshape processor capital allocation.
- Battery Grade:Purity exceeds 99.5 percent lithium content with stringent particle-size distribution and trace-metal controls. Solid-state battery developers in South Korea and Japan are absorbing this material at accelerating rates as lithium-metal anode platforms advance toward pre-production scale. Multi-stage crystallization requirements cap throughput at existing Qinghai and Atacama conversion facilities.
- Industrial Grade:Technical specifications center on hygroscopic performance for humidity-control applications rather than electrochemical purity. Desiccant manufacturers in pharmaceutical packaging and electronics assembly are widening purity spreads for technical-grade material with certified moisture-absorption rates.
- Technical Grade:Lower-purity salt serves welding flux and metallurgical applications where lithium content matters more than trace-element control.
- Food Grade:Meets pharmacopeial and food-additive standards for low-sodium salt substitutes and specialized nutritional formulations.
Industrial grade leads volumes today; battery grade is gaining share fastest.
Application:
Application segmentation tracks how lithium chloride's hygroscopic and electrochemical properties translate into distinct value propositions across thermal management, moisture control, and chemical synthesis.
- Desiccants:Humidity-control formulations exploit lithium chloride's exceptional moisture-adsorption capacity, with pharmaceutical blister packaging and semiconductor dry boxes representing high-specification demand pockets. Jiangsu province processors have automated impurity-monitoring systems to serve European packaging OEMs facing EU REACH documentation requirements.
- Refrigerants:Absorption-cycle cooling systems in industrial HVAC and mobile air-conditioning utilize lithium chloride brine solutions. The F-Gas Regulation is redirecting investment toward alternative refrigerant chemistries that incorporate lithium salts in closed-loop designs.
- Fertilizers:Lithium-enriched crop nutrients target specific soil-chemistry deficiencies in controlled-environment agriculture.
- Pharmaceuticals:Precursor applications in psychiatric medication synthesis and diagnostic reagent production require pharmacopeial certification.
Refrigerants anchor current volume; desiccants show the steepest expansion trajectory.
End User:
End-user segmentation reveals how downstream industry maturity and qualification intensity fragment demand into long-contract battery supply chains versus spot-market industrial procurement.
- Automotive:OEM qualification of lithium-metal anodes for extended-range electric platforms is pulling battery-grade chloride through cathode manufacturer offtake agreements. German and Japanese tier-one suppliers are negotiating five-year contracts with floating-price mechanisms indexed to lithium carbonate benchmarks.
- Chemicals:Broad industrial consumption spans catalyst manufacturing, polymerization initiators, and specialty synthesis where technical-grade material suffices.
- Aerospace:Lightweight desiccant systems and specialized thermal management applications serve satellite and aircraft humidity-control requirements.
- Electronics:Cleanroom humidity control and semiconductor manufacturing processes demand certified low-particulate desiccant formulations.
Chemicals processing leads volumes today; automotive is climbing the fastest.
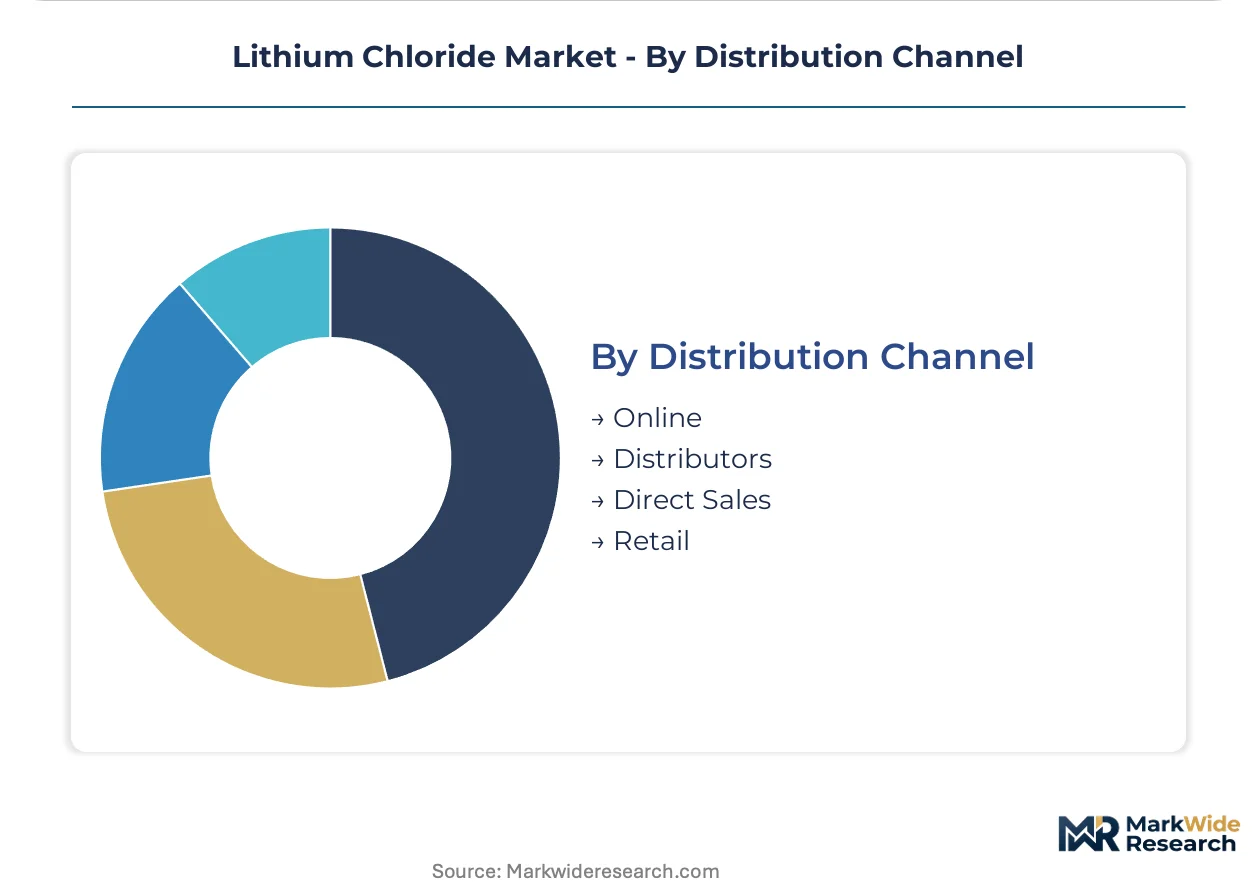
Distribution Channel:
Channel selection in this market reflects the tension between spot-market liquidity for industrial grades and the structured service relationships battery-grade procurement demands.
- Direct Sales:Long-term offtake agreements with embedded price-adjustment clauses dominate battery-grade flows, compressing spot-market availability. Albemarle Corporation leverages Chilean brine assets to sustain multi-year cathode producer relationships.
- Distributors:Technical and industrial grades move through regional chemical distributors serving fragmented desiccant and refrigerant formulators.
- Online:Spot-market platforms facilitate small-lot procurement for research quantities and specialty chemical synthesis.
- Retail:Consumer-facing channels serve hobbyist and small-scale industrial applications with packaged technical-grade material.
Direct sales commands battery-grade value; distributors handle the greatest tonnage across industrial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance gaps between jurisdictions are redirecting lithium chloride conversion capacity toward regions with streamlined permitting and lower environmental remediation burdens. Brine processors increasingly site operations where SAMR, EPA, and ECHA regulatory thresholds create arbitrage opportunities for battery-grade material qualification.
China
Jiangsu province cathode manufacturers and Qinghai brine processors dominate battery-grade chloride output. SAMR enforces GB/T 26008-2022 purity specifications that domestic converters meet through automated solar evaporation infrastructure. Qinghai's salt lake cluster has achieved unit-cost parity with Chilean operations, concentrating investment in high-altitude conversion facilities.
United States
The Inflation Reduction Act's critical mineral sourcing requirements are pulling battery-grade demand toward domestic supply chains. EPA wastewater discharge limits constrain brine processing location decisions, favoring geothermal brine operations in Nevada and California. Direct lithium extraction ventures in the Salton Sea region are advancing selective sorbent technologies for chloride production.
Chile
Atacama Desert brine operations supply the majority of South American lithium chloride feedstock. Chilean environmental regulators enforce water extraction quotas that limit evaporation pond expansion, concentrating output among incumbent operators with grandfathered permits. Antofagasta and Calama host the primary conversion infrastructure serving Asian cathode contracts.
Germany
EU Battery Regulation recycled-content thresholds and carbon-footprint declarations are reshaping import qualification requirements. ECHA REACH documentation mandates extend product approval timelines for non-European material. German cathode producers in Saxony and North Rhine-Westphalia are dual-sourcing from certified Asian and South American supply chains to mitigate compliance risk.
Japan
Solid-state battery developers in Osaka and Nagoya are accelerating lithium-metal anode qualification, pulling chloride-derived material through pre-production pilot lines. METI industrial policy supports domestic electrolyte chemistry research, though conversion capacity remains concentrated in partner jurisdictions. Japanese tier-one suppliers negotiate five-year offtake agreements with floating-price mechanisms indexed to lithium carbonate benchmarks.
Lithium Chloride Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated brine-to-chloride operators commanding battery-grade margins while toll converters serve industrial applications. The market exhibits tiered concentration: three to four vertically integrated players anchor long-term cathode supply relationships, while regional processors compete on technical-grade spot volumes. Strategic archetypes include brine-asset owners with captive conversion, hard-rock miners backward-integrating into chloride production, and pure-play refiners sourcing third-party feedstock. Dominant competitive moves center on multi-year offtake negotiations with embedded price-adjustment clauses and jurisdictional diversification to satisfy dual-certification requirements.
Within the integrated-asset tier, Albemarle Corporation and Ganfeng Lithium occupy positions defined by continental brine portfolios and multi-continent processing footprints. Tianqi Lithium exemplifies the hard-rock-to-chloride archetype through upstream control over Australian spodumene operations. These three entities represent the concentration of long-term contracting capacity, with each anchoring distinct geographic supply strategies—Chilean brine dominance, Chinese domestic scaling, and Australian feedstock security respectively.
| Leading Market Players |
|---|
| Albemarle Corporation |
| Ganfeng Lithium |
| Tianqi Lithium |
| SQM |
| Nippon Chemical Industrial |
| Leverton |
| Shenzhen Chengxin Lithium Group |
| Jiangxi Ganfeng Lithium |
| Qinghai Salt Lake Industry |
| Others |
Value Chain & Pricing Dynamics
Lithium carbonate benchmark indices cascade through lithium chloride value chains, compressing spot-market liquidity for battery-grade material while amplifying long-term contract premiums tied to cathode producer qualification timelines.
Pricing Analysis
Distributor margins for technical-grade lithium chloride range between 8-15 percent, while direct-to-OEM battery-grade contracts embed volume-discount mechanisms that compress intermediary participation. Three-tier pricing structure across battery-grade, technical-grade, and industrial-grade levels separates cathode manufacturer offtake agreements from desiccant formulator spot purchases. Cost compression in technical-grade segments is intensifying because Qinghai brine processors are automating crystallization trains. Battery-grade buyers at German and Japanese cathode plants show the lowest price sensitivity, prioritizing multi-year supply security over unit-cost optimization.
Supply Chain Analysis
Spodumene concentrate feedstock draws from Australian hard-rock mines and Chilean-Argentine brine evaporation ponds, with acid-leaching and solar-conversion routes competing on energy cost and impurity profiles. Lithium chloride supply concentrates in China, Chile, and Argentina, with Qinghai province and Atacama Desert operations anchoring global conversion capacity. Single-source vulnerability runs through Chilean water extraction quotas that cap evaporation pond expansion. Distribution runs through long-term offtake agreements for battery-grade material, while technical-grade flows via regional chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Lithium chloride functions as a stable compounder anchored by irreversible cathode chemistry commitments from automotive OEMs qualifying extended-range platforms.
For Market Incumbents: Anchor multi-year offtake relationships through embedded price-adjustment clauses indexed to lithium carbonate benchmarks. Secure backward integration into brine assets or spodumene concentrate offtake to defend feedstock priority against emerging direct lithium extraction ventures. Invest in dual-certification laboratory capacity to compress the 12-18 month qualification timeline for GB/T and REACH compliance. For New Entrants and Emerging Players: Launch via toll-processing arrangements with Qinghai brine operators lacking in-house chloride conversion capability. Target industrial desiccant segments in pharmaceutical packaging where moisture-absorption certification commands widening purity spreads. Pursue selective sorbent technology licensing from geothermal brine developers in Nevada's Salton Sea region. For Investors and Strategic Acquirers: Asymmetric upside sits with direct lithium extraction technology licensors capable of bypassing traditional evaporation pond infrastructure. Five-to-ten year viability favors processors with captive brine assets and demonstrated multi-jurisdictional certification. Watch for Chilean environmental regulator water quota announcements as inflection triggers for supply-constraint pricing.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Five-year cathode producer contracts with floating-price mechanisms secure volume commitment from German and Japanese tier-one suppliers. |
| Backward Integration | Upstream control over Greenbushes spodumene or Atacama brine assets eliminates feedstock competition for chloride conversion facilities. |
| Capacity Expansion | Qinghai solar evaporation retrofitting with automated impurity monitoring achieves unit-cost parity with Chilean operations. |
| Joint Venture | Geothermal brine partnerships in Nevada leverage selective sorbent technology for IRA-compliant domestic chloride production. |
| Green Manufacturing Transition | Closed-loop brine processing with renewable energy sourcing satisfies EU Battery Regulation carbon-footprint declaration requirements. |
Study Parameters
Multiple input streams — executive interviews with cathode procurement directors, technical discussions with brine process engineers, and validation sessions with chemical distribution channel managers — were reconciled against customs trade databases, SEC 10-K filings, and SAMR regulatory bulletins. Bottom-up volume estimates from individual conversion facility capacities were triangulated with top-down demand projections derived from electric vehicle production schedules and solid-state battery pilot line announcements.
Data-stream reconciliation across the analysis window applied grade-tier, end-use industry, and regional production hub segmentation to isolate battery-grade chloride premium dynamics from technical-grade commodity flows. CAGRs were derived from regression analysis of historical lithium carbonate price elasticity and forward-looking cathode capacity buildout announcements. Direct lithium extraction technology maturation curves and EU Battery Regulation compliance cost trajectories served as scenario-weighting inputs.
Several conditions sit outside the modeled scope, including unannounced drought events affecting Atacama evaporation rates, abrupt shifts in automotive OEM solid-state battery qualification timelines, and potential SAMR purity specification revisions. Forecasts reflect assumptions about sustained electric vehicle penetration and stable Chilean-Argentine diplomatic relations governing cross-border brine logistics. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Methyl Mercaptan Market
Bulk Chemicals
Naphthalene Market
Bulk Chemicals
Cobalt Acetate Crystals Market
Bulk Chemicals
Zinc Gluconate Granules Market
Bulk Chemicals
Asia-Pacific Ammonium Nitrate Market
Bulk Chemicals
North America Starch Derivatives Market
Bulk Chemicals
Bio-Succinic Acid Market
Bulk Chemicals
Iodine Market
Bulk Chemicals
Magnesium Lactate Market
Bulk Chemicals
Global Levulinic Acid Market
Bulk Chemicals
Global Tetrahydrofuran Market
Bulk Chemicals
Nahcolite Market
Bulk Chemicals
Lithium Bromide Market
Bulk Chemicals
Europe Carbon Black Market
Bulk Chemicals
Refined Naphthalene Market
Bulk Chemicals
Aerospace and Defense Chemical Distribution Market