
 Formic Acid Market | 2026-2036
Formic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Formic Acid Market Intelligence
Demand from specialized agricultural end-users seeking high-purity grades for feed preservation is bifurcating the market from traditional industrial consumers in leather tanning. BASF SE leverages its extensive global distribution network and integrated production capabilities to serve diverse applications. Eastman Chemical Company specializes in advanced chemical intermediates, including specific formic acid grades for various industrial processes. Gujarat Narmada Valley Fertilizers & Chemicals Limited anchors its position through large-scale production capacity primarily serving the Indian domestic market.
Formic acid, with the chemical formula HCOOH, is the simplest carboxylic acid, characterized by its pungent odor and corrosive properties. Primarily produced through the carbonylation of methanol, it functions as a potent preservative and antibacterial agent in various industrial settings. The agriculture application, particularly for silage treatment, represents the fastest-growing demand segment, outpacing traditional uses like leather tanning. While industrial grade formic acid constitutes the largest volume, higher-margin opportunities are found in food grade and pharmaceutical grade products.
Market access and product formulation are governed by a complex web of regulations, including Europe's REACH framework managed by ECHA and the EPA's registration requirements in the United States. In China, the Ministry of Ecology and Environment (MEE) imposes stringent standards on industrial effluent and emissions from formic acid production facilities. Producers must now decide whether to optimize existing carbonylation processes or invest in nascent biomass conversion methods to align with sustainability mandates.
Market Dynamics
The central dynamic in the formic acid market is the tension between legacy methanol carbonylation production and emerging, sustainable biomass conversion routes. This shift is driven by a combination of stringent environmental regulations and demand from agricultural end-users for greener inputs.
Growth Catalysts
- Antibiotic Reduction Policies:European regulations under the EU Green Deal limiting antibiotic use in livestock feed directly stimulate demand for formic acid as an effective, non-antibiotic preservative and antibacterial agent in animal nutrition.
- Livestock Sector Expansion:Rapid growth in the pork and poultry industries across Southeast Asian nations necessitates greater use of silage and feed preservatives to ensure feed quality and security, increasing regional formic acid consumption.
- Biomass Conversion Technology:Innovations in the gasification and fermentation of lignocellulosic materials are creating commercially viable pathways for producing 'green' formic acid, attracting customers with corporate sustainability mandates.
Market Restraints
- Feedstock Price Volatility:The market's reliance on the methanol carbonylation process ties formic acid production costs directly to the fluctuating price of methanol, which is subject to global energy market instability and supply disruptions.
- Substitution from Other Acids:In certain feed preservation and cleaning applications, formic acid faces competition from substitutes like propionic acid, lactic acid, and other organic acid blends which can offer different cost-performance profiles.
- Corrosive Properties:The inherent corrosivity of formic acid necessitates specialized stainless steel or polymer-lined storage tanks and transportation equipment, increasing logistical complexity and overall handling costs for distributors and end-users.
Strategic Opportunities
- Agricultural Modernization in Latin America:The adoption of modern farming techniques in countries like Brazil and Argentina creates an opportunity for market penetration, particularly for formic acid as a silage additive to improve feed quality for growing cattle herds.
- Hydrogen Carrier Applications:Emerging use of formic acid as a stable, liquid organic hydrogen carrier (LOHC) for hydrogen storage and transport presents a high-value, technology-driven opportunity outside of its traditional industrial and agricultural uses.
- High-Purity Grade Development:There is significant margin potential in developing and marketing ultra-pure formic acid grades for specialized sectors, including pharmaceutical synthesis, semiconductor cleaning, and as a mobile phase in laboratory chromatography.
Industry Challenges
- High Capital Investment:Producers face significant capital expenditure to either build new biomass-based production facilities or to retrofit existing plants with advanced pollution control systems to comply with stringent emissions standards from regulators like China's MEE.
- Multi-Regional Compliance Burden:Obtaining and maintaining regulatory approvals for products across different jurisdictions, such as registering under both Europe's REACH framework and with the US EPA, is a costly and time-consuming process that can delay market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Formic Acid Market |
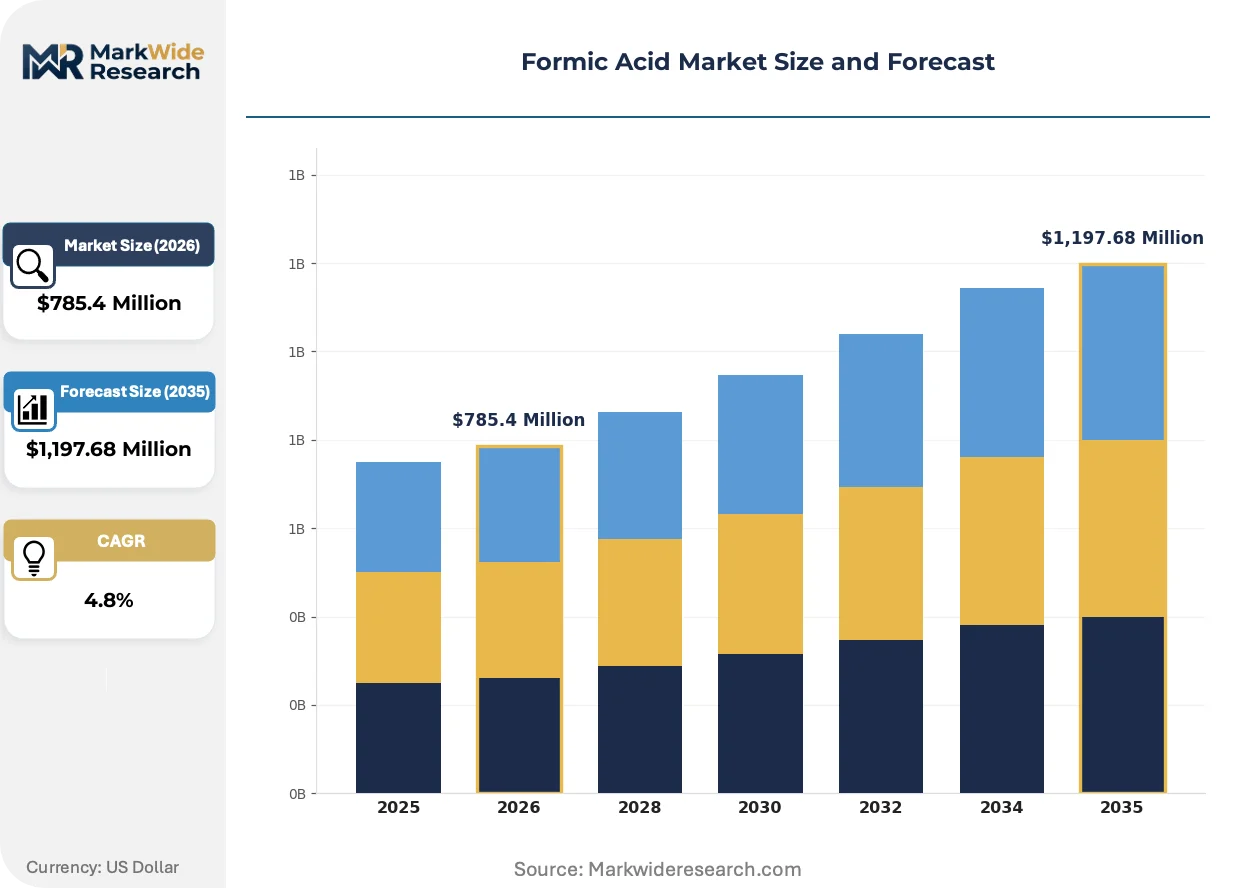
| Market Size in 2026 | $785.4 Million |
| Market Size in 2035 | $1,197.68 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Leather Tanning, Textiles, Pharmaceuticals, Agriculture Grade: Industrial Grade, Food Grade, Reagent Grade, Technical Grade Production Method: Sodium Formate Method, Carbonylation, Hydrolysis, Biomass Conversion End User: Chemical Manufacturers, Textile Producers, Food Industry, Agricultural Sector |
| Companies Covered | Feicheng Acid Chemicals Co., Ltd., Gujarat Narmada Valley Fertilizers & Chemicals Limited, BASF SE, Mitsubishi Gas Chemical Company, Inc., Chongqing Chuandong Chemical (Group) Co., Ltd., Eastman Chemical Company, Luxi Chemical Group Co., Ltd., Anhui Asahi Kasei Chemical, Perstorp AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Formic Acid Market Strategic Shifts & Innovations
Sustainability mandates and the pursuit of production efficiency are fundamentally altering the formic acid market. Innovation is focused on creating greener production pathways and developing specialized grades that command higher value, moving beyond traditional bulk chemical applications.
Biomass conversion technology, which utilizes feedstocks like wood waste, is a key area of development for producing 'green' formic acid. Environmentally conscious buyers in the food, feed, and pharmaceutical sectors are actively seeking these sustainable alternatives. This new production route is displacing a portion of the market traditionally dominated by methanol-based carbonylation, particularly for premium-grade applications.
China's "dual carbon" policy and strict MEE regulations are forcing significant operational changes. These rules impose tight limits on wastewater and air emissions from chemical production facilities. The leather tanning sector, a major consumer, is heavily impacted, which accelerates the industry's move toward more resource-efficient processes and closed-loop systems to minimize environmental discharge.
A notable behavioral shift is the move by large agricultural cooperatives and feed producers toward direct sourcing agreements. This model often bypasses traditional chemical distributors for high-volume purchases of specific grades used in applications like silage treatment. This trend is most visible in North America and Europe, where large-scale operators prioritize supply chain stability and cost transparency.
Formic Acid Market Segmentation
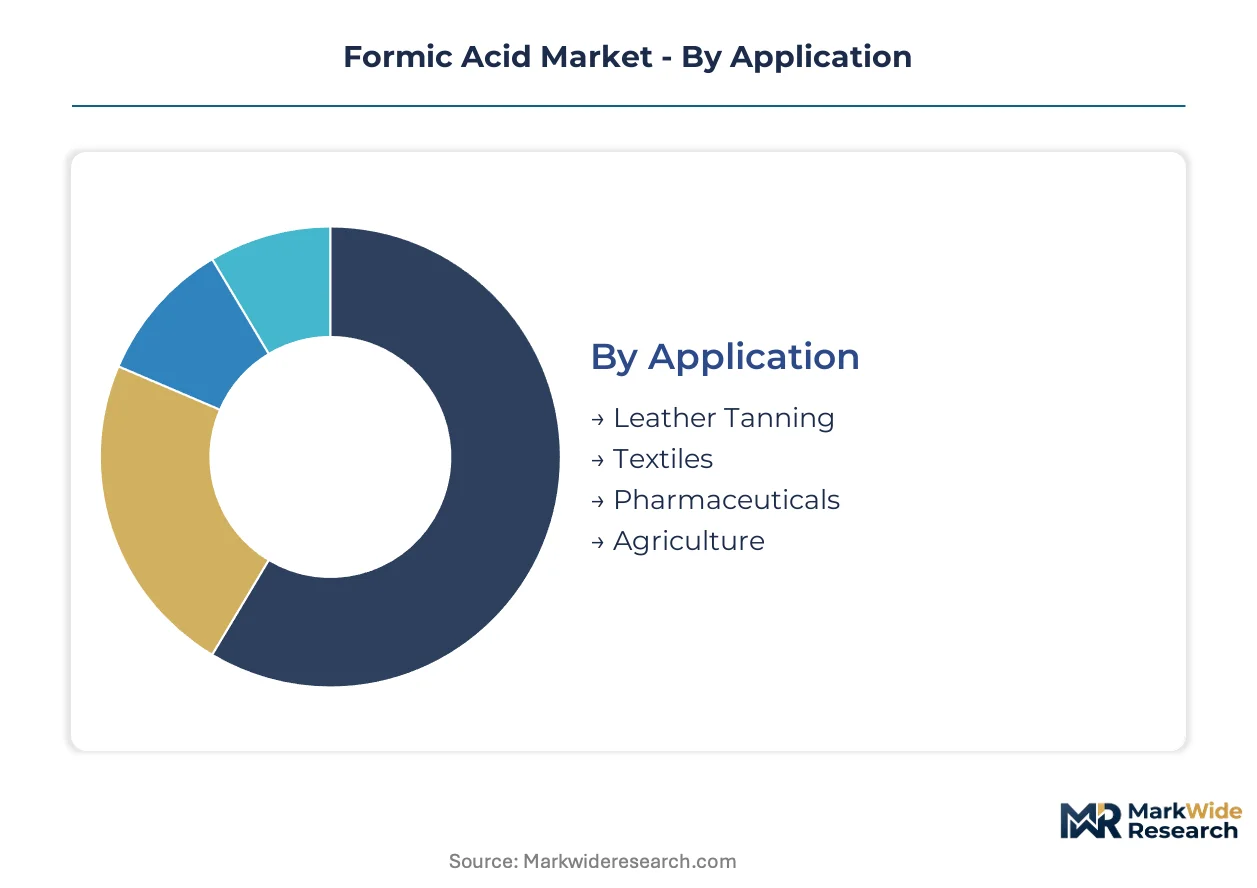
The formic acid market diversifies across various applications, grades, production methods, and end-users. Understanding these distinct segments illuminates the varying demand drivers and competitive dynamics influencing market participants. Each category presents unique challenges and opportunities for producers.
Application:
The application landscape for formic acid faces varying degrees of substitution pressure, particularly from alternative organic acids in preservation and traditional processes in industrial uses.
- Agriculture:This application leverages formic acid as a potent silage additive and animal feed preservative, improving nutritional value and preventing spoilage. Demand is concentrating in Southeast Asia due to the rapidly expanding pork and poultry industries.
- Leather Tanning:Formic acid acts as a deliming agent and pH regulator in the leather processing industry, preparing hides for subsequent tanning steps. Environmental regulations, especially from China's MEE, are forcing this sector to adopt more resource-efficient practices.
- Textiles:Formic acid functions as a dyeing and finishing agent, enhancing color fastness and fabric properties in textile manufacturing.
- Pharmaceuticals:It serves as a solvent, reducing agent, or intermediate in the synthesis of various pharmaceutical compounds and active ingredients.
Leather Tanning anchors the volume base while Agriculture gains share at the steepest rate.
Grade:
Formic acid grades differentiate significantly by purity levels, directly impacting their margin potential and suitability for sensitive applications.
- Industrial Grade:This grade represents the largest volume segment, characterized by standard purity levels suitable for bulk chemical manufacturing, leather processing, and basic cleaning formulations. Its widespread use underpins the market's foundational demand across various heavy industries.
- Food Grade:Meeting stringent purity standards, this grade is critical for feed preservation, food additives, and certain food processing applications. European regulations on antibiotic reduction in livestock directly stimulate demand for this high-purity product.
- Reagent Grade:This grade offers high purity for laboratory use, analytical testing, and specialized chemical synthesis where precise concentrations are required.
- Technical Grade:With purity levels above industrial but below reagent, this grade finds use in specific industrial processes requiring moderate chemical specifications.
Higher purity grades command premium pricing, reflecting their specialized processing and stringent quality control.
Production Method:
Sustainability mandates and the drive for reduced environmental impact are influencing the evolution of formic acid production methods.
- Carbonylation:This is the predominant industrial method, involving the reaction of methanol with carbon monoxide to produce methyl formate, which is then hydrolyzed to formic acid. It benefits from established infrastructure but faces feedstock price volatility.
- Biomass Conversion:Emerging technologies like gasification and fermentation of lignocellulosic materials offer a 'green' pathway for formic acid production. This method aligns with corporate sustainability objectives, particularly for environmentally conscious buyers.
- Sodium Formate Method:This traditional method involves the reaction of sodium hydroxide with carbon monoxide, followed by acidification to yield formic acid.
- Hydrolysis:This method typically refers to the hydrolysis of methyl formate, often an intermediate from carbonylation, to produce formic acid and methanol.
While traditional methods continue to dominate output, new technologies are attracting investment for long-term growth.
End User:
Demand for formic acid concentrates within specific end-user industries, each with distinct consumption patterns and purity requirements.
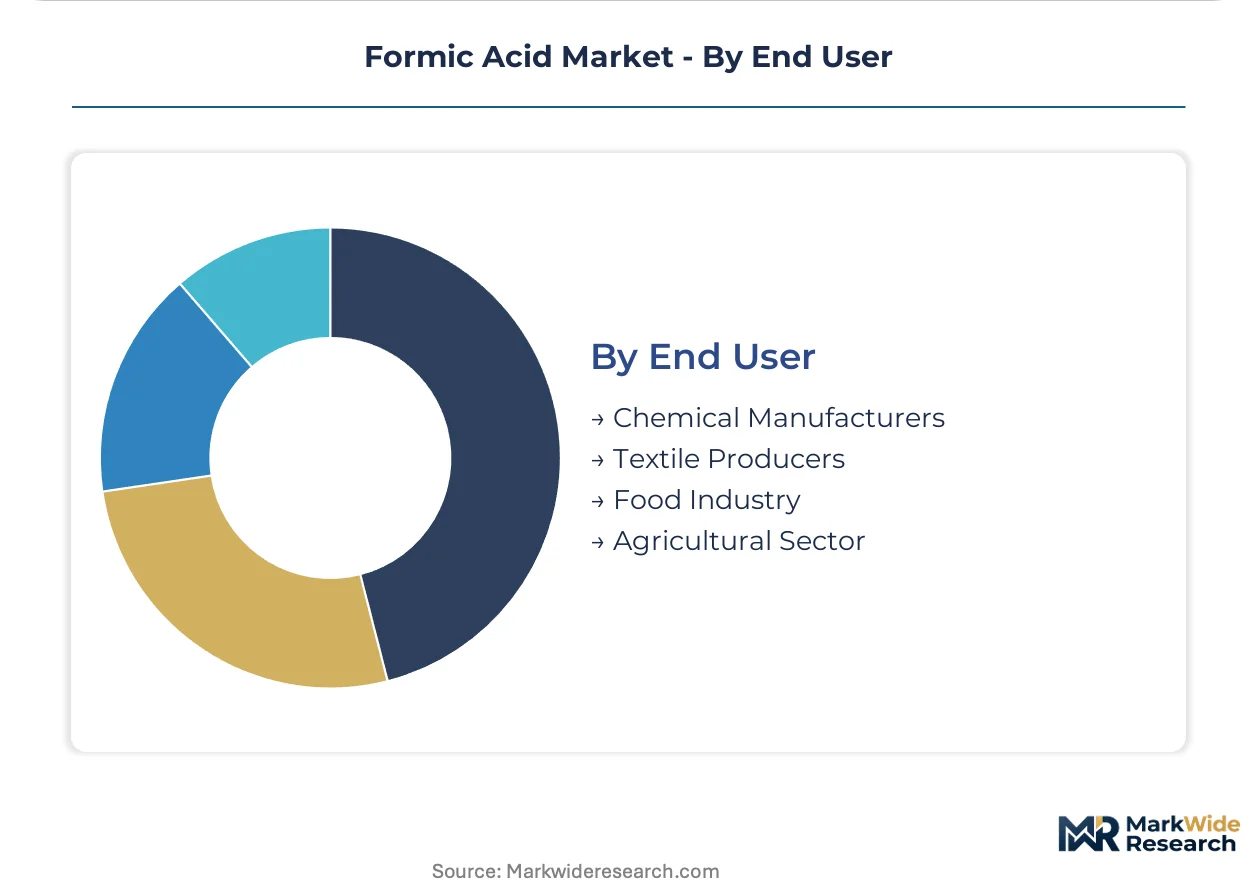
- Agricultural Sector:This sector utilizes formic acid extensively for silage preservation, animal feed acidification, and as an antibacterial agent in livestock nutrition. Policies limiting antibiotic use in Europe directly elevate demand for this application.
- Chemical Manufacturers:These entities use formic acid as a key intermediate in the synthesis of various organic chemicals, including formates, esters, and other specialty chemicals. They often require industrial or technical grades for their processes.
- Food Industry:Formic acid serves as a food additive, preservative, and flavoring agent in specific food products, adhering to strict food-grade regulations.
- Textile Producers:This industry employs formic acid in dyeing processes, fabric finishing, and as a reducing agent for certain textile treatments.
The agricultural sector drives significant volume expansion, with chemical manufacturers providing foundational demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's chemical exports to Southeast Asian agricultural markets drive significant formic acid trade. This global market sees diverse regional demand patterns influenced by local regulations and industrial development. Biomass conversion technologies are reshaping supply chains in several key geographies.
China
China's extensive chemical manufacturing and livestock industries create substantial demand for formic acid. The Ministry of Ecology and Environment (MEE) imposes stringent standards on industrial effluent and emissions from production facilities. Chemical producers in the Yangtze River Delta are investing in advanced pollution control systems to comply with these regulations.
United States
Agricultural modernization and demand for advanced chemical intermediates support formic acid consumption in the United States. The Environmental Protection Agency (EPA) maintains strict registration requirements for chemical products, influencing market access. Producers in the Gulf Coast chemical corridor focus on optimizing carbonylation processes to meet industrial demand.
Germany
European antibiotic reduction policies under the EU Green Deal stimulate demand for formic acid as a feed preservative in Germany. The ECHA-managed REACH framework governs chemical market access and product formulation across the European Union. Chemical manufacturers in the Rhine-Main region are developing high-purity grades for pharmaceutical applications.
Brazil
Agricultural modernization in Brazil, particularly for growing cattle herds, drives demand for formic acid as a silage additive. National agricultural policies encourage the adoption of modern farming techniques to improve feed quality and security. Producers and distributors in São Paulo State are expanding their networks to serve the expanding agricultural sector.
India
India's extensive domestic chemical market and large-scale production capacities underpin formic acid consumption. The Bureau of Indian Standards (BIS) sets quality benchmarks for industrial chemicals, impacting local manufacturing. Gujarat-based producers like Gujarat Narmada Valley Fertilizers & Chemicals Limited serve the national market from their facilities.
Formic Acid Market Key Industry Players
Listed leaders compete with private specialists across production scale and purity grades in the formic acid market. The market exhibits a tiered structure, with large integrated chemical companies at the top and specialized regional players below. Strategic archetypes include global chemical giants, regional bulk producers, and niche players focusing on high-purity applications. Dominant competitive moves involve capacity expansion to meet agricultural demand and strategic partnerships for biomass conversion technologies.
Within the global chemical giant tier, BASF SE exemplifies extensive integrated production capabilities across diverse applications. This archetype leverages broad distribution networks to serve multiple end-use sectors, from agriculture to pharmaceuticals. Eastman Chemical Company occupies a position among advanced chemical intermediate specialists, developing specific formic acid grades for various industrial processes. Such specialists often focus on higher-purity products for niche, technology-driven markets. Gujarat Narmada Valley Fertilizers & Chemicals Limited anchors the Indian domestic market through its large-scale production capacity, characteristic of regional bulk producers.
| Leading Market Players |
|---|
| Feicheng Acid Chemicals Co., Ltd. |
| Gujarat Narmada Valley Fertilizers & Chemicals Limited |
| BASF SE |
| Mitsubishi Gas Chemical Company, Inc. |
| Chongqing Chuandong Chemical (Group) Co., Ltd. |
| Eastman Chemical Company |
| Luxi Chemical Group Co., Ltd. |
| Anhui Asahi Kasei Chemical |
| Perstorp AB |
| Others |
Cost & Logistics Intelligence
Europe's REACH framework gates supply qualification and enables price differentiation for compliant formic acid grades. This regulation ensures product safety while influencing market access and pricing tiers.
Pricing Analysis
A distinct pricing gap exists between traditional methanol-carbonylation-derived formic acid and newer biomass-converted 'green' alternatives. Contract-based long-term offtake agreements dominate industrial-grade transactions, while purity levels and certified sustainability attributes drive price differentiation. Feedstock price volatility, particularly for methanol, exerts downward pressure on commodity pricing. Pharmaceutical and food-grade buyers exhibit low price sensitivity, prioritizing quality and regulatory compliance.
Supply Chain Analysis
The global reliance on methanol as a primary feedstock for carbonylation processes creates a supply chokepoint, tying formic acid production directly to global energy market stability. Supply concentrates heavily in China, Germany, and the United States. Key dependencies include methanol and carbon monoxide. Feedstock price volatility represents a significant structural risk across the supply chain. Distribution runs through both traditional chemical distributors and direct sourcing agreements, especially for large agricultural cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The formic acid market is experiencing a significant buyer-power shift, driven by the consolidation of large agricultural cooperatives and feed producers. These entities increasingly pursue direct sourcing agreements, bypassing traditional distribution channels.
For Market Incumbents: Fortify existing market positions by investing in advanced biomass conversion technologies and expanding capacity for high-purity grades. This strategy mitigates the threat from emerging sustainable alternatives and stringent environmental regulations from bodies like China's MEE. Deepen vertical integration into key raw materials or secure long-term supply contracts to counter feedstock price volatility. Focus R&D efforts on novel applications beyond traditional bulk chemicals.
For New Entrants and Emerging Players: A service-layer gap exists in providing specialized, certified 'green' formic acid to mid-sized agricultural and pharmaceutical end-users. Target underpenetrated segments in Latin America, particularly for silage additives in modernizing farming sectors. Develop high-purity grades with clear sustainability credentials for these niche markets. A go-to-market angle emphasizing environmental benefits and supply chain transparency can differentiate offerings.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-cap chemical specialists possessing proprietary biomass conversion intellectual property or strong regional distribution networks. The market exhibits long-term viability, supported by agricultural demand and emerging hydrogen carrier applications. Identify acquisition targets that offer established access to high-growth agricultural markets or unique sustainable production capabilities. A key signal to watch is the successful commercial scale-up of novel biomass-to-formic acid facilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion (Biomass) | Meet demand for sustainable agricultural inputs. |
| Green Manufacturing Transition | Align with global sustainability mandates and attract environmentally conscious buyers. |
| Long-term Supply Agreement | Ensure stable feedstock access and secure high-volume customer commitments. |
| Joint Venture (Technology) | Accelerate development and commercialization of advanced biomass conversion processes. |
| High-Purity Grade Development | Capture higher margins in pharmaceutical and semiconductor applications. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through extensive primary interviews to gather qualitative insights into market dynamics. These discussions included plant managers, procurement leads, R&D directors, and agricultural cooperative managers. Secondary validation involved reviewing chemical industry reports, customs data, and regulatory filings from ECHA and EPA.
The analytical framework, applied across the analysis window, models market evolution based on historical trends and projected industry dynamics. Segmentation dimensions modeled include application, purity grade, production method, end-user sector, and regional regulatory environments. Compound annual growth rates were derived from a comprehensive analysis of market drivers and restraints. Key forecast inputs include methanol price projections and agricultural sector growth estimates.
Forecasts assume regulatory continuity in frameworks like REACH and under China's MEE; material policy shifts would require re-modeling. These projections reflect inherent assumptions; significant shifts in global energy markets or substitute technologies could alter outcomes. Practitioners should keep alternative scenarios live as market conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Lysine Market
Bulk Chemicals
North America Malic Acid Market
Bulk Chemicals
Styrene Market
Bulk Chemicals
Asia-Pacific Bitumen Market
Bulk Chemicals
Dicyclopentadiene (DCPD) Market
Bulk Chemicals
North America Titanium Dioxide Market
Bulk Chemicals
Global Bulk Ferroalloys Market
Bulk Chemicals
Pyridine Market
Bulk Chemicals
Methyl Cyclohexane Market
Bulk Chemicals
Sodium, Potassium, and Calcium Salts Market
Bulk Chemicals
Sodium Ferrocyanide Market
Bulk Chemicals
Palmitic Acid Market
Bulk Chemicals
Global Ammonium Phosphate Market
Bulk Chemicals
Sodium Bisulfite Market
Bulk Chemicals
Global Naphthalene Derivatives Market
Bulk Chemicals
Global Molten Sulfur Market