
 Desiccant Air Breather Market | 2026-2036
Desiccant Air Breather Market Size, Share, and Industry Trends Forecast 2026-2036
Desiccant Air Breather Market Insights
ISO 4406 cleanliness-class upgrades is collapsing the gap between commodity breathers and premium conditioned air systems. Donaldson Company Inc. leverages its filtration engineering heritage to dominate high-specification hydraulic applications. Parker Hannifin Corporation anchors North American distribution through its Motion Systems Group channel density. Bosch Rexroth Corporation differentiates via captive integration into its own hydraulic power unit portfolios.
A desiccant air breather is a moisture-adsorbing filtration device installed on fluid reservoirs, gearboxes, and storage vessels to prevent atmospheric water vapor and particulate ingress; typical units incorporate silica gel or molecular sieve media with particulate filtration ratings between 3 and 10 microns, regenerating through color-change indicators or replaceable cartridge designs. Silica gel breathers retain the largest volume share due to cost-effective humidity capacity across industrial equipment applications, while molecular sieves command premium positioning in pharmaceutical cleanrooms and electronics manufacturing where ultra-low dew points prove mandatory. Activated alumina segments occupy niche roles in high-temperature compressor installations where thermal cycling degrades organic desiccants.
EPA NESHAP standards for metalworking fluids and OSHA oil mist exposure limits compel manufacturers to seal reservoirs with validated breather systems rather than open vents. REACH restrictions on cobalt chloride indicator dyes force European suppliers toward methyl violet or proprietary orange-to-green transition chemistry. Stakeholders must weigh media replacement economics against sealed-system redesigns as predictive maintenance platforms integrate breather condition monitoring into broader fluid health dashboards.
Market Dynamics
ISO 4406 cleanliness-class upgrades are collapsing the gap between commodity breathers and premium conditioned air systems, forcing mid-tier suppliers to recertify or exit hydraulic and wind turbine applications entirely.
Growth Catalysts
- EPA NESHAP metalworking fluid standards:These mandates compel manufacturers to seal reservoirs with validated breather systems rather than open vents, expanding addressable equipment base across US metal fabrication.
- Wind turbine gearbox maintenance programs:Offshore and onshore wind fleets in Germany and Denmark drive specification-grade breather procurement as predictive maintenance platforms integrate condition monitoring.
- Silica gel humidity capacity:Cost-effective moisture adsorption across industrial equipment applications sustains volume leadership despite premium alternatives entering pharmaceutical cleanrooms.
Market Restraints
- REACH cobalt chloride restrictions:ECHA-mandated phaseout of indicator dyes forces European suppliers toward methyl violet chemistry, raising R&D compliance costs without price recovery mechanisms.
- Molecular sieve input concentration:Zeolite supply chains concentrate among specialty chemical producers in Germany and Japan, exposing buyers to single-source vulnerability for ultra-low dew point applications.
- Activated alumina thermal limitations:High-temperature compressor installations degrade organic desiccants, restricting addressable market to niche petrochemical and steel processing segments.
Strategic Opportunities
- Underpenetrated Indian precision manufacturing:BIS cleanliness standards for hydraulic fluids remain below ISO 4406 thresholds, creating first-mover advantage for certified breather suppliers as PLI scheme expands capital equipment.
- Electronics manufacturing dew point requirements:Semiconductor fabs in South Korea and Taiwan mandate molecular sieve performance levels that commodity silica gel cannot achieve, opening premium positioning.
- Fluid health dashboard integration:IoT-enabled breather condition monitoring converges with broader predictive maintenance platforms, enabling recurring revenue streams through cartridge replacement subscriptions.
Industry Challenges
- Filtration engineering talent scarcity:Cross-functional expertise spanning desiccant chemistry, particulate filtration ratings, and hydraulic system design concentrates among legacy Donaldson and Parker Hannifin engineering teams.
- ISO 4406 recertification timelines:Mid-tier suppliers face 18-24 month validation cycles to upgrade from commodity to specification-grade breather production, compressing cash conversion during transition.
- Legacy hydraulic power unit integration:Captive breather integration by Bosch Rexroth into proprietary portfolios forces independent suppliers to develop adapter kits for non-standard reservoir geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Desiccant Air Breather Market |
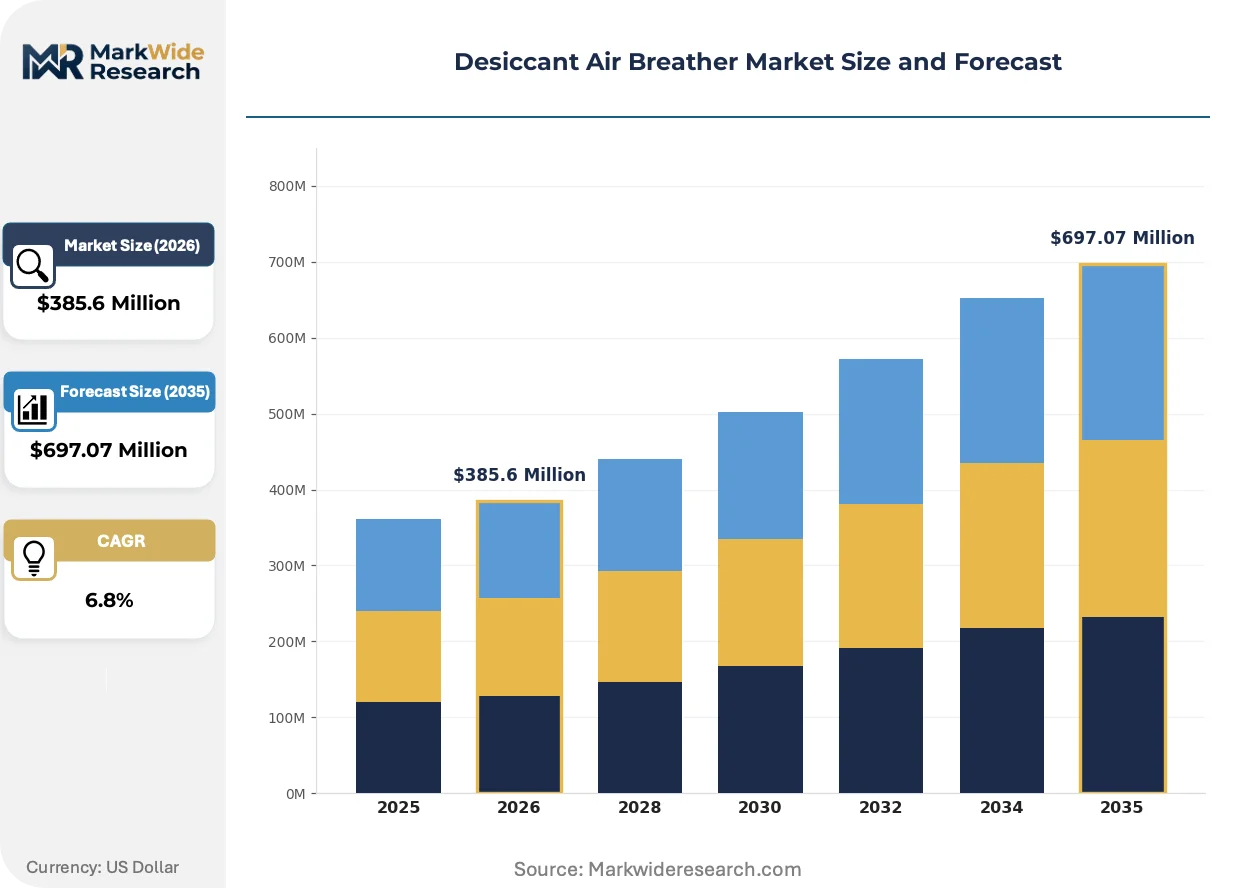
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $697.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silica Gel, Molecular Sieves, Clay, Activated Alumina End User: Manufacturing, Automotive, Electronics, Pharmaceuticals Application: Industrial Equipment, Air Compressors, Hydraulic Systems, Storage Tanks Packaging Type: Boxes, Bags, Bulk Containers, Pouches |
| Companies Covered | Des-Case Corporation, Donaldson Company Inc., Parker Hannifin Corporation, Eaton Corporation, HYDAC International GmbH, Bosch Rexroth Corporation, Drytech Inc., Schroeder Industries, Air Sentry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Desiccant Air Breather Market Trends and Innovations
Condition monitoring integration and indicator chemistry reformulation are actively reshaping competitive positioning, while end-use procurement patterns rotate toward lifecycle cost models over unit price.
Smart breather cartridges with embedded humidity sensors are bifurcating the installed base. Wind turbine operators in Denmark and Germany adopt these units fastest, compressing replacement cycle predictability into digital maintenance workflows and marginalizing color-change-only alternatives.
REACH restrictions on cobalt chloride indicator dyes are forcing chemistry transitions across European supply chains. Methyl violet and proprietary orange-to-green formulations now dominate ECHA-compliant production, with pharmaceutical and food-contact applications in Germany and Switzerland most affected due to traceability requirements.
Buyer evaluation criteria now center on total fluid lifecycle cost rather than breather unit price. Original equipment manufacturers in US hydraulic power unit assembly increasingly specify validated systems upfront, displacing aftermarket retrofit decisions and concentrating procurement authority with engineering rather than maintenance functions.
Desiccant Air Breather Market Segmentation
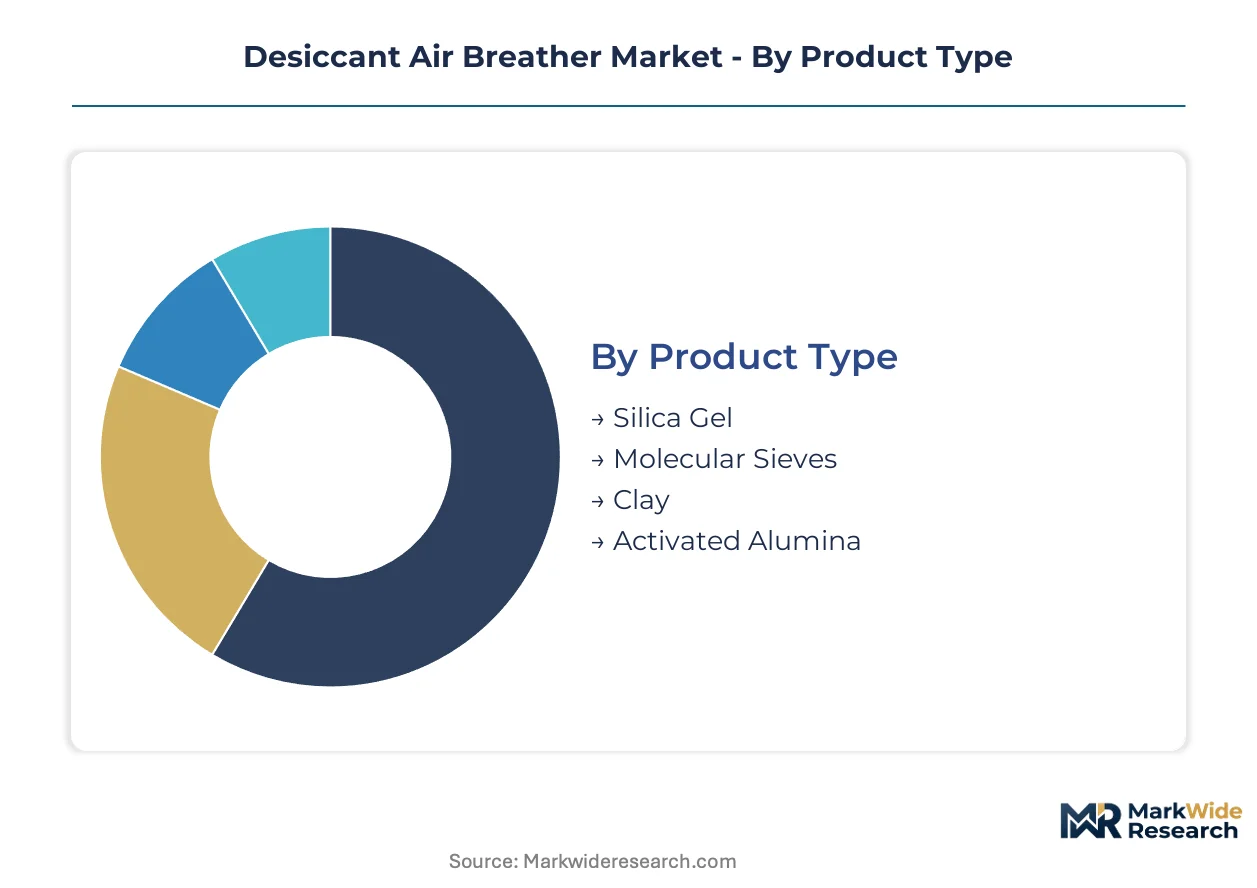
Desiccant air breather procurement splits sharply between specification-grade systems commanding lifecycle cost premiums and commodity units competing on replacement cartridge economics. Understanding where margin pools concentrate within each dimension reveals why engineering specifications now override maintenance department purchasing authority.
Product Type:
Margin pools concentrate in molecular sieve formulations where ultra-low dew point performance justifies 3-4x pricing multiples over silica gel alternatives.
- Molecular Sieves:Synthetic zeolite structures with precise pore apertures (3Å, 4Å, 5Å, 13X) enable dew points below -40°C. Semiconductor fabs in South Korea and Taiwan mandate this specification grade for cleanroom compressor protection, with ECHA REACH compliance adding indicator chemistry reformulation costs.
- Silica Gel:Amorphous silicon dioxide with high surface area (700-800 m²/g) provides cost-effective humidity capacity across industrial equipment. Wind turbine gearbox maintenance programs in Germany and Denmark drive volume procurement despite color-change indicator limitations under cobalt chloride restrictions.
- Clay:Natural montmorillonite offers moderate moisture adsorption at lower price points. Food packaging and agricultural machinery applications favor this segment where extreme dryness thresholds remain unnecessary.
- Activated Alumina:Aluminum oxide spheres withstand thermal cycling above 150°C that degrades organic desiccants. Petrochemical compressor installations and steel processing environments constitute the addressable niche.
Silica gel holds installed capacity. Molecular sieves are rotating up the share rankings.
End User:
Volume leadership sits with manufacturing, though electronics and pharmaceuticals concentrate the premium tier where validated systems displace commodity alternatives.
- Manufacturing:Metal fabrication, plastics processing, and general machinery operations generate baseline demand across ISO 4406 cleanliness thresholds. EPA NESHAP standards for metalworking fluids compel reservoir sealing with validated breather systems rather than open vents.
- Electronics:Semiconductor and flat-panel display manufacturing impose molecular sieve requirements for ultra-low dew point maintenance. Cleanroom protocols in Taiwan and South Korea reject silica gel performance limits.
- Automotive:Hydraulic power unit assembly lines and transmission fluid reservoirs constitute steady replacement demand. OEM specification authority increasingly concentrates procurement with engineering functions over aftermarket retrofit decisions.
- Pharmaceuticals:Sterile manufacturing and API storage mandate traceable indicator chemistry under ECHA and Swissmedic oversight. Methyl violet and proprietary orange-to-green formulations dominate ECHA-compliant production.
Manufacturing anchors volume procurement. Electronics is climbing the fastest toward specification-grade adoption.
Application:
Application selection determines breather sizing, filtration rating, and replacement cycle economics, with hydraulic systems commanding the most stringent validation requirements.
- Hydraulic Systems:Power units, presses, and mobile equipment require 3-10 micron particulate filtration combined with moisture adsorption. ISO 4406 cleanliness-class upgrades force mid-tier suppliers through 18-24 month recertification cycles.
- Industrial Equipment:Gearboxes, transformers, and lubrication systems span the broadest specification range. Wind turbine operators in Denmark and Germany adopt smart breather cartridges with embedded humidity sensors fastest.
- Air Compressors:Inlet and discharge moisture control protects downstream instrumentation. High-temperature installations favor activated alumina over organic desiccants vulnerable to thermal degradation.
- Storage Tanks:Bulk fluid and chemical storage requires large-capacity breather designs with extended service intervals. Petrochemical terminals and agricultural chemical depots drive demand for color-change monitoring at scale.
Industrial Equipment maintains broadest deployment. Hydraulic Systems is gaining share fastest through specification tightening.
Packaging Type:
Packaging configuration shapes logistics economics and replacement workflow integration, with bulk containers serving high-volume industrial accounts and pouches addressing distributed maintenance operations.
- Boxes:Rigid corrugated packaging protects cartridge integrity through distribution. OEM supply agreements and distributor stock-keeping favor this format for predictable consumption patterns.
- Bags:Flexible polyethylene or foil laminates reduce shipping cube for desiccant media refill quantities. Regional distributors serving fragmented maintenance accounts prefer this handling efficiency.
- Bulk Containers:Drum and tote quantities serve wind farm operators and manufacturing plants with centralized fluid management. Predictive maintenance platforms integrating breather condition monitoring enable subscription-based cartridge replacement at this scale.
- Pouches:Unit-dose packaging supports field service technicians and distributed equipment bases. Mining operations and remote infrastructure maintenance value portable replacement inventory.
Boxes dominate OEM specification channels. Bulk Containers is rotating up the share rankings through predictive maintenance integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty chemical producers in Germany and Japan concentrate molecular sieve supply chains for ultra-low dew point applications. Demand clusters concentrate in precision manufacturing corridors where ISO 4406 cleanliness mandates drive specification-grade procurement.
Germany
Wind turbine gearbox maintenance programs and precision manufacturing clusters drive specification-grade breather procurement. ECHA REACH restrictions on cobalt chloride indicator dyes force suppliers toward methyl violet chemistry. Bavaria and North Rhine-Westphalia host the densest concentrations of hydraulic power unit OEMs integrating validated breather systems.
United States
EPA NESHAP metalworking fluid standards compel reservoir sealing across metal fabrication operations. OSHA oil mist exposure limits tighten moisture control requirements for industrial fluids. Midwest manufacturing corridors and Gulf Coast petrochemical terminals generate concentrated demand for high-capacity storage tank breathers.
China
GB standards for hydraulic fluid cleanliness and MIIT industrial equipment modernization programs expand addressable equipment bases. Yangtze River Delta semiconductor fabs and Pearl River Delta electronics manufacturing impose molecular sieve requirements that commodity silica gel cannot satisfy.
India
BIS cleanliness standards for hydraulic fluids remain below ISO 4406 thresholds, creating first-mover positioning for certified suppliers. PLI scheme capital equipment expansion accelerates precision manufacturing adoption. Maharashtra and Gujarat industrial corridors concentrate early specification-grade breather deployment.
South Korea
Semiconductor fabs mandate molecular sieve performance levels for cleanroom compressor protection. MFDS pharmaceutical manufacturing oversight drives traceable indicator chemistry requirements. Gyeonggi-do and Seoul Capital Area electronics clusters reject silica gel performance limits for ultra-low dew point maintenance.
Desiccant Air Breather Market Competitive Landscape
Concentration sits with diversified filtration engineering conglomerates and captive hydraulic system integrators. The vendor base stratifies across three tiers: specification-grade specialists serving wind turbine and semiconductor applications, diversified industrial filtration conglomerates leveraging distribution density, and captive integrators embedding breathers into proprietary power unit portfolios. Dominant competitive moves include backward integration into desiccant media supply and predictive maintenance platform partnerships.
Among diversified filtration conglomerates, Donaldson Company Inc., Parker Hannifin Corporation, and Eaton Corporation exemplify archetypes leveraging engineering heritage and channel density. Donaldson occupies a position anchored in hydraulic application expertise, while Parker Hannifin sits within the North American distribution-centric tier. Eaton Corporation represents the diversified industrial portfolio approach. HYDAC International GmbH and Bosch Rexroth Corporation exemplify European-based specialists with captive integration strategies, with Bosch Rexroth embedding breather systems into proprietary hydraulic power unit portfolios.
| Leading Market Players |
|---|
| Des-Case Corporation |
| Donaldson Company Inc. |
| Parker Hannifin Corporation |
| Eaton Corporation |
| HYDAC International GmbH |
| Bosch Rexroth Corporation |
| Drytech Inc. |
| Schroeder Industries |
| Air Sentry |
| Others |
Pricing and Supply Chain Analysis
Eighteen-to-twenty-four month ISO 4406 recertification timelines concentrate pricing power with specification-grade specialists while compressing margins for mid-tier commodity suppliers attempting upstream migration.
Pricing Analysis
EPA NESHAP standards dictate the pricing tier structure across US metal fabrication, separating validated breather systems from open-vent commodity alternatives. Three-tier pricing stratifies across molecular sieve premium, silica gel standard, and clay-based economy levels, with certification grade and volume scale as primary differentiation drivers. Pricing pressure stems from REACH cobalt chloride restrictions forcing chemistry reformulation without price recovery mechanisms. Aftermarket retrofit buyers exhibit highest price sensitivity, while wind turbine OEMs prioritize lifecycle cost over unit economics.
Supply Chain Analysis
Forty-five to sixty days of safety stock for molecular sieve media reflects single-source vulnerability in Germany and Japan, where specialty chemical producers concentrate zeolite supply chains for ultra-low dew point applications. Raw material dependencies center on synthetic zeolites, silica gel substrates, and methyl violet indicator dyes. Tariff exposure on specialty chemical imports from Japan creates structural risk for US-based specification-grade assemblers. Distribution runs through Motion Systems Group channel density in North America and captive integration into proprietary hydraulic power unit portfolios for European OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward engineering functions as OEM specification authority concentrates procurement decisions, fragmenting traditional maintenance-department purchasing channels.
For Market Incumbents: Secure backward integration into desiccant media supply to defend against single-source zeolite vulnerability in Germany and Japan. Deepen predictive maintenance platform partnerships to lock in recurring cartridge replacement revenue before IoT-enabled challengers capture wind turbine condition monitoring workflows. For New Entrants and Emerging Players: ISO 4406 fast-track certification for hydraulic applications opens underpenetrated Indian precision manufacturing corridors where BIS standards lag international thresholds. Target electronics manufacturing in South Korea and Taiwan with molecular sieve performance levels that commodity silica gel cannot achieve, leveraging semiconductor fab procurement centralization for rapid reference customer acquisition. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because filtration engineering talent scarcity concentrates among legacy Donaldson and Parker Hannifin teams, making specialist engineering acquisitions the primary capacity expansion mechanism. Watch for predictive maintenance platform partnerships as the inflection signal separating recurring-revenue winners from transactional cartridge suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Desiccant Media | Captive zeolite supply from German specialty chemical producers mitigates single-source concentration risk. |
| Predictive Maintenance Platform Partnership | IoT-enabled condition monitoring with wind turbine operators in Denmark compresses replacement cycle predictability. |
| ISO 4406 Recertification Investment | Eighteen-to-twenty-four month validation cycles separate specification-grade suppliers from commodity tier exits. |
| REACH-Compliant Indicator Chemistry Reformulation | Methyl violet and orange-to-green transition chemistry maintains European market access under ECHA restrictions. |
| Electronics Manufacturing Dew Point Specialization | Molecular sieve performance for semiconductor fabs in South Korea commands 3-4x pricing multiples over silica gel. |
Research Methodology
The analysis maps desiccant media types, end-use industries, application specifications, and packaging configurations, each validated through maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads. Primary fieldwork combined with secondary validation from customs/trade data, SEC 10-K filings, and industrial equipment association reports enables bottom-up and top-down triangulation across market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, end user, application, and packaging format, with CAGRs derived from equipment installation bases and replacement cycle economics. Forecast inputs incorporated EPA NESHAP compliance timelines and wind turbine gearbox maintenance program adoption curves.
Underlying assumptions cover regulatory enforcement continuity, supply chain stability for zeolite inputs, and predictive maintenance platform integration rates, with deviation risk concentrated in REACH chemistry transition timelines and ISO 4406 recertification completion schedules. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Quality Control Systems
Asia-Pacific Air Quality Control System Market
Air Quality Control Systems
Environmental Control System (ECS) Market
Air Quality Control Systems
Emission Management Software Market
Air Quality Control Systems
Sustainable Air Filter Market
Air Quality Control Systems
Ozone Analyzer Market
Air Quality Control Systems
US Air Quality Analyzers Market
Air Quality Control Systems
Europe Nitrogen Oxide Control Systems Market
Air Quality Control Systems
Middle-East and Africa Industrial Air Quality Control Systems Market
Air Quality Control Systems
Air Pollution Control Equipment Market
Air Quality Control Systems
North America Industrial Air Quality Control Systems Market
Air Quality Control Systems
Southeast Asia Air Purifier Market
Air Quality Control Systems
Indoor Air Purification Market
Air Quality Control Systems
Air Quality Control Systems Market
Air Quality Control Systems
Ozone Generation Market
Air Quality Control Systems
UV Air Purifiers Market
Air Quality Control Systems
Asia-Pacific Indoor Air Purification Market