
 Ozone Analyzer Market | 2026-2036
Ozone Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Ozone Analyzer Market Analytics
EPA Method 205 and EN 14625 certification cycles is reorganizing competitive entry barriers for UV photometry suppliers. Teledyne API leverages its TUV-approved reference design footprint across North American ambient monitoring networks. Thermo Fisher Scientific anchors its position through captive optical component sourcing and in-house production of mercury-free UV lamps. HORIBA competes via JIS-compliant calibration protocols that satisfy Japanese industrial procurement standards.
An ozone analyzer measures ozone concentration in gas or liquid matrices using UV absorption at 254 nm, electrochemical redox reactions, or gas chromatographic separation with electron capture detection; instruments achieve detection limits from parts-per-billion to percent-level for applications spanning ambient air surveillance and semiconductor process control. Portable units dominate field deployment for emergency response and stack testing, while stationary UV photometry systems capture the bulk of regulatory compliance revenue in continuous ambient monitoring networks. Electrochemical sensors extend into cost-sensitive indoor air quality installations where drift tolerance trades against capital outlay.
The EPA enforces Clean Air Act NAAQS compliance through Federally Equivalent Methods that specify analyzer performance, while the EU Ambient Air Quality Directive mandates EN-standardized ozone measurement across member state reporting stations. China's MEE implements GB 3095-2012 ambient ozone limits with increasing calibration audit frequency. Buyers must weigh total cost of ownership against certification breadth as regulatory divergence between jurisdictions deepens.
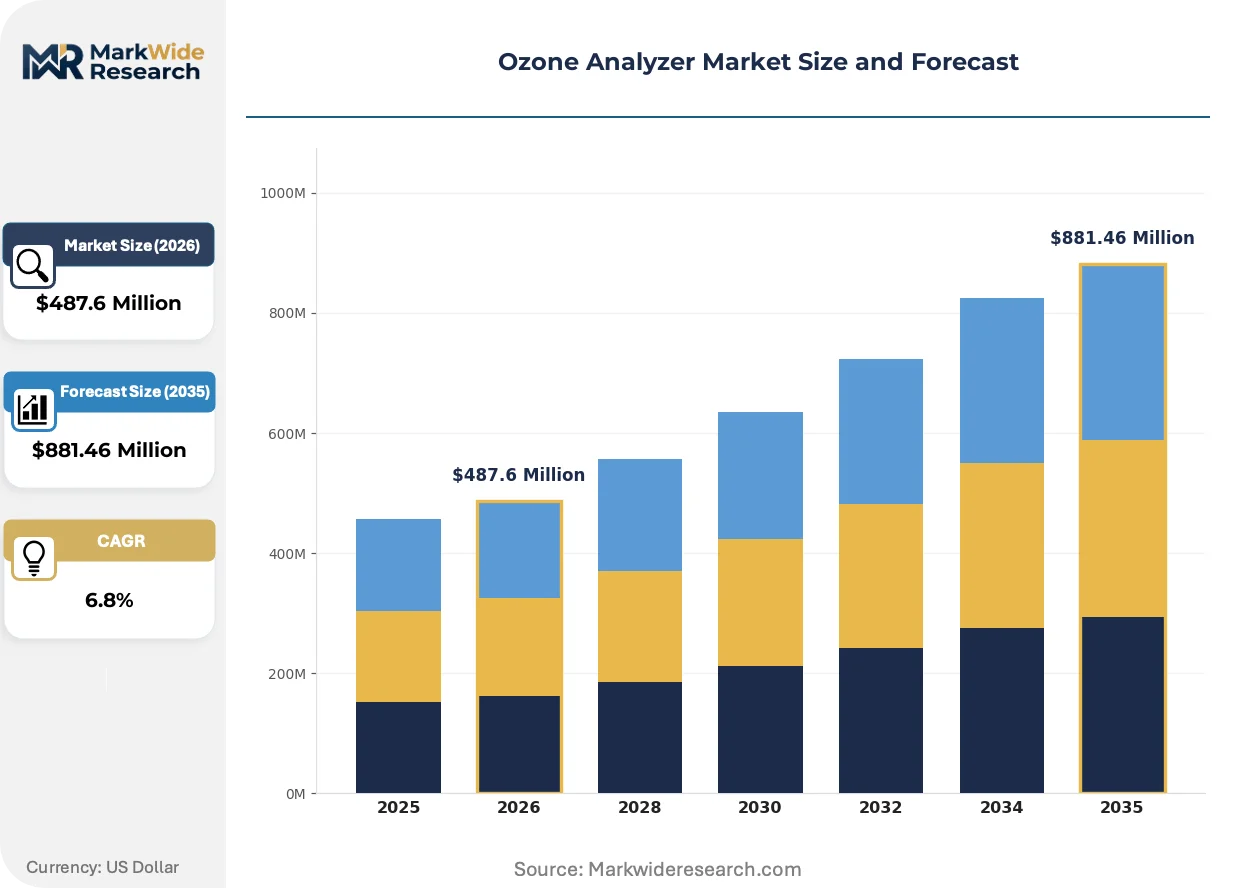
Market Dynamics
Precision requirements under tightening EPA and EU drinking water directives are compressing tolerance bands for residual ozone measurement, forcing utilities and industrial operators toward higher-grade UV photometry instrumentation with certified traceability chains.
Growth Catalysts
- EPA Method 205 certification cycles:Federally Equivalent Methods designation creates recurring revenue streams for compliant analyzer suppliers serving North American ambient monitoring networks.
- Semiconductor fab expansion:Process gas purity mandates in advanced node manufacturing drive demand for sub-ppb detection systems in cleanroom environments.
- Upper Rhine industrial corridor:German chemical manufacturers face intensified MEE emissions audits, accelerating replacement of legacy electrochemical sensors with UV photometry systems.
Market Restraints
- Mercury-free UV lamp supply concentration:Captive production of specialized lamps at a limited supplier base creates input bottleneck risk for mid-tier analyzer manufacturers.
- EN 14625 calibration infrastructure gaps:Scarce accredited laboratories in Eastern Europe extend certification timelines and raise total cost of ownership for utilities.
- Electrochemical sensor drift rates:Baseline degradation in humid environments limits deployment confidence for continuous compliance monitoring applications.
Strategic Opportunities
- Indian municipal water sector:BIS drinking water standards adoption lags behind EU equivalents, creating first-mover positioning for certified UV photometry suppliers as treatment capacity expands.
- Cloud-connected predictive maintenance:Remote calibration drift alerting converges with analyzer hardware to unbundle service contracts and capture recurring software revenue.
- Portable stack testing demand:Mobile units for MEE audit response represent underpenetrated replacement cycle opportunity against fixed-installation dominance in ambient networks.
Industry Challenges
- Cross-jurisdiction certification stacking:Simultaneous EPA, EN, and JIS compliance requirements fragment engineering resources and extend product development timelines for multi-regional suppliers.
- Optical component cleanroom assembly:UV photometer mirror alignment demands specialized technician labor that concentrates in German and Japanese manufacturing clusters, constraining geographic diversification of final assembly.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ozone Analyzer Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Stationary, Indoor, Outdoor Technology: UV Photometry, Electrochemical, Electrochemical Sensor, Gas Chromatography End User: Environmental Monitoring, Industrial, Research Laboratories, Automotive Application: Air Quality Assessment, Process Monitoring, Emission Testing, Water Treatment |
| Companies Covered | Teledyne API, Thermo Fisher Scientific, ECOTECH, Eco Sensors, 2B Technologies, Aeroqual, HORIBA, BMT MESSTECHNIK, DKK-TOA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ozone Analyzer Market Evolving Landscape
Analyzer architectures are pivoting toward modular optical benches with field-swappable components, reducing downtime costs while complicating supplier strategies around captive versus outsourced component sourcing.
Mercury-free UV lamp technology is supplanting traditional mercury vapor excitation sources in regulatory-grade instruments. Semiconductor process control buyers in Taiwan and South Korea now specify mercury-free designs for new fab installations. This transition is compressing the installed base refresh cycle and elevating qualification barriers for suppliers lacking in-house lamp production capability.
The EU Ambient Air Quality Directive's 2025 recalibration mandate tightens uncertainty budgets for ozone reference measurements. National metrology institutes in Germany, France, and Italy are expanding primary standard capacity. Stationary network operators face accelerated replacement schedules for pre-2020 analyzers that cannot meet tightened performance specifications.
Service unbundling is fragmenting traditional capital-plus-maintenance contracting. German municipal utilities now separately procure analyzer hardware, calibration gas, and field service through distinct tender processes. This disintermediation pressures integrated suppliers to defend position through software differentiation rather than bundled service lock-in.
Ozone Analyzer Market Segmentation
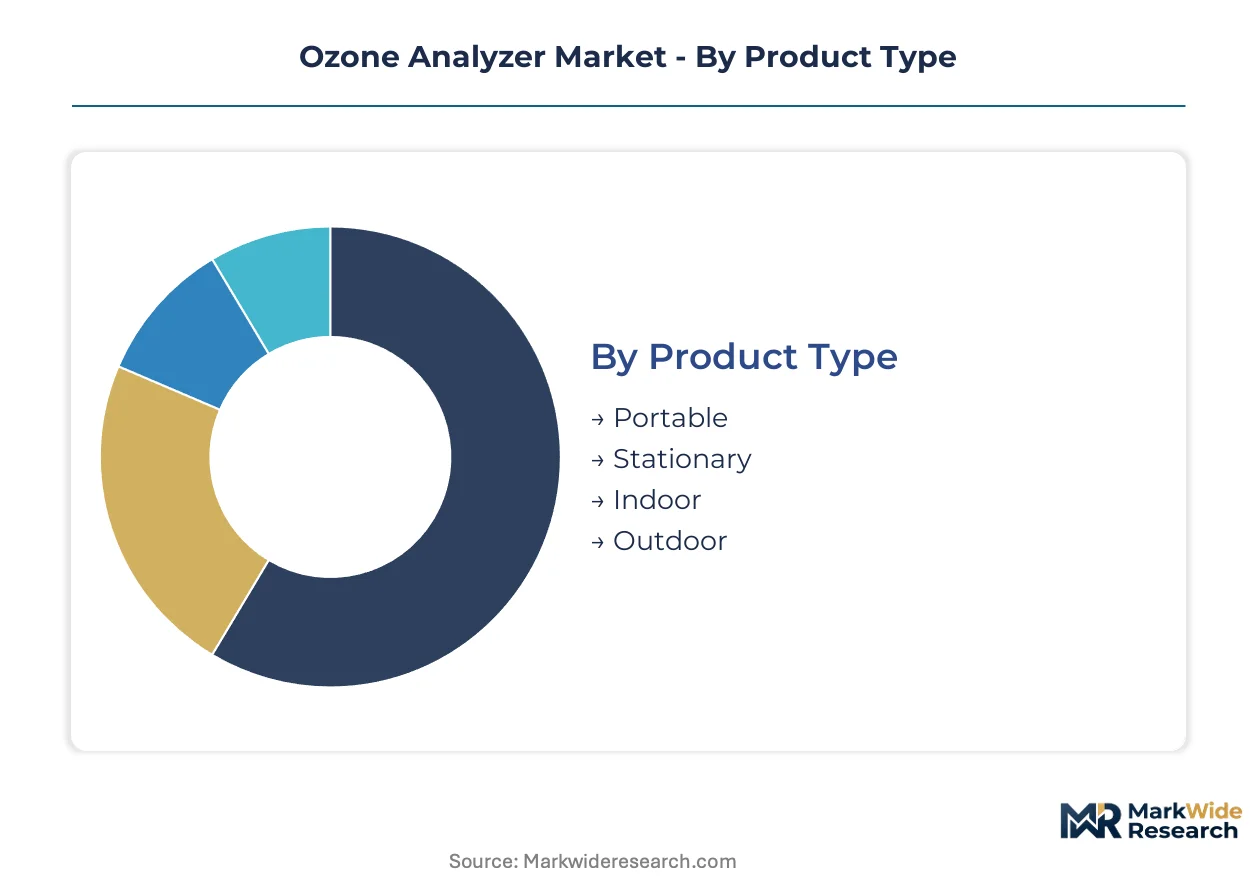
Segmentation in the ozone analyzer market reflects divergent certification requirements across jurisdictions. Buyers must match instrument specifications to precise regulatory mandates rather than selecting on generic performance metrics.
Product Type:
Regulatory frameworks differentiate compliance obligations between fixed installations and mobile deployments, creating distinct procurement channels.
- Stationary:UV photometry systems dominate continuous ambient monitoring networks with EN 14625 and EPA Method 205 certification. German municipal utilities and US state environmental agencies anchor demand through network expansion and analyzer refresh cycles.
- Portable:Battery-powered units serve emergency response and stack testing applications where site access is intermittent. Mobile deployment for MEE audit response in the Upper Rhine corridor accelerates replacement demand against fixed-installation dominance.
- Indoor:Compact electrochemical designs address workplace safety and cleanroom process control. Semiconductor fabs in Taiwan and South Korea specify mercury-free configurations for advanced node manufacturing environments.
- Outdoor:Weather-hardened enclosures protect optical benches in unattended monitoring stations. Deployment concentrates along industrial corridors subject to intensified emissions audits.
Established volume favors Stationary; emerging adoption favors Portable.
Technology:
Detection principle selection hinges on precision requirements and total cost of ownership trade-offs across end-use contexts.
- UV Photometry:Absorption measurement at 254 nm delivers parts-per-billion detection limits with certified traceability chains. Tightening EPA and EU drinking water directives compress tolerance bands and force utilities toward higher-grade instrumentation.
- Electrochemical:Redox reaction-based sensors offer lower capital outlay for cost-sensitive indoor air quality installations. Baseline degradation in humid environments limits deployment confidence for continuous compliance monitoring.
- Electrochemical Sensor:Miniaturized cell designs extend into distributed monitoring nodes. Drift tolerance trades against capital outlay in applications where recalibration frequency can be managed.
- Gas Chromatography:Separation with electron capture detection addresses complex matrix interference in research and forensic applications. Method complexity restricts deployment to laboratory settings with trained operator support.
UV Photometry commands the compliance premium tier; Electrochemical captures volume in cost-constrained segments.
End User:
Procurement sophistication varies sharply across buyer categories, from standardized network tenders to customized research specifications.
- Environmental Monitoring:Government-operated networks drive standardization through Federally Equivalent Methods and EN-standardized performance specifications. National metrology institutes in Germany, France, and Italy expand primary standard capacity to meet recalibration mandates.
- Industrial:Chemical manufacturers and semiconductor fabs demand sub-ppb detection systems with process integration capabilities. Process gas purity mandates in advanced node manufacturing elevate qualification barriers.
- Research Laboratories:Academic and government research facilities prioritize method flexibility over regulatory certification breadth. Custom calibration protocols and data export compatibility dominate selection criteria.
- Automotive:Emissions testing laboratories and vehicle certification centers require portable stack testing capabilities. Mobile units for regulatory audit response represent underpenetrated replacement opportunities.
Environmental Monitoring anchors standardization; Industrial buyers drive specification escalation.
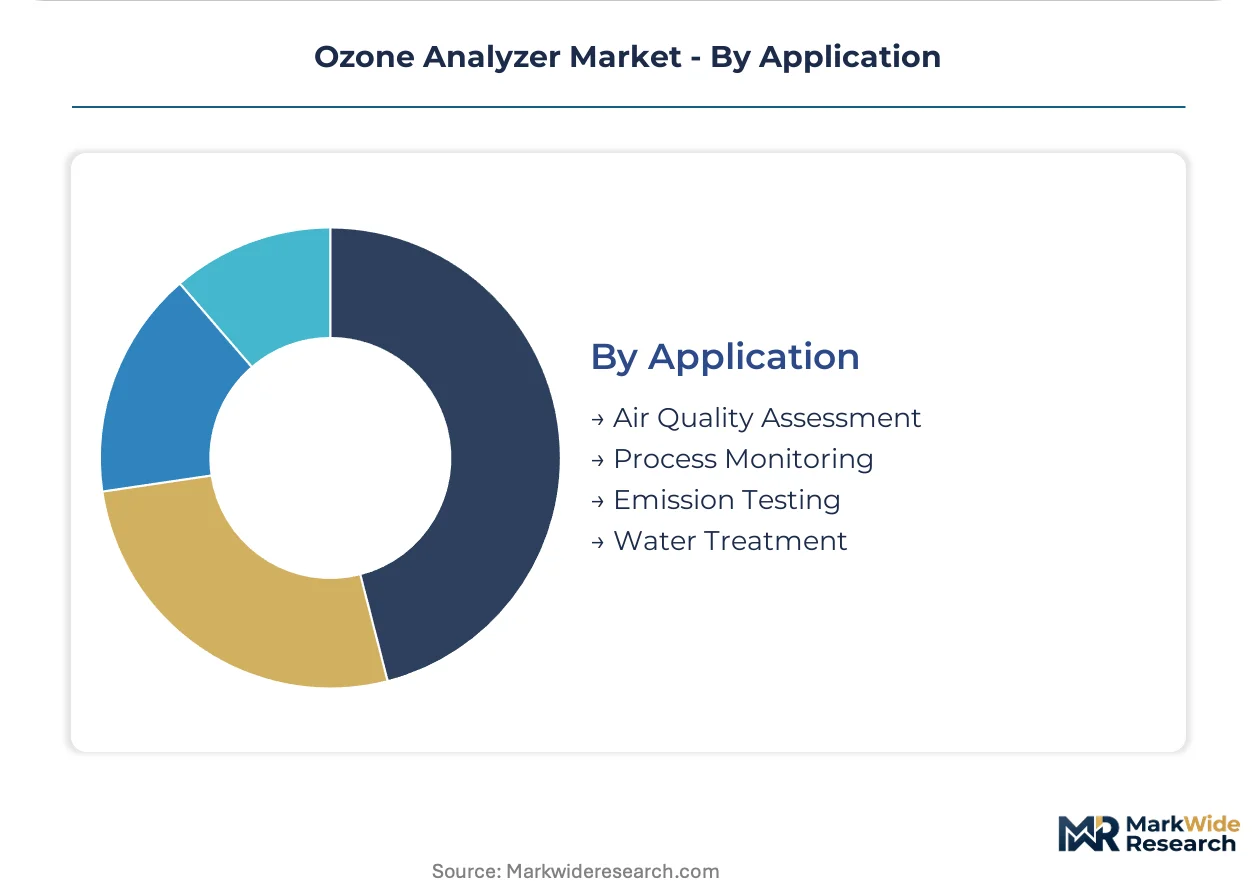
Application:
Use case specificity determines instrument configuration, from unattended network operation to point-source emission verification.
- Water Treatment:Residual ozone monitoring in municipal and industrial facilities demands certified traceability for regulatory reporting. EPA and EU drinking water directives tighten residual limits and push utilities toward higher-precision UV photometry.
- Air Quality Assessment:Continuous ambient monitoring networks specify analyzer performance through Federally Equivalent Methods. Cloud-connected predictive maintenance converges with hardware to unbundle traditional service contracts.
- Process Monitoring:Semiconductor and pharmaceutical manufacturing require real-time purity verification with minimal maintenance interruption. Modular optical benches with field-swappable components reduce downtime costs in cleanroom environments.
- Emission Testing:Stack testing and fence-line monitoring combine fixed reference stations with portable verification units. MEE emissions audits in industrial corridors accelerate sensor replacement cycles.
Water Treatment concentrates regulatory-grade procurement; Process Monitoring climbs fastest on semiconductor fab expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Method 205 and EN 14625 certification cycles are reorganizing procurement patterns across national monitoring networks. Utilities and industrial operators in Germany, the United States, China, Japan, and India face diverging compliance timelines and calibration infrastructure availability.
United States
State environmental agencies anchor demand through ambient monitoring network expansion and analyzer refresh cycles. EPA enforces Clean Air Act NAAQS compliance through Federally Equivalent Methods that specify analyzer performance. Municipal water treatment facilities in the Upper Midwest are expanding ozone dissolution monitoring programs under tightening residual limits.
Germany
Chemical manufacturers in the Upper Rhine industrial corridor face intensified emissions audits, accelerating sensor replacement demand. EU Ambient Air Quality Directive mandates EN-standardized ozone measurement across member state reporting stations. National metrology institutes in Berlin and Braunschweig are expanding primary standard capacity to meet 2025 recalibration mandates.
China
Semiconductor fabs in Taiwan and South Korea now specify mercury-free designs for new installations, compressing refresh cycles for Chinese component suppliers. MEE implements GB 3095-2012 ambient ozone limits with increasing calibration audit frequency. Yangtze River Delta industrial clusters drive process monitoring demand for sub-ppb detection systems.
Japan
Industrial procurement standards favor JIS-compliant calibration protocols in environmental monitoring tenders. METI oversees technology roadmaps that influence cleanroom instrumentation specifications. Nagoya-area automotive emissions testing laboratories require portable stack testing capabilities for regulatory audit response.
India
BIS drinking water standards adoption lags behind EU equivalents, creating positioning opportunities as municipal treatment capacity expands. Central Pollution Control Board guidelines are tightening stack emission monitoring requirements for thermal power and cement sectors. Maharashtra and Gujarat industrial corridors represent concentrated demand for MEE audit-responsive instrumentation.
Ozone Analyzer Market Competitive Landscape
Listed leaders compete with private specialists across certification breadth and captive component sourcing. The vendor base organizes into three tiers: integrated multinationals with in-house optical production, mid-tier assemblers dependent on outsourced UV lamps, and regional specialists serving single-jurisdiction compliance markets. Two strategic archetypes dominate: mercury-free lamp producers capturing semiconductor fab specifications, and calibration service bundlers defending position through unbundling-resistant contracts. Competitive moves concentrate on backward integration into specialized lamp production and cloud-connected predictive maintenance offerings.
Within the integrated multinational tier, Teledyne API and Thermo Fisher Scientific exemplify divergent sourcing strategies. Teledyne API occupies a position tied to TUV-approved reference designs across North American networks. Thermo Fisher Scientific anchors the premium tier through captive optical component sourcing and in-house mercury-free UV lamp production. HORIBA sits within the standards-specialist archetype, with JIS-compliant calibration protocols satisfying Japanese industrial procurement requirements.
| Leading Market Players |
|---|
| Teledyne API |
| Thermo Fisher Scientific |
| ECOTECH |
| Eco Sensors |
| 2B Technologies |
| Aeroqual |
| HORIBA |
| BMT MESSTECHNIK |
| DKK-TOA |
| Others |
Value Network & Pricing Analysis
Captive mercury-free UV lamp production at Thermo Fisher Scientific and concentrated optical bench assembly in German and Japanese manufacturing clusters create asymmetric scale economies that elevate price floors for mid-tier competitors while compressing margins for non-integrated assemblers.
Pricing Analysis
Certification level (EPA Method 205, EN 14625, JIS-compliant) creates the primary spread between premium UV photometry systems and economy electrochemical alternatives. Three-tier pricing structure across regulatory-grade, industrial-process, and indoor-air-quality levels segments buyer willingness-to-pay, with German municipal utilities and semiconductor fabs absorbing premium tiers while cost-constrained Indian water utilities cluster at standard levels. Cost compression in electrochemical sensors is intensifying because Chinese component suppliers are expanding mercury-free lamp foundry capacity. Environmental monitoring agencies exhibit lowest price sensitivity due to mandated compliance budgets, whereas commercial indoor air quality installers face acute capital-outlay constraints.
Supply Chain Analysis
Extended lead times for TUV-approved reference designs and JIS-certified optical benches stretch procurement cycles to 16-24 weeks for specialized UV photometry systems. Manufacturing concentrates in Germany, Japan, and the United States, with final assembly tethered to cleanroom technician labor pools in Stuttgart and Nagoya industrial corridors. Critical inputs include mercury-free UV lamps, precision optical mirrors, and certified calibration gases. Single-source vulnerability in specialized lamp production constrains mid-tier analyzer manufacturers. Distribution runs through direct OEM channels for regulatory-grade instrumentation and regional distributors for portable and indoor segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German municipal utilities and Upper Rhine chemical manufacturers are consolidating procurement through separate tender processes for hardware, calibration gas, and field service, shifting bargaining power toward buyers and fragmenting traditional bundled-service lock-in.
For Market Incumbents: Consolidate backward integration into mercury-free UV lamp production to defend against supply bottlenecks that threaten mid-tier competitors. Lock in calibration service contracts with national metrology institutes in Germany, France, and Italy before 2025 recalibration mandates accelerate. The priority lever rests on cloud-connected predictive maintenance software that resists unbundling pressures from disaggregating municipal procurement. For New Entrants and Emerging Players: Cloud-based calibration drift alerting and remote diagnostic services represent under-served layers where integrated incumbents retain legacy field-service infrastructure. Target portable stack testing units for MEE audit response in India's Maharashtra and Gujarat industrial corridors, where regulatory enforcement is tightening but certified UV photometry penetration remains shallow. Lead with mercury-free specifications to capture semiconductor fab procurement in Taiwan and South Korea. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors suppliers with in-house optical component sourcing and captive lamp production as mercury-free transitions compress refresh cycles. Long-term viability hinges on software differentiation recurring revenue streams rather than hardware replacement cycles. Watch for EN 14625 calibration infrastructure expansion in Eastern Europe as an inflection signal for market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lamp Production | Captive mercury-free UV supply secures semiconductor fab qualification and defends against input bottlenecks. |
| Cloud-Connected Predictive Maintenance | Remote drift alerting unbundles traditional service contracts and captures recurring software revenue from German utilities. |
| Multi-Jurisdiction Certification Stacking | Simultaneous EPA, EN, and JIS compliance opens procurement channels across North American, European, and Japanese networks. |
| Portable Stack Testing Expansion | Mobile MEE audit-responsive units penetrate under-served replacement cycles against fixed-installation dominance. |
| Calibration Infrastructure Partnerships | Accredited laboratory alliances in Eastern Europe and India reduce certification timelines and total cost of ownership. |
Research Methodology
Cross-validation between primary interviews with environmental monitoring network operators, semiconductor fab process engineers, and municipal water utility procurement managers anchors the qualitative findings, while secondary validation draws from EPA Method 205 certification records, EN 14625 laboratory accreditation databases, and MEE emissions audit disclosures. Bottom-up triangulation across instrument shipment data and top-down reconciliation against national ambient monitoring network expansion budgets ensures dimensional consistency.
Sensitivity analysis around regulatory enforcement intensity and mercury-free lamp supply elasticity tests forecast robustness across the projection horizon. Segmentation dimensions modeled include product type (stationary, portable, indoor, outdoor), detection technology (UV photometry, electrochemical, gas chromatography), end-user category (environmental monitoring, industrial, research laboratories, automotive), and application context (water treatment, air quality assessment, process monitoring, emission testing). CAGRs derive from polynomial trend fitting against historical certification cycle data and semiconductor fab capital expenditure patterns.
Underlying assumptions cover sustained EPA and EU drinking water directive enforcement, stable mercury-free lamp technology transition timelines, and continued MEE emissions audit intensification in Chinese and Indian industrial corridors, with deviation risk concentrated in regulatory harmonization delays and optical component cleanroom labor availability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Quality Control Systems
Middle-East and Africa Industrial Air Quality Control Systems Market
Air Quality Control Systems
Nitrogen Oxide Control Systems Market
Air Quality Control Systems
Oxygen Filters Market
Air Quality Control Systems
Desiccant Air Breather Market
Air Quality Control Systems
Europe Industrial Air Quality Control Systems Market
Air Quality Control Systems
Asia Pacific Air Filtration Market
Air Quality Control Systems
Air Pollution Control Equipment Market
Air Quality Control Systems
Asia-Pacific Indoor Air Purification Market
Air Quality Control Systems
US Air Quality Analyzers Market
Air Quality Control Systems
Air Scrubber Market
Air Quality Control Systems
Green Emissions Analyzers Market
Air Quality Control Systems
Singapore Air Purifier Market
Air Quality Control Systems
Anti-Pollution Toner Market
Air Quality Control Systems
Industrial Air Quality Control Systems Market
Air Quality Control Systems
Asia-Pacific Air Quality Control System Market
Air Quality Control Systems
Southeast Asia Air Purifier Market