
 ISO Certification Market | 2026-2036
ISO Certification Market Size, Share, and Industry Trends Forecast 2026-2036
ISO Certification Market Outlook
Mid-market manufacturers are reorganizing their procurement priorities around third-party certification as enterprise buyers harden supplier qualification requirements. SGS leverages its multi-standard portfolio to serve cross-border supply chains, while Bureau Veritas anchors its position through deep sector specialization in energy and infrastructure audits. DNV differentiates by concentrating on maritime and renewable energy certification niches where technical depth commands premium positioning.
ISO certification constitutes a formal conformity assessment process in which accredited bodies evaluate whether an organization's management systems, processes, or products meet specific International Organization for Standardization criteria; audits examine documented procedures, implementation evidence, and measurable outcomes against standards such as ISO 9001 for quality management or ISO 27001 for information security. The primary purpose is to reduce transactional risk between buyers and suppliers by providing independently verified assurance of operational consistency. ISO 9001 quality management certification represents the most mature segment with the largest installed base of certified organizations, while ISO 27001 information security is expanding fastest as ransomware exposure and data breach liability reshape enterprise risk priorities. Remote audit delivery modes are gaining structural share from on-site audits as digital documentation platforms and video inspection tools reduce travel-dependent cost structures.
The International Organization for Standardization itself coordinates standard development, while national accreditation bodies such as the UK's United Kingdom Accreditation Service and Germany's Deutsche Akkreditierungsstelle govern certifier competence and impartiality. Regulatory frameworks including the EU's CSRD and GDPR indirectly amplify certification demand by embedding management system requirements into corporate accountability and data governance obligations. Stakeholders must monitor whether accreditation mutual recognition agreements expand or fragment, as this determines the portability of certification investments across jurisdictions and supply chain tiers.
Market Dynamics
Enterprise procurement departments now mandate ISO credentials as a non-negotiable gate for supplier onboarding, converting certification from voluntary quality signal into contractual prerequisite across automotive, pharmaceutical, and food supply chains.
Growth Catalysts
- EU AI Act compliance mandates:European enterprises deploying high-risk AI systems must demonstrate conformity through auditable management systems, directly expanding ISO 27001 and ISO 42001 certification pipelines.
- Healthcare patient safety frameworks:Joint Commission accreditation and FDA quality system regulations in the US require ISO 13485 for medical device manufacturers, embedding certification into regulatory compliance pathways.
- German industrial corridor concentration:Manufacturing exporters in Baden-Württemberg and Bavaria require dual ISO 9001 and ISO 14001 credentials to maintain Tier-1 supplier status with automotive OEMs.
Market Restraints
- Accreditation body concentration:National accreditation services in France, Germany, and the UK control certifier authorization, creating jurisdictional bottlenecks that limit new market entry.
- Remote audit technical limitations:Physical asset verification and operational observation requirements in ISO 45001 and ISO 22000 constrain full digital migration of audit delivery.
- Third-party audit cost inflation:Travel-intensive on-site assessment models face persistent aviation and accommodation cost pressure, squeezing margins for fixed-fee certification contracts.
Strategic Opportunities
- India manufacturing compliance wave:Bureau of Indian Standards alignment with ISO frameworks and PLI scheme export requirements position the subcontinent for certification volume expansion.
- Blockchain-anchored audit trails:Immutable documentation verification converges with ISO management system records, enabling automated compliance monitoring and continuous certification models.
- Scope 3 emissions verification:CSRD supply chain disclosure requirements create demand for ISO 14064 certification services that validate upstream and downstream carbon accounting.
Industry Challenges
- Auditor talent scarcity:Technical specialists capable of assessing integrated management systems across quality, environmental, and information security domains command premium compensation that strains certifier economics.
- Multi-standard integration complexity:Organizations pursuing simultaneous ISO 9001, ISO 14001, and ISO 45001 certification face documentation harmonization challenges that extend implementation timelines and consulting costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ISO Certification Market |
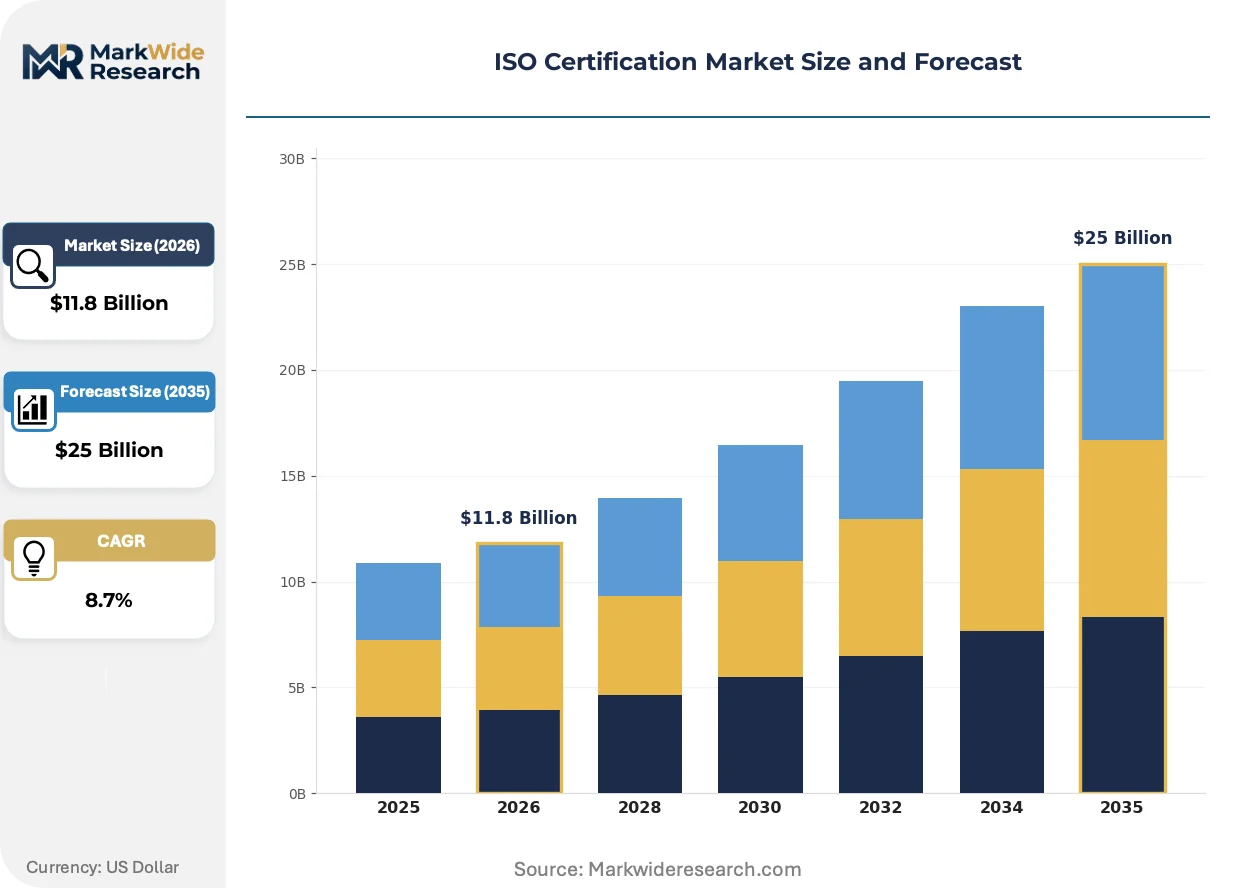
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $25 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Certification Type: ISO 9001, ISO 14001, ISO 45001, ISO 27001 Industry Vertical: Manufacturing, Healthcare, IT Services, Construction Application: Quality Management, Environmental Management, Occupational Health, Information Security Delivery Mode: On-site Audit, Remote Audit, Continuous Surveillance, Documentation Review |
| Companies Covered | Lloyd's Register, The British Standards Institution, SGS, UL, TUV, Bureau Veritas, Intertek, Dcycle, DNV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ISO Certification Market Strategic Shifts
Digital audit infrastructure is compressing assessment timelines while regulatory fragmentation across jurisdictions is forcing certifiers to build modular compliance architectures. These shifts are reconfiguring how assurance services are produced, delivered, and consumed.
Artificial intelligence-powered document analysis tools are miniaturizing pre-audit preparation phases. Mid-market manufacturers in the US Midwest and Central Europe deploy these platforms to auto-classify quality records and environmental monitoring data before assessor arrival. The technology is compressing certification cycle times from twelve weeks to four weeks for repeat audits.
REACH substance restriction updates and the EU F-Gas Regulation phase-down are mandating supply chain chemical inventory audits that extend beyond traditional ISO 14001 scope. Industrial chemical distributors and refrigeration equipment manufacturers must now document fluorinated gas containment and SVHC substitution through supplementary certification modules. German automotive suppliers are responding by integrating ECHA compliance verification into their existing ISO management system audits.
Certification-driven supplier qualification is consolidating procurement decision-making authority within enterprise sustainability and risk functions. Food retailers in France and pharmaceutical distributors in Switzerland now bypass traditional quality departments to engage certifiers directly for supplier verification. This channel shift concentrates contract value with accreditation bodies capable of delivering multi-jurisdiction credential portability.
ISO Certification Market Segmentation
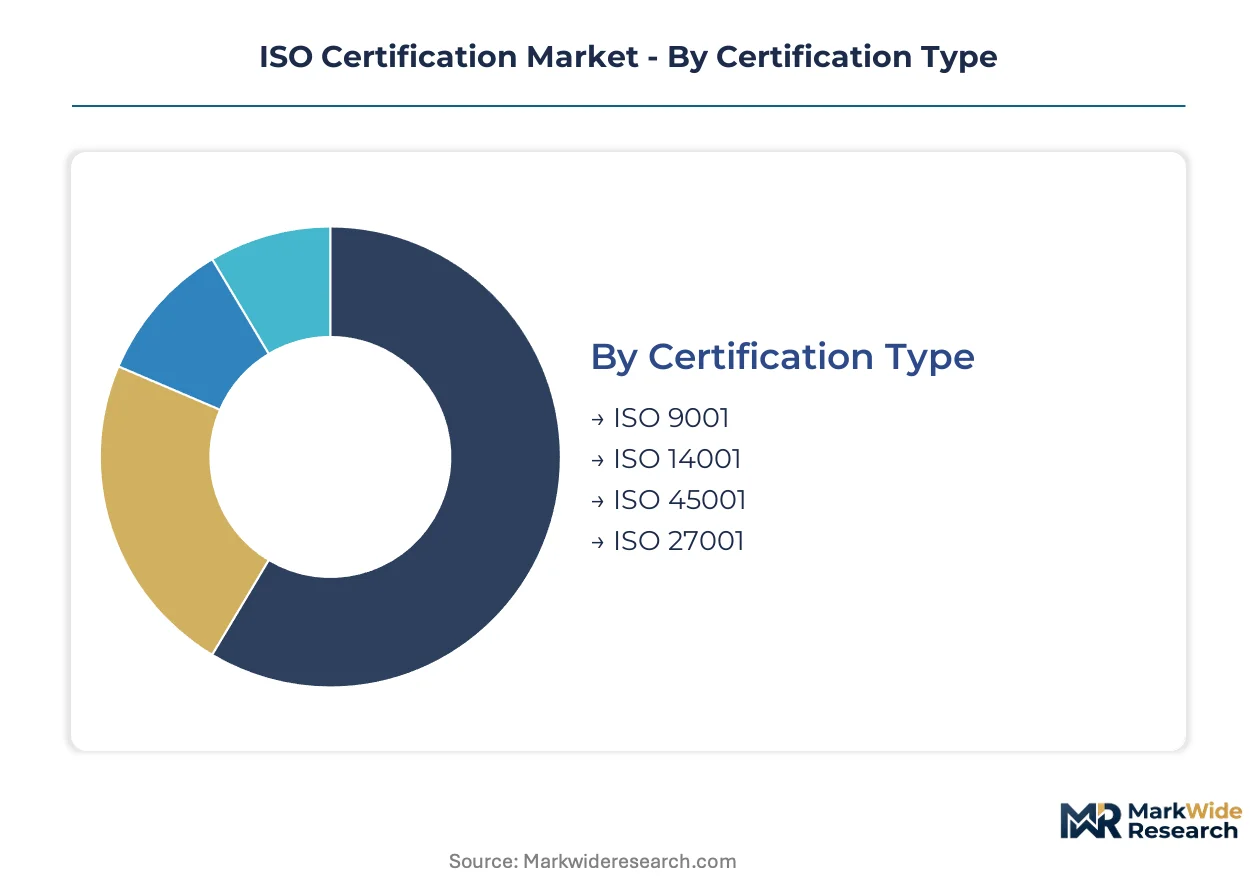
ISO certification segmentation reveals how demand patterns split between domestic compliance requirements and export-driven credentialing. Certification type and delivery mode choices diverge sharply based on whether organizations seek market access or regulatory defense.
Certification Type:
German automotive exporters drive disproportionate volume for quality and environmental standards, while healthcare and technology firms anchor information security growth.
- ISO 9001:Quality management systems certification evaluates documented procedures for consistent product and service delivery. Manufacturing exporters in Baden-Württemberg and Bavaria require this credential to maintain Tier-1 supplier status with automotive OEMs like BMW and Volkswagen.
- ISO 14001:Environmental management systems certification assesses organizational controls for environmental impact reduction. German industrial clusters pursue dual ISO 9001 and ISO 14001 credentials to satisfy supply chain sustainability mandates from export buyers.
- ISO 45001:Occupational health and safety management certification addresses workplace hazard controls and worker protection frameworks.
- ISO 27001:Information security management certification evaluates data protection controls and cyber risk governance; ransomware exposure and breach liability reshape enterprise priorities fastest here.
ISO 9001 holds the largest share; momentum sits with ISO 27001.
Industry Vertical:
Cost tier stratification separates capital-intensive manufacturers seeking multi-standard bundles from service sectors purchasing single-standard compliance.
- Manufacturing:Industrial producers across automotive, machinery, and electronics subsectors require integrated ISO 9001, ISO 14001, and ISO 45001 certification to qualify for supplier networks. German Mittelstand firms in the industrial corridor represent concentrated demand for bundled audit services.
- Healthcare:Medical device manufacturers and hospital systems pursue ISO 13485 and ISO 27001 credentials to satisfy FDA quality system regulations and patient data protection requirements.
- IT Services:Cloud providers and software vendors seek ISO 27001 and ISO 42001 certification to demonstrate AI system conformity under the EU AI Act.
- Construction:Infrastructure contractors and building material suppliers require ISO 45001 and ISO 14001 credentials for public procurement qualification and environmental permit maintenance.
Manufacturing commands premium pricing for integrated audits; IT Services climbs fastest on regulatory tailwinds.
Application:
Maturity gradients separate decades-established quality management from rapidly evolving security and AI governance domains.
- Quality Management:The most mature certification application with standardized audit protocols and highest certifier capacity. Automotive supply chains in Germany and aerospace contractors in France anchor stable demand.
- Environmental Management:CSRD disclosure requirements and Scope 3 emissions verification are extending ISO 14001 scope into supply chain carbon accounting services.
- Occupational Health:Construction and heavy manufacturing sectors in France and Germany drive steady demand for workplace safety certification.
- Information Security:The steepest expansion trajectory as ransomware exposure, GDPR enforcement, and EU AI Act compliance reshape enterprise risk priorities.
Quality Management retains the deepest installed base; Information Security gains share fastest on regulatory amplification.
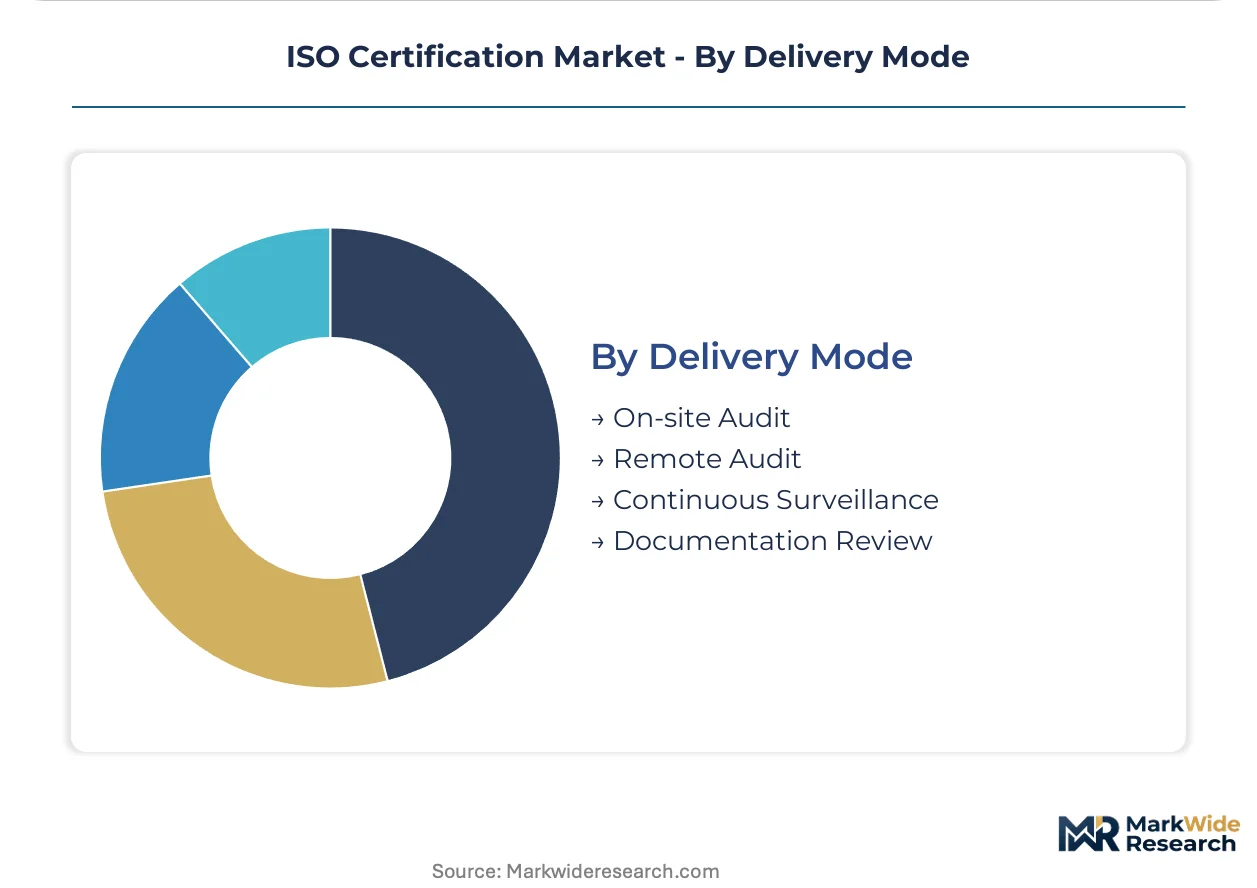
Delivery Mode:
Customer type splits between large enterprises accepting remote audit cost savings and small manufacturers requiring physical verification for asset-intensive standards.
- On-site Audit:Traditional assessment mode requiring physical facility access for operational observation and asset verification. ISO 45001 and ISO 22000 retain mandatory on-site components due to workplace safety and food handling observation requirements.
- Remote Audit:Video inspection tools and digital documentation platforms enable cost reduction for repeat ISO 9001 and ISO 14001 surveillance audits. Mid-market manufacturers in Central Europe deploy pre-audit AI document analysis to compress cycle times from twelve weeks to four weeks.
- Continuous Surveillance:Blockchain-anchored audit trails and automated compliance monitoring enable subscription-based certification models with real-time verification.
- Documentation Review:Desk-based assessment of policies, procedures, and records without operational observation; suitable for low-risk certification extensions and scope expansions.
On-site Audit still dominates initial certification; Remote Audit captures the fastest growth in repeat surveillance cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput underwrites Europe's certification verification hub, while Germany's Rhine-Ruhr rail corridor moves audit personnel between industrial clusters. These infrastructure assets anchor regional compliance service distribution.
Germany
Automotive OEM procurement mandates drive dual ISO 9001 and ISO 14001 adoption among Mittelstand suppliers. The KBA enforces component traceability standards that require third-party management system verification. Manufacturing exporters in Baden-Württemberg and Bavaria maintain Tier-1 supplier credentials through bundled audit services.
United States
FDA quality system regulations embed ISO 13485 into medical device commercialization pathways. Healthcare systems in the Boston-Cambridge corridor and Minneapolis-St. Paul metro pursue Joint Commission alignment through certification. Midwest manufacturers reorganize procurement around third-party verification as enterprise buyers harden supplier gates.
India
PLI scheme export requirements and BIS alignment with ISO frameworks position the subcontinent for certification volume expansion. Pharmaceutical manufacturers in Maharashtra and Gujarat pursue FDA and EMA parallel compliance through integrated management systems. Bangalore's IT services cluster drives ISO 27001 adoption for data protection governance.
United Kingdom
UKAS accreditation governance maintains certifier competence standards post-Brexit. London's financial services sector anchors ISO 27001 demand for cyber risk management. Midlands manufacturing and Scottish energy infrastructure projects require ISO 45001 and ISO 14001 credentials for public procurement qualification.
France
ANSM medical device regulations and CNIL data protection enforcement amplify certification demand. REACH substance restriction updates mandate supply chain chemical inventory audits beyond traditional ISO 14001 scope. Lyon and Grenoble industrial clusters integrate ECHA compliance verification into existing management system audits.
ISO Certification Market Competitive Environment
Concentration sits with diversified assurance conglomerates that leverage multi-standard portfolios across borderless supply chains. The vendor base organizes around three strategic archetypes: diversified testing giants with cross-border accreditation networks, sector-specialized technical assessors with deep vertical expertise, and emerging digital-native platforms compressing audit delivery timelines. Competitive positioning hardens through accreditation body partnerships and technology-enabled service modularization.
Among diversified assurance providers, SGS, Bureau Veritas, and DNV exemplify distinct specialization vectors within the certification ecosystem. SGS occupies a position anchored in multi-standard portfolio breadth across industrial supply chains. Bureau Veritas represents deep sector concentration in energy and infrastructure verification services. DNV sits within maritime and renewable energy niches where technical depth commands premium positioning. These three entities collectively illustrate how geographic reach, sector focus, and technical specialization define competitive differentiation in third-party conformity assessment.
| Leading Market Players |
|---|
| Lloyd's Register |
| The British Standards Institution |
| SGS |
| UL |
| TUV |
| Bureau Veritas |
| Intertek |
| Dcycle |
| DNV |
| Others |
Value Chain & Pricing Dynamics
Fourteen-day audit scheduling windows in Germany's industrial corridor concentrate pricing power with accredited bodies holding multi-standard portfolios, while travel-intensive on-site requirements tether cost structures to aviation and accommodation inputs across European supply chains.
Pricing Analysis
Volume-discount tiering structures separate enterprise multi-site contracts from single-facility Mittelstand engagements, with pricing stratifying across integrated audit bundles, standalone certifications, and surveillance-only renewals. Cost differentiation hinges on auditor travel distance and standard complexity, with ISO 27001 commanding premiums over mature ISO 9001 offerings. Pricing pressure stems from remote audit adoption compressing billable hours for repeat surveillance cycles. Mid-market manufacturers in Central Europe exhibit highest price sensitivity, while automotive OEMs prioritize credential portability over rate negotiation.
Supply Chain Analysis
Just-in-time auditor deployment dominates initial certification, while strategic stockpiling of technical specialist capacity buffers peak demand periods in Germany, France, and the United Kingdom. Supply draws from accreditation body networks in Western Europe, auditor training pipelines in India, and digital documentation platforms hosted in Ireland and the Netherlands. Single-source vulnerability concentrates in maritime and renewable energy niches where DNV holds specialized assessor depth. Distribution runs through national accreditation services controlling certifier authorization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market as EU AI Act compliance mandates and CSRD disclosure requirements penetrate mid-market enterprises previously outside certification scope.
For Market Incumbents: Compound accreditation body partnerships across German, French, and UK jurisdictions to defend against emerging digital-native platforms automating document review. Deepen technical specialist pipelines in ISO 42001 and ISO 14064 to capture AI governance and carbon verification premiums. Vertical integration into pre-audit consulting extends client lock-in before surveillance cycles commoditize.
For New Entrants and Emerging Players: Anchor in India's pharmaceutical and IT services clusters where PLI scheme export requirements and FDA parallel compliance create certification volume expansion. Target ISO 27001 adoption among Bangalore cloud providers and Maharashtra medical device manufacturers as the most penetrable white-space. Deploy AI-powered document analysis as differentiated go-to-market positioning against incumbent travel-dependent models.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified testing conglomerates seeking to divest non-core certification units amid portfolio rationalization. Long-term viability rests on regulatory amplification embedding management system requirements into corporate accountability frameworks. Watch accreditation mutual recognition agreement fragmentation as the signal indicating certification investment portability erosion across supply chain tiers.
| Strategic Initiative | Industry Significance |
|---|---|
| Accreditation Network Expansion | Multi-jurisdiction credential portability captures automotive OEM procurement mandates across German Mittelstand suppliers. |
| Digital Audit Platform Deployment | AI document analysis compresses ISO 9001 surveillance cycles from twelve weeks to four for repeat audits. |
| Technical Specialist Acquisition | Integrated management system assessors command premium positioning in ISO 42001 and ISO 14064 niches. |
| Pre-Audit Consulting Integration | Documentation harmonization services address multi-standard complexity extending client retention before surveillance. |
| Blockchain-Anchored Verification | Immutable audit trails enable subscription-based continuous certification models displacing periodic assessment. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of accreditation body annual reports, national standards institute filings, and EU regulatory gazettes. Interviews with certification body executives, auditor training program directors, and enterprise procurement managers in automotive and pharmaceutical sectors inform demand-side validation. Secondary sources include Deutsche Akkreditierungsstelle competence records, UKAS authorization directories, and BIS alignment documentation. Bottom-up certification volume estimates triangulate against top-down market sizing from assurance conglomerate segment disclosures.
Segmentation dimensions modeled span certification type, industry vertical, application domain, and delivery mode across the projection horizon. Analytical framework derives CAGRs from accreditation body pipeline data, regulatory mandate implementation timelines, and supply chain qualification requirement diffusion curves. Forecast inputs incorporate EU AI Act compliance phase-in schedules and CSRD Scope 3 emissions verification adoption curves.
Material uncertainties — accreditation mutual recognition agreement fragmentation, remote audit technical limitation resolution, auditor talent scarcity escalation — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory enforcement consistency and enterprise procurement mandate hardening. Revision becomes warranted when jurisdictional certification portability erosion crosses thresholds affecting cross-border supply chain qualification.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environment & Sustainability
Climate Tech Market
Environment & Sustainability
Packaging Waste Recycling Market
Environment & Sustainability
Construction and Demolition Waste Management Market
Environment & Sustainability
North America Emission Monitoring System Market
Environment & Sustainability
Waste Management Market
Environment & Sustainability
Aeration Pads Market
Environment & Sustainability
Smart Waste Management Market
Environment & Sustainability
Continuous Emission Monitoring Systems (CEMS) Market
Environment & Sustainability
India Waste-To-Energy Market
Environment & Sustainability
Compostable and Biodegradable Refuse Bags Market
Environment & Sustainability
China Waste Management Market
Environment & Sustainability
Anti-Pollution Mask Market
Environment & Sustainability
Nitrogen Oxide Control Systems Market
Environment & Sustainability
Environmental Remediation Technologies Market
Environment & Sustainability
Home Water Softener System Market
Environment & Sustainability
Water Quality Monitoring Equipment Market