
 UV Air Purifiers Market | 2026-2036
UV Air Purifiers Market Size, Share, and Industry Trends Forecast 2026-2036
UV Air Purifiers Market Analysis
Modular add-on configurations that pair UV-C modules with existing HVAC infrastructure is rebalancing buyer choice away from standalone portable units. Daikin Industries leverages its captive HVAC installed base to bundle duct-mounted UV systems with new climate equipment. Honeywell International Inc. anchors its position through backward integration into UV-C LED semiconductor sourcing, controlling component cost and supply security. Coway Co., Ltd. specializes in compact wall-mounted designs for premium residential channels across East Asian markets.
UV air purifiers employ ultraviolet germicidal irradiation, typically in the 254 nanometer wavelength band, to inactivate airborne microorganisms by disrupting nucleic acid structures. These systems serve commercial and healthcare environments where ventilation rates and pathogen load demand continuous disinfection beyond mechanical filtration. Portable units and whole-house systems represent the dominant product configurations, with the former capturing margin pools in premium residential segments while the latter locks in recurring maintenance revenue through professional installation channels. UV-C LED technology is displacing traditional mercury lamp architectures, offering instant-on capability and eliminating hazardous material disposal liabilities that complicate regulatory compliance.
The U.S. EPA sets voluntary verification protocols for air cleaner efficacy, while the FDA regulates UV medical devices in clinical settings, creating dual compliance pathways that favor established manufacturers with dedicated regulatory affairs capacity. OSHA workplace air quality standards and ASHRAE ventilation guidelines increasingly reference ultraviolet air treatment as a supplemental engineering control, embedding UV purification into building code conversations. Stakeholders must monitor how photocatalytic oxidation and ionization technologies compete for the same capital expenditure budgets in commercial building upgrades.
Market Dynamics
The transition from mercury vapor lamps to UV-C LED architectures is compressing product lifecycles and forcing manufacturers to reconfigure supply chains around semiconductor sourcing rather than glass tube fabrication.
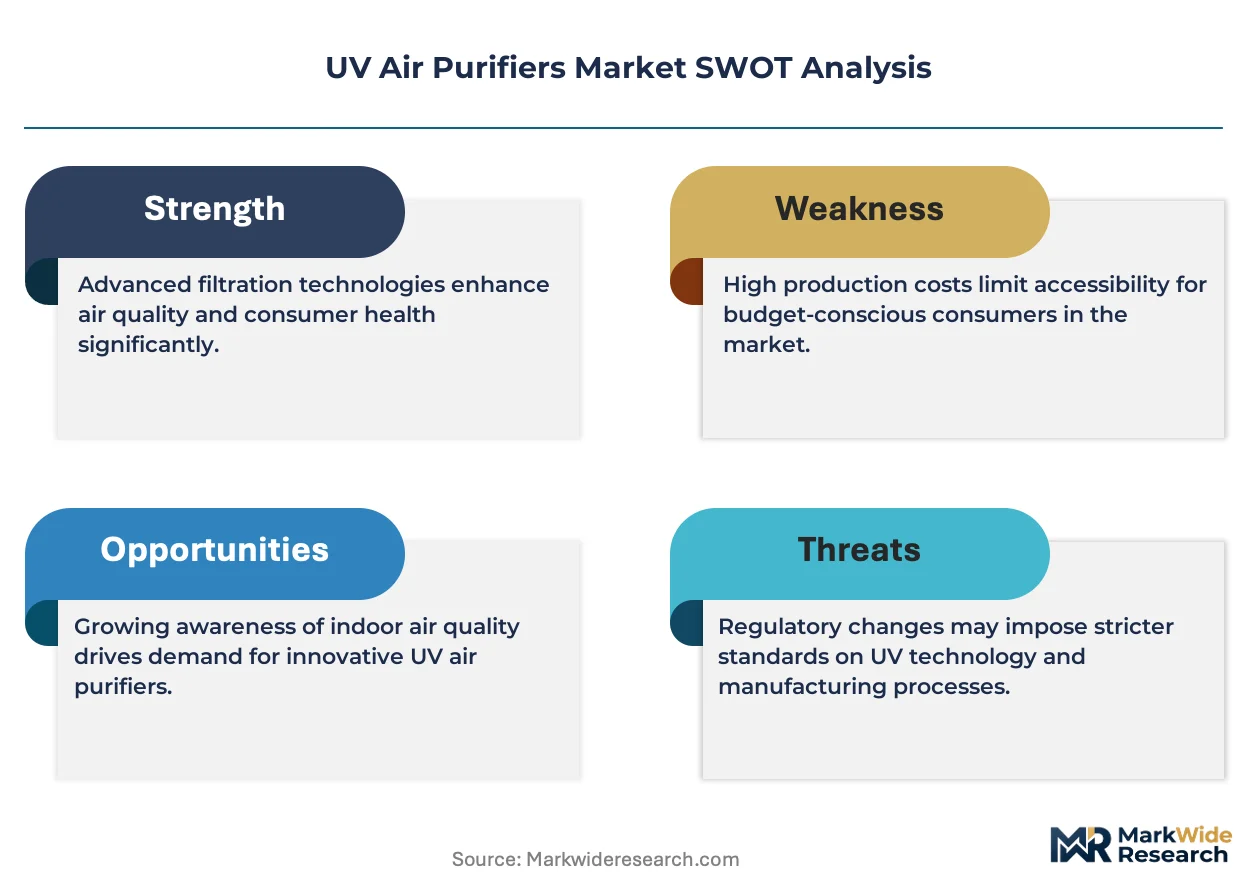
Growth Catalysts
- ASHRAE ventilation guideline updates:The 241 standard for airborne infection risk management now explicitly recommends UV-C as a supplemental engineering control, embedding air purification into commercial building mechanical specifications.
- Healthcare facility infrastructure:Hospital HVAC retrofit programs are specifying duct-mounted UV systems to reduce nosocomial pathogen transmission beyond what HEPA filtration achieves alone.
- UV-C LED instant-on capability:Solid-state emitters eliminate warm-up delays and mercury disposal liabilities, accelerating adoption in settings requiring intermittent operation.
Market Restraints
- Aluminum nitride substrate supply:UV-C LED fabrication depends on constrained high-purity wafer supply concentrated among Japanese and Korean semiconductor specialists.
- Mercury lamp residual installed base:Legacy systems in commercial buildings carry 10,000-hour rated lifespans, delaying replacement cycles despite LED efficiency advantages.
- FDA device classification friction:UV medical air purifiers face 510(k) pathway complexity that extends time-to-market for clinical-grade products versus general environmental units.
Strategic Opportunities
- Residential smart home integration:Voice-controlled UV air purifiers communicating with thermostat and humidity systems capture premium positioning in connected building ecosystems.
- India BIS certification pathway:Mandatory IS 16289 standards for room air purifiers create compliance-driven demand for certified UV-C systems in Delhi-NCR and Mumbai metropolitan markets.
- Photocatalytic oxidation convergence:TiO2-coated UV reactors addressing VOC loads alongside biological targets expand addressable market beyond pathogen-focused buyers.
Industry Challenges
- Optical engineering talent scarcity:UV-C LED system design requires rare expertise in radiometric modeling and reactor chamber fluid dynamics.
- Legacy BACnet integration complexity:Building automation protocols vary across commercial HVAC vintages, complicating unified control interface deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UV Air Purifiers Market |
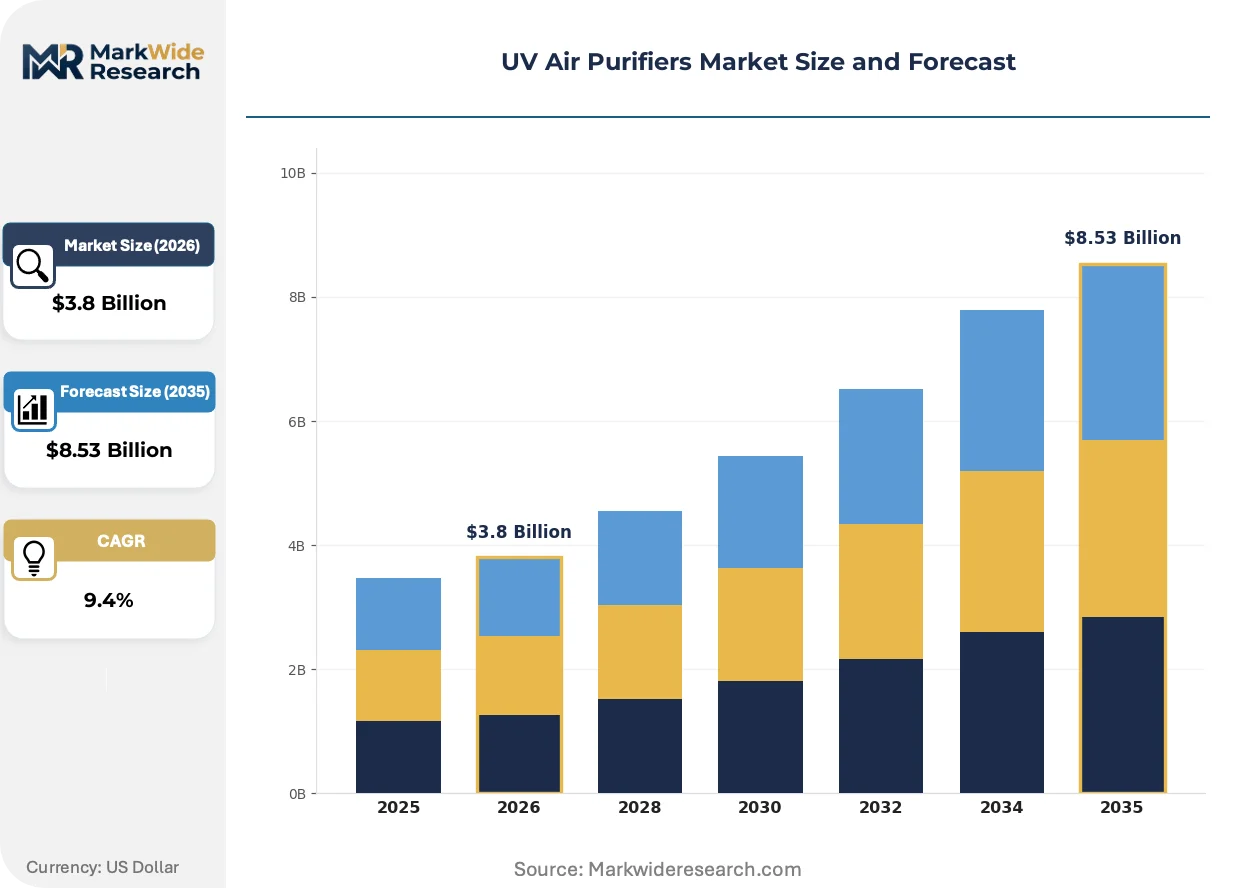
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Units, Wall-Mounted Units, Whole-House Systems, Duct-Mounted Devices Technology: UV-C, UV-C LED, Photocatalytic Oxidation, Ionization End User: Residential, Commercial, Industrial, Healthcare Installation: DIY, Professional Installation, Integrated Systems, Retrofitted Solutions |
| Companies Covered | Honeywell International Inc., Daikin Industries, Ltd., Resideo Technologies Inc., Air Oasis LLC, Guardian Technologies LLC, Koninklijke Philips N.V., Coway Co., Ltd., Eureka Forbes Limited, LG Electronics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UV Air Purifiers Market Emerging Trajectories
UV air purification is fragmenting into application-specific architectures rather than converging on universal platforms, with form factor and control intelligence now differentiating more than core germicidal efficacy.
UV-C LED emitter technology is modularizing around standardized 275 nanometer chip-on-board packages that slot into retrofit lamp sockets and custom reactor geometries alike. Hospital facilities are specifying these swappable modules to reduce maintenance downtime and eliminate mercury handling protocols. The technology is modularizing supply chains by decoupling semiconductor fabrication from final fixture assembly, enabling regional players to enter without vertical wafer production.
EPA verification protocols for air cleaner efficacy are tightening documentation requirements for ozone generation claims and microbial reduction percentages. Manufacturers must now submit standardized test reports under ANSI/AHAM AC-1 methodology to access federal procurement channels. Commercial building specifiers are responding by demanding third-party certification as a baseline qualification rather than premium differentiator.
Facility managers are unbundling equipment purchase from maintenance contracts, treating UV system lamp replacement and quartz sleeve cleaning as separately negotiated service lines. This disintermediation of the traditional single-source supplier model is compressing equipment margins while expanding recurring revenue pools for specialized service contractors. The pattern is most visible in United States healthcare and education verticals where capital and operating budgets sit under separate approval authorities.
UV Air Purifiers Market Segmentation
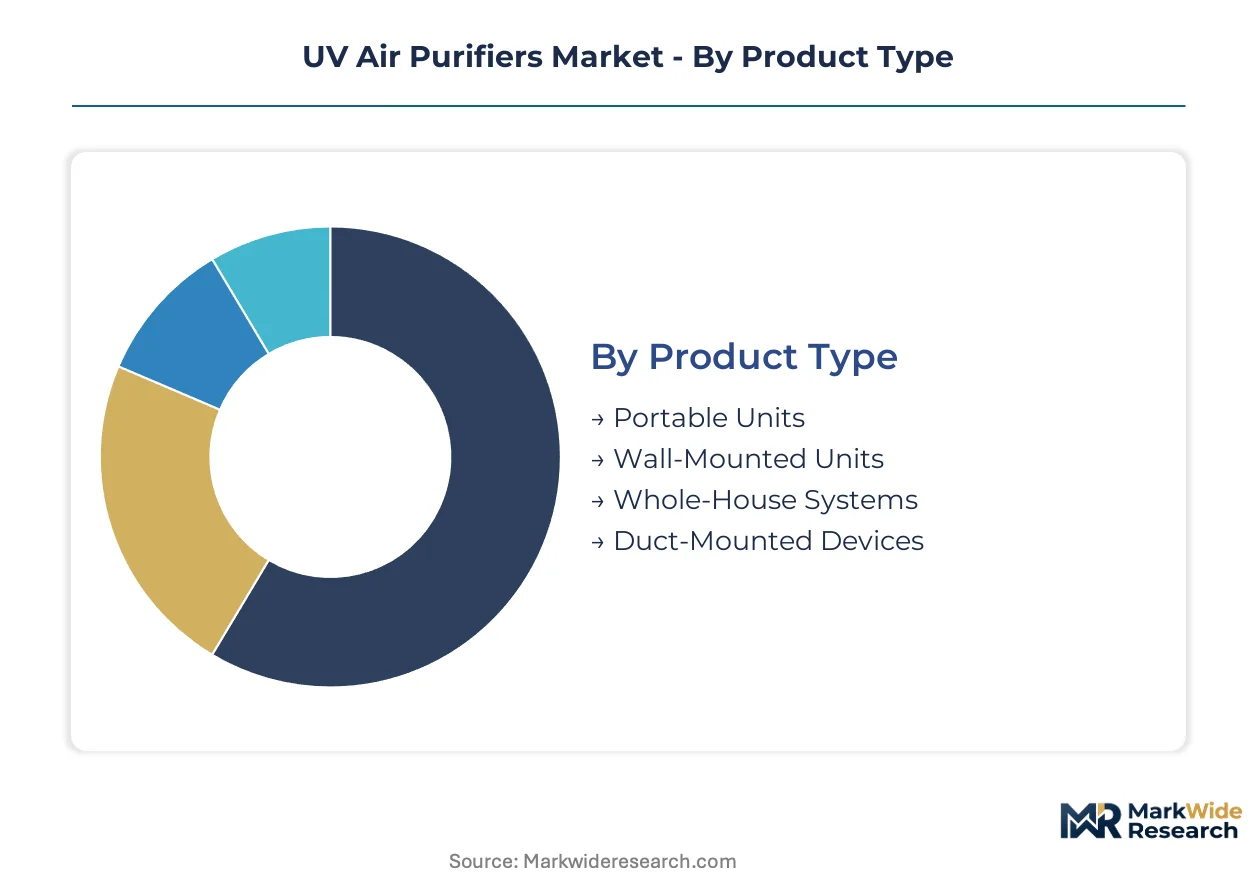
Segmentation in UV air purification reveals how technology maturity and buyer sophistication split the addressable market. Product architecture and installation complexity determine margin structure, while end-use requirements dictate regulatory exposure and replacement cycle timing.
Product Type:
Volume concentrates in portable formats, while premium positioning clusters around integrated whole-building systems.
- Portable Units:Self-contained 254nm mercury or UV-C LED emitters housed in floor-standing or desktop enclosures. Demand clusters in premium residential channels across the United States and East Asian metropolitan markets where consumers prioritize plug-and-play pathogen reduction.
- Whole-House Systems:Central air handlers with UV-C modules installed downstream of filtration media, requiring dedicated electrical and ductwork modification. Healthcare facilities in the United States specify these for continuous disinfection beyond what HEPA achieves alone.
- Wall-Mounted Units:Fixed-position emitters serving single rooms without floor footprint.
- Duct-Mounted Devices:In-line UV modules for commercial HVAC retrofit programs.
Mature deployment sits with Whole-House Systems. Newer deployment is concentrated in Duct-Mounted Devices.
Technology:
Mercury-based architectures dominate installed base, while semiconductor emitters capture replacement and new-build specification.
- UV-C LED:Solid-state 275nm emitters on aluminum nitride substrates delivering instant-on capability and eliminating hazardous material disposal liabilities. ASHRAE guideline updates explicitly recommend this architecture for intermittent operation in United States commercial buildings.
- UV-C:Traditional low-pressure mercury vapor lamps at 254nm wavelength with established efficacy documentation but warm-up delays and end-of-life handling complexity.
- Photocatalytic Oxidation:Titanium dioxide-coated UV reactors targeting VOC loads alongside biological inactivation.
- Ionization:Bipolar or needlepoint emitters producing reactive oxygen species, competing for the same capital expenditure budgets.
Established specification favors UV-C. Fastest technology transition is occurring in UV-C LED.
End User:
Healthcare and commercial verticals drive professional installation revenue, while residential channels favor retail procurement with minimal service attachment.
- Healthcare:Hospitals and outpatient clinics requiring FDA-regulated medical devices with 510(k) clearance for airborne infection control. United States hospital HVAC retrofit programs specify duct-mounted systems to reduce nosocomial transmission.
- Commercial:Office buildings, hospitality, and education facilities responding to OSHA workplace air quality standards and ASHRAE ventilation guidelines.
- Residential:Individual consumers purchasing through retail or e-commerce channels.
- Industrial:Manufacturing and warehousing environments with high particulate loads.
Regulatory complexity peaks in Healthcare. Volume expansion is strongest in Commercial.
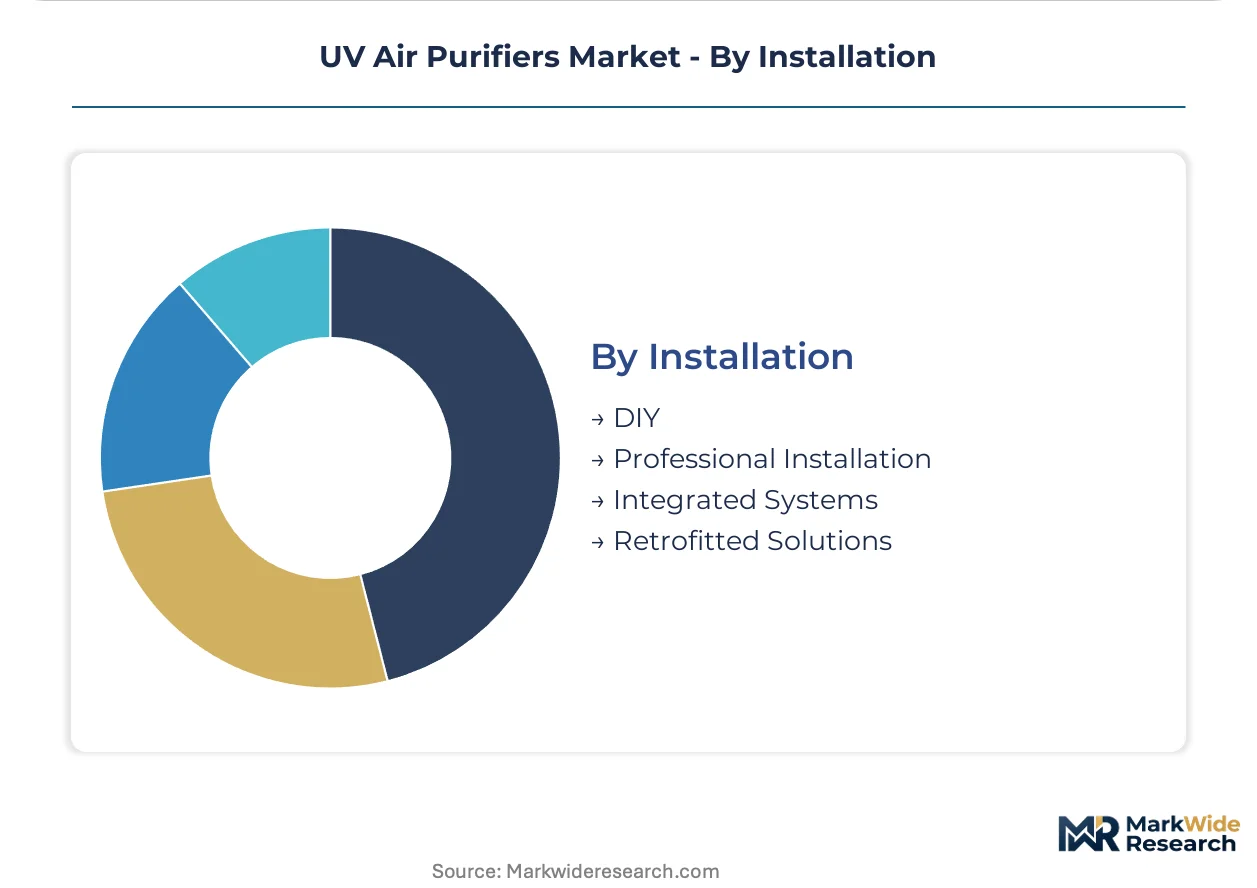
Installation:
Professional channels lock in recurring maintenance revenue, while DIY formats compete on upfront price with minimal service attachment.
- Professional Installation:Certified technician deployment with ongoing lamp replacement and quartz sleeve cleaning contracts. United States healthcare and education verticals unbundle equipment from service, treating these as separately negotiated lines.
- Integrated Systems:Factory-installed UV modules bundled with new HVAC equipment by climate manufacturers.
- DIY:Consumer self-installation of portable or simple wall-mounted units.
- Retrofitted Solutions:Field modification of existing ductwork and air handlers.
Margin stability resides in Professional Installation. Fastest channel growth is appearing in Integrated Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of UV-C LED emitters concentrates in East Asian semiconductor corridors, while deployment demand clusters in North American healthcare infrastructure and European commercial building retrofits. This production-consumption divide shapes trade flows and regulatory harmonization pressures across the industry.
United States
Hospital HVAC retrofit programs in Texas and Florida are specifying duct-mounted UV systems to reduce nosocomial transmission. The FDA maintains 510(k) clearance pathways for clinical-grade devices, while the EPA administers voluntary verification protocols under ANSI/AHAM AC-1 methodology. The Boston-Cambridge corridor hosts specialized optical engineering talent pools for UV-C LED reactor design.
China
GB standards for indoor air quality are tightening documentation requirements for microbial reduction claims in commercial buildings. MIIT industrial policy channels subsidies toward semiconductor packaging capabilities for UV-C LED modules. The Yangtze River Delta manufacturing belt dominates aluminum nitride substrate fabrication for solid-state emitter production.
Germany
Commercial building specifiers in Bavaria and North Rhine-Westphalia are embedding UV-C into ASHRAE-aligned ventilation upgrades for workplace infection control. The EU Green Deal and REACH regulations are accelerating mercury lamp phase-out timelines across member states. The Stuttgart industrial cluster specializes in precision optical components for reactor chamber engineering.
Japan
METI energy efficiency mandates favor instant-on UV-C LED architectures over legacy mercury systems in intermittent-use commercial settings. JIS standards for electrical safety and electromagnetic compatibility create baseline qualification requirements for equipment imports. The Nagoya-Chubu corridor hosts captive supply chains linking semiconductor wafer production to finished fixture assembly.
India
BIS mandatory IS 16289 certification for room air purifiers is creating compliance-driven demand in Delhi-NCR and Mumbai metropolitan markets. CDSCO medical device regulations parallel FDA pathways for clinical-grade UV equipment in hospital procurement. The Maharashtra industrial belt is emerging as a regional assembly hub for duct-mounted commercial systems serving South Asian export markets.
UV Air Purifiers Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Tier-one positions are occupied by climate equipment manufacturers with captive HVAC distribution channels and semiconductor fabricators with backward integration into UV-C LED sourcing. Tier-two comprises regional specialists in optical reactor engineering and building automation integrators. The dominant competitive moves are bundling UV modules with new climate equipment sales and securing long-term maintenance contracts through professional installation channels.
Among diversified technology conglomerates, Honeywell International Inc. and LG Electronics Inc. exemplify scale-driven archetypes with upstream control over component supply chains. Daikin Industries, Ltd. represents the climate-equipment bundling model, leveraging installed HVAC bases to attach duct-mounted UV systems. Coway Co., Ltd. occupies a specialist position in compact residential formats for premium East Asian channels.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Daikin Industries, Ltd. |
| Resideo Technologies Inc. |
| Air Oasis LLC |
| Guardian Technologies LLC |
| Koninklijke Philips N.V. |
| Coway Co., Ltd. |
| Eureka Forbes Limited |
| LG Electronics Inc. |
| Others |
Supply Flow & Price Mechanics
EU REACH mercury phase-out mandates gate qualified supply for premium-tier UV-C LED architectures, restricting access to certified aluminum nitride substrate sources and concentrating pricing power among Japanese and Korean semiconductor specialists serving clinical-grade buyers.
Pricing Analysis
Margin tightening in portable residential units reflects mercury lamp oversupply and LED emitter cost-down curves. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared clinical systems from EPA-verified commercial units and uncertified consumer imports. Healthcare facilities show lowest price sensitivity due to bundled service contracts, while residential e-commerce channels face acute cost compression from private-label competition.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from climate equipment manufacturers bundling UV modules with new HVAC systems. Aluminum nitride wafer fabrication concentrates in Japan, South Korea, and the Yangtze River Delta manufacturing belt. UV-C LED chip packaging draws from Taiwan and Malaysia assembly facilities. Single-source vulnerability in high-purity substrate supply creates procurement risk for reactor chamber fabricators. Distribution runs through specialized HVAC wholesalers and building automation integrators rather than general electronics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aluminum nitride wafer capacity constraints prop pricing across qualified supply tiers, favoring incumbents with long-term substrate offtake agreements.
For Market Incumbents: Anticipate ionization technology substitution in commercial building budgets by deepening backward integration into UV-C LED semiconductor sourcing and securing exclusive distribution through GPO contracts with United States hospital systems. Lock in 10,000-hour maintenance service agreements before LED modularization disintermediates traditional single-source supplier relationships. For New Entrants and Emerging Players: BIS mandatory IS 16289 certification in India opens a window for compliance-first positioning in Delhi-NCR and Mumbai metropolitan markets where incumbent presence remains thin. Target duct-mounted commercial retrofits in Texas and Florida hospital infrastructure programs, leveraging ASHRAE 241 standard alignment as the primary specification wedge against portable unit specialists. For Investors and Strategic Acquirers: FDA 510(k) clearance acceleration for clinical-grade UV medical devices is the leading indicator that regulatory moats are widening for purpose-built healthcare systems over general environmental units. Position for 5-10 year holding periods around optical reactor engineering specialists with captive aluminum nitride substrate relationships, monitoring EPA verification protocol tightening as the signal for consolidation timing toward certified manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into UV-C LED Sourcing | Captive aluminum nitride wafer supply secures margin control against Japanese and Korean substrate specialists. |
| ASHRAE 241 Standard Alignment | Explicit UV-C recommendation embeds products into commercial building mechanical specifications. |
| Hospital GPO Contract Securement | Group purchasing organization agreements lock out competitors from United States healthcare infrastructure spending. |
| Photocatalytic Oxidation Convergence | TiO2-coated reactor expansion captures VOC remediation budgets beyond pathogen-focused buyers. |
| Smart Home Platform Integration | Voice-controlled thermostat connectivity captures premium positioning in connected residential ecosystems. |
Methodological Framework
EPA verification protocols, FDA 510(k) device databases, and ASHRAE guideline documentation formed the secondary backbone, cross-referenced with primary interviews involving HVAC specification engineers, hospital biomedical equipment managers, semiconductor packaging executives, and building automation integrators. Bottom-up unit shipment estimates triangulated against top-down addressable market sizing across the projection horizon.
Historical trendline analysis of mercury lamp replacement cycles and UV-C LED adoption curves informed the analytical framework, with segmentation across product architecture, emitter technology, end-use vertical, and installation channel. CAGRs derived from installed base turnover modeling and new-build specification rates, incorporating aluminum nitride substrate supply constraints and regulatory compliance timeline shifts as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for UV-C LED modularization would alter the outlook if semiconductor packaging cost curves steepen unexpectedly. Periodic stress-testing of base assumptions is recommended given FDA device classification friction and REACH mercury phase-out enforcement variability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Quality Control Systems
Singapore Air Purifier Market
Air Quality Control Systems
Global Mist Eliminator Market
Air Quality Control Systems
Emission Management Software Market
Air Quality Control Systems
Sustainable Air Filter Market
Air Quality Control Systems
Asia Pacific Air Filtration Market
Air Quality Control Systems
North America Industrial Air Quality Control Systems Market
Air Quality Control Systems
Indoor Air Purification Market
Air Quality Control Systems
Air Scrubber Market
Air Quality Control Systems
United States Pollution Mask Market
Air Quality Control Systems
Ozone Analyzer Market
Air Quality Control Systems
Middle-East and Africa Industrial Air Quality Control Systems Market
Air Quality Control Systems
Air Pollution Control Systems Market
Air Quality Control Systems
Green Emissions Analyzers Market
Air Quality Control Systems
Ozone Generation Market
Air Quality Control Systems
Southeast Asia Air Purifier Market
Air Quality Control Systems
Air Quality Monitoring Software Market