
 Industrial Air Quality Control Systems Market | 2026-2036
Industrial Air Quality Control Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Air Quality Control Systems Market Foresight
Scarce instrumentation engineering talent is bifurcating the competitive landscape into technology-integrated leaders and component-assembly followers. Siemens Energy AG leverages its digital twin platforms to anchor premium positioning in predictive maintenance for electrostatic precipitators. Donaldson Company specializes in membrane filtration media, sustaining margin pools in semiconductor cleanroom applications where contamination thresholds tighten quarterly. Thermax Limited dominates India's power utility retrofit segment through localized fabrication and aftermarket service density.
Industrial air quality control systems encompass engineered equipment and monitoring networks designed to capture, neutralize, or remove particulate matter, gaseous pollutants, and volatile organic compounds from process exhaust and ambient industrial air, typically operating across temperature ranges from ambient to 400°C with pressure differentials calibrated to specific capture velocities. These systems serve primary industrial purposes including regulatory compliance assurance, worker respiratory protection, product contamination prevention, and corrosion mitigation in sensitive manufacturing environments. Electrostatic precipitator technology leads capital deployment in power generation and heavy metallurgy due to mature efficiency curves above 99% for sub-micron particulate, while UV treatment systems represent the fastest-expanding technology segment as food processing facilities adopt photocatalytic oxidation for ethylene and microbial control in cold storage. Air filtration products occupy the largest product revenue pool, though monitoring systems command superior margins as facilities integrate continuous emissions monitoring to satisfy real-time reporting obligations from environmental regulators.
EPA enforcement of National Ambient Air Quality Standards and the Cross-State Air Pollution Rule shapes retrofit demand across US manufacturing and utility fleets, while China's MEE administers ultra-low emission benchmarks that mandate particulate concentrations below 10 mg per cubic meter for key industrial sectors. The EU Industrial Emissions Directive and associated Best Available Techniques reference documents establish technology-forcing thresholds that equipment suppliers must certify against for CE-marked market access. Stakeholders must monitor evolving state-level implementation timelines and technology transition deadlines that determine replacement versus upgrade economics across facility portfolios.
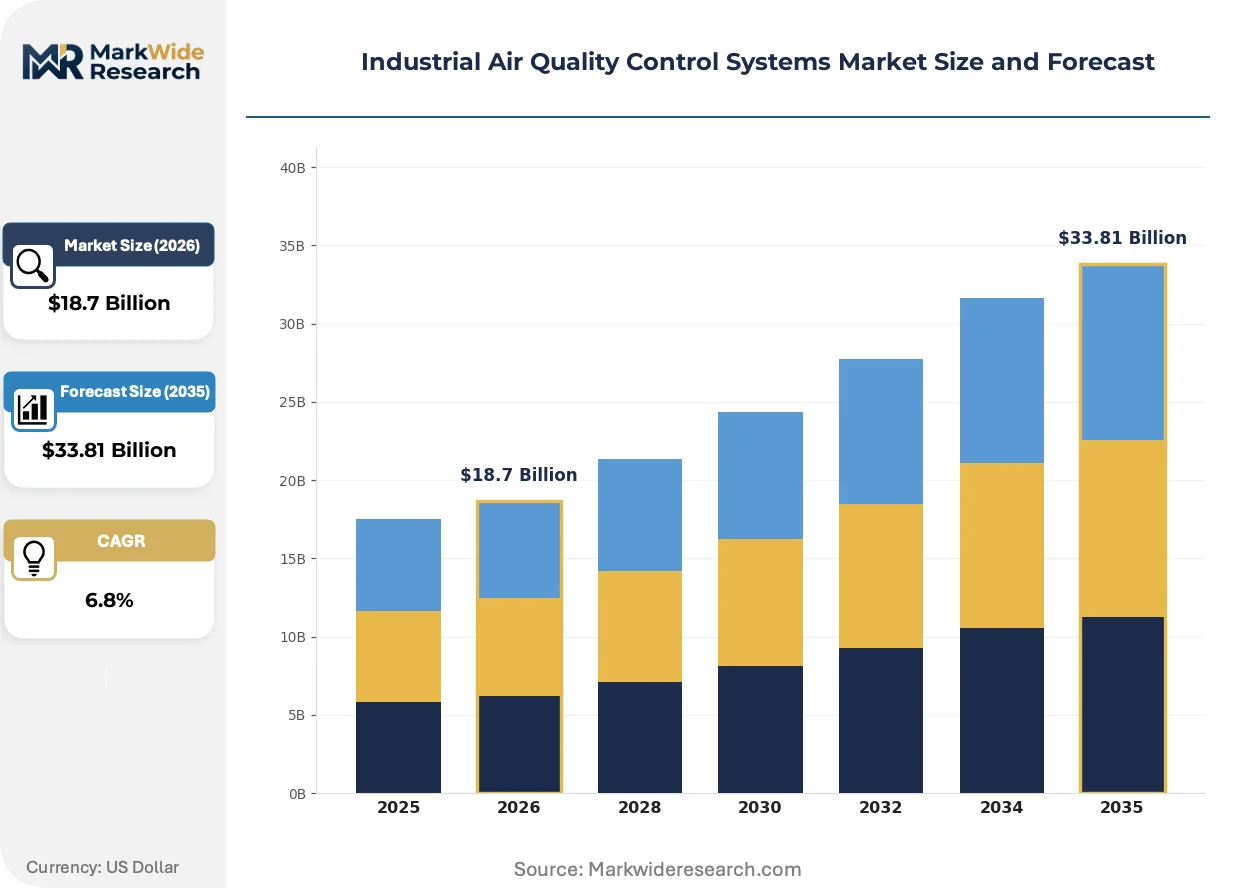
Market Dynamics
Ultra-low emission mandates from China's MEE and the US EPA are compressing retrofit timelines for coal-fired utilities, forcing capital allocation toward continuous emissions monitoring and predictive maintenance platforms rather than episodic hardware replacement.
Growth Catalysts
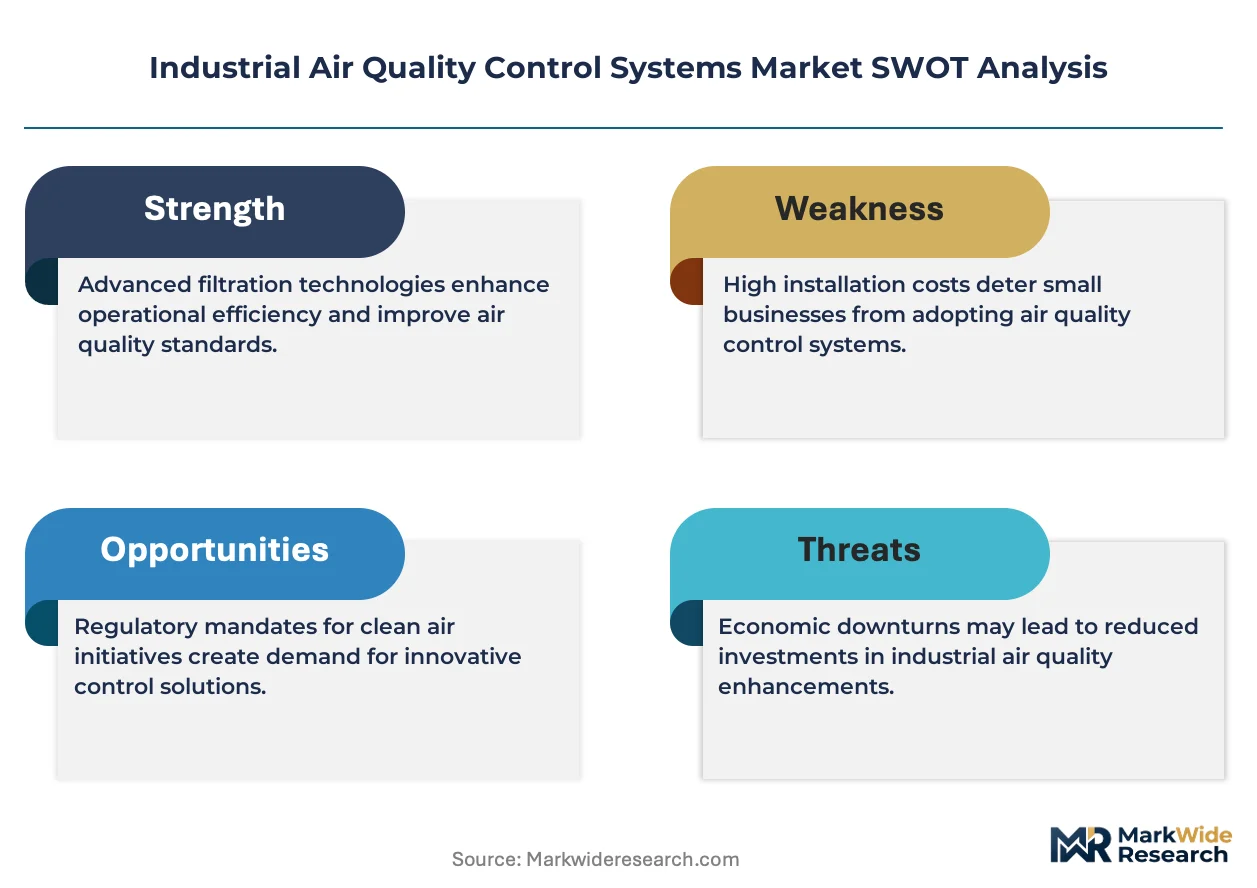
- China's MEE ultra-low emission benchmarks:Coal plants in Tangshan and Zhengzhou face monthly compliance audits, accelerating scrubber and precipitator deployments.
- Electrostatic precipitator efficiency curves:Mature capture rates above 99% for sub-micron particulate sustain capital flows into power generation and heavy metallurgy.
- UV photocatalytic oxidation:Food processing cold storage facilities adopt ethylene and microbial control systems as contamination thresholds tighten.
Market Restraints
- Scarce instrumentation engineering talent:Technology-integrated leaders capture premium positioning while component-assembly followers face margin compression.
- High-purity membrane filtration media supply:Semiconductor cleanroom applications concentrate demand among limited qualified suppliers.
- CE-marked certification timelines:EU Industrial Emissions Directive Best Available Techniques reference documents create technology-forcing bottlenecks for equipment suppliers.
Strategic Opportunities
- India's power utility retrofit segment:Localized fabrication and aftermarket service density gaps create openings for integrated service providers.
- Real-time reporting obligations:Continuous emissions monitoring systems command superior margins as facilities integrate regulatory compliance infrastructure.
- Digital twin convergence with predictive maintenance:Electrostatic precipitator asset management platforms enable subscription revenue models.
Industry Challenges
- Instrumentation engineering skill scarcity:Predictive maintenance platform deployment stalls without qualified field technicians.
- Legacy DCS integration complexity:New monitoring networks face protocol incompatibility with existing plant control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Air Quality Control Systems Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Filtration, Monitoring Systems, Ventilation Equipment, Air Purifiers Technology: Mechanical, Electrostatic Precipitators, UV Treatment, Chemical Scrubbing Application: Manufacturing, Warehousing, Power Generation, Food Processing End User: Industrial Facilities, Commercial Buildings, Construction Sites, Transportation Hubs |
| Companies Covered | Mitsubishi Heavy Industries, Thermax Limited, Siemens Energy AG, Babcock & Wilcox Enterprises, General Electric (GE Vernova), Andritz AG, Ducon Technologies, GEA Group Aktiengesellschaft, Donaldson Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Air Quality Control Systems Market Shifts & Advancements
Digital instrumentation and real-time analytics are displacing scheduled maintenance calendars across heavy industrial exhaust treatment, compressing the window between fault detection and corrective action from weeks to hours.
Electrostatic precipitator digital twin platforms combine physics-based modeling with live sensor feeds to simulate collection efficiency under varying load conditions. Power generators in the United States deploy these systems to anticipate plate rapping schedules and optimize power consumption. The technology is bifurcating the service market between predictive analytics providers and traditional mechanical contractors.
China's MEE enforcement of ultra-low emission limits for coal-fired plants mandates particulate concentrations below 10 mg per cubic meter across steel, cement, and power sectors. Provincial environmental bureaus conduct unannounced stack testing, eliminating grace periods for non-compliant facilities. Equipment suppliers must certify against GB standards to maintain market access in Tangshan, Zhengzhou, and other industrial corridor cities.
Continuous emissions monitoring procurement now favors integrated hardware-software bundles over component sourcing. Utility buyers in India and China specify real-time data transmission to regulator portals as a contractual requirement. This specification shift compresses vendor qualification timelines and elevates total cost of ownership calculations above upfront capital expenditure in supplier selection criteria.
Industrial Air Quality Control Systems Market Segmentation
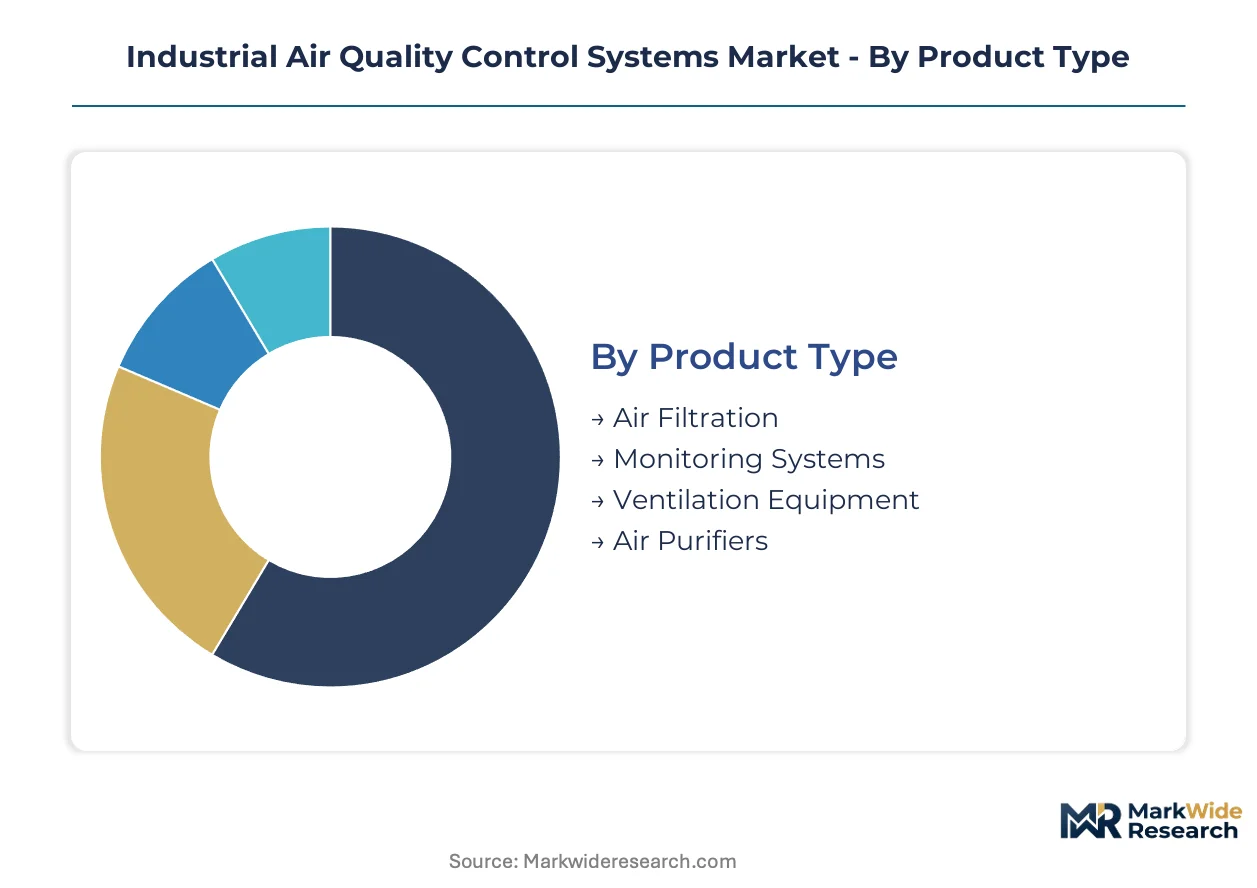
Industrial air quality control systems fragment across four dimensions that determine procurement criteria and vendor qualification pathways. Product type and technology selection hinge on capture efficiency requirements and thermal operating conditions, while application and end-user categories dictate compliance frameworks and service intensity models.
Product Type:
Substitution pressure runs highest against standalone air purifiers as integrated filtration-ventilation bundles capture specification share in new facility design.
- Air Filtration:Engineered media assemblies including HEPA, activated carbon, and membrane configurations remove particulate and gaseous contaminants across pressure differentials calibrated to capture velocity. Manufacturing facilities in China's industrial corridor cities deploy these systems to satisfy MEE ultra-low emission mandates below 10 mg per cubic meter.
- Monitoring Systems:Continuous emissions monitoring hardware with real-time data transmission capabilities to regulator portals. Power generators in India and the United States specify these as contractual requirements, elevating total cost of ownership above upfront capital in supplier selection.
- Ventilation Equipment:Dilution and local exhaust systems managing airflow rates for contaminant dispersion.
- Air Purifiers:Self-contained units for localized contamination control in commercial and light industrial settings.
Air filtration anchors the volume base while monitoring systems gain share at the steepest rate.
Technology:
Cost tier stratification separates mature mechanical methods from premium electrostatic and UV platforms commanding service attach rates.
- Electrostatic Precipitators:High-voltage ionization fields capture sub-micron particulate above 99% efficiency across temperature ranges to 400°C. Heavy metallurgy and coal-fired power deployment sustains capital flows, with digital twin platforms now enabling predictive maintenance subscriptions.
- UV Treatment:Photocatalytic oxidation systems for ethylene and microbial control in food processing cold storage. Contamination thresholds tightening quarterly drive specification in semiconductor and pharmaceutical cleanroom adjacent applications.
- Mechanical:Cyclonic separation and media filtration using physical barrier methods.
- Chemical Scrubbing:Wet and dry absorption systems neutralizing acid gases and volatile organic compounds.
Mechanical methods retain the installed base while UV treatment climbs the fastest on food safety regulation.
Application:
Volume concentration maps directly to emission-intensive process intensity and regulatory enforcement visibility.
- Power Generation:Scrubber and precipitor deployments for stack emission compliance. EPA Mercury and Air Toxics Standards and China's MEE enforcement compress retrofit timelines, forcing capital toward continuous monitoring rather than episodic hardware replacement.
- Manufacturing:Process exhaust capture for worker respiratory protection and product contamination prevention. Semiconductor fabs and battery cell production drive high-purity membrane demand where qualified supplier pools remain limited.
- Food Processing:Cold storage ethylene control and microbial management.
- Warehousing:Ambient air quality maintenance for inventory protection and worker safety.
Power generation anchors the volume base while food processing gains share at the steepest rate.
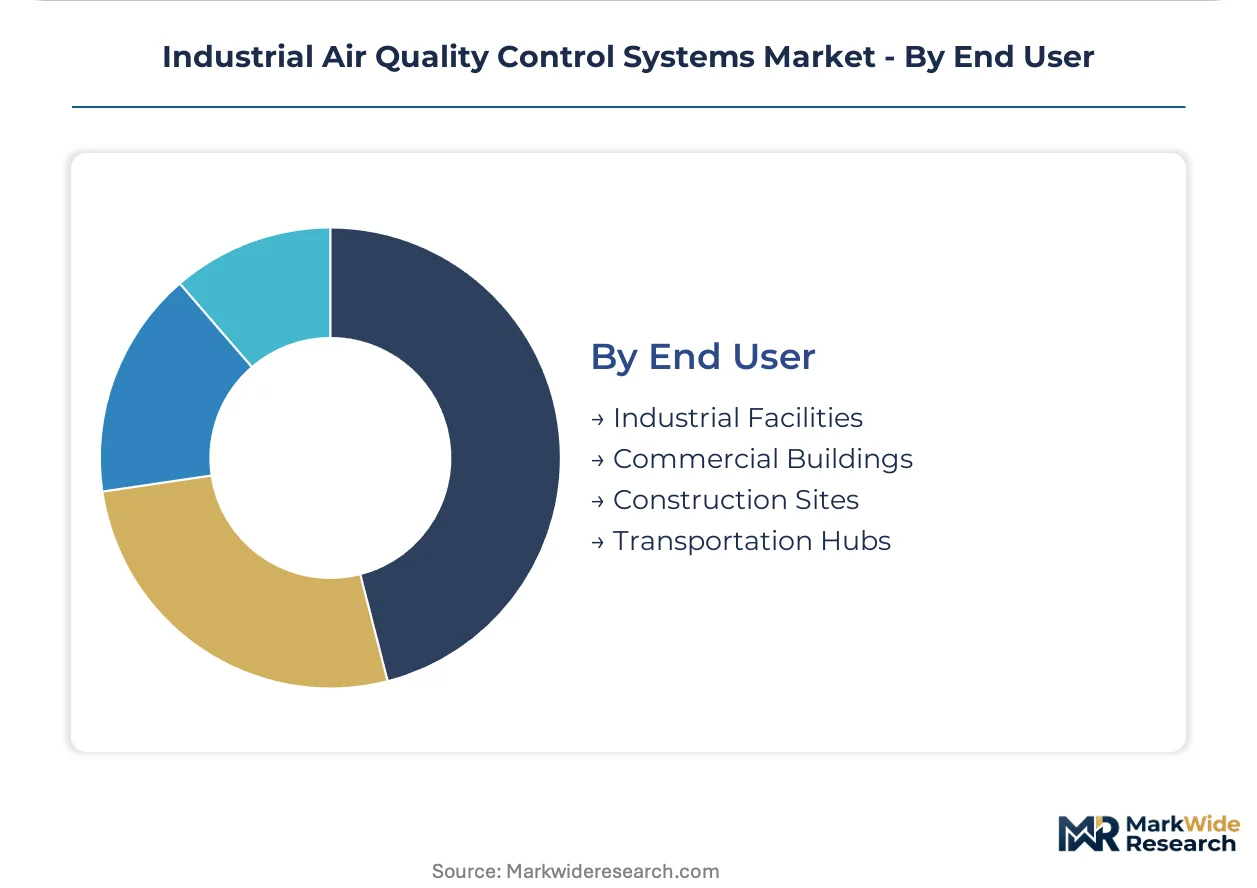
End User:
Customer type determines service density requirements and aftermarket revenue potential across equipment lifecycles.
- Industrial Facilities:Heavy process exhaust treatment with predictive maintenance platform integration. Scarce instrumentation engineering talent bifurcates procurement between technology-integrated leaders and component-assembly followers.
- Commercial Buildings:Ventilation and filtration for occupant health and HVAC system protection.
- Construction Sites:Temporary dust suppression and worker respiratory protection.
- Transportation Hubs:High-occupancy ventilation and filtration for passenger safety.
Industrial facilities anchor the volume base while commercial buildings gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MEE anchors the dominant geography through ultra-low emission mandates that compress retrofit timelines for coal-fired utilities and heavy industry. Equipment suppliers must certify against GB standards to maintain market access in industrial corridor cities.
China
Provincial environmental bureaus conduct monthly compliance audits in Tangshan and Zhengzhou, forcing scrubber and precipitator deployments. The MEE mandates particulate concentrations below 10 mg per cubic meter across steel, cement, and power sectors. Equipment suppliers face unannounced stack testing with eliminated grace periods for non-compliant facilities.
United States
Power generators expand scrubber installations to satisfy EPA Mercury and Air Toxics Standards enforcement. The Cross-State Air Pollution Rule shapes retrofit demand across manufacturing and utility fleets. Facilities in the Ohio River Valley and Texas Gulf Coast concentrate capital allocation toward continuous emissions monitoring platforms.
India
Thermax Limited dominates power utility retrofits through localized fabrication and aftermarket service density. The CEA mandates emission norms for thermal power plants that drive electrostatic precipitator upgrades. Industrial clusters in Maharashtra and Gujarat face tightening state pollution control board inspections.
Germany
Industrial facilities integrate predictive maintenance platforms to satisfy EU Industrial Emissions Directive Best Available Techniques requirements. CE-marked certification timelines create technology-forcing bottlenecks for equipment suppliers. The Ruhr industrial region and Bavarian manufacturing belt concentrate demand for integrated hardware-software bundles.
Japan
Semiconductor fabs and battery cell production drive high-purity membrane filtration demand where qualified supplier pools remain limited. METI promotes clean manufacturing standards that tighten contamination thresholds quarterly. The Kyushu and Kansai industrial corridors anchor precision equipment specification.
Industrial Air Quality Control Systems Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the Industrial Air Quality Control Systems Market. Technology-integrated players capture premium positioning through digital twin platforms and predictive maintenance subscriptions, while component-assembly followers face margin compression from scarce instrumentation engineering talent. Strategic archetypes include full-stack solution providers, membrane filtration specialists, and regional fabrication champions. Dominant competitive moves center on geographic expansion through localized service density and portfolio diversification into monitoring system integration.
Within the integrated technology tier, Siemens Energy AG and Mitsubishi Heavy Industries exemplify platform-centric positioning, while Donaldson Company occupies a specialist position in filtration media. Thermax Limited anchors the regional fabrication archetype through India-based aftermarket service networks. These three represent distinct competitive vectors: digital instrumentation convergence, high-purity membrane supply, and localized retrofit execution.
| Leading Market Players |
|---|
| Mitsubishi Heavy Industries |
| Thermax Limited |
| Siemens Energy AG |
| Babcock & Wilcox Enterprises |
| General Electric (GE Vernova) |
| Andritz AG |
| Ducon Technologies |
| GEA Group Aktiengesellschaft |
| Donaldson Company |
| Others |
Supply & Pricing Matrix
Capacity utilization at electrostatic precipitator fabrication facilities in China and India shapes both supply concentration and price floors for integrated air quality systems. High fixed-cost structures in membrane filtration media production tether margin recovery to volume throughput, compressing pricing flexibility for component-assembly followers while technology-integrated leaders capture premium positioning through predictive maintenance subscriptions.
Pricing Analysis
Price spreads between Chinese-manufactured electrostatic precipitators and European-certified systems reach three-to-one multiples depending on GB versus CE compliance tiers. Three-tier pricing structure across premium digital-twin-enabled, standard integrated-bundle, and economy component-assembly levels reflects certification grade and after-sales service density. Cost compression in the economy tier is intensifying because provincial environmental bureaus in Tangshan and Zhengzhou mandate real-time data transmission capabilities that legacy hardware cannot satisfy. Power utilities in India exhibit highest price sensitivity due to CEA-mandated retrofit timelines, while semiconductor fabs in Japan and South Korea show lowest sensitivity given quarterly contamination threshold tightening.
Supply Chain Analysis
Inbound logistics costs from Shanghai and Busan port congestion ripple through high-purity membrane filtration media lead times, compressing just-in-time delivery windows for semiconductor cleanroom applications. Component supply concentrates in China for electrostatic precipitator internals, Germany for precision instrumentation, and Japan for ceramic filter media. Raw material dependencies span high-grade stainless steel for precipitator casings, specialized ceramics for high-temperature filtration, and rare-earth elements for UV photocatalytic catalysts. Single-source vulnerability in qualified membrane suppliers for sub-10-nanometer semiconductor applications creates qualification bottlenecks. Distribution runs through regional fabrication champions with localized aftermarket service networks in India and China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of instrumentation engineers capable of deploying predictive maintenance platforms is concentrating competitive advantage among technology-integrated leaders, leaving component-assembly followers exposed to margin compression and share erosion.
For Market Incumbents: Secure digital twin platform penetration across electrostatic precipitator installed bases before emerging analytics specialists capture retrofit upgrade cycles. Deepen backward integration into high-purity membrane filtration media production to defend against qualified supplier scarcity in semiconductor applications. Anchor capacity expansion in India's Maharashtra and Gujarat industrial clusters where CEA emission norms compress vendor qualification timelines. For New Entrants and Emerging Players: GB standard fast-track certification for ultra-low emission compliance opens immediate access to Tangshan and Zhengzhou procurement cycles where monthly MEE audits eliminate grace periods. Target food processing cold storage UV treatment segments in Southeast Asia where contamination thresholds tighten quarterly but incumbent service density remains thin. Pursue hardware-software bundle positioning that satisfies real-time regulator portal transmission requirements as primary go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among predictive maintenance platform providers serving power utility fleets with compressed EPA and MEE retrofit timelines. Long-term viability centers on digital instrumentation convergence rather than standalone hardware manufacturing. Acquisition focus should center on regional fabrication champions with dense aftermarket service networks. Monitor CEA enforcement intensity in India and state pollution control board inspection frequency as inflection indicators for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Deployment | Digital twin integration for electrostatic precipitators enables subscription revenue models beyond episodic hardware replacement. |
| GB Standard Certification Fast-Track | Accelerated compliance approval unlocks procurement access in Tangshan and Zhengzhou where MEE audits operate monthly. |
| Backward Integration into Membrane Media | Captive supply of high-purity filtration materials defends margin pools in semiconductor cleanroom applications. |
| Localized Fabrication Capacity Expansion | Regional production in Maharashtra and Gujarat compresses delivery timelines for India's CEA-mandated utility retrofits. |
| Hardware-Software Bundle Specification | Integrated continuous emissions monitoring satisfies real-time data transmission requirements in utility procurement contracts. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads across power generation and semiconductor manufacturing; and secondary validation through EPA enforcement disclosures, MEE ultra-low emission compliance databases, customs trade records for filtration media, and SEC filings from listed equipment suppliers. Bottom-up unit economics triangulated against top-down sectoral expenditure patterns.
Across the analysis window, the forecasting framework modeled product type segmentation alongside technology maturity curves, application-specific compliance intensity, and end-user service density requirements. CAGRs derived from installed base turnover rates, regulatory deadline clustering, and technology substitution elasticity. Key inputs included MEE audit frequency data, CEA retrofit mandate progression, and EPA Mercury and Air Toxics Standards enforcement intensity.
Decision-makers should treat outputs as directional under sustained EPA and MEE enforcement intensity, stable raw material availability for ceramic and membrane components, and continued instrumentation engineering scarcity; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Quality Control Systems
Europe Nitrogen Oxide Control Systems Market
Air Quality Control Systems
Environmental Control System (ECS) Market
Air Quality Control Systems
Emission Management Software Market
Air Quality Control Systems
US Air Quality Analyzers Market
Air Quality Control Systems
Ozone Generation Market
Air Quality Control Systems
Southeast Asia Air Purifier Market
Air Quality Control Systems
Europe Industrial Air Quality Control Systems Market
Air Quality Control Systems
Green Emissions Analyzers Market
Air Quality Control Systems
Sustainable Air Filter Market
Air Quality Control Systems
Oxygen Filters Market
Air Quality Control Systems
Indoor Air Purification Market
Air Quality Control Systems
Singapore Air Purifier Market
Air Quality Control Systems
UV Air Purifiers Market
Air Quality Control Systems
Anti-Pollution Toner Market
Air Quality Control Systems
North America Industrial Air Quality Control Systems Market
Air Quality Control Systems
Air Pollution Control Equipment Market