
 Oxygen Filters Market | 2026-2036
Oxygen Filters Market Size, Share, and Industry Trends Forecast 2026-2036
Oxygen Filters Market Insights
Medical-grade filtration standards are redrawing competitive boundaries in oxygen filter supply. Invacare Corporation leverages its homecare distribution network to sustain replacement filter volumes across North American retail channels. Philips Respironics anchors its position through R&D intensity in miniaturized HEPA assemblies for portable oxygen concentrators. ResMed Inc. competes on technology leadership in low-resistance membrane designs that extend battery life in mobile therapeutic devices.
Oxygen filters are porous or fibrous media engineered to remove particulates, moisture, and gaseous contaminants from oxygen streams, typically rated by filtration efficiency at particle sizes down to 0.3 microns and maximum allowable pressure drop across the media. Their primary purpose is protecting downstream equipment and patients from impurities that could degrade combustion performance, foul precision instruments, or introduce respiratory pathogens in therapeutic settings. Membrane filtration segments command premium positioning where ultrahigh-purity oxygen is required for semiconductor fabrication and aerospace life-support systems. HEPA and activated carbon configurations dominate medical device applications, with electrostatic variants gaining traction in industrial process environments where lower operating costs offset higher initial media replacement frequency.
FDA 510(k) premarket notification requirements and ISO 18562 biocompatibility evaluation standards for breathing gas pathways are elevating validation costs for new oxygen filter entrants while consolidating procurement around established certified suppliers. The EPA's National Emission Standards for Hazardous Air Pollutants indirectly shapes industrial oxygen filter specifications by mandating cleaner combustion inputs that depend on contaminant-free oxygen feedstock. Stakeholders must monitor evolving convergence between medical device quality management systems and industrial gas purity certifications as cross-sector procurement standardization accelerates.
Market Dynamics
Medical device manufacturers and industrial gas processors face converging certification demands as ISO 18562 biocompatibility standards and EPA combustion purity mandates begin overlapping in procurement specifications. This regulatory compression is forcing filter suppliers to maintain dual validation pathways for previously distinct end-use segments.
Growth Catalysts
- Portable Oxygen Concentrator Expansion:Homecare respiratory therapy is driving HEPA-grade filter volumes as manufacturers miniaturize filtration assemblies for battery-operated devices. Patient mobility preferences are accelerating replacement cycle frequency.
- REACH Chemical Compliance:The EU's extended restrictions on fluorinated polymers are redirecting membrane development toward bio-based alternatives, opening procurement windows for certified European suppliers.
- Semiconductor Fabrication Purity Demands:Advanced chip manufacturing requires ultrahigh-purity oxygen streams with sub-ppb contaminant thresholds, commanding premium membrane filtration pricing and technical service contracts.
Market Restraints
- PTFE Raw Material Concentration:Fluoropolymer membrane production depends on concentrated Asian chemical feedstock suppliers, exposing filter manufacturers to input cost volatility and supply rationing during geopolitical friction.
- FDA 510(k) Validation Burden:Extended premarket notification timelines for respiratory accessories are freezing smaller suppliers out of medical device procurement, consolidating volume around established certificated vendors.
- Electrostatic Filter Substitution:Industrial process environments are adopting lower-efficiency electrostatic precipitation for oxygen pre-treatment, compressing demand for mechanical HEPA media in non-medical combustion applications.
Strategic Opportunities
- India Homecare Oxygen Infrastructure:The country's PLI scheme for medical devices is attracting filter manufacturers to establish local production for nascent portable concentrator assembly operations.
- Activated Carbon-HEPA Hybrid Convergence:Dual-function media combining particulate and gaseous contaminant removal are capturing design wins in aerospace life-support systems where weight and volume constraints dominate.
- Direct-to-Patient Replacement Channels:E-commerce platforms specializing in durable medical equipment are disintermediating traditional distributor networks for consumer-replaceable filter cartridges.
Industry Challenges
- Biocompatibility Testing Talent Scarcity:ISO 18562 cytotoxicity and sensitization evaluation requires specialized toxicology expertise that filter manufacturers struggle to recruit outside established medical device hubs.
- Legacy Equipment Integration Complexity:New low-resistance membrane designs face retrofit friction with installed concentrator bases optimized for higher pressure-drop legacy media specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oxygen Filters Market |
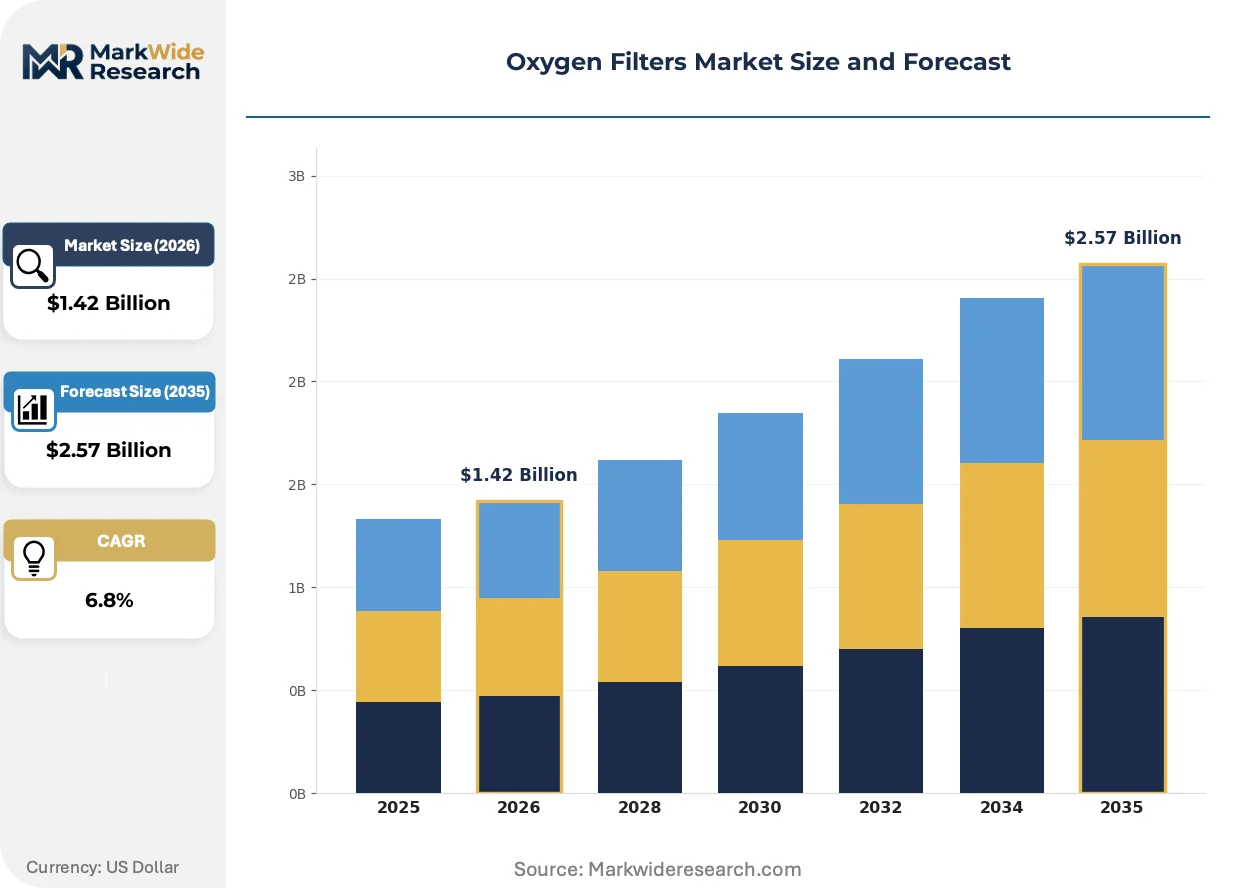
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Activated Carbon, HEPA, Membrane, Electrostatic Application: Aerospace, Medical Devices, Industrial Processes, Water Purification End User: Hospitals, Manufacturing Plants, Research Institutions, Individuals Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Wholesale |
| Companies Covered | Invacare Corporation, Philips Respironics, Medtronic plc, Drive DeVilbiss Healthcare, CAIRE Inc., AirSep Corporation, Nidek Medical Products Inc., ResMed Inc., Fisher & Paykel Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oxygen Filters Market Trends and Innovations
Filter media engineering is pivoting toward multifunctional architectures that simultaneously address particulate, moisture, and gaseous contaminant removal. Material science advances and regulatory harmonization efforts are compressing product development cycles.
Polymeric nanofiber membranes are decomposing traditional melt-blown nonwoven dominance in medical-grade oxygen filtration. Portable concentrator manufacturers in Germany and the United States are qualifying these sub-micron fiber structures for their superior pressure-drop characteristics. The technology is decomposing the historical trade-off between filtration efficiency and battery life that constrained mobile therapeutic device design.
The FDA's updated 510(k) premarket notification requirements for respiratory gas pathway accessories are elevating biocompatibility documentation burdens. Filter suppliers must now submit comprehensive ISO 18562-1 through -4 testing protocols for all breathing gas contact materials. Homecare device manufacturers in North America are responding by consolidating procurement around suppliers with existing FDA master files.
Hospital procurement departments are unbundling filter replacement from capital equipment service contracts. Group purchasing organizations are negotiating direct supply agreements with certified filter manufacturers, bypassing original equipment manufacturer markup. This purchasing autonomy is most visible in German acute care networks where homecare transition programs require standardized filtration across institutional and domiciliary settings.
Oxygen Filters Market Segmentation
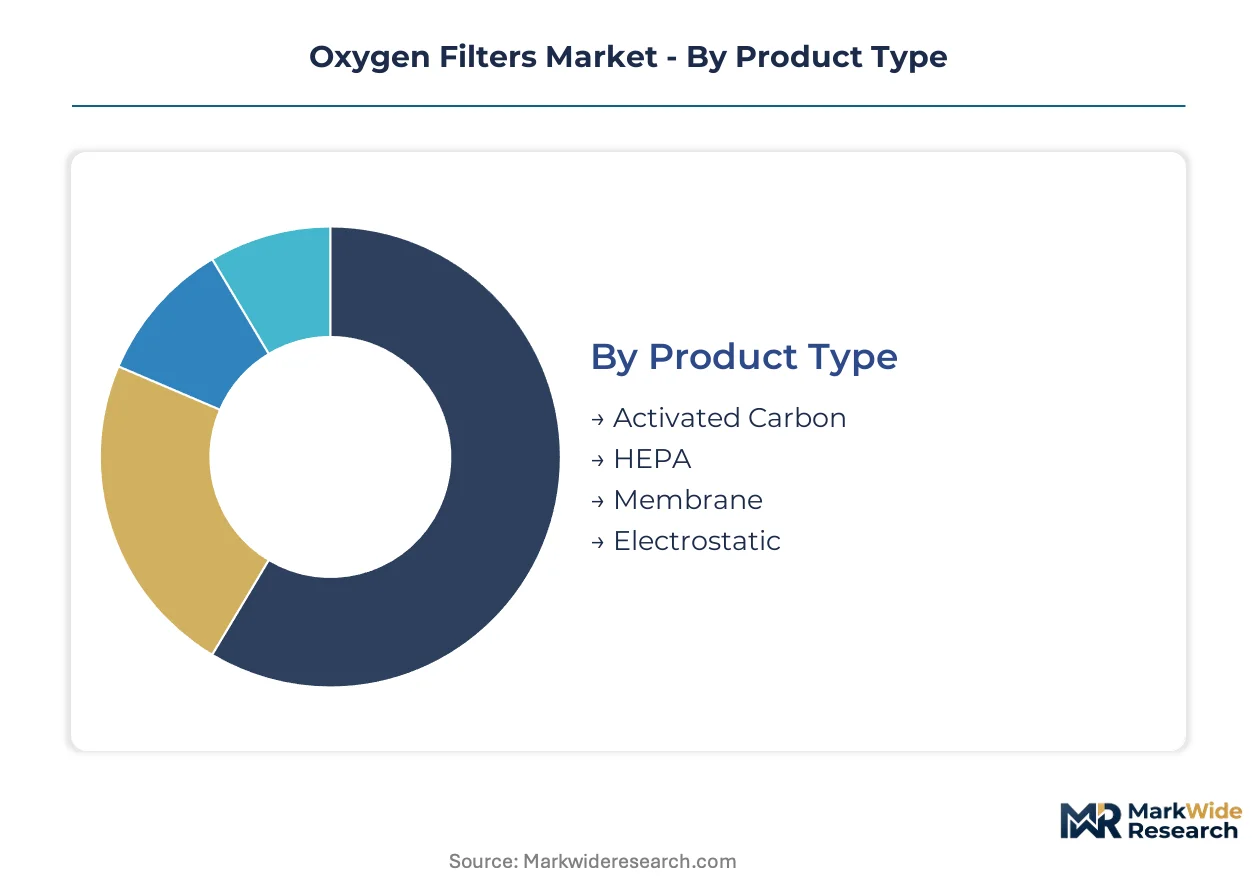
Oxygen filter procurement splits sharply between medical certification premiums and industrial volume efficiency. Understanding segment boundaries clarifies where technical differentiation commands pricing power versus where scale economies dominate supplier selection.
Product Type:
Margin pools concentrate in membrane technologies where semiconductor and aerospace purity thresholds justify technical service contracts and long-term supply agreements.
- Membrane:Polymeric nanofiber structures achieve sub-ppb contaminant removal for semiconductor fabrication and life-support systems. German portable concentrator manufacturers in Munich and Stuttgart are qualifying these for battery-operated devices where pressure-drop minimization extends operational runtime. REACH chemical compliance is redirecting development toward bio-based fluoropolymer alternatives.
- HEPA:Fibrous media rated at 0.3-micron efficiency dominates medical device applications where FDA 510(k) clearance and ISO 18562 biocompatibility documentation create supplier stickiness. Homecare oxygen concentrator replacement cycles are accelerating as patient mobility preferences intensify.
- Activated Carbon:Adsorptive media targets gaseous contaminant removal in industrial combustion pre-treatment.
- Electrostatic:Precipitation systems are gaining industrial process adoption where lower operating costs offset higher maintenance frequency.
Membrane holds installed capacity. Electrostatic is rotating up the share rankings in non-medical combustion applications.
Application:
Volume concentration follows regulatory stringency gradients, with medical and aerospace applications absorbing disproportionate qualification overhead.
- Medical Devices:Portable oxygen concentrators and institutional respiratory equipment demand HEPA-grade particulate removal combined with moisture control. The FDA's tightened 510(k) pathways for breathing gas pathway accessories are consolidating procurement around established certified suppliers with existing master files. German homecare transition programs are standardizing filtration specifications across hospital and domiciliary settings.
- Aerospace:Life-support systems require dual-function media addressing particulate, moisture, and gaseous contaminants within severe weight and volume constraints. Activated carbon-HEPA hybrid configurations are capturing design wins in crew and passenger oxygen systems.
- Industrial Processes:Combustion feedstock purification responds to EPA National Emission Standards for Hazardous Air Pollutants mandating cleaner oxygen inputs.
- Water Purification:Dissolved oxygen control in wastewater and aquaculture applications employs lower-specification mechanical filtration.
Medical Devices anchors revenue concentration. Aerospace is climbing the fastest on purity premium expansion.
End User:
Customer type determines contract structure, with institutional procurement favoring multi-year supply agreements and individual channels driving replacement cartridge frequency.
- Hospitals:Acute care networks in Germany are unbundling filter replacement from capital equipment service contracts, with group purchasing organizations negotiating direct manufacturer agreements. Standardization requirements across institutional and homecare transition programs are compressing supplier rosters.
- Individuals:Direct-to-patient e-commerce channels for durable medical equipment are disintermediating traditional distributor networks. Replacement cartridge subscriptions for home oxygen concentrators are building recurring revenue streams for certified suppliers.
- Manufacturing Plants:Industrial gas processors face converging ISO 18562 and EPA certification demands previously distinct across medical and combustion applications.
- Research Institutions:Laboratory oxygen supply requires intermediate purity grades with flexible procurement volumes.
Hospitals hold installed capacity. Individuals are rotating up the share rankings on channel disintermediation.
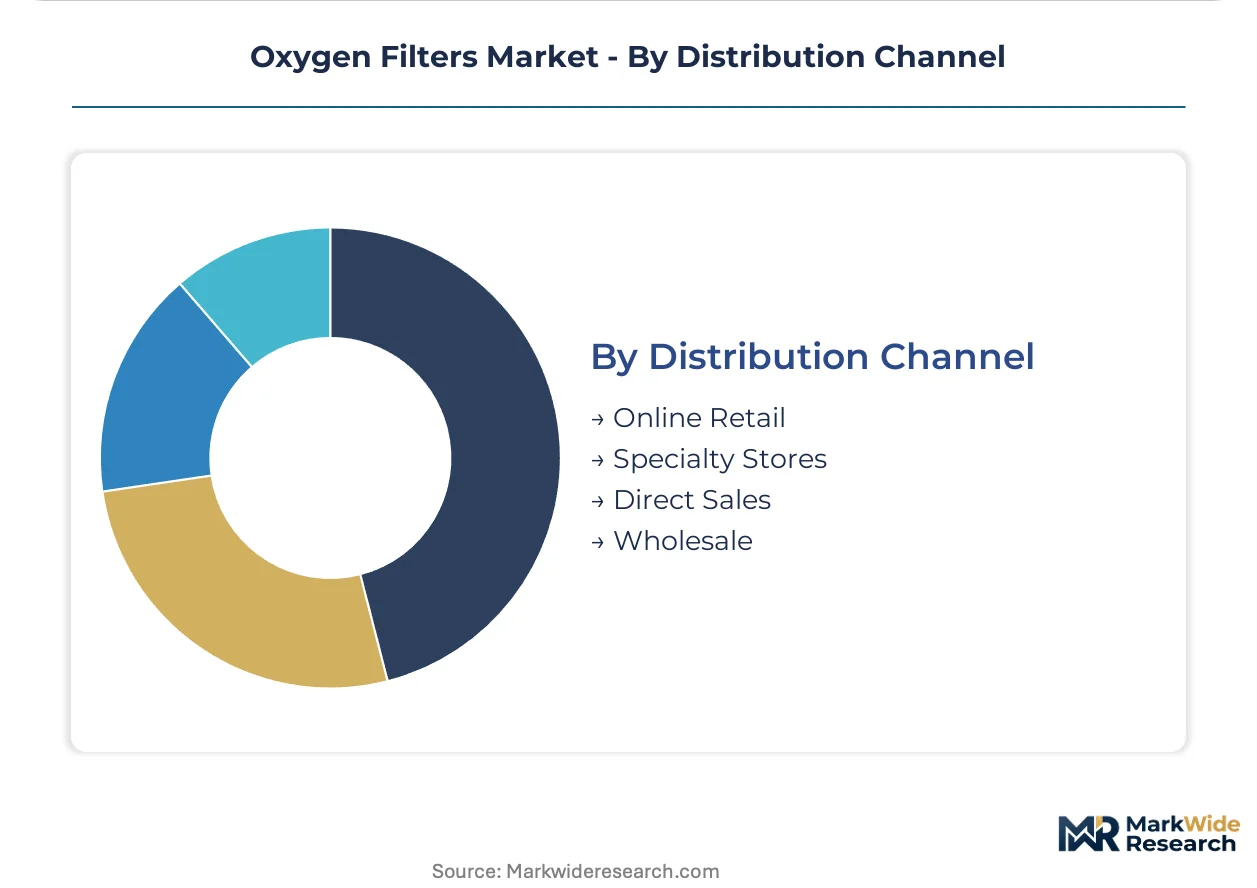
Distribution Channel:
Channel economics diverge between technical consultation requirements for industrial accounts and convenience-driven consumer replacement purchasing.
- Direct Sales:Industrial gas processors and semiconductor fabs require application engineering support and technical service contracts. Field technical consultation justifies relationship-based procurement over transactional purchasing.
- Online Retail:E-commerce platforms specializing in durable medical equipment are capturing consumer-replaceable filter cartridge volumes. Homecare oxygen patients in the United States and Germany are shifting replacement purchasing to digital channels.
- Specialty Stores:Regional durable medical equipment suppliers maintain local inventory for urgent replacement needs.
- Wholesale:Distributor networks serve smaller manufacturing plants and research institutions with consolidated procurement.
Direct Sales holds installed capacity. Online Retail is rotating up the share rankings on patient channel migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fluoropolymer membrane production clusters in Germany, China, and the United States dominate upstream supply for precision oxygen filtration. Medical device certification requirements and industrial gas purity mandates are converging procurement specifications across these manufacturing centers.
Germany
Portable oxygen concentrator manufacturers in Munich and Stuttgart are qualifying nanofiber membrane structures for battery-operated devices. REACH chemical compliance is redirecting membrane development toward bio-based fluoropolymer alternatives. The country's industrial gas purification clusters in North Rhine-Westphalia are converging with homecare oxygen standards.
United States
FDA 510(k) premarket notification requirements are consolidating procurement around established certified suppliers with existing master files. Homecare oxygen patients are shifting replacement filter purchasing to durable medical equipment e-commerce platforms. The EPA's National Emission Standards for Hazardous Air Pollutants mandate cleaner combustion inputs dependent on contaminant-free oxygen feedstock.
China
Fluoropolymer membrane production depends on concentrated chemical feedstock suppliers, exposing filter manufacturers to input cost volatility. GB standards for medical device breathing gas pathways are elevating biocompatibility documentation burdens. Yangtze River Delta industrial gas processors face converging domestic and export certification demands.
India
The PLI scheme for medical devices is attracting filter manufacturers to establish local production for nascent portable concentrator assembly operations. CDSCO medical device regulations are tightening validation requirements for respiratory accessories. Maharashtra and Karnataka are emerging as assembly hubs for homecare oxygen infrastructure.
Japan
PMDA regulatory pathways for respiratory gas pathway accessories require comprehensive ISO 18562 testing protocols. METI industrial standards for ultrahigh-purity oxygen supply semiconductor fabrication facilities. Kanto region precision equipment manufacturers command premium membrane filtration pricing for technical service contracts.
Oxygen Filters Market Competitive Landscape
Concentration sits with diversified medical device conglomerates and specialized respiratory equipment manufacturers. The vendor base stratifies across three tiers: integrated healthcare technology groups with homecare distribution networks, standalone respiratory therapy specialists, and industrial gas filtration contractors. Competitive moves center on backward integration into membrane material supply and geographic expansion into India's PLI-subsidized manufacturing zones.
Among North American healthcare technology groups, Invacare Corporation, Philips Respironics, and ResMed Inc. exemplify divergent strategic positioning. Invacare Corporation represents the homecare distribution archetype, anchoring replacement filter volumes across retail channels. Philips Respironics occupies a position emphasizing R&D intensity in miniaturized filtration assemblies. ResMed Inc. sits within the technology leadership tier, exemplifying low-resistance membrane design specialization for mobile therapeutic devices.
| Leading Market Players |
|---|
| Invacare Corporation |
| Philips Respironics |
| Medtronic plc |
| Drive DeVilbiss Healthcare |
| CAIRE Inc. |
| AirSep Corporation |
| Nidek Medical Products Inc. |
| ResMed Inc. |
| Fisher & Paykel Healthcare |
| Others |
Pricing and Supply Chain Analysis
Bio-based fluoropolymer alternatives replacing PTFE feedstocks are redrawing supply geography toward European chemical clusters while compressing membrane pricing premiums previously anchored in legacy fluorinated polymer supply chains. REACH chemical compliance is accelerating this substitution dynamic as manufacturers absorb reformulation costs into procurement negotiations with medical device OEMs.
Pricing Analysis
FDA 510(k) dictates the pricing tier structure across oxygen filter procurement, separating cleared suppliers with existing master files from uncertified competitors locked out of medical device channels. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments. Cost compression in standard-grade HEPA media is intensifying because electrostatic precipitation substitutes are capturing industrial combustion pre-treatment volumes. Manufacturing plants represent the most price-sensitive buyer segment, while semiconductor fabs show minimal sensitivity due to ultrahigh-purity technical service requirements.
Supply Chain Analysis
China and Japan anchor fluoropolymer membrane production for precision oxygen filtration, with Germany's North Rhine-Westphalia industrial gas purification clusters emerging as a secondary hub. Raw material flows draw from concentrated Asian chemical feedstock suppliers for PTFE precursors, bio-based polymer alternatives, and activated carbon media. Single-source vulnerability in fluoropolymer feedstocks exposes filter manufacturers to input cost volatility during geopolitical friction. Distribution runs through direct technical service contracts for industrial accounts and e-commerce platforms for consumer-replaceable cartridges.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oxygen filter procurement is consolidating around platform-standardized filtration specifications that span hospital and homecare settings, with German homecare transition programs demonstrating how interoperability mandates create winner-take-most dynamics for certified suppliers.
For Market Incumbents: Secure backward integration into membrane material supply to defend margin position against PTFE raw material concentration risks. Prioritize certification investment in India's PLI-subsidized manufacturing zones before CDSCO regulatory pathways tighten further. Consolidate channel control through direct-to-patient e-commerce platforms that disintermediate traditional distributor networks. For New Entrants and Emerging Players: Lead with biocompatibility testing capabilities as the most penetrable service wedge, given ISO 18562 talent scarcity among established filter manufacturers. Target Maharashtra and Karnataka assembly hubs for nascent portable concentrator operations where local production requirements are still forming. Pursue go-to-market partnerships with durable medical equipment e-commerce platforms rather than capital equipment OEMs. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed respiratory therapy specialists that consolidated during prior homecare oxygen infrastructure buildouts. Long-term viability hinges on dual-use membrane technologies spanning medical and semiconductor applications rather than single-segment HEPA commodity exposure. Watch for REACH chemical compliance acceleration as the inflection indicator for bio-based fluoropolymer alternative valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Material Supply | Captive fluoropolymer production insulates margins from Asian feedstock volatility and REACH substitution mandates. |
| FDA Master File Expansion for Respiratory Accessories | Existing 510(k) clearances create procurement stickiness as notification timelines extend for new entrants. |
| India PLI Manufacturing Zone Establishment | Local production qualifies for CDSCO fast-track pathways while serving nascent portable concentrator assembly demand. |
| Direct-to-Patient E-commerce Channel Development | Digital platforms capture replacement cartridge subscriptions that bypass OEM service contract markups. |
| Bio-Based Fluoropolymer R&D Partnerships | REACH-compliant alternatives open procurement windows with German industrial gas purification clusters. |
Research Methodology
The analysis maps membrane, HEPA, activated carbon, and electrostatic filtration technologies, each validated through biomedical engineers, hospital GPO contracts managers, industrial gas procurement leads, and regulatory affairs specialists at medical device manufacturers. Primary fieldwork combined with secondary validation from FDA 510(k) filings, EPA National Emission Standards documentation, REACH chemical restriction updates, and ISO 18562 biocompatibility protocols. Bottom-up segment sizing triangulated against top-down market aggregates across product type, application, end user, and distribution channel dimensions.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation modeling incorporated filtration efficiency grade, certification tier, battery-operated versus stationary device compatibility, and regional regulatory cluster. CAGRs derived from trend extrapolation of portable concentrator replacement cycle acceleration, semiconductor fabrication capacity expansion, and homecare oxygen infrastructure buildout rates. Industry-specific inputs included EPA combustion purity mandate compliance timelines and FDA premarket notification backlog estimates.
The analysis sits within stated boundaries; outcomes outside sustained FDA 510(k) pathway stringency or REACH chemical restriction enforcement would require recalibration. Forecasts reflect assumptions regarding fluoropolymer feedstock availability, biocompatibility testing capacity expansion, and patient mobility preference durability. Specific risk factors that could revise projections include electrostatic precipitation technology substitution in industrial applications and geopolitical disruption of Asian chemical feedstock flows. Recalibration cycles align with material shifts in regulatory harmonization between medical device and industrial gas purity standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Quality Control Systems
Sustainable Air Filter Market
Air Quality Control Systems
Ozone Analyzer Market
Air Quality Control Systems
Global Mist Eliminator Market
Air Quality Control Systems
Air Pollution Control Equipment Market
Air Quality Control Systems
Singapore Air Purifier Market
Air Quality Control Systems
Air Quality Monitoring Software Market
Air Quality Control Systems
Asia-Pacific Indoor Air Purification Market
Air Quality Control Systems
Asia-Pacific Air Quality Control System Market
Air Quality Control Systems
Green Emissions Analyzers Market
Air Quality Control Systems
Desiccant Air Breather Market
Air Quality Control Systems
North America Industrial Air Quality Control Systems Market
Air Quality Control Systems
Anti-Pollution Toner Market
Air Quality Control Systems
Environmental Control System (ECS) Market
Air Quality Control Systems
Middle-East and Africa Industrial Air Quality Control Systems Market
Air Quality Control Systems
Nitrogen Oxide Control Systems Market
Air Quality Control Systems
Asia Pacific Air Filtration Market