
 Southeast Asia Air Purifier Market | 2026-2036
Southeast Asia Air Purifier Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia Air Purifier Market Analytics
ASEAN appliance efficiency harmonization is repositioning the cost-of-entry calculus for air purifier vendors across the region. Daikin Industries leverages its captive compressor manufacturing in Thailand to sustain margin advantage against tariff-exposed imports. Samsung Electronics anchors its regional position through integrated filter supply chains and dedicated R&D facilities in Vietnam. Xiaomi competes aggressively on channel control, dominating Southeast Asian e-commerce platforms with direct-to-consumer pricing that bypasses traditional distributor markups.
An air purifier is an electromechanical device engineered to remove particulate matter, volatile organic compounds, and biological contaminants from enclosed air volumes, typically employing fibrous media filtration with specified minimum efficiency reporting value ratings alongside activated carbon adsorption beds or ultraviolet germicidal irradiation chambers. Its primary commercial purpose spans protecting occupant respiratory health in healthcare, hospitality, education, and residential settings where ambient outdoor air quality falls below WHO interim targets. Portable units currently dominate unit shipments across Southeast Asia due to lower capital outlay and installation flexibility, though centralized systems command disproportionate margin pools in premium commercial developments. HEPA technology leads revenue contribution given its established efficacy certification and regulatory recognition, while UV-C integration represents the fastest-growing technology segment as post-pandemic institutional buyers prioritize pathogen neutralization capabilities.
Indonesia's Ministry of Industry enforces SNI marking requirements that restrict market access for uncertified electrical appliances, while Thailand's TISI standards mandate specific energy consumption disclosures that reshape product development priorities for manufacturers targeting Bangkok's commercial sector. Singapore's NEA environmental performance labeling creates transparent differentiation that steers procurement decisions in government buildings and healthcare facilities. Stakeholders must monitor how rapidly Philippines' Bureau of Product Standards extends mandatory certification to online-direct imports, as this single regulatory shift would force immediate channel restructuring for brands dependent on cross-border e-commerce fulfillment.
Market Dynamics
ASEAN harmonization of appliance efficiency standards is compressing margins for uncertified imports while rewarding localized assembly operations. This regulatory convergence is forcing vendors to restructure supply chains around captive manufacturing in Thailand and Vietnam or exit the market entirely.
Growth Catalysts
- HEPA-grade procurement mandates:Hospitals and healthcare clinics across Indonesia, Thailand, and Vietnam are accelerating unit purchases to meet stricter indoor air quality requirements. Regulatory pressure from health ministries is converting deferred maintenance budgets into immediate capital expenditure.
- Class-A office specification shifts:Building managers in Greater Jakarta now specify centralized filtration in new commercial developments. This specification creep is pulling demand from portable units toward duct-integrated systems with higher service contract attach rates.
- UV-C technology integration:Post-pandemic institutional buyers prioritize pathogen neutralization capabilities alongside particulate filtration. This dual-technology specification is expanding addressable unit value in healthcare and education verticals.
Market Restraints
- SNI marking compliance costs:Indonesia's Ministry of Industry enforces certification requirements that restrict market access for uncertified electrical appliances. Testing and localization expenses disproportionately burden smaller import-dependent vendors.
- Filter media supply concentration:High-efficiency fibrous media production clusters in East Asia, creating freight cost volatility and extended lead times for ASEAN-based assemblers. This geographic dependency constrains working capital flexibility.
- Activated carbon price volatility:Coconut shell feedstock prices fluctuate with agricultural yield cycles in Indonesia and the Philippines. This input cost instability compresses margin predictability for manufacturers relying on adsorption bed configurations.
Strategic Opportunities
- Philippines e-commerce certification gap:The Bureau of Product Standards has not yet extended mandatory certification to online-direct imports. Brands with cross-border fulfillment infrastructure can capture market share before regulatory closure forces channel restructuring.
- Smart home ecosystem convergence:Integration of air quality sensors with building management systems and consumer IoT platforms creates attach revenue streams. Technology vendors with API-ready hardware can capture recurring software and data service margins.
- Vietnam manufacturing incentives:Government industrial zone policies reward localized component production and final assembly. Vendors establishing captive compressor or filter supply in Vietnamese facilities gain tariff and logistics advantages against pure-import competitors.
Industry Challenges
- Multi-jurisdiction certification timelines:Parallel SNI, TISI, and NEA approval processes create product launch delays averaging 8-14 months. Vendors must maintain separate technical documentation and testing regimens for each ASEAN market.
- Filter replacement service infrastructure:After-market consumable fulfillment requires last-mile logistics capabilities that conflict with centralized e-commerce models. Brands must build localized technician networks or cede recurring revenue to third-party service aggregators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia Air Purifier Market |
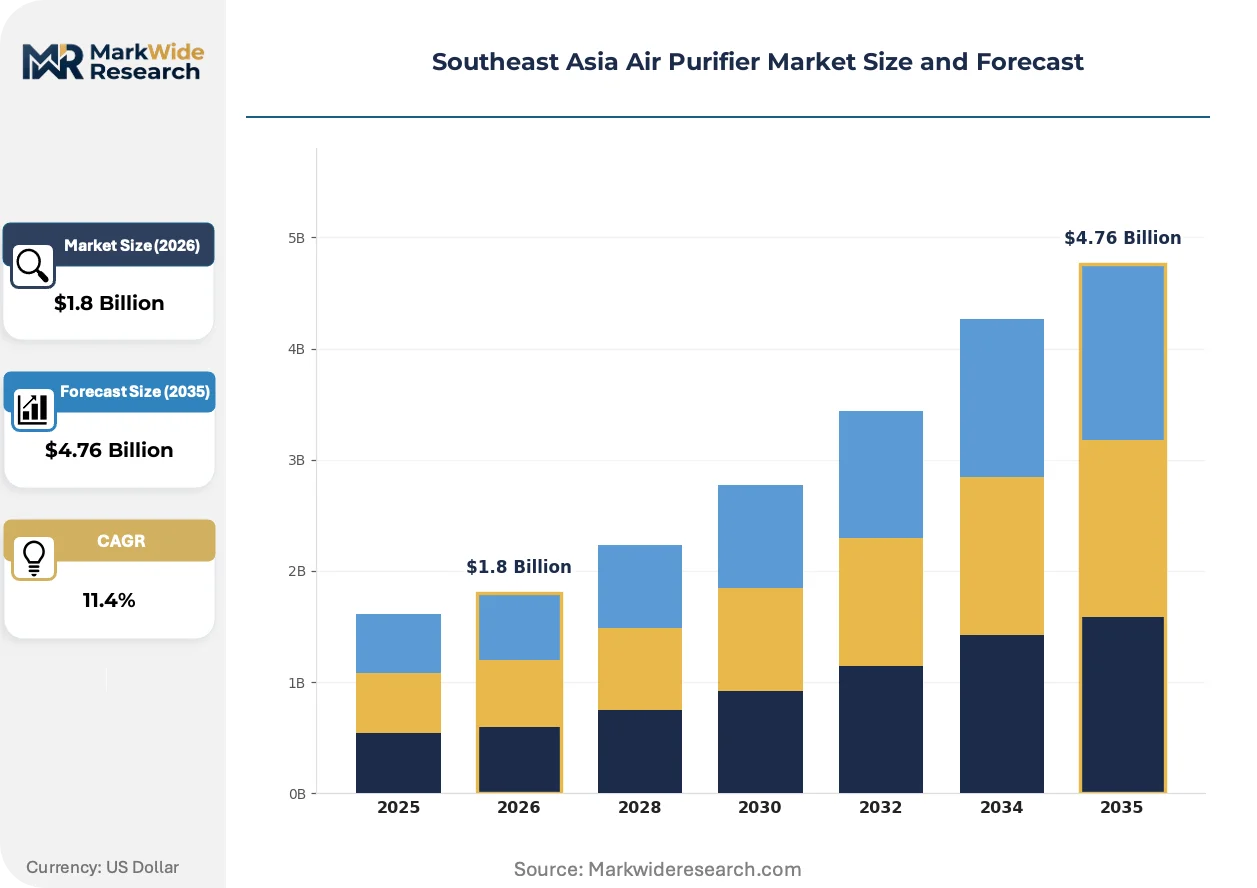
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Wall-Mounted, Centralized, In-Duct Technology: HEPA, Activated Carbon, UV-C, Ionizer End User: Residential, Commercial, Industrial, Institutional Distribution Channel: Online, Offline, Wholesalers, Direct Sales |
| Companies Covered | Dyson Ltd., Samsung Electronics Co., Ltd., Daikin Industries, Ltd., IQAir, Panasonic Corporation, Sharp Corporation, LG Electronics Inc., Xiaomi Corporation, Koninklijke Philips N.V., Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia Air Purifier Market Evolving Landscape
Electrochemical sensor miniaturization and AI-driven filter lifecycle prediction are converging to transform how building operators manage air quality infrastructure. These capabilities are shifting competitive differentiation from hardware specifications toward predictive service outcomes.
Photocatalytic oxidation paired with UV-C irradiation is rewriting efficacy benchmarks for volatile organic compound removal in healthcare settings. Bangkok's private hospital chains are specifying these dual-stage systems for oncology and immunocompromised patient wards. The technology is compressing demand for standalone carbon filtration units in premium institutional segments.
Singapore's NEA environmental performance labeling creates transparent differentiation that steers procurement decisions in government buildings and healthcare facilities. The mandatory disclosure regime is forcing manufacturers to redesign product lines around measurable efficiency tiers rather than marketing claims. Vendors without Tier 1 or Tier 2 ratings are losing access to public sector tenders and large corporate facility management contracts.
Direct-to-consumer platform dominance is fragmenting traditional distributor networks across Indonesia and Vietnam. Xiaomi's channel control through Lazada and Shopee storefronts is bypassing importer markups and compressing retail price bands. This disintermediation is most visible in Jakarta and Ho Chi Minh City's residential segments, where offline appliance retailers are consolidating or pivoting toward installation and maintenance services.
Southeast Asia Air Purifier Market Segmentation
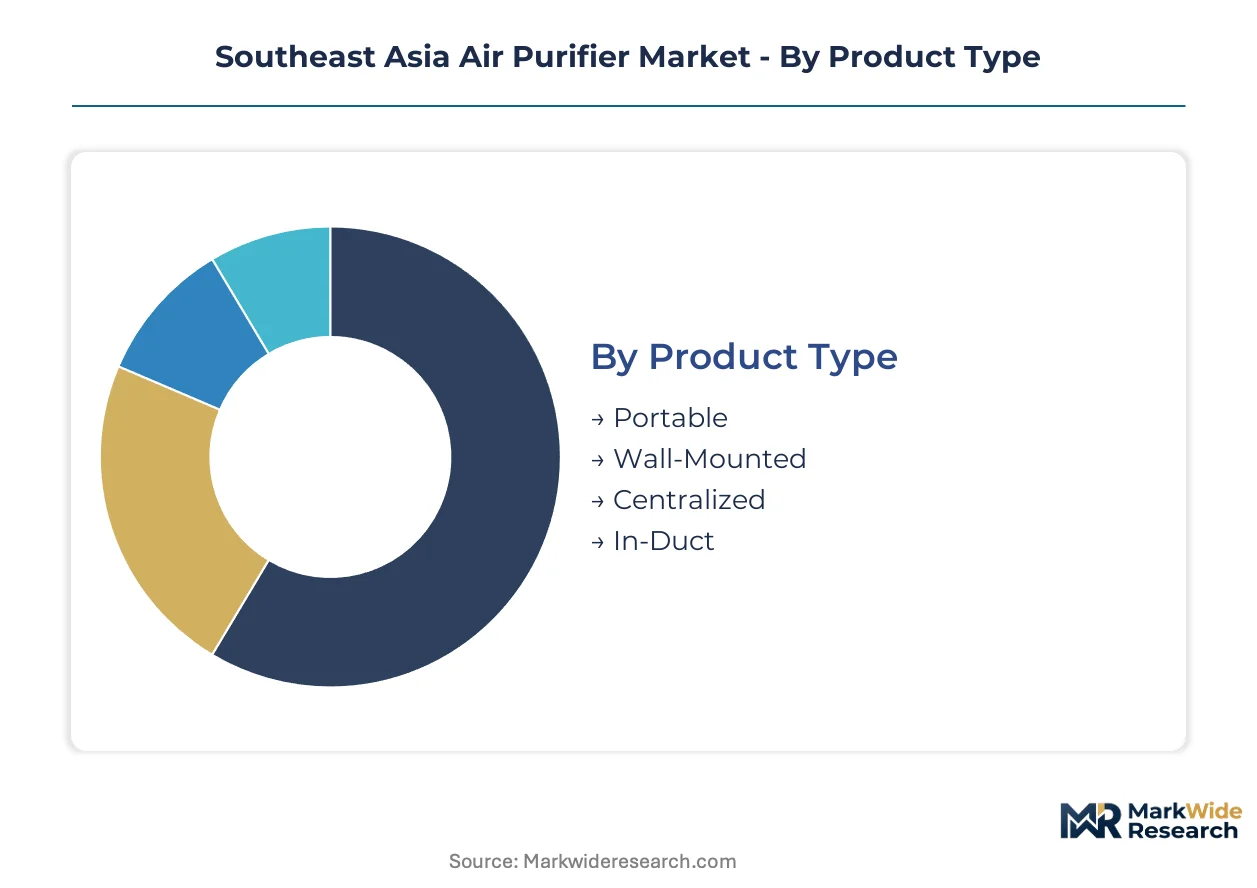
Product architecture and technology selection in Southeast Asia's air purifier market reflect divergent capital deployment strategies across installation permanence, filtration sophistication, and channel infrastructure. Segment boundaries increasingly blur as building managers specify hybrid configurations and manufacturers bundle hardware with predictive service contracts.
Product Type:
Capital requirements vary sharply across installation categories, with permanent infrastructure demanding substantially higher upfront engineering and commissioning expenditure than plug-and-play alternatives.
- Centralized:Duct-integrated systems engineered for whole-building air handling with multi-stage filtration banks and variable airflow control. Demand concentrates in Greater Jakarta's Class-A office developments where building managers specify centralized filtration to meet green building certification requirements and secure premium lease rates.
- Portable:Freestanding units with castor-mounted chassis and plug-in electrical connectivity requiring minimal installation labor. Procurement accelerates across Vietnam's healthcare clinics and Thailand's hospitality renovations where deferred maintenance budgets convert to immediate capital expenditure for HEPA-grade units.
- Wall-Mounted:Semi-permanent installations affixed to vertical surfaces with dedicated electrical drops and localized airflow distribution. These units dominate Singapore's compact residential layouts and Indonesia's mid-tier commercial retrofits where floor space constraints override centralized system economics.
- In-Duct:Retrofit modules inserted into existing HVAC infrastructure without full system replacement. Adoption clusters in Bangkok's aging commercial stock where owners seek compliance with TISI energy disclosure mandates without complete mechanical overhaul.
Portable units absorb the bulk of installed capacity across residential and light commercial applications; centralized systems are expanding most quickly in premium new construction verticals.
Technology:
Technology selection tracks end-use risk profiles, with healthcare and education buyers prioritizing pathogen neutralization while commercial operators optimize for particulate efficiency per unit energy consumed.
- HEPA:Fibrous media filtration achieving specified minimum efficiency reporting value ratings through dense pleated matrices with defined pressure drop characteristics. This technology anchors procurement in Indonesia's hospitals and Singapore's NEA Tier 1-rated government buildings where regulatory recognition drives specification.
- UV-C:Ultraviolet germicidal irradiation chambers delivering 254-nanometer wavelength exposure for pathogen DNA disruption. Integration accelerates fastest in Bangkok's private hospital chains and Ho Chi Minh City's oncology wards where post-pandemic institutional buyers mandate dual-technology specifications.
- Activated Carbon:Adsorption beds utilizing coconut shell-derived porous media for volatile organic compound capture. Feedstock price volatility from Indonesian and Philippine agricultural yield cycles constrains margin predictability for manufacturers configuring these units.
- Ionizer:Corona discharge or needle-point electrodes generating charged particles for electrostatic precipitation of airborne contaminants. Deployment concentrates in budget residential segments where first-cost sensitivity outweighs ongoing filter replacement economics.
HEPA filtration commands the largest revenue share given established certification protocols; UV-C integration is climbing the fastest as healthcare procurement mandates expand across ASEAN member states.
End User:
Customer archetypes distribute across risk tolerance, procurement sophistication, and total cost-of-ownership calculation horizons.
- Commercial:Property management entities, corporate facility operators, and hospitality groups with centralized procurement functions and multi-year service contract frameworks. This segment concentrates in Jakarta's central business district and Bangkok's Sukhumvit corridor where building automation integration drives specification.
- Institutional:Healthcare systems, educational institutions, and government agencies with mandated indoor air quality thresholds and public accountability requirements. Procurement accelerates across Indonesia's Ministry of Health facilities and Singapore's public healthcare clusters where regulatory pressure converts to immediate capital allocation.
- Residential:Individual households and multi-unit dwelling occupants purchasing through retail or direct-to-consumer channels. Xiaomi's platform dominance through Lazada and Shopee has fragmented traditional distributor networks in this segment.
- Industrial:Manufacturing facilities, warehousing operations, and logistics hubs with process-specific contamination control requirements. Demand remains concentrated in Vietnam's northern industrial zones and Thailand's Eastern Economic Corridor where electronics and food processing sectors maintain cleanroom-adjacent specifications.
Commercial end users absorb the bulk of centralized system deployment; institutional buyers are gaining share fastest as healthcare infrastructure investment accelerates across Indonesia, Thailand, and Vietnam.
Distribution Channel:
Channel economics reflect margin compression from platform disintermediation versus the service attach rates achievable through relationship-based sales motions.
- Online:E-commerce platforms and brand-direct storefronts with centralized fulfillment and algorithmic demand generation. Xiaomi's channel control through Southeast Asian platforms bypasses importer markups and compresses retail price bands in Jakarta and Ho Chi Minh City residential segments.
- Offline:Appliance retailers, specialty HVAC dealers, and building materials showrooms with physical product demonstration and immediate inventory availability. These channels retain strength in centralized system specification where technical consultation and installation coordination justify margin premiums.
- Wholesalers:Regional distributors aggregating volume from multiple manufacturers for resale to installer networks and smaller retailers. Indonesia's archipelago geography and Philippines' island dispersion sustain wholesaler relevance despite platform encroachment.
- Direct Sales:Manufacturer-employed account executives and specification engineers calling on project developers, facility managers, and institutional procurement committees. This channel dominates premium commercial and healthcare verticals where long sales cycles and custom engineering requirements reward dedicated technical resources.
Online channels absorb the bulk of portable unit volume in residential segments; direct sales is expanding most quickly in institutional and premium commercial verticals where specification influence determines competitive outcomes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand's Eastern Economic Corridor tax incentives and Vietnam's industrial zone policies are concentrating manufacturing investment, reshaping competitive positioning across ASEAN member states.
Indonesia
Jakarta's commercial real estate boom and healthcare infrastructure expansion drive centralized system procurement. The Ministry of Industry enforces SNI marking requirements that restrict market access for uncertified electrical appliances. Greater Jakarta's Class-A office developments now specify duct-integrated filtration as standard.
Thailand
Bangkok's private hospital chains and hospitality renovations accelerate HEPA-grade unit purchases. TISI standards mandate specific energy consumption disclosures that reshape product development priorities for manufacturers. The Eastern Economic Corridor hosts captive compressor manufacturing serving regional export markets.
Vietnam
Ho Chi Minh City's oncology wards and northern industrial electronics zones sustain dual-technology demand. Government industrial zone policies reward localized component production and final assembly. Da Nang's emerging healthcare infrastructure attracts specification-focused vendor investment.
Singapore
NEA environmental performance labeling steers procurement in government buildings and healthcare facilities. The mandatory disclosure regime forces manufacturers to redesign product lines around measurable efficiency tiers. Compact residential layouts sustain wall-mounted unit preference.
Philippines
Manila's archipelago geography sustains wholesaler relevance despite platform encroachment. The Bureau of Product Standards has not yet extended mandatory certification to online-direct imports. Cebu and Davao medical facilities accelerate procurement ahead of anticipated regulatory closure.
Southeast Asia Air Purifier Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market segments. The vendor base distributes across integrated HVAC multinationals, consumer electronics platforms, and dedicated air quality specialists. Three archetypes dominate: diversified industrial conglomerates with captive component supply, platform-native consumer electronics brands with direct-to-consumer channel control, and premium specialists with specification-engineering capabilities. Capacity localization and certification compliance represent the dominant competitive moves reshaping market access.
Among diversified industrial conglomerates, Daikin Industries and Samsung Electronics exemplify archetypes leveraging integrated manufacturing and R&D infrastructure. Daikin Industries occupies a position anchored by captive compressor production in Thailand, while Samsung Electronics sits within the tier benefiting from dedicated regional R&D facilities. Xiaomi Corporation represents the platform-native vector dominating Southeast Asian e-commerce channels. These three entities collectively illustrate how manufacturing depth, supply chain integration, and channel architecture determine competitive outcomes across institutional and consumer segments.
| Leading Market Players |
|---|
| Dyson Ltd. |
| Samsung Electronics Co., Ltd. |
| Daikin Industries, Ltd. |
| IQAir |
| Panasonic Corporation |
| Sharp Corporation |
| LG Electronics Inc. |
| Xiaomi Corporation |
| Koninklijke Philips N.V. |
| Others |
Value Network & Pricing Analysis
Coconut shell feedstock price volatility in Indonesia and the Philippines cascades through activated carbon adsorption bed configurations into three distinct pricing tiers across Southeast Asian air purifier markets. Procurement officers in Jakarta's Class-A offices and Bangkok's private hospital chains face compressed margins when agricultural yield cycles spike input costs for manufacturers dependent on adsorption-based VOC removal systems.
Pricing Analysis
Lead-time premiums compress standard pricing bands for HEPA-grade units sourced through regional e-commerce platforms versus project-based procurement for centralized duct-integrated systems. Pricing stratifies across NEA Tier 1-certified premium tiers, TISI-compliant standard tiers, and uncertified economy imports vulnerable to SNI enforcement gaps. Cost compression in the economy tier intensifies because cross-border fulfillment models bypass traditional importer markups. Residential buyers through Lazada and Shopee storefronts exhibit highest price sensitivity, while institutional procurement committees in Singapore's public healthcare clusters prioritize certification grade over unit cost.
Supply Chain Analysis
Workforce availability constraints in Thailand's Eastern Economic Corridor and Vietnam's northern industrial zones limit expansion velocity for captive compressor and filter media assembly operations. Manufacturing gravity centers on Thailand for electromechanical components, Vietnam for final assembly and R&D facilities, and China for high-efficiency fibrous media production. Supply chain risk hinges on single-source vulnerability for HEPA-grade pleated matrices sourced from East Asian production clusters. Distribution runs through platform-direct fulfillment for portable residential units and specification-engineer networks for institutional and premium commercial verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
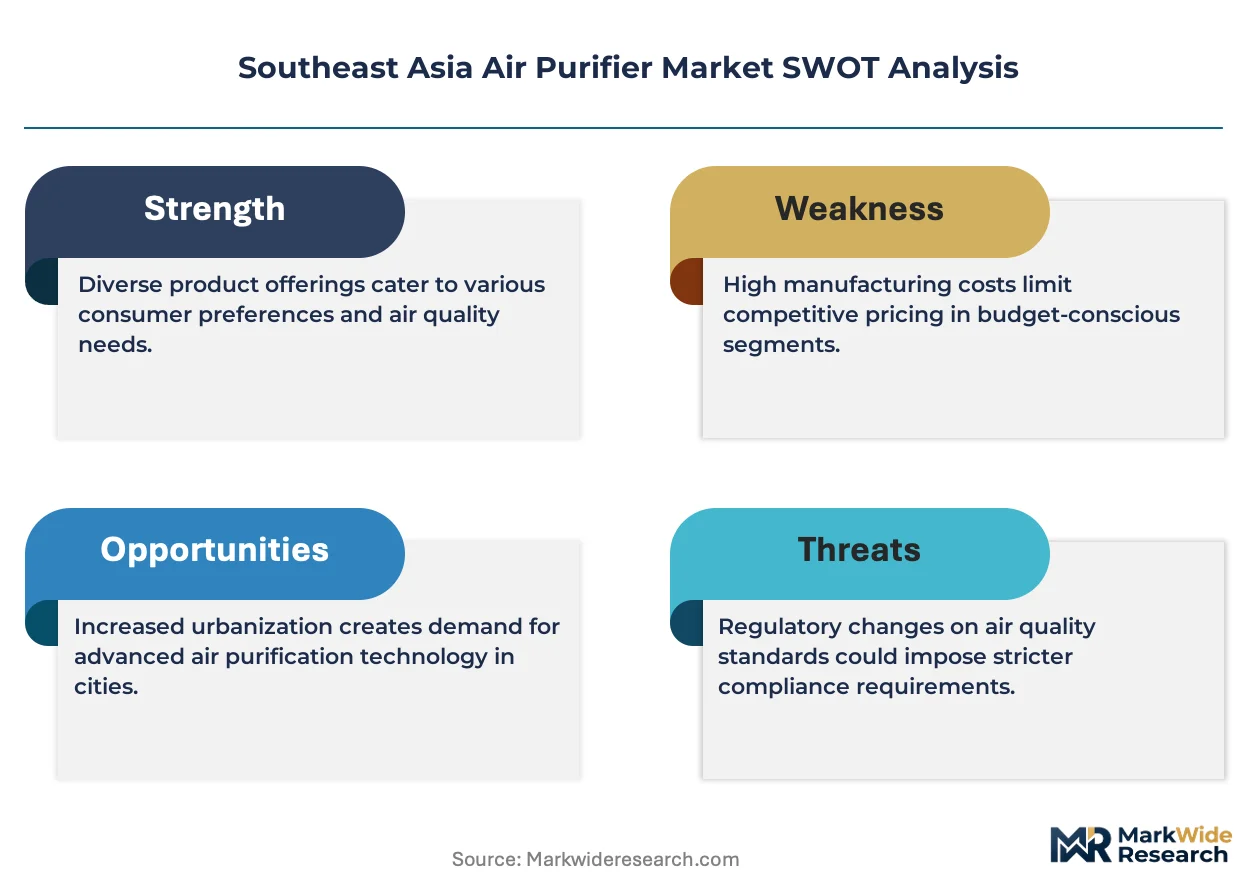
Southeast Asia's air purifier market operates as a cost-of-compliance story where Indonesia's SNI marking requirements and Singapore's NEA environmental performance labeling construct regulatory moats favoring certified incumbents over uncertified import-dependent competitors.
For Market Incumbents: Acquire captive filter media production capacity in Vietnamese industrial zones to insulate margin structures from East Asian supply concentration risks. Consolidate specification-engineer relationships with Bangkok's private hospital chains and Jakarta's Class-A office developers before regulatory harmonization closes certification gaps. Threat substitution from UV-C photocatalytic oxidation systems demands accelerated R&D investment in dual-technology integration. For New Entrants and Emerging Players: Smart home ecosystem integration with API-ready air quality sensors represents the most penetrable technology wedge for residential segments in Ho Chi Minh City and Manila where platform dominance has fragmented traditional distributor networks. Target the Philippines e-commerce certification gap before the Bureau of Product Standards extends mandatory SNI-equivalent requirements to online-direct imports. Go-to-market execution should leverage cross-border fulfillment infrastructure with predictive filter replacement subscription attach. For Investors and Strategic Acquirers: Distressed-cycle entries favor component-specialist manufacturers with established Vietnamese assembly operations and NEA Tier 1 or Tier 2 ratings during periods of activated carbon feedstock price spikes. Long-term viability over a multi-year horizon rests on regulatory compliance durability rather than channel scale alone. Monitor Philippines Bureau of Product Standards regulatory closure timing as the critical inflection signal for platform-dependent brand valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Filter Media Production | Backward integration into Vietnamese fibrous media assembly reduces East Asian supply dependency and tariff exposure. |
| NEA Tier 1 Certification Investment | Singapore's mandatory disclosure regime steers public sector procurement toward measurable efficiency tiers. |
| Smart Home Platform Integration | API-ready air quality sensors unlock recurring software revenue in Jakarta and Ho Chi Minh City residential segments. |
| Philippines E-commerce Market Entry | Pre-regulatory closure window enables cross-border share capture before mandatory certification forces channel restructuring. |
| Dual-Technology R&D Partnership | Photocatalytic oxidation paired with UV-C irradiation rewrites efficacy benchmarks for Bangkok oncology ward specifications. |
Research Methodology
Independent corroboration across facility engineering directors, hospital procurement committees, e-commerce platform category managers, and HVAC specification consultants underwrites the qualitative findings in this study. Primary interviews with biomedical engineers in Singapore's public healthcare clusters, maintenance directors in Jakarta's central business district, and aftermarket service heads in Thailand's Eastern Economic Corridor combined with secondary validation from ASEAN customs records, NEA environmental performance databases, and SNI certification registries. Bottom-up unit shipment estimates triangulate against top-down addressable market calculations across product architecture and technology segments.
Comparable-period anchoring to historical procurement cycles in Indonesia's Ministry of Health facilities and Thailand's private hospital renovation waves structured the projection horizon. The analytical framework models segmentation across installation permanence, filtration technology sophistication, end-user risk profiles, and distribution channel economics. CAGRs derive from installed base growth rates, replacement cycle compression, and specification shift elasticities. Forecast inputs incorporate regulatory harmonization timelines for appliance efficiency standards and coconut shell feedstock agricultural yield cycle patterns.
Several conditions sit outside the modeled scope, including abrupt regulatory reversals in Philippines e-commerce certification policy, sustained activated carbon price spikes exceeding historical volatility bands, and supply chain disruptions from East Asian fibrous media production constraints. Forecasts reflect assumptions about ASEAN harmonization continuity and institutional procurement mandate enforcement. Material deviation in SNI marking compliance timelines or NEA labeling tier revisions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Quality Control Systems
Asia Pacific Air Filtration Market
Air Quality Control Systems
Air Pollution Control Systems Market
Air Quality Control Systems
Asia-Pacific Indoor Air Purification Market
Air Quality Control Systems
Europe Nitrogen Oxide Control Systems Market
Air Quality Control Systems
Nitrogen Oxide Control Systems Market
Air Quality Control Systems
UV Air Purifiers Market
Air Quality Control Systems
United States Pollution Mask Market
Air Quality Control Systems
Ozone Analyzer Market
Air Quality Control Systems
Environment Controllers Market
Air Quality Control Systems
Air Scrubber Market
Air Quality Control Systems
Green Emissions Analyzers Market
Air Quality Control Systems
Oxygen Filters Market
Air Quality Control Systems
Industrial Air Quality Control Systems Market
Air Quality Control Systems
Air Pollution Control Equipment Market
Air Quality Control Systems
Sustainable Air Filter Market
Air Quality Control Systems
Anti-Pollution Mask Market