
 Europe Industrial Air Quality Control Systems Market | 2026-2036
Europe Industrial Air Quality Control Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Industrial Air Quality Control Systems Market Foresight
Electrification of filter media monitoring and predictive maintenance architectures is tilting procurement criteria toward digitally integrated stack platforms. Siemens AG leverages its automation portfolio to anchor premium positioning in sensor-embedded fume extraction systems across German automotive foundries. GEA Group Aktiengesellschaft sustains engineering intensity in wet scrubber variants for chemical processing clusters in the Netherlands and Belgium. John Cockerill Group dominates heavy fabrication capabilities for custom electrostatic precipitator housings serving Wallonian steel mills.
Industrial air quality control systems encompass engineered assemblies of filtration, absorption, and electrostatic separation equipment designed to capture particulate matter, acid gases, and volatile organic compounds from exhaust streams, typically operating at temperatures between 120°C and 350°C with pressure drops of 500–2,500 Pa depending on configuration. These installations serve the primary purpose of ensuring occupational safety within production halls while guaranteeing stack emissions remain below permit thresholds set by environmental authorities. Electrostatic precipitator technology occupies mature installed bases across Central European coal-fired power plants where long asset life cycles constrain replacement frequency. Bag filter systems lead upgrade revenue pools as manufacturing facilities pursue mercury and fine particulate capture beyond legacy fabric specifications. Activated carbon filter segments compete for incineration and chemical solvent recovery applications where dioxin and benzene removal drive specification intensity.
The EU Industrial Emissions Directive and associated Best Available Techniques reference documents mandate continuous emissions monitoring and periodic equipment upgrades across covered sectors, directly shaping capital expenditure timing for regulated installations. ECHA's REACH restrictions on filter material chemistries and the F-Gas Regulation's phase-down of certain fluorinated compounds constrain material selection freedom for system designers and operators. Stakeholders must monitor emerging BAT conclusion revisions and carbon border adjustment mechanism compliance requirements to anticipate retrofit waves and technology substitution patterns.
Market Dynamics
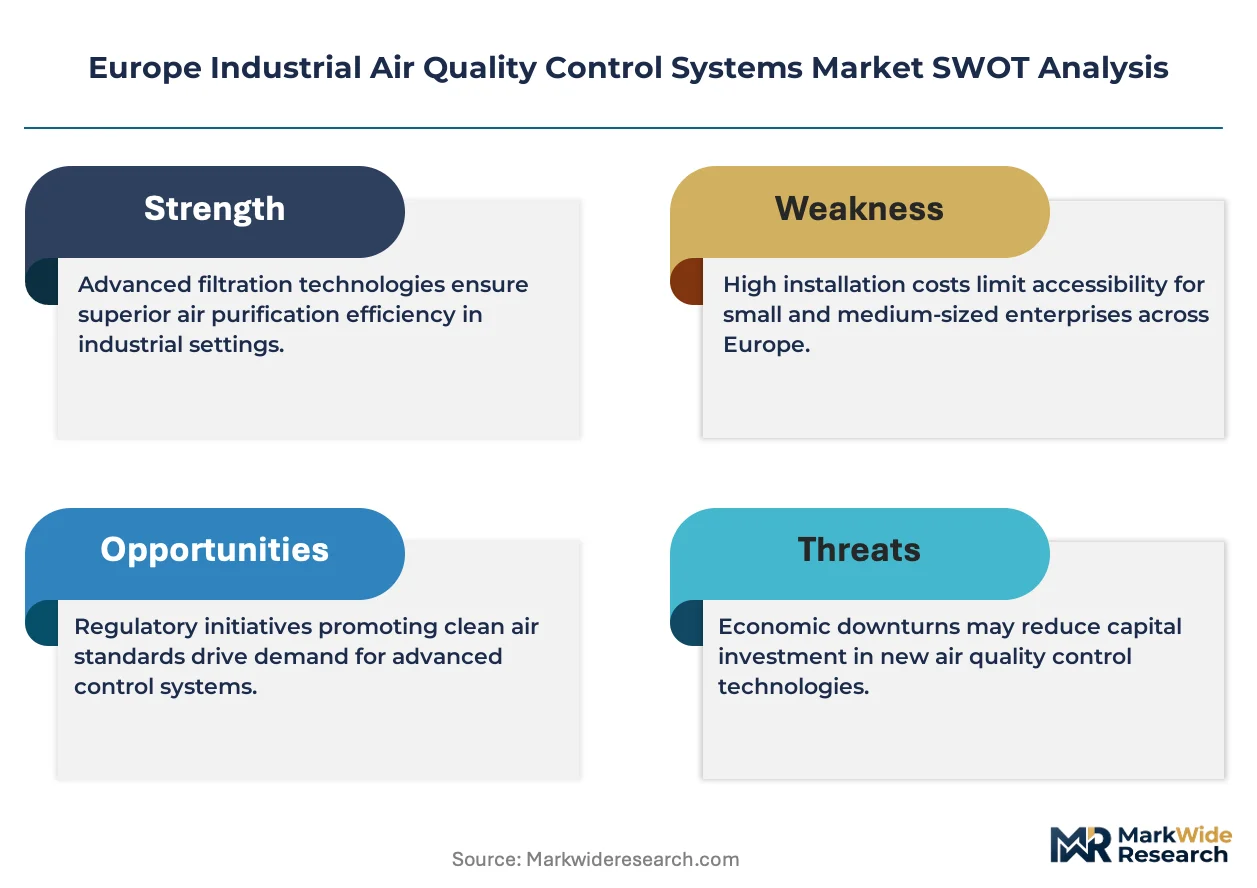
EU Industrial Emissions Directive enforcement timelines are compressing capital expenditure cycles across Central European heavy manufacturing, forcing simultaneous scrubber upgrades and continuous monitoring retrofits that strain maintenance budgets and engineering capacity.
Growth Catalysts
- Mercury capture mandates:Tightened BAT reference documents for waste incineration and cement kilns are mandating activated carbon injection systems and bag filter upgrades across Polish and Romanian facilities.
- Digital stack platforms:Predictive maintenance architectures embedded in fume extraction systems are reducing unplanned downtime for German automotive foundries and Belgian chemical processors.
- Southeastern European power corridors:Electrostatic precipitator replacement cycles are accelerating in Bulgarian and Greek coal-fired generation assets approaching end-of-design-life.
Market Restraints
- Filter media chemistry constraints:ECHA REACH restrictions on certain synthetic fiber treatments are limiting material selection freedom for high-temperature bag filter specifications above 250°C.
- F-Gas phase-down friction:The EU F-Gas Regulation's hydrofluorocarbon quota reductions are complicating refrigerant-based condensing scrubber designs for volatile organic compound recovery.
- Steel fabrication concentration:Custom electrostatic precipitator housing supply concentrates in Wallonian and northern Italian heavy fabrication clusters, creating delivery bottlenecks for large-diameter installations.
Strategic Opportunities
- Carbon border adjustment readiness:EU CBAM compliance documentation requirements are creating demand for certified emissions monitoring integration in Czech and Slovak steel and cement installations.
- Wet scrubber-carbon capture hybrids:Convergence of acid gas absorption and amine-based carbon capture is opening retrofit opportunities at Netherlands and Belgium chemical processing clusters.
- Service unbundling:Aftermarket filter media supply and remote diagnostics are decoupling from original equipment contracts, enabling independent service providers to penetrate Spanish and Portuguese industrial maintenance markets.
Industry Challenges
- Commissioning timeline compression:Synchronized BAT conclusion deadlines and permit renewal cycles are overwhelming qualified installation and commissioning engineering teams across German heavy industry.
- Legacy control system integration:Digital sensor retrofits into 1990s-era distributed control architectures at Polish and Hungarian power plants require custom protocol translation and extended validation periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Industrial Air Quality Control Systems Market |
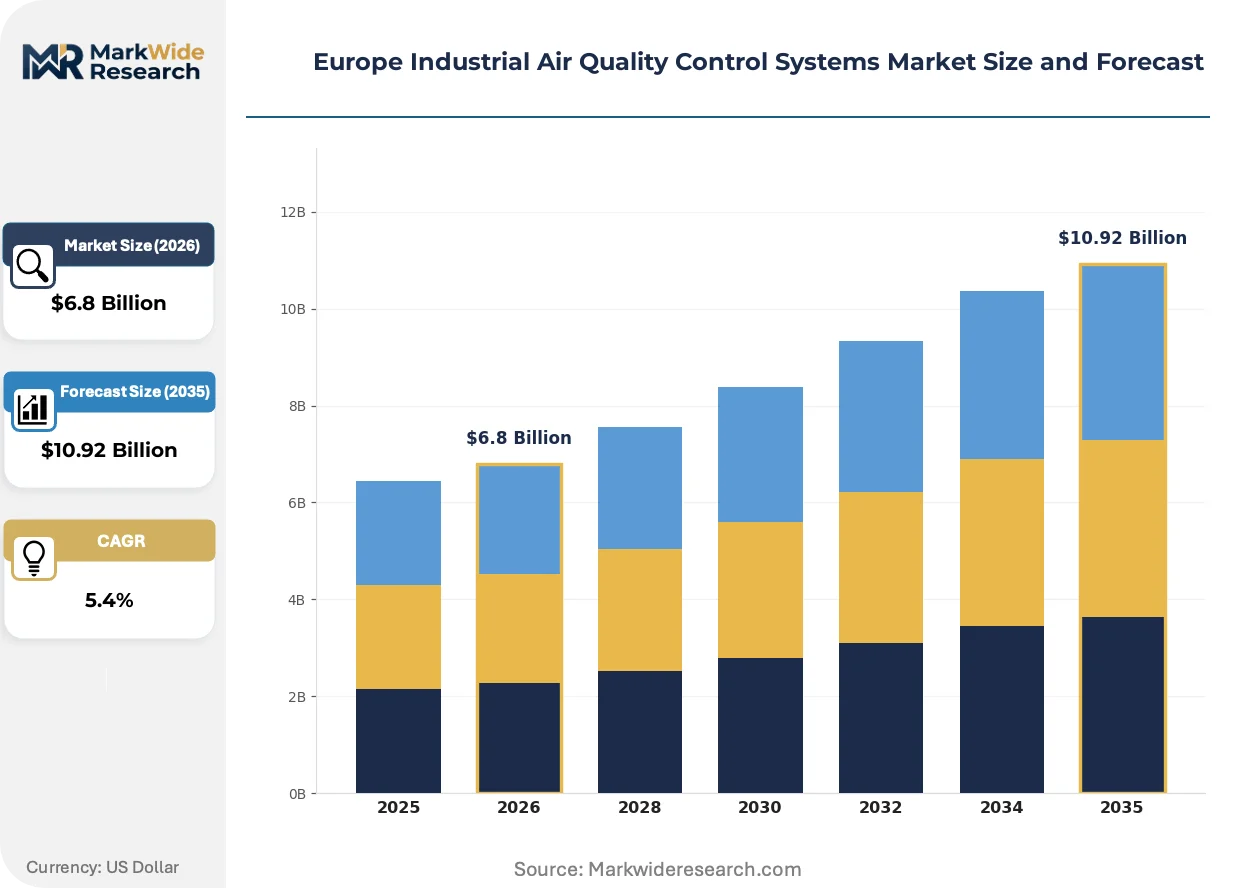
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Electrostatic Precipitators, Bag Filters, Activated Carbon Filters, Ionizers End User: Manufacturing Facilities, Power Plants, Chemical Processing, Food Processing Application: Fume Extraction, Dust Control, Gas Treatment, Indoor Air Quality Component: Control Panels, Sensors, Ductwork, Filter Media |
| Companies Covered | John Cockerill Group, Operational Group Limited, Munstermann GmbH & Co KG, Alfa Laval AB, GEA Group Aktiengesellschaft, Fives Group, John Wood Group PLC, Siemens AG, Andritz AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Industrial Air Quality Control Systems Market Shifts & Advancements
Electrification of monitoring architectures and chemistry-aware filter design are converging to redefine equipment specification criteria, shifting procurement emphasis from standalone capture efficiency to integrated data platforms and material compliance documentation.
High-temperature ceramic fiber filter media is migrating from pilot installations to mainstream specification for cement kiln exhaust streams above 300°C. German and Polish cement manufacturers are adopting these materials to eliminate pre-cooling stages and reduce plant footprint. This migration is compressing demand for traditional aramid and fiberglass blends in new-build applications while creating aftermarket service complexity for mixed installed bases.
The EU F-Gas Regulation's accelerated hydrofluorocarbon quota phase-down is forcing refrigerant substitution in condensing scrubber systems for volatile organic compound recovery. Chemical processors in Belgium and the Netherlands are retrofitting absorption-based alternatives or switching to cryogenic condensation. Small-batch pharmaceutical and specialty chemical installations face disproportionate compliance burden due to limited scale economies for alternative technology adoption.
Buyers are consolidating filter media procurement under multi-year framework agreements with certified suppliers capable of documenting REACH compliance and carbon footprint data. Dutch chemical clusters and German automotive supply chains are leading this consolidation, displacing spot purchasing through distributor networks. This concentration is marginalizing smaller media converters lacking in-house testing and certification capabilities.
Europe Industrial Air Quality Control Systems Market Segmentation
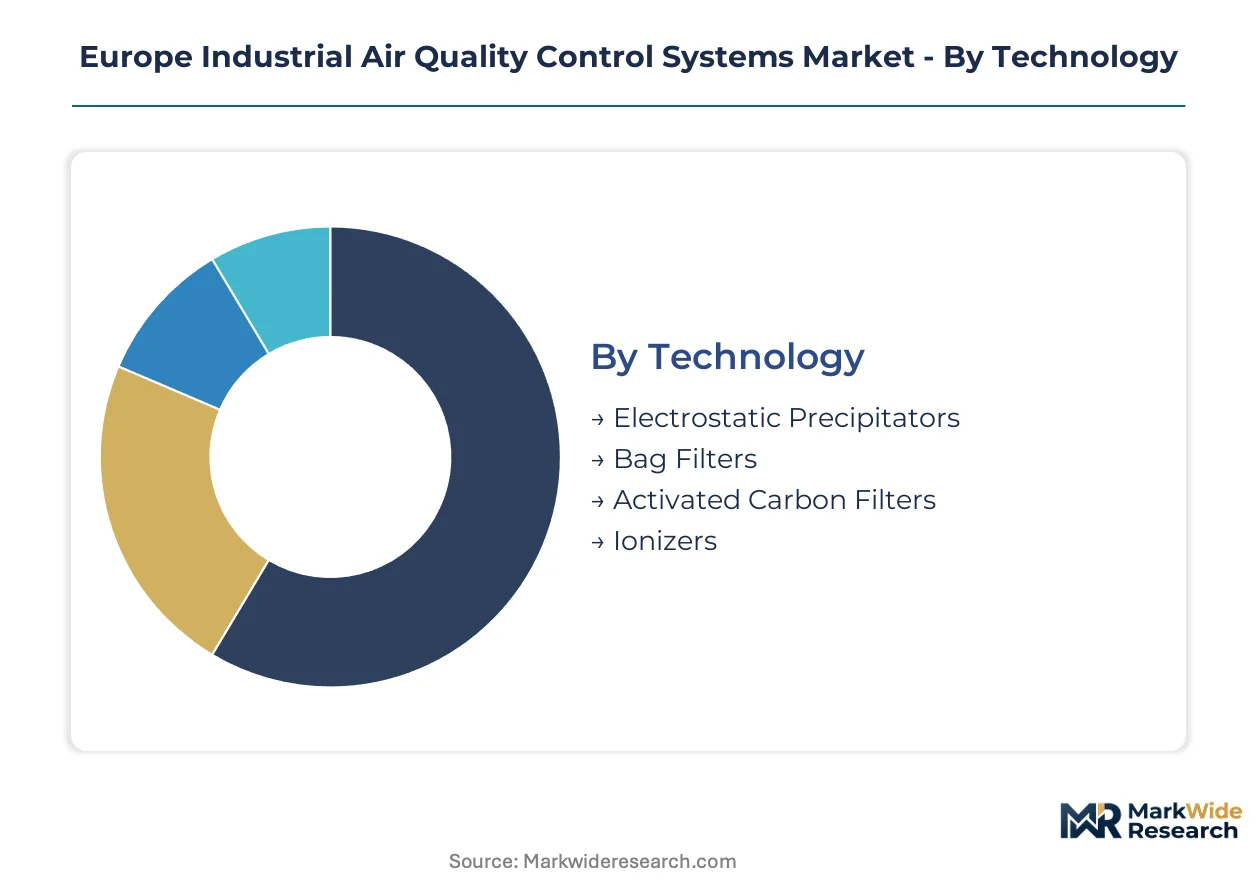
Industrial air quality control systems serve distinct operational regimes across temperature ranges, particulate loads, and chemical compositions. Procurement patterns diverge sharply between heavy manufacturing exhaust treatment and precision indoor environments. Each segment category reflects different engineering priorities, regulatory exposure, and lifecycle economics.
Technology:
Use cases span from high-temperature particulate capture in coal combustion to low-concentration VOC recovery in solvent handling, with each technology matching specific exhaust stream characteristics and contaminant profiles.
- Electrostatic Precipitators:These systems apply high-voltage electrostatic fields to ionize and collect particulate matter across large gas volumes. Bulgarian and Greek coal-fired power corridors are accelerating replacement cycles as assets approach end-of-design-life, with procurement concentrated in southeastern European generation clusters facing EU Industrial Emissions Directive compliance deadlines.
- Bag Filters:Fabric-based filtration assemblies capture fine particulates and mercury across variable temperature ranges. German and Polish cement manufacturers dominate upgrade demand as tightened BAT reference documents mandate activated carbon injection compatibility and enhanced fine particulate capture beyond legacy fabric specifications.
- Activated Carbon Filters:Adsorption systems target dioxins, benzene, and mercury in incineration and chemical solvent recovery applications. Waste-to-energy facilities in Poland and Romania are retrofitting these units under tightened mercury capture mandates.
- Ionizers:Electrostatic precipitation variants for indoor air quality management in production halls and cleanroom environments. Food processing installations in Belgium and the Netherlands are specifying these for occupational safety compliance.
Established volume favors Electrostatic Precipitators; emerging adoption favors Bag Filters.
End User:
Capital intensity and regulatory scrutiny vary dramatically across end-use sectors, with power generation and heavy manufacturing bearing the most stringent continuous monitoring obligations.
- Manufacturing Facilities:Automotive foundries, steel mills, and cement plants generate high-particulate exhaust streams requiring robust fume extraction. German automotive supply chains are embedding predictive maintenance architectures into procurement specifications.
- Power Plants:Coal and biomass combustion drives demand for high-capacity particulate and acid gas control. Southeastern European assets are entering replacement cycles.
- Chemical Processing:Solvent recovery and acid gas absorption dominate application profiles. Netherlands and Belgium clusters are piloting wet scrubber-carbon capture hybrid configurations.
- Food Processing:Indoor air quality and odor control priorities shape specifications. Installations focus on occupational safety within production halls rather than stack emissions.
Power Plants anchor replacement demand; Chemical Processing offers the steepest expansion trajectory for integrated digital platforms.
Application:
Operational requirements diverge between source capture at process equipment and ambient control within facility envelopes, with distinct sensor and automation architectures for each.
- Fume Extraction:Localized capture systems at welding stations, melting furnaces, and chemical reactors. German automotive foundries are specifying sensor-embedded platforms with predictive maintenance capabilities.
- Dust Control:Bulk material handling and grinding operations generate high particulate loads requiring heavy-duty filtration. Cement and mining applications dominate this segment.
- Gas Treatment:Acid gas absorption and VOC recovery through scrubbers and adsorption systems. Chemical processors in Belgium and the Netherlands are retrofitting refrigerant-based designs due to F-Gas Regulation constraints.
- Indoor Air Quality:Occupational safety-focused systems maintaining production hall environments. Food processing and pharmaceutical installations prioritize these specifications.
Dust Control commands the largest installed base; Gas Treatment is climbing the fastest on carbon capture convergence.
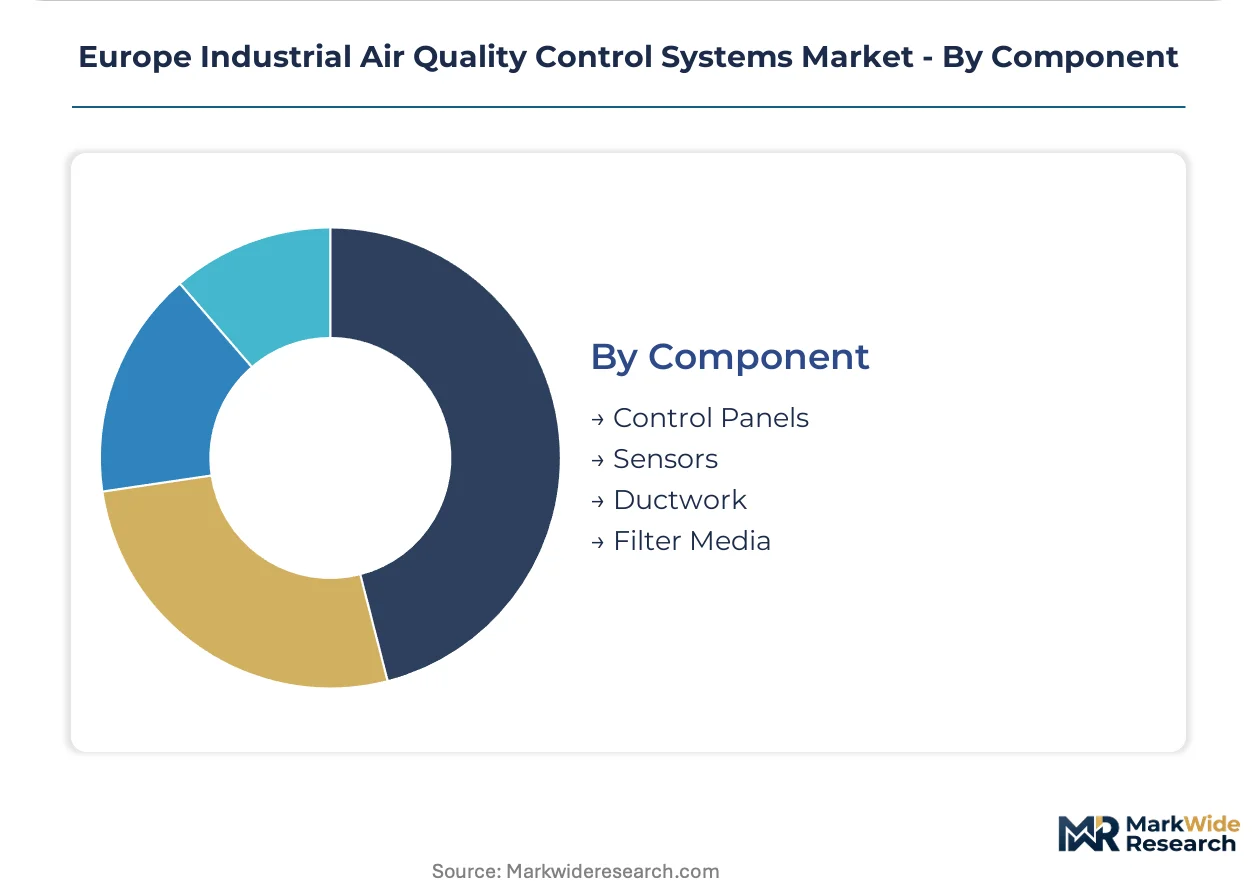
Component:
Procurement concentration is shifting from original equipment packages toward aftermarket and digital components as maintenance strategies unbundle from capital contracts.
- Control Panels:Distributed control architectures managing fan speeds, damper positions, and cleaning cycles. Polish and Hungarian power plants face integration challenges with 1990s-era legacy systems.
- Sensors:Particulate, gas, and pressure monitoring devices enabling continuous emissions documentation. EU CBAM compliance requirements are driving certified monitoring integration in Czech and Slovak steel installations.
- Ductwork:Exhaust collection and transport infrastructure customized to facility layouts. Heavy fabrication capacity constraints in Wallonia and northern Italy are creating delivery bottlenecks.
- Filter Media:Replacement fabrics, ceramic elements, and activated carbon beds. Dutch chemical clusters and German automotive supply chains are consolidating procurement under multi-year framework agreements with REACH-certified suppliers.
Filter Media generates the most recurring revenue; Sensors are gaining share fastest on digital platform integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer concentration among German automotive foundries and Polish cement manufacturers drives procurement patterns across the region, with regulatory enforcement timelines compressing capital expenditure cycles in heavy manufacturing corridors.
Germany
Automotive supply chains and steel mills dominate equipment demand as Siemens AG anchors sensor-embedded fume extraction specifications. The EU Industrial Emissions Directive mandates continuous monitoring retrofits across Baden-Württemberg and North Rhine-Westphalia manufacturing clusters. Bavarian foundries are embedding predictive maintenance architectures into procurement criteria for new stack platforms.
Poland
Cement kiln expansions and waste-to-energy retrofits drive activated carbon injection system demand under tightened mercury capture mandates. ECHA REACH restrictions on filter media chemistries constrain material selection for high-temperature specifications above 250°C. Silesian heavy industry corridors are accelerating bag filter upgrade cycles to meet BAT reference document deadlines.
Netherlands
Chemical processing clusters in Rotterdam and Antwerp-adjacent zones pilot wet scrubber-carbon capture hybrid configurations. The EU F-Gas Regulation's hydrofluorocarbon quota phase-down forces refrigerant substitution in condensing scrubber designs for volatile organic compound recovery. Dutch chemical buyers consolidate filter media procurement under multi-year framework agreements with REACH-certified suppliers.
Belgium
Wallonian steel mills rely on John Cockerill Group fabrication capabilities for custom electrostatic precipitator housings. ECHA's evolving restrictions on synthetic fiber treatments limit specification freedom for bag filter applications in high-temperature chemical processing. GEA Group Aktiengesellschaft sustains engineering intensity in wet scrubber variants serving Antwerp chemical corridors.
Bulgaria and Greece
Southeastern European coal-fired power assets are entering replacement cycles as electrostatic precipitator installations approach end-of-design-life. EU Industrial Emissions Directive compliance deadlines accelerate procurement in generation clusters lacking recent upgrade investment. Bulgarian power operators face commissioning timeline compression as synchronized BAT conclusion deadlines strain qualified engineering capacity.
Europe Industrial Air Quality Control Systems Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement channels. The vendor base spans automation-anchored conglomerates, heavy fabrication specialists, and regional engineering houses. Three archetypes dominate: integrated automation providers leveraging sensor portfolios, wet scrubber engineering specialists with chemical process expertise, and custom fabrication houses serving steel mill precipitator requirements. Competitive moves concentrate on digital platform integration and aftermarket service unbundling.
Within the integrated automation tier, Siemens AG occupies a position exemplifying sensor-embedded system anchoring. GEA Group Aktiengesellschaft represents the wet scrubber engineering specialist archetype with sustained presence in chemical processing clusters. John Cockerill Group sits within the custom heavy fabrication tier, serving precipitator housing demand from Wallonian steel corridors.
| Leading Market Players |
|---|
| John Cockerill Group |
| Operational Group Limited |
| Munstermann GmbH & Co KG |
| Alfa Laval AB |
| GEA Group Aktiengesellschaft |
| Fives Group |
| John Wood Group PLC |
| Siemens AG |
| Andritz AG |
| Others |
Supply & Pricing Matrix
Wallonian heavy fabrication clusters anchor electrostatic precipitator housing supply, concentrating margin capture with steel mill proximity and constraining pricing flexibility for Bulgarian and Greek power operators sourcing large-diameter custom installations.
Pricing Analysis
Cost-plus contracts with steel indexation dominate electrostatic precipitator procurement, insulating Wallonian fabricators from raw material volatility while exposing downstream buyers to alloy surcharge pass-throughs. Three-tier pricing structure across sensor-embedded premium platforms, standard mechanical assemblies, and economy retrofit configurations reflects certification grade and digital integration intensity. Pricing pressure stems from REACH compliance documentation burdens compressing margins for smaller filter media converters lacking in-house testing capabilities. Chemical processors in Belgium and the Netherlands exhibit lowest price sensitivity due to F-Gas Regulation compliance deadlines, while Spanish and Portuguese maintenance markets show highest sensitivity as independent service providers unbundle aftermarket supply.
Supply Chain Analysis
High-temperature ceramic fiber feedstock draws from German and Polish specialty refractory producers, with activated carbon media sourcing concentrated in Belgian and Dutch chemical processing corridors. Synthetic fiber treatments for bag filters above 250°C hinge on ECHA REACH compliant chemistries, while sensor hardware rests on German automation component supply. Single-source vulnerability concentrates in Wallonian heavy fabrication capacity for precipitator housings. Distribution runs through OEM-anchored direct sales for large installations, with filter media and sensors increasingly channeled through multi-year framework agreements consolidating procurement under certified suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market as EU Industrial Emissions Directive enforcement compresses capital expenditure timing across Central European heavy manufacturing, accelerating replacement waves ahead of synchronized BAT conclusion deadlines.
For Market Incumbents: Harden digital platform differentiation by embedding predictive maintenance architectures into fume extraction specifications, defending against automation-anchored conglomerates encroaching from adjacent industrial control markets. Deepen backward integration into REACH-certified filter media production to capture recurring revenue pools as Dutch chemical clusters and German automotive supply chains consolidate procurement under multi-year frameworks. For New Entrants and Emerging Players: Pursue aftermarket service unbundling opportunities in Spanish and Portuguese industrial maintenance markets, where independent filter media supply and remote diagnostics penetration remains nascent. Target wet scrubber-carbon capture hybrid configurations in Netherlands and Belgium chemical clusters as the most penetrable retrofit segment, leveraging chemical process expertise against heavy fabrication specialists lacking absorption system engineering depth. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional engineering houses holding precipitator fabrication capabilities in Wallonia and northern Italy, positioned for consolidation as replacement cycles accelerate in southeastern European power corridors. Watch for CBAM compliance documentation requirements triggering certified emissions monitoring integration demand in Czech and Slovak steel installations as the inflection signal for platform valuation expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Filter Media | Captures recurring revenue as Dutch chemical clusters consolidate procurement under REACH-certified suppliers. |
| Sensor-Embedded Platform Development | Secures premium positioning in German automotive foundry specifications requiring predictive maintenance architectures. |
| Wet Scrubber-Carbon Capture Hybrid Deployment | Opens retrofit opportunities at Netherlands and Belgium chemical processing clusters converging acid gas absorption with amine-based capture. |
| Aftermarket Service Unbundling | Enables independent penetration of Spanish and Portuguese maintenance markets as procurement decouples from original equipment contracts. |
| REACH Compliance Documentation Investment | Creates qualification barrier marginalizing smaller media converters lacking in-house testing and carbon footprint certification capabilities. |
Research Methodology
A standing panel of plant engineers, maintenance directors at cement and steel facilities, OEM procurement teams, aftermarket service heads, and EHS compliance officers provided ongoing calibration across the study period, combining structured primary interviews with secondary validation from EU BAT reference documents, ECHA REACH restriction filings, F-Gas Regulation quota disclosures, and national emissions inventory databases. Bottom-up equipment shipment tracking and top-down capital expenditure analysis triangulated market sizing.
Scenario-bracketing around regulatory enforcement timing and technology substitution curves shaped the analytical framework across the projection horizon, with segmentation modeling spanning technology type, end-use sector, temperature regime, and digital integration intensity. CAGRs derived from equipment replacement cycle analysis and permit renewal pattern correlation, incorporating EU Industrial Emissions Directive compliance deadline phasing and carbon border adjustment mechanism documentation requirements as industry-specific forecast inputs.
Sensitivities concentrate around BAT conclusion revision schedules, F-Gas Regulation acceleration scenarios, and ceramic fiber filter media adoption curves in cement applications. Cross-checking against national emissions trading scheme verification data and continuous monitoring system installation records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Quality Control Systems
Nitrogen Oxide Control Systems Market
Air Quality Control Systems
Air Quality Monitoring Software Market
Air Quality Control Systems
Asia Pacific Air Filtration Market
Air Quality Control Systems
Indoor Air Purification Market
Air Quality Control Systems
Air Quality Control Systems Market
Air Quality Control Systems
Ozone Analyzer Market
Air Quality Control Systems
United States Pollution Mask Market
Air Quality Control Systems
Ozone Generation Market
Air Quality Control Systems
Anti-Pollution Mask Market
Air Quality Control Systems
Asia-Pacific Air Quality Control System Market
Air Quality Control Systems
Middle-East and Africa Industrial Air Quality Control Systems Market
Air Quality Control Systems
Air Pollution Control Equipment Market
Air Quality Control Systems
Industrial Air Quality Control Systems Market
Air Quality Control Systems
Oxygen Filters Market
Air Quality Control Systems
Global Mist Eliminator Market
Air Quality Control Systems
Europe Nitrogen Oxide Control Systems Market